
 Minimally Invasive Spine Technologies Market | 2026-2036
Minimally Invasive Spine Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Minimally Invasive Spine Technologies Market Foresight
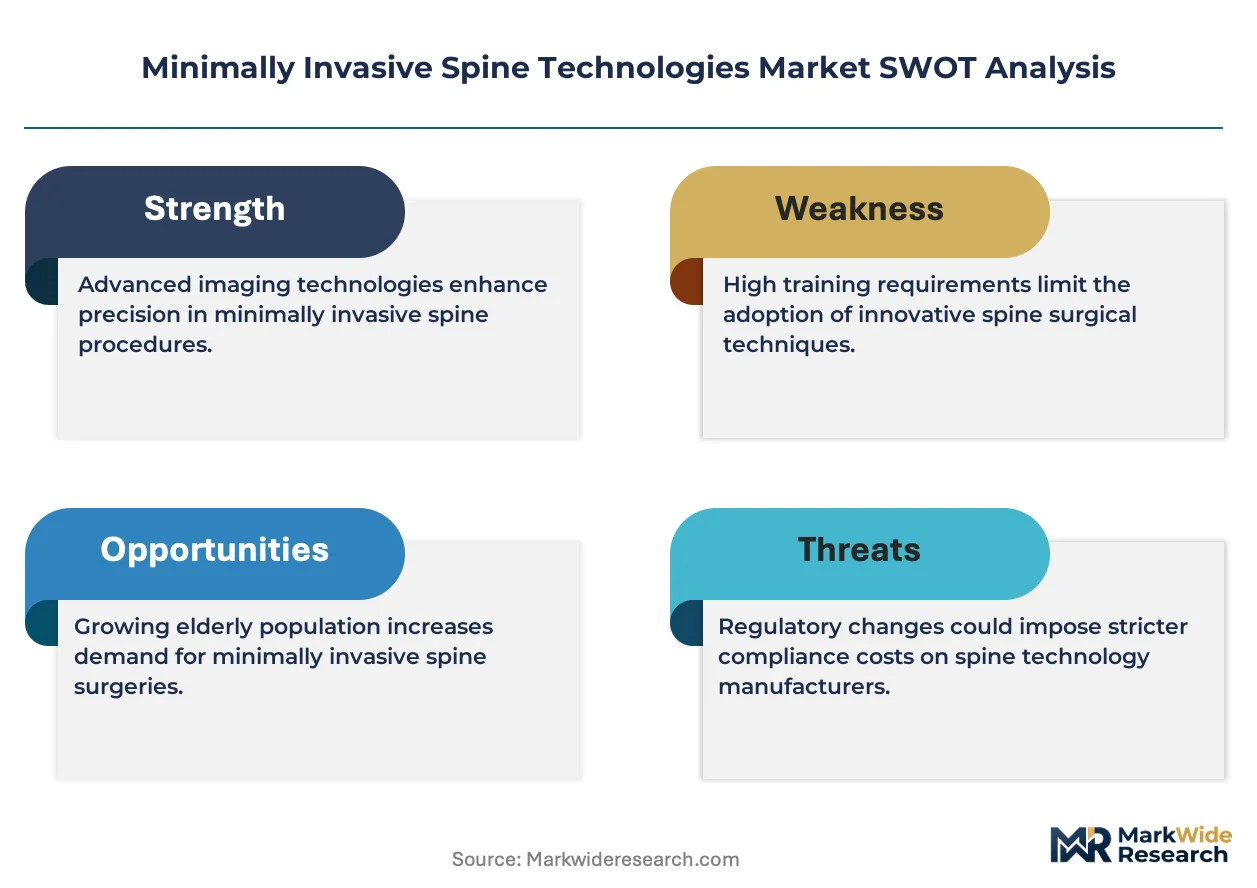
Hospital buyer consolidation across integrated delivery networks is repositioning procurement leverage toward bundled contract frameworks. Medtronic leverages its navigation-robotics ecosystem to sustain premium positioning within these consolidated accounts. Globus Medical anchors its competitive stance through manufacturing scale in expandable interbody devices. NuVasive differentiates via specialized lateral access platforms that reduce tissue disruption.
Minimally invasive spine technologies encompass instruments, implants, and visualization systems designed to access the spinal column through incisions under two centimeters while preserving paraspinal musculature. These systems employ tubular retractors, percutaneous screw placement, and real-time fluoroscopic or navigational guidance to achieve decompression, stabilization, or fusion with reduced blood loss and recovery intervals. Interbody devices command the deepest margin pools as titanium and polyetheretherketone constructs capture recurring revision volumes. Robotics within the technology segment is expanding fastest as capital placement shifts from early adopters toward community hospital settings. Spinal fusion applications remain the volume anchor while decompression procedures grow through migration to ambulatory surgery centers.
FDA 510(k) and premarket approval pathways govern device commercialization in the United States, while the EU Medical Device Regulation enforces clinical evidence and post-market surveillance requirements across European markets. Japan's PMDA maintains distinct biocompatibility and mechanical testing standards that extend registration timelines for foreign manufacturers. Stakeholders must monitor reimbursement parity between inpatient and outpatient codes as this determines site-of-service economics and capital allocation across hospital and ambulatory channels.
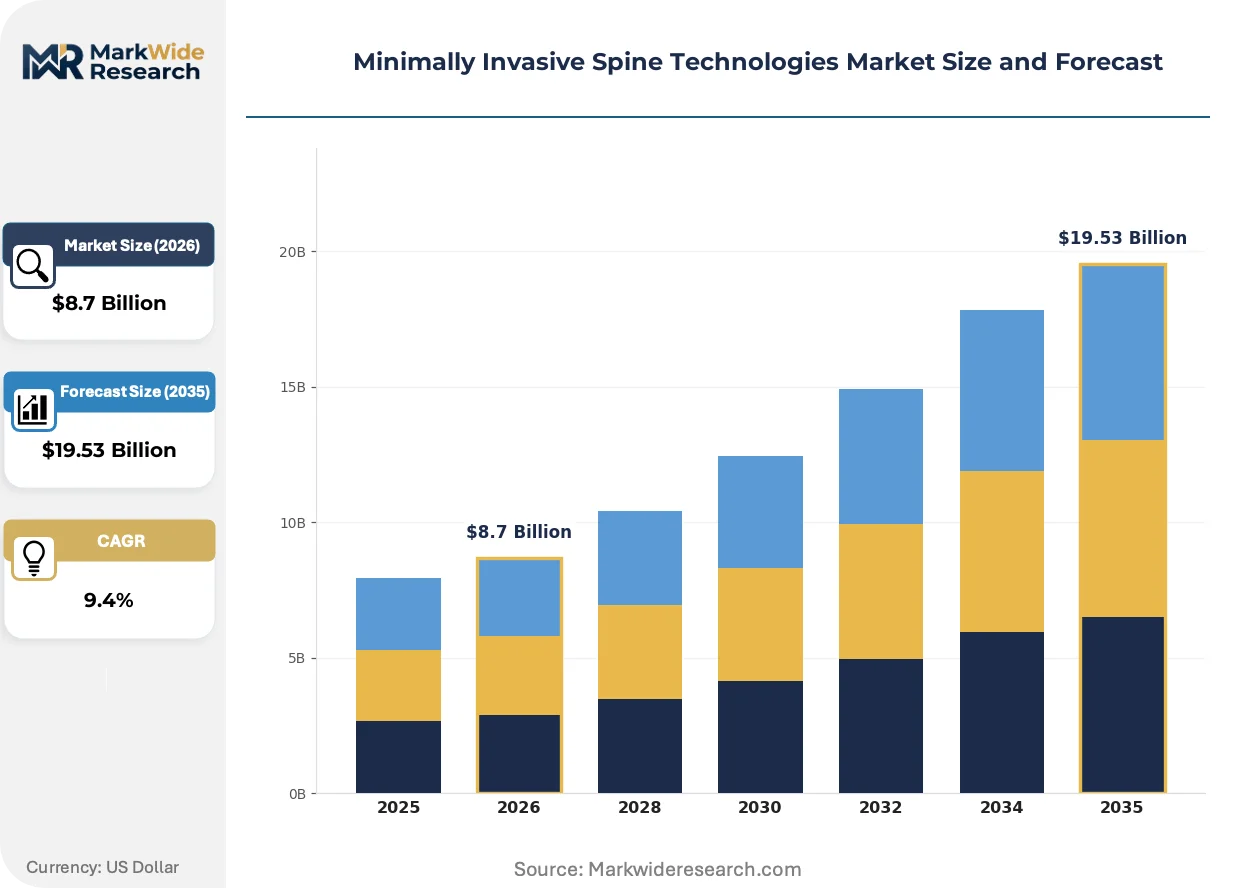
Market Dynamics
Migration of spinal procedures to ambulatory surgery centers is compressing site-of-service economics and forcing manufacturers to reconfigure instrument sets for smaller facility footprints.
Growth Catalysts
- Outpatient reimbursement parity:CMS and commercial payors in the United States now reimburse minimally invasive lumbar fusion at equivalent rates regardless of setting, accelerating capital deployment toward ASCs.
- Navigation-robotics convergence:Real-time intraoperative guidance systems reduce screw malposition rates and enable percutaneous placement through smaller incisions.
- German statutory health insurance:G-BA assessments now favor endoscopic decompression over open laminectomy for selected stenosis grades, redirecting procedure volumes.
Market Restraints
- Titanium powder supply concentration:Additive manufacturing feedstock for patient-specific interbody cages relies on a concentrated supplier base in China, creating input cost volatility.
- PMDA biocompatibility testing:Japan's extended mechanical fatigue protocols add eighteen to twenty-four months to foreign manufacturer registration timelines versus FDA 510(k) pathways.
- Learning curve barriers:Surgeon proficiency in tubular retractor systems requires fifty to one hundred supervised cases, constraining adoption in low-volume community hospitals.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives reduce import duty exposure and enable price-competitive positioning for expandable interbody systems.
- Augmented reality overlay:Integration of AR headsets with preoperative planning software enables junior surgeons to execute complex lateral approaches with reduced supervision.
- Direct-to-ASC distribution:Bypassing hospital central sterile supply through procedure-specific kit consignment reduces inventory carrying costs for independent surgery centers.
Industry Challenges
- Cross-training surgical staff:Hybrid operating rooms require simultaneous competency in fluoroscopy, navigation, and robotic arm positioning, stretching technical labor pools.
- Legacy EHR integration:Navigation systems generate proprietary data formats that resist seamless incorporation into existing hospital information architectures.
- Surgeon ownership disclosure:Physician investment in ASCs triggers Stark Law scrutiny when bundled implant contracts create referral incentives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Minimally Invasive Spine Technologies Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interbody Devices, Imaging Systems, Access Instruments, Energy Devices Technology: Navigation Systems, Robotics, Endoscopy, Biologics Application: Spinal Fusion, Decompression, Discectomy, Osteotomy End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Rehabilitation Centers |
| Companies Covered | Medtronic, Globus Medical, DePuy Synthes, Stryker, Zimmer Biomet, NuVasive, SI-BONE, Orthofix Medical, B. Braun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Minimally Invasive Spine Technologies Market Shifts & Advancements
Robotics and augmented guidance systems are compressing the gap between high-volume academic centers and community hospital capabilities, redistributing procedural access across facility tiers.
Spinal navigation platforms are automating screw trajectory planning and reducing fluoroscopy exposure during percutaneous pedicle placement. Community hospitals with annual caseloads below two hundred procedures now justify capital acquisition through shared service models. This technology is automating elements of surgical workflow previously reserved for fellowship-trained specialists.
The EU Medical Device Regulation now mandates post-market clinical follow-up for Class III implantable devices, extending surveillance obligations from passive reporting to active patient registry maintenance. German notified bodies have consolidated under stricter designation criteria, reducing review capacity across the continent. Expandable interbody manufacturers targeting European markets face compressed submission timelines and expanded clinical evidence requirements.
Hospital procurement committees now unbundle navigation capital from implant contracts, reversing prior bundled leasing arrangements that locked facilities into single-vendor ecosystems. Independent ASCs exploit this fragmentation to negotiate spot pricing on disposables while renting capital equipment per procedure. This shift is most visible in Texas and Florida, where ambulatory spine volumes exceed national averages by forty percent.
Minimally Invasive Spine Technologies Market Segmentation
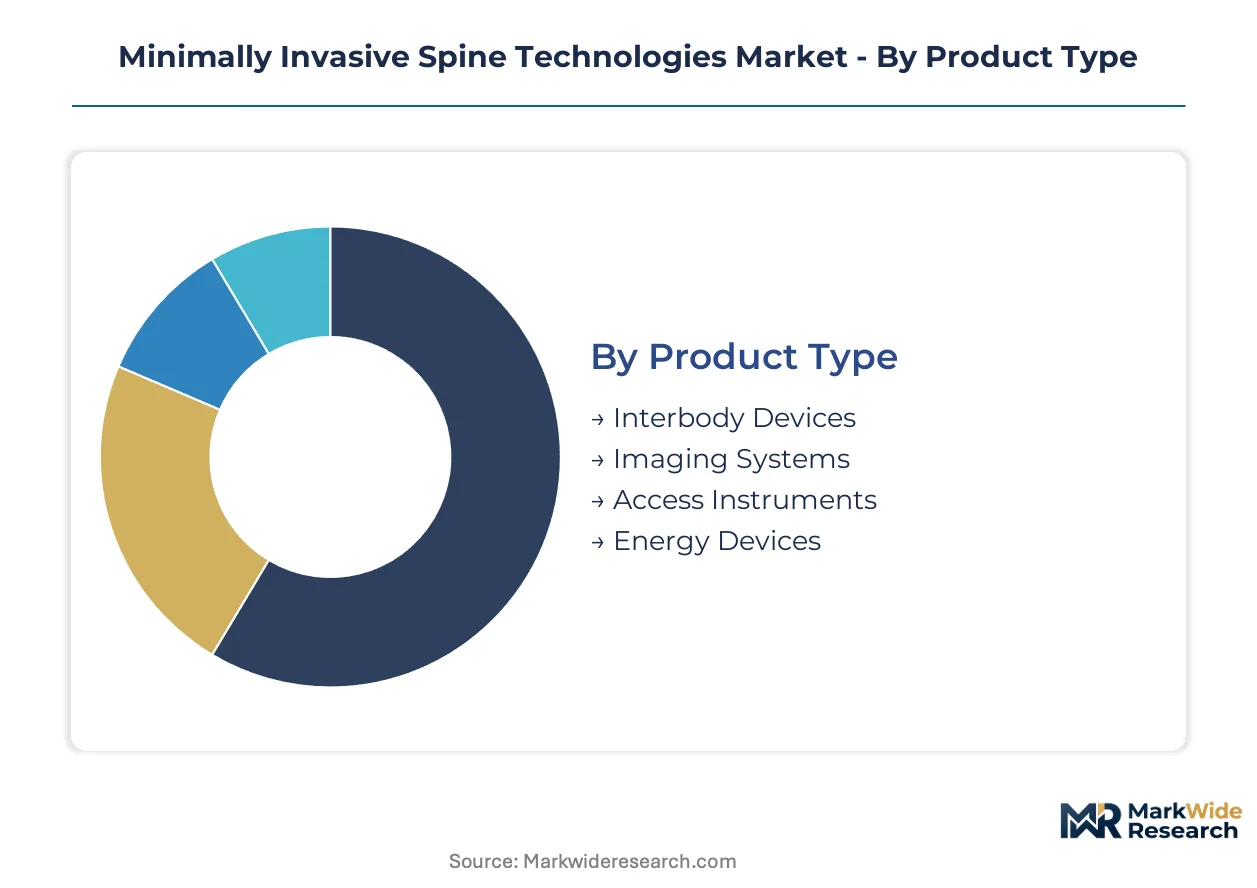
Segmentation in minimally invasive spine technologies reveals divergent margin structures and capital intensity across product categories. Procurement committees evaluate navigation capital separately from implant contracts, reshaping vendor relationships across each segment boundary.
Product Type:
Hospital procurement leverage concentrates on implant margins while imaging systems command separate capital budgets.
- Interbody Devices:Titanium and polyetheretherketone constructs anchor recurring revision volumes with the deepest margin pools. Demand clusters in United States integrated delivery networks where bundled contracts favor expandable cage platforms.
- Imaging Systems:Real-time fluoroscopy and intraoperative CT enable percutaneous screw placement through sub-two-centimeter incisions. German statutory health insurance assessments now mandate navigation-assisted placement for selected fusion grades, redirecting capital allocation.
- Access Instruments:Tubular retractors and specialized dilators preserve paraspinal musculature during lateral approaches.
- Energy Devices:Radiofrequency and ultrasonic tools enable precise tissue dissection with reduced thermal spread.
Interbody devices lead on scale; imaging systems lead on momentum.
Technology:
Capital deployment patterns distinguish between installed-base expansion and disruptive platform adoption.
- Navigation Systems:Optical and electromagnetic tracking automate screw trajectory planning while reducing fluoroscopy exposure. United States ambulatory surgery centers now justify acquisition through shared service models with annual caseloads below two hundred procedures.
- Robotics:Robotic arm platforms compress the capability gap between academic centers and community hospitals. Placement is shifting from early adopters toward community settings across Texas and Florida where outpatient spine volumes exceed national benchmarks.
- Endoscopy:Visualized decompression through working channels enables tissue-sparing laminectomy.
- Biologics:Demineralized bone matrix and synthetic graft materials supplement mechanical fixation.
Navigation systems anchor current revenue; robotics claims the steepest expansion trajectory.
Application:
Site-of-service economics drive divergence between inpatient fusion volumes and outpatient migration.
- Spinal Fusion:Interbody and posterolateral fusion procedures remain the volume anchor across hospital settings. CMS reimbursement parity between inpatient and ambulatory settings accelerates lateral access adoption in United States surgery centers.
- Decompression:Laminectomy and foraminotomy procedures migrate fastest to ambulatory settings with reduced blood loss protocols. German G-BA assessments now favor endoscopic decompression over open laminectomy for selected stenosis grades.
- Discectomy:Herniated nucleus pulposus removal through tubular access preserves motion segments.
- Osteotomy:Three-column resection for deformity correction demands navigation assistance.
Spinal fusion dominates absolute volume; decompression gains share fastest.
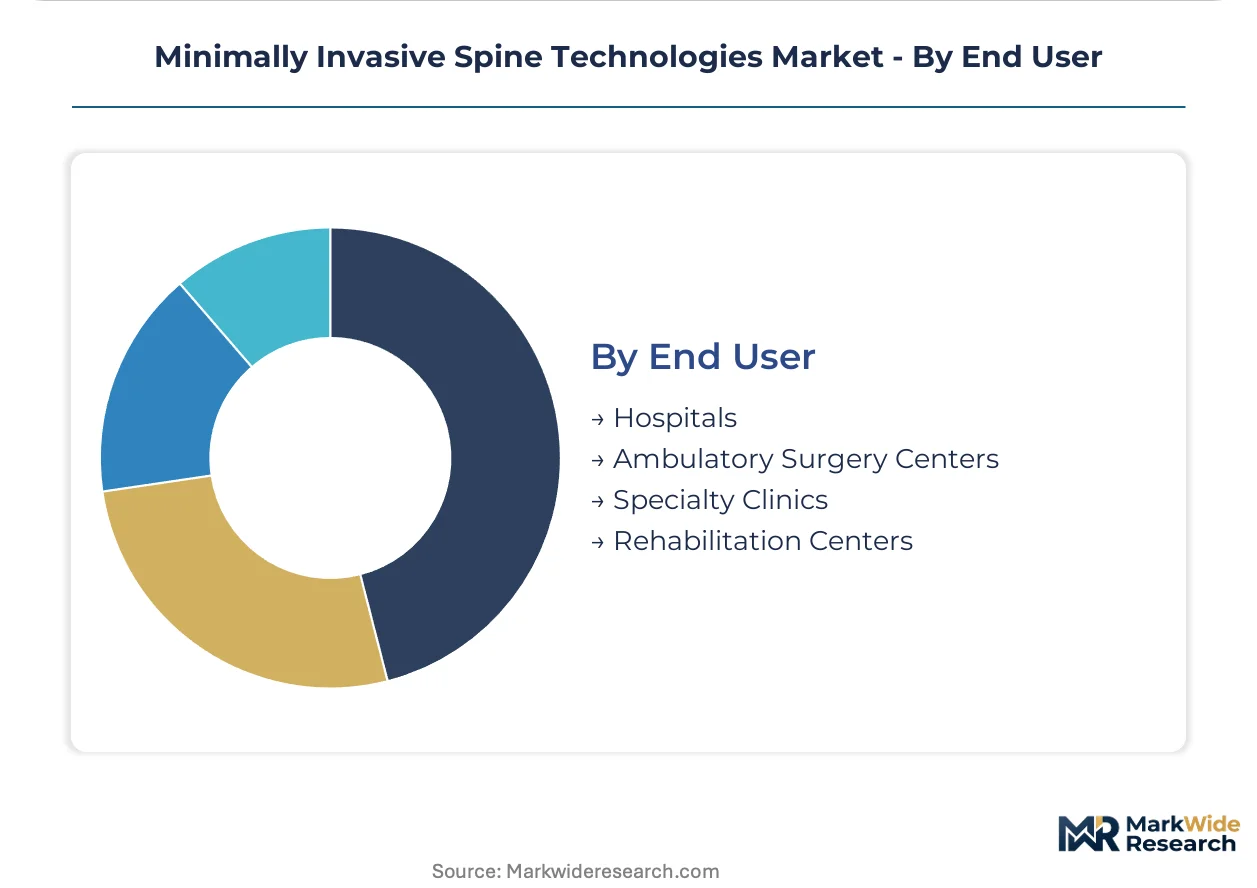
End User:
Facility type determines instrument set configuration and inventory carrying cost tolerance.
- Hospitals:Integrated delivery networks exploit consolidated procurement leverage across hybrid operating rooms. United States hospital systems now unbundle navigation capital from implant contracts, reversing prior single-vendor lock-in arrangements.
- Ambulatory Surgery Centers:Independent facilities negotiate spot pricing on disposables while renting capital equipment per procedure. Texas and Florida ASCs exploit fragmented vendor relationships to reduce inventory costs.
- Specialty Clinics:Orthopedic and neurosurgical focused practices concentrate high-volume surgeons.
- Rehabilitation Centers:Post-acute facilities coordinate recovery protocols following minimally invasive discharge.
Hospitals retain volume concentration; ambulatory surgery centers expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory health insurance system accelerates endoscopic decompression adoption faster than Japan's extended PMDA timelines permit foreign entry, creating divergent competitive windows across developed markets.
United States
Integrated delivery networks consolidate procurement leverage across Texas and Florida, where ambulatory spine volumes exceed national benchmarks. CMS reimbursement parity between inpatient and outpatient settings redirects capital toward surgery centers. The Greater Boston cluster anchors navigation-robotics development with shared service models enabling community hospital access.
Germany
G-BA assessments favor minimally invasive protocols over open laminectomy for selected stenosis grades, redirecting procedure volumes. The EU Medical Device Regulation enforces active patient registry maintenance for Class III implants. The Baden-Württemberg industrial corridor concentrates expandable interbody manufacturing with compressed submission timelines under consolidated notified bodies.
Japan
Aging demographics drive demand for tissue-preserving approaches, yet PMDA biocompatibility testing extends foreign manufacturer registration timelines eighteen to twenty-four months beyond FDA pathways. METI coordinates domestic production incentives. The Kanto region around Tokyo anchors specialist training centers for tubular retractor proficiency.
India
The PLI scheme for medical devices reduces import duty exposure for expandable interbody systems. CDSCO registration pathways compress domestic commercialization timelines versus foreign manufacturer routes. Maharashtra and Gujarat host emerging manufacturing clusters targeting price-competitive positioning across South Asian markets.
United Kingdom
NICE technology appraisals increasingly reference minimally invasive comparator arms in spinal fusion guidance. The NHS long-term plan accelerates day-case surgery migration for decompression procedures. The Oxford-Cambridge arc concentrates navigation software development with proximity to academic surgical trial networks.
Minimally Invasive Spine Technologies Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered structure where scale advantages concentrate in implant manufacturing and navigation capital fragments across regional service models. Three archetypes dominate: diversified med-tech conglomerates with robotics ecosystems, pure-play spine specialists with lateral access platforms, and regional manufacturers leveraging domestic production incentives. Competitive moves center on unbundling navigation capital from implant contracts and establishing shared service models for community hospital penetration.
Among diversified conglomerates, Medtronic anchors the navigation-robotics ecosystem tier, while Globus Medical and NuVasive exemplify pure-play specialists with differentiated access platform positioning. These three occupy distinct competitive vectors rather than direct overlapping contest, with the first representing capital-intensive system integration and the latter pair exemplifying focused procedural innovation.
| Leading Market Players |
|---|
| Medtronic |
| Globus Medical |
| DePuy Synthes |
| Stryker |
| Zimmer Biomet |
| NuVasive |
| SI-BONE |
| Orthofix Medical |
| B. Braun |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up ASC networks concentrate purchasing power across Texas and Florida, compressing implant price points while simultaneously demanding consignment inventory models that shift carrying costs back to manufacturers. This ownership pattern tightens margin discipline across interbody device tiers and forces suppliers to absorb logistics complexity in exchange for procedural volume commitments.
Pricing Analysis
Capacity additions in India's PLI scheme zones are reshaping price floors for titanium expandable cages, pressuring legacy premium positioning. Three-tier pricing structure across navigation-integrated, standard modular, and basic instrument sets separates academic medical centers from community hospitals and independent ASCs. Price differentiation hinges on FDA 510(k) clearance tier and bundled service intensity. Cost compression in disposable retractor kits is intensifying because spot-buying ASCs bypass GPO contracts. Independent surgery centers exhibit highest price sensitivity; integrated delivery networks with robotics lock-in show lowest.
Supply Chain Analysis
ISO 13485 and FDA QSR compliance gates concentrate qualified suppliers across Germany, Switzerland, and the United States for precision-machined titanium components. Additive manufacturing feedstock for patient-specific cages draws from concentrated powder metallurgy sources in China and Germany. Supply chain risk centers on single-source vulnerability for navigation system optical tracking modules. Distribution runs through hybrid models: direct-to-hospital for capital equipment, consignment-to-ASC for disposables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory ratchets—CMS reimbursement parity between inpatient and outpatient settings permanently shifted site-of-service economics toward ASCs. That milestone continues redirecting capital allocation and vendor contracting structures.
For Market Incumbents: Anticipate unbundling pressure from hospital procurement committees by pre-emptively separating navigation capital from implant contracts. Defend against independent ASC spot-buying by embedding software subscription hooks that raise switching costs. Prioritize backward integration into titanium powder processing to offset feedstock volatility from Chinese suppliers.
For New Entrants and Emerging Players: Independent ambulatory surgery centers in Texas and Florida offer the most penetrable channel for lateral access platform entry. Target decompression procedure kits first, where G-BA assessments in Germany already favor minimally invasive protocols and create referenceable outcomes data. Pursue direct-to-ASC distribution with procedure-specific sterile consignment to bypass hospital central supply.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional manufacturers with CDSCO registrations in India but limited European notified body relationships. Long-term viability over the next decade rests on navigating MDR surveillance obligations and robotics ecosystem integration. Watch for FDA breakthrough device designations in augmented reality navigation as an inflection signal for platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Navigation-Robotics Ecosystem Integration | Medtronic's platform consolidation locks hospital accounts through shared service models. |
| Direct-to-ASC Distribution Buildout | Bypassing central sterile supply reduces inventory carrying costs for independent surgery centers. |
| EU MDR Post-Market Surveillance Compliance | German notified body consolidation extends review timelines for Class III implantable devices. |
| India PLI Manufacturing Localization | Domestic production incentives enable price-competitive expandable interbody positioning. |
| Reimbursement Strategy Alignment | CMS outpatient parity codes determine capital allocation across hospital and ambulatory channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with spine surgeons, hospital purchasing committee directors, ASC operations managers, and biomedical engineers with secondary validation against FDA 510(k) filings, CMS reimbursement databases, GPO contract repositories, and EU MDR notified body registries. Bottom-up procedure volume estimates and top-down capital expenditure flows were triangulated across product and technology segments.
Comparable historical periods anchored the projection horizon, with modeling spanning product type, technology platform, application procedure, end-user facility tier, and regional regulatory cluster dimensions. CAGRs were derived from segmented growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs incorporated ambulatory surgery center migration rates, navigation system capital replacement cycles, and PMDA registration timeline differentials.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to reimbursement code revisions, titanium powder supply disruptions, and robotics adoption inflections. A model refresh is warranted upon material change in CMS site-of-service parity policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Digital Medical Thermometers Market
Medical Devices
Global Stone Retrieval Basket Market
Medical Devices
Europe Aligner Sheet Market
Medical Devices
India Drug Delivery Devices Market
Medical Devices
Global Ablation Technologies Market
Medical Devices
Ankle Syndesmosis Treatment Devices Market
Medical Devices
Global Coronary Artery Bypass Graft Devices Market
Medical Devices
Germany Contraceptive Devices Market
Medical Devices
Airway Clearance Systems Market
Medical Devices
Tourniquet Systems Market
Medical Devices
Wrist Fixator Procedure Kit Market
Medical Devices
LAMEA Breast Pumps Market
Medical Devices
Global Electronic Drug Delivery Systems Market
Medical Devices
Kidney Stone Management Devices Market
Medical Devices
Global Bone Tumor Ablation Devices Market
Medical Devices
US Medical Bionic Implants & Artificial Organs Market