
 Ear Tube Devices Market | 2026-2036
Ear Tube Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ear Tube Devices Market Analysis
Biocompatibility-grade silicone specifications is unwinding legacy polypropylene dominance across otologic device portfolios. Medtronic leverages its surgical navigation ecosystem to anchor hospital procurement decisions for integrated ENT suites. Grace Medical specializes in patient-matched tube geometries that reduce extrusion rates in pediatric populations. Preceptis Medical competes through focused R&D intensity on insertion instrumentation rather than commoditized tube commodity lines.
Ear tube devices are small cylindrical implants, typically 1.0–2.3 mm in outer diameter, inserted through the tympanic membrane to ventilate the middle ear and equalize pressure; they are manufactured via precision extrusion or micro-molding of medical-grade polymers and metals, with surface finishes engineered to minimize biofilm adhesion and tissue granulation during residence periods of six to eighteen months. Ventilation tubes lead procedural volumes due to established reimbursement codes and surgeon familiarity, while pressure equalization tubes represent the fastest-expanding category as ambulatory surgery centers adopt same-day pediatric protocols. Silicone commands premium positioning for its flexibility and lower extrusion incidence, whereas stainless steel occupies cost-sensitive procurement channels where durability outweighs biocompatibility concerns.
FDA 510(k) clearance pathways govern US market entry, while CE marking under the EU MDR imposes stricter clinical evidence requirements on implantable otologic devices; Japan's PMDA maintains distinct biocompatibility testing protocols that extend registration timelines for foreign manufacturers. Stakeholders must monitor evolving regulatory convergence between FDA and MDR material characterization standards, as divergence in testing burdens will reshape competitive access across the North Atlantic corridor.
Market Dynamics
Biocompatibility-grade silicone specifications are unwinding legacy polypropylene dominance across otologic device portfolios, forcing manufacturers to requalify material supply chains and reformulate surface engineering protocols for pediatric implant acceptance.
Growth Catalysts
- EU MDR material characterization standards:Stricter clinical evidence requirements for implantable otologic devices are accelerating R&D investment in next-generation surface coatings that reduce biofilm adhesion.
- Minimally invasive insertion systems:Pediatric clinics are expanding adoption of precision instrumentation that enables same-day ambulatory protocols and reduces anesthesia exposure in young patients.
- United States ENT surgical volumes:Elevated procedural frequency in tertiary care centers sustains demand for ventilation tubes with established reimbursement coding.
Market Restraints
- Medical-grade silicone supply concentration:Specialty polymer feedstock production clusters in select chemical manufacturing regions, exposing device makers to input cost volatility and qualification delays.
- Japan PMDA biocompatibility testing protocols:Distinct evaluation timelines for foreign manufacturers extend registration cycles and compress effective patent life for novel tube geometries.
- Stainless steel substitution threat:Cost-sensitive procurement channels in emerging markets prioritize durability over biocompatibility, limiting premium silicone penetration.
Strategic Opportunities
- Germany ambulatory surgery center expansion:Same-day pediatric protocols create demand for integrated insertion systems combining patient-matched tube geometries with disposable instrumentation.
- ISO 10993-5 cytotoxicity harmonization:Convergence between FDA and EU MDR material testing standards reduces duplicate qualification burdens for manufacturers with transatlantic portfolios.
- Tele-ENT diagnostic integration:Remote tympanic membrane visualization technologies enable pre-screening workflows that expand addressable patient populations in underserved regions.
Industry Challenges
- Micro-molding process engineering talent:Precision extrusion of 1.0–2.3 mm diameter tubes requires specialized polymer processing expertise that concentrates in select manufacturing clusters.
- FDA 510(k) predicate device strategy:Substantial equivalence determinations for novel surface finishes demand extensive bench testing documentation that extends development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ear Tube Devices Market |
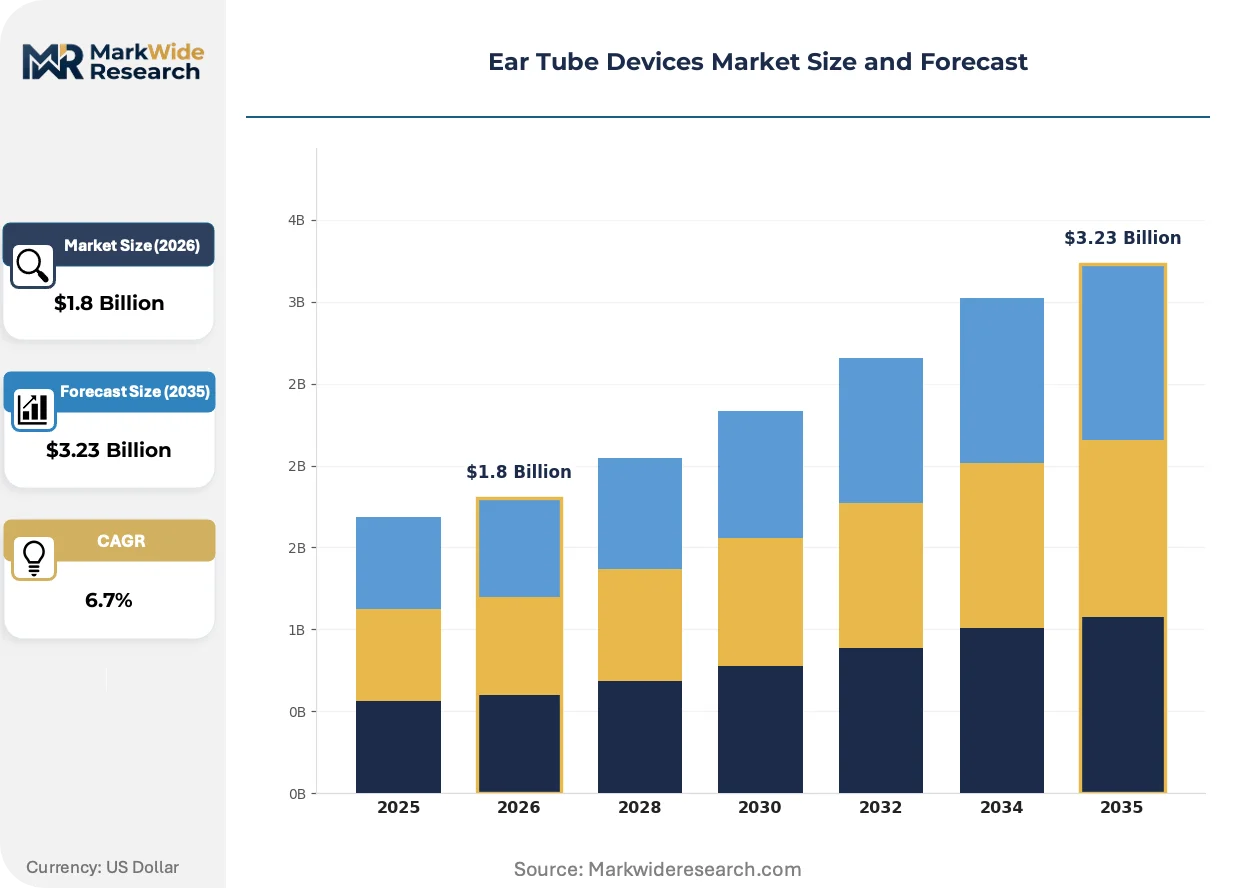
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Lumen Tubes, Double-Lumen Tubes, Ventilation Tubes, Pressure Equalization Tubes Material: Silicone, Stainless Steel, Polypropylene, Teflon Indication: Recurrent Otitis Media, Eustachian Tube Dysfunction, Hearing Loss, Chronic Otitis Media End User: Pediatric Clinics, ENT Hospitals, Ambulatory Surgery Centers, Outpatient Settings |
| Companies Covered | Medtronic, Grace Medical, Preceptis Medical, Acclarent, Teleflex, Olympus Corporation, AventaMed, Summit Medical, Anthony Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ear Tube Devices Market Emerging Trajectories
Active material substitution and regulatory convergence are compressing traditional competitive moats while ambulatory care expansion rewires distribution economics for disposable ENT instrumentation.
Biocompatibility-grade silicone is supplanting polypropylene in premium otologic device portfolios due to superior flexibility and reduced extrusion incidence in pediatric populations. Tertiary care hospitals and specialized pediatric clinics are adopting silicone-dominant tube specifications at accelerating pace. This material transition is supplanting legacy commodity lines and forcing stainless steel manufacturers toward cost-sensitive channel defense.
CE marking under the EU MDR imposes stricter clinical evidence requirements on implantable otologic devices than predecessor directives. Manufacturers must now submit extended biocompatibility documentation and post-market surveillance protocols. Pediatric ventilation tube categories face the heaviest compliance burden, driving consolidation among sponsors with limited regulatory affairs capacity.
Ambulatory surgery centers are unbundling after-sales service from device procurement contracts for ENT suites. Same-day discharge protocols favor disposable insertion instrumentation over capital equipment purchases. This procurement model compression is most visible in United States metropolitan markets where facility reimbursement incentives reward throughput velocity over capital intensity.
Ear Tube Devices Market Segmentation
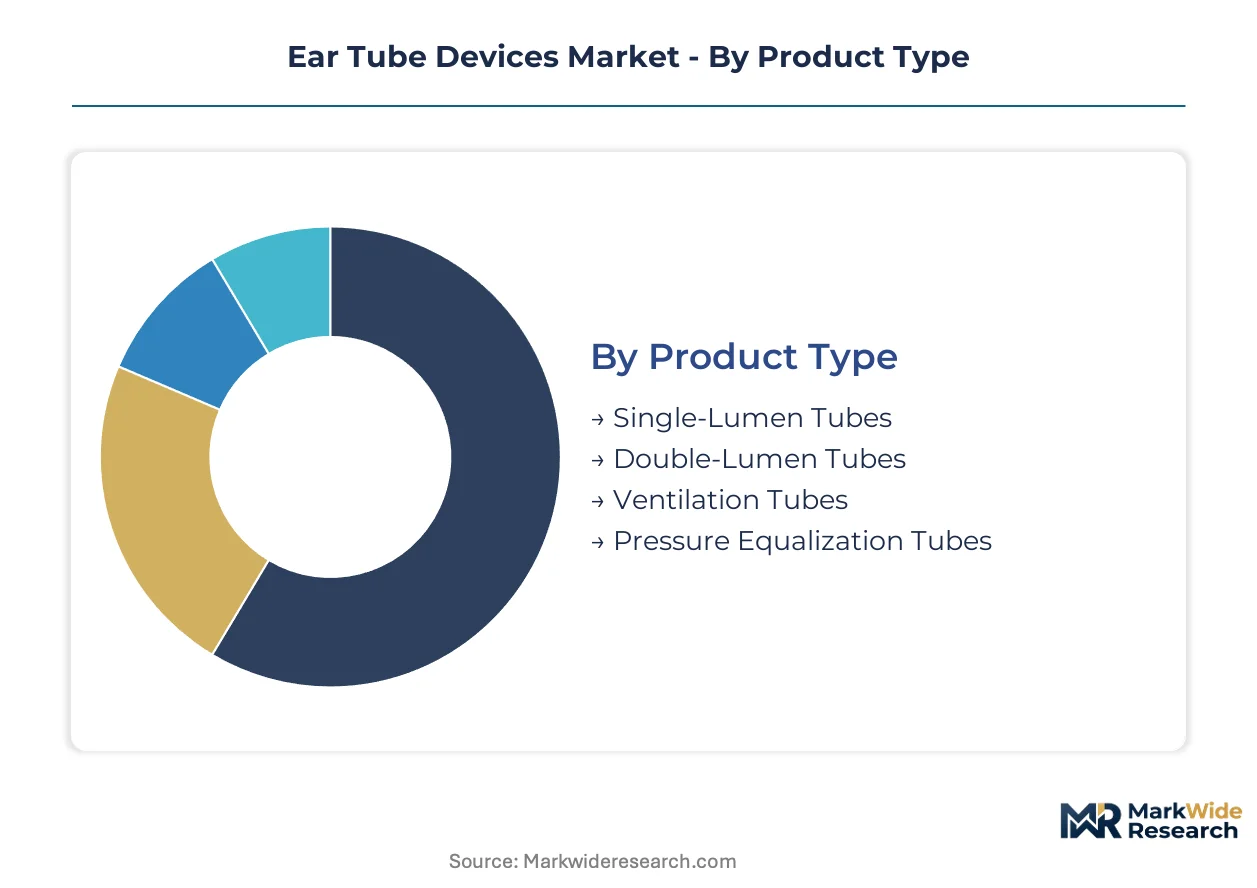
Ear tube device procurement varies sharply across clinical settings and patient populations. Manufacturers configure product portfolios around material biocompatibility thresholds, procedural venue economics, and pediatric versus adult anatomical requirements.
Product Type:
Ventilation tubes dominate domestic hospital procurement in the United States and Germany, while pressure equalization tubes find stronger export traction into ambulatory networks across Japan and emerging Asian markets.
- Ventilation Tubes:Cylindrical implants with single or multiple side ports enable middle ear aeration and fluid drainage. United States tertiary care centers sustain procedural volumes through established CPT reimbursement codes and surgeon familiarity with insertion protocols.
- Pressure Equalization Tubes:Flanged designs with retention collars reduce extrusion rates in pediatric populations. Ambulatory surgery centers in Germany and Japan adopt same-day discharge protocols that favor these geometries for reduced follow-up burden.
- Single-Lumen Tubes:Simple cylindrical construction suits cost-sensitive procurement channels where basic ventilation suffices.
- Double-Lumen Tubes:Dual-channel designs accommodate complex chronic otitis cases requiring prolonged residence periods.
Ventilation tubes hold the largest share; momentum sits with pressure equalization tubes.
Material:
Cost tier stratification separates premium silicone specifications from commodity metal alternatives, with procurement decisions hinging on biocompatibility requirements versus durability priorities.
- Silicone:Medical-grade elastomer formulations offer flexibility and reduced tissue granulation. Pediatric clinics in the United States and Germany pay material premiums to minimize extrusion-related revision surgeries.
- Polypropylene:Legacy thermoplastic dominates emerging market procurement where cost constraints override biocompatibility optimization.
- Stainless Steel:Hardened alloys resist deformation during insertion but trigger higher tissue reaction rates.
- Teflon:Fluoropolymer surfaces minimize biofilm adhesion in chronic infection presentations.
Silicone commands premium positioning; polypropylene defends volume in price-sensitive channels.
Indication:
Application severity determines device specification intensity, with recurrent infection cases driving standardized geometries while chronic conditions demand patient-matched engineering.
- Recurrent Otitis Media:Repeated acute infections in pediatric populations constitute the dominant procedural indication. United States pediatric clinics and ENT hospitals process high volumes of standardized tube insertions.
- Chronic Otitis Media:Persistent middle ear pathology requires specialized tube geometries with extended residence design. German and Japanese tertiary centers invest in patient-matched specifications.
- Eustachian Tube Dysfunction:Pressure regulation failures in adult populations generate secondary demand.
- Hearing Loss:Conductive impairment secondary to fluid accumulation drives urgent intervention protocols.
Recurrent otitis media anchors procedural volume; chronic otitis media shows steepest expansion trajectory.
End User:
Customer type dictates packaging, instrumentation bundling, and service intensity, with pediatric clinics demanding integrated insertion systems while hospitals prioritize bulk supply contracts.
- Pediatric Clinics:Specialized outpatient facilities require patient-matched tube geometries and disposable insertion instrumentation. Same-day protocols in United States metropolitan markets favor turnkey system procurement.
- Ambulatory Surgery Centers:High-throughput facilities prioritize disposable instrumentation over capital equipment. Germany's expanding ASC network drives demand for integrated disposable suites.
- ENT Hospitals:Tertiary care centers maintain inventory breadth across material and geometry specifications.
- Outpatient Settings:General practice ENT procedures rely on standardized tube lines with minimal instrumentation.
Pediatric clinics concentrate premium procurement; ambulatory surgery centers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in ear tube devices tilt toward manufacturing clusters in Germany, Japan, and the United States, with finished device shipments gravitating toward tertiary care centers while raw polymer feedstock moves in reverse from chemical production hubs.
United States
Pediatric ENT surgical volumes at tertiary centers in Boston, New York, and Los Angeles sustain procurement of premium silicone specifications. FDA 510(k) clearance pathways govern market entry with predicate device strategies dominating regulatory submissions. Minnesota's medical device corridor anchors headquarters operations for integrated ENT suite manufacturers.
Germany
Ambulatory surgery center expansion across Bavaria and North Rhine-Westphalia drives demand for disposable insertion instrumentation. CE marking under the EU MDR imposes stricter clinical evidence requirements than predecessor directives. Tübingen and Stuttgart clusters concentrate precision micro-molding expertise for biocompatibility-grade polymer processing.
Japan
Chronic otitis media cases in aging populations generate secondary demand beyond pediatric segments. PMDA biocompatibility testing protocols extend registration timelines for foreign manufacturers. Osaka-Kobe industrial zone hosts domestic device fabricators serving Kansai region ENT hospitals.
United Kingdom
NHS procurement frameworks prioritize cost containment in ventilation tube categories. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR material standards while streamlining UKCA marking timelines. London-Oxford-Cambridge corridor concentrates pediatric otolaryngology research capacity.
India
Private hospital chains in Mumbai and Delhi expand pediatric ENT service lines. CDSCO medical device rules impose import licensing requirements on foreign manufacturers. Gujarat chemical belt supplies medical-grade polymer feedstock to domestic device assemblers.
Ear Tube Devices Market Vendor Landscape
Concentration sits with diversified medical technology conglomerates and specialized otologic device houses. The vendor base stratifies across three tiers: integrated surgical platform providers, patient-matched geometry specialists, and commodity tube fabricators. Strategic moves center on material requalification for EU MDR compliance and ambulatory care distribution partnerships.
Within the integrated platform tier, Medtronic anchors hospital procurement decisions through surgical navigation ecosystem bundling. Grace Medical exemplifies the patient-matched specialization archetype with focus on pediatric population geometries. Preceptis Medical occupies a position emphasizing insertion instrumentation R&D intensity over commoditized tube lines.
| Leading Market Players |
|---|
| Medtronic |
| Grace Medical |
| Preceptis Medical |
| Acclarent |
| Teleflex |
| Olympus Corporation |
| AventaMed |
| Summit Medical |
| Anthony Products |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German precision polymer processors and US pediatric device manufacturers lock in biocompatibility-grade silicone access while anchoring price visibility against medical-grade feedstock volatility. These contractual structures insulate premium tube portfolios from spot-market swings in specialty elastomer costs.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the ear tube devices market. Price differentiation rests on FDA 510(k) clearance tier and pediatric-specific geometry customization, with US hospital systems paying material premiums for silicone specifications. Cost compression in polypropylene commodity lines is intensifying because stainless steel substitution threats from emerging market procurement channels erode legacy margin pools. Ambulatory surgery centers in Germany exhibit highest price sensitivity due to disposable instrumentation bundling requirements, while Japanese tertiary ENT hospitals show lowest sensitivity given extended residence design premiums.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg container terminals elevates inbound logistics costs for medical-grade polymer feedstock moving from US Gulf Coast chemical hubs to European micro-molding facilities. Geographic supply concentration centers on Germany, Japan, and the United States for precision extrusion equipment and biocompatibility-grade silicone formulations. Raw material dependencies draw from specialty elastomer feedstock, precision-machined insertion instrumentation, and sterilization packaging materials. Single-source vulnerability concentrates in medical-grade silicone supply chains where qualification timelines for alternative feedstock extend beyond standard procurement cycles. Distribution runs through hospital GPO contracts in the United States, direct ASC partnerships in Germany, and regional device fabricators serving Japanese ENT hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ear tube device incumbents face sustained substitution pressure from stainless steel alternatives in cost-sensitive procurement channels, requiring defensive repositioning around material biocompatibility certification and pediatric-specific geometry portfolios.
For Market Incumbents: Secure dual-source qualification for medical-grade silicone feedstock from German and US chemical suppliers to mitigate single-source concentration risk. Anchor hospital procurement decisions through integrated ENT suite bundling that combines patient-matched tube geometries with disposable insertion instrumentation, neutralizing commodity tube price erosion from emerging market metal alternatives. For New Entrants and Emerging Players: Lead with tele-ENT diagnostic integration partnerships that expand pre-screening workflows in underserved US metropolitan markets and Indian private hospital chains. Target ambulatory surgery center expansion across Germany's Bavaria and North Rhine-Westphalia regions with turnkey disposable instrumentation systems rather than competing on commoditized tube specifications alone. For Investors and Strategic Acquirers: Capital is best deployed toward patient-matched geometry specialists with established EU MDR technical documentation and pediatric clinic distribution relationships in the United States. Long-term viability across the analysis window favors sponsors with regulatory affairs capacity for extended biocompatibility testing protocols. The signal to watch is convergence between FDA and EU MDR material characterization standards, which would compress duplicate qualification burdens and reward transatlantic portfolio breadth.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Extended biocompatibility dossiers satisfy CE marking requirements for implantable otologic devices under stricter clinical evidence mandates. |
| Hospital System Partnership | Integrated ENT suite procurement at US tertiary centers anchors silicone-dominant tube specifications against stainless steel substitution. |
| Reimbursement Strategy | Established CPT coding for ventilation tube procedures sustains procedural volumes at pediatric clinics and ambulatory surgery centers. |
| Software Companion Development | Tele-ENT diagnostic platforms enable remote tympanic membrane visualization that expands addressable patient populations. |
| CE Marking Pathway | Post-market surveillance protocols under EU MDR impose compliance burdens that consolidate market position among regulatory-capable sponsors. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pediatric otolaryngologists, hospital purchasing committee members, biomedical engineers at ENT device manufacturers, GPO contracts managers, and regulatory affairs specialists. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up segmentation modeling triangulated against top-down market sizing from polymer feedstock production disclosures.
Across the analysis window, volume and value outputs reflect segment-level modeling across material type, tube geometry specification, procedural venue economics, and regional regulatory cluster. CAGRs were derived from procedure volume trajectories, reimbursement code stability, and material substitution elasticity coefficients. Forecast inputs incorporated ENT surgical volume trends at US tertiary centers, German ambulatory surgery center expansion rates, and PMDA registration timeline assumptions for foreign manufacturers.
The analysis sits within stated boundaries; outcomes outside stable FDA 510(k) predicate device pathways, sustained EU MDR compliance cost structures, or unaltered Japan PMDA biocompatibility protocols would require recalibration. Forecasts reflect assumptions around silicone material substitution velocity, ambulatory care distribution economics, and pediatric clinic procurement consolidation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
High Tibial Osteotomy (HTO) Plates Market
Medical Devices
Powered Mattress System Market
Medical Devices
Veterinary Anesthesia Equipment Market
Medical Devices
Global Eye Massage Machine Market
Medical Devices
Homecare Medical Devices Market
Medical Devices
Flow Diverters Market
Medical Devices
Breast Biopsy Marker Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
Bioresorbable Coronary Scaffolds Market
Medical Devices
Global Stereotactic Surgery Devices Market
Medical Devices
Europe Intraocular Lens Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
Pulmonary Function Testing System Market
Medical Devices
Global PC-Based Audiometer Market
Medical Devices
Global Abutment Implants Market
Medical Devices
Computer Assisted Surgical (CAS) Systems Market