
 Intravascular Ultrasound Market | 2026-2036
Intravascular Ultrasound Market Size, Share, and Industry Trends Forecast 2026-2036
Intravascular Ultrasound Market Intelligence
The EU Medical Device Regulation is shifting procurement criteria across European catheterization networks toward devices with enhanced biocompatibility documentation and post-market surveillance traceability. Boston Scientific leverages its integrated catheter manufacturing footprint to sustain supply continuity for IVUS-guided coronary procedures. Philips dominates the European installed base of multimodality imaging systems that incorporate intravascular ultrasound modules. Abbott specializes in optical coherence tomography hybrid platforms that compete directly with standalone IVUS configurations in complex lesion assessment.
Intravascular ultrasound deploys high-frequency sound waves via catheter-mounted transducers, typically operating at 20-60 MHz, to generate real-time cross-sectional images of vessel lumen and wall morphology for interventional guidance. The technology serves primarily to optimize stent sizing, detect edge dissections, and minimize procedural complications during percutaneous coronary intervention. Catheter systems anchor the revenue pool given their disposable nature and procedural volume correlation, while 3D imaging capabilities are displacing conventional 2D reconstruction in high-volume centers. Software segments that enable automated plaque characterization and vessel measurements represent the fastest-growing margin tier as artificial intelligence integration deepens.
The FDA's 510(k) clearance framework shapes device iteration cycles and predicates substantial equivalence claims on acoustic performance benchmarks. Japan's PMDA imposes additional clinical evidence requirements for IVUS-guided indication expansions, filtering market access for non-domestic manufacturers. China's NMPA has accelerated review timelines for innovative cardiovascular devices under its priority review pathway, altering competitive sequencing. Stakeholders must monitor reimbursement parity between IVUS-guided and angiography-only procedures across major health systems, as coding distinctions directly influence cath lab capital allocation and physician training commitments.
Market Dynamics
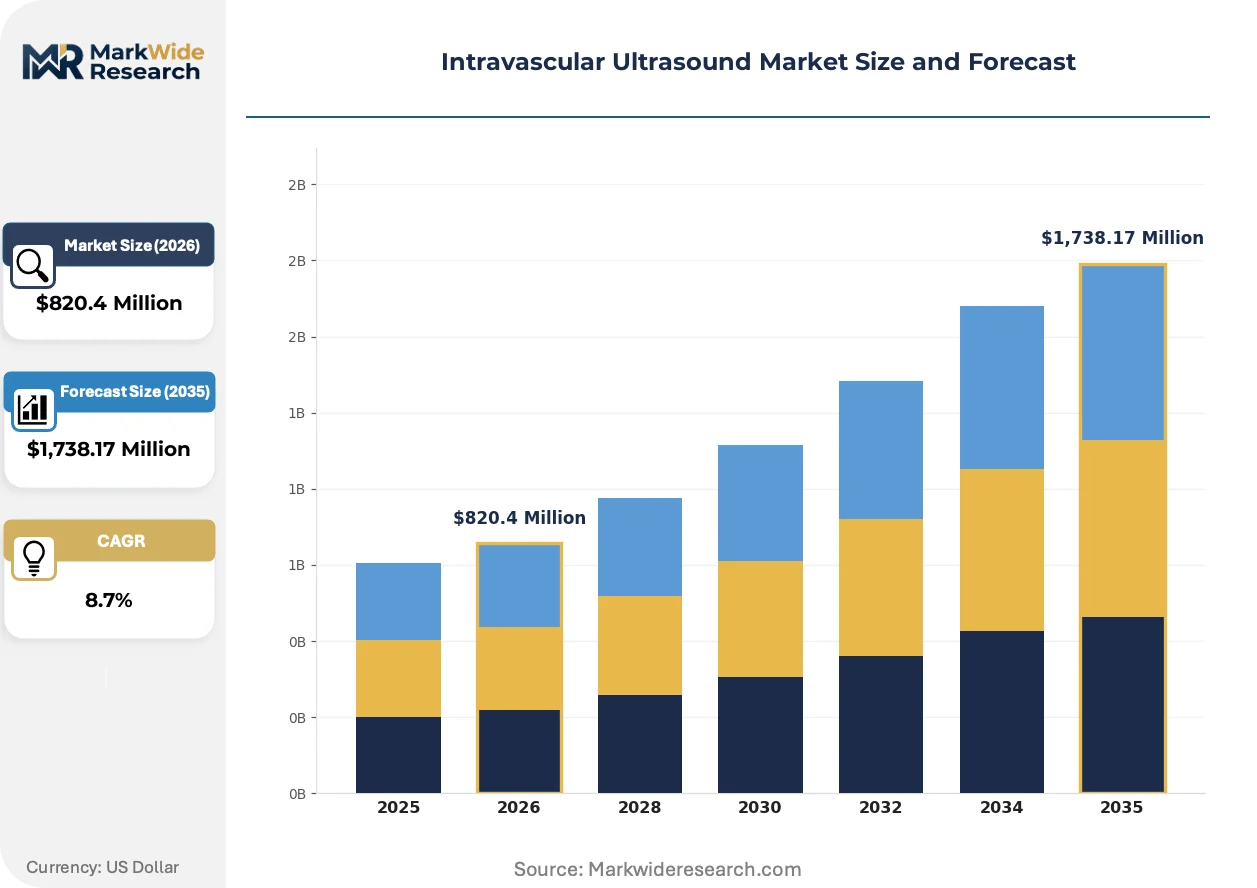
The intravascular ultrasound market pivots on cath lab capital allocation cycles, where reimbursement parity between IVUS-guided and angiography-only procedures determines physician training commitments and device procurement volumes across integrated hospital networks.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's updated premarket notification pathway for intravascular imaging catheters compresses device approval timelines, accelerating iteration cycles for acoustic performance benchmarks.
- Cardiac Catheterization Laboratory Expansion:Integrated cath lab networks in the United States are scaling IVUS-guided procedural volumes through dedicated physician training programs and capital equipment bundling.
- China NMPA Priority Review:China's accelerated review timelines for innovative cardiovascular devices under its priority review pathway are altering competitive sequencing for catheter system manufacturers.
Market Restraints
- Reimbursement Asymmetry:Coding distinctions between IVUS-guided and angiography-only procedures create reimbursement gaps that suppress cath lab capital allocation in budget-constrained health systems.
- Japan PMDA Clinical Evidence Barriers:Additional clinical evidence requirements for IVUS-guided indication expansions filter market access for non-domestic manufacturers seeking Japanese regulatory clearance.
- Optical Coherence Tomography Substitution:Hybrid OCT platforms compete directly with standalone IVUS configurations in complex lesion assessment, fragmenting technology adoption in high-volume interventional centers.
Strategic Opportunities
- Software-Enabled Plaque Characterization:Artificial intelligence integration into automated vessel measurement algorithms opens margin expansion in diagnostic software tiers beyond disposable catheter revenue pools.
- EU MDR Biocompatibility Premium:The EU Medical Device Regulation's procurement criteria shift toward enhanced post-market surveillance traceability creates differentiation value for compliant device portfolios.
- 3D Imaging Module Adoption:Three-dimensional reconstruction capabilities are displacing conventional 2D imaging in high-volume centers, opening upgrade cycles for installed base conversions.
Industry Challenges
- Acoustic Engineer Talent Scarcity:Specialized expertise in 20-60 MHz transducer design and signal processing limits R&D throughput for next-generation catheter development.
- Multimodality System Integration Complexity:IVUS module compatibility with existing angiography and OCT platforms requires substantial firmware adaptation, extending deployment timelines in mixed-vendor environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intravascular Ultrasound Market |
| Market Size in 2026 | $820.4 Million |
| Market Size in 2035 | $1,738.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Systems, Catheters, Software, Accessories End User: Hospitals, Cardiac Clinics, Research Institutions, Outpatient Facilities Technology: Optical Coherence Tomography, Doppler Ultrasound, 3D Imaging, 2D Imaging Application: Coronary Intervention, Peripheral Vascular Procedures, Plaque Assessment, Guiding Interventional Procedures |
| Companies Covered | Canon Medical Systems Corporation, Siemens Healthineers AG, Boston Scientific Corporation, Medtronic plc, GE Healthcare, Koninklijke Philips N.V., Terumo Corporation, Conavi Medical Inc., Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intravascular Ultrasound Market Strategic Shifts & Innovations
Artificial intelligence is penetrating intravascular imaging workflows, compressing diagnostic interpretation cycles and enabling real-time plaque characterization that reshapes physician decision-making at the point of intervention.
Machine learning algorithms trained on histopathology-validated plaque libraries are rewriting the speed and consistency of automated vessel measurements. High-volume interventional cardiology programs are deploying these tools to reduce procedural variability and standardize stent sizing protocols. The technology is compressing the competitive advantage gap between experienced operators and generalist practitioners.
The EU Medical Device Regulation's enhanced biocompatibility documentation requirements are elevating supply chain scrutiny for catheter materials. Manufacturers must now maintain batch-level traceability for polymers and coatings used in transducer housings. European catheterization networks are prioritizing vendors with established post-market surveillance infrastructure.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, forcing device manufacturers to compete on standalone software subscription terms. This shift is most visible in United States integrated delivery networks, where cath lab directors negotiate separate agreements for imaging system maintenance, software updates, and physician training modules.
Intravascular Ultrasound Market Segmentation
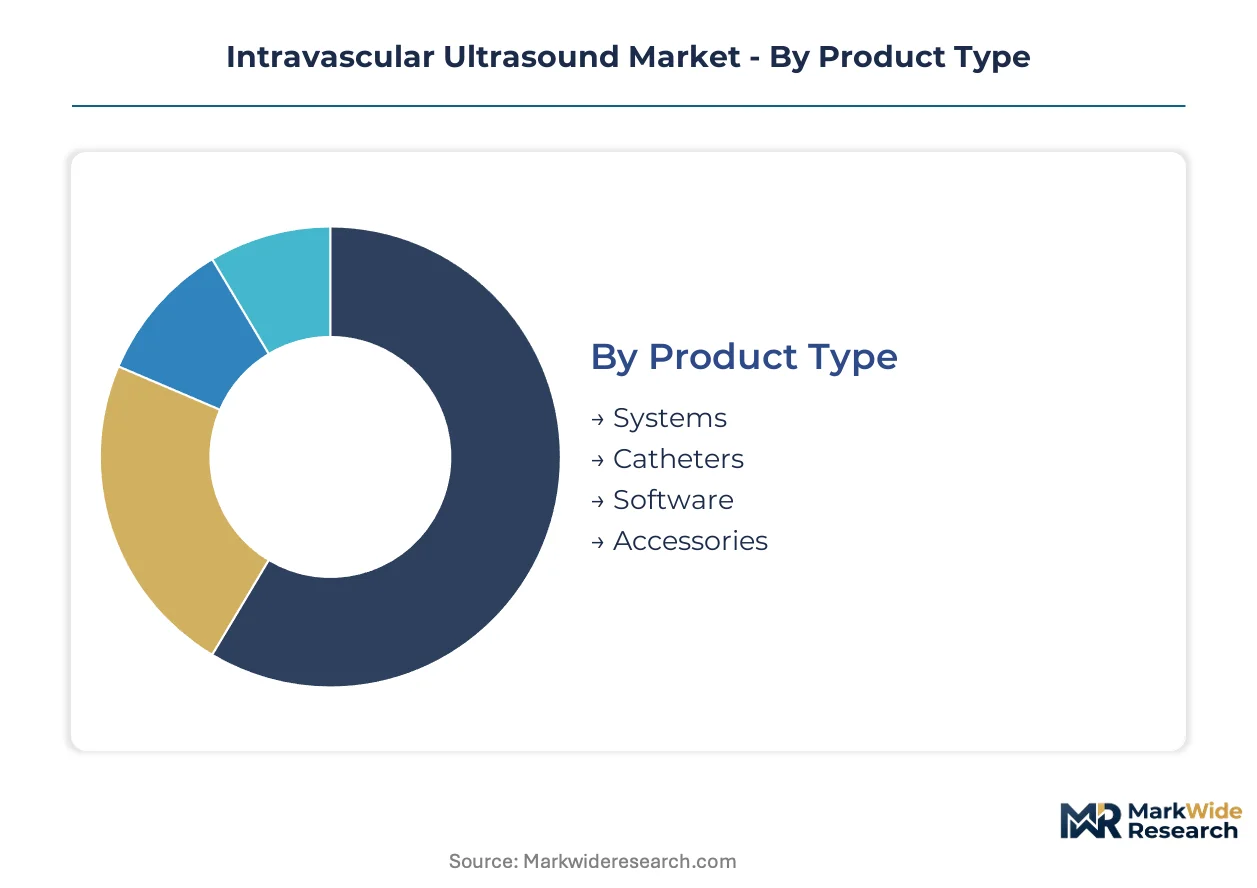
IVUS market segmentation reveals distinct procurement patterns across disposable catheters, capital systems, and software tiers. Technology differentiation between 2D and 3D imaging modules creates divergent upgrade cycles within cath lab networks.
Product Type:
Catheter specifications anchor purchasing decisions, with acoustic frequency bandwidth and transducer array density determining procedural utility.
- Catheters:Disposable catheter systems generate recurring revenue tied to procedural volumes. High-volume United States cath lab networks prioritize 40-60 MHz transducer configurations for coronary interventions, with single-use sterility requirements driving replacement frequency.
- Systems:Capital imaging consoles integrate IVUS modules with angiography platforms through proprietary docking interfaces. United States integrated delivery networks bundle system purchases with multi-year service agreements to lock in supply continuity.
- Software:Automated plaque characterization algorithms and vessel measurement tools command subscription pricing separate from hardware. Artificial intelligence integration is climbing the fastest as cath labs seek to standardize stent sizing protocols.
- Accessories:Sterile sheaths, torque devices, and calibration phantoms complete procedural setups. Demand tracks catheter procurement volumes with minimal brand switching.
Mature deployment sits with Catheters. Newer deployment is concentrated in Software.
End User:
Procurement authority varies sharply across facility types, with capital budgets and reimbursement pathways shaping technology access.
- Hospitals:Academic medical centers and community hospital systems dominate installed base expansion. United States hospital networks leverage scale to negotiate bundled pricing for multimodality imaging suites.
- Cardiac Clinics:Dedicated interventional cardiology centers prioritize throughput-optimized IVUS configurations. These facilities in the United States drive procedural volume concentration in metropolitan corridors.
- Research Institutions:Histopathology validation studies and algorithm training datasets originate from university-affiliated cath labs. Funding cycles determine equipment refresh timing.
- Outpatient Facilities:Ambulatory surgical centers face reimbursement constraints that limit IVUS adoption to high-complexity cases. Regulatory clarity on coding distinctions determines capital commitment.
Volume concentrates in Hospitals. Margin expansion sits with Cardiac Clinics.
Technology:
Imaging modality selection hinges on lesion complexity and operator training pathways, with hybrid platforms gaining traction in high-volume centers.
- 3D Imaging:Volumetric reconstruction capabilities enable longitudinal vessel assessment and stent apposition analysis. United States academic centers lead conversion from 2D systems as training programs incorporate three-dimensional interpretation.
- 2D Imaging:Conventional cross-sectional imaging maintains installed base dominance in cost-sensitive settings. Legacy system compatibility preserves segment presence despite technical displacement.
- Optical Coherence Tomography:Near-infrared light-based imaging offers superior resolution for superficial plaque assessment. Hybrid IVUS-OCT platforms compete for capital allocation in complex lesion centers.
- Doppler Ultrasound:Flow velocity measurement augments structural imaging in peripheral vascular applications. Functional assessment capabilities differentiate this modality in limb salvage procedures.
Revenue scale favors 2D Imaging. Technical transition is accelerating in 3D Imaging.
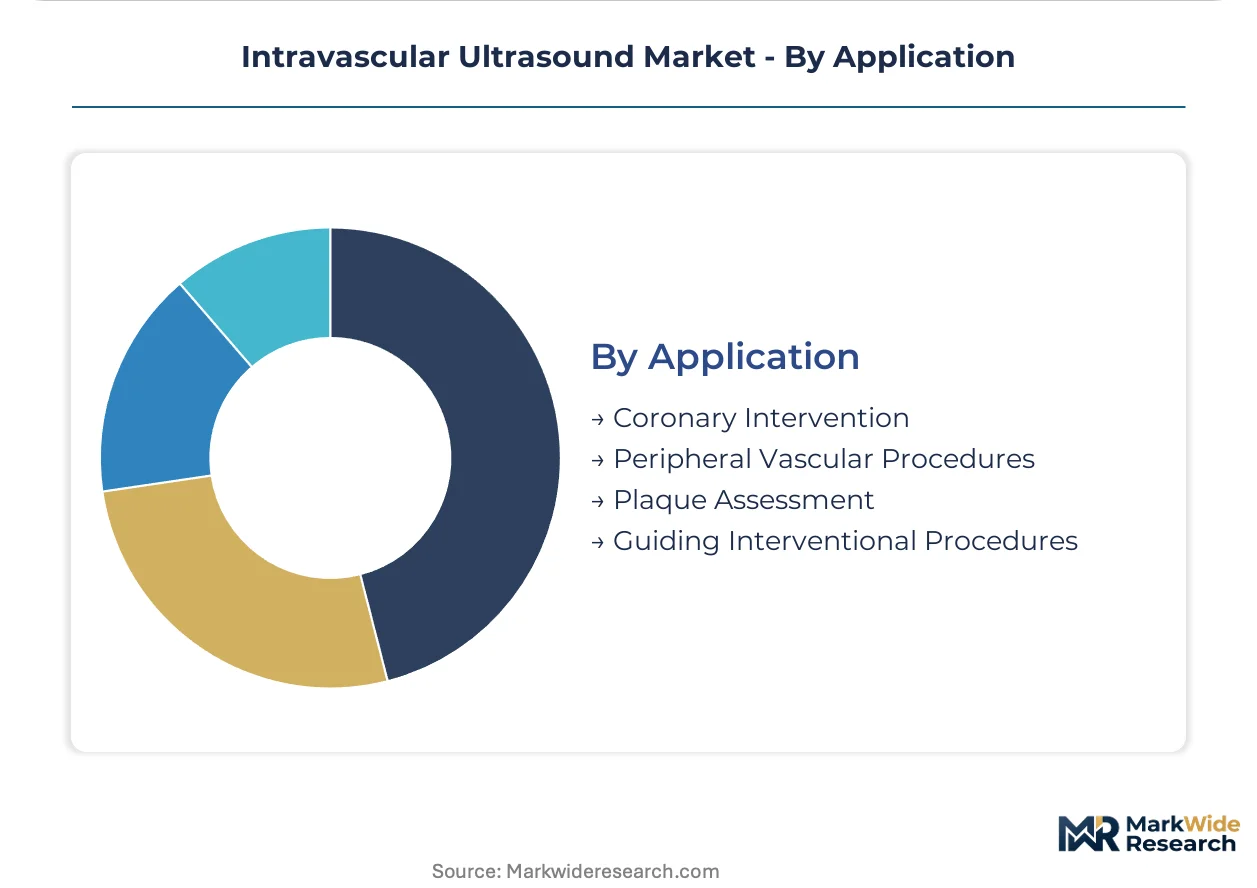
Application:
Clinical indication breadth determines catheter specification requirements and software feature prioritization across user sites.
- Coronary Intervention:Stent optimization and edge dissection detection dominate IVUS utilization. United States cath lab networks report highest per-procedure adoption rates in left main and bifurcation cases.
- Peripheral Vascular Procedures:Lower extremity and renal artery interventions leverage IVUS for calcification assessment. Procedure volume growth in outpatient settings is expanding fastest.
- Plaque Assessment:Pre-intervention characterization guides revascularization strategy selection. Research applications drive software feature development for automated tissue classification.
- Guiding Interventional Procedures:Real-time navigation support extends IVUS utility beyond stent placement. Atherectomy and thrombectomy guidance represent emerging utilization vectors.
Procedural volume anchors in Coronary Intervention. Expansion trajectory is steepest in Peripheral Vascular Procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors the densest concentration of IVUS-guided procedural networks, with United States integrated cath lab systems driving the majority of global installed base expansion through bundled capital equipment procurement.
United States
Academic medical centers in Boston and Cleveland scale physician training programs for 3D IVUS interpretation. FDA 510(k) streamlining accelerates catheter iteration cycles for domestic manufacturers. The Texas Medical Center corridor concentrates procedural volume growth in complex coronary interventions.
Germany
University hospitals in Munich and Heidelberg validate automated plaque characterization algorithms for clinical deployment. EU MDR biocompatibility documentation requirements filter procurement toward compliant device portfolios. The Rhine-Ruhr catheterization network leads European conversion from 2D to volumetric imaging systems.
Japan
Tokyo metropolitan cath labs maintain the highest per-capita IVUS utilization rates for left main bifurcation cases. PMDA clinical evidence requirements for indication expansions constrain non-domestic manufacturer market access. Osaka-based interventional cardiology centers drive hybrid IVUS-OCT platform adoption.
China
Shanghai and Beijing hospital networks expand IVUS-guided peripheral vascular procedures in outpatient settings. NMPA priority review timelines compress competitive sequencing for innovative catheter systems. The Yangtze River Delta region concentrates domestic manufacturing capacity for transducer components.
United Kingdom
NHS England integrated care systems negotiate bundled pricing for multimodality imaging suites across London and Manchester networks. MHRA post-Brexit regulatory alignment maintains CE-marking recognition for EU-manufactured devices. The Oxford-Cambridge corridor hosts histopathology validation studies for machine learning training datasets.
Intravascular Ultrasound Market Key Industry Players
Premium-margin players sit above commodity-margin players across software-enabled diagnostic tiers, with AI-integrated plaque characterization commanding subscription pricing multiples above disposable catheter revenue pools. The vendor base concentrates around multimodality imaging conglomerates with captive cath lab relationships, diversified cardiovascular device portfolios, and specialized catheter engineering boutiques. Three strategic archetypes dominate: integrated imaging platform owners, standalone IVUS technology specialists, and hybrid OCT-IVUS platform developers. Competitive moves center on firmware compatibility standardization for mixed-vendor environments and backward integration into transducer array manufacturing.
Among diversified cardiovascular technology conglomerates, Boston Scientific Corporation and Abbott Laboratories exemplify platform-integrated archetypes with multimodality imaging footprints. Koninklijke Philips N.V. anchors the European installed base tier through angiography system bundling. These three entities represent distinct geographic positioning strategies—American portfolio diversification, American hybrid-platform specialization, and Dutch capital equipment dominance—each occupying defensive positions against software-native diagnostic entrants.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Siemens Healthineers AG |
| Boston Scientific Corporation |
| Medtronic plc |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Terumo Corporation |
| Conavi Medical Inc. |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
EU MDR biocompatibility documentation mandates gate qualified supply access and premium-tier pricing power for catheter manufacturers serving European catheterization networks. Batch-level polymer traceability requirements elevate procurement costs for compliant vendors while filtering out non-certified competitors from high-margin contract tiers.
Pricing Analysis
Outcome-based pricing anchors IVUS catheter contracts, with reimbursement parity between IVUS-guided and angiography-only procedures determining cath lab willingness to pay premium tiers. Pricing stratifies across FDA 510(k)-cleared, CE-marked, and economy-grade configurations, with acoustic frequency bandwidth and transducer array density driving tier placement. Cost compression in standard-grade catheters is intensifying as Chinese domestic manufacturers expand NMPA-cleared production capacity. Outpatient surgical centers exhibit highest price sensitivity due to reimbursement coding constraints, while academic medical centers prioritize performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Minneapolis, Boston, and Cleveland anchor North American hub-and-spoke patterns for just-in-time catheter delivery to integrated cath lab networks. Transducer array manufacturing concentrates in Japan, the United States, and Germany, with piezoelectric crystal supply anchored in Chinese and Japanese material processing facilities. Single-source vulnerability in 40-60 MHz transducer design expertise limits R&D throughput for next-generation catheter development. Distribution runs through manufacturer-direct sales organizations serving hospital IDNs and specialized cardiovascular distributors reaching independent cardiac clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acoustic engineer talent scarcity props pricing power for qualified catheter manufacturers, constraining supply expansion despite accelerating procedural demand across integrated cath lab networks.
For Market Incumbents: Deploy backward integration into transducer array manufacturing to secure captive supply of 20-60 MHz piezoelectric components against Japanese and Chinese material processing bottlenecks. Fortify firmware compatibility layers for mixed-vendor angiography environments to defend installed base positions against hybrid OCT-IVUS platform substitution. Prioritize EU MDR certification maintenance to preserve European procurement access as biocompatibility documentation requirements tighten. For New Entrants and Emerging Players: Begin with software-enabled plaque characterization algorithms targeting United States outpatient surgical centers underserved by bundled capital equipment vendors. Peripheral vascular procedure expansion in Chinese and United States ambulatory settings offers the most penetrable white-space for catheter volume entry. Pursue NMPA priority review pathway qualification to compress competitive sequencing against established multimodality imaging conglomerates. For Investors and Strategic Acquirers: FDA 510(k) clearance streamlining announcements are the leading indicator that acoustic performance iteration cycles will accelerate, favoring R&D-capable mid-cap specialists over capital equipment bundlers. Five-to-ten year viability hinges on AI-integrated diagnostic software subscription retention rather than disposable catheter revenue pools. Target acquisition profiles should emphasize automated vessel measurement algorithm developers with histopathology-validated training datasets and established hospital system pilot contracts.| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Companion Development | Automated plaque characterization algorithms command subscription pricing multiples above hardware revenue pools. |
| CE Marking Pathway Investment | EU MDR biocompatibility documentation requirements filter procurement toward compliant device portfolios. |
| Hospital System Partnership | Bundled capital equipment procurement locks in supply continuity across United States integrated delivery networks. |
| Reimbursement Strategy Execution | Coding parity between IVUS-guided and angiography-only procedures determines cath lab capital allocation cycles. |
| 3D Imaging Module Launch | Volumetric reconstruction capabilities displace 2D systems in high-volume academic medical centers. |
Research Approach
Multi-period observation of FDA 510(k) clearance timelines, NMPA priority review outcomes, and cath lab capital expenditure patterns anchored the trend analysis, supplemented by interviews with interventional cardiologists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from FDA premarket notification databases, EU MDR technical documentation filings, CMS Medicare procedure coding records, and hospital procurement database extracts. Bottom-up catheter shipment modeling triangulated against top-down cath lab installed base estimates.
Input-output matrices mapped transducer frequency specifications, software feature tiers, and end-user facility types across the projection horizon. Segmentation dimensions included product type, technology modality, application indication, and geographic regulatory cluster. CAGRs were derived from procedure volume elasticity modeling and capital equipment replacement cycle analysis. Forecast inputs incorporated reimbursement coding parity assumptions and EU MDR compliance transition timelines.
Underlying measurement precision varies by segment; catheter shipment volumes carry tighter precision than software subscription forecasts due to distributor reporting granularity. Outputs reflect documented assumptions regarding regulatory pathway efficiency and reimbursement stability. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that PMDA clinical evidence requirement shifts or optical coherence tomography technology breakthroughs could materially revise trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiovascular Needle Market
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market
Cardiovascular Devices
Patient-Controlled Injectors Market
Cardiovascular Devices
Iliac Artery Stents Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
Global Artificial Heart Market
Cardiovascular Devices
Global Vascular Graft Market
Cardiovascular Devices
Ventricular Drainage Sets Market
Cardiovascular Devices
Australia Cardiovascular Devices Market
Cardiovascular Devices
Venous Reservoirs Market
Cardiovascular Devices
Global Drug Eluting Balloon Catheters Market
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market
Cardiovascular Devices
Global Cardiac Resynchronization Therapy Market
Cardiovascular Devices
Spain Cardiovascular Devices Market
Cardiovascular Devices
Transcatheter Market