
 US Thrombectomy Devices Market | 2026-2036
US Thrombectomy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
US Thrombectomy Devices Market Insights
Hospital purchasing for thrombectomy systems is hardening around integrated stroke networks that bundle device procurement with physician training and outcome guarantees. Medtronic leverages its neurovascular portfolio to dominate catheter-based clot retrieval across major academic medical centers. Stryker sustains competitive pressure through its Trevo platform and dedicated stroke care sales infrastructure. Penumbra anchors its position in aspiration-first workflows with specialized interventional neuroradiology relationships.
Thrombectomy devices are interventional instruments designed to mechanically remove or dissolve blood clots from occluded vessels, typically incorporating aspiration lumens ranging from 0.054 to 0.088 inches or stent-retriever configurations with radial force optimized for fibrin engagement. These systems restore perfusion in acute ischemic stroke, deep vein thrombosis, and coronary occlusion procedures where pharmacological lysis contraindications exist. Automated aspiration systems lead installed base metrics due to reproducible vacuum pressure protocols and reduced operator variability in clot engagement. Mechanical devices retain the largest revenue share in cerebral thrombectomy applications where stent-retriever technology commands premium positioning against first-generation aspiration alternatives. Robotic-assisted devices represent the fastest-growing technology segment as procedural standardization demands drive capital investment in telemanipulation platforms.
FDA 510(k) premarket notification requirements and ISO 13485 quality management standards govern device commercialization, with FDA breakthrough device designations accelerating review timelines for technologies demonstrating substantial equivalence with enhanced safety profiles. The Centers for Medicare & Medicaid Services (CMS) reimbursement codes for mechanical thrombectomy procedures directly influence hospital capital allocation and device adoption velocity across stroke center tiers. Stakeholders must monitor evolving CMS site-of-service payment differentials and state-level stroke system certification requirements that reshape device procurement criteria.
Market Dynamics
Integrated stroke center networks across Texas and Florida are consolidating device procurement around outcome-guaranteed bundles, compressing vendor selection cycles and elevating physician training partnerships to parity with device specifications.
Growth Catalysts
- CMS Reimbursement Codes:Medicare coverage for mechanical thrombectomy procedures drives hospital capital allocation toward comprehensive stroke center certification. Academic medical centers in the Midwest accelerate device adoption to capture eligible patient flows.
- Aspiration Catheter Innovation:Next-generation lumens ranging from 0.054 to 0.088 inches enable faster clot engagement with reduced operator variability. FDA 510(k) clearance pathways shorten time-to-market for device iterations.
- Stroke System Certification:State-level requirements in the Southeast reshape procurement criteria toward devices with proven workflow integration. Hospital systems prioritize technologies that satisfy Joint Commission stroke center standards.
Market Restraints
- Capital Equipment Intensity:Robotic-assisted thrombectomy platforms require substantial upfront investment in telemanipulation infrastructure. Community hospitals face constrained budgets for stroke program expansion.
- Specialized Workforce Scarcity:Interventional neuroradiologists and neurovascular surgeons concentrate in academic medical centers. Rural and suburban facilities struggle to recruit operators qualified for mechanical thrombectomy.
- Reimbursement Compression:Site-of-service payment differentials between comprehensive and primary stroke centers limit device utilization in lower-tier facilities. CMS rate adjustments create margin pressure across hospital systems.
Strategic Opportunities
- Telestroke Network Expansion:Hub-and-spoke models connecting rural hospitals to urban comprehensive centers create demand for portable aspiration systems. Texas and Florida networks actively seek devices compatible with telerobotic consultation.
- Peripheral Vascular Extension:Deep vein thrombosis applications represent underpenetrated territory for stent-retriever technology. Device manufacturers can leverage cerebral thrombectomy expertise into venous intervention workflows.
- Automated Aspiration Protocols:Reproducible vacuum pressure systems reduce operator learning curves and expand treatable patient populations. Standardized workflows align with Joint Commission quality metrics for stroke care.
Industry Challenges
- Interventional Neuroradiology Training Pipeline:Fellowship programs produce insufficient operators to match expanding stroke center networks. Academic medical centers compete aggressively for qualified specialists.
- ISO 13485 Compliance Burden:Quality management system maintenance demands sustained documentation investment. Smaller device manufacturers face resource constraints for regulatory surveillance.
- Legacy Device Integration:New aspiration-first workflows require retraining staff accustomed to stent-retriever protocols. Hospital systems hesitate to disrupt established procedural routines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Thrombectomy Devices Market |
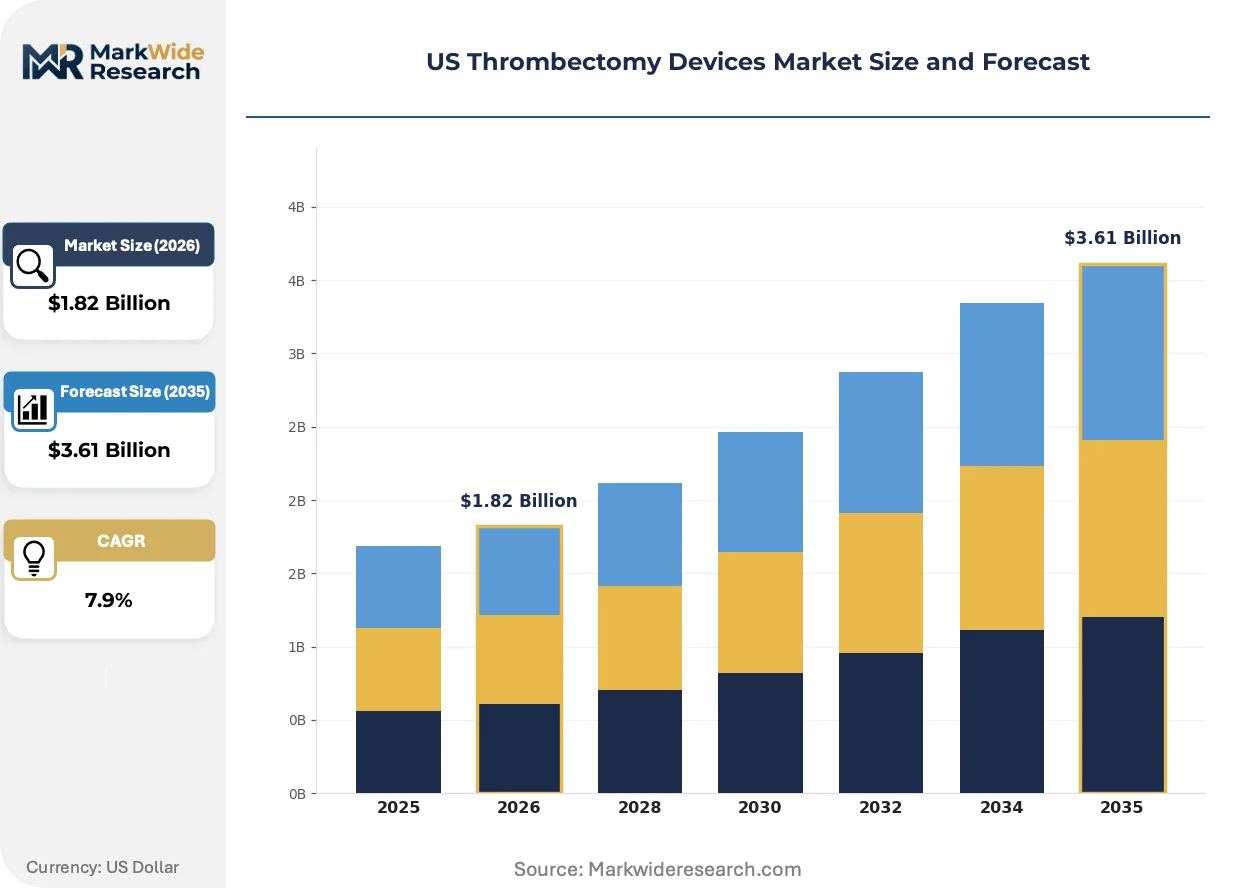
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.61 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Devices, Automated Devices, Surgical Instruments, Catheters End User: Hospitals, Ambulatory Surgical Centers, Emergency Departments, Clinics Technology: Mechanical Devices, Aspiration Systems, Combination Therapies, Robotic-Assisted Devices Application: Cerebral Thrombectomy, Peripheral Thrombectomy, Coronary Thrombectomy, Venous Thrombectomy |
| Companies Covered | Medtronic, Stryker, Penumbra, Johnson & Johnson, Terumo Corporation, Boston Scientific Corporation, Teleflex Incorporated, Koninklijke Philips, AngioDynamics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Thrombectomy Devices Market Trends and Innovations
Device architecture and care delivery models are simultaneously evolving as aspiration-first workflows challenge established stent-retriever dominance and reimbursement incentives reward procedural standardization.
Artificial intelligence-powered imaging analysis is converging with real-time clot characterization to guide catheter selection and aspiration pressure optimization. Comprehensive stroke centers in the Southeast deploy these systems to reduce door-to-puncture times. The technology is converging with automated aspiration platforms to compress variability in operator decision-making and elevate consistency in clinical outcomes.
FDA breakthrough device designations are accelerating review timelines for thrombectomy technologies demonstrating substantial equivalence with enhanced safety profiles. The pathway compresses commercialization cycles for next-generation aspiration catheters. Academic medical centers prioritize devices with breakthrough status in capital planning to secure competitive positioning in stroke center rankings.
Hospital purchasing committees now bundle device procurement with mandatory physician training and outcome reporting requirements. Integrated delivery networks in the Midwest displace traditional distributor relationships with direct manufacturer partnerships. This concentration is most visible in Texas and Florida stroke center networks where volume guarantees determine vendor selection.
US Thrombectomy Devices Market Segmentation
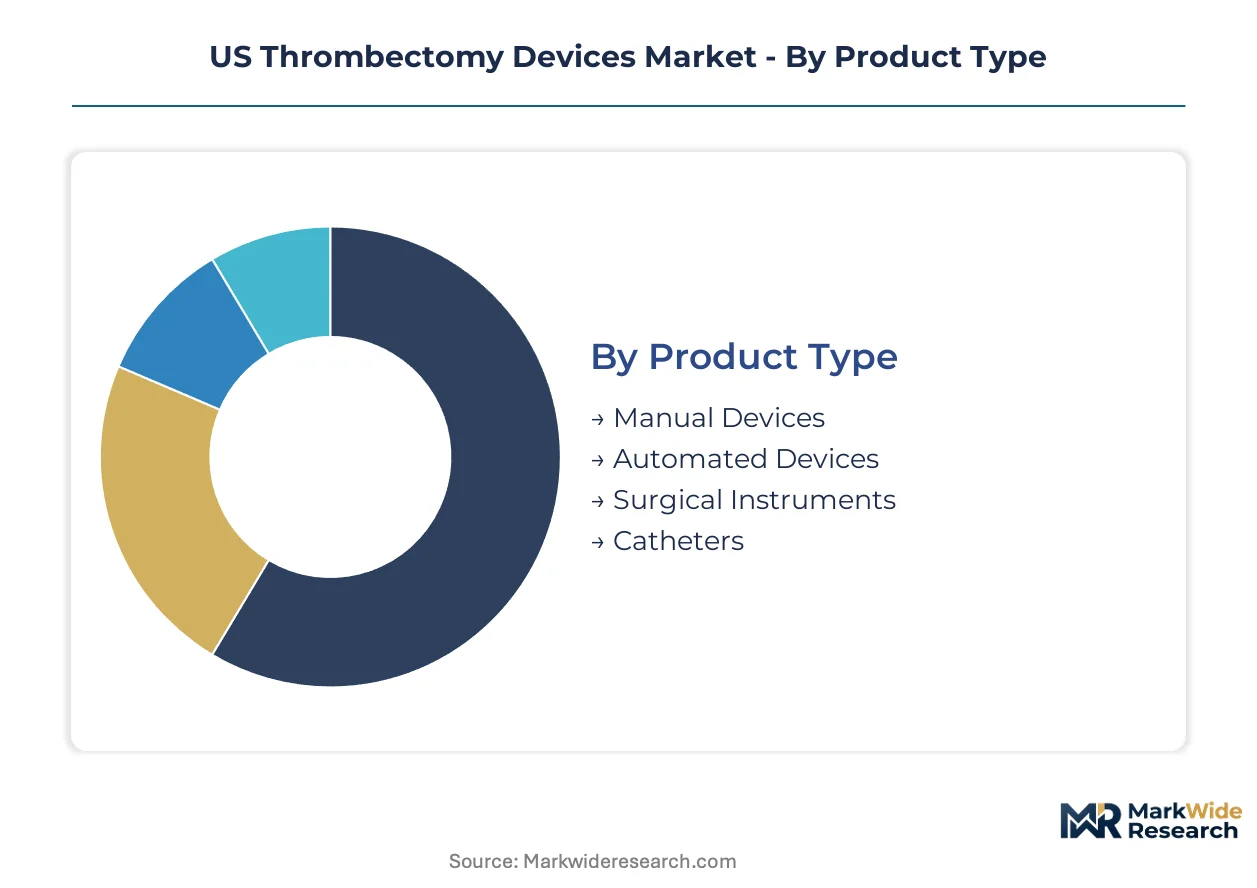
Thrombectomy device segmentation reveals how capital allocation, regulatory pathways, and clinical workflow requirements fragment procurement decisions across US hospital systems. Product architecture and end-user infrastructure constraints create distinct competitive battlegrounds that vendors must navigate simultaneously.
Product Type:
Capital intensity varies sharply across this category, with automated platforms demanding telemanipulation infrastructure investments that manual alternatives avoid entirely.
- Manual Devices:Hand-operated aspiration syringes and retrieval sheaths deliver clot extraction through direct physician control without powered vacuum systems. Demand clusters in emergency departments across rural Texas and Florida networks where capital budgets constrain robotic acquisition.
- Automated Devices:Reproducible vacuum pressure protocols reduce operator variability through calibrated aspiration engines and real-time pressure monitoring. Comprehensive stroke centers in the Midwest prioritize these systems to satisfy Joint Commission quality metrics and standardize door-to-puncture workflows.
- Surgical Instruments:Open surgical embolectomy tools and vascular clamps address cases where percutaneous access fails or anatomical complexity demands direct vessel exposure.
- Catheters:Aspiration lumens ranging from 0.054 to 0.088 inches enable navigable clot engagement across tortuous cerebral vasculature.
Automated devices absorb the bulk of installed capacity; catheters are expanding most quickly as aspiration-first protocols displace stent-retriever workflows.
End User:
Procurement authority concentrates differently across this dimension, with integrated delivery networks centralizing purchasing for hospital systems while emergency departments retain discretionary capital for point-of-care systems.
- Hospitals:Comprehensive stroke centers anchor device demand through mechanical thrombectomy program certification requirements. Academic medical centers in the Southeast leverage CMS reimbursement codes to justify capital allocation for next-generation aspiration platforms.
- Emergency Departments:Front-line stroke diagnosis and stabilization create demand for portable aspiration systems compatible with rapid transfer protocols. Hub-and-spoke networks in Texas actively deploy these units to extend thrombectomy access before patient transport.
- Ambulatory Surgical Centers:Limited procedural volume and reimbursement constraints restrict thrombectomy device adoption to select peripheral vascular interventions.
- Clinics:Diagnostic and referral functions predominate; direct thrombectomy capacity remains minimal outside specialized interventional suites.
Hospitals command the dominant share of capital deployment; emergency departments are gaining share fastest as pre-hospital stroke networks mature.
Technology:
Margin profiles diverge substantially here, with robotic-assisted platforms capturing premium pricing against commoditized mechanical alternatives while aspiration systems occupy a defendable mid-tier.
- Mechanical Devices:Stent-retriever technology employs radial force optimization for fibrin engagement and controlled clot extraction through deployed mesh structures. Cerebral applications sustain revenue concentration despite aspiration-first workflow displacement in comprehensive stroke centers.
- Robotic-Assisted Devices:Telemanipulation platforms enable remote procedural execution and standardized catheter control across operator experience levels. FDA breakthrough device designations accelerate review timelines for systems demonstrating enhanced safety profiles in academic medical center trials.
- Aspiration Systems:Direct suction thrombectomy through large-bore catheters challenges stent-retriever dominance with faster procedural times and reduced distal embolization risk.
- Combination Therapies:Sequential or simultaneous deployment of aspiration and stent-retriever techniques addresses refractory clot burdens.
Mechanical devices retain the largest revenue base; robotic-assisted platforms are climbing the fastest as procedural standardization demands intensify.
Application:
Volume concentration and pricing power separate unevenly across clinical domains, with cerebral procedures commanding premium device positioning against underpenetrated peripheral and venous territories.
- Cerebral Thrombectomy:Acute ischemic stroke intervention drives the majority of device innovation and regulatory investment. State-level stroke system certification requirements in Florida and Texas reshape procurement toward technologies with proven workflow integration and outcome reporting capabilities.
- Peripheral Thrombectomy:Deep vein thrombosis and arterial occlusion applications represent expansion territory for aspiration catheter technology originally developed for neurovascular use. Limb salvage protocols in Midwest hospital systems generate incremental demand as interventional radiology capabilities extend.
- Coronary Thrombectomy:Myocardial infarction applications compete with established percutaneous coronary intervention device ecosystems.
- Venous Thrombectomy:Pulmonary embolism and iliofemoral DVT interventions remain technologically underserved relative to arterial applications.
Cerebral thrombectomy dominates current revenue composition; peripheral thrombectomy is gaining share fastest as venous intervention workflows mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US thrombectomy device demand concentrates in comprehensive stroke centers across the Midwest and Southeast, with Texas and Florida networks driving procurement consolidation through outcome-guaranteed bundles.
Texas
Hub-and-spoke stroke networks in Houston and Dallas-Fort Worth expand mechanical thrombectomy access to rural catchments. FDA 510(k) clearance pathways accelerate device deployment across state-designated comprehensive centers. The Texas Medical Center anchors clinical trial activity for next-generation aspiration catheters.
Florida
State-level stroke system certification requirements reshape procurement toward workflow-integrated technologies. Joint Commission standards drive hospital capital allocation in Tampa and Miami metropolitan clusters. Academic medical centers in Jacksonville prioritize devices with proven door-to-puncture time reduction.
Midwest
Illinois and Michigan hospital systems leverage CMS reimbursement codes to justify robotic-assisted platform investments. The Cleveland Clinic and Mayo Clinic networks influence device selection criteria across neighboring states. Chicago-area integrated delivery networks consolidate purchasing around physician training partnerships.
Southeast
Georgia and North Carolina stroke centers compete for comprehensive certification to capture eligible patient flows. CMS site-of-service payment differentials concentrate device utilization in Atlanta and Charlotte academic hubs. Regional networks seek portable aspiration systems compatible with telestroke consultation.
US Thrombectomy Devices Market Competitive Landscape
US-based producers anchor the premium tier; European and Japanese specialists hold positions in complementary technology segments. The vendor base concentrates around three dominant archetypes: diversified medical technology conglomerates with neurovascular portfolios, dedicated interventional device specialists, and diversified healthcare conglomerates with cardiovascular franchises. Competitive moves center on outcome-based contracting with integrated delivery networks and regulatory pathway optimization for FDA breakthrough device designations.
Within the diversified medical technology tier, Medtronic and Stryker exemplify scale-driven positioning through comprehensive stroke care portfolios. Penumbra occupies a specialist position focused on aspiration-first workflow technologies. These three entities represent distinct strategic archetypes: full-spectrum neurovascular platform providers, integrated stroke system solution vendors, and interventional neuroradiology-focused device developers.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Penumbra |
| Johnson & Johnson |
| Terumo Corporation |
| Boston Scientific Corporation |
| Teleflex Incorporated |
| Koninklijke Philips |
| AngioDynamics |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up device specialists now dominate catheter manufacturing capacity, compressing vendor margins through volume consolidation while simultaneously elevating pricing discipline among ISO 13485-certified producers who can absorb regulatory audit costs.
Pricing Analysis
High-volume aspiration catheters trade at compressed margins against low-volume robotic platforms that capture premium positioning. Pricing stratifies across FDA breakthrough-designated, standard 510(k)-cleared, and economy manual device tiers, with certification level and after-sales training bundling as primary differentiation levers. Cost compression in the manual device tier is intensifying because integrated stroke networks in Texas and Florida consolidate procurement around outcome guarantees. Community hospitals exhibit highest price sensitivity; academic medical centers prioritize workflow integration over unit cost.
Supply Chain Analysis
Freight cost volatility for nitinol wire and polymer catheter substrates has compressed just-in-time inventory strategies across domestic assembly operations. Manufacturing draws from Japan for precision hypotube components, Ireland for catheter extrusion, and domestic US facilities for final device assembly and sterilization. Single-source vulnerability concentrates in laser-cut stent-retriever mesh supply. Distribution runs through specialized neurovascular distributors and direct manufacturer partnerships with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
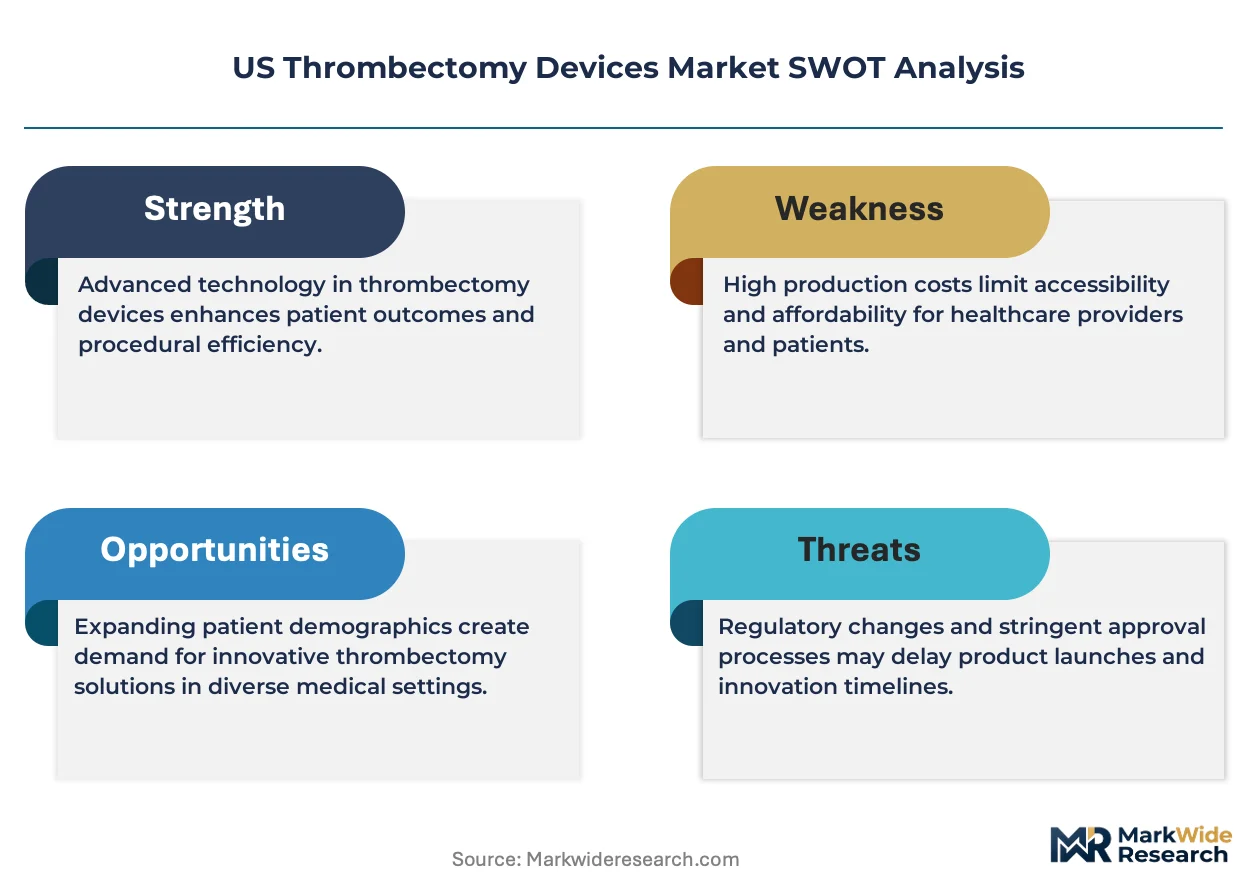
FDA 510(k) clearance pathways and ISO 13485 quality management requirements create a cost-of-compliance moat that favors scaled incumbents with dedicated regulatory affairs infrastructure over undercapitalized entrants.
For Market Incumbents: Anticipate reimbursement compression from CMS site-of-service payment differentials by deepening physician training partnerships that lock in stroke center loyalty. Prioritize backward integration into catheter extrusion capacity to defend margin position against polymer cost volatility. Counter robotic-assisted device entrants through accelerated FDA breakthrough designations for next-generation aspiration platforms. For New Entrants and Emerging Players: Begin with portable aspiration systems for emergency departments in rural Texas and Florida hub-and-spoke networks, the most penetrable white space underserved by capital-intensive robotic platforms. Target peripheral venous thrombectomy applications where stent-retriever technology remains underdeployed. Pursue direct GPO contracting as the primary go-to-market channel to bypass established distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor aspiration-first technology specialists with established interventional neuroradiology relationships in the Midwest, where stroke center certification demands are accelerating capital deployment. Long-term viability hinges on reimbursement strategy execution and FDA regulatory pathway velocity. Monitor CMS mechanical thrombectomy coverage determinations as the critical inflection signal for valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates review timelines for aspiration catheters demonstrating enhanced safety profiles in academic trials. |
| Hospital System Partnership | Bundles device procurement with mandatory physician training and outcome reporting across Texas stroke networks. |
| Backward Integration into Extrusion | Captures polymer catheter substrate production to mitigate freight cost volatility and supply disruption. |
| Reimbursement Strategy | Aligns CMS mechanical thrombectomy code utilization with comprehensive stroke center certification requirements. |
| Software Companion Development | Integrates AI-powered imaging analysis with automated aspiration platforms to reduce door-to-puncture variability. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, GPO contract databases, and FDA 510(k) filing records underwrites the qualitative findings. Primary fieldwork engaged interventional neuroradiologists, biomedical engineers, stroke program directors, and GPO contracts managers across Midwest and Southeast hospital systems. Secondary validation drew from CMS Medicare reimbursement data, Joint Commission stroke center certification records, and hospital procurement disclosures. Bottom-up device shipment estimates triangulate against top-down stroke center capacity modeling.
Comparable-period anchoring to historical mechanical thrombectomy procedure volumes and installed base metrics structures the projection framework across the analysis window. Segmentation dimensions encompass product architecture, end-user infrastructure tier, technology modality, and clinical application area. CAGRs derive from logistic diffusion curves fitted to stroke center certification trajectories and CMS reimbursement elasticity estimates. Forecast inputs incorporate state-level stroke system mandates and interventionalist training pipeline constraints.
Underlying measurement precision varies by segment; comprehensive stroke center device procurement carries tighter precision than emergency department point-of-care estimates. Forecasts incorporate assumptions regarding CMS coverage stability and FDA review timeline consistency that regulatory shifts could revise. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intravascular Warming Systems Market
Medical Devices
Pulse Lavage Market
Medical Devices
Baby Warmer Devices Market
Medical Devices
Ultrasonic Skin Care Devices Market
Medical Devices
Morcellators Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Left Atrial Appendage Devices Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Global Syringe Pumps Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market
Medical Devices
Neurofeedback Systems Market
Medical Devices
Walking Aids Market
Medical Devices
Asia Pacific Hearing Aids Market
Medical Devices
Liquid Oxygen Devices Market
Medical Devices
Cholecystectomy Devices Market
Medical Devices
Global Artificial Organ Market