
 Cardiovascular Needle Market | 2026-2036
Cardiovascular Needle Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiovascular Needle Market Analysis
Buyer consolidation among hospital procurement networks is recalibrating how cardiovascular needle suppliers negotiate volume contracts. Medtronic leverages its integrated surgical portfolio to secure multi-year supply agreements with large health systems. B. Braun Melsungen AG anchors European distribution through specialized cardiac surgery channels. Johnson & Johnson competes on suture-needle bundling that reduces per-procedure costs for integrated delivery networks.
Cardiovascular needles are precision-engineered penetrating instruments, typically fabricated from surgical-grade stainless steel with siliconized or polymer coatings to minimize tissue trauma during cardiac and vascular procedures. Suture needles dominate current volume due to their ubiquity in open-heart surgery, while safety needles represent the fastest-expanding category as sharps-injury regulations tighten across operating rooms. Catheter needles command premium positioning within interventional cardiology suites where radial access procedures require specialized bevel geometries. Stainless steel formulations retain the largest material share, though coated variants capture margin pools in high-end cardiac surgery applications.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and commercialization costs for cardiovascular needle manufacturers. ISO 7864 standards govern needle performance testing, while OSHA bloodborne pathogen rules directly accelerate safety needle conversion in US hospital settings. Stakeholders must monitor how evolving MDR notified body capacity constraints and FDA quality system inspection priorities reshape competitive access timelines for new entrants.
Market Dynamics
Cardiovascular needle procurement is consolidating around integrated delivery networks that demand multi-year volume commitments in exchange for sole-source or dual-source supplier status. This structural concentration is compressing margins for manufacturers while elevating the strategic value of surgical portfolio breadth.
Growth Catalysts
- EU MDR implementation:Stricter technical documentation requirements for Class IIa surgical devices are accelerating hospital replacement cycles for legacy needle inventories across German and French cardiac centers.
- Radial access expansion:Transradial catheterization protocols now dominate interventional cardiology suites in the United States and Japan, generating specialized demand for micro-bevel catheter needles with enhanced torque response.
- Siliconized coatings:Polymer surface treatments that reduce tissue drag and suture pull-through resistance are penetrating high-volume coronary artery bypass procedures.
Market Restraints
- Raw material concentration:Surgical-grade 300-series stainless steel supply concentrates among a limited cohort of European and Japanese specialty mills, exposing manufacturers to alloy pricing volatility.
- Notified body capacity:EU MDR technical file review queues at designated conformity assessment organizations are extending product certification timelines by 12-18 months for new cardiovascular needle submissions.
- Safety needle conversion costs:OSHA bloodborne pathogen compliance mandates require capital-intensive retooling of production lines to manufacture retractable or shielded needle mechanisms.
Strategic Opportunities
- Indian cardiac surgery expansion:Greenfield hospital construction in Mumbai, Chennai, and Delhi-NCR is creating first-mover advantage for suppliers establishing direct distribution to private cardiac institutes.
- Bioresorbable polymer convergence:Integration of polylactic acid and polyglycolic acid formulations with precision needle delivery systems enables single-procedure implantable suture-needle combinations.
- Centralized procurement platforms:Group purchasing organizations in the United States are consolidating cardiovascular device sourcing, creating channel access for manufacturers with integrated suture-needle portfolios.
Industry Challenges
- Regulatory talent scarcity:Qualified EU MDR technical documentation specialists and FDA 510(k) submission consultants command premium compensation, constraining mid-tier manufacturer expansion capacity.
- Legacy sterilization validation:Ethylene oxide alternative qualification for needle packaging requires extensive bioburden testing cycles that delay product line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular Needle Market |
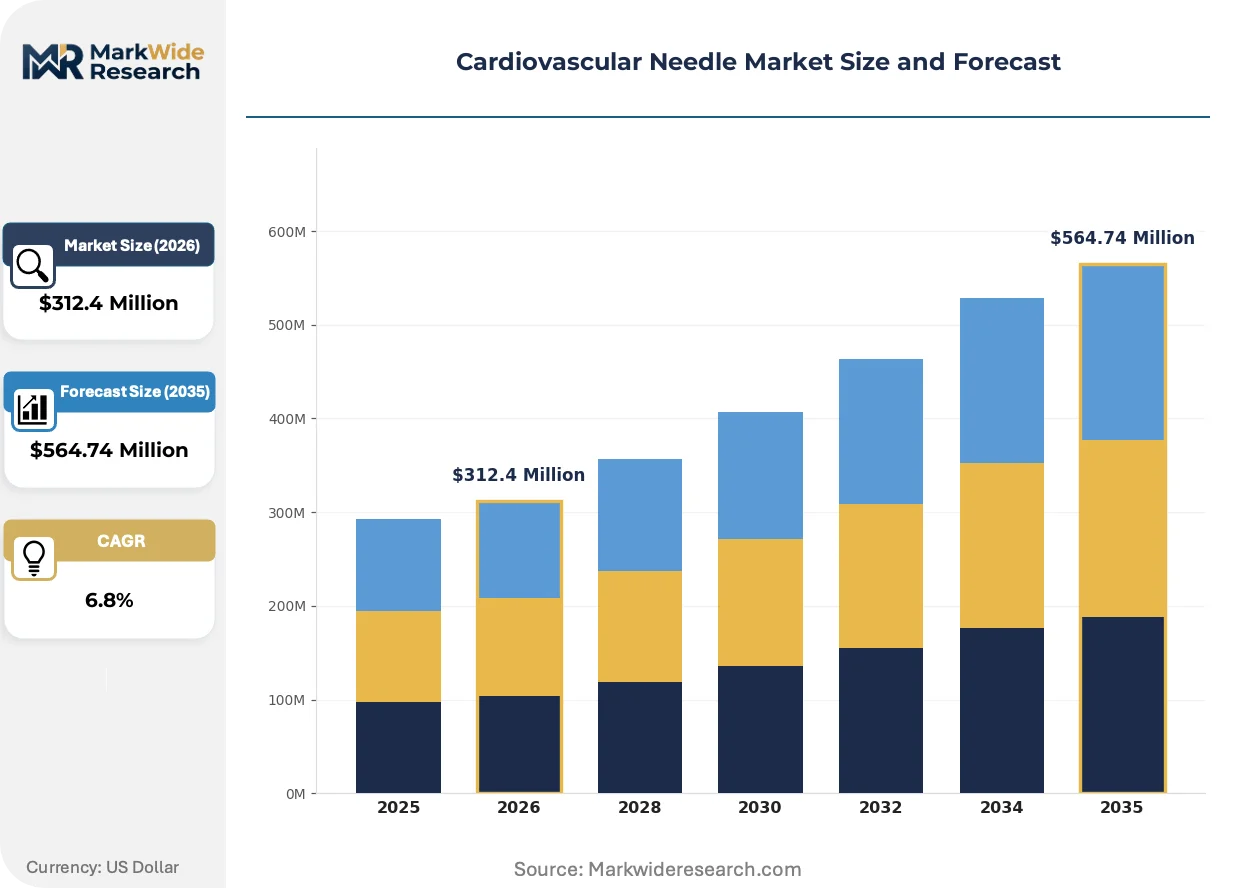
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy Needles, Catheter Needles, Suture Needles, Safety Needles Application: Cardiac Surgery, Diagnostic Procedures, Interventional Procedures, Vascular Access End User: Hospitals, Clinics, Diagnostic Labs, Surgical Centers Material: Stainless Steel, Plastic, Coated Blades, Surgical Grade |
| Companies Covered | Medtronic, Johnson & Johnson, Boston Scientific, B. Braun Melsungen AG, Becton, Dickinson and Company, Abbott Laboratories, Teleflex Incorporated, Cardinal Health, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular Needle Market Emerging Trajectories
Active coating technologies and automated inspection systems are compressing the performance gap between commodity and premium cardiovascular needle tiers. These innovations are simultaneously elevating baseline quality expectations and challenging traditional premium positioning strategies.
Siliconized and polymer-coated needle surfaces are consolidating market preference across open-heart and minimally invasive cardiac procedures. Academic medical centers in the United States and university hospitals in Germany are standardizing on coated variants for all coronary artery bypass grafting. This technology is consolidating procurement specifications around surface friction coefficients and penetration force consistency metrics that coated products reliably deliver.
EU MDR Article 10 technical documentation requirements and FDA quality system regulation inspections are reshaping competitive access timelines for cardiovascular needle manufacturers. The notified body capacity crunch in Europe is forcing manufacturers to front-load clinical evaluation resources. Small-to-mid tier suppliers are responding by consolidating regulatory affairs functions and outsourcing post-market surveillance to specialized consultancies.
Hospital procurement committees are unbundling suture and needle sourcing decisions that were historically locked in bundled contracts. Integrated delivery networks in the United States are establishing separate category managers for penetrating instruments and closure materials. This pattern is most visible in Texas and Florida health systems where cardiac surgery volumes justify dedicated needle sourcing analysis.
Cardiovascular Needle Market Segmentation
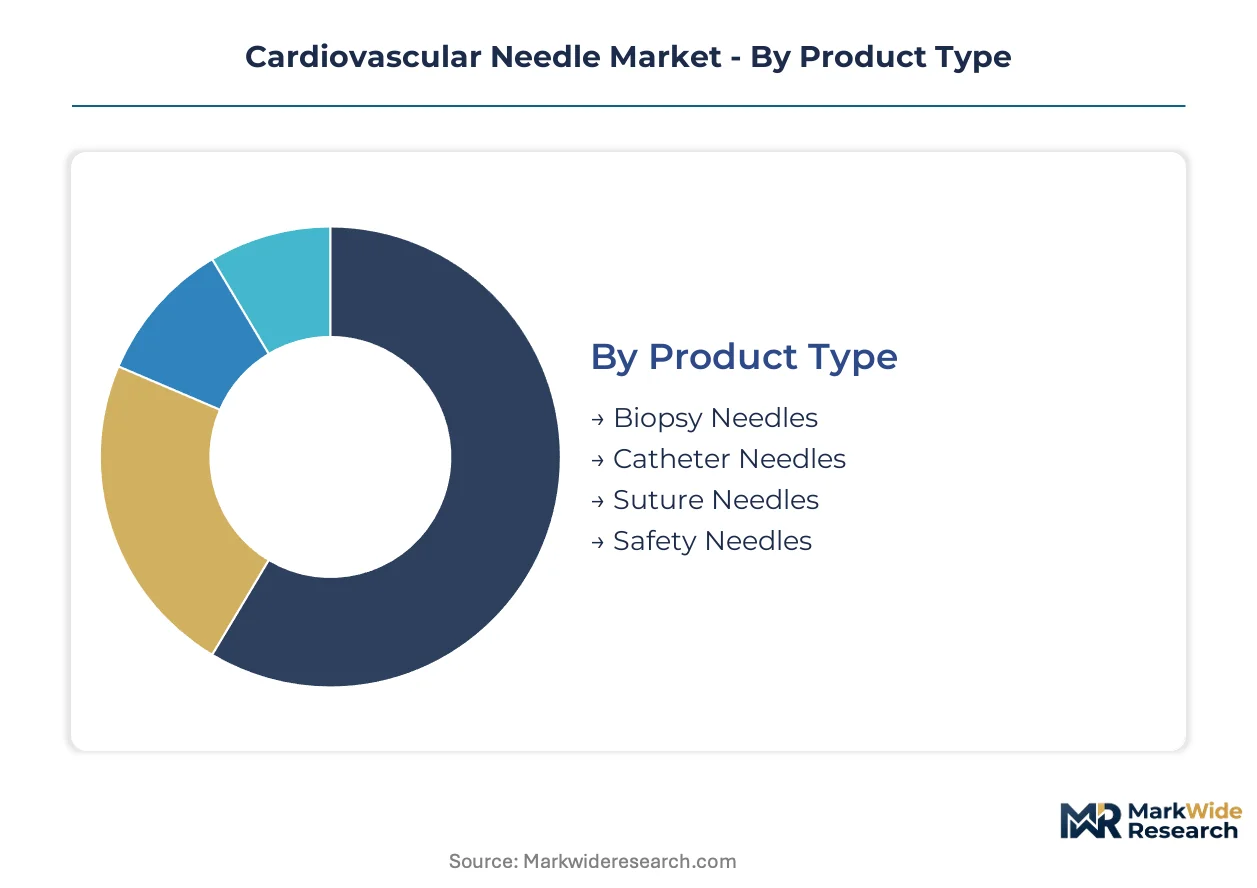
Cardiovascular needle procurement operates through distinct technical and commercial lenses. Surgeons prioritize penetration geometry and coating performance; procurement committees weigh volume economics against safety compliance mandates.
Product Type:
Hospital procurement committees segment their sourcing strategies by procedural risk tier and regulatory exposure.
- Suture Needles:These precision-curved instruments dominate open-heart surgery suites, typically fabricated from surgical-grade stainless steel with siliconized coatings to minimize tissue drag. Demand concentrates in coronary artery bypass grafting procedures across German and United States cardiac centers, where procedure volumes sustain high-volume contracting.
- Safety Needles:Retractable and shielded mechanisms address OSHA bloodborne pathogen compliance in US operating rooms. These devices command price premiums but eliminate sharps-injury liability exposure that drives hospital risk management priorities.
- Catheter Needles:Micro-bevel geometries engineered for radial access procedures in interventional cardiology suites.
- Biopsy Needles:Specialized cutting edges for myocardial tissue sampling in diagnostic cardiac catheterization labs.
Volume sits with suture needles; growth tilts toward safety needles.
Application:
Procedure complexity determines needle specification requirements and supplier qualification thresholds.
- Cardiac Surgery:Sternotomy and minimally invasive approaches demand precision penetration instruments with consistent force profiles. German university hospitals and US academic medical centers standardize on coated variants for all coronary artery bypass grafting, establishing specification benchmarks that diffuse through teaching hospital networks.
- Interventional Procedures:Transradial catheterization protocols now dominate cardiology suites in Japan and the United States, generating specialized demand for torque-responsive catheter needles with enhanced bevel geometries that navigate radial artery tortuosity.
- Vascular Access:Central line placement and peripheral access procedures in emergency departments and intensive care units.
- Diagnostic Procedures:Electrophysiology studies and cardiac biopsy protocols requiring precision tissue acquisition.
Revenue concentrates in cardiac surgery; interventional procedures are climbing the fastest.
End User:
Capital intensity and case mix shape procurement authority and vendor relationship structures.
- Hospitals:Integrated delivery networks in Texas and Florida consolidate cardiovascular device sourcing through dedicated category managers, unbundling historical suture-needle contracts to optimize penetrating instrument economics separately from closure materials.
- Surgical Centers:Ambulatory cardiac facilities concentrate on high-volume, low-acuity procedures where disposable safety needles reduce regulatory compliance overhead.
- Clinics:Cardiology group practices performing diagnostic catheterization and pacemaker implantation.
- Diagnostic Labs:Independent cardiac imaging and electrophysiology testing facilities.
Procurement authority rests with hospitals; surgical centers are gaining share fastest.
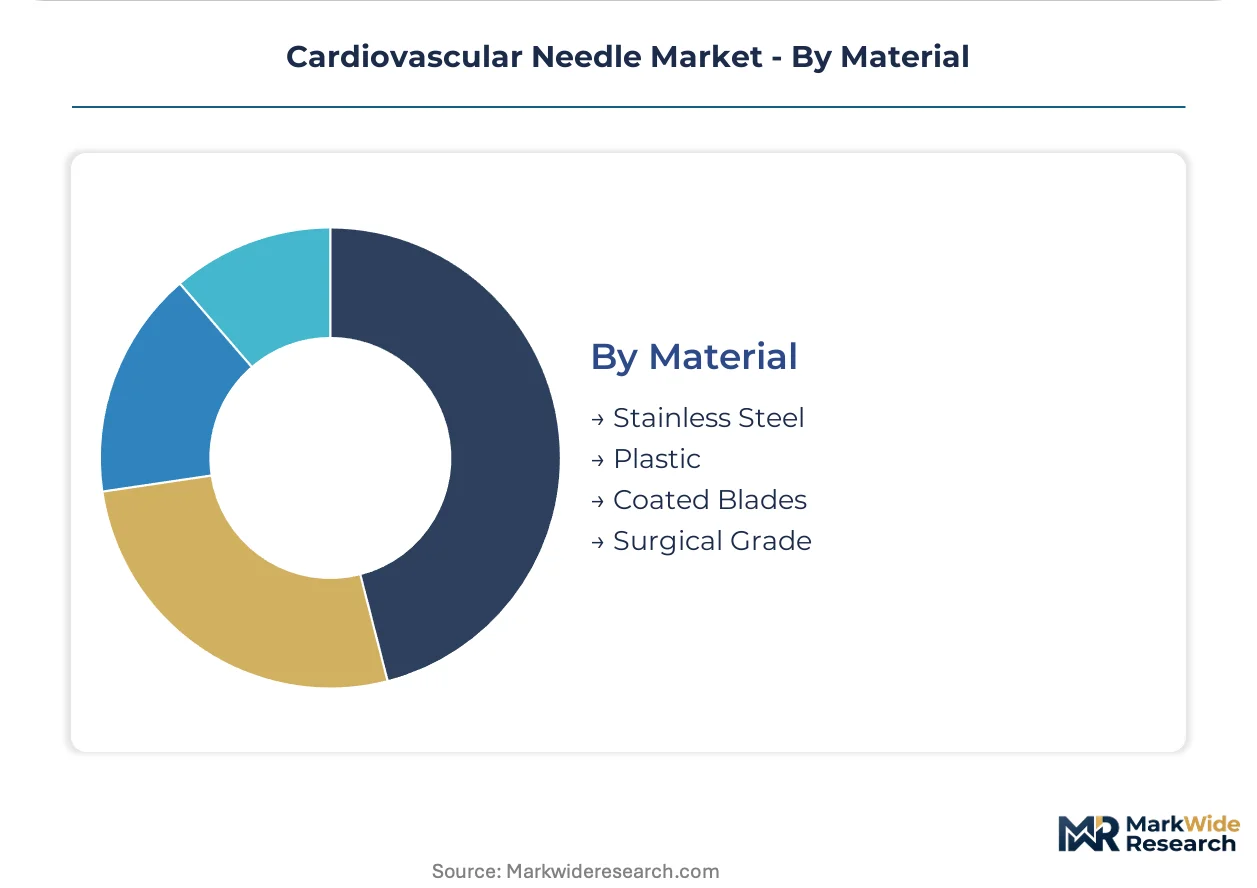
Material:
Raw material specifications cascade through manufacturing cost structures and sterilization validation requirements.
- Stainless Steel:Surgical-grade 300-series formulations retain the largest volume share due to established supply chains from European and Japanese specialty mills. Alloy pricing volatility concentrates manufacturing risk among producers dependent on concentrated raw material sourcing.
- Coated Blades:Polymer and siliconized surface treatments reduce penetration force and suture pull-through resistance. These variants penetrate high-end cardiac surgery applications where academic medical centers standardize on friction coefficient specifications.
- Plastic:Disposable safety mechanisms and needle shields molded from medical-grade polymers.
- Surgical Grade:Enhanced alloy formulations meeting ISO 7864 performance testing standards for critical cardiac applications.
Stainless steel anchors volume; coated blades command the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surgical-grade 300-series stainless steel from Japanese and German specialty mills anchors cardiovascular needle manufacturing geography. Cardiac procedure volumes and regulatory frameworks then determine where finished devices concentrate consumption.
United States
Radial access catheterization protocols dominate interventional cardiology suites across Texas and Florida health systems. OSHA bloodborne pathogen regulations accelerate safety needle conversion in hospital operating rooms. The Cleveland Clinic and Mayo Clinic cardiac centers in Ohio and Minnesota standardize procurement specifications that diffuse through integrated delivery networks.
Germany
University hospitals in Bavaria and Baden-Württemberg perform high volumes of coronary artery bypass grafting with coated needle standardization. EU MDR technical documentation requirements force accelerated replacement of legacy needle inventories. The Frankfurt-Rhine-Main medical technology cluster concentrates sterilization validation and notified body consulting services.
Japan
Aging demographics sustain elevated cardiac surgery utilization rates in Tokyo and Osaka metropolitan areas. PMDA consultation pathways shape pre-market submission strategies for coated needle variants. The Kobe and Nagoya industrial corridors host precision metalworking suppliers serving domestic needle manufacturers.
India
Greenfield cardiac hospital construction in Mumbai, Chennai, and Delhi-NCR generates first-mover distribution opportunities. CDSCO medical device rules are tightening quality system expectations for imported surgical instruments. The Karnataka and Telangana medical device parks attract contract manufacturers seeking cost-competitive sterilization capacity.
China
Domestic cardiac surgery volume expansion in Shanghai and Beijing drives procurement of precision penetrating instruments. NMPA Class II medical device registration timelines influence multinational market entry sequencing. The Suzhou and Shenzhen industrial zones concentrate polymer coating application capabilities for needle surface treatments.
Cardiovascular Needle Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue safety mechanism specialization and bioresorbable material convergence. The cardiovascular needle market structures around three tiers: diversified surgical conglomerates with integrated suture portfolios, mid-scale specialists focused on coating technologies, and regional fabricators serving price-sensitive procurement channels. Two dominant competitive moves define current positioning: surgical portfolio bundling to secure sole-source hospital contracts, and regulatory affairs consolidation to navigate EU MDR certification queues.
Among diversified surgical conglomerates, Medtronic plc and Johnson & Johnson exemplify archetypes that leverage integrated device portfolios for multi-year supply agreements. B. Braun Melsungen AG represents the European specialist tier with concentrated cardiac surgery channel presence. These three entities occupy positions where manufacturing scale intersects with regulatory compliance infrastructure, anchoring competitive dynamics without dictating specific strategic actions.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Boston Scientific |
| B. Braun Melsungen AG |
| Becton, Dickinson and Company |
| Abbott Laboratories |
| Teleflex Incorporated |
| Cardinal Health |
| Terumo Corporation |
| Others |
Supply Flow & Price Mechanics
Surgical-grade 300-series stainless steel alloy pricing volatility cascades from Japanese and German specialty mills through three distinct procurement tiers, with coated variants commanding separation from commodity suture needles based on surface treatment validation costs and sterilization protocol complexity.
Pricing Analysis
Warranty and technical documentation bundling separates premium cardiovascular needle suppliers from commodity competitors, with EU MDR compliance packages and post-market surveillance services increasingly unbundled in large health system negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects coating technology sophistication, ISO 7864 certification tier, and volume commitment scale. Cost compression in the standard tier is intensifying because integrated delivery networks leverage multi-year sole-source contracts. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers prioritize performance specifications over per-unit cost.
Supply Chain Analysis
Return flows and legacy inventory replacement cycles create reverse logistics complexity as EU MDR implementation forces hospital systems to decommission non-compliant needle stocks. Manufacturing concentrates in Germany, Japan, and the United States, with precision metalworking clusters in Bavaria and Kobe anchoring upstream fabrication. Supply chains draw from concentrated surgical-grade stainless steel sourcing, siliconized coating chemical inputs, and ethylene oxide sterilization capacity. Single-source vulnerability in notified body certification creates bottlenecks extending product launch timelines. Distribution runs through group purchasing organizations and specialized cardiac surgery distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR notified body capacity constraints prop pricing power for manufacturers with established technical documentation infrastructure, as certification queues limit competitive entry and sustain margin structures.
For Market Incumbents: Anchor market position through backward integration into coating application capabilities and captive sterilization capacity in Germany or Japan. Defend against emerging safety needle specialists by securing dual-source status with integrated delivery networks in Texas and Florida. Prioritize regulatory affairs talent retention as EU MDR technical file specialists command premium compensation. For New Entrants and Emerging Players: Enter via greenfield cardiac hospital construction in Mumbai, Chennai, and Delhi-NCR where procurement specifications remain fluid. Target interventional cardiology catheter needles as the most penetrable segment given transradial protocol expansion and specialized bevel geometry requirements. Pursue direct distribution partnerships with private cardiac institutes bypassing established GPO channels. For Investors and Strategic Acquirers: FDA 510(k) clearance backlog duration is the leading indicator that mid-tier manufacturers with approved portfolios represent acquisition targets before MDR certification queues clear. Long-term viability favors suppliers with integrated suture-needle bundling capability and established hospital system contracts. Monitor notified body capacity expansion announcements as the signal for competitive entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates hospital replacement cycles for legacy inventories across German cardiac centers. |
| Coating Technology Partnership | Secures siliconized surface treatment supply for coronary artery bypass grafting standardization. |
| Integrated Delivery Network Contract | Locks multi-year volume commitments with Texas and Florida health systems. |
| Safety Needle Production Line Conversion | Addresses OSHA bloodborne pathogen compliance mandates in US operating rooms. |
| Indian Distribution Infrastructure | Captures first-mover advantage in Mumbai, Chennai, and Delhi-NCR greenfield hospitals. |
Methodological Framework
Multi-period observation of cardiac surgery procedure volumes, safety needle conversion rates, and EU MDR certification timelines anchored the trend analysis, supplemented by interviews with cardiac surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body submission records, hospital procurement databases, and CMS Medicare procedure data. Bottom-up manufacturer shipment analysis and top-down healthcare expenditure modeling provided triangulation.
Segment-weighting across product type, application, end user, material, and regional regulatory cluster determined value allocation throughout the forecast period. CAGRs were derived from procedure volume elasticity modeling and price trajectory analysis. Forecast inputs incorporated radial access protocol adoption curves, coating technology penetration rates, and integrated delivery network consolidation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under notified body capacity constraints and raw material alloy pricing volatility. Forecasts reflect assumptions about procedural volume continuity, regulatory implementation timelines, and hospital capital expenditure cycles. Practitioners should monitor EU MDR designation expansion announcements and OSHA enforcement priority shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Global Pericardiocentesis Procedures Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Global Cardiac Output Monitoring Devices Market
Cardiovascular Devices
Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
North America Vascular Stents Market
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
Neurovascular Stent Retrievers Market
Cardiovascular Devices
Iliac Artery Stents Market
Cardiovascular Devices
Vital Sign Simulators Market
Cardiovascular Devices
India Coronary Stent Market
Cardiovascular Devices
Percutaneous Coronary Intervention Market
Cardiovascular Devices
Ventricular Drainage Sets Market
Cardiovascular Devices
Chronic Total Occlusion Catheter Market
Cardiovascular Devices
Arteriovenous (Av) Fistula Needle Market
Cardiovascular Devices
Acute Surgical Mechanical Circulatory Support System Market