
 Transcatheter Market | 2026-2036
Transcatheter Market Size, Share, and Industry Trends Forecast 2026-2036
Transcatheter Market Outlook
Multi-source procurement for nitinol and cobalt-chromium alloys is broadening supply security among tier-one manufacturers. Edwards Lifesciences Corporation anchors its position through captive polymer processing capabilities. Medtronic plc leverages vertically integrated delivery system production across North American and European facilities. Abbott Laboratories differentiates via proprietary transcatheter mitral repair platforms.
Transcatheter devices are minimally invasive instruments delivered through vascular access points to repair or replace cardiac valves and vessels without open surgery, typically constructed from shape-memory alloys and biological tissue leaflets engineered for radial fatigue resistance exceeding 400 million cycles. Their primary purpose is reducing perioperative mortality and recovery time in patients deemed inoperable for conventional surgery. Structural heart disease applications command the deepest margin pools due to complex reimbursement and premium pricing for transcatheter aortic valve replacement systems. Catheters represent the highest-volume product category, though valves generate disproportionate revenue per unit. Delivery systems are experiencing the fastest design iteration cycles as manufacturers pursue lower-profile sheath compatibility.
The FDA's premarket approval framework and the European Union's Medical Device Regulation impose escalating clinical evidence requirements for transcatheter valve durability claims, compressing timelines for smaller entrants. ISO 25539 standards for cardiovascular implants establish fatigue testing protocols that directly shape R&D resource allocation. Japan's PMDA maintains distinct pharmacovigilance reporting thresholds that influence post-market study commitments. Stakeholders must monitor evolving health technology assessment methodologies in major markets to anticipate reimbursement access shifts before committing to capacity expansion.
Market Dynamics
The transcatheter market pivots on the FDA's breakthrough device designation pathway, which compresses commercialization timelines for novel valve systems and rewards manufacturers who front-load clinical evidence generation. This regulatory velocity differential is widening competitive moats between well-capitalized incumbents and capital-constrained entrants.
Growth Catalysts
- Aging Demographics:The United States population aged 75 and above is expanding procedural volume for transcatheter aortic valve replacement as surgical risk profiles exclude conventional open-heart intervention.
- ISO 25539 Fatigue Standards:Codified testing protocols for cardiovascular implants above 400 million cycles provide regulatory clarity that accelerates R&D resource allocation toward durability claims.
- Captive Polymer Processing:In-house production of delivery system components reduces supply chain fragility and tightens quality control loops for tier-one manufacturers.
Market Restraints
- Nitinol Supply Concentration:Shape-memory alloy sourcing clusters among limited superelastic wire suppliers, creating input cost volatility when aerospace demand competes for titanium-nickel capacity.
- EU MDR Evidence Escalation:The European Union's Medical Device Regulation imposes expanded clinical data requirements for valve durability claims that compress timelines for smaller manufacturers lacking established post-market surveillance infrastructure.
- Surgical Valve Substitution:Sutureless surgical aortic valve replacement retains preference in low-risk patient cohorts where transcatheter systems face reimbursement headwinds.
Strategic Opportunities
- Transcatheter Mitral Repair:Proprietary clip-based platforms address the underserved functional mitral regurgitation population where surgical intervention carries prohibitive perioperative mortality.
- Japan PMDA Pathway:Distinct pharmacovigilance reporting thresholds create regulatory arbitrage for manufacturers willing to commit dedicated post-market study resources.
- Lower-Profile Sheath Compatibility:Convergence of delivery system miniaturization with femoral access vessel sizing databases enables expansion into peripheral vascular labs beyond dedicated cardiac catheterization suites.
Industry Challenges
- Radial Fatigue Engineering Talent:Scarcity of computational modeling specialists capable of simulating 400-million-cycle leaflet deformation limits R&D throughput for durability validation.
- Sheath-to-Valve Integration Complexity:Compressible bioprosthetic frames must interface with hydrophilic-coated delivery systems across variable anatomical tortuosity, requiring iterative physical testing that extends development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transcatheter Market |
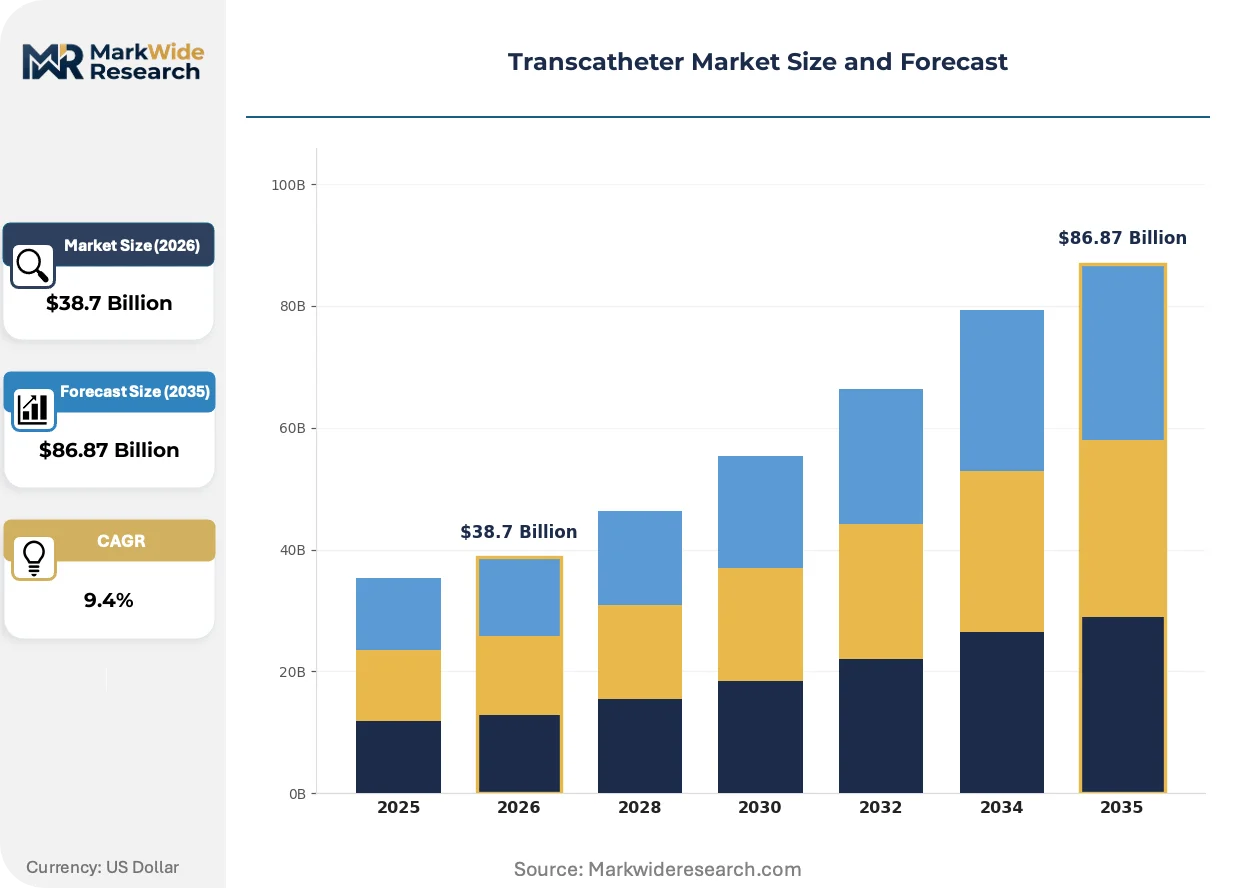
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Delivery Systems, Valves, Stents End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutes Application: Cardiology, Structural Heart Disease, Peripheral Vascular Disease, Interventional Procedures Technology: X-ray Imaging, 3D Visualization, Ultrasound, Magnetic Resonance Imaging |
| Companies Covered | Edwards Lifesciences Corporation, Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, Terumo Corporation, Meril Lifesciences Pvt. Ltd., B. Braun Interventional Systems Inc., JenaValve Technology, Inc., Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transcatheter Market Strategic Shifts
Design iteration cycles for delivery systems are compressing as manufacturers pursue compatibility with smaller vascular access profiles. This engineering race is reshaping competitive positioning around sheath technology rather than valve hemodynamics alone.
Self-expanding nitinol frame technology is consolidating market preference for transfemoral delivery routes. Academic medical centers in the United States are adopting these systems for intermediate-risk patients previously routed to surgical referral. The structural consequence is compression of hybrid operating room utilization as procedures migrate to standard catheterization laboratories.
Japan's PMDA maintains distinct pharmacovigilance reporting thresholds that diverge from FDA and EMA frameworks. Device manufacturers must maintain parallel adverse event databases that trigger differential post-market study commitments. Transcatheter mitral repair platforms face the steepest compliance burden under these bifurcated requirements.
Hospital procurement committees are unbundling valve and delivery system contracts that were previously bundled under single-source agreements. Cardiovascular service line administrators in Germany and France now negotiate sheath compatibility across multiple vendor platforms. This behavioral shift is most visible in European markets where health technology assessment methodologies weight capital equipment utilization against disposable device costs.
Transcatheter Market Segmentation
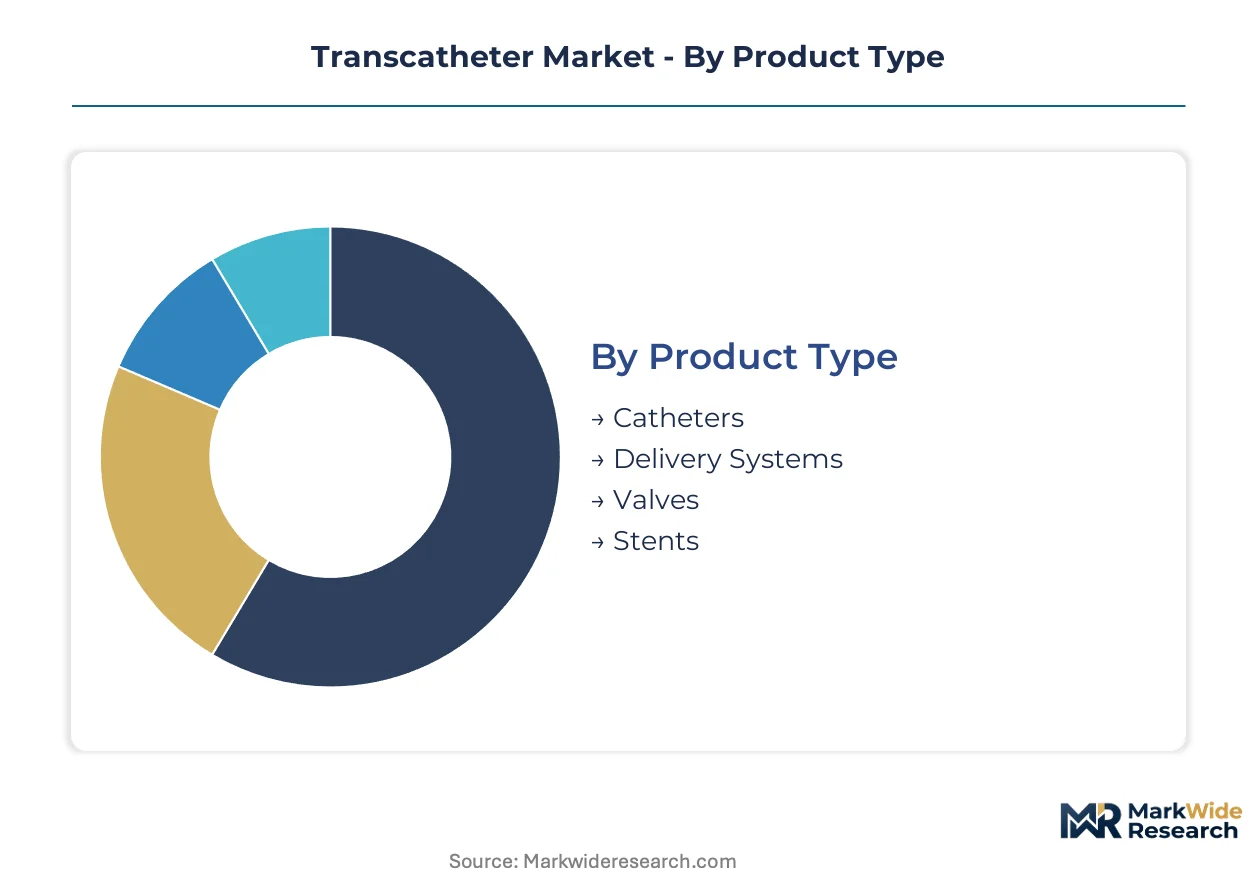
Segmentation in transcatheter markets tracks how procurement committees unbundle valve and delivery system contracts. Reimbursement pathways diverge sharply across end-user settings, while imaging modality choices reshape capital equipment requirements for catheterization laboratories.
Product Type:
Procurement committees weight durability claims against per-procedure economics when allocating budgets across device categories.
- Catheters:Polymer-based access sheaths and guiding catheters constitute the highest-volume category, with hydrophilic coatings reducing vascular trauma during femoral entry. Demand concentrates in United States hospital systems where outpatient migration drives single-use preferences and inventory velocity requirements.
- Valves:Bioprosthetic tissue leaflets mounted on nitinol or cobalt-chromium frames generate disproportionate revenue per unit through premium TAVR and TMVR indications. United States academic medical centers anchor demand as intermediate-risk patient eligibility expands procedural volume.
- Delivery Systems:Integrated sheath-to-valve mechanisms enable transfemoral deployment with lower-profile compatibility.
- Stents:Self-expanding and balloon-expandable vascular scaffolds address peripheral and coronary indications.
Volume sits with Catheters; growth tilts toward Valves.
End User:
Capital equipment requirements and reimbursement density separate institutional tiers.
- Hospitals:Hybrid operating rooms and dedicated cardiac catheterization laboratories concentrate high-acuity structural heart procedures. United States health systems with established TAVR programs capture the deepest reimbursement pools through bundled payment arrangements.
- Ambulatory Surgical Centers:Lower-cost settings are gaining selective structural heart cases as device miniaturization enables conscious sedation protocols.
- Clinics:Diagnostic and follow-up settings drive catheter utilization for peripheral vascular access.
- Research Institutes:Preclinical and early-phase clinical trial infrastructure supports regulatory evidence generation.
Revenue concentrates in Hospitals; site-of-service expansion favors Ambulatory Surgical Centers.
Application:
Clinical evidence thresholds and regulatory pathway complexity segment margin profiles.
- Structural Heart Disease:Transcatheter aortic and mitral interventions command premium pricing through complex FDA PMA pathways and established Medicare coverage. United States procedural volume expansion in intermediate-risk cohorts sustains manufacturer R&D commitments.
- Cardiology:Coronary interventions span diagnostic catheterization through chronic total occlusion recanalization.
- Peripheral Vascular Disease:Limb salvage and claudication indications drive femoropopliteal and below-the-knee device utilization.
- Interventional Procedures:Cross-specialty adoption includes neurovascular and oncologic embolization applications.
Margin depth aligns with Structural Heart Disease; procedural volume expansion tracks Peripheral Vascular Disease.
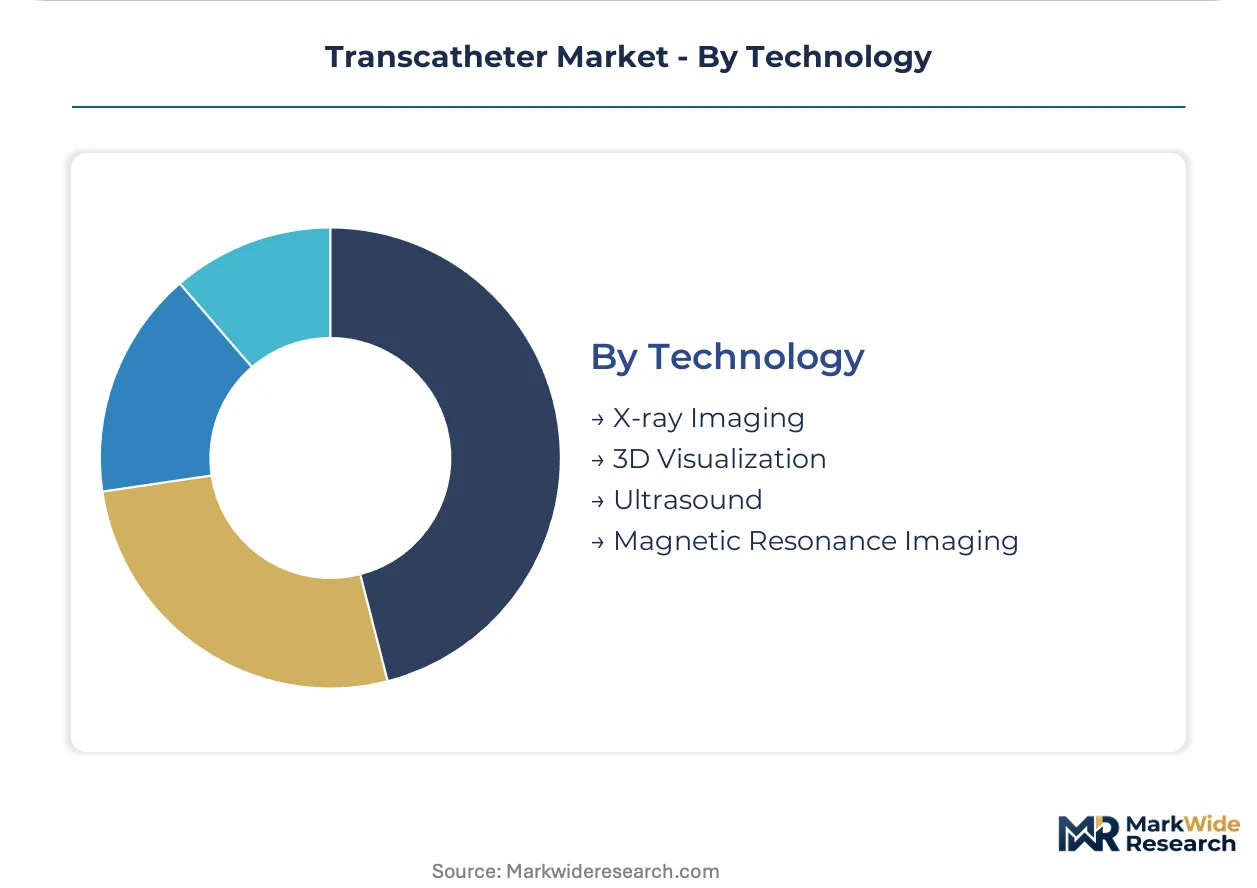
Technology:
Imaging modality selection determines capital allocation and disposable device bundling.
- X-ray Imaging:Fluoroscopy remains the procedural backbone for real-time device navigation, with radiation dose optimization driving flat-panel detector upgrades. United States hospital capital budgets prioritize angiography suite modernization to support TAVR program accreditation.
- 3D Visualization:Computed tomography-based planning software enables annular sizing and access route simulation.
- Ultrasound:Intracardiac and transesophageal modalities guide valve deployment without radiation exposure.
- Magnetic Resonance Imaging:Preprocedural tissue characterization and post-implant surveillance applications are emerging.
Installed base dominance rests with X-ray Imaging; integration investment flows toward 3D Visualization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nitinol wire drawing capacity clusters in the United States and Germany, anchoring transcatheter device manufacturing geography. Reimbursement density and regulatory pathway velocity separate high-volume markets from emerging access points.
United States
Medicare coverage determinations for transcatheter aortic valve replacement drive procedural volume in patients aged 75 and above. The FDA's breakthrough device designation pathway compresses commercialization timelines for novel valve systems. Minneapolis and Irvine host concentrated delivery system engineering clusters where manufacturers iterate sheath-to-valve integration designs.
Germany
Hospital procurement committees in Bavaria and North Rhine-Westphalia unbundle valve and delivery system contracts under health technology assessment frameworks. The EU MDR imposes expanded clinical evidence requirements for durability claims that favor established post-market surveillance infrastructure. The Tübingen-Stuttgart corridor anchors nitinol processing capabilities serving continental European device assembly.
Japan
Aging demographics exceeding United States velocity expand eligible patient pools for structural heart interventions. PMDA pharmacovigilance reporting thresholds diverge from FDA frameworks, requiring parallel adverse event databases. Tokyo and Osaka academic medical centers concentrate transcatheter mitral repair procedural expertise and post-market study commitments.
Switzerland
Swissmedic maintains alignment with EMA regulatory frameworks while offering streamlined market access for CE-marked devices. Geneva and Zurich host cardiovascular research institutes generating clinical evidence for European reimbursement submissions. Precision manufacturing clusters in the Jura region supply cobalt-chromium alloy components to tier-one device manufacturers.
India
Domestic procedural volume concentrates in Delhi-NCR and Mumbai metropolitan cardiac centers where private health systems absorb imported device costs. CDSCO regulatory pathways for class D cardiovascular implants require local clinical bridging studies. Meril Lifesciences anchors indigenous manufacturing capacity for delivery system components serving South Asian markets.
Transcatheter Market Competitive Environment
Global majors compete with regional champions across regulatory evidence generation and supply chain control. The vendor base consolidates around three tier-one manufacturers with captive polymer processing and vertically integrated delivery system production. Strategic archetypes include full-stack structural heart platforms, specialized mitral repair innovators, and regional cost-optimized assemblers. Competitive moves center on FDA breakthrough designation pursuit and multi-source nitinol procurement security.
Among United States-based incumbents, Edwards Lifesciences Corporation and Medtronic plc exemplify the full-stack platform archetype with integrated valve and delivery system portfolios. Abbott Laboratories occupies a differentiated position through proprietary transcatheter mitral repair technology addressing functional regurgitation indications. These three anchors represent the competitive gravity center against which mid-cap specialists and regional challengers define market entry strategies.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Terumo Corporation |
| Meril Lifesciences Pvt. Ltd. |
| B. Braun Interventional Systems Inc. |
| JenaValve Technology, Inc. |
| Stryker |
| Others |
Value Chain & Pricing Dynamics
Titanium-nickel alloy spot pricing volatility cascades through transcatheter device manufacturing into three distinct procurement tiers. Aerospace demand competition for nitinol wire capacity compresses margins for manufacturers lacking long-term offtake agreements with United States or German superelastic suppliers.
Pricing Analysis
Warranty bundling separates premium valve contracts from unbundled delivery system procurement. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough designation status and ISO 25539 fatigue certification tiers. Cost compression in mid-tier valves is intensifying because hospital procurement committees now negotiate sheath compatibility across multiple vendor platforms. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with established TAVR programs demonstrate lowest sensitivity due to bundled payment capture.
Supply Chain Analysis
Regional distribution centers in Minneapolis, Irvine, and the Tübingen-Stuttgart corridor anchor hub-and-spoke patterns for delivery system components. Manufacturing concentration rests on nitinol wire drawing in the United States and Germany plus cobalt-chromium processing in Switzerland. Raw material dependencies center on titanium-nickel alloys, biological tissue leaflets, and hydrophilic polymer coatings. Single-source vulnerability in superelastic wire suppliers creates exposure when aerospace demand spikes. Distribution runs through hospital procurement committees and cardiovascular service line administrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where the EU MDR's expanded clinical evidence requirements for valve durability claims erect barrier-to-entry moats favoring manufacturers with established post-market surveillance infrastructure.
For Market Incumbents: Hedge against nitinol supply concentration through multi-source procurement agreements with German and United States wire suppliers. Backward integration into captive polymer processing tightens quality control loops and defends margin position against emerging regional assemblers in India.
For New Entrants and Emerging Players: Enter via transcatheter mitral repair platforms addressing functional regurgitation where surgical perioperative mortality excludes conventional intervention. Japan's PMDA pathway offers regulatory arbitrage for manufacturers committing dedicated post-market study resources. Target hospital procurement committees in Germany and France through health technology assessment-aligned value demonstration.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with ISO 25539 fatigue validation capabilities in European markets. Long-term viability hinges on FDA breakthrough designation velocity and reimbursement density in United States Medicare coverage determinations. Watch PMDA pharmacovigilance reporting threshold adjustments as inflection indicator for Japanese market access costs.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Compresses commercialization timelines for novel valve systems against PMA pathway competitors. |
| CE Marking Pathway Under EU MDR | Requires expanded clinical evidence for durability claims that favors post-market surveillance infrastructure. |
| Hospital System Partnership | Secures bundled payment arrangements through cardiovascular service line administrator relationships. |
| Backward Integration into Nitinol Processing | Reduces supply chain fragility when aerospace demand competes for titanium-nickel capacity. |
| Reimbursement Strategy | Aligns Medicare coverage determinations with intermediate-risk patient eligibility expansion. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with cardiovascular service line administrators, biomedical engineers, hospital procurement committee members, and GPO contracts managers combined with FDA 510(k) and PMA databases, EU MDR notified body submissions, and CMS Medicare claims data. Bottom-up device shipment analysis triangulated against top-down reimbursement expenditure estimates.
Data-stream reconciliation across product type, end user setting, application indication, and imaging technology dimensions shaped the analytical framework. CAGRs derived from procedural volume trajectories and per-unit pricing dynamics across the analysis window. Industry-specific inputs included ISO 25539 fatigue testing protocol adoption rates and FDA breakthrough designation velocity by manufacturer archetype.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR evidence escalation timelines and nitinol supply disruption scenarios. Forecasts reflect assumptions regarding Medicare coverage determination stability and PMDA pharmacovigilance threshold continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Embolotherapy Market
Cardiovascular Devices
Heart Valves Market
Cardiovascular Devices
Global Critical Limb Ischemia Treatment Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Absorbable Heart Stent Market
Cardiovascular Devices
Perfusion Systems Market
Cardiovascular Devices
Surgical Heart Valves Market
Cardiovascular Devices
Global Cardiovascular Ultrasound System Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Global Angio Suites Market
Cardiovascular Devices
Cardiac Sutures Market
Cardiovascular Devices
Disposable Blood Pressure Cuffs Market
Cardiovascular Devices
South Africa Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular Diagnostic and Monitoring Devices Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
Ventricular Drainage Sets Market