
 Intravascular Imaging Market | 2026-2036
Intravascular Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Intravascular Imaging Market Outlook
Equipment leasing and pay-per-procedure service models is tilting competitive dynamics toward vendors with balance-sheet capacity to carry installed-base assets. Boston Scientific Corp. leverages captive catheter supply to lock in system placements across integrated delivery networks. Philips Healthcare sustains R&D intensity in optical coherence tomography hardware to defend premium positioning. Abbott Laboratories anchors its presence through hybrid intravascular ultrasound and physiology platforms that occupy cath lab workflow.
Intravascular imaging encompasses catheter-based modalities that generate cross-sectional or tomographic visualizations of vessel lumen, wall morphology, and plaque composition using acoustic or optical energy, typically at spatial resolutions of 10-150 micrometers depending on modality. These systems enable real-time guidance during percutaneous coronary intervention, atherectomy, and stent optimization by providing luminal measurements and tissue characterization unavailable from conventional angiography alone. Optical coherence tomography commands premium pricing due to superior resolution for stent apposition assessment, while intravascular ultrasound retains volume leadership through broader reimbursement and established clinical utility in left main and bifurcation lesions. Hybrid systems integrating both modalities with physiology sensors represent the fastest-expanding segment as hospitals consolidate capital purchases.
The FDA premarket notification pathway and European MDR conformity assessment shape device commercialization timelines and post-market surveillance obligations for manufacturers seeking dual-territory approval. Japan's PMDA and METI reimbursement pricing for intravascular imaging procedures directly influence vendor go-to-market sequencing across Asia-Pacific. Stakeholders must monitor evolving health technology assessment criteria in Germany and France, where hospital procurement increasingly ties capital allocation to demonstrated reductions in target lesion revascularization.
Market Dynamics
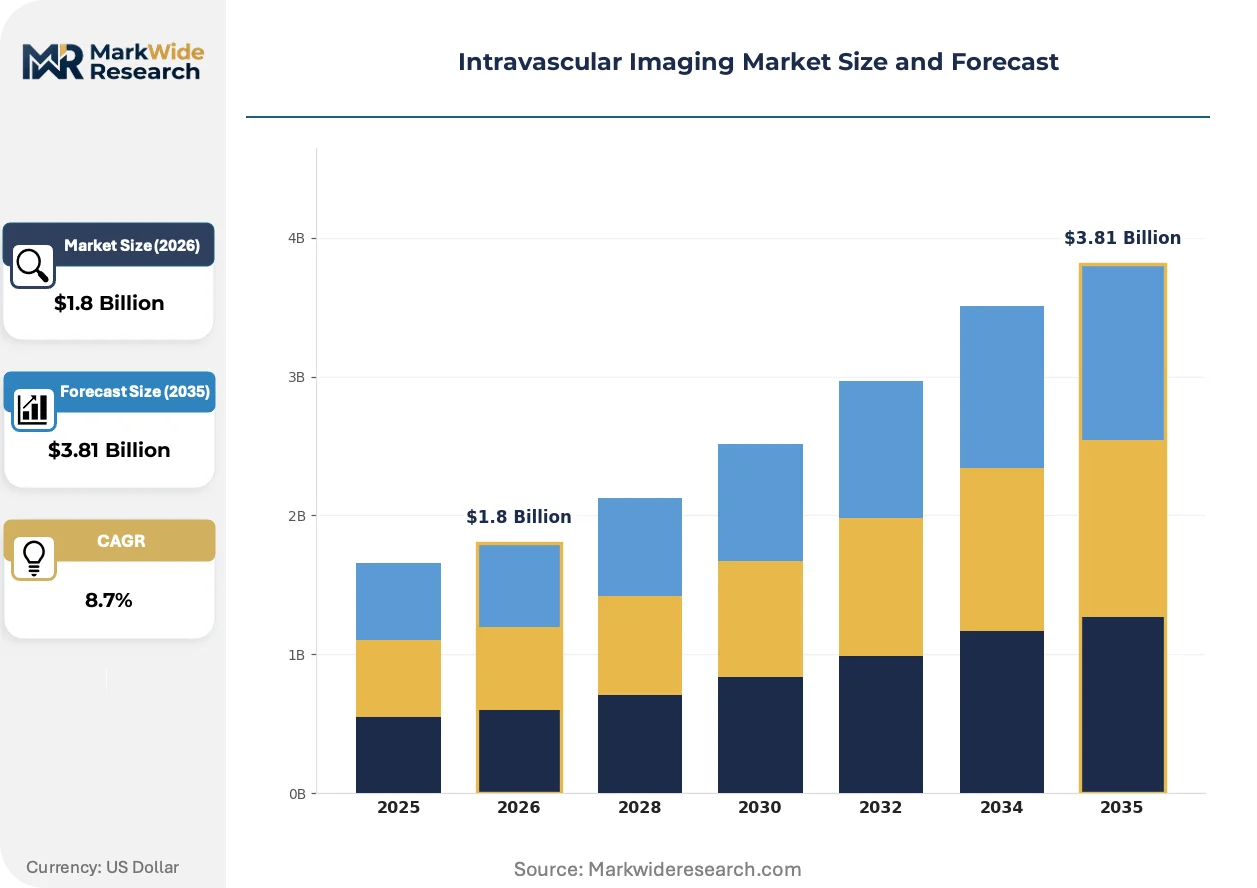
Equipment leasing models and pay-per-procedure service contracts are restructuring capital deployment across catheterization laboratories, favoring vendors with balance-sheet depth to carry installed-base assets while compressing margins for pure-hardware competitors.
Growth Catalysts
- Medicare reimbursement pathways:The United States Medicare program maintains coverage for intravascular ultrasound in complex coronary lesions, sustaining hospital investment in system procurement and procedure volume expansion.
- FDA premarket notification acceleration:The FDA's streamlined 510(k) pathway for optical coherence tomography catheters reduces commercialization timelines, enabling faster market entry for iterative device improvements.
- Hybrid platform consolidation:Cath labs are consolidating capital purchases around integrated intravascular ultrasound and physiology systems that reduce footprint and streamline workflow.
Market Restraints
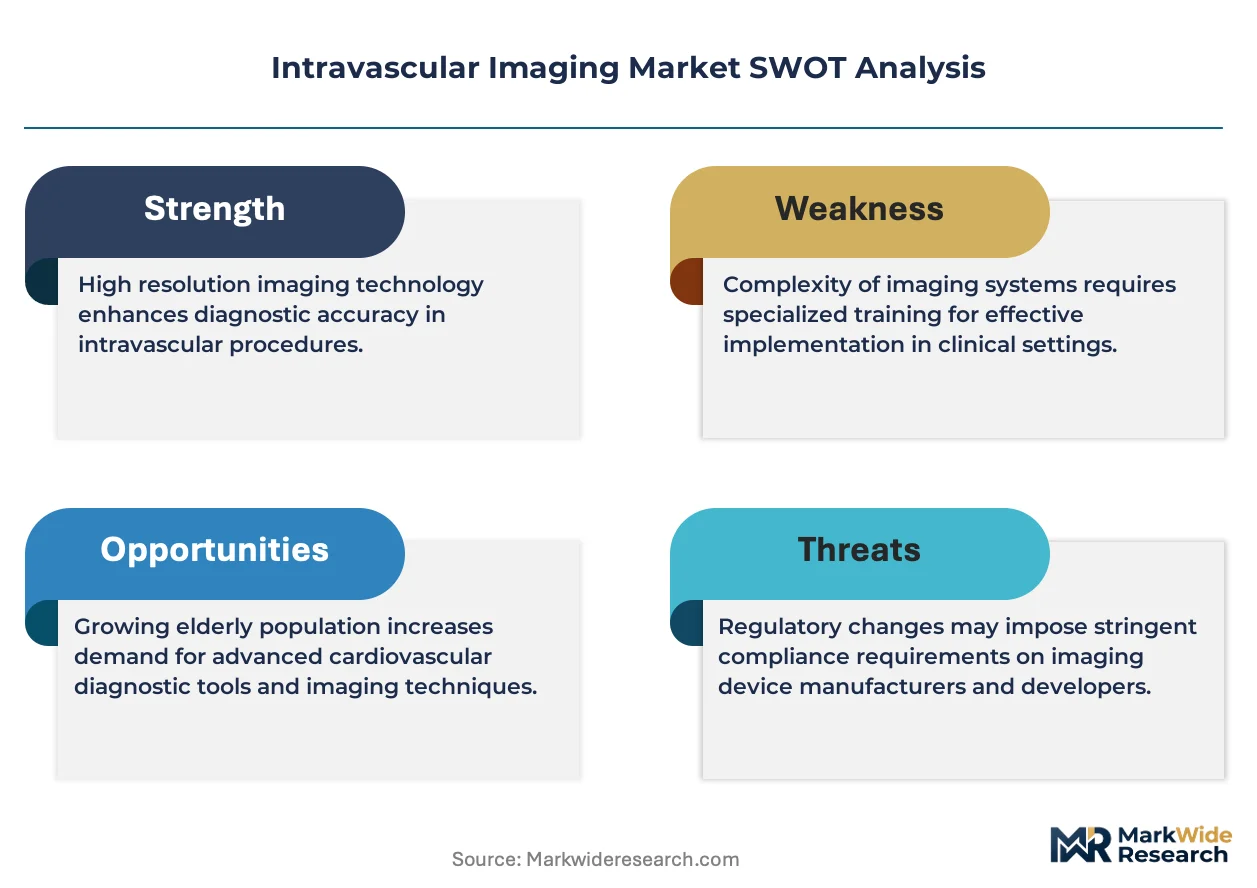
- Reimbursement fragmentation:Inconsistent private payer coverage for optical coherence tomography outside Medicare Advantage networks limits procedure adoption in non-academic settings.
- Single-source catheter dependency:Proprietary catheter-to-console lock-in creates supply concentration risk and limits hospital negotiating leverage on consumable pricing.
- Training pathway duration:Extended learning curves for image interpretation and stent optimization protocols constrain operator pool expansion in community hospital settings.
Strategic Opportunities
- Japan METI pricing corridors:Japan's Ministry of Economy, Trade and Industry reimbursement pricing for intravascular imaging procedures creates predictable revenue streams for vendors prioritizing Asia-Pacific sequencing.
- Artificial intelligence integration:Machine learning algorithms for automated plaque characterization and stent apposition scoring are converging with hardware platforms to differentiate premium offerings.
- Ambulatory surgical center penetration:Shifting site-of-service economics for diagnostic coronary procedures creates channel expansion potential outside traditional hospital cath labs.
Industry Challenges
- Interventional cardiologist training bandwidth:Competing procedural demands and fellowship program capacity constraints limit the pipeline of imaging-competent operators.
- European MDR conformity timelines:Extended notified body review periods for intravascular imaging systems under the Medical Device Regulation delay product launches and strain regulatory affairs resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intravascular Imaging Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Coherence Tomography, Intravascular Ultrasound, Hybrid Systems, Other Modalities End User: Hospital, Diagnostic Center, Research Institute, Cardiology Clinic Technology: Angiography, CT Imaging, MRI, 3D Reconstruction Application: Coronary Artery Disease, Peripheral Vascular Disease, Aortic Disease, Others |
| Companies Covered | Boston Scientific Corp., Philips Healthcare, GE Healthcare, Siemens Healthineers, Canon Medical Systems Corp., Abbott Laboratories, Terumo Corporation, Medtronic, ACIST Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intravascular Imaging Market Strategic Shifts
Real-time image processing capabilities and workflow integration demands are compressing development cycles, with vendors racing to embed decision-support tools directly into cath lab consoles before competitors establish platform dominance.
Optical coherence tomography is collapsing the resolution-performance tradeoff that previously favored intravascular ultrasound for vessel sizing, as near-infrared interferometry achieves 10-micrometer resolution for stent strut coverage assessment. Academic medical centers in Germany and Japan are adopting next-generation swept-source systems for complex bifurcation interventions. The structural consequence is a narrowing price-performance gap between modalities that pressures hybrid system pricing.
The European Union Medical Device Regulation's enhanced post-market surveillance requirements are extending conformity assessment timelines and forcing manufacturers to rebuild clinical evidence portfolios for legacy devices. Small-to-mid sized vendors face disproportionate compliance costs, accelerating consolidation toward entities with dedicated regulatory infrastructure. Optical coherence tomography catheters with predicate claims are experiencing the longest review backlogs.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, forcing vendors to compete on discrete maintenance and training pricing rather than bundled lifetime value propositions. Integrated delivery networks in the United States are standardizing across fewer vendor relationships to extract volume discounts. This behavior is most visible in multi-hospital systems consolidating cath lab standardization decisions at the corporate level rather than individual facility autonomy.
Intravascular Imaging Market Segmentation
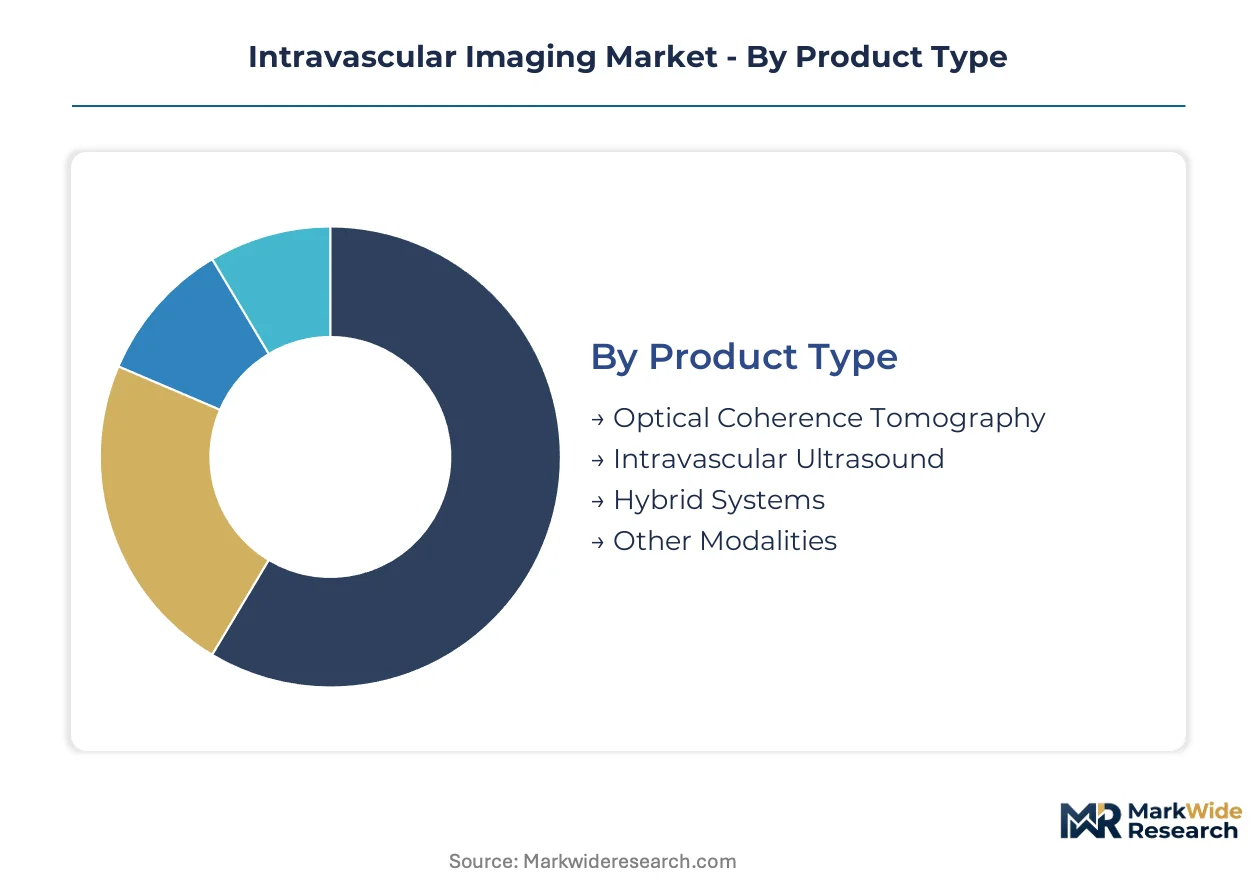
Segmentation in intravascular imaging reveals how capital deployment, consumable economics, and clinical workflow requirements diverge across technology platforms and care settings. Vendors structure pricing, service contracts, and training programs differently for each slice, making granular understanding essential for competitive positioning.
Product Type:
After-sales-service intensity varies sharply across product types, with hybrid systems demanding integrated maintenance protocols and optical platforms requiring specialized optical component replacement.
- Optical Coherence Tomography:Near-infrared interferometry generates 10-micrometer resolution images for stent apposition assessment. Demand concentrates in Germany and Japan where academic centers perform complex bifurcation interventions; premium pricing reflects superior tissue characterization capabilities.
- Intravascular Ultrasound:Acoustic energy produces cross-sectional vessel visualizations at 150-micrometer resolution with established reimbursement pathways. United States Medicare coverage for complex coronary lesions sustains hospital procurement volume through predictable revenue capture.
- Hybrid Systems:Integrated intravascular ultrasound and physiology platforms reduce cath lab footprint while streamlining workflow. Cath labs in integrated delivery networks favor these for capital consolidation.
- Other Modalities:Includes emerging spectroscopic and photoacoustic technologies in early clinical validation.
Intravascular ultrasound holds the largest share; momentum sits with hybrid systems.
End User:
Procurement authority and capital allocation timelines diverge meaningfully across end users, with hospital systems leveraging corporate-level standardization while cardiology clinics negotiate individual service contracts.
- Hospital:Tertiary hospital catheterization laboratories drive system procurement through procedure volume and resident training programs. United States integrated delivery networks extract volume discounts through multi-facility standardization decisions.
- Diagnostic Center:Freestanding imaging facilities prioritize throughput metrics and lease-based financing to minimize capital risk.
- Research Institute:Academic medical centers in Japan and Germany adopt next-generation swept-source systems for protocol development and clinical evidence generation.
- Cardiology Clinic:Community-based practices face reimbursement fragmentation constraints that limit optical coherence tomography adoption outside Medicare Advantage networks.
Hospitals dominate installed base; cardiology clinics are expanding most quickly as site-of-service economics shift.
Technology:
Technology selection in intravascular imaging reflects a cost-to-resolution tradeoff that vendors exploit through tiered platform positioning and modular upgrade paths.
- Angiography:X-ray based luminal visualization remains the procedural default against which intravascular imaging adjuncts are measured.
- CT Imaging:Computed tomography angiography provides non-invasive coronary assessment that competes for diagnostic procedure referrals.
- MRI:Magnetic resonance imaging offers radiation-free soft tissue characterization with limited real-time interventional guidance capability.
- 3D Reconstruction:Software-based volumetric rendering from rotational angiography or intravascular imaging pullbacks enables lesion complexity assessment.
Angiography anchors procedural workflow; 3D reconstruction is gaining share fastest through AI-enhanced automation.
Application:
Application-specific reimbursement coding and clinical evidence requirements shape vendor targeting, with coronary applications commanding premium pricing and peripheral segments offering volume expansion.
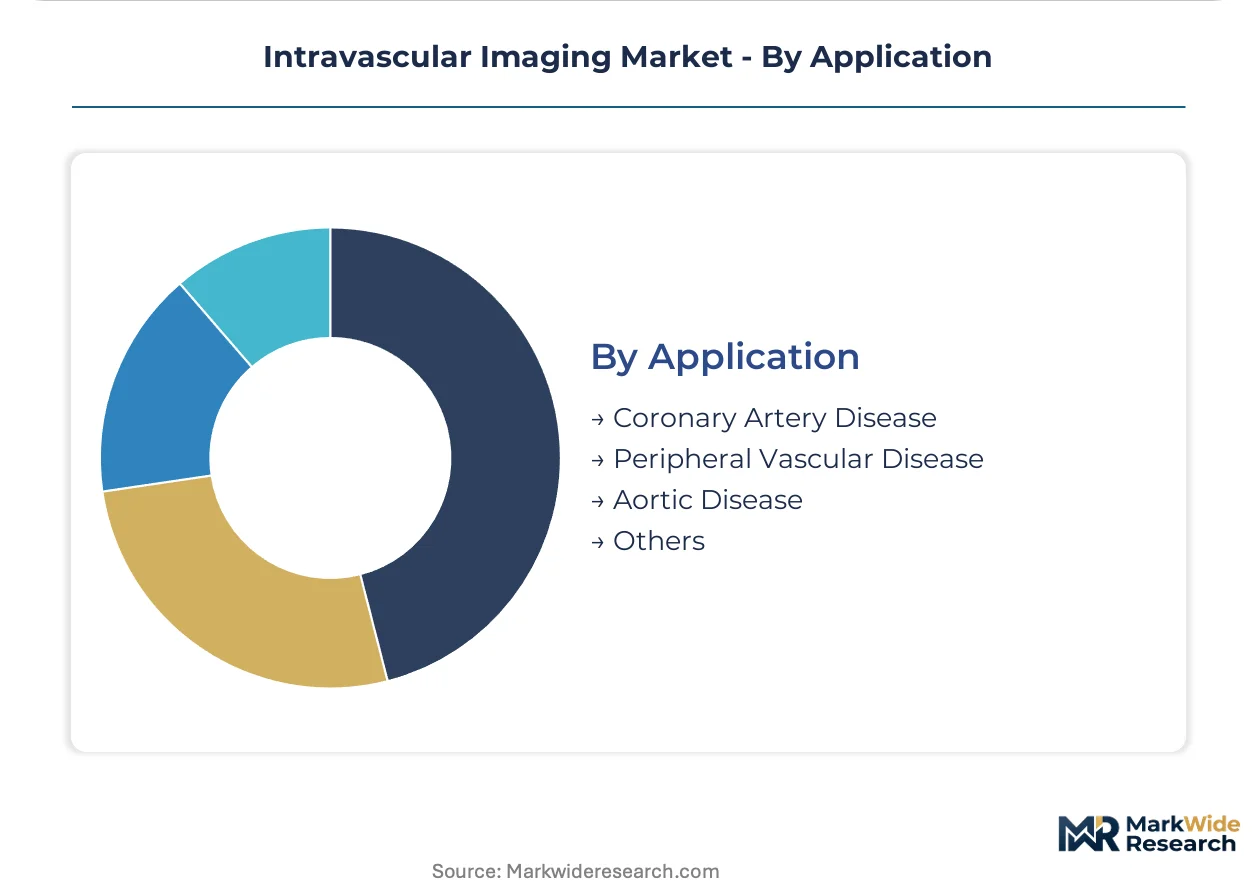
- Coronary Artery Disease:Percutaneous coronary intervention guidance represents the core revenue pool with established CPT codes and Medicare coverage. Complex lesion subsets including left main and bifurcation drive intravascular ultrasound utilization.
- Peripheral Vascular Disease:Lower extremity and renal interventions expand addressable procedure volume with evolving reimbursement pathways. United States hospital outpatient departments are building dedicated peripheral labs.
- Aortic Disease:Endovascular aortic repair planning utilizes intravascular imaging for landing zone assessment and stent graft sizing.
- Others:Includes carotid, venous, and structural heart applications with emerging clinical utility.
Coronary artery disease holds the largest share; peripheral vascular disease shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in intravascular imaging tilt heavily toward net-importing markets with advanced cath lab infrastructure. Germany and Japan run structural trade deficits in optical coherence tomography hardware, sourcing consoles and catheters from US and Dutch manufacturers while exporting limited volumes of specialized components.
United States
Medicare reimbursement for intravascular ultrasound in complex coronary lesions sustains hospital procurement volume. The FDA's 510(k) premarket notification pathway accelerates optical coherence tomography catheter commercialization. Boston and Minneapolis anchor device development clusters where integrated delivery networks consolidate vendor relationships.
Germany
Academic medical centers in Munich and Heidelberg drive adoption of next-generation swept-source systems for bifurcation interventions. The EU Medical Device Regulation extends conformity assessment timelines for legacy device recertification. The Baden-Württemberg medical technology corridor concentrates catheter manufacturing and regulatory affairs expertise.
Japan
METI reimbursement pricing for intravascular imaging procedures creates predictable revenue corridors for vendors prioritizing Asia-Pacific sequencing. PMDA review timelines for hybrid systems remain shorter than European MDR equivalents. Tokyo and Osaka cath labs standardize on dual-modality platforms for resident training programs.
China
Domestic catheter production scales rapidly under NMPA innovation pathways for Class III devices. Provincial procurement consortiums in Jiangsu and Guangdong drive price compression on intravascular ultrasound systems. The Yangtze River Delta medical device cluster attracts joint ventures seeking localized manufacturing.
Switzerland
Swissmedic's streamlined conformity assessment attracts EU-parallel submissions from premium-tier vendors. Geneva and Basel host European headquarters for US-based imaging manufacturers seeking regulatory efficiency. The country's reimbursement autonomy permits earlier adoption of AI-integrated platforms than neighboring EU markets.
Intravascular Imaging Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in catheter and optical subassembly supply. The vendor base concentrates around cath lab console manufacturers with captive catheter ecosystems, compressing margins for pure-hardware competitors. Three archetypes dominate: diversified medtech conglomerates with full-stack imaging portfolios, cardiovascular-focused device specialists with deep catheter supply chains, and emerging AI-software vendors seeking hardware partnerships. Consolidation pressure favors balance-sheet capacity for leasing model deployment; regulatory infrastructure scale determines European MDR survival.
Among US-based diversified manufacturers, Boston Scientific Corp., Abbott Laboratories, and GE Healthcare exemplify platform-integrated positioning. Boston Scientific anchors system placements through catheter supply lock-in across integrated delivery networks. Abbott occupies the hybrid modality segment with combined intravascular ultrasound and physiology platforms. GE Healthcare leverages diagnostic imaging installed bases to cross-sell interventional guidance systems.
| Leading Market Players |
|---|
| Boston Scientific Corp. |
| Philips Healthcare |
| GE Healthcare |
| Siemens Healthineers |
| Canon Medical Systems Corp. |
| Abbott Laboratories |
| Terumo Corporation |
| Medtronic |
| ACIST Medical Systems |
| Others |
Value Chain & Pricing Dynamics
Single-source catheter dependency between proprietary console manufacturers and disposable suppliers determines both pricing tier spreads and supply chain shape in intravascular imaging. Hospital procurement committees face locked-in consumable economics that compress negotiating leverage while vendors with captive catheter ecosystems capture recurring revenue streams.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels in intravascular imaging systems. Price differentiation hinges on modality integration depth and after-sales service bundling, with hybrid platforms commanding premium positioning against standalone intravascular ultrasound. Cost compression in the standard tier is intensifying because provincial procurement consortiums in China drive price compression on intravascular ultrasound systems. Community cardiology clinics exhibit highest price sensitivity due to reimbursement fragmentation, while academic medical centers in Germany and Japan demonstrate lowest sensitivity for next-generation swept-source optical coherence tomography platforms.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for intravascular imaging catheter manufacturing. Component sourcing concentrates in the Netherlands for optical coherence tomography hardware, Japan for precision optical subassemblies, and China for scaled intravascular ultrasound transducer production. Raw material dependencies include near-infrared laser diodes, piezoelectric crystals, and specialized polymer catheter shafts. Single-source vulnerability persists at the optical subassembly tier where swept-source laser manufacturers maintain concentrated supply positions. Distribution runs through integrated delivery network procurement committees in the United States and hospital group purchasing organizations in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intravascular imaging market sits in early-cycle expansion as Medicare reimbursement pathways for complex coronary lesions sustain hospital investment momentum. Hybrid platform consolidation represents the primary adoption tailwind accelerating capital deployment across catheterization laboratories.
For Market Incumbents: Pre-empt emerging AI-software vendors from establishing diagnostic algorithm partnerships by embedding machine learning plaque characterization directly into cath lab consoles. Defend installed base positions through equipment leasing models that lock in catheter supply agreements across integrated delivery networks. Vertical integration into optical subassembly production reduces single-source supplier vulnerability for swept-source laser components. For New Entrants and Emerging Players: Pursue ambulatory surgical center penetration as site-of-service economics shift diagnostic coronary procedures outside traditional hospital cath labs. Target peripheral vascular disease applications where reimbursement pathways remain underdeveloped and incumbent positioning is weakest. Deploy pay-per-procedure service contracts to bypass capital purchase barriers in community cardiology clinic settings. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors diversified medtech conglomerates with balance-sheet capacity for leasing model deployment. Long-term viability centers on regulatory infrastructure scale for European MDR survival and captive catheter ecosystem economics. Acquisition target archetypes include AI-software vendors with FDA-cleared stent apposition algorithms and mid-tier intravascular ultrasound manufacturers with GPO contract access. Monitor FDA 510(k) clearance backlogs for optical coherence tomography catheters as inflection indicator for competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Platform Integration | Cath labs in integrated delivery networks consolidate capital purchases around combined intravascular ultrasound and physiology systems. |
| AI Software Companion Development | Machine learning algorithms for automated plaque characterization differentiate premium offerings from hardware-only competitors. |
| Reimbursement Strategy | Medicare coverage pathways for intravascular ultrasound in complex coronary lesions sustain predictable hospital procurement volume. |
| CE Marking Pathway | EU MDR conformity assessment timelines determine European market entry sequencing and regulatory affairs resource allocation. |
| Hospital System Partnership | Equipment leasing and pay-per-procedure contracts lock in catheter supply relationships across multi-facility standardization decisions. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with interventional cardiologists, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and catheterization laboratory directors. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare reimbursement filings, EU MDR notified body submission records, and hospital procurement database aggregators. Bottom-up procedure volume estimates were triangulated against top-down capital equipment shipment data across the analysis window.
Calibration against historical adoption curves for analogous cath lab technologies informed the analytical framework across the projection horizon. Segmentation dimensions modeled include modality type, end-user facility tier, application area, and regional regulatory cluster. CAGRs were derived from procedure volume elasticity to reimbursement coverage expansion and capital replacement cycle timing. Forecast inputs incorporated METI pricing corridor stability in Japan and NMPA innovation pathway velocity in China.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles or Medicare reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory approval timelines and catheter supply chain stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Argentina Computed Tomography Market
Medical Imaging
Global Digital Radiography Market
Medical Imaging
Global Picture Archiving Communications System Market
Medical Imaging
Global Portable Magnetic Resonance Imaging Market
Medical Imaging
Weightbearing Low Dose (CT) Systems Market
Medical Imaging
Forensic Imaging Market
Medical Imaging
Global Veterinary X-Ray Market
Medical Imaging
France Mammography Market
Medical Imaging
Panoramic and Cephalometric Radiography Systems Market
Medical Imaging
Dental Imaging Market
Medical Imaging
North America Computed Tomography (CT) Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
Brain PET-MRI Systems Market
Medical Imaging
Europe Fluoroscopy Market
Medical Imaging
Global Computer Vision in Healthcare Market
Medical Imaging
Intraoperative Imaging Market