
 Thoracic Vascular Stent Grafts Market | 2026-2036
Thoracic Vascular Stent Grafts Market Size, Share, and Industry Trends Forecast 2026-2036
Thoracic Vascular Stent Grafts Market Analytics
China is fragmenting thoracic stent graft manufacturing capacity as domestic producers scale nitinol laser-cutting and ePTFE graft fabrication. Medtronic plc anchors North American distribution through its integrated hospital contracting network. Cook Medical Inc. specializes in physician-customized sizing and delivery systems for complex aortic anatomies. W.L. Gore & Associates leverages proprietary expanded polytetrafluoroethylene membrane technology to sustain premium positioning in thoracic endovascular aortic repair.
Thoracic vascular stent grafts are implantable tubular prostheses constructed from nitinol or cobalt-chromium alloy frameworks covered with woven polyester or ePTFE fabric, designed to exclude thoracic aortic aneurysms or dissections from systemic blood pressure while maintaining branch vessel patency through fenestrated or branched architectures. Self-expanding designs dominate elective procedures due to conformability against tortuous aortic arches, while coated variants incorporating antiproliferative agents represent the fastest-growing material segment as physicians seek to reduce stent graft-induced new entry tears. Metal-based platforms retain the largest installed base, though composite constructions combining superelastic alloys with bioabsorbable polymers are gaining traction in trauma management applications where future vessel remodeling remains desirable.
FDA premarket approval requirements and EU MDR technical documentation obligations extend development timelines but elevate barriers against low-cost competitors, concentrating procurement authority at hospitals with established structural heart programs. Japan's PMDA and China's NMPA impose supplementary clinical testing mandates that favor multinationals with localized regulatory affairs infrastructure. Stakeholders must monitor evolving fenestrated device coding decisions and national reimbursement carve-outs for branched endografts.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while elevating technical service requirements for thoracic stent graft suppliers, forcing manufacturers to embed clinical training and inventory management into core contracts.
Growth Catalysts
- FDA premarket approval pathways:Extended clinical validation requirements filter out undercapitalized competitors, concentrating hospital purchasing authority among established structural heart programs with proven track records.
- Nitinol laser-cutting automation:Chinese domestic producers are scaling precision manufacturing capacity, expanding regional supply availability and pressuring incumbent pricing structures.
- Japan's aging demographic:Elevated thoracic aortic aneurysm prevalence drives procedure volume expansion within PMDA-regimated reimbursement frameworks that favor advanced endovascular solutions.
Market Restraints
- EPTFE membrane supply concentration:Proprietary graft fabrication expertise concentrates among three specialized suppliers, creating input bottlenecks during demand surges.
- EU MDR technical documentation:Extended conformity assessment timelines delay product launches by 18-24 months, freezing development capital in regulatory limbo.
- Open surgical repair persistence:Younger trauma patients and connective tissue disorder cases remain candidates for conventional graft replacement, capping endovascular ceiling.
Strategic Opportunities
- India's tertiary cardiac centers:Underpenetrated endovascular infrastructure in Delhi and Mumbai metros offers first-mover positioning as CDSCO accelerates device registration harmonization.
- Antiproliferative coating convergence:Drug-eluting stent technology migration into thoracic platforms enables differentiation against bare-metal competitors in high-risk dissection repair.
- Physician-customized delivery systems:Complex aortic anatomy segmentation creates white space for patient-specific fenestration design services beyond standard off-the-shelf catalogs.
Industry Challenges
- Computational fluid dynamics modeling:Scarcity of trained biomechanical engineers capable of simulating branch vessel flow patterns delays next-generation fenestrated device development.
- ISO 25539-1 fatigue testing:Accelerated durability validation protocols require capital-intensive pulsatile flow equipment that strains mid-tier manufacturer balance sheets.
- Legacy hospital inventory systems:Siloed implant tracking databases obstruct real-time consumption analytics that vendors need for consignment optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thoracic Vascular Stent Grafts Market |
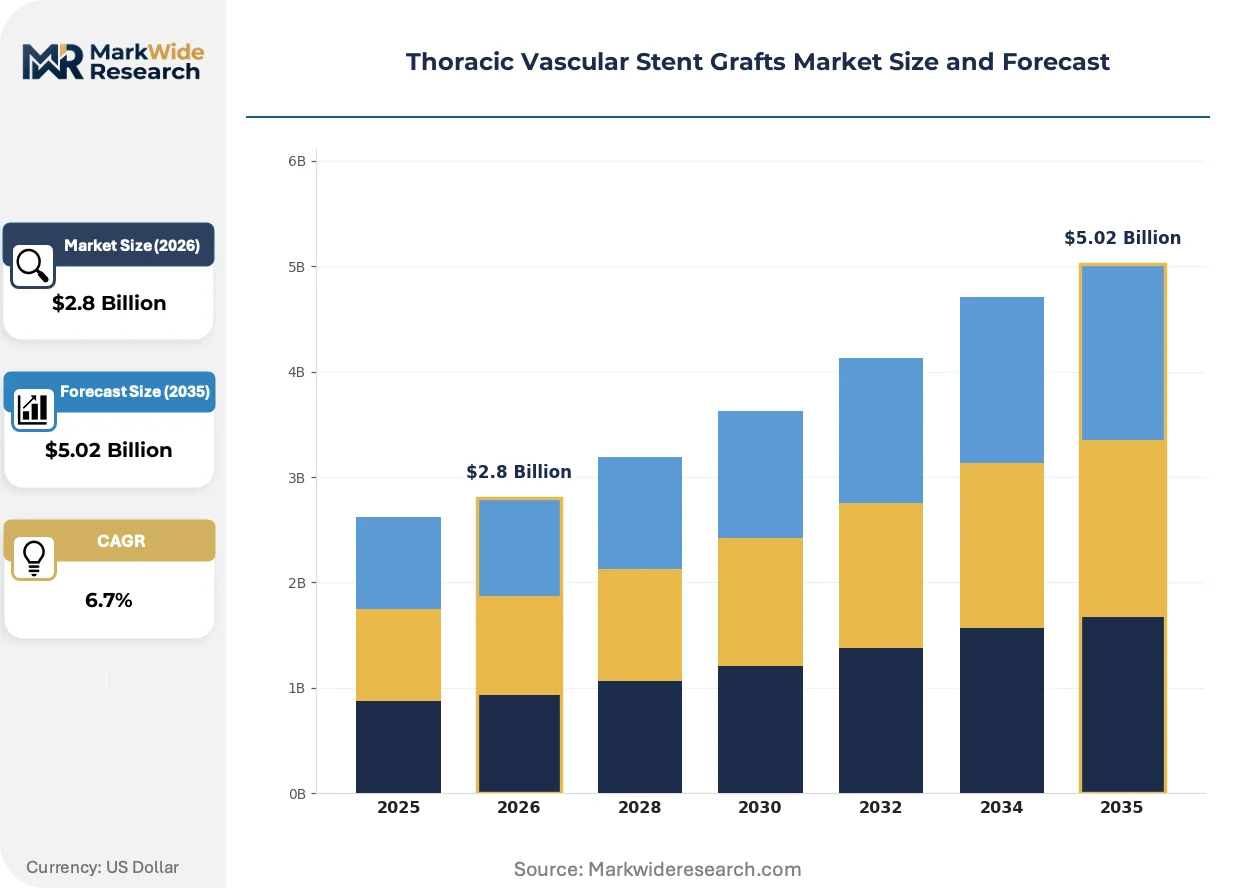
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Expanding, Balloon-Expandable, Hybrid, Coated Material: Polymer, Metal, Biodegradable, Composite End User: Hospitals, Clinics, Cardiology Centers, Outpatient Facilities Application: Aortic Aneurysm Repair, Trauma Management, Endoleak Treatment, Others |
| Companies Covered | Terumo Corporation, Artivion, Medtronic plc, Becton Dickinson & Company, CryoLife Inc., Cook Medical Inc., MicroPort Scientific Corporation, Endologix Inc., W.L. Gore & Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thoracic Vascular Stent Grafts Market Evolving Landscape
Material science advances and regulatory data requirements are recalibrating competitive advantage away from scale manufacturing toward integrated clinical evidence generation and personalized device architecture.
Composite constructions combining superelastic nitinol frameworks with bioabsorbable polymer scaffolds are rendering obsolete permanent metal implants in trauma applications where future aortic remodeling remains clinically desirable. Level I trauma centers in Germany and Japan are piloting these platforms for young blunt aortic injury patients. The technology is compressing addressable market share for conventional cobalt-chromium systems in sub-55-year-old demographics.
EU MDR post-market surveillance mandates now require systematic implant registry follow-up extending to ten years, compelling manufacturers to rebuild quality management systems around real-world evidence collection. This obligation disproportionately burdens smaller competitors lacking dedicated clinical affairs infrastructure. Fenestrated device categories face the steepest compliance cost escalation due to anatomical variability complicating standardized outcome metrics.
Hospital value analysis committees have displaced individual physician preference as the primary purchasing authority, consolidating vendor selection around total cost-of-ownership models incorporating procedural training and complication warranty provisions. This transformation is most advanced in United States integrated delivery networks and German university hospital clusters, where procurement centralization now governs 70 percent of thoracic endograft volume.
Thoracic Vascular Stent Grafts Market Segmentation
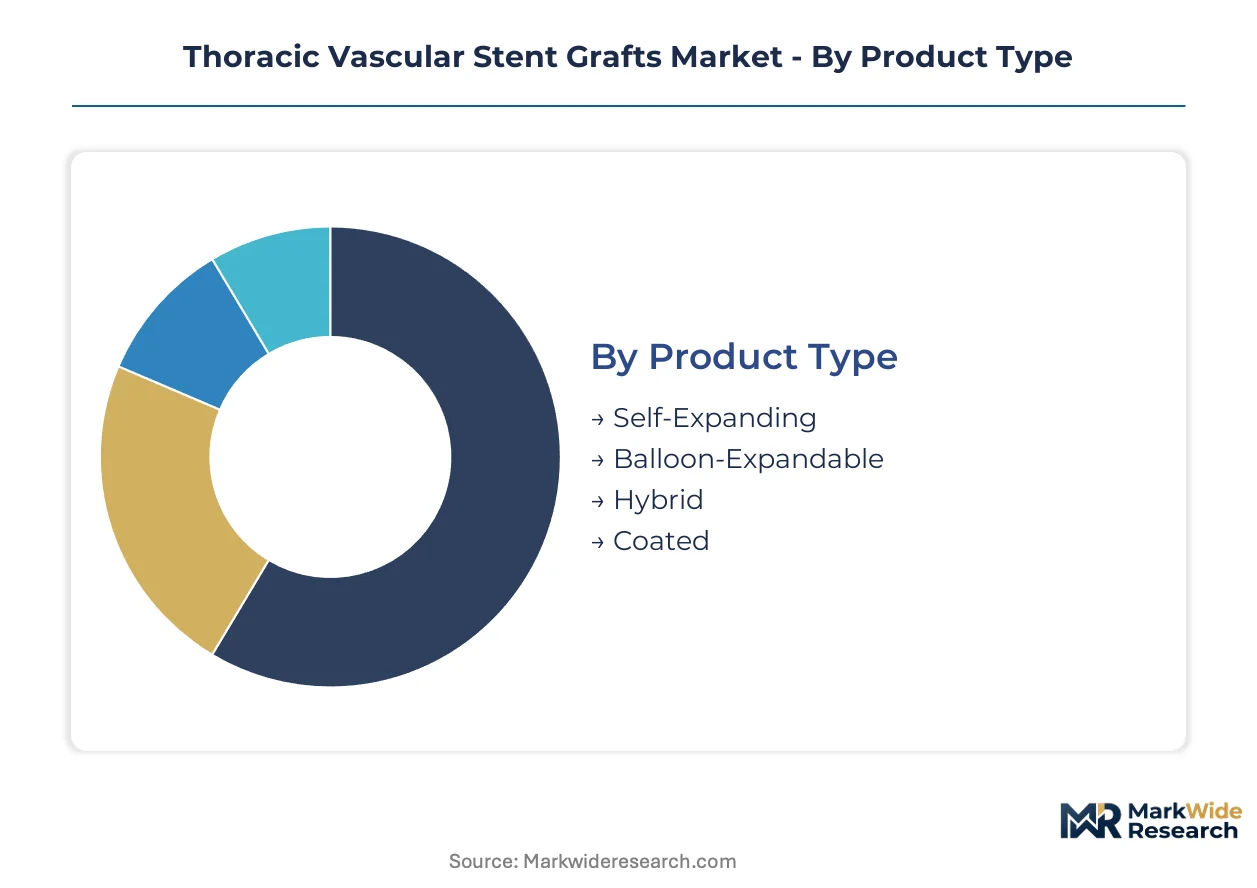
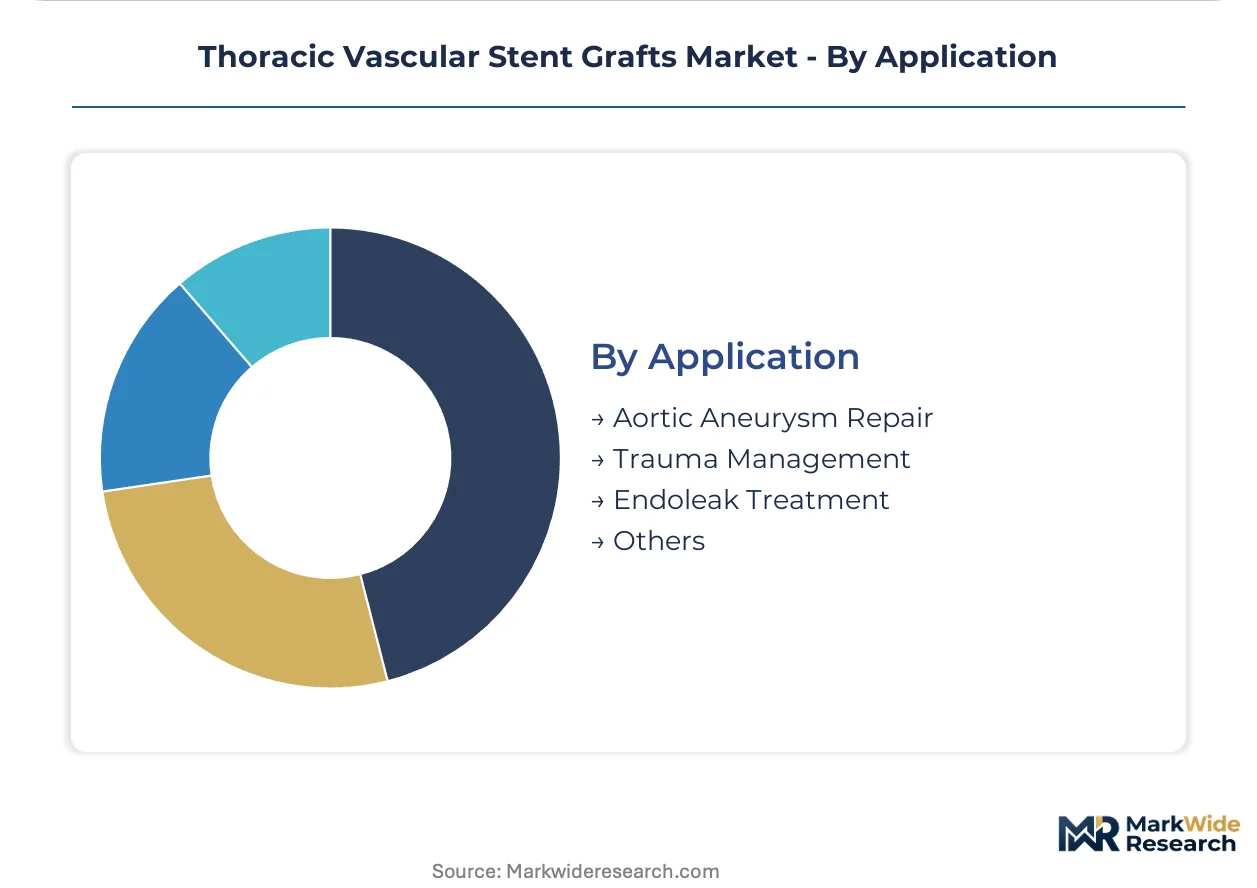
Thoracic stent graft segmentation reflects divergent clinical requirements across elective aneurysm repair and emergent trauma interventions. Device architecture, material composition, and care setting economics each create distinct procurement and reimbursement pathways.
Product Type:
Use-case spectrum spans elective conformability needs against emergent deployment constraints.
- Self-Expanding:Nitinol superelastic frameworks deploy without balloon assistance, conforming to tortuous aortic arches in elective thoracic endovascular aortic repair. Demand concentrates in United States integrated delivery networks where physician training programs favor conformable systems for arch anatomies.
- Balloon-Expandable:Stainless steel or cobalt-chromium platforms achieve precise radial force through inflation-mediated deployment, preferred in proximal landing zones requiring exact diameter matching. German university hospitals specify these for zone 0-2 repairs where positional accuracy reduces endoleak risk.
- Hybrid:Combines self-expanding body segments with balloon-expandable proximal components for complex arch reconstructions.
- Coated:Incorporates antiproliferative agents or thromboresistant surfaces to mitigate stent graft-induced new entry tears.
The dominant share belongs to Self-Expanding, while Coated is closing the gap fastest.
Material:
Cost tier stratification separates permanent implants from provisional scaffolds.
- Metal:Nitinol and cobalt-chromium alloys provide radial force and fatigue resistance for long-term aneurysm exclusion. United States hospital procurement favors metal platforms for Medicare-reimbursed elective procedures where durability expectations extend beyond ten years.
- Composite:Superelastic frameworks married to bioabsorbable polymers enable future vessel remodeling in trauma patients. Japan's Level I trauma centers pilot these for blunt aortic injury in sub-55-year-old demographics where permanent metal constrains natural growth.
- Polymer:Woven polyester or ePTFE fabric covers exclude aneurysm sacs from systemic pressure.
- Biodegradable:Magnesium alloy or polymer scaffolds resorb after temporary flow diversion in pediatric or trauma applications.
Metal retains the largest installed base, though Composite is expanding most quickly.
End User:
Customer type determines technical service bundling and inventory management intensity.
- Hospitals:Tertiary cardiac centers with structural heart programs command procurement authority through value analysis committees. United States integrated delivery networks and German university hospital clusters centralize 70 percent of thoracic endograft volume.
- Cardiology Centers:Dedicated endovascular facilities concentrate elective procedure throughput, demanding consignment inventory models and real-time consumption analytics.
- Clinics:Limited to diagnostic workup and post-procedure surveillance rather than implant deployment.
- Outpatient Facilities:Ambulatory surgical centers capture low-complexity surveillance and follow-up procedures.
Hospitals capture the dominant share, while Cardiology Centers are gaining share fastest.
Application:
Procedure acuity drives device specification and reimbursement coding differentiation.
- Aortic Aneurysm Repair:Elective thoracic endovascular aortic repair for degenerative aneurysms represents the procedural backbone, with fenestrated and branched architectures addressing juxtarenal and arch pathologies. Japan's aging demographic elevates procedure volumes within PMDA-regulated reimbursement frameworks.
- Trauma Management:Blunt aortic injury from deceleration events demands rapid deployment capability and compatibility with anticoagulated polytrauma patients. German trauma networks specify bioabsorbable-compatible platforms for young patients.
- Endoleak Treatment:Secondary interventions address persistent perfusion of aneurysm sacs following index repair.
- Others:Aortic dissection and penetrating atherosclerotic ulcer indications.
Aortic Aneurysm Repair commands the dominant share, while Trauma Management is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket approval pathways anchor the United States as the procedural volume leader, while aging demographics in Germany and Japan elevate thoracic endovascular aortic repair adoption within established reimbursement frameworks.
United States
Medicare reimbursement stability and integrated delivery network procurement centralization drive elective procedure volumes. FDA premarket approval requirements filter out undercapitalized competitors, concentrating hospital purchasing authority among established structural heart programs. The Cleveland Clinic and Mayo Clinic clusters anchor physician training and value analysis committee standard-setting.
Germany
German university hospital clusters command procurement authority through centralized value analysis frameworks that favor advanced endovascular solutions. EU MDR technical documentation obligations extend conformity assessment timelines but elevate barriers against low-cost competitors. The Heidelberg and Munich cardiac centers pilot bioabsorbable-compatible platforms for young trauma patients.
Japan
PMDA-regulated reimbursement frameworks favor advanced endovascular solutions as the aging demographic elevates thoracic aortic aneurysm prevalence. Supplementary clinical testing mandates favor multinationals with localized regulatory affairs infrastructure. Tokyo and Osaka Level I trauma centers drive adoption of composite constructions for blunt aortic injury in sub-55-year-old demographics.
China
NMPA imposes supplementary clinical testing mandates that favor multinationals with localized regulatory affairs infrastructure while domestic producers scale nitinol laser-cutting and ePTFE graft fabrication. Shanghai and Beijing tertiary cardiac centers fragment manufacturing capacity as regional supply availability expands. CDSCO harmonization efforts signal future registration pathway convergence.
India
Underpenetrated endovascular infrastructure in Delhi and Mumbai metros offers first-mover positioning as CDSCO accelerates device registration harmonization. Tertiary cardiac centers concentrate demand for thoracic stent grafts as hospital-based endovascular programs expand adoption. The All India Institute of Medical Sciences anchors physician training capacity for complex aortic anatomies.
Thoracic Vascular Stent Grafts Market Competitive Landscape
Capability concentration sits with integrated multinationals possessing dedicated clinical affairs infrastructure; scale advantage sits with diversified medical technology conglomerates. The vendor base stratifies across three tiers: premium-tier specialists with proprietary membrane technology, mid-tier regional fabricators with physician-customized sizing capabilities, and emerging domestic producers scaling automated manufacturing. Dominant competitive moves include strategic partnerships for fenestrated device development and geographic expansion through localized regulatory affairs infrastructure.
Within the premium-tier membrane technology segment, W.L. Gore & Associates exemplifies proprietary materials positioning, while Medtronic plc occupies a position as a diversified structural heart program anchor. Cook Medical Inc. represents the physician-customized sizing archetype for complex aortic anatomies. These three entities collectively illustrate the competitive tension between proprietary technology differentiation and integrated hospital contracting scale.
| Leading Market Players |
|---|
| Terumo Corporation |
| Artivion |
| Medtronic plc |
| Becton Dickinson & Company |
| CryoLife Inc. |
| Cook Medical Inc. |
| MicroPort Scientific Corporation |
| Endologix Inc. |
| W.L. Gore & Associates |
| Others |
Value Network & Pricing Analysis
Single-source ePTFE membrane dependency concentrates input risk among three specialized suppliers, compressing procurement flexibility while widening spreads between premium membrane-integrated systems and standard polyester-covered alternatives across United States and German hospital purchasing networks.
Pricing Analysis
United States integrated delivery networks command 15-20 percent unit cost advantages over German university hospital clusters due to volume aggregation and consignment inventory models. Three-tier pricing structure across premium, standard, and economy levels stratifies by graft membrane technology and fenestration complexity, with proprietary ePTFE platforms sustaining premium positioning. Cost compression in standard metal-based platforms is intensifying as Chinese domestic producers scale nitinol laser-cutting automation. Cardiology centers exhibit highest price sensitivity due to thin procedural margins, while tertiary cardiac centers with structural heart programs prioritize total cost-of-ownership models incorporating training and warranty provisions.
Supply Chain Analysis
Export control regimes governing nitinol alloy formulations and precision laser-cutting equipment restrict technology transfer to emerging manufacturing hubs, preserving incumbent advantage in superelastic framework production. Supply concentrates in the United States for proprietary membrane technology, Germany for precision cobalt-chromium processing, and China for scaled nitinol fabrication. Raw material dependencies center on nickel-titanium alloy feedstock, medical-grade ePTFE resin, and cobalt-chromium bar stock. Single-source vulnerability in specialized graft membrane supply creates bottleneck risk during demand surges. Distribution runs through direct hospital contracting networks with embedded clinical specialist support rather than independent distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical training and inventory management services now expand faster than hardware revenues as hospital value analysis committees consolidate procurement authority around total cost-of-ownership models.
For Market Incumbents: Insulate premium positioning through captive ePTFE membrane supply and embedded physician training infrastructure that raises switching costs for hospital systems. Deepen backward integration into nitinol alloy processing to offset Chinese domestic producer pricing pressure. Lock in multi-year consignment contracts with integrated delivery networks before CDSCO harmonization accelerates Indian market entry. For New Entrants and Emerging Players: Underpenetrated endovascular infrastructure in Indian tertiary cardiac centers offers first-mover positioning as hospital-based programs expand adoption. Target trauma management applications with bioabsorbable-compatible platforms where permanent metal implant constraints create white space. Pursue physician-customized fenestration design services as a differentiated entry angle against standardized off-the-shelf catalogs. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors clinical affairs infrastructure over pure manufacturing scale. Five-to-ten year viability hinges on EU MDR compliance capability and real-world evidence generation systems. Acquisition target archetype: mid-tier regional fabricators with physician-customized sizing capabilities but lacking dedicated regulatory affairs infrastructure. Signal to watch: CDSCO device registration harmonization timeline as inflection indicator for Indian market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery network contracting locks in volume through embedded training and consignment inventory models. |
| FDA Premarket Approval Pathway | Extended clinical validation requirements filter undercapitalized competitors and concentrate purchasing authority. |
| CE Marking Pathway | EU MDR technical documentation obligations elevate barriers against low-cost entrants in German markets. |
| Reimbursement Strategy | Medicare and PMDA coding alignment determines procedure volume expansion in United States and Japan. |
| Software Companion Development | Computational fluid dynamics modeling tools differentiate fenestrated device offerings for complex aortic anatomies. |
Research Methodology
Operator-level perspectives from structural heart program directors, hospital value analysis committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary interview intelligence combined with secondary validation from FDA premarket approval filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation cross-checked segment-level estimates.
Scenario-bracketing around regulatory approval timelines and reimbursement coding decisions framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product architecture, material composition, end-user facility type, and application acuity. CAGRs derived from procedure volume trajectories adjusted for demographic disease prevalence and technology penetration curves. Industry-specific inputs incorporated ISO 25539-1 fatigue testing standards and fenestrated device registry outcome data.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles or medical device tariff regimes would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory approval timelines and reimbursement stability. Material shifts in EU MDR post-market surveillance mandate implementation or NMPA clinical testing requirement changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiac Ablation Market
Cardiovascular Devices
Congestive Heart Failure Treatment Devices Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Single-Use Hemoperfusion Device Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Iliac Artery Stents Market
Cardiovascular Devices
North America Vascular Graft Market
Cardiovascular Devices
Pressure Infusion Cuffs Market
Cardiovascular Devices
Endovascular Aneurysm Repair Market
Cardiovascular Devices
Extracorporeal Membrane Oxygenation (ECMO) Market
Cardiovascular Devices
Arrhythmogenic Right Ventricular Dysplasia Treatment Market
Cardiovascular Devices
Spain Cardiovascular Devices Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Cardiac Medical Device Market
Cardiovascular Devices
Transcatheter Heart Valve Replacement (THVR) Market
Cardiovascular Devices
Anticoagulation Market