
 Artificial Airway Holders Market | 2026-2036
Artificial Airway Holders Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Airway Holders Market Outlook
The artificial airway holders category is pivoting between premium adjustable systems and commodity non-adjustable alternatives. Smiths Medical leverages polymer science expertise to sustain leadership in critical care configurations. Teleflex anchors North American hospital contracts through dedicated airway management portfolios. Flexicare Medical Limited specializes in cost-engineered disposable lines for emergency services budgets.
Artificial airway holders are mechanical stabilization devices that secure endotracheal tubes, tracheostomy tubes, or supraglottic airways using adjustable straps, bite blocks, or adhesive interfaces; most incorporate silicone or thermoplastic elastomer cushions rated for 24-72 hour skin contact to prevent pressure injury and tube displacement. Their primary purpose is maintaining patent ventilation pathways during anesthesia induction, mechanical ventilation, or resuscitation. Disposable holders capture the fastest expansion as infection control protocols harden across hospital systems, while reusable titanium-reinforced variants retain margin concentration in academic medical centers. Critical care applications generate the highest throughput volumes, whereas transportable deployment formats are gaining traction in air ambulance and field military settings.
The FDA's 510(k) clearance framework governs device entry in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements for invasive airway accessories sold in Europe. Japan's PMDA enforces JIS-compatible biocompatibility testing that adds certification lead time but filters out low-integrity suppliers. Stakeholders must monitor how dual regulatory track convergence between FDA and notified bodies reshapes portfolio rationalization decisions for holders spanning invasive and non-invasive deployment modes.
Market Dynamics
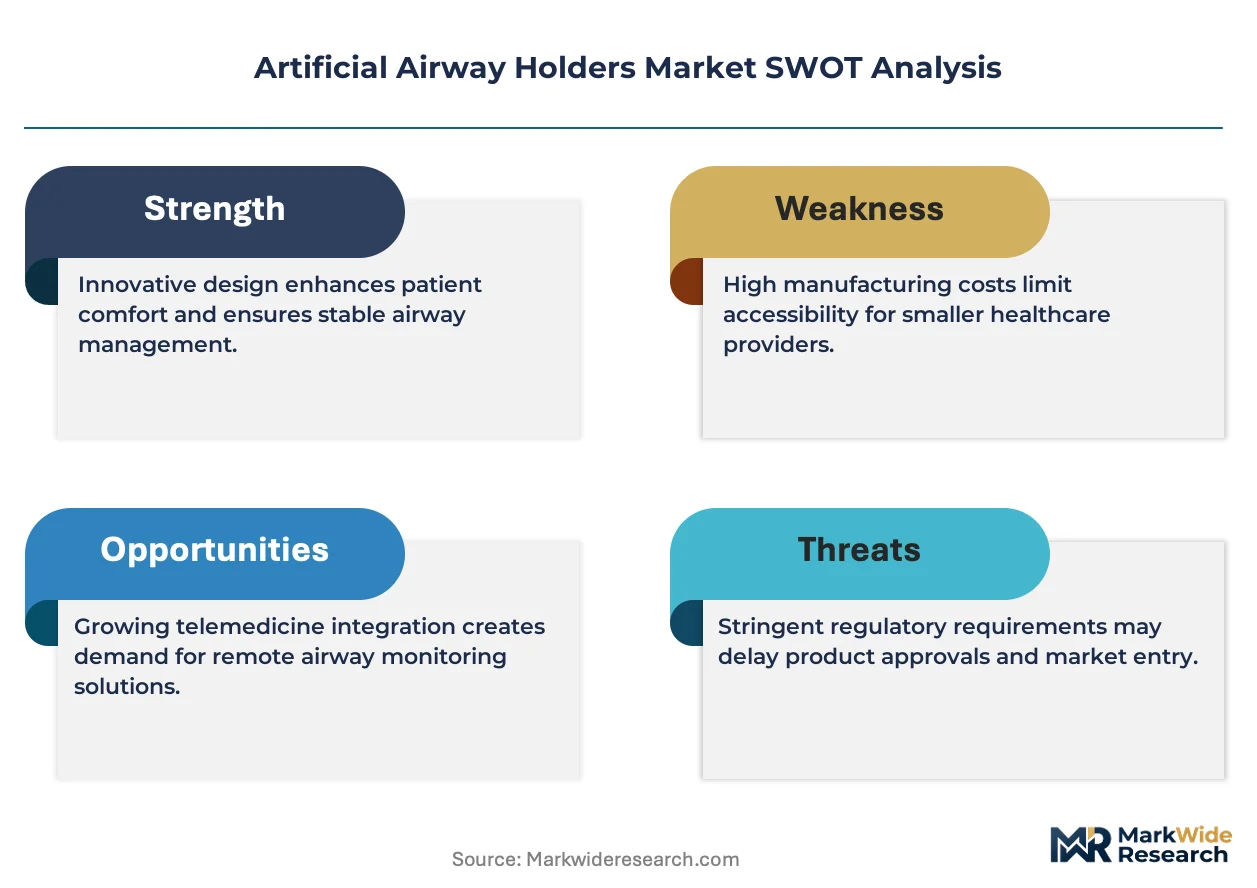
Disposable infection-control protocols are compressing procurement cycles across hospital systems, forcing manufacturers to reconfigure production lines toward single-use polymer configurations while maintaining margin structures previously sustained by reusable titanium-reinforced alternatives.
Growth Catalysts
- EU Medical Device Regulation:Strengthened clinical evidence requirements for invasive airway accessories are filtering out low-integrity suppliers, creating clearance advantages for established manufacturers with dedicated regulatory affairs infrastructure.
- Silicone elastomer cushions:Advanced thermoplastic formulations rated for 72-hour skin contact are reducing pressure injury incidence in ICU settings, driving protocol-level adoption across tertiary hospital networks.
- Air ambulance deployment:Transportable holder formats with integrated bite blocks are capturing emergency services procurement budgets as field stabilization protocols expand beyond traditional hospital boundaries.
Market Restraints
- Medical-grade silicone volatility:Petrochemical feedstock fluctuations compress gross margins on disposable lines already pressured by bulk purchasing agreements.
- Notified body concentration:EU MDR designation bottlenecks in Germany and the Netherlands extend certification timelines, freezing new product introductions for mid-tier manufacturers lacking existing CE mark portfolios.
- Supraglottic airway substitution:Laryngeal mask advances in short-duration procedures reduce endotracheal tube dependency, constraining holder attachment volumes in ambulatory surgical centers.
Strategic Opportunities
- Japan PMDA pathway optimization:JIS-compatible biocompatibility testing investments unlock premium pricing in a market where domestic procurement favors certified foreign suppliers over unverified imports.
- Military field medicine:Combat casualty care protocols are standardizing compact, multi-size adjustable holders for pre-hospital airway management in expeditionary medical units.
- Smart material convergence:Pressure-sensing polymer integration with wireless monitoring systems enables real-time displacement alerts, creating subscription revenue models beyond hardware sales.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with medical-device biocompatibility expertise command premium compensation, constraining R&D expansion at emerging manufacturers.
- Dual-track FDA-EU synchronization:Divergent evidence requirements for 510(k) versus MDR submissions force parallel clinical study designs, doubling regulatory affairs overhead without guaranteeing either clearance.
- Legacy sterilization infrastructure:Hospital systems with captive autoclave capacity resist disposable conversion despite infection control mandates, requiring field-level clinical education investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Airway Holders Market |
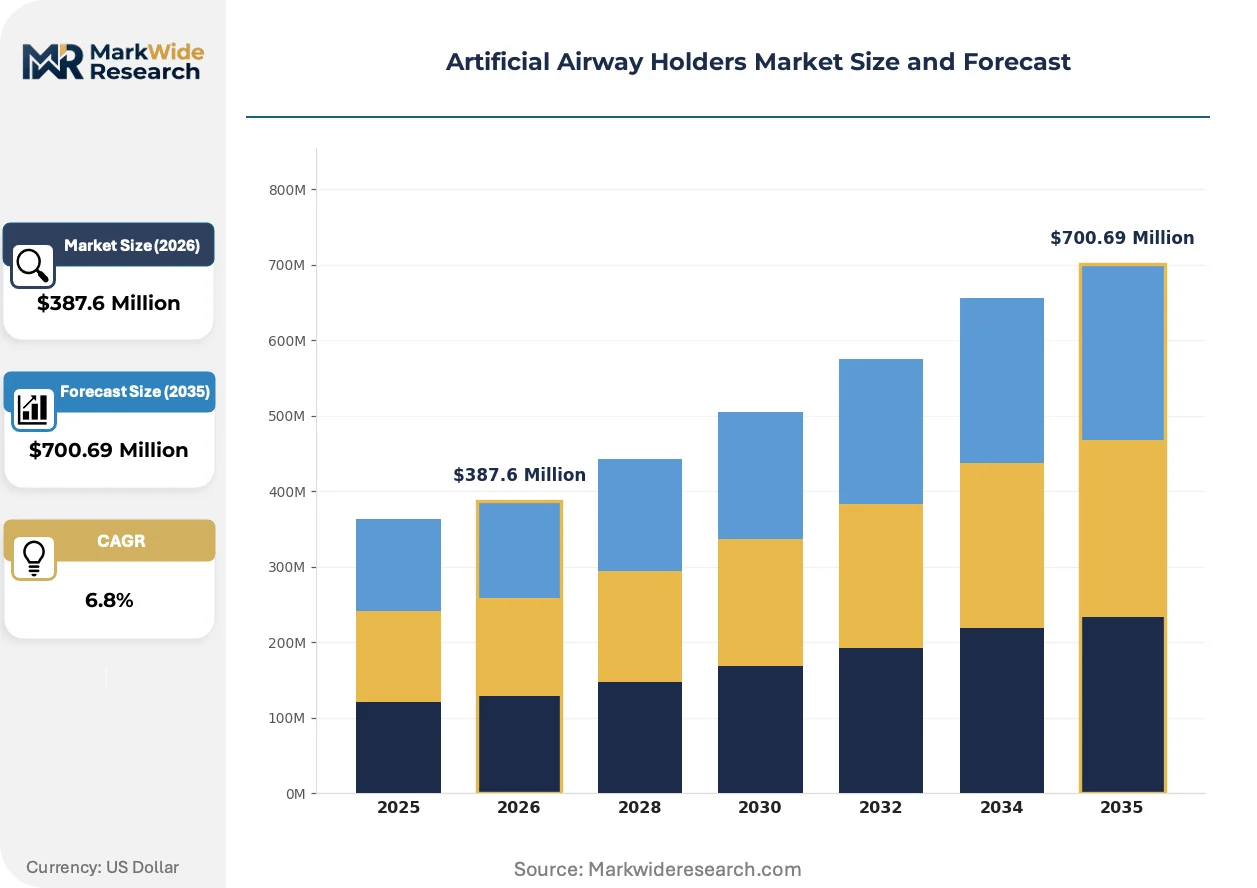
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Holders, Disposable Holders, Adjustable Holders, Non-adjustable Holders End User: Hospitals, Emergency Services, Home Care, Clinics Application: Anesthesia, Critical Care, Airway Management, Resuscitation Deployment: Invasive, Non-invasive, Hybrid, Transportable |
| Companies Covered | Smiths Medical, Teleflex, Vyaire Medical, Ambu, Flexicare Medical Limited, Armstrong Medical, Intersurgical, Mercury Medical, SunMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Airway Holders Market Strategic Shifts
Material science advances and regulatory stringency are converging to reshape product architecture, with manufacturers racing to integrate sensor capabilities while navigating divergent certification pathways across major jurisdictions.
Pressure-sensing polymer substrates embedded within holder cushions are decentralizing clinical monitoring responsibility from centralized nursing stations to bedside devices. Academic medical centers in Germany and Japan are piloting these configurations for high-risk intubations exceeding 48 hours. The technology is decentralizing alarm response workflows, compressing intervention times from minutes to seconds while generating continuous documentation streams for liability protection.
Japan's PMDA has tightened JIS T 0993 biocompatibility testing protocols for devices exceeding 24-hour skin contact, extending certification lead times by four to six months for foreign applicants. Domestic manufacturers with established testing relationships capture first-mover advantage in hospital tenders specifying extended-wear silicone configurations. Intensive care applications face the steepest compliance burden, as prolonged ventilation protocols trigger the stricter testing tier.
Hospital procurement departments are consolidating airway management spend into dedicated portfolio contracts with single-source suppliers, displacing fragmented purchasing across anesthesia, emergency, and critical care silos. Teleflex and Smiths Medical anchor these arrangements in the United States through bundled holder-tube-suction configurations. Germany's university hospital networks exhibit the most advanced procurement consolidation, with centralized biomedical engineering departments standardizing holder specifications across fifty-plus facility systems.
Artificial Airway Holders Market Segmentation
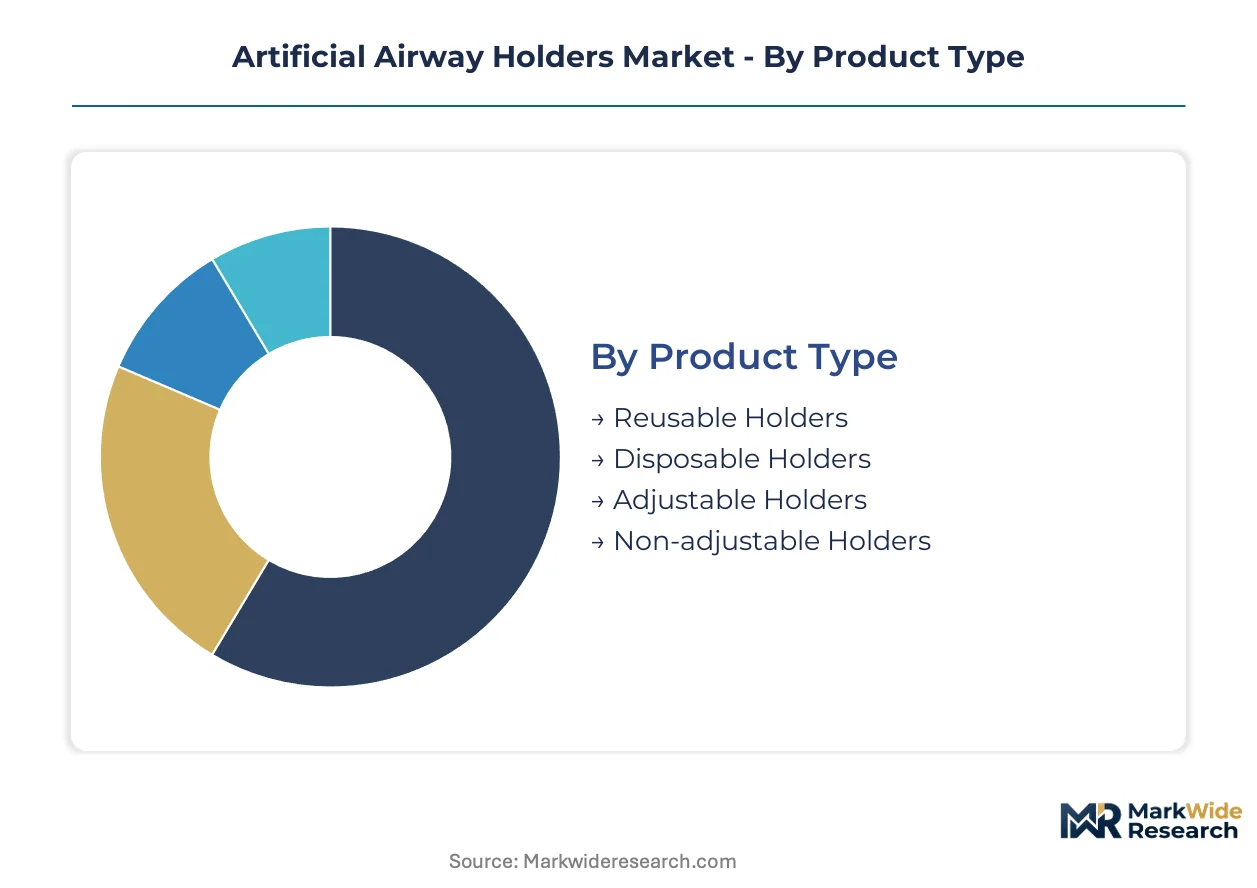
Artificial airway holders segment across material durability, clinical setting, and deployment urgency. Each dimension shapes procurement patterns differently—capital equipment cycles favor reusable titanium-reinforced systems, while infection control mandates accelerate disposable polymer turnover.
Product Type:
Capital intensity varies sharply across product categories, with reusable titanium-reinforced holders demanding substantial upfront tooling investment and sterilization validation infrastructure.
- Reusable Holders:Titanium-reinforced frames with autoclavable silicone cushions serve academic medical centers with captive sterilization departments. Germany's university hospital networks anchor demand here, prioritizing total cost-of-ownership models over per-procedure pricing.
- Disposable Holders:Single-use polymer configurations with integrated adhesive interfaces dominate emergency services procurement in the United States. Infection control protocol hardening across tertiary hospital systems is compressing procurement cycles toward these lines despite petrochemical feedstock margin pressure.
- Adjustable Holders:Multi-size strap systems with bite block integration command premium positioning in anesthesia suites.
- Non-adjustable Holders:Fixed-dimension commodity lines serve cost-constrained ambulatory settings with standardized tube specifications.
Reusable holders absorb the bulk of installed capacity in academic medical centers; disposable holders are expanding most quickly across consolidated hospital procurement networks.
End User:
Customer concentration patterns reveal where purchasing authority has shifted—tertiary hospitals now control centralized airway management spend, while emergency services operate on decentralized rapid-replenishment models.
- Hospitals:Tertiary ICU departments in the United States, Germany, and Japan generate the highest throughput volumes. Bundled portfolio contracts with Smiths Medical and Teleflex displace fragmented purchasing across anesthesia, emergency, and critical care silos.
- Emergency Services:Air ambulance and field military units in the United States are standardizing transportable formats with integrated bite blocks. Combat casualty care protocols in expeditionary medical units drive specification for compact, multi-size adjustable systems.
- Home Care:Long-term tracheostomy patients in Japan utilize extended-wear silicone configurations rated for 72-hour skin contact.
- Clinics:Ambulatory surgical centers face volume constraints from laryngeal mask substitution in short-duration procedures.
Hospitals command the deepest procurement consolidation; emergency services are climbing the fastest as field stabilization protocols expand beyond traditional boundaries.
Application:
Clinical urgency and duration of intubation determine material specifications and monitoring integration requirements.
- Anesthesia:Short-duration induction protocols in ambulatory surgical centers favor lightweight polymer holders with rapid-release mechanisms.
- Critical Care:Prolonged ventilation exceeding 48 hours in German and Japanese academic medical centers is piloting pressure-sensing polymer substrates. These configurations decentralize alarm response workflows from centralized nursing stations to bedside devices.
- Airway Management:Standardized stabilization across OR and ICU environments drives specification consistency within hospital networks.
- Resuscitation:Pre-hospital emergency protocols demand disposable lines with immediate deployment capability and minimal training requirements.
Critical care applications concentrate the most advanced material science adoption; resuscitation is gaining share fastest as field protocols standardize.
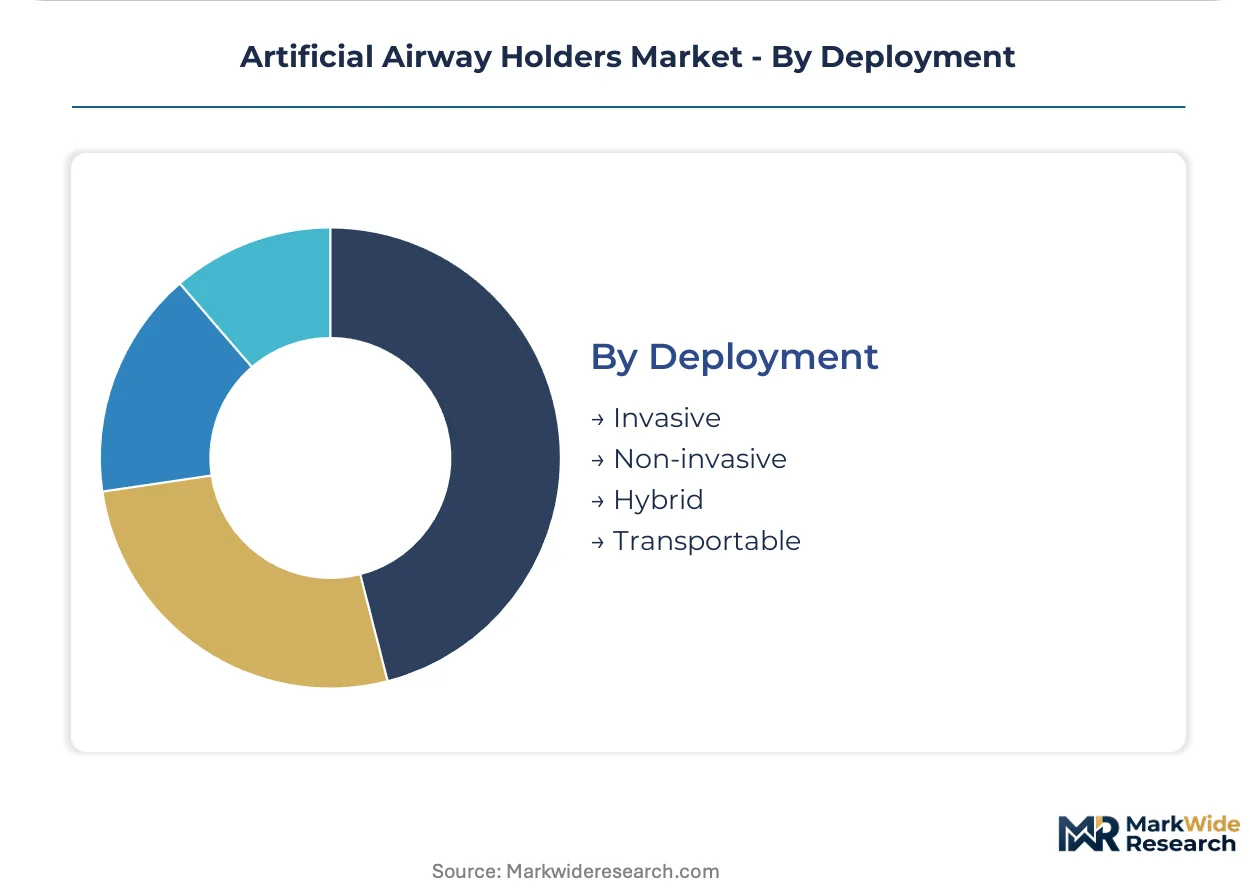
Deployment:
Physical configuration determines regulatory pathway complexity and supply chain logistics requirements.
- Invasive:Endotracheal and tracheostomy tube holders face the steepest biocompatibility testing burden under Japan's PMDA JIS T 0993 protocols for devices exceeding 24-hour skin contact.
- Non-invasive:Supraglottic airway stabilization systems encounter reduced regulatory scrutiny but face substitution pressure from advanced laryngeal mask designs.
- Hybrid:Convertible holders spanning invasive and non-invasive modes force parallel FDA 510(k) and EU MDR submission strategies, doubling regulatory affairs overhead.
- Transportable:Compact formats with integrated bite blocks capture military field medicine standardization in the United States and air ambulance procurement budgets.
Invasive deployment absorbs the bulk of regulatory validation investment; transportable configurations are expanding most quickly across emergency services and military procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American airway holder manufacturing through Smiths Medical's polymer science operations, while tertiary hospital procurement consolidation across three continents reshapes regional demand patterns.
United States
The FDA's 510(k) clearance framework governs device entry, with tertiary ICU departments driving bundled portfolio contracts through dedicated airway management suppliers. The Minneapolis-St. Paul corridor concentrates polymer formulation expertise for critical care configurations.
Germany
University hospital networks standardize holder specifications across fifty-plus facility systems under the EU Medical Device Regulation's strengthened clinical evidence requirements. The Rhine-Ruhr metropolitan region anchors notified body concentration that extends certification timelines for invasive airway accessories.
Japan
PMDA enforces JIS T 0993 biocompatibility testing protocols for devices exceeding 24-hour skin contact, filtering out low-integrity suppliers in intensive care applications. The Kanto region around Tokyo captures first-mover advantage in extended-wear silicone configurations for prolonged ventilation protocols.
United Kingdom
NHS procurement consolidation favors disposable infection-control protocols, compressing procurement cycles toward single-use polymer lines despite petrochemical feedstock margin pressure. The Greater London hospital network pilots pressure-sensing polymer substrates for high-risk intubations.
India
CDSCO medical device regulations are tightening quality standards for imported airway accessories, creating clearance advantages for established manufacturers with dedicated regulatory affairs infrastructure. The Maharashtra-Gujarat pharmaceutical corridor is developing cost-engineered disposable manufacturing capacity for emergency services budgets.
Artificial Airway Holders Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the artificial airway holders category, with polymer science expertise determining tier placement. The market structure concentrates around three strategic archetypes: premium adjustable system specialists, commodity disposable fabricators, and integrated critical care portfolio suppliers. M&A activity targets regulatory clearance capabilities, while capacity expansion focuses on single-use polymer lines to match infection control protocol hardening.
Within the premium-tier vector, Smiths Medical and Teleflex occupy positions that exemplify integrated portfolio dominance through bundled holder-tube-suction configurations. Flexicare Medical Limited represents the cost-engineered disposable archetype, anchoring emergency services procurement with polymer lines optimized for rapid-replenishment models. These three entities collectively illustrate how regulatory infrastructure investment separates sustainable participants from marginal competitors across FDA, EU MDR, and Japan PMDA jurisdictions.
| Leading Market Players |
|---|
| Smiths Medical |
| Teleflex |
| Vyaire Medical |
| Ambu |
| Flexicare Medical Limited |
| Armstrong Medical |
| Intersurgical |
| Mercury Medical |
| SunMed |
| Others |
Value Chain & Pricing Dynamics
Single-use polymer conversion across hospital systems is compressing cost structures while concentrating procurement authority with consolidated GPOs and tertiary hospital networks. This manufacturing transition simultaneously erodes margin buffers on disposable lines and rewards suppliers with captive medical-grade silicone sourcing relationships.
Pricing Analysis
Throughput-based pricing anchors artificial airway holder contracts, with per-procedure costing models dominating emergency services procurement while total cost-of-ownership frameworks govern academic medical center negotiations. Price differentiation separates FDA 510(k)-cleared configurations from unverified imports, with JIS T 0993 certification in Japan commanding additional premiums. Cost compression in commodity disposable tiers is intensifying because petrochemical feedstock volatility squeezes polymer margins. Emergency services budgets exhibit the highest price sensitivity, whereas German university hospital networks prioritize clinical evidence packages over per-unit economics.
Supply Chain Analysis
Biocompatibility certification gating filters supplier participation, with EU MDR notified body bottlenecks in Germany and the Netherlands freezing mid-tier entrants lacking established CE mark portfolios. Manufacturing concentrates in the United States, Germany, and Japan, with the Minneapolis-St. Paul corridor anchoring polymer formulation expertise. Supply chains draw from medical-grade silicone, thermoplastic elastomers, and titanium feedstocks. Single-source vulnerability runs through concentrated notified body capacity for invasive device classifications. Distribution runs through dedicated airway management portfolio contracts with hospital procurement departments and rapid-replenishment channels for emergency services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory clearance infrastructure acts as a consolidation mechanism, with EU MDR clinical evidence requirements and Japan PMDA biocompatibility protocols forcing capital-constrained competitors toward exit.
For Market Incumbents: To counter supraglottic airway substitution in ambulatory surgical centers, anchor hospital system loyalty through bundled holder-tube-suction configurations and deepen backward integration into medical-grade silicone compounding to secure margin protection against petrochemical volatility. For New Entrants and Emerging Players: Air ambulance and expeditionary military units represent the most penetrable buyer archetype, as field stabilization protocol standardization creates specification windows for compact, multi-size adjustable formats without entrenched supplier relationships; pursue direct contracting with emergency services procurement rather than hospital GPO channels. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier manufacturers possessing existing CE mark portfolios and FDA 510(k) clearances given EU MDR designation bottlenecks freezing new product introductions; monitor notified body capacity expansion announcements as the inflection signal for MDR backlog resolution and renewed competitive entry.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Investment | Strengthened biocompatibility documentation filters low-integrity suppliers from German hospital tenders. |
| Japan PMDA JIS T 0993 Certification | Extended-wear silicone testing unlocks premium positioning in Tokyo-intensive care procurement. |
| Hospital System Portfolio Partnership | Bundled airway management contracts displace fragmented purchasing across anesthesia and critical care silos. |
| Pressure-Sensing Polymer Integration | Wireless monitoring substrate development enables subscription revenue beyond hardware sales. |
| Military Field Medicine Standardization | Combat casualty care protocol adoption secures multi-year expeditionary medical unit supply agreements. |
Study Parameters
Independent corroboration across hospital procurement committee interviews, biomedical engineering director consultations, and emergency services supply chain manager discussions underwrites the qualitative findings. Primary fieldwork engaged GPO contracts managers, regulatory affairs specialists at notified bodies, and polymer formulation chemists. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation summaries, and Japan PMDA QMS inspection records. Bottom-up demand modeling across end-user segments triangulates against top-down market sizing from trade flow analysis.
Rate-of-change decomposition separates volume expansion from price trajectory across the projection horizon. Segmentation modeling incorporates material durability tiers, clinical setting intensity, deployment urgency classifications, and regulatory pathway complexity. CAGRs derive from procedure volume elasticity estimates, infection control protocol adoption curves, and military procurement cycle timing. Forecast inputs include silicone elastomer price indices and notified body capacity utilization rates.
Revisions become necessary when EU MDR designation timelines extend beyond current bottlenecks or when Japan PMDA tightens JIS T 0993 testing protocols further. Forecasts reflect assumptions about hospital consolidation trajectories and polymer feedstock supply stability. A model refresh is warranted upon material change in military field medicine standardization schedules or supraglottic airway substitution rates in ambulatory settings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Airway Catheters Market
Anesthesiology
Global Anesthesia Delivery Systems Market
Anesthesiology
Anesthesia Delivery Units Market
Anesthesiology
Anaesthesia Machines Market
Anesthesiology
Smart Anesthesia System Market
Anesthesiology
Dental Anesthesia Market
Anesthesiology
Anesthesia CO2 Absorbent Market
Anesthesiology
Global Anesthesia and Respiratory Devices Market
Anesthesiology
Artificial Coma/Medically Induced Coma Market
Anesthesiology
Global Anesthesia Endotracheal Tubes Market
Anesthesiology
Delirium Market
Anesthesiology
Inhalation Anesthetics Market
Anesthesiology
Anesthetics Market
Anesthesiology
Anesthesia Breathing Bags Market
Anesthesiology
Aspirating System Market
Anesthesiology
Vasopressin for Vasoplegic Shock Market