
 Global Cardiac Resynchronization Therapy Market | 2026-2036
Global Cardiac Resynchronization Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiac Resynchronization Therapy Market Foresight
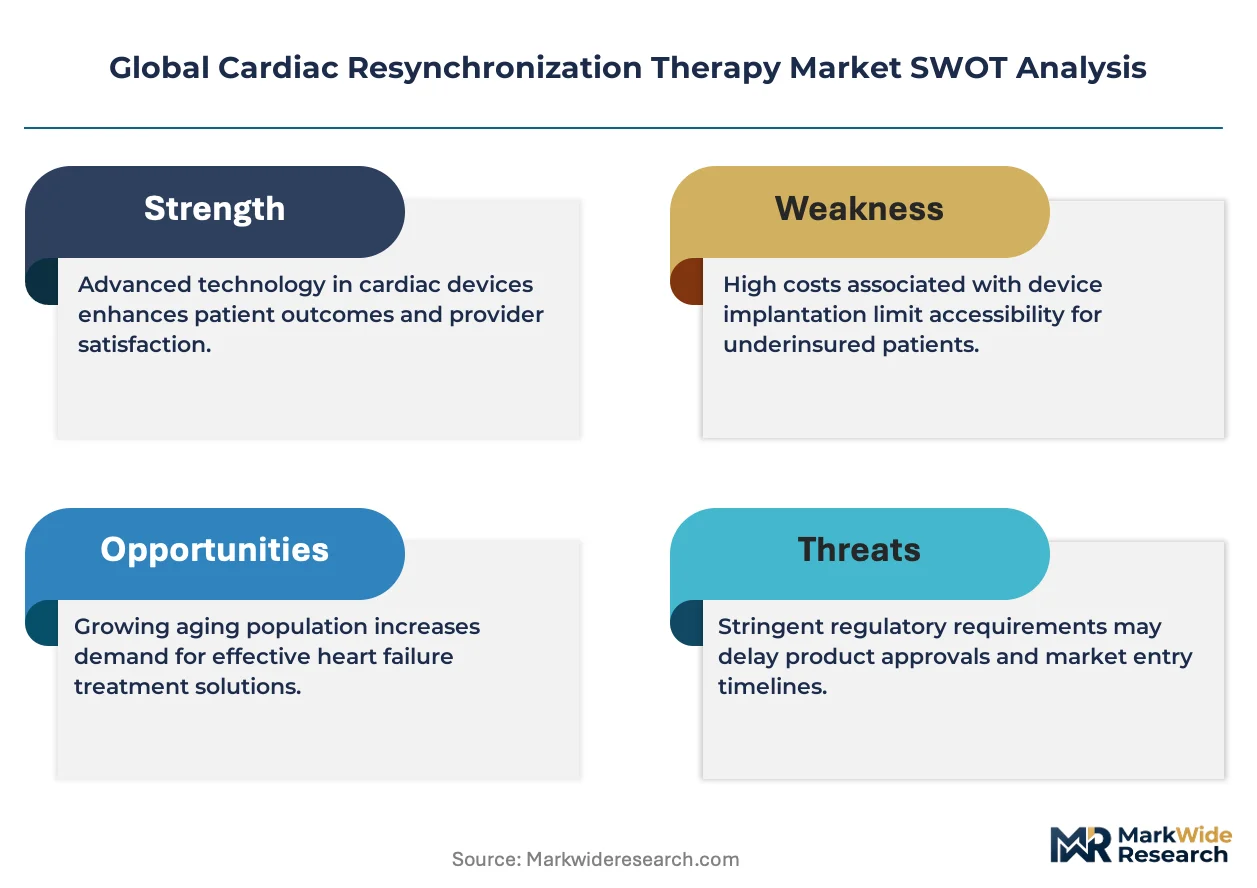
The divergence between premium MRI-compatible CRT-D systems and commodity CRT-P devices is realigning procurement patterns across hospital networks. Medtronic leverages its integrated manufacturing scale to dominate the high-complexity segment, while Abbott sustains competitive positioning through bi-ventricular pacing specialization. Boston Scientific Corporation anchors its presence in electrophysiology lab channels with adaptive CRT algorithms that reduce implant procedure time.
Cardiac resynchronization therapy delivers timed electrical impulses to both ventricles via transvenous or leadless delivery systems, resynchronizing cardiac contraction in patients with reduced ejection fraction and QRS prolongation. CRT-D systems incorporating defibrillation capability command the dominant revenue share due to higher reimbursement and dual-function clinical utility. Leadless devices represent the fastest-growing technology segment as infection risk reduction drives physician preference, while wireless CRT approaches remain early-stage with concentrated R&D investment from specialized players.
FDA premarket notification requirements and EU MDR technical documentation standards shape device approval timelines and post-market surveillance obligations for manufacturers. The EPA oversees lithium battery disposal protocols embedded in CRT generator end-of-life management, adding compliance layers to reverse logistics. Stakeholders must monitor adaptive CRT algorithm regulatory classification shifts and reimbursement coding updates that will determine commercial viability of next-generation pacing modalities.
Market Dynamics
The cardiac resynchronization therapy market pivots on the tension between leadless device miniaturization and established transvenous infrastructure, as electrophysiology labs weigh infection-risk reduction against capital reinvestment cycles and physician retraining requirements.
Growth Catalysts
- EU MDR recertification timelines:Accelerated device refresh cycles are pushing hospitals toward MRI-compatible CRT-D upgrades before legacy systems lose market access, compressing replacement windows across German and French hospital networks.
- Leadless delivery systems:Transcatheter implant techniques eliminate lead-related complications, driving physician preference shifts in high-volume implant centers where redo procedures carry substantial cost penalties.
- Metropolitan hospital cluster density:United States electrophysiology lab concentration in urban corridors creates concentrated demand zones where reimbursement alignment and specialist availability reinforce adoption momentum.
Market Restraints
- Lithium battery supply concentration:Generator power source dependency on limited cathode material suppliers exposes manufacturers to input volatility and EPA disposal protocol compliance layers.
- Transvenous lead extraction complexity:Device replacement procedures carry elevated perforation risk in patients with multiple prior implants, constraining upgrade willingness among long-dwelling CRT populations.
- FDA premarket notification burden:Adaptive algorithm classification uncertainty extends approval timelines for next-generation pacing modalities, deferring commercial launch schedules.
Strategic Opportunities
- Japan's aging heart failure demographic:PMDA accelerated review pathways for breakthrough devices create favorable entry conditions for wireless CRT platforms targeting underpenetrated rural prefectures.
- Bi-ventricular pacing specialization:Convergence of hemodynamic monitoring sensors with CRT generators enables real-time optimization, opening differentiated positioning for integrated device-ecosystem vendors.
- India's CDSCO medical device rules:Local manufacturing incentives and streamlined import substitution frameworks offer cost-advantaged production bases for standard CRT-P devices.
Industry Challenges
- Electrophysiologist training bottlenecks:Leadless implant technique proficiency requires dedicated proctoring programs, limiting rollout velocity in community hospital settings outside academic medical centers.
- Generator-battery end-of-life logistics:EPA hazardous waste protocols and reverse supply chain infrastructure gaps complicate patient recall compliance and device retrieval economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiac Resynchronization Therapy Market |
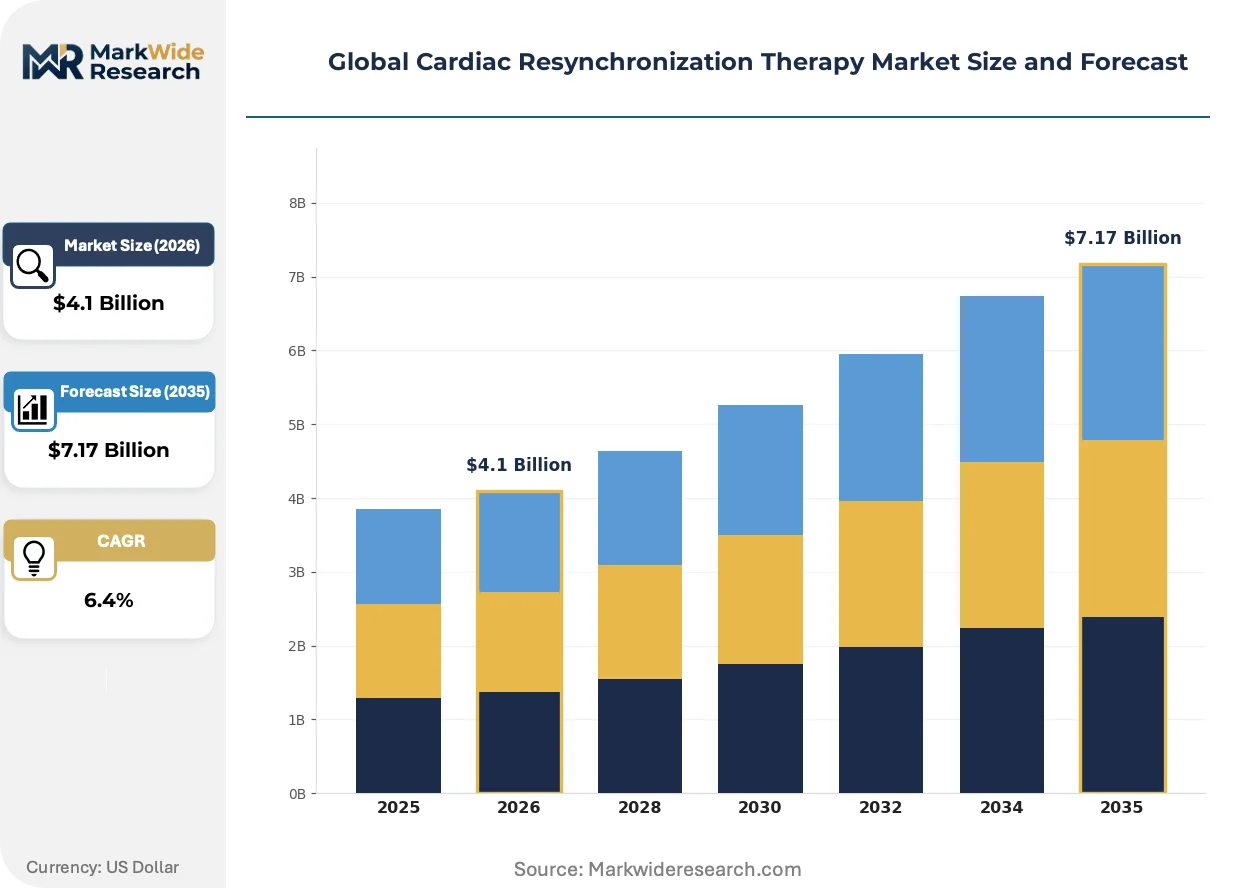
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: CRT-P, CRT-D, Leadless Devices, MRI-Compatible Devices Therapy Application: Heart Failure Management, Ventricular Dysynchrony, Arrhythmia Control, Sudden Cardiac Arrest Prevention End User: Cardiology Clinics, Electrophysiology Labs, Specialty Hospitals, Ambulatory Surgery Centers Technology: Bi-Ventricular Pacing, Adaptive CRT, Multipoint Pacing, Wireless CRT |
| Companies Covered | Medtronic, Abbott, Boston Scientific Corporation, BIOTRONIK, MicroPort Scientific Corporation, LivaNova PLC, MEDICO S.R.L., EBR Systems, Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiac Resynchronization Therapy Market Shifts & Advancements
Active convergence of sensor-enabled hemodynamic feedback, regulatory pathway compression, and procurement model restructuring is redefining competitive advantage in cardiac rhythm management.
Leadless CRT technology is integrating multi-sensor arrays for real-time ventricular contractility assessment directly into the pacing electrode. Major academic electrophysiology programs in the United States and Germany are adopting these systems at measured pace, constrained by capital equipment cycles. The technology is integrating hemodynamic optimization into standard pacing workflows, compressing the clinical differentiation window between premium and standard device tiers.
EU MDR technical documentation standards now mandate extended post-market surveillance for active implantable devices, including systematic follow-up of battery longevity and lead performance. Manufacturers face expanded clinical data obligations that favor integrated players with established registries. High-complexity CRT-D systems with defibrillation capability face the steepest compliance burden, driving consolidation of notified body relationships among mid-tier competitors.
Hospital procurement committees increasingly unbundle device selection from implant procedure contracting, separating capital equipment decisions from physician preference items. Integrated delivery networks in United States metropolitan markets are centralizing CRT generator purchasing through group purchasing organizations, displacing individual hospital autonomy. This restructuring is most visible in Texas and California health systems where electrophysiology service line consolidation has advanced furthest.
Global Cardiac Resynchronization Therapy Market Segmentation
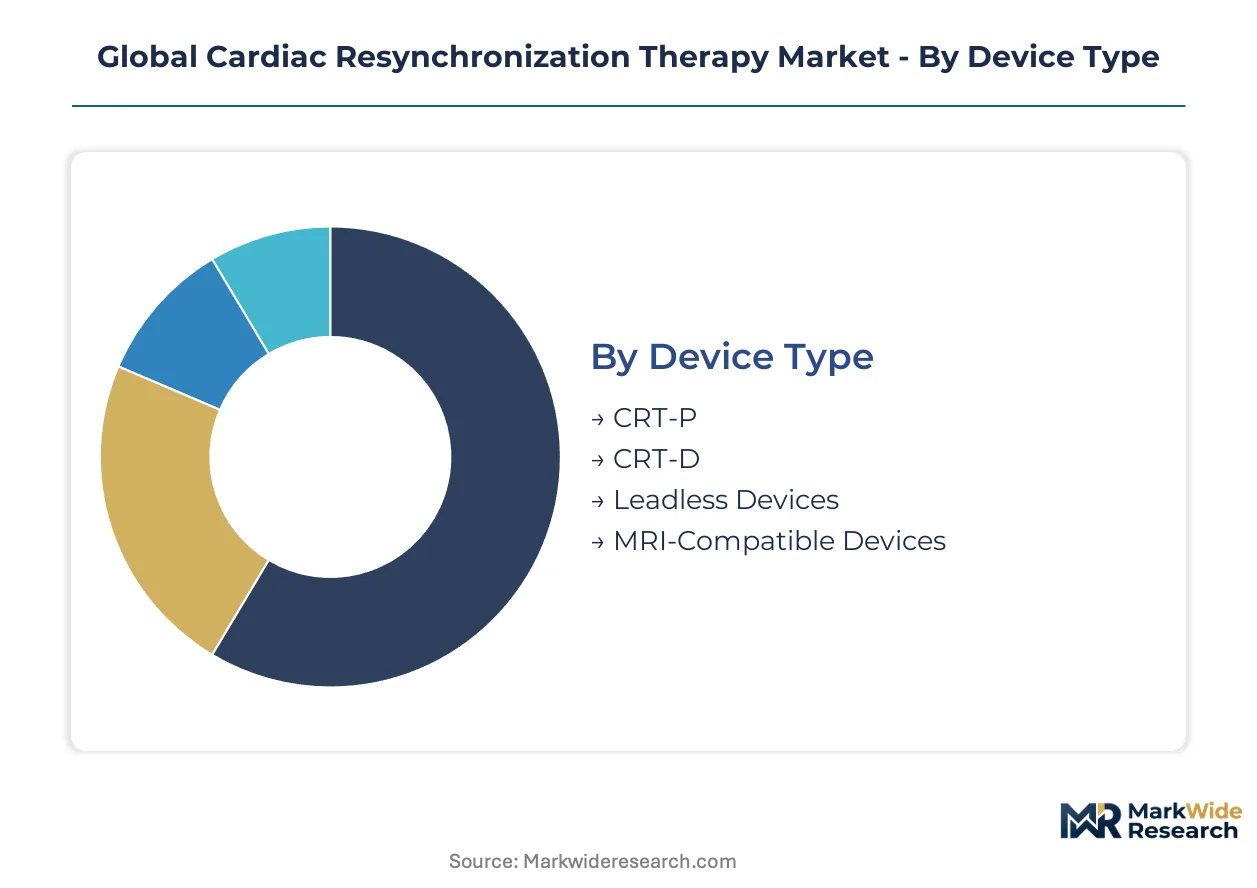
CRT market segmentation reveals distinct regulatory pathways and procurement economics across device tiers. FDA premarket approval requirements and EU MDR technical documentation standards create asymmetric compliance burdens that favor integrated manufacturers with established quality management systems.
Device Type:
FDA premarket notification (510(k)) pathways apply to CRT-P devices, while CRT-D systems require premarket approval (PMA) with extended clinical trials; leadless devices navigate breakthrough device designation routes.
- CRT-D:Defibrillation-capable generators incorporate high-voltage capacitors and tiered therapy algorithms. Demand concentrates in United States metropolitan hospital clusters where dual-chamber ICD reimbursement codes align with electrophysiology lab density. EU MDR recertification timelines compress replacement windows for legacy systems.
- Leadless Devices:Transcatheter delivery eliminates transvenous lead extraction risks through self-contained pacing electrodes. German specialty hospitals and Japanese academic medical centers drive early adoption where redo procedure costs and infection liability shape procurement decisions. PMDA accelerated review pathways favor breakthrough designations.
- CRT-P:Standard biventricular pacing without defibrillation capability serves cost-sensitive patient populations.
- MRI-Compatible Devices:Conditional labeling for magnetic resonance imaging access requires specialized lead insulation and generator shielding.
CRT-D sits at the top of the volume ranking, with leadless devices climbing the fastest.
Therapy Application:
Reimbursement coding density varies sharply across clinical indications, with heart failure management commanding established DRG classifications while emerging applications face coverage determination lags.
- Heart Failure Management:NYHA Class III-IV patients with reduced ejection fraction and QRS prolongation constitute the core addressable population. United States electrophysiology labs and German specialty hospitals generate concentrated procedure volumes where guideline-directed medical therapy failure triggers CRT evaluation. CMS national coverage determinations establish payment parity across implant settings.
- Sudden Cardiac Arrest Prevention:Primary and secondary prevention indications leverage shared generator platforms with extended longevity programming. Japanese metropolitan hospital networks and United States integrated delivery systems prioritize devices with remote monitoring connectivity to reduce in-person follow-up burden. PMDA and FDA both mandate post-approval safety surveillance for pediatric and congenital heart disease extensions.
- Ventricular Dysynchrony:Mechanical dyssynchrony assessment via echocardiography or cardiac MRI guides patient selection.
- Arrhythmia Control:Atrial fibrillation burden reduction through rate smoothing and mode-switching algorithms.
Heart failure management captures the dominant share of procedures, though sudden cardiac arrest prevention is gaining share fastest among guideline-expanded populations.
End User:
Capital equipment requirements and physician credentialing standards create tiered access barriers that concentrate high-complexity implants in academic-affiliated settings.
- Specialty Hospitals:Dedicated cardiovascular centers maintain 24/7 electrophysiology coverage and hybrid operating room capabilities for complex lead extraction. German university hospitals and United States academic medical centers generate disproportionate CRT-D volumes where fellowship-trained faculty anchor referral networks. EU MDR mandates systematic device registries in these high-volume implant centers.
- Electrophysiology Labs:Procedure-focused units within larger hospital systems optimize throughput through dedicated anesthesia and imaging support. Texas and California health systems in the United States have consolidated electrophysiology service lines, centralizing procurement through group purchasing organizations. FDA inspectional oversight targets these labs for adverse event reporting compliance.
- Cardiology Clinics:Outpatient-based practices manage pre-implant evaluation and post-discharge device monitoring.
- Ambulatory Surgery Centers:Lower-acuity settings capture select CRT-P procedures where patient comorbidity profiles permit same-day discharge.
Specialty hospitals anchor implant volume, with electrophysiology labs expanding most quickly through service line consolidation.
Technology:
Algorithm sophistication and sensor integration differentiate premium tiers, with regulatory classification uncertainty delaying commercialization of adaptive pacing modalities.
- Bi-Ventricular Pacing:Established simultaneous or sequential stimulation of right and left ventricles via transvenous coronary sinus lead placement. United States and German implant centers favor this proven approach where physician training infrastructure and device longevity data support standardized workflows. FDA 510(k) clearance pathways apply to incremental algorithm modifications.
- Wireless CRT:Ultrasound or radiofrequency energy transfer eliminates intravascular leads entirely, enabling pacing in patients with obstructed venous anatomy. Japanese rural prefectures and United States tertiary centers with structural heart disease specialization drive pilot adoption where transvenous implant failure rates run highest. PMDA breakthrough device designation and FDA early feasibility study frameworks govern initial commercial access.
- Adaptive CRT:Automatic adjustment of pacing intervals based on real-time hemodynamic feedback or intrinsic conduction sensing.
- Multipoint Pacing:Multiple left ventricular stimulation sites optimize electrical activation patterns.
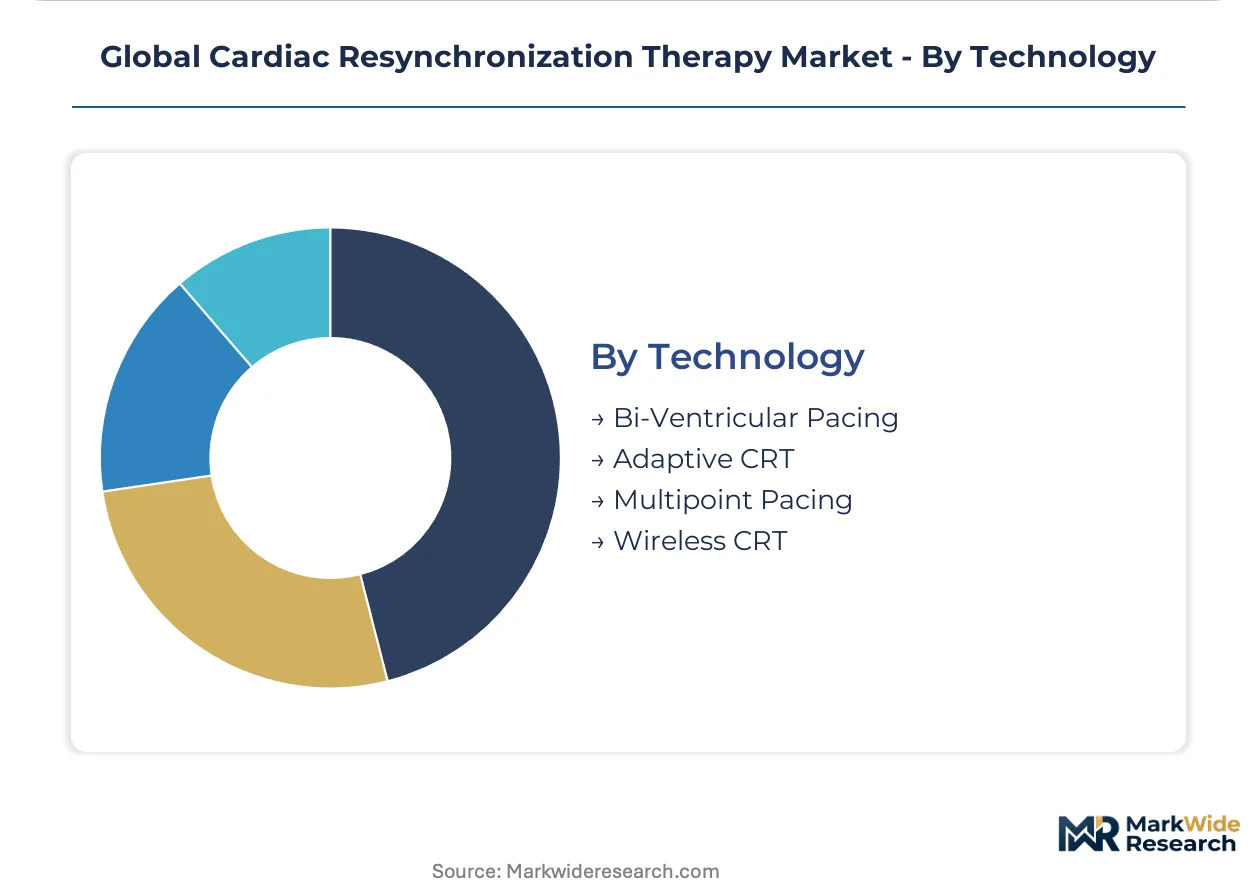
Bi-ventricular pacing maintains volume leadership, with wireless CRT showing the steepest expansion trajectory among next-generation platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fellowship-trained electrophysiologists cluster in metropolitan hospital corridors across Germany, the United States, and Japan, anchoring concentrated CRT implant volumes where referral networks and reimbursement alignment reinforce procedure density.
United States
Integrated delivery networks in Texas and California health systems centralize CRT generator purchasing through group purchasing organizations, displacing individual hospital autonomy. FDA premarket approval pathways for CRT-D systems require extended clinical trials, compressing launch schedules for next-generation devices. Electrophysiology lab concentration in urban corridors creates demand zones where CMS national coverage determinations establish payment parity.
Germany
University hospitals generate disproportionate CRT-D volumes where EU MDR recertification timelines accelerate device refresh cycles before legacy systems lose market access. German specialty hospitals maintain 24/7 electrophysiology coverage and hybrid operating room capabilities for complex lead extraction. The Bavarian medical technology cluster anchors notified body relationships that favor integrated manufacturers with established quality management systems.
Japan
PMDA accelerated review pathways for breakthrough devices create favorable entry conditions for wireless CRT platforms targeting underpenetrated rural prefectures. Japanese metropolitan hospital networks prioritize devices with remote monitoring connectivity to reduce in-person follow-up burden. The Kanto region's academic medical centers drive early adoption of leadless systems where redo procedure costs shape procurement decisions.
India
CDSCO medical device rules offer local manufacturing incentives and streamlined import substitution frameworks for standard CRT-P devices. Maharashtra and Gujarat host emerging production bases where cost-advantaged manufacturing meets rising heart failure patient volumes. Cardiology clinics in Delhi-NCR and Bangalore manage pre-implant evaluation and post-discharge device monitoring for expanding urban patient populations.
United Kingdom
NHS England specialized commissioning frameworks concentrate high-complexity CRT implants in designated cardiovascular centers across London and the Midlands. MHRA post-market surveillance requirements align with EU MDR technical documentation standards for active implantable devices. The Oxford-Cambridge-London golden triangle anchors electrophysiology research programs evaluating adaptive CRT algorithms.
Global Cardiac Resynchronization Therapy Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the cardiac rhythm management value chain, with integrated device manufacturers maintaining captive manufacturing scale while specialized technology licensors monetize algorithmic IP. The vendor base concentrates among tiered competitors with full regulatory quality management systems, mid-tier notified body relationships, and emerging regional challengers. Three archetypes dominate: vertically integrated multinational conglomerates with established electrophysiology lab channel presence; mid-cap specialists with bi-ventricular pacing or leadless delivery technology focus; and regional manufacturers leveraging local regulatory compliance for cost-advantaged standard device production. Competitive moves center on M&A for algorithmic capability acquisition and strategic partnerships for wireless energy transfer platform development.
Within the integrated multinational tier, Medtronic, Abbott, and Boston Scientific Corporation exemplify archetypes anchored in distinct competitive vectors. Medtronic represents manufacturing scale dominance across high-complexity CRT-D segments. Abbott occupies a position defined by bi-ventricular pacing specialization and hemodynamic sensor integration. Boston Scientific Corporation anchors electrophysiology lab channel presence with procedure time reduction technologies. These three entities collectively illustrate the structural concentration where regulatory compliance burden and capital equipment requirements favor established quality management system holders.
| Leading Market Players |
|---|
| Medtronic |
| Abbott |
| Boston Scientific Corporation |
| BIOTRONIK |
| MicroPort Scientific Corporation |
| LivaNova PLC |
| MEDICO S.R.L. |
| EBR Systems |
| Merit Medical Systems |
| Others |
Supply & Pricing Matrix
Captive manufacturing of high-voltage capacitors and generator housings anchors Medtronic's cost position across CRT-D tiers, while outsourced lead production and third-party battery cell sourcing expose mid-tier competitors to input volatility and asymmetric pricing power. This integration choice separates premium MRI-compatible system margins from commodity CRT-P economics.
Pricing Analysis
Bundled device-plus-procedure contracting dominates United States metropolitan hospital clusters, though unbundled generator procurement through group purchasing organizations is displacing physician preference item autonomy in Texas and California health systems. Three-tier pricing structure across premium MRI-compatible CRT-D, standard CRT-D, and economy CRT-P levels reflects FDA PMA pathway investment recovery and EU MDR compliance cost allocation. Pricing pressure stems from CMS reimbursement code compression and hospital procurement committee consolidation. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers with fellowship-trained electrophysiology faculty show lowest.
Supply Chain Analysis
Direct-to-hospital channels serve high-volume implant centers in Germany and the United States, while distributor-mediated routes penetrate Japanese rural prefectures and Indian cardiology clinics. Generator assembly concentrates in Ireland, Costa Rica, and Malaysia manufacturing zones; lithium battery cells source primarily from South Korea and Japan suppliers. Raw material dependencies span tantalum capacitors, platinum-iridium electrodes, and hermetic titanium enclosures. Single-source vulnerability for cathode active materials creates supply chain risk. Distribution runs through specialized cardiac rhythm management distributors with field clinical engineering support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR recertification timelines and FDA PMA pathway compression accelerate device refresh cycles and consolidate procurement toward integrated manufacturers with established quality management systems.
For Market Incumbents: Anchor defibrillation-capable generator market share through backward integration into high-voltage capacitor production and captive supply of hermetic feedthrough components. Expand notified body relationship consolidation to compress EU MDR technical documentation timelines for legacy system replacements. Threat: wireless CRT platforms with PMDA breakthrough designation eroding transvenous infrastructure dependency. Lever: hemodynamic sensor ecosystem lock-in through proprietary algorithm IP.
For New Entrants and Emerging Players: Leadless delivery miniaturization offers technology-first wedge into infection-risk-sensitive hospital accounts where redo procedure costs dominate procurement criteria. Target Japanese rural prefectures with PMDA accelerated review pathway navigation and remote monitoring connectivity as differentiated go-to-market angle. White-space targets: India's CDSCO-import-substitution-compliant CRT-P production and wireless CRT pilot programs in United States structural heart disease centers.
For Investors and Strategic Acquirers: Roll-up economics work for adaptive CRT algorithm specialists because FDA classification uncertainty and extended PMA timelines strand mid-tier developers without capital to reach commercial launch. Long-term viability centers on platform-ecosystem positioning with real-time hemodynamic feedback integration. Acquisition target archetype: wireless energy transfer platform developers with PMDA breakthrough designation and early United States feasibility study enrollment. Signal to watch: CMS national coverage determination shifts for leadless CRT reimbursement parity.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Acceleration | Compresses legacy device replacement windows across German and French hospital networks before market access expiration. |
| Leadless Device Breakthrough Designation | PMDA accelerated review pathways in Japan reduce time-to-revenue for infection-risk-reduction platforms. |
| Hospital System Partnership Consolidation | Texas and California integrated delivery networks centralize procurement through group purchasing organization contracts. |
| Software Companion Development | Remote monitoring algorithms reduce in-person follow-up burden for Japanese metropolitan hospital networks. |
| Reimbursement Strategy Alignment | CMS national coverage determination navigation secures payment parity across United States implant settings. |
Research Methodology
Direct dialogue with electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded qualitative insights in implant center operational realities. Secondary validation drew from FDA 510(k) and PMA filings, CMS Medicare claims data, EU MDR notified body documentation, and hospital procurement database extracts. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation converged on segment-level estimates.
Segmentation outputs across device type, therapy application, end user, and technology dimensions were generated through the projection horizon. CAGRs were derived from installed base replacement cycles, guideline expansion trajectories, and reimbursement code evolution. Industry-specific forecast inputs incorporated electrophysiology lab density mapping and EU MDR recertification deadline clustering.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to adaptive CRT algorithm regulatory reclassification and wireless energy transfer clinical trial readouts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Absorbable Heart Stent Market
Cardiovascular Devices
Intravascular Ultrasound Market
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Microsclerotherapy Treatment Market
Cardiovascular Devices
Global Non-Vascular Stents Market
Cardiovascular Devices
Lung Stent Market
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
Surgical and Interventional Cardiology Devices Market
Cardiovascular Devices
Australia Cardiovascular Devices Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Cardiac Valve Market
Cardiovascular Devices
Intravascular Ultrasound (IVUS) System Market
Cardiovascular Devices
Latin America Compression Therapy Market
Cardiovascular Devices
Integrated Cardiology Devices Market