
 Airway Catheters Market | 2026-2036
Airway Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Airway Catheters Market Outlook
CE marking under the EU Medical Device Regulation is hardening compliance costs for airway catheter manufacturers seeking European market access. Medtronic leverages its integrated critical care portfolio to sustain channel dominance across hospital systems. Teleflex anchors its position through specialized airway management portfolios that compete on clinical workflow integration.
Airway catheters are sterile, flexible tubes manufactured from medical-grade silicone or polyvinyl chloride, typically ranging from 2.0 mm to 12.0 mm in internal diameter, designed to establish or maintain patent airways during mechanical ventilation, anesthesia delivery, or emergency resuscitation. Endotracheal tubes occupy the largest volume position due to their ubiquity in operating theaters and intensive care units, while laryngeal masks represent the fastest-expanding category as ambulatory surgical centers adopt supraglottic airway devices for shorter procedures. Hospitals command the dominant end-user channel, though home care settings are gaining traction as respiratory support shifts toward decentralized delivery models.
The FDA enforces biocompatibility and sterility standards under 21 CFR Part 820 quality system regulations, while ISO 10993 governs biological evaluation of catheter materials internationally. Health Canada and TGA Australia maintain parallel conformity frameworks that manufacturers must navigate for multi-jurisdiction product registration. Stakeholders should monitor evolving material science innovations and regulatory harmonization efforts as determinants of competitive positioning in airway catheter supply chains.
Market Dynamics
Biocompatibility testing mandates from the FDA are forcing manufacturers to reformulate catheter materials, creating a structural bottleneck where silicone suppliers with validated ISO 10993 documentation command premium positioning in procurement negotiations.
Growth Catalysts
- MDR Compliance Deadlines:The EU Medical Device Regulation's 2024-2026 transition window compels hospital systems to refresh inventory with CE-marked devices, accelerating replacement cycles across German and French procurement networks.
- Ambulatory Surgical Centers:Medicare reimbursement shifts toward same-day procedures drive laryngeal mask adoption in United States outpatient facilities, displacing endotracheal intubation for anesthesia durations under two hours.
- Silicone Material Advances:Medical-grade silicone with enhanced kink resistance enables thinner-walled catheter designs that maintain patency at reduced diameters, expanding pediatric and neonatal application viability.
Market Restraints
- Polymer Feedstock Volatility:Medical-grade PVC resin prices fluctuate with ethylene and chlorine supply disruptions from Gulf Coast petrochemical complexes, compressing margin predictability for high-volume catheter producers.
- Single-Source Validation Burden:FDA 510(k) clearance pathways require extensive biocompatibility documentation that locks manufacturers into qualified silicone compounders, creating supplier concentration risk.
- Supraglottic Device Substitution:Second-generation laryngeal masks with gastric access channels encroach on endotracheal tube indications in elective surgery, threatening volume positions in operating theater contracts.
Strategic Opportunities
- Home Respiratory Care:Post-acute tracheostomy patient management creates demand for disposable suction catheters and speaking valves in United States home health agencies, a channel historically dominated by durable equipment suppliers.
- India Critical Care Expansion:Private hospital chains in Mumbai and Delhi invest in ICU bed expansion under Ayushman Bharat insurance coverage, opening catheter procurement relationships with distributors lacking legacy entrenchment.
- Closed-Suction System Integration:Ventilator-associated pneumonia prevention protocols favor integrated catheter-suction systems that reduce circuit breaks, creating technology bundling opportunities with mechanical ventilation OEMs.
Industry Challenges
- Biocompatibility Testing Backlogs:ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization studies face 16-24 week queue times at contracted laboratories, delaying product launch timelines for material formulation changes.
- Cleanroom Capacity Constraints:Sterile catheter extrusion and packaging operations require ISO Class 7 environments with validated environmental monitoring; qualified facility expansion demands capital deployment exceeding $4 million per production line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airway Catheters Market |
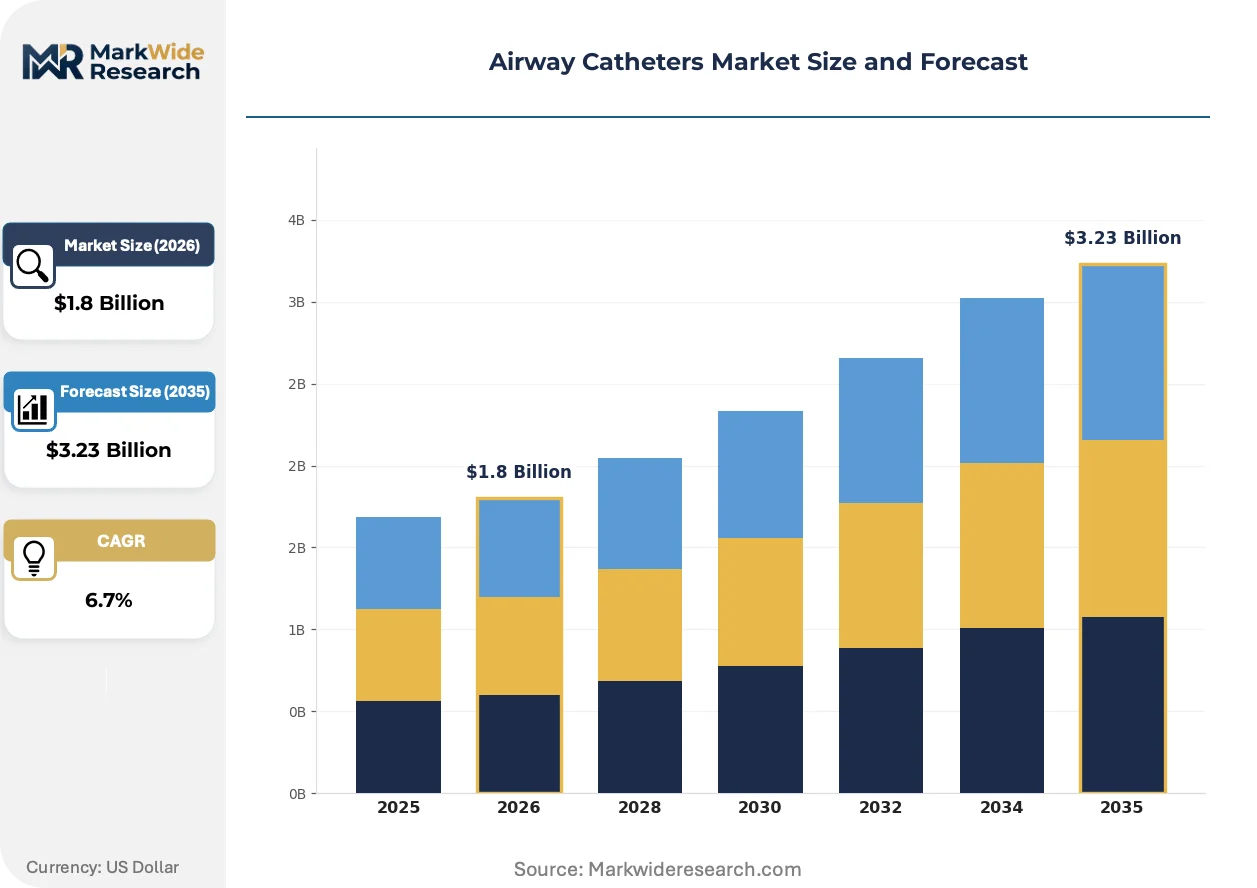
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endotracheal Tubes, Tracheostomy Tubes, Laryngeal Masks, Orotracheal Tubes Application: Emergency Medicine, Anesthesia, Critical Care, Respiratory Support End User: Hospitals, Ambulatory Surgical Centers, Home Care Settings, Clinics Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Medtronic, Teleflex, Smiths Medical, Cook Medical, ICU Medical, Pennine Healthcare, Vyaire Medical, VBM Medizintechnik, SSCOR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airway Catheters Market Strategic Shifts
Material science convergence with infection control protocols is restructuring competitive advantage around surface modification technologies rather than commoditized extrusion capabilities.
Antimicrobial-impregnated silicone is overtaking standard medical-grade formulations in United States ICU purchasing specifications. Hospital infection control committees mandate catheters with silver-ion or chlorhexidine coatings for patients exceeding 48 hours of intubation. This specification compression disadvantages manufacturers lacking validated coating partnerships with specialty chemical suppliers.
REACH substance restrictions on phthalate plasticizers in the European Union accelerate bio-based PVC alternative development. Compounders in Germany and the Netherlands invest in citrate and trimellitate ester formulations that maintain flexibility at body temperature while satisfying ECHA authorization requirements. Pediatric and neonatal segments face earliest compliance pressure due to heightened toxicity sensitivity.
Consolidated purchasing through United States group purchasing organizations compresses supplier rosters to three approved vendors per catheter category. Hospital systems in Texas and California negotiate multi-year contracts with performance guarantees on supply continuity and sterility assurance. Independent distributors lose shelf space as direct manufacturer agreements capture standardized product flows.
Airway Catheters Market Segmentation
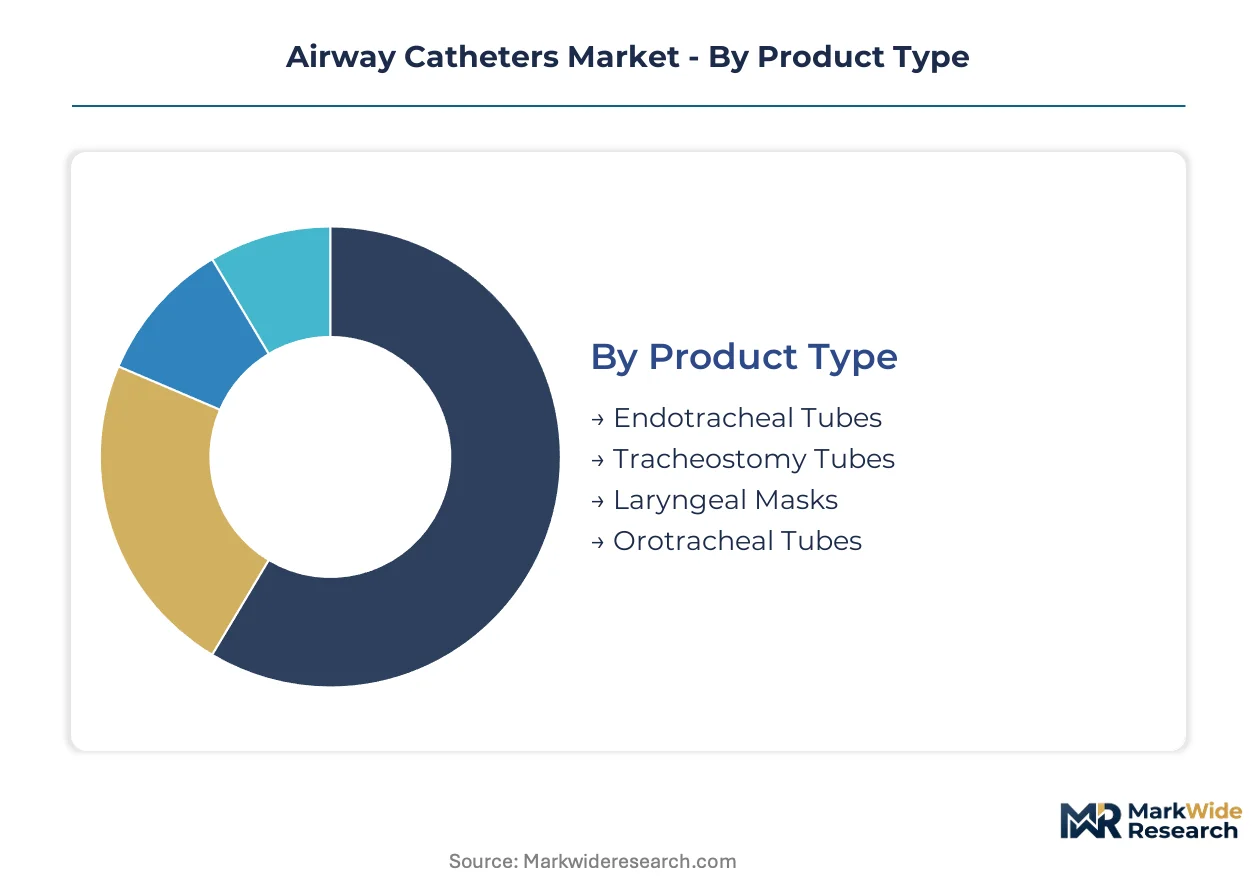
Airway catheter purchasing decisions pivot on procedural duration, patient acuity, and regulatory compliance requirements across clinical settings. Manufacturers align product portfolios to these decision drivers, creating distinct competitive battlegrounds within each segmentation dimension.
Product Type:
Hospital procurement committees weight unit economics against complication rates when selecting among airway catheter formats.
- Endotracheal Tubes:Polyvinyl chloride or silicone tubes inserted through the mouth or nose into the trachea, sized 2.0-12.0 mm internal diameter. United States tertiary hospitals consume the highest volumes for mechanical ventilation in ICU protocols, driven by ventilator-associated pneumonia prevention bundles that mandate regular tube exchanges.
- Laryngeal Masks:Supraglottic airway devices with inflatable cuffs that seal the perilaryngeal space without tracheal intubation. Ambulatory surgical centers in Texas and California deploy these for anesthesia under two hours, displacing endotracheal tubes as Medicare reimbursement shifts toward same-day procedures.
- Tracheostomy Tubes:Curved cannulas inserted through a surgical opening in the neck for long-term ventilation.
- Orotracheal Tubes:Endotracheal tubes specifically designed for oral insertion in emergency airway management.
Volume sits with endotracheal tubes; growth tilts toward laryngeal masks.
Application:
Clinical workflow integration determines technology adoption speed across acute care settings.
- Anesthesia:Airway management during surgical procedures requiring controlled ventilation. United States operating theaters specify laryngeal masks for elective cases under two hours, while cardiac and neurosurgical teams demand cuffed endotracheal tubes for precise airway control.
- Critical Care:Prolonged mechanical ventilation in intensive care units with ventilator weaning protocols. German and French hospital systems refresh inventory with MDR-compliant devices, accelerating replacement cycles for silicone-based tubes with antimicrobial coatings.
- Emergency Medicine:Rapid airway establishment in trauma and resuscitation scenarios.
- Respiratory Support:Chronic ventilation and weaning in subacute and home settings.
Critical care commands the highest unit consumption; anesthesia is climbing the fastest as ambulatory volumes expand.
End User:
Capital intensity and reimbursement models shape channel economics for catheter suppliers.
- Hospitals:Integrated delivery networks with centralized purchasing through group purchasing organizations. Texas and California systems negotiate multi-year contracts with supply continuity guarantees, compressing vendor rosters to three approved suppliers per catheter category.
- Ambulatory Surgical Centers:Outpatient facilities optimized for same-day procedures. Medicare reimbursement shifts drive laryngeal mask adoption, with centers in Florida and Arizona prioritizing disposables that eliminate reprocessing costs.
- Home Care Settings:Post-acute respiratory support for tracheostomy patients.
- Clinics:Office-based procedures requiring basic airway management.
Hospitals dominate current procurement; home care settings are gaining share fastest as respiratory support decentralizes.
Distribution Channel:
Supply chain configuration determines margin capture and customer access for manufacturers.
- Direct Sales:Manufacturer contracts with hospital systems and integrated delivery networks. Medtronic and Teleflex deploy dedicated critical care representatives to secure multi-year agreements with standardized product flows.
- Distributors:Regional medical supply intermediaries with local inventory and clinical support. Independent distributors in India serve private hospital chains in Mumbai and Delhi expanding ICU capacity under Ayushman Bharat coverage.
- Wholesalers:High-volume, low-touch distribution for commoditized catheter formats.
- Online Retail:E-commerce platforms serving smaller clinics and home care providers.
Direct sales capture the highest value; distributor relationships are expanding most quickly in emerging markets lacking legacy entrenchment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Costa Rica and Malaysia concentrate catheter manufacturing for North American and Asian hospital systems respectively, creating tax-advantaged production nodes that reshape procurement geography.
United States
Aging demographics and surgical volume expansion sustain catheter consumption across Texas and California hospital systems. FDA biocompatibility testing under 21 CFR Part 820 quality system regulations forces material reformulation timelines that favor established silicone compounders. Boston and Minneapolis medical device clusters anchor critical care portfolio development for integrated delivery networks.
Germany
Tertiary hospital ICU expansion drives demand for MDR-compliant airway management devices in Bavaria and North Rhine-Westphalia. ECHA REACH substance restrictions on phthalate plasticizers accelerate bio-based PVC alternative development among compounders. Frankfurt and Stuttgart procurement networks refresh inventory with CE-marked devices ahead of regulatory deadlines.
India
Private hospital chains in Mumbai and Delhi invest in ICU bed expansion under Ayushman Bharat insurance coverage, opening catheter procurement relationships. CDSCO medical device rules align with international standards for multi-jurisdiction registration pathways. Hyderabad and Bangalore medical technology parks attract contract manufacturing for export-oriented production.
China
Domestic critical care infrastructure expansion drives consumption of mechanical ventilation accessories in Shanghai and Beijing hospital systems. NMPA medical device registration requirements emphasize biocompatibility documentation parallel to ISO 10993 frameworks. Suzhou and Shenzhen manufacturing zones concentrate sterile extrusion capacity for regional supply.
Japan
Aging population respiratory support needs sustain demand for long-term ventilation accessories in Tokyo and Osaka metropolitan hospitals. PMDA quality management system requirements mirror international standards while maintaining distinct documentation protocols. Nagoya medical device clusters specialize in precision extrusion for neonatal and pediatric catheter formats.
Airway Catheters Market Competitive Environment
United States producers anchor one tier of integrated critical care portfolios; German and Japanese specialists hold positions in precision extrusion and material science innovation. The vendor base stratifies across three tiers: diversified medical technology conglomerates with hospital system contracts, mid-scale catheter specialists with validated coating partnerships, and regional fabricators serving emerging market distributors. Dominant competitive moves include antimicrobial surface technology licensing agreements and sterile manufacturing capacity expansion in Costa Rican and Malaysian special economic zones.
Within the diversified conglomerate tier, Medtronic and Teleflex occupy positions defined by channel dominance across hospital systems and specialized airway management portfolios respectively. Vyaire Medical exemplifies the respiratory-focused specialist archetype with concentrated positioning in mechanical ventilation accessories. These three entities represent distinct strategic postures: integrated portfolio breadth, workflow-centric specialization, and respiratory device category depth.
| Leading Market Players |
|---|
| Medtronic |
| Teleflex |
| Smiths Medical |
| Cook Medical |
| ICU Medical |
| Pennine Healthcare |
| Vyaire Medical |
| VBM Medizintechnik |
| SSCOR |
| Others |
Value Chain & Pricing Dynamics
Medical-grade silicone resin price indices cascade through airway catheter supply chains, compressing margin structures for manufacturers locked into long-term hospital contracts while rewarding compounders with validated ISO 10993 documentation. This commodity-driven cost architecture stratifies procurement tiers across United States group purchasing organizations and European hospital systems.
Pricing Analysis
Short lead-time premiums command substantial markups in United States ICU procurement, where ventilator-associated pneumonia prevention protocols mandate rapid catheter exchanges that standard inventory cycles cannot satisfy. Three-tier pricing structure across premium antimicrobial-coated, standard silicone, and economy PVC levels reflects FDA biocompatibility certification tiers and volume scale commitments. Price erosion runs through economy PVC segments as Gulf Coast petrochemical volatility compresses compounder margins. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement constraints, while tertiary hospital systems absorb premium tier costs through bundled critical care contracts.
Supply Chain Analysis
Single-source vulnerability sits with German and Dutch specialty compounders supplying REACH-compliant phthalate-free PVC alternatives for European pediatric segments. Manufacturing gravity centers on Costa Rican and Malaysian medical device special economic zones, with sterile extrusion capacity concentrated in ISO Class 7 facilities requiring capital deployment exceeding four million dollars per production line. Raw material dependencies rest on medical-grade silicone from South Korean suppliers, ethylene feedstock from Gulf Coast petrochemical complexes, and antimicrobial coating chemicals from Swiss specialty chemical producers. Tariff exposure threatens cost structures for United States distributors sourcing finished catheters from Chinese contract manufacturers. Distribution runs through direct manufacturer agreements with integrated delivery networks, displacing independent distributors in Texas and California procurement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antimicrobial-impregnated silicone coatings are displacing standard medical-grade formulations as United States infection control committees mandate silver-ion and chlorhexidine specifications for prolonged intubation. This technology transition compresses competitive advantage around validated coating partnerships rather than commoditized extrusion capabilities.
For Market Incumbents: Acquire sterile cleanroom manufacturing assets in Costa Rican and Malaysian special economic zones to secure tax-advantaged production capacity and supply continuity guarantees demanded by United States group purchasing organizations. Backward integration into medical-grade silicone compounding reduces exposure to ISO 10993-5 cytotoxicity testing backlogs that delay product launches. Defensive positioning requires antimicrobial coating technology licensing agreements with Swiss and German specialty chemical suppliers before second-generation laryngeal masks with gastric access channels erode endotracheal tube volume positions. For New Entrants and Emerging Players: Home health agencies managing post-acute tracheostomy patients represent an underserved buyer archetype historically dominated by durable equipment suppliers lacking catheter specialization. Private hospital chains in Mumbai and Delhi expanding ICU capacity under Ayushman Bharat coverage offer procurement relationships free from legacy distributor entrenchment. Direct-to-clinic distribution models bypassing group purchasing organization vendor compression enable margin capture in Florida and Arizona ambulatory surgical centers prioritizing disposables that eliminate reprocessing costs. For Investors and Strategic Acquirers: The window for entry favors mid-scale catheter specialists with validated antimicrobial coating partnerships and established CE marking pathways under EU Medical Device Regulation. Long-term viability hinges on five-to-ten year positioning around surface modification technologies rather than extrusion scale. Watch FDA biocompatibility testing queue times at contracted laboratories as the inflection indicator for product launch velocity and competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Partnership | Validates silver-ion and chlorhexidine specifications for United States ICU procurement committees. |
| CE Marking Pathway Investment | Secures European market access ahead of MDR compliance deadlines in German and French hospital systems. |
| Hospital System Partnership | Captures multi-year contracts with supply continuity guarantees through Texas and California integrated delivery networks. |
| Sterile Manufacturing Scale-Up | Expands ISO Class 7 cleanroom capacity in Costa Rican special economic zones for North American supply. |
| Reimbursement Strategy Development | Aligns laryngeal mask positioning with Medicare same-day procedure reimbursement shifts in ambulatory settings. |
Study Parameters
Document review covered FDA 510(k) clearance databases, EU MDR technical documentation requirements, and hospital procurement contracts from United States group purchasing organizations, complemented by interviews with critical care physicians, biomedical engineers, GPO contracts managers, and sterile manufacturing facility operators. Secondary validation drew from ISO 10993 biocompatibility standards, CDSCO medical device registration filings, and customs trade data on medical-grade silicone imports. Bottom-up demand modeling from catheter consumption rates in tertiary hospital ICUs triangulated against top-down market sizing from manufacturer revenue disclosures.
Historical volume trajectories cross-referenced against expert panel input from supply chain directors at German compounders and Costa Rican contract manufacturers anchored projection frameworks. Segmentation dimensions modeled encompassed product type, application setting, end-user channel, and regional regulatory cluster. CAGRs derived from weighted average of procedure volume growth, material cost escalation indices, and reimbursement policy shifts across the analysis window. Industry-specific forecast inputs incorporated ventilator-associated pneumonia prevention protocol adoption rates and ambulatory surgical center expansion trajectories.
Revisions become necessary when FDA biocompatibility testing mandates tighten material specifications, EU REACH substance restrictions accelerate phthalate displacement timelines, or Medicare reimbursement policies shift procedure site economics. Forecasts reflect assumptions on regulatory harmonization progress and supply chain concentration stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Dental Anesthesia Market
Anesthesiology
Delirium Market
Anesthesiology
Global Anesthesia Endotracheal Tubes Market
Anesthesiology
Artificial Coma/Medically Induced Coma Market
Anesthesiology
Global Inhalation Anesthesia Market
Anesthesiology
Sedation in ICU Setting Market
Anesthesiology
Smart Anesthesia System Market
Anesthesiology
Anesthesia Breathing Circuits Market
Anesthesiology
Epinephrine Market
Anesthesiology
Endotracheal Tube Cuffs Market
Anesthesiology
Anaesthesia Machines Market
Anesthesiology
Artificial Airway Holders Market
Anesthesiology
Inhalation Anesthetics Market
Anesthesiology
US Anesthesiology Service Market
Anesthesiology
Anesthetics Market
Anesthesiology
Vasopressin for Vasoplegic Shock Market