
 Global Artificial Heart Market | 2026-2036
Global Artificial Heart Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Heart Market Foresight
Specialized cardiovascular device distribution is reshaping how artificial heart manufacturers reach end-users, with direct-to-hospital contracting replacing traditional wholesale medical supply channels. Abbott Laboratories leverages its structural heart portfolio to sustain integrated cath-lab and surgical suite presence across major health systems. Medtronic anchors its position through deep relationships with transplant centers and ventricular assist device programs in North America and Western Europe. CARMAT differentiates through its total artificial heart platform designed for destination therapy rather than bridge-to-transplant indications.
An artificial heart constitutes a mechanical circulatory support device engineered to replace or assist failing native cardiac function, typically incorporating biocompatible polymers, titanium housings, and magnetically levitated or continuous flow impeller systems capable of delivering systemic perfusion. Its primary commercial purpose centers on sustaining patients with end-stage heart failure, cardiogenic shock, or transplant incompatibility where pharmacologic intervention proves insufficient. Left ventricular assist devices occupy the dominant revenue position given established reimbursement and broader implant candidacy, while total artificial hearts represent the fastest-expanding category as destination therapy protocols mature and biocompatibility improves. Magnetically levitated pump technology commands premium positioning due to reduced hemolysis and extended device durability compared with earlier pulsatile designs.
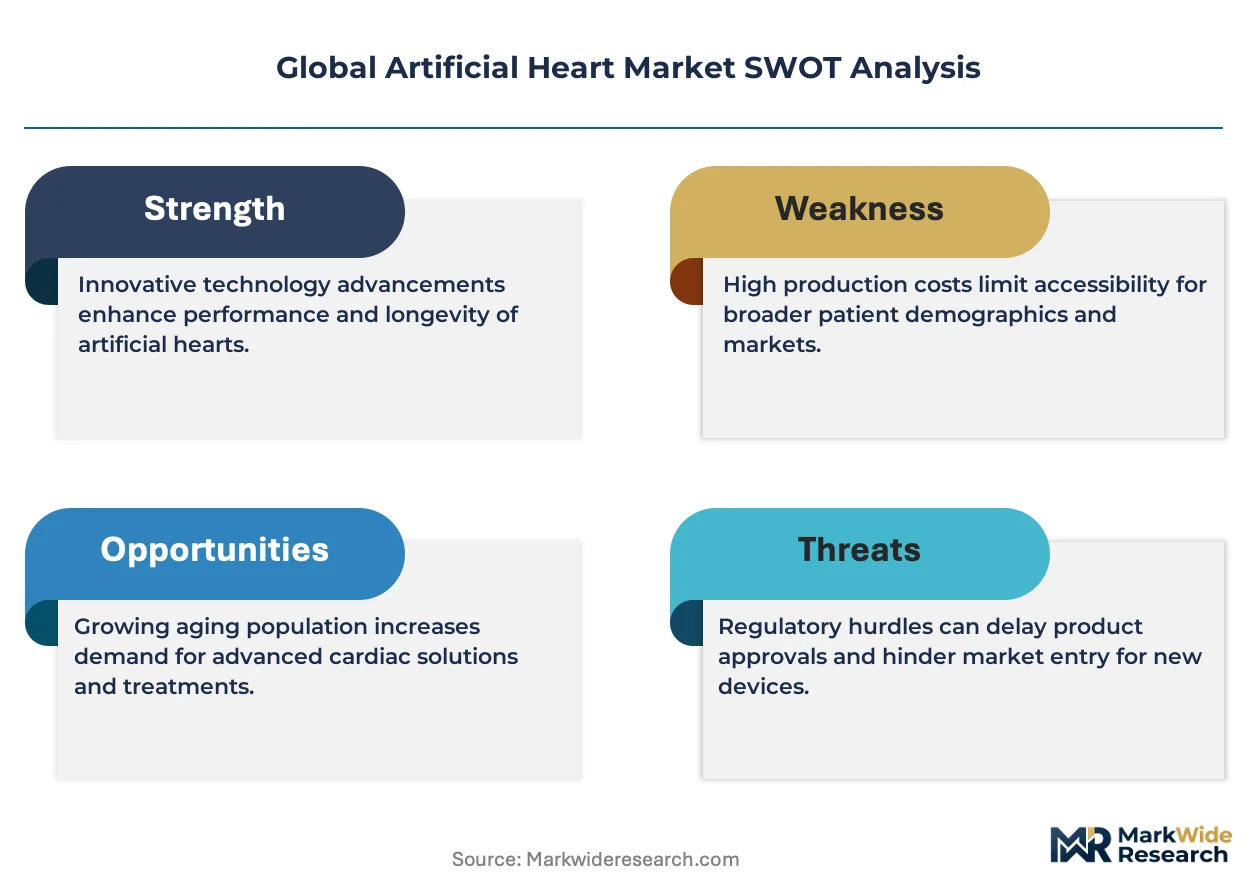
FDA premarket approval and humanitarian device exemption pathways govern United States market entry, while EMA MDR conformity assessment and CE marking dictate European commercialization timelines for these life-sustaining devices. ISO standards for cardiovascular implants and biocompatibility testing establish baseline safety benchmarks that manufacturers must satisfy across all target jurisdictions. Stakeholders must monitor evolving CMS reimbursement determinations and national health technology assessment outcomes, as these decisions directly dictate patient access and manufacturer revenue realization irrespective of clinical efficacy demonstrations.
Market Dynamics
Magnetically levitated impeller systems are compressing replacement timelines for earlier pulsatile pump architectures, forcing manufacturers to recalibrate R&D roadmaps and manufacturing footprints around continuous-flow durability benchmarks.
Growth Catalysts
- Destination therapy protocols:Expanded CMS reimbursement for permanent implantation rather than bridge-to-transplant indications is broadening patient candidacy across United States transplant centers.
- EU MDR harmonization:Streamlined conformity assessment pathways for Class III cardiovascular implants are reducing time-to-market for biocompatible polymer innovations.
- Titanium supply localization:Japanese and German precision machining clusters are securing aerospace-grade material flows for pump housing production.
Market Restraints
- Neodymium magnet volatility:Rare earth price swings from Chinese export quotas are squeezing margins for levitated pump manufacturers dependent on magnetic bearing systems.
- Transplant center concentration:Device implantation capacity clusters in under 200 specialized United States surgical programs, creating demand bottlenecks and geographic access inequities.
- Thrombogenicity limitations:Current polymer surfaces require lifelong anticoagulant regimens, restricting candidacy for patients with bleeding diatheses or contraindications to warfarin therapy.
Strategic Opportunities
- Brazilian regulatory acceleration:ANVISA priority review pathways for breakthrough cardiovascular devices are opening Latin America's largest healthcare market to early entrants.
- Peripheral vascular convergence:Integration of artificial heart controllers with implantable hemodynamic sensors is enabling closed-loop autoregulation systems.
- Direct-to-hospital contracting:Bypassing wholesale distributors through integrated cath-lab service agreements is capturing margin and capturing real-world performance data.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 cytotoxicity and hemocompatibility testing protocols extend preclinical validation by 18-24 months for novel polymer formulations.
- Perfusionist workforce scarcity:Specialized extracorporeal membrane oxygenation and ventricular assist device training programs are failing to match surgical program expansion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Heart Market |
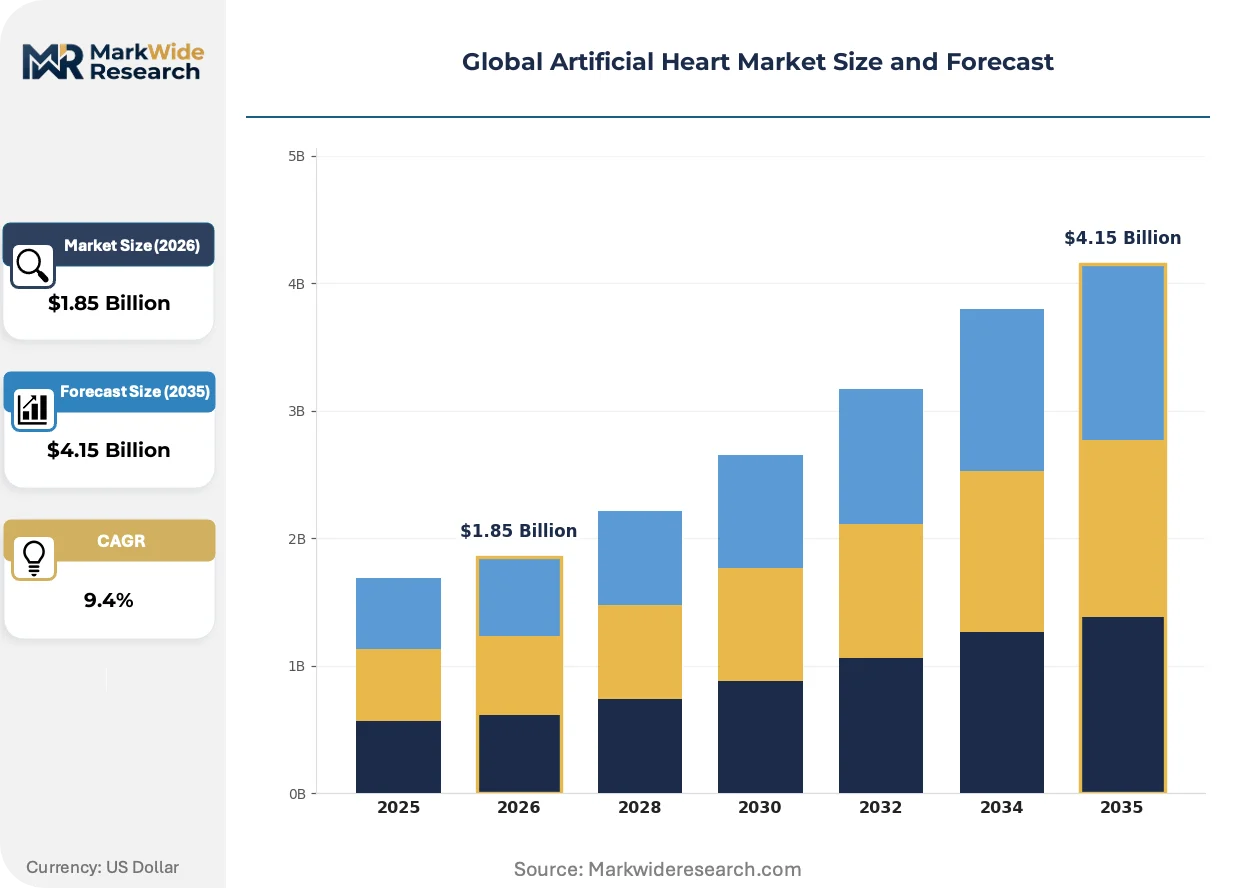
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Total Artificial Heart, Left Ventricular Assist Device, Right Ventricular Assist Device, Biventricular Device End User: Hospitals, Cardiovascular Clinics, Research Institutions, Home Care Settings Application: Heart Failure, Cardiogenic Shock, Myocardial Infarction, Transplant Compatibility Technology: Magnetically Levitated Pumps, Pulsatile Pumps, Continuous Flow Devices, Biocompatible Materials |
| Companies Covered | Abbott Laboratories, Medtronic, SynCardia Systems, CARMAT, BiVACOR, Jarvik Heart, Berlin Heart GmbH, Abiomed, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Heart Market Shifts & Advancements
Computational modeling and sensor integration are compressing the gap between bench testing and clinical performance prediction, reshaping how manufacturers validate device durability before human trials.
Magnetically levitated centrifugal pump technology is digitizing hemodynamic monitoring by embedding flow sensors and wireless telemetry directly into impeller housings. Transplant centers in Germany and Japan are adopting these systems for outpatient destination therapy management. Real-time data streams are digitizing post-implant surveillance protocols and enabling predictive intervention before thrombotic or pump malfunction events.
EMA MDR post-market surveillance requirements are mandating systematic collection of long-term device performance data through European implant registries. Manufacturers must now fund 15-year follow-up studies as a condition of CE marking renewal. This regulatory burden is concentrating commercialization resources among firms with established European clinical infrastructure.
Hospital procurement committees are consolidating ventricular assist device purchasing through multi-year sole-source agreements tied to outcome guarantees and training support. United States health systems with integrated cardiac surgery and heart failure programs are leading this consolidation. Bundled payment models are displacing fee-for-service device reimbursement in major academic medical centers.
Global Artificial Heart Market Segmentation
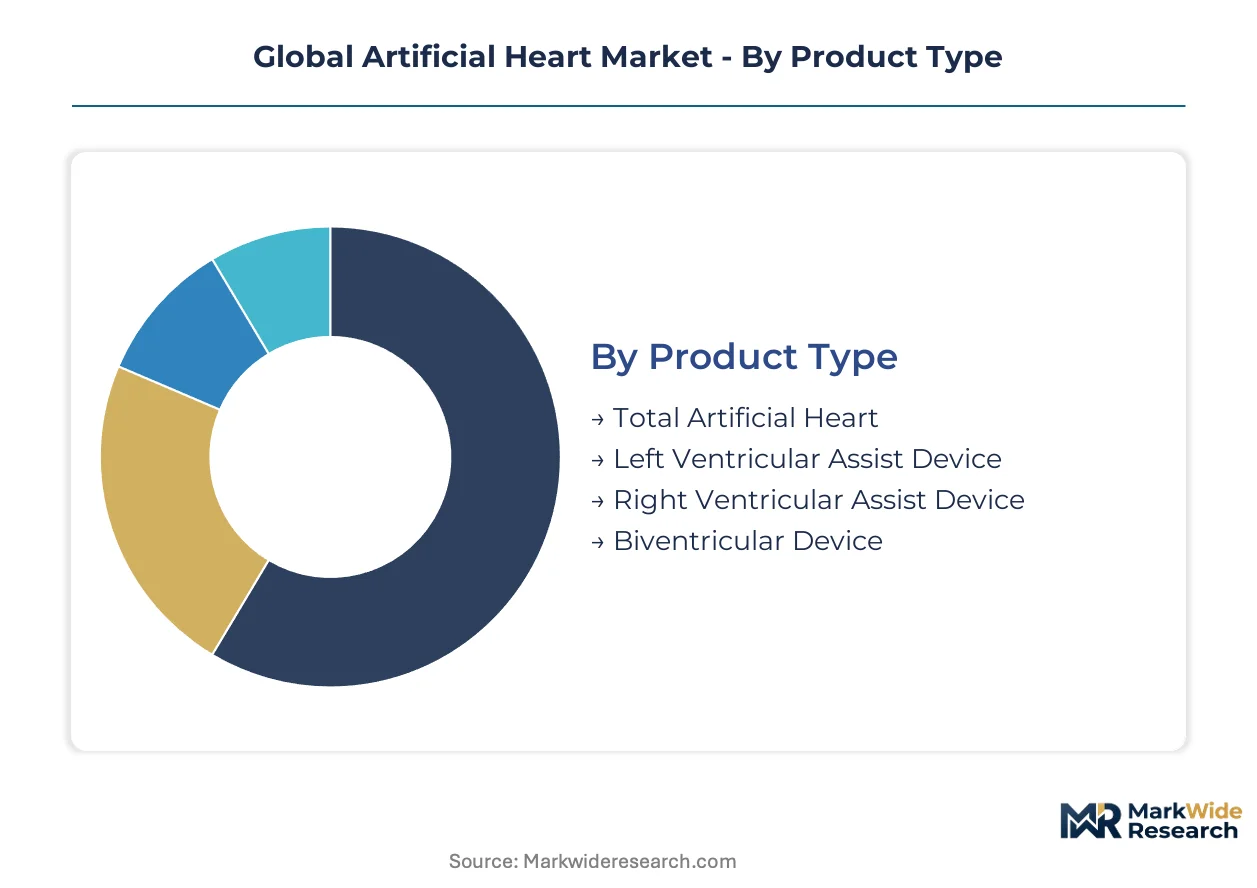
Device categorization in the artificial heart market tracks reimbursement pathways, surgical complexity, and patient candidacy thresholds. Each segmentation dimension reveals distinct commercial access patterns and manufacturing investment priorities across transplant centers and destination therapy programs.
Product Type:
Cost tier differentiation separates bridge-to-transplant devices from permanent implantation systems with divergent pricing and regulatory burden.
- Total Artificial Heart:Biventricular replacement systems incorporating biocompatible polymers and titanium housings deliver systemic perfusion for patients ineligible for transplant. German and Japanese transplant centers are expanding destination therapy protocols for this category as CMS reimbursement broadens permanent implant candidacy.
- Left Ventricular Assist Device:Continuous-flow pumps with magnetically levitated impellers dominate procedural volume due to established reimbursement codes and broader implant eligibility. United States health systems with integrated heart failure programs anchor demand for durable circulatory support.
- Right Ventricular Assist Device:Temporary support configurations address isolated right heart failure with shorter intended duration.
- Biventricular Device:Synchronized dual-pump systems serve bridge-to-recovery scenarios in acute cardiogenic shock.
Left Ventricular Assist Device holds installed capacity. Total Artificial Heart is rotating up the share rankings.
End User:
Customer type determines procurement scale, training infrastructure requirements, and outcome accountability structures.
- Hospitals:Academic medical centers and specialized cardiac surgical programs concentrate implant volume through dedicated ventricular assist device teams. United States transplant centers with ECMO capabilities and perfusionist staffing drive device adoption through bundled payment arrangements.
- Cardiovascular Clinics:Outpatient facilities manage post-implant anticoagulation monitoring and hemodynamic surveillance for destination therapy patients. German heart failure networks are expanding clinic-based pump management with wireless telemetry integration.
- Research Institutions:Preclinical testing and early feasibility trials evaluate novel biocompatible surfaces and control algorithms.
- Home Care Settings:Portable driver systems and remote monitoring enable discharge for stable destination therapy patients.
Hospitals command procurement volume concentration. Cardiovascular Clinics are expanding fastest into longitudinal patient management.
Application:
Clinical indication severity dictates device selection, expected support duration, and regulatory pathway eligibility.
- Heart Failure:Chronic end-stage systolic dysfunction represents the dominant addressable population with established destination therapy protocols. Japanese reimbursement frameworks are expanding permanent implant access for INTERMACS profile 4-7 patients.
- Cardiogenic Shock:Acute hemodynamic collapse requiring temporary mechanical support bridges patients to recovery or decision. United States emergency departments with rapid deployment protocols drive short-term device utilization.
- Myocardial Infarction:Post-infarction ventricular dysfunction with cardiogenic shock complications.
- Transplant Compatibility:Bridge-to-transplant indications for patients awaiting donor organ allocation.
Heart Failure anchors the installed base. Cardiogenic Shock is climbing fastest as emergency deployment protocols mature.
Technology:
Maturity gradients separate legacy pulsatile architectures from next-generation magnetic bearing systems with divergent durability profiles.
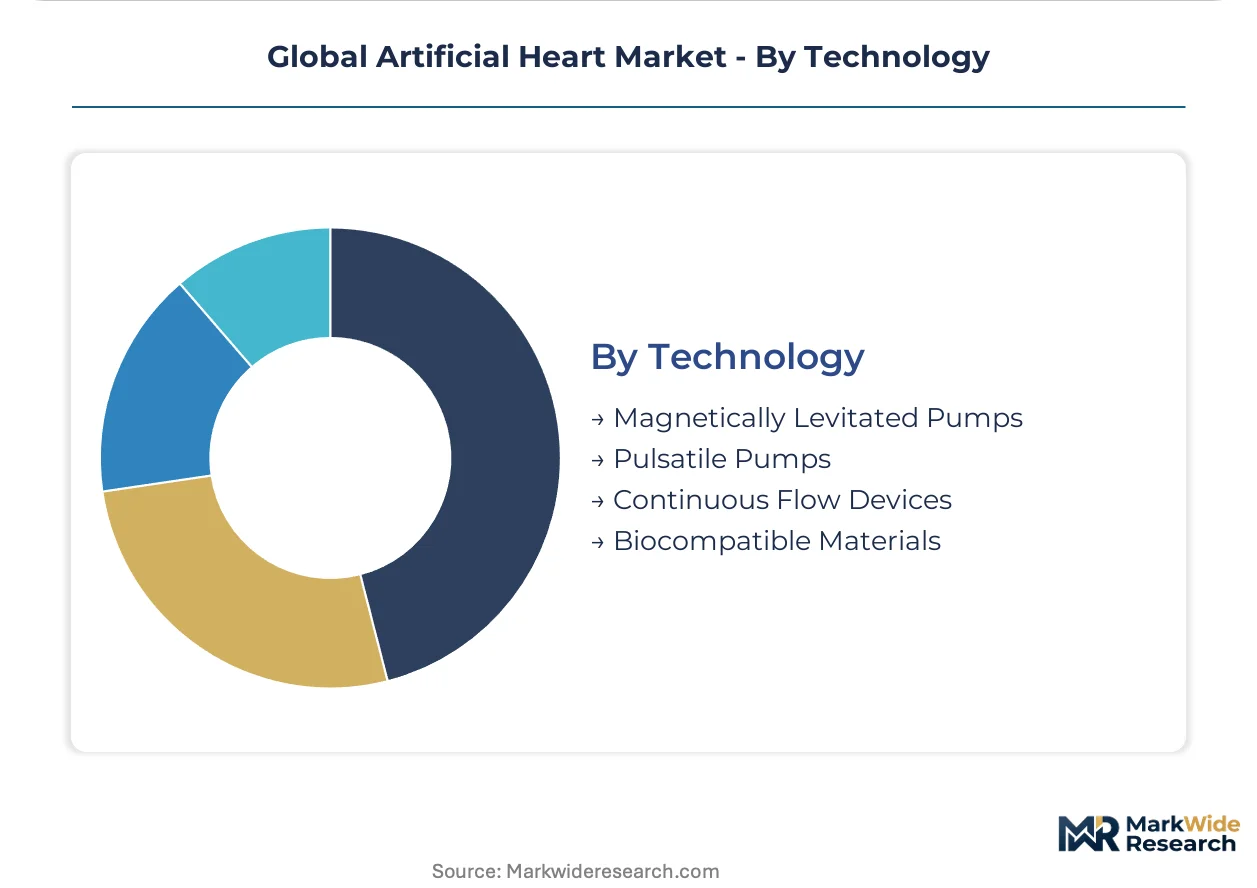
- Magnetically Levitated Pumps:Bearingless impeller designs eliminate mechanical wear surfaces, reducing hemolysis and extending device longevity beyond five years. German precision machining clusters supply aerospace-grade titanium housings for these systems.
- Continuous Flow Devices:Axial and centrifugal pump configurations without magnetic levitation occupy mid-tier positioning.
- Pulsatile Pumps:First-generation pneumatic systems with limited commercial presence remain in specific bridge-to-transplant protocols.
- Biocompatible Materials:Polymer surface engineering and antithrombotic coatings address thrombogenicity limitations across all pump categories.
Magnetically Levitated Pumps command premium positioning. Continuous Flow Devices retain volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cleveland Clinic's cardiac surgical program anchors United States implant volume through its dedicated ventricular assist device infrastructure. Specialized transplant networks in Germany and Japan extend destination therapy access through integrated heart failure management protocols.
United States
CMS reimbursement expansion for permanent implantation drives demand at INTERMACS-registered centers. FDA premarket approval pathways govern commercial entry for magnetically levitated pump systems. The Texas Medical Center in Houston concentrates multi-site ventricular assist device trials and post-market surveillance operations.
Germany
Bundled payment models for heart failure management accelerate adoption at university hospitals with ECMO capabilities. EMA MDR conformity assessment and CE marking renewal requirements mandate 15-year follow-up studies through European implant registries. The Stuttgart precision machining cluster supplies aerospace-grade titanium housings for pump component fabrication.
Japan
PMDA accelerated approval pathways for breakthrough cardiovascular devices expand patient candidacy for destination therapy protocols. METI industrial policy supports domestic production of biocompatible polymer formulations for implantable surfaces. The Osaka-Kobe medical device corridor hosts specialized cardiac surgical training programs and perfusionist education centers.
Brazil
ANVISA priority review pathways for life-sustaining devices reduce regulatory timelines for total artificial heart platforms. Public health system procurement through SUS reimbursement frameworks creates volume concentration at São Paulo and Rio de Janeiro transplant centers. The Campinas medical technology cluster attracts foreign manufacturers establishing Latin American distribution infrastructure.
Switzerland
Swissmedic certification for Class III cardiovascular implants enables streamlined EU market access through mutual recognition agreements. Reimbursement frameworks at cantonal university hospitals support bridge-to-transplant and destination therapy indications. The Zurich biomedical engineering ecosystem integrates precision manufacturing with clinical validation partnerships at University Hospital Zurich.
Global Artificial Heart Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying biocompatible polymers, titanium housings, and magnetic bearing subassemblies. The market structure concentrates among diversified cardiovascular device conglomerates with established cath-lab and surgical suite relationships, while mid-scale specialists occupy niche total artificial heart segments. Three archetypes dominate: diversified med-tech conglomerates with structural heart portfolios, pure-play mechanical circulatory support developers, and precision component fabricators serving pump assembly supply chains. Competitive moves center on direct-to-hospital contracting arrangements and integrated service agreements capturing real-world performance data.
Among diversified cardiovascular device manufacturers, Abbott Laboratories and Medtronic occupy positions anchored by broad structural heart portfolios and deep transplant center relationships. CARMAT exemplifies the pure-play total artificial heart developer archetype, representing destination therapy-focused innovation outside traditional ventricular assist device categories. Berlin Heart GmbH anchors the European specialist tier, sitting within the precision mechanical circulatory support segment with concentration on pediatric and bridge-to-transplant applications.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| SynCardia Systems |
| CARMAT |
| BiVACOR |
| Jarvik Heart |
| Berlin Heart GmbH |
| Abiomed |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
Undercapacity in Japanese precision titanium machining is tightening supplier leverage and amplifying pricing power for magnetically levitated pump housings, while CMS reimbursement compression forces manufacturers to absorb input cost volatility rather than pass through to transplant centers.
Pricing Analysis
Three-tier pricing structure across premium magnetically levitated systems, standard continuous-flow devices, and economy pulsatile configurations separates reimbursement-eligible implants from trial-stage hardware. Price differentiation hinges on FDA PMA certification tier and surgical volume scale, with academic medical centers commanding steeper discounts than community hospitals. Pricing pressure stems from neodymium magnet cost volatility and extended ISO 10993 testing timelines. Cardiovascular clinics exhibit highest price sensitivity due to thin margins on outpatient pump management, while integrated health systems with bundled payment contracts show lowest sensitivity.
Supply Chain Analysis
Extended payment terms from German aerospace-grade titanium suppliers are compressing working capital for pump housing fabricators, forcing assembly manufacturers to secure supply-chain finance facilities. Component sourcing concentrates in Japan, Germany, and the United States for precision-machined housings, biocompatible polymer formulations, and magnetic bearing subassemblies. Raw material dependencies include neodymium rare earth elements, medical-grade titanium, and antithrombotic polymer coatings. Single-source vulnerability in Chinese rare earth processing creates structural exposure. Distribution runs through direct-to-hospital contracting rather than wholesale medical supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from next-generation biologic cardiac repair platforms and xenotransplantation advances that could erode mechanical circulatory support addressable populations.
For Market Incumbents: Entrench destination therapy market share by deepening in-house production of magnetically levitated impeller systems in Stuttgart and Osaka precision clusters, while securing 15-year EMA MDR post-market surveillance data exclusivity through European implant registry partnerships to raise rival certification barriers against CARMAT-type pure-play entrants. For New Entrants and Emerging Players: Establish a beachhead in Brazilian ANVISA priority review pathways for total artificial heart platforms, exploiting SUS reimbursement framework gaps and Campinas distribution infrastructure to build Latin American clinical evidence before attempting FDA PMA submission, while targeting cardiogenic shock emergency deployment protocols where regulatory timelines compress. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across magnetically levitated pump sub-assemblies due to aerospace-grade titanium localization investments and 15-year EMA follow-up study funding obligations. Long-term viability favors diversified cardiovascular conglomerates with existing cath-lab relationships over pure-play mechanical circulatory support developers. Monitor CMS reimbursement determination timing for permanent implant candidacy expansion as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | PMA submission for magnetically levitated systems secures United States commercial exclusivity against CE-marked rivals. |
| CE Marking Renewal Strategy | Fifteen-year EMA MDR follow-up study funding locks European registry data access and blocks competitor entry. |
| Hospital System Partnership | Direct-to-hospital contracting with INTERMACS-registered centers captures real-world performance data and procurement volume. |
| Software Companion Development | Wireless telemetry integration enables closed-loop autoregulation and outpatient destination therapy management. |
| Reimbursement Strategy | CMS permanent implant code expansion broadens patient candidacy beyond bridge-to-transplant indications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cardiac surgeons, perfusionists, hospital purchasing committee members, and ventricular assist device program directors, cross-validated against secondary sources including FDA PMA filings, EMA MDR conformity assessments, CMS Medicare reimbursement determinations, and INTERMACS registry data, with bottom-up implant volume modeling triangulated against top-down market sizing.
Calibration against historical INTERMACS implant volume trajectories and reimbursement code adoption curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include device type, end-user setting, clinical application, and technology platform tier. CAGRs were derived from weighted regression of procedural volume growth and pricing trajectory assumptions, incorporating neodymium price volatility indices and transplant center capacity expansion plans as industry-specific inputs.
Sensitivities concentrate around FDA PMA timeline delays, EMA MDR post-market surveillance cost inflation, and CMS reimbursement determination reversals. Forecasts reflect documented assumptions regarding regulatory pathway progression and surgical program expansion rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Global PTA Balloon Catheter Market
Cardiovascular Devices
Atherectomy Systems Market
Cardiovascular Devices
Shock Wave Therapy Devices Market
Cardiovascular Devices
Surgical and Interventional Cardiology Devices Market
Cardiovascular Devices
Arterial Cannula Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
India Cardiovascular Devices Market
Cardiovascular Devices
Hypertension Management Devices Market
Cardiovascular Devices
Pressure Infusion Cuffs Market
Cardiovascular Devices
Intravascular Ultrasound Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market
Cardiovascular Devices
Intravascular Ultrasound (IVUS) System Market
Cardiovascular Devices
Australia Cardiovascular Devices Market
Cardiovascular Devices
Stent-Assisted Coiling Market