
 Ventricular Drainage Sets Market | 2026-2036
Ventricular Drainage Sets Market Size, Share, and Industry Trends Forecast 2026-2036
Ventricular Drainage Sets Market Outlook
Asset-light leasing models for neurosurgical consumables are tilting competitive dynamics toward firms with flexible balance sheets. Medtronic plc leverages its hospital contracting infrastructure to sustain multi-year supply agreements across integrated delivery networks. B. Braun Melsungen AG anchors its position through backward integration into silicone catheter extrusion. Integra LifeSciences Corporation specializes in premium hydrocephalus drainage configurations that command preference among pediatric neurosurgeons.
Ventricular drainage sets are sterile, closed-circuit systems comprising catheters, collection chambers, and pressure monitoring components, typically manufactured from medical-grade silicone or PVC with Luer-lock connectors and graduated volume markings; they divert cerebrospinal fluid to relieve elevated intracranial pressure following trauma, hemorrhage, or obstructive hydrocephalus. External drainage systems dominate hospital procurement due to their reversibility and lower infection risk profile, while internal shunt systems capture the chronic hydrocephalus segment where long-term implantation reduces revision burden. Silicone material formulations lead the material category because of biocompatibility and kink resistance, though polyurethane blends are gaining traction in micro-catheter designs for pediatric applications.
FDA Class II device controls and the EU Medical Device Regulation (MDR) impose stringent biocompatibility and sterility assurance requirements that filter out smaller contract manufacturers. Japan's PMDA enforces JIS-standard conformance for neurosurgical implants, creating additional documentation barriers for non-domestic entrants. Stakeholders must monitor how evolving notified body capacity constraints in Europe and post-market surveillance mandates reshape compliance costs and competitive field composition.
Market Dynamics
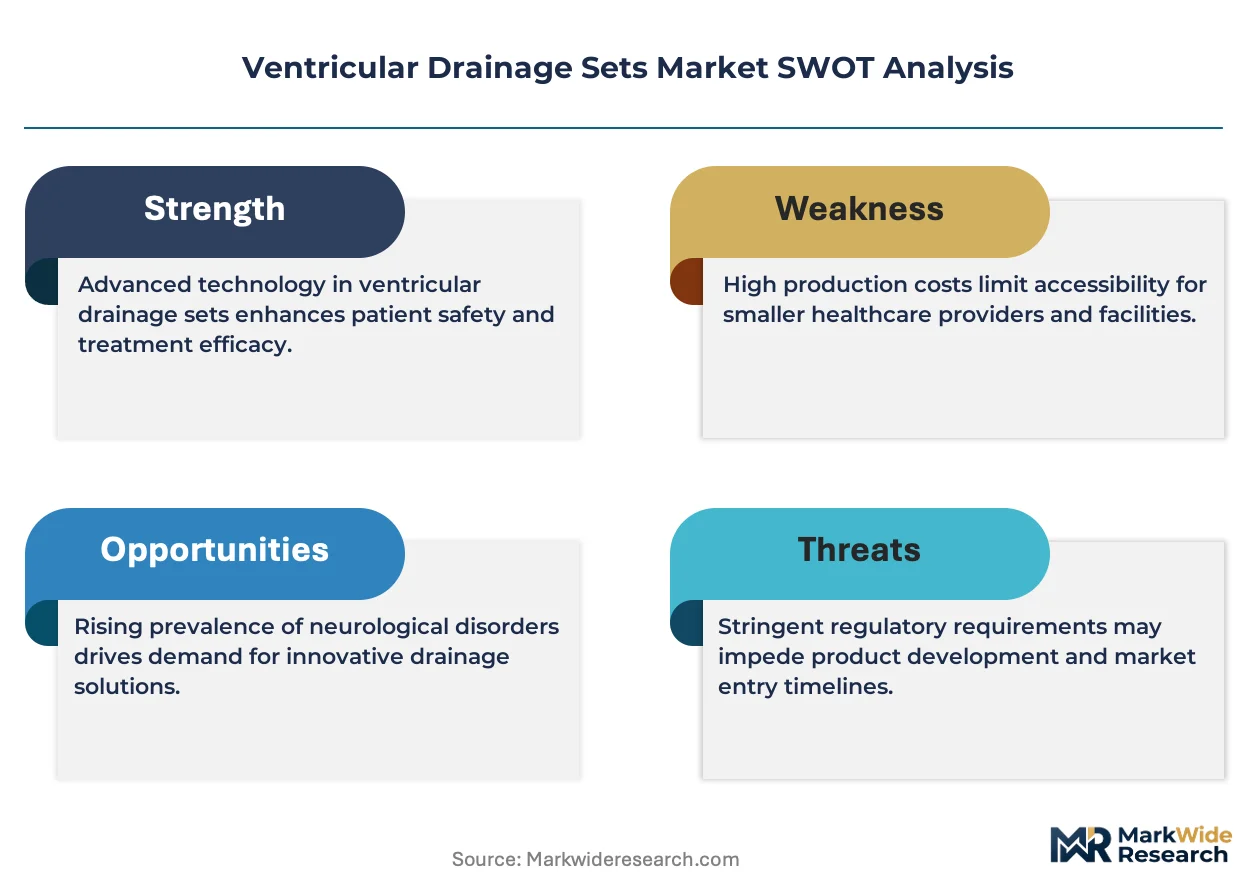
Hospital procurement consolidation is compressing vendor margins while simultaneously demanding extended sterilization validation documentation under FDA's updated Class II quality system regulations, forcing manufacturers to absorb compliance costs or exit the field.
Growth Catalysts
- Aging Demographics:Japan, Germany, and the United States are experiencing elevated intracranial pressure management procedure volumes as elderly populations expand, directly stimulating ventricular drainage set consumption in tertiary neurosurgery departments.
- EU Medical Device Regulation:MDR implementation is filtering out smaller contract manufacturers through stringent biocompatibility and sterility assurance requirements, concentrating market share among established producers with notified body relationships.
- Silicone Material Advances:Medical-grade silicone formulations with enhanced kink resistance are extending catheter functional lifespan, reducing revision frequency and strengthening preference among pediatric neurosurgeons for premium configurations.
Market Restraints
- Sterilization Validation Costs:FDA's tightened Class II device controls mandate expanded sterilization assurance documentation, imposing fixed cost burdens that disproportionately constrain mid-tier manufacturers lacking captive ethylene oxide processing capacity.
- Notified Body Bottlenecks:Europe's constrained notified body capacity is extending MDR certification timelines, delaying product launches and freezing working capital in regulatory limbo for 18-24 month periods.
- Polyurethane Substitution Threat:Micro-catheter designs utilizing polyurethane blends are capturing pediatric segment share from traditional silicone, threatening material-based competitive moats in high-growth application niches.
Strategic Opportunities
- Asset-Light Leasing Models:Flexible balance sheet structures enabling neurosurgical consumable leasing are penetrating integrated delivery networks, displacing capital purchase cycles with recurring revenue arrangements that deepen customer lock-in.
- PMDA Documentation Services:Japan's JIS-standard conformance requirements create advisory service revenue streams for firms willing to navigate PMDA neurosurgical implant documentation barriers on behalf of Western entrants lacking Tokyo regulatory presence.
- Chronic Hydrocephalus Migration:Internal shunt systems for long-term implantation are capturing patient flows from external drainage, offering manufacturers with implantable portfolio capabilities a pathway to reduce infection liability and revision burden.
Industry Challenges
- Ethylene Oxide Sterilization Expertise:Specialized technician scarcity for medical device sterilization validation is extending hiring cycles and inflating compensation costs for manufacturers expanding capacity under FDA quality system mandates.
- Legacy System Integration:New pressure monitoring components must interface with proprietary hospital data architectures, requiring custom engineering support that fragments R&D resources and delays product standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ventricular Drainage Sets Market |
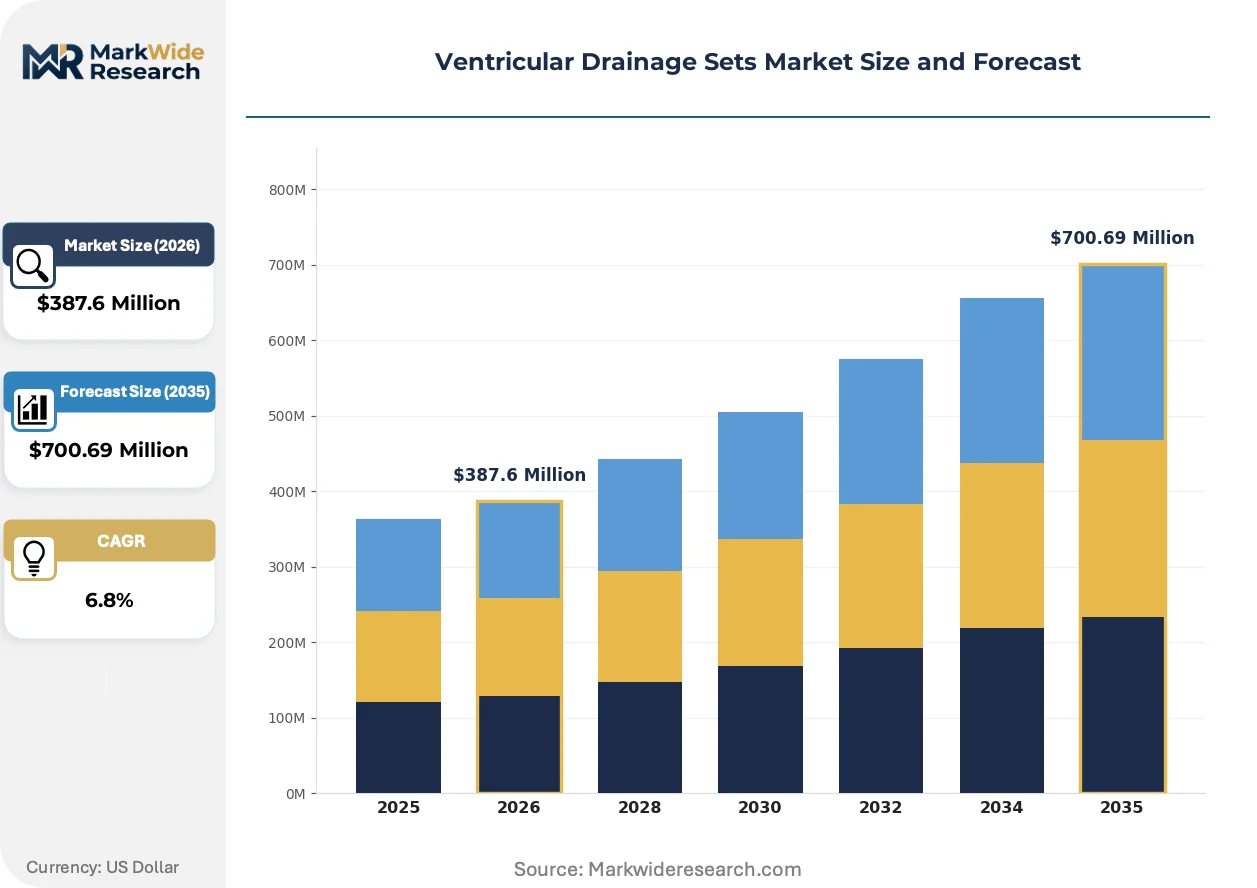
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: External Drainage Systems, Internal Drainage Systems, Accessories, Catheters End User: Hospitals, Surgical Centers, Rehabilitation Facilities, Home Care Material: Silicone, PVC, Polyethylene, Polyurethane Application: Traumatic Brain Injury, Hydrocephalus, Brain Tumors, Neurosurgery |
| Companies Covered | Spiegelberg GmbH & Co. KG, Möller Medical GmbH, Medtronic plc, Stryker Corporation, Johnson & Johnson Services, Inc., Integra LifeSciences Corporation, Sophysa S.A., Teleflex Incorporated, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ventricular Drainage Sets Market Strategic Shifts
Digital pressure monitoring integration is transforming ventricular drainage from passive fluid diversion to real-time intracranial pressure telemetry, compressing the gap between critical care and neurosurgical workflow.
Wireless intracranial pressure sensors embedded within drainage catheters are transmitting continuous data to centralized monitoring stations. Neurosurgical ICUs at academic medical centers are adopting these systems at accelerating rates, replacing manual hourly readings. This capability is virtualizing the traditional nursing observation function, enabling remote patient surveillance and reducing bedside labor intensity.
Japan's PMDA has tightened JIS-standard documentation requirements for neurosurgical implants imported from non-domestic manufacturers. The industrial consequence is a documentation arms race where Western firms must establish Tokyo-based regulatory affairs subsidiaries or surrender market access. Pediatric neurosurgery departments are most affected, as they rely on specialized micro-catheter configurations subject to enhanced scrutiny.
Hospital supply chain directors are consolidating ventricular drainage procurement into multi-year framework agreements with integrated delivery networks. Group purchasing organizations are displacing individual hospital contracting authority, concentrating purchasing power and demanding volume-based price concessions. This concentration is most visible across United States health systems where IDN consolidation has reduced independent neurosurgery department autonomy.
Ventricular Drainage Sets Market Segmentation
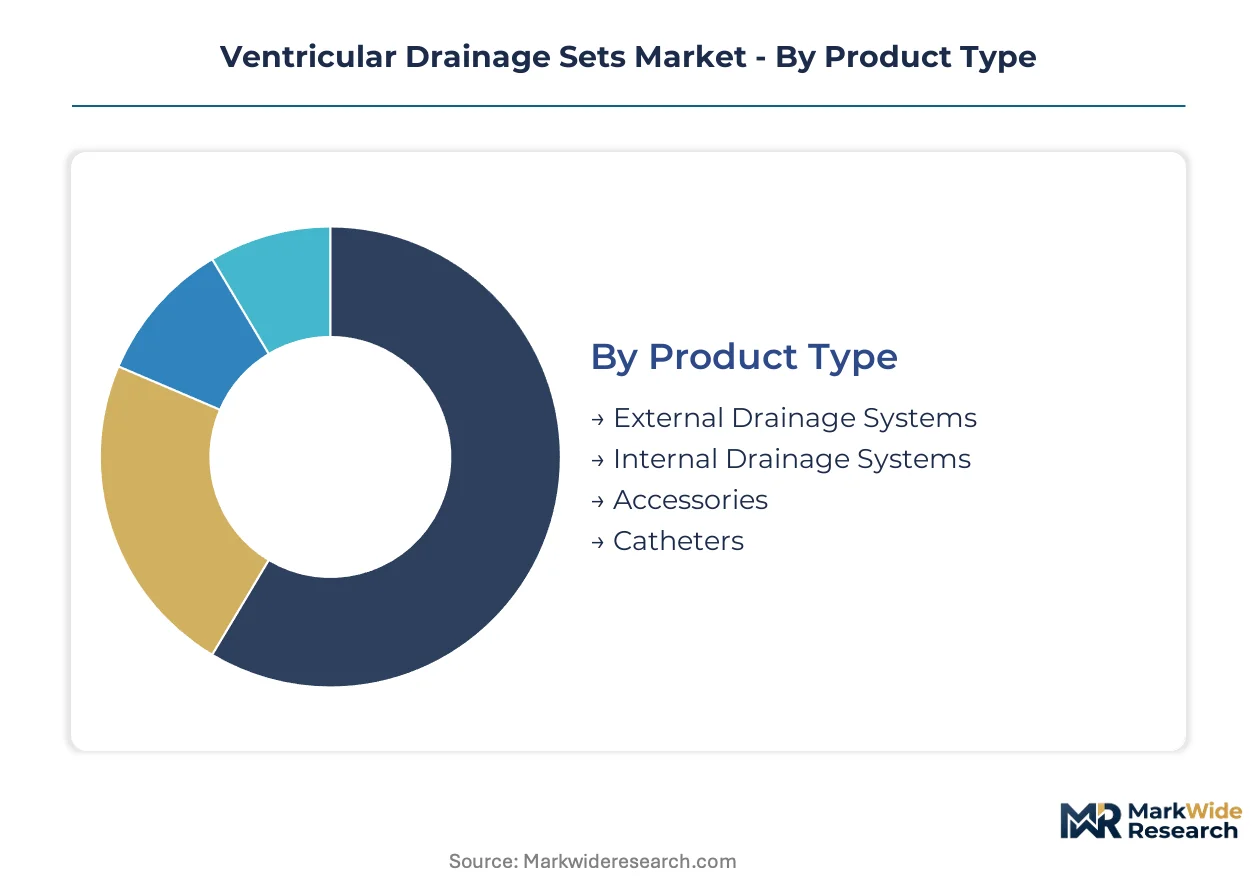
Ventricular drainage set procurement patterns diverge sharply across clinical settings and material specifications. Manufacturers must align product portfolios with distinct sterilization requirements, reimbursement pathways, and anatomical application constraints.
Product Type:
External drainage systems dominate acute care protocols where reversibility and infection control outweigh long-term implantation risks.
- External Drainage Systems:Closed-circuit configurations with collection chambers and pressure monitoring ports enable temporary cerebrospinal fluid diversion. Tertiary hospital neurosurgery departments in the United States and Germany concentrate procurement here due to lower revision burden and explant flexibility.
- Internal Drainage Systems:Implantable shunt assemblies with programmable valve mechanisms serve chronic hydrocephalus management. Demand clusters in pediatric neurosurgery units across Japan where long-term implantation reduces repeated surgical exposure.
- Accessories:Sterile tubing sets, connector adapters, and sampling ports complete circuit configurations.
- Catheters:Ventricular and lumbar insertion variants with radiopaque markers and multi-hole tip designs.
The dominant share belongs to External Drainage Systems, while Internal Drainage Systems is closing the gap fastest.
End User:
Procurement authority concentrates differently across facility types, with integrated delivery networks reshaping contracting leverage.
- Hospitals:Tertiary academic medical centers and community hospital systems generate the bulk of volume through emergency neurosurgery and ICU-based intracranial pressure management. Japan's aging demographic expansion and Germany's trauma center network density sustain concentrated demand.
- Surgical Centers:Ambulatory settings handle elective shunt revisions and diagnostic lumbar drainage with streamlined sterilization protocols.
- Rehabilitation Facilities:Post-acute settings manage external drainage weaning and pressure monitoring during recovery phases.
- Home Care:Specialized nursing services support external drainage maintenance for palliative hydrocephalus patients.
Hospitals capture the volume majority, though Surgical Centers are expanding share through outpatient shunt revision migration.
Material:
Biocompatibility and kink resistance specifications filter supplier qualification across pediatric and adult applications.
- Silicone:Medical-grade formulations with platinum-cured elastomer structures deliver superior tissue tolerance and catheter longevity. Pediatric neurosurgeons in the United States prefer silicone for neonatal ventricular access due to flexibility and reduced granuloma formation.
- PVC:Cost-efficient formulations serve short-term external drainage with standard Luer-lock compatibility.
- Polyethylene:Rigid-wall configurations support specialty drainage applications requiring column stability.
- Polyurethane:Micro-catheter designs exploit thin-wall strength-to-diameter ratios for minimally invasive insertion.
Silicone maintains the installed base leadership, yet Polyurethane is gaining fastest in micro-catheter pediatric niches.
Application:
Clinical indication severity dictates product configuration complexity and monitoring integration requirements.
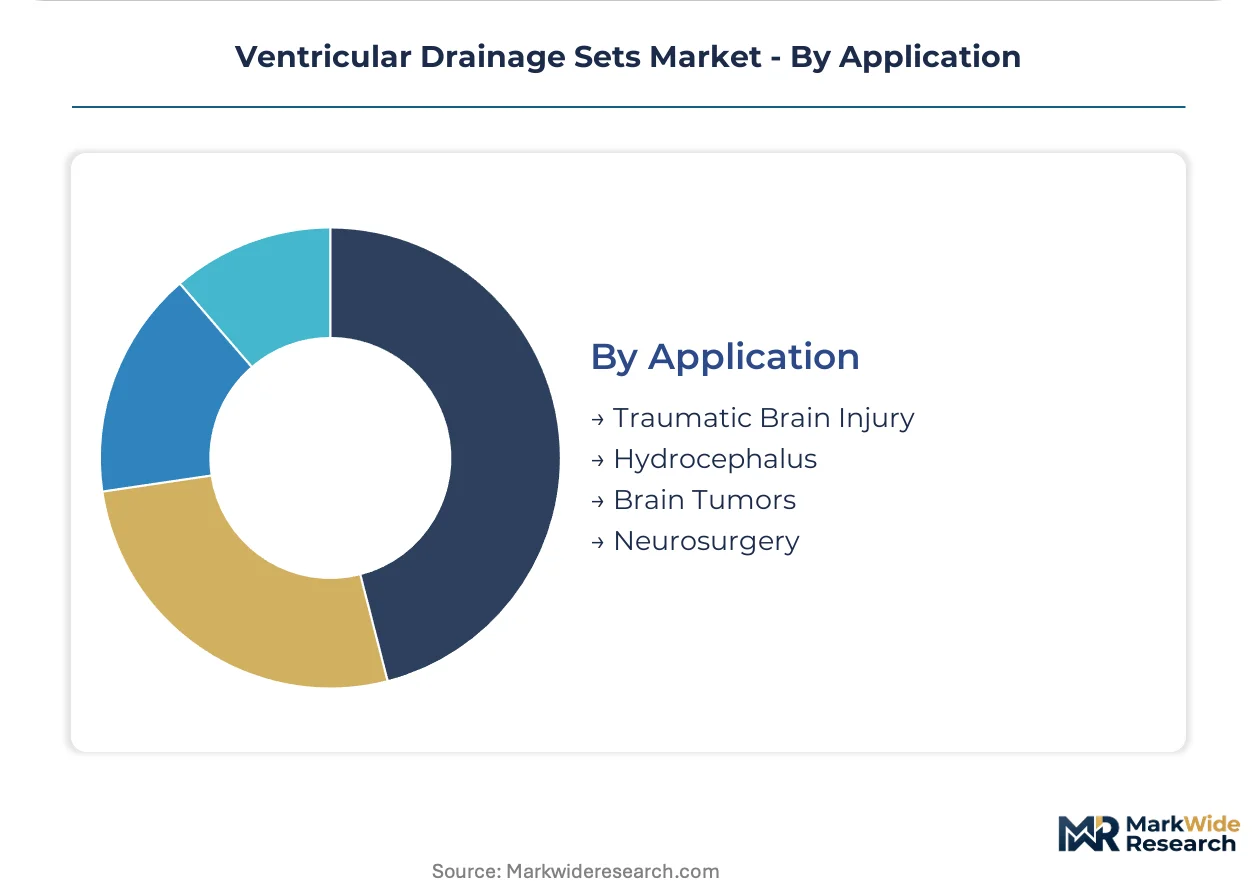
- Traumatic Brain Injury:Emergency external drainage with continuous pressure telemetry dominates neurocritical care protocols. United States trauma centers and German emergency surgery networks drive consumption through high-acuity case volume.
- Hydrocephalus:Congenital and acquired forms require differentiated approaches spanning temporary external diversion to permanent programmable shunt implantation.
- Brain Tumors:Perioperative edema management and post-resection pressure control utilize drainage adjunctively.
- Neurosurgery:General cranial and spinal procedures incorporate drainage for cerebrospinal fluid egress control.
Traumatic Brain Injury commands the largest procedure volume, while Hydrocephalus applications are expanding most quickly through pediatric and geriatric demographic pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of ventricular drainage sets track toward markets with concentrated neurosurgical infrastructure and aging patient populations. Import dependency patterns reveal regulatory complexity as the primary trade barrier rather than manufacturing capacity constraints.
United States
Tertiary hospital neurosurgery departments drive procurement volume through trauma center networks and academic medical centers. FDA Class II device controls mandate sterilization validation documentation that filters smaller contract manufacturers from import eligibility. The Greater Boston and Houston medical corridors concentrate domestic manufacturing and distribution infrastructure for silicone catheter assemblies.
Germany
Trauma center network density and emergency surgery protocols sustain elevated intracranial pressure management procedure rates. EU Medical Device Regulation implementation through notified body relationships concentrates certification capacity among established producers. The Baden-Württemberg industrial corridor hosts specialized silicone extrusion and medical device sterilization facilities serving Central European hospital systems.
Japan
Aging demographic expansion generates concentrated demand for both acute external drainage and chronic hydrocephalus shunt systems. PMDA enforces JIS-standard documentation requirements that create regulatory barriers for non-domestic entrants lacking Tokyo-based regulatory affairs presence. The Kanto region surrounding Tokyo anchors pediatric neurosurgery specialization and micro-catheter procurement.
United Kingdom
National Health Service procurement consolidation shifts contracting authority toward integrated care systems and group purchasing frameworks. MHRA post-Brexit regulatory alignment with EU MDR maintains biocompatibility and sterility assurance requirements. The Oxford-Cambridge-London triangle concentrates neurosurgical research hospitals driving premium drainage configuration adoption.
India
Expanding private hospital infrastructure and medical tourism channels stimulate demand for cost-efficient external drainage systems. CDSCO medical device regulations impose import licensing requirements that favor distributors with established regulatory compliance capabilities. Metropolitan hospital clusters in Mumbai and Delhi-NCR represent the primary consumption centers for neurosurgical consumables.
Ventricular Drainage Sets Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying catheter extrusion and sterile assembly services. Market structure tilts toward consolidation as hospital procurement aggregation and regulatory compliance costs filter marginal participants. Three archetypes dominate: diversified medical technology conglomerates with hospital contracting infrastructure, specialized neurosurgical device manufacturers with backward integration into material processing, and regional contract manufacturers serving private-label arrangements. Competitive dynamics center on multi-year supply agreement capture and sterilization capacity expansion under tightening FDA quality system mandates.
Among diversified platform operators, Medtronic plc and Stryker Corporation exemplify the hospital infrastructure leverage archetype through integrated delivery network contracting scale. B. Braun Melsungen AG occupies a distinct position representing specialized manufacturers with captive silicone supply chain control. These three entities anchor the competitive field by embodying the primary strategic vectors: contracting breadth, manufacturing integration, and regulatory compliance depth.
| Leading Market Players |
|---|
| Spiegelberg GmbH & Co. KG |
| Möller Medical GmbH |
| Medtronic plc |
| Stryker Corporation |
| Johnson & Johnson Services, Inc. |
| Integra LifeSciences Corporation |
| Sophysa S.A. |
| Teleflex Incorporated |
| B. Braun Melsungen AG |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on medical-grade silicone extrusion capacity in Germany and the United States compresses pricing flexibility while simultaneously forcing supply chain regionalization to hedge against ethylene oxide sterilization bottlenecks. Hospital procurement consolidation amplifies this tension, squeezing tier spreads between premium silicone configurations and standard PVC alternatives as manufacturers absorb compliance cost burdens.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure across integrated delivery networks. Price differentiation separates FDA-validated silicone catheter assemblies from standard PVC drainage sets, with volume scale and sterilization certification tier as the primary spread drivers. Pricing pressure stems from group purchasing organization aggregation, which is forcing manufacturers to bundle accessories at compressed margins. Pediatric neurosurgery departments demonstrate the least price sensitivity due to liability exposure, while community hospital systems in India exhibit acute cost consciousness.
Supply Chain Analysis
Export-control restrictions on medical-grade silicone precursor chemicals limit raw material flows from Germany, Japan, and the United States to contract manufacturers in lower-cost jurisdictions. Supply chains draw from platinum-cured elastomer suppliers in Baden-Württemberg, radiopaque marker compounders in the Greater Boston corridor, and sterile assembly facilities in Ireland. Single-source vulnerability concentrates in ethylene oxide sterilization capacity, where EPA emissions regulations have shuttered domestic processing sites. Distribution runs through specialized medical device distributors serving hospital systems and direct contracting with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethylene oxide sterilization technician scarcity defines competitive durability in this market, privileging manufacturers with captive validation expertise and hospital contracting infrastructure over asset-light assemblers.
For Market Incumbents: Build regulatory documentation moats by expanding Tokyo-based PMDA affairs subsidiaries and securing multi-year sterilization capacity commitments under FDA quality system mandates. Absorb mid-tier manufacturers facing compliance cost exhaustion to consolidate notified body relationships. Defend against polyurethane micro-catheter substitution by locking pediatric neurosurgery departments into silicone-based premium configurations through extended service agreements. For New Entrants and Emerging Players: Establish a beachhead in India's private hospital infrastructure by offering cost-efficient PVC external drainage systems with streamlined CDSCO import licensing support. Target surgical centers in Germany's outpatient shunt revision migration as the most penetrable channel, bypassing entrenched IDN contracting blocks. Deploy regulatory documentation advisory services as the primary go-to-market angle, monetizing PMDA and FDA navigation expertise for Western firms lacking Asian regulatory presence. For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape by filtering out smaller contract manufacturers and concentrating value among entities with notified body certification and backward integration into silicone catheter extrusion. Long-term viability favors manufacturers with implantable shunt portfolio capabilities, as chronic hydrocephalus applications reduce infection liability and revision burden. Monitor notified body capacity expansion timelines as the critical inflection signal for certification backlog resolution and working capital release.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | Class II device controls demand expanded sterilization validation documentation for market access. |
| Hospital System Partnership | Multi-year framework agreements with integrated delivery networks lock in volume and deepen customer captivity. |
| Backward Integration | In-house silicone catheter extrusion insulates margin pressure from medical-grade elastomer supply concentration. |
| Software Companion Development | Digital pressure monitoring integration transforms passive drainage into real-time telemetry revenue streams. |
| Reimbursement Strategy | Alignment with CMS and German DRG pathways secures procedure volume for acute and chronic applications. |
Study Parameters
A spread of perspectives from neurosurgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists converged on the working assumptions underlying demand and supply calibration. Primary fieldwork across tertiary academic medical centers in the United States, Germany, and Japan was cross-validated against FDA 510(k) filings, PMDA approval databases, EU MDR notified body certificates, hospital procurement contract repositories, and customs trade records. Bottom-up procedure volume estimates and top-down manufacturer shipment data were triangulated to anchor segmentation outputs.
Demand-supply balance dynamics across the analysis window were modeled through procedure volume projections by clinical indication, material substitution elasticities, and sterilization capacity constraints. Segmentation dimensions spanned product type, end-user facility tier, material formulation, and application severity. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns and adjusted for regulatory milestone effects. Forecast inputs incorporated aging demographic trajectories in Japan and Germany, trauma center network density in the United States, and pediatric hydrocephalus prevalence rates.
Stress conditions across ethylene oxide sterilization capacity availability, notified body certification timelines, and polyurethane material substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and hospital procurement consolidation velocity. Material shifts in FDA Class II quality system enforcement stringency or PMDA JIS-standard documentation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiac Surgery Devices Market
Cardiovascular Devices
Vital Sign Simulators Market
Cardiovascular Devices
Infusion System Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Cardiovascular Stents Market
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
South Africa Cardiovascular Devices Market
Cardiovascular Devices
Global Non-Vascular Stents Market
Cardiovascular Devices
Interventional Cardiology Market
Cardiovascular Devices
Drug-Coated Balloon Catheter Market
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market
Cardiovascular Devices
Hemodynamic Monitoring Devices Market
Cardiovascular Devices
Peripheral Vascular Devices Market
Cardiovascular Devices
Global Cardiac Arrest Treatment Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market