
 Australia Cardiovascular Devices Market | 2026-2036
Australia Cardiovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Cardiovascular Devices Market Outlook
Cardiac centers is expanding their share of cardiovascular device procurement across Australia, shifting volume away from general hospital wards toward dedicated intervention facilities. Abbott Laboratories anchors its position through deep catheter and stent portfolios aligned with cath lab workflows. Medtronic PLC competes across pacemaker and monitoring device lines, leveraging its cardiac rhythm management heritage. Boston Scientific Corporation specializes in interventional cardiology platforms, sustaining R&D intensity in drug-eluting stent technologies.
Cardiovascular devices encompass implantable and interventional instruments designed to diagnose, monitor, or treat heart and vascular conditions, typically manufactured from biocompatible alloys, polymers, or biological tissues under cleanroom conditions with precision micromachining. These instruments restore blood flow, regulate cardiac rhythm, or enable minimally invasive structural repair across acute and chronic care settings. Stents and catheters occupy mature margin pools where procurement consolidation pressures pricing, while robotic surgery systems represent the fastest-growing technology segment as Australian hospitals invest in precision intervention platforms. Pacemakers maintain steady replacement demand, though imaging systems now capture expanding capital budgets as pre-procedural planning intensifies.
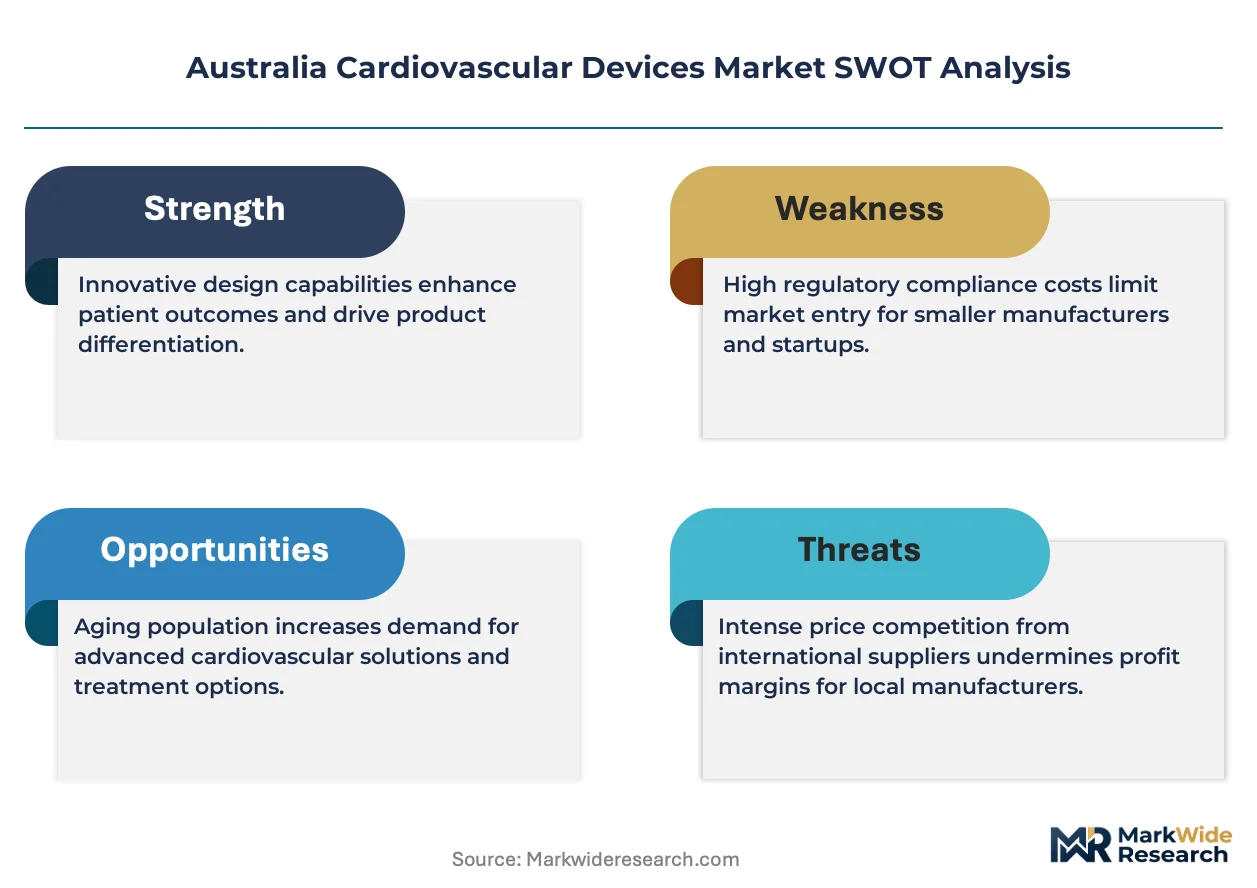
TGA regulates medical device registration through risk-based classification, requiring clinical evidence and post-market surveillance for Class III implantables such as pacemakers and valves. The Therapeutic Goods Act and ISO 13485 quality management standards govern manufacturing compliance, directly influencing which manufacturers secure Australian Register of Therapeutic Goods listings. Stakeholders must monitor TGA's evolving software as a medical device framework, as algorithm-enabled monitoring devices and robotic surgery platforms trigger new conformity assessment pathways that will reshape competitive access.
Market Dynamics
Australia's cardiovascular device market is restructuring around cath lab consolidation as metropolitan hospital networks centralize complex procedures into dedicated cardiac centers, concentrating procurement power and reshaping supplier access patterns across New South Wales and Victoria.
Growth Catalysts
- TGA software as a medical device framework:Algorithm-enabled monitoring devices and robotic surgery platforms are creating new registration pathways that reward early-mover manufacturers with differentiated market access.
- Aging demographic structural demand:Australia's population over 65 is expanding intervention volumes for pacemaker replacements and structural heart repairs, locking in baseline device consumption regardless of economic cycles.
- Metropolitan cath lab infrastructure investment:Hospital networks in Sydney and Melbourne are expanding interventional capacity, creating concentrated demand nodes that justify premium device stocking and specialist technical support.
Market Restraints
- Biocompatible alloy input cost volatility:Nickel-titanium and cobalt-chrome prices fluctuate with mining supply disruptions, compressing margins on stent and pacemaker lead manufacturing.
- TGA clinical evidence requirements:Class III implantable device registration demands extensive local trial data, extending time-to-revenue for novel valve and leadless pacemaker technologies by multiple years.
- Metropolitan demand concentration risk:Over 70% of complex procedures flow through Sydney and Melbourne hospital networks, creating geographic dependency that amplifies reimbursement policy shocks.
Strategic Opportunities
- Western Australia and Queensland cath lab expansion:Perth and Brisbane hospital networks are building interventional capacity to reduce patient transfer costs, opening procurement relationships outside the southeastern corridor.
- Remote monitoring platform convergence:Integration of implantable cardiac monitors with cloud-based patient management systems is enabling subscription revenue models that decouple device sales from procedure volumes.
- Public hospital procurement consolidation:State-based health department bulk purchasing frameworks are creating volume incentives for manufacturers willing to standardize device configurations across hospital networks.
Industry Challenges
- Specialist interventional cardiologist workforce scarcity:Complex structural heart procedures require fellowship-trained operators, and training pipeline constraints limit procedure volume growth regardless of device availability.
- Legacy hospital information system integration:Robotic surgery platforms and AI-enabled imaging systems require costly middleware development to interface with entrenched electronic medical record architectures.
- ISO 13485 quality management recertification timelines:Manufacturing facility audits and documentation updates consume internal resources during periods of product portfolio expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Cardiovascular Devices Market |
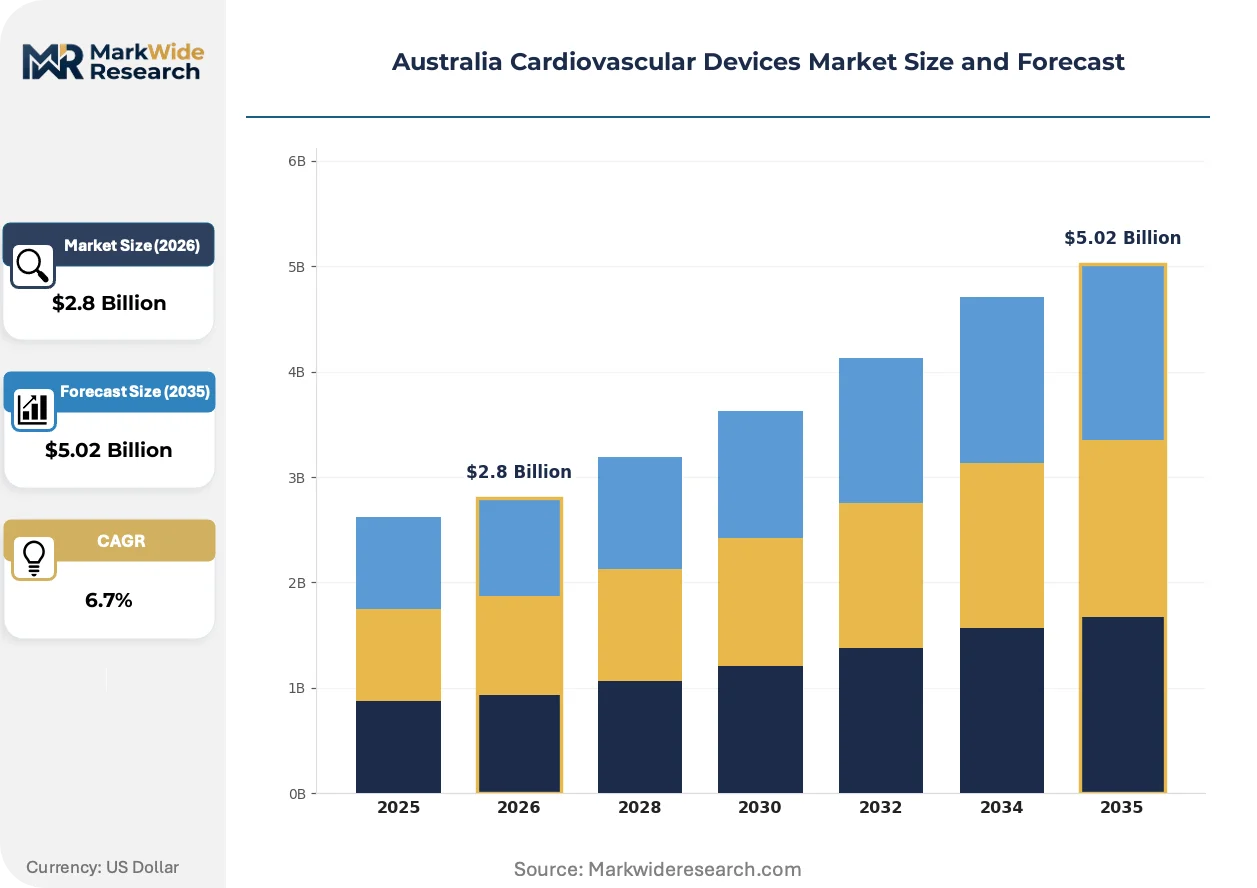
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Pacemakers, Catheters, Valves End User: Hospitals, Outpatient Clinics, Cardiac Centers, Rehabilitation Facilities Technology: Minimal Invasive, Robotic Surgery, Imaging Systems, Monitoring Devices Delivery Mode: Direct Sales, Online Sales, Distributors, Third-party Providers |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Medtronic PLC, B. Braun SE, Cardinal Health Inc., Edwards Lifesciences, Biotronik, GE Healthcare, W. L. Gore & Associates Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Cardiovascular Devices Market Strategic Shifts
Digital integration and precision intervention platforms are compressing the gap between diagnostic imaging and therapeutic delivery, enabling same-session diagnosis-to-treatment workflows that reshape capital allocation and staffing models across Australian cardiac centers.
Robotic-assisted coronary intervention systems are electrifying cath lab procedure workflows by enabling sub-millimeter catheter control and reducing operator radiation exposure. Major teaching hospitals in Sydney and Melbourne are piloting these platforms for complex chronic total occlusion cases, compressing the learning curve for advanced interventional techniques and creating tiered service capabilities between metropolitan and regional centers.
TGA's evolving software as a medical device framework is reclassifying algorithm-enabled diagnostic tools and remote patient monitoring systems, triggering new conformity assessment obligations for manufacturers embedding AI into cardiovascular devices. The regulatory friction falls heaviest on Class III implantable monitors with predictive analytics, forcing sponsors to rebuild clinical evidence packages around software validation rather than traditional hardware safety endpoints.
State health department procurement frameworks are consolidating device selection authority away from individual cath lab directors toward centralized value-analysis committees. New South Wales and Victoria hospital networks now mandate standardized stent and catheter configurations across their cardiac centers, compressing supplier rosters and forcing manufacturers to compete on total cost-of-ownership metrics rather than individual product performance claims.
Australia Cardiovascular Devices Market Segmentation
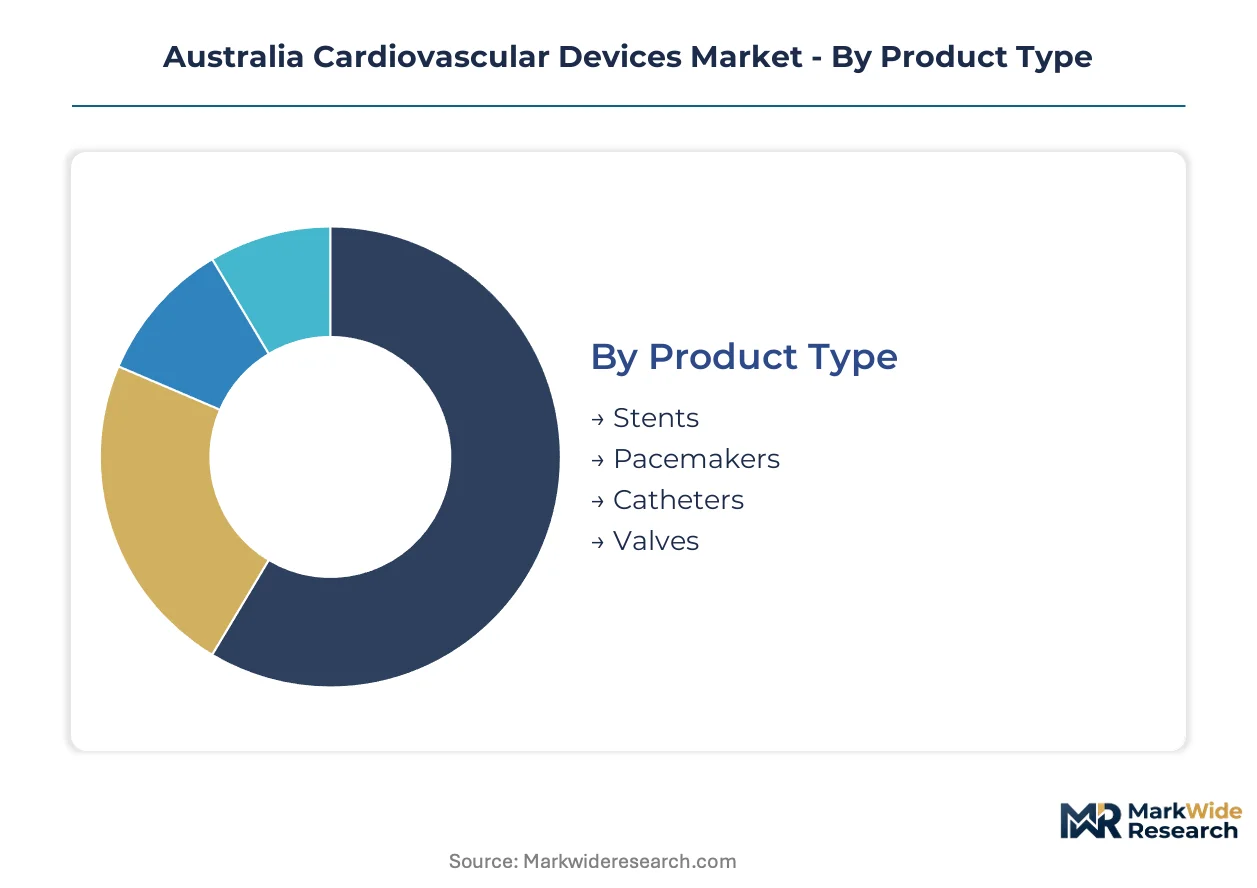
Segmentation reveals how capital allocation and procurement authority concentrate across Australia's cardiovascular device landscape. Understanding these divisions exposes where manufacturers must deploy technical support resources and which customer types command pricing leverage.
Product Type:
Stents and pacemakers demand the heaviest upfront manufacturing investment in precision micromachining and cleanroom infrastructure, while catheters and valves require specialized biological testing facilities.
- Stents:Drug-eluting and bare-metal coronary stents manufactured from nickel-titanium or cobalt-chrome alloys. New South Wales and Victorian cardiac centers drive procurement volume as cath lab networks consolidate complex intervention workflows.
- Pacemakers:Implantable pulse generators with transvenous or leadless configurations. Replacement cycles for Australia's aging population sustain baseline demand through metropolitan hospital networks in Sydney and Melbourne.
- Catheters:Diagnostic and interventional catheters for angiography and electrophysiology mapping.
- Valves:Surgical and transcatheter aortic valve replacements requiring extensive TGA clinical evidence packages.
Stents absorb the bulk of installed cath lab capacity; robotic-compatible catheter platforms are expanding most quickly.
End User:
Procurement authority clusters differently across facility types, with cardiac centers wielding disproportionate influence over high-value implantable selections.
- Hospitals:General acute care facilities with mixed cardiovascular service lines. State health department bulk purchasing frameworks in New South Wales and Victoria constrain individual hospital autonomy over device selection.
- Cardiac Centers:Dedicated intervention facilities with concentrated cath lab infrastructure. Sydney and Melbourne networks drive premium device stocking and specialist technical support requirements.
- Outpatient Clinics:Diagnostic and follow-up care settings with limited procedural capacity.
- Rehabilitation Facilities:Post-acute care centers managing device monitoring and patient recovery protocols.
Cardiac centers capture the steepest expansion trajectory in procurement volume; rehabilitation facilities remain the most price-sensitive segment.
Technology:
Capital intensity stratifies sharply across technology platforms, with robotic surgery systems requiring multimillion-dollar installation commitments versus disposable monitoring devices.
- Robotic Surgery:Computer-assisted intervention platforms enabling sub-millimeter catheter control. Major teaching hospitals in Sydney and Melbourne pilot these systems for chronic total occlusion cases, compressing operator learning curves.
- Imaging Systems:Intravascular ultrasound and optical coherence tomography for pre-procedural planning. Metropolitan hospital networks allocate expanding capital budgets as diagnostic precision demands intensify.
- Minimal Invasive:Percutaneous techniques reducing patient recovery time and hospital length of stay.
- Monitoring Devices:Implantable cardiac monitors and external telemetry systems with cloud connectivity.
Imaging systems command the largest capital deployment; robotic surgery platforms are gaining share fastest.
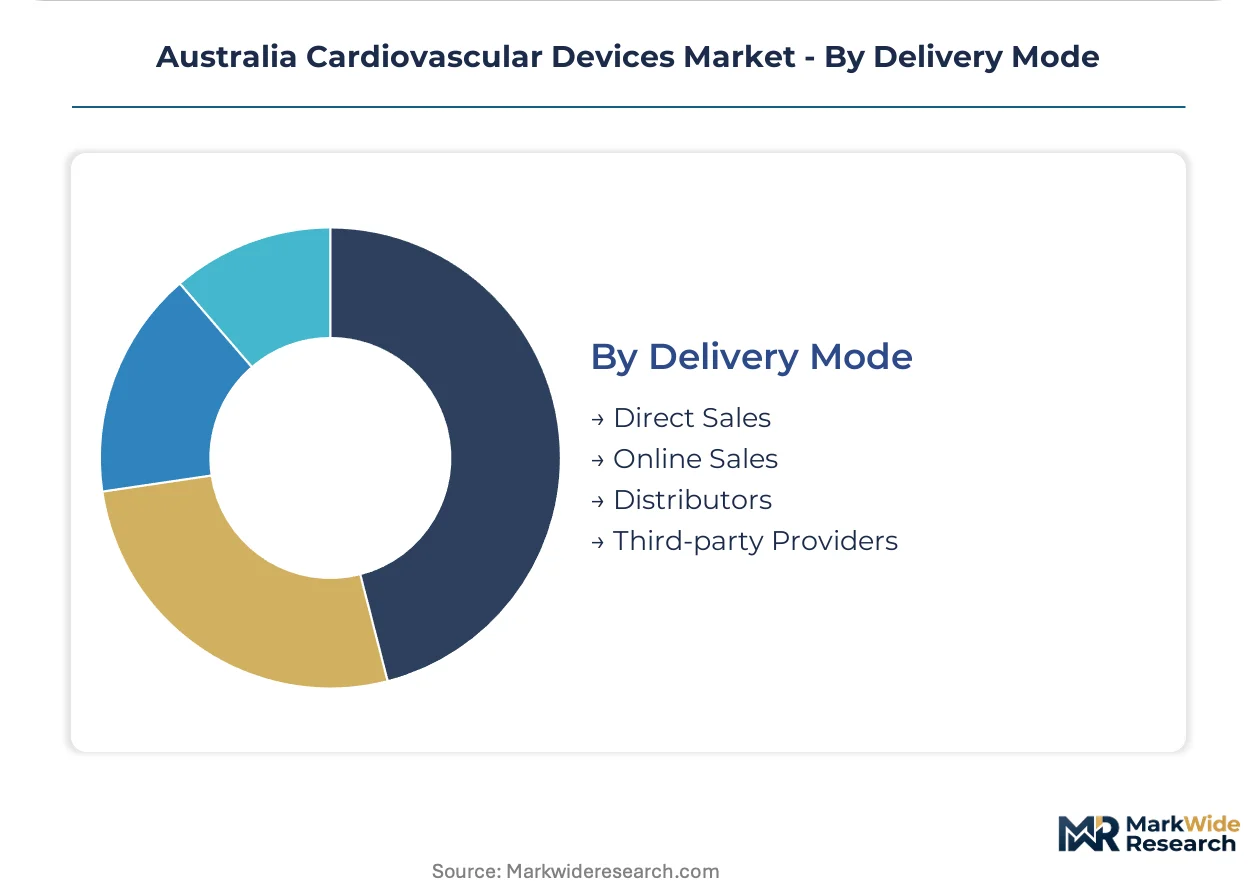
Delivery Mode:
Channel economics diverge based on device complexity and the technical support intensity required for implantable products.
- Direct Sales:Manufacturer-employed specialists managing high-value implantable relationships. Cardiac center consolidation in Sydney and Melbourne rewards dedicated account teams with deep clinical workflow expertise.
- Distributors:Third-party logistics providers handling inventory and regional delivery. Western Australia and Queensland expansion creates opportunities outside manufacturer direct coverage zones.
- Online Sales:E-procurement platforms for consumables and replacement components.
- Third-party Providers:Group purchasing organizations and managed service arrangements.
Direct sales retains dominance for Class III implantables; distributor relationships are deepening fastest in peripheral states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing of cardiovascular devices remains limited in Australia, with the majority of implantable and interventional products imported from US and European suppliers. Consumption concentrates heavily in the southeastern corridor, where cath lab infrastructure and specialist workforce density create demand nodes that outpace local production capacity. State health department procurement frameworks now govern device selection authority across public hospital networks.
New South Wales
Sydney's metropolitan hospital networks drive the steepest procurement volumes for drug-eluting stents and robotic surgery platforms. The NSW Ministry of Health mandates standardized device configurations across cardiac centers, compressing supplier rosters through bulk purchasing agreements. The Royal Prince Alfred Hospital and Westmead Hospital anchor interventional capacity, with cath lab consolidation funneling complex structural heart procedures into dedicated facilities.
Victoria
Melbourne's teaching hospitals pilot robotic-assisted coronary intervention systems for chronic total occlusion cases, creating tiered service capabilities that differentiate metropolitan from regional centers. The Victorian Department of Health's value-analysis committees now control implantable device selection across public networks. Alfred Hospital and Royal Melbourne Hospital concentrate specialist workforce density, attracting premium device stocking and technical support resources from manufacturers.
Queensland
Brisbane hospital networks are expanding interventional capacity to reduce patient transfer costs to Sydney and Melbourne, opening procurement relationships outside the southeastern corridor. Queensland Health's cardiac services plan directs capital investment toward cath lab infrastructure in metropolitan and regional centers. The Prince Charles Hospital and Gold Coast University Hospital are building structural heart programs that justify dedicated device inventory and specialist staffing.
Western Australia
Perth's isolation from eastern demand centers is driving self-sufficient cath lab development at Fiona Stanley Hospital and Sir Charles Gairdner Hospital. The WA Department of Health prioritizes reducing interstate patient transfers for complex interventions, creating localized procurement nodes. Royal Perth Hospital maintains the state's highest procedural volumes for transcatheter valve replacements, attracting manufacturer technical support commitments.
South Australia
Adelaide's cardiac centers operate at smaller scale than Sydney or Melbourne, with Flinders Medical Centre and Royal Adelaide Hospital managing regional referral networks for South Australia and the Northern Territory. The SA Health procurement framework emphasizes cost containment over premium technology adoption, favoring standardized stent and pacemaker configurations. Workforce constraints limit expansion of robotic surgery platforms despite capital availability.
Australia Cardiovascular Devices Market Competitive Environment
Top-tier vendors anchor the premium implantable segment, while mid-scale specialists and regional distributors populate the interventional consumables tier. The market structure reflects concentrated cath lab procurement authority alongside fragmented distributor networks serving peripheral states. Three archetypes dominate: diversified medical technology conglomerates with full cardiac rhythm management portfolios; interventional cardiology specialists focused on catheter and stent technologies; and imaging and monitoring platform providers integrating software-enabled diagnostics. Competitive dynamics center on strategic partnerships with state health departments and technology licensing arrangements for robotic surgery platforms.
Within the diversified conglomerate tier, Abbott Laboratories and Medtronic PLC occupy positions defined by comprehensive cardiac rhythm management heritage and deep cath lab workflow integration. Boston Scientific Corporation exemplifies the interventional cardiology specialist archetype, with its positioning tied to drug-eluting stent technology leadership and electrophysiology mapping platform development. These three companies represent the competitive anchors around which procurement consolidation in New South Wales and Victoria is restructuring supplier access patterns.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Medtronic PLC |
| B. Braun SE |
| Cardinal Health Inc. |
| Edwards Lifesciences |
| Biotronik |
| GE Healthcare |
| W. L. Gore & Associates Inc. |
| Others |
Value Chain & Pricing Dynamics
Nickel-titanium and cobalt-chrome price indices cascade through cardiovascular device manufacturing into three-tier pricing structures across premium, standard, and economy levels. Biocompatible alloy volatility compresses margins on stent and pacemaker leads while state health department bulk purchasing concentrates buyer power in New South Wales and Victoria cardiac centers.
Pricing Analysis
Margin tightening in the implantable tier reflects TGA clinical evidence requirements extending registration timelines for novel valve and leadless pacemaker technologies. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale commitments. Cost-down pressure on interventional consumables accelerates as cath lab consolidation funnels procurement authority toward centralized value-analysis committees. Rehabilitation facilities exhibit the steepest price sensitivity; cardiac centers in Sydney and Melbourne networks demonstrate the least.
Supply Chain Analysis
Nickel-titanium alloy supply rests on mining operations in Australia and Indonesia with specialty refining concentrated in Germany and Japan. Cobalt-chrome feedstock draws from South African and Russian sources with European precision alloy processing. Single-source vulnerability in biocompatible polymer coatings creates exposure to logistics chokepoints through Singapore and Rotterdam distribution hubs. Distribution runs through manufacturer direct sales teams for Class III implantables and third-party logistics networks for consumables in Western Australia and Queensland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's cardiovascular device market sits in a technology-transition phase as robotic-assisted intervention platforms displace conventional catheter workflows in metropolitan teaching hospitals.
For Market Incumbents: Cement cath lab workflow integration through dedicated technical support teams embedded in Sydney and Melbourne cardiac centers. Deepen software companion development for remote monitoring platforms to capture subscription revenue models decoupled from procedure volumes. Threat from TGA's evolving software as a medical device framework demands rebuilt clinical evidence packages; certification investment in algorithm validation capabilities serves as the priority lever. For New Entrants and Emerging Players: TGA's software as a medical device framework in Australia opens a window for algorithm-enabled diagnostic tools and AI-embedded monitoring devices. Target Western Australia and Queensland cath lab expansion zones where distributor relationships deepen fastest outside incumbent direct coverage. Perth and Brisbane hospital networks building interventional capacity represent the most penetrable geography. Go-to-market through state health department procurement frameworks with standardized device configurations tailored to bulk purchasing requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale interventional cardiology specialists with catheter and stent portfolios in Queensland and Western Australia. Long-term viability across the analysis window hinges on robotic surgery platform licensing arrangements and hospital system partnership density. Watch TGA registration pathway acceleration for Class III implantables with predictive analytics as the inflection signal indicating competitive access reshuffling.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Software Registration Pathway | Algorithm-enabled devices gain differentiated market access through early compliance with evolving conformity assessment obligations. |
| Hospital System Partnership | State health department bulk purchasing frameworks in New South Wales and Victoria reward standardized configuration commitments. |
| Robotic Surgery Platform Licensing | Sub-millimeter catheter control capabilities compress operator learning curves for chronic total occlusion cases in teaching hospitals. |
| Remote Monitoring Platform Integration | Cloud-based patient management systems enable subscription revenue models decoupled from acute procedure volumes. |
| Cath Lab Technical Support Deployment | Dedicated account teams with deep clinical workflow expertise capture procurement consolidation in metropolitan cardiac centers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this cardiovascular device market analysis. Primary interviews with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with TGA registration databases, state health department procurement disclosures, and hospital capital expenditure records. Bottom-up device shipment estimates and top-down healthcare expenditure allocations were triangulated to reconcile volume and value outputs.
Data-stream reconciliation across implantable unit sales, cath lab procedure volumes, and capital equipment installations shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, end-user facility tier, technology platform, and delivery mode with regional demand concentration patterns. CAGRs were derived from trend extrapolation of aging demographic intervention rates and infrastructure investment pipelines. Robotic surgery adoption curves and TGA registration timeline assumptions served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for robotic-assisted coronary intervention would alter the outlook if specialist workforce training pipelines constrain deployment velocity. Forecasts reflect assumptions around TGA software framework implementation timing and state health department procurement consolidation trajectories. Supply disruption in nickel-titanium alloy markets and reimbursement policy shocks concentrated in Sydney and Melbourne networks represent specific risk factors. A small set of triggers including TGA registration acceleration signals and cath lab expansion announcements in Perth and Brisbane warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Sclerotherapy Market
Cardiovascular Devices
Sweden Cardiovascular Devices Market
Cardiovascular Devices
Peripheral Vascular Interventions Market
Cardiovascular Devices
Neurovascular Stent Retrievers Market
Cardiovascular Devices
Mobile Cardiac Telemetry Device Market
Cardiovascular Devices
Continuous Cardiac Monitoring Systems Market
Cardiovascular Devices
Global Heart Valve Repair and Replacement Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
Saphenous Vein Grafts Market
Cardiovascular Devices
Global Pediatric Interventional Cardiology Market
Cardiovascular Devices
Vital Signs Monitoring Devices Market
Cardiovascular Devices
Global Peripheral Stent Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Vascular Access Systems Market
Cardiovascular Devices
Canada Cardiovascular Devices Market