
 Interventional Cardiology Market | 2026-2036
Interventional Cardiology Market Size, Share, and Industry Trends Forecast 2026-2036
Interventional Cardiology Market Outlook
Aftermarket service revenue is reconfiguring how device manufacturers capture lifetime value from installed imaging and physiology systems. Boston Scientific Corporation leverages dedicated field engineering teams to sustain high-margin service contracts across its intravascular ultrasound fleet. Medtronic anchors its coronary portfolio through integrated cath lab ecosystems that combine hardware, disposables, and remote monitoring. Abbott Laboratories differentiates via optical coherence tomography platforms that occupy the premium imaging tier in complex lesion assessment.
Interventional cardiology encompasses catheter-based diagnostic and therapeutic procedures targeting coronary, peripheral, and structural heart pathologies, utilizing devices typically constructed from nickel-titanium alloys, cobalt-chromium, or polymeric matrices and delivered through 5-7 French guiding catheters under fluoroscopic guidance. Its primary purpose is to restore vessel patency or correct valvular defects without sternotomy, reducing procedural trauma and recovery intervals. Drug-eluting stents retain the largest revenue share within product type segmentation, while bioabsorbable platforms represent the fastest-growing technology category as polymer science resolves mechanical integrity and controlled degradation timelines. Catheters and guidewires compete primarily on trackability and torque response, with margin pools concentrating in hydrophilic-coated and steerable configurations for chronic total occlusion cases.
FDA premarket approval pathways and the EU MDR clinical evidence requirements shape device development timelines and market access costs for manufacturers seeking transatlantic commercialization. The EPA and OSHA additionally govern sterilization facility emissions and operator radiation exposure limits, respectively, influencing capital deployment decisions for cath lab construction. Stakeholders must monitor how CMS procedural code valuations and site-of-service differentials reshape the economic viability of ambulatory versus hospital-based intervention settings.
Market Dynamics
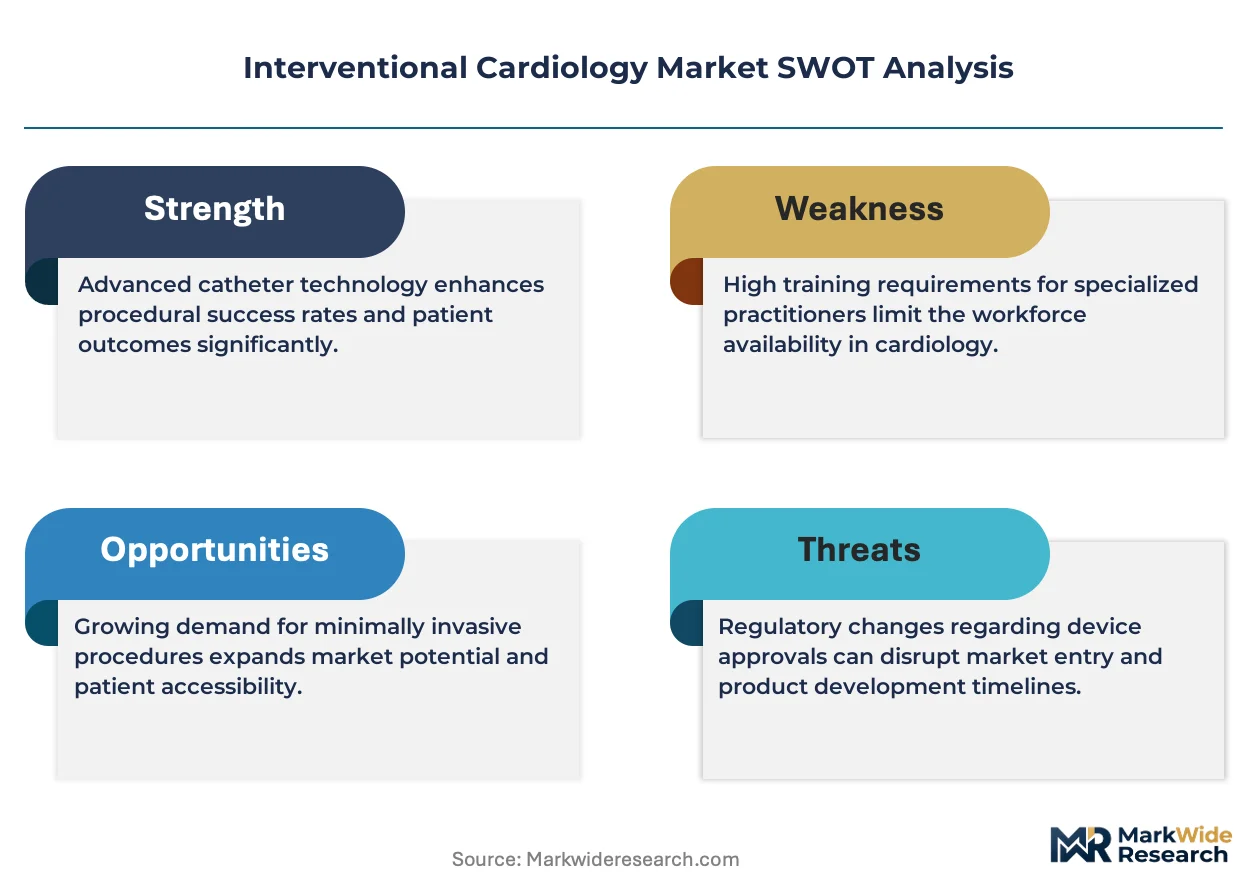
The migration of complex coronary procedures from hospital inpatient settings to ambulatory surgical centers is restructuring site-of-service economics and forcing manufacturers to recalibrate device form factors for leaner cath lab environments.
Growth Catalysts
- CMS site-of-service reimbursement differentials:Medicare payment spreads between hospital outpatient departments and ambulatory surgical centers now favor catheter-based interventions performed outside traditional hospitals, accelerating capital deployment into physician-owned superlabs across the United States.
- Polymer science advances in bioabsorbable scaffolds:Controlled degradation timelines and mechanical integrity improvements in polylactic acid matrices are expanding the treatable lesion complexity range for bioresorbable vascular scaffolds.
- Chronic total occlusion specialist networks:Dedicated CTO clubs and proctoring programs in Japan and South Korea are standardizing complex lesion techniques and driving demand for specialized guidewire and microcatheter platforms.
Market Restraints
- Nickel-titanium alloy supply concentration:Superelastic nitinol wire drawing capacity concentrates among a handful of German and Japanese metallurgical suppliers, creating vulnerability for stent and guidewire manufacturers dependent on consistent alloy properties.
- EU MDR clinical evidence escalation:The Medical Device Regulation's expanded requirements for post-market surveillance and PMCF studies have extended approval timelines and multiplied regulatory spend for bioabsorbable stent platforms seeking CE marking.
- Operator radiation exposure limits:OSHA-mandated dose thresholds and ALARA principles constrain procedural throughput in high-volume cath labs, capping revenue per operator hour regardless of device efficiency gains.
Strategic Opportunities
- India's underserved peripheral artery disease population:Below-the-knee intervention penetration remains minimal outside tertiary urban centers, creating whitespace for catheter-based limb salvage platforms adapted to cost-sensitive procurement environments.
- Integrated physiology-imaging convergence:The combination of intravascular ultrasound with instantaneous wave-free ratio measurement in single-catheter platforms reduces hardware footprint and disposable inventory complexity.
- Japan's aging structural heart cohort:METI reimbursement pathways for transcatheter edge-to-edge repair are expanding treatable patient pools beyond surgical ineligibility criteria, opening valve intervention to intermediate-risk profiles.
Industry Challenges
- Fluoroscopy-to-CT image registration expertise:Fusion imaging for structural heart procedures demands cross-trained electrophysiology and imaging technologists, a hybrid skill set scarce in community hospital settings.
- Legacy PACS integration with optical coherence tomography:DICOM compatibility gaps between next-generation intravascular imaging consoles and existing hospital archive systems delay deployment and fragment data workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interventional Cardiology Market |
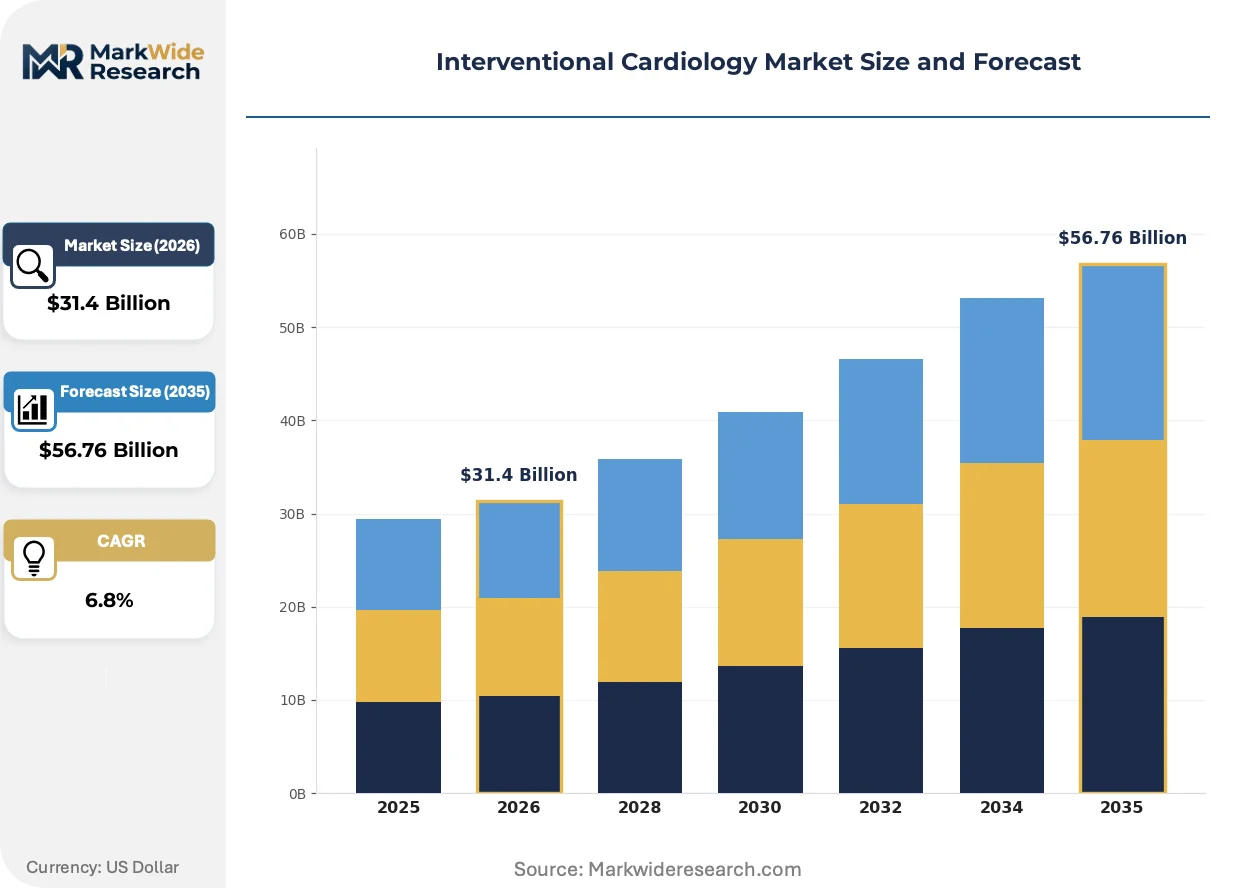
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $56.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Balloons, Catheters, Guidewires Application: Coronary Intervention, Peripheral Intervention, Structural Heart, Endovenous Procedures Technology: Drug-Eluting, Bioabsorbable, Mechanical, Imaging End User: Hospitals, Cardiac Centers, Ambulatory Surgical Centers, Research Institutions |
| Companies Covered | Boston Scientific Corporation, Medtronic, Abbott Laboratories, Edwards Lifesciences Corporation, B. Braun SE, Terumo Corporation, Koninklijke Philips N.V., BIOTRONIK SE & Co. KG, Cook Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interventional Cardiology Market Strategic Shifts
Computational modeling and artificial intelligence are compressing the feedback loop between procedural imaging and real-time therapeutic decision-making, shifting competitive advantage from hardware specifications to algorithmic interpretation layers.
Intravascular imaging analysis software is virtualizing the diagnostic function previously performed by human operators interpreting grayscale IVUS or OCT frames. High-volume interventional cardiologists in integrated US health systems are adopting AI-powered lesion characterization tools that automate calcium scoring and stent apposition assessment. This virtualization of image interpretation is compressing training curves for complex PCI while reducing procedural variability across operator experience levels.
The EU MDR's heightened clinical evidence requirements for Class III implantable devices are extending development timelines and restructuring trial design priorities for bioabsorbable scaffold manufacturers. Premarket approval dossiers now demand extended follow-up data that exceeds historical bare-metal stent evidentiary thresholds, favoring well-capitalized sponsors with existing infrastructure. European notified body capacity constraints are forcing sequential rather than parallel market submissions, delaying commercial access for novel polymer platforms.
Aftermarket service unbundling is disrupting traditional capital equipment purchasing in US hospital systems. Cath lab administrators are separating imaging system hardware acquisition from multi-year service contracts, soliciting independent service organizations for preventive maintenance and probe refurbishment. This procurement fragmentation is most visible in the southeastern United States, where health system consolidation has centralized purchasing authority and intensified vendor price negotiation leverage.
Interventional Cardiology Market Segmentation
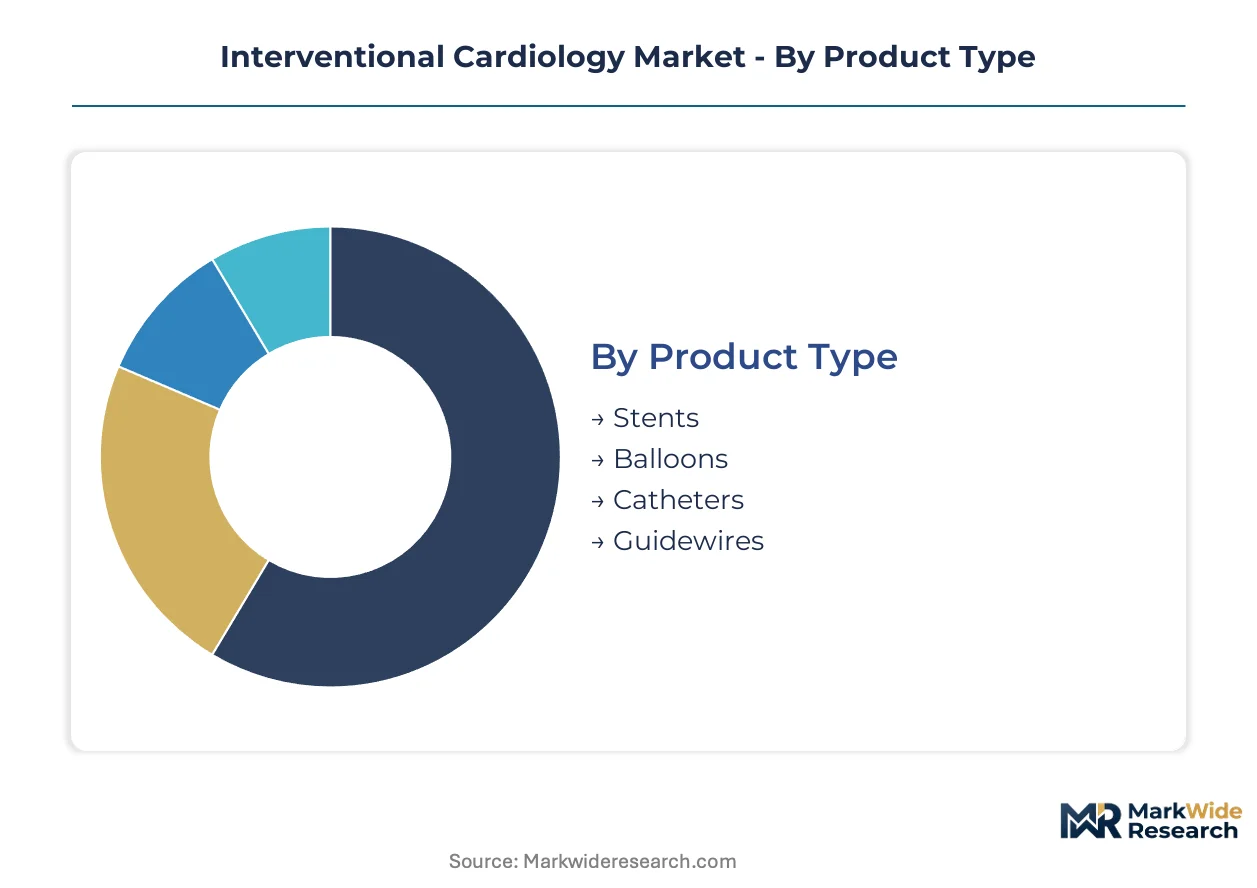
Segmentation in interventional cardiology reveals how procurement cycles, reimbursement pathways, and clinical complexity stratify across device categories and care settings. Understanding these divisions exposes where manufacturers capture recurring revenue versus one-time capital sales.
Product Type:
Stents turn over on multiyear implant cycles while balloons and guidewires deplete within single procedures, creating diverging inventory velocity profiles across hospital supply chains.
- Stents:Metallic or polymeric scaffolds deployed via balloon catheter to maintain vessel patency, with drug-eluting coatings suppressing neointimal hyperplasia. Demand concentrates in US integrated delivery networks where bundled payment contracts favor device standardization. FDA premarket approval timelines and EU MDR clinical evidence requirements extend replacement cycles for novel platforms.
- Balloons:Compliant, semi-compliant, and non-compliant inflation systems for lesion preparation and stent delivery. High-volume US ambulatory surgical centers drive consumption through same-day discharge protocols that maximize case throughput. Single-use economics favor disposable procurement over reprocessing despite environmental pressure.
- Catheters:Guiding, diagnostic, and specialty configurations delivering devices and contrast media.
- Guidewires:Steerable and hydrophilic-coated platforms for lesion crossing and device rail support.
Stents anchor the volume base while bioabsorbable platforms within this category gain share at the steepest rate.
Application:
Coronary procedures dominate installed base utilization, yet structural heart and peripheral interventions attract capital deployment as reimbursement expands treatable patient pools.
- Coronary Intervention:Percutaneous revascularization of epicardial vessels via stent implantation or balloon angioplasty. US hospital outpatient departments and physician-owned superlabs capture the majority of complex PCI volume as CMS site-of-service differentials shift economics away from inpatient settings. Operator radiation exposure limits constrain throughput regardless of device efficiency.
- Peripheral Intervention:Catheter-based treatment of iliac, femoropopliteal, and infrapopliteal arterial disease. India's below-the-knee penetration remains minimal outside tertiary urban centers, creating whitespace for limb salvage platforms adapted to cost-sensitive procurement. Chronic total occlusion specialist networks in Japan and South Korea standardize techniques and drive specialized guidewire demand.
- Structural Heart:Transcatheter valve repair and replacement, septal defect closure, and left atrial appendage occlusion.
- Endovenous Procedures:Catheter-based venous insufficiency treatment including radiofrequency and laser ablation.
Coronary intervention sustains the revenue foundation while structural heart applications expand most quickly as aging demographics broaden treatable cohorts.
Technology:
Cost tiers separate mature mechanical platforms from premium drug-eluting and imaging systems, with bioabsorbable scaffolds occupying an emerging price-performance position.
- Drug-Eluting:Stents incorporating antiproliferative agents in durable or biodegradable polymer matrices. US integrated cardiac service lines standardize on specific drug-polymer combinations to streamline inventory and reduce stent thrombosis variation. Patent cliffs on first-generation limus analogs intensify biosimilar competition.
- Bioabsorbable:Polylactic acid scaffolds providing temporary radial support with complete metabolic degradation. EU MDR post-market surveillance requirements and extended PMCF study obligations favor well-capitalized sponsors with existing trial infrastructure. Polymer science advances in controlled degradation timelines expand treatable lesion complexity.
- Mechanical:Bare-metal stents, cutting balloons, and atherectomy systems without pharmacological modification.
- Imaging:Intravascular ultrasound and optical coherence tomography consoles with disposable catheters.
Drug-eluting platforms anchor the volume base while bioabsorbable technology climbs the fastest as polymer integrity and degradation control improve.
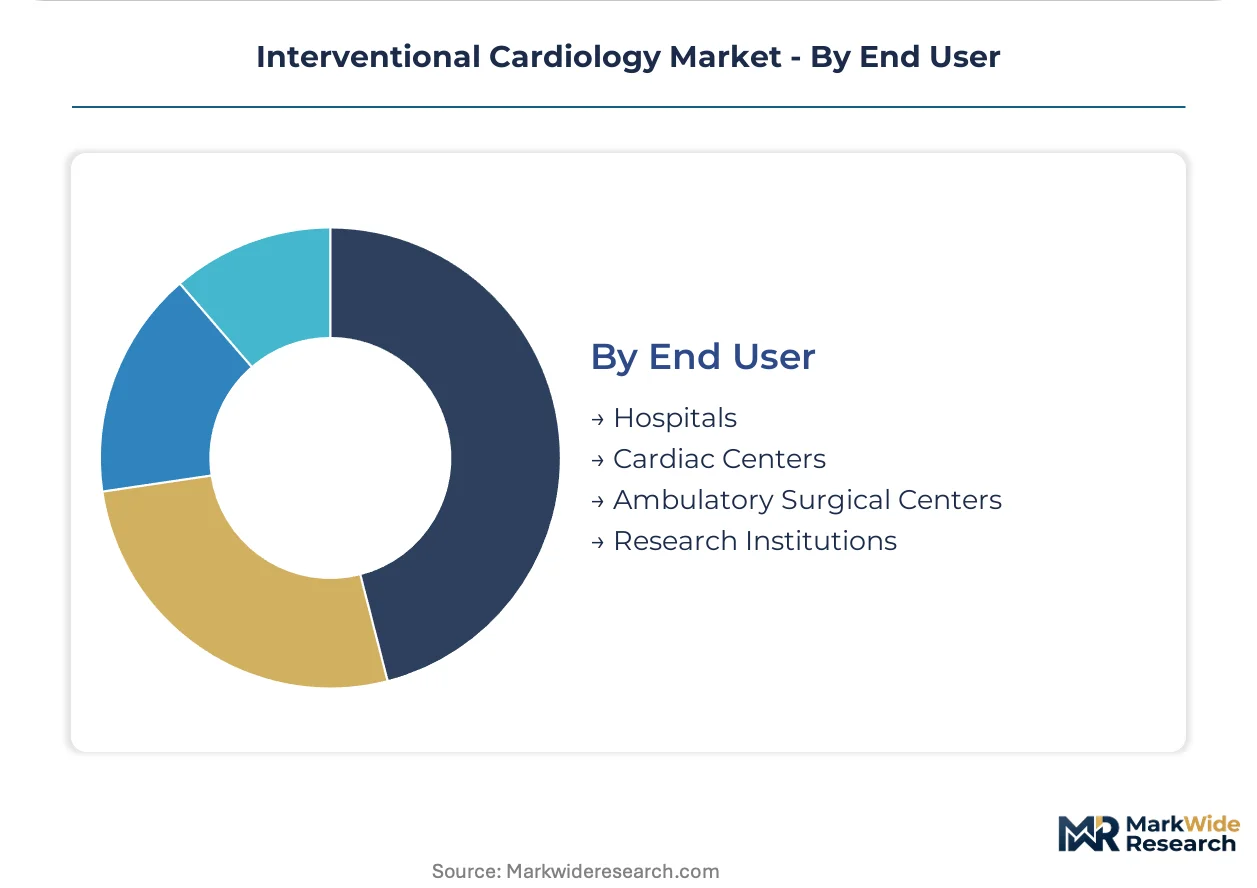
End User:
Customer type determines procurement authority concentration, with consolidated US health systems extracting price concessions unavailable to fragmented cardiac centers.
- Hospitals:Academic medical centers and community hospitals maintaining full-service cardiac catheterization laboratories. Southeastern US health system consolidation has centralized purchasing authority and intensified vendor negotiation leverage through unbundled service contracts. Legacy PACS integration gaps with next-generation imaging consoles delay deployment.
- Ambulatory Surgical Centers:Physician-owned facilities performing same-day catheter-based interventions. Medicare reimbursement shifts favoring outpatient settings accelerate capital deployment into superlabs across the United States. Leaner cath lab environments demand device form factors optimized for smaller footprints.
- Cardiac Centers:Dedicated cardiovascular specialty hospitals and institute networks.
- Research Institutions:Academic centers conducting clinical trials and device development studies.
Hospitals anchor the volume base while ambulatory surgical centers gain share at the steepest rate as site-of-service economics restructure procedure migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and Southeast Asia exhibit acute price elasticity for bare-metal stents and balloon catheters, while Japan and the United States absorb premium pricing for drug-eluting platforms and intravascular imaging systems with minimal volume sensitivity.
United States
Physician-owned superlabs in Florida and Texas are capturing complex PCI volume as Medicare site-of-service differentials widen. FDA premarket approval pathways for bioabsorbable scaffolds demand extended follow-up data that favors established sponsors with trial infrastructure. The southeastern health system consolidation around Atlanta and Charlotte has centralized cath lab purchasing authority and intensified vendor negotiation leverage.
Germany
Chronic total occlusion specialist networks in Munich and Heidelberg standardize complex lesion techniques that drive demand for specialized guidewire platforms. The EU MDR's expanded PMCF study obligations have extended approval timelines for novel polymer scaffolds seeking CE marking. Superelastic nitinol wire drawing capacity concentrates in the Ruhr industrial corridor, creating supply vulnerability for stent manufacturers dependent on consistent alloy properties.
Japan
METI reimbursement pathways for transcatheter edge-to-edge repair are expanding treatable structural heart pools beyond surgical ineligibility criteria. The PMDA's clinical evidence requirements for Class III implantable devices favor well-capitalized sponsors with existing trial infrastructure. Tokyo and Osaka anchor high-volume CTO clubs that standardize complex lesion techniques and drive specialized microcatheter demand.
India
Below-the-knee intervention penetration remains minimal outside tertiary urban centers in Maharashtra and Tamil Nadu, creating whitespace for limb salvage platforms adapted to cost-sensitive procurement. The CDSCO's medical device registration requirements are tightening quality standards for imported catheter systems. Hyderabad and Bengaluru are emerging as domestic manufacturing clusters for bare-metal stents targeting price-sensitive public hospital procurement.
South Korea
Proctoring programs in Seoul and Busan are standardizing complex PCI techniques that expand treatable lesion complexity ranges. The MFDS post-market surveillance requirements for drug-eluting stents align with EU MDR evidentiary thresholds, extending regulatory timelines for novel platforms. Asan Medical Center and Samsung Medical Center anchor high-volume cath lab networks that drive adoption of intravascular imaging systems.
Interventional Cardiology Market Competitive Environment
Integrated cath lab ecosystem providers and specialized imaging platform developers split the market along capital-intensity lines. The vendor base concentrates around three strategic archetypes: diversified medical technology conglomerates with full cardiac portfolios, pure-play interventional device specialists, and imaging system manufacturers extending into disposable catheters. Dominant competitive moves include unbundling of aftermarket service contracts from hardware sales and convergence of physiology measurement with intravascular imaging in single-catheter platforms.
Within the diversified conglomerate tier, Boston Scientific Corporation and Medtronic exemplify integrated cath lab ecosystem strategies that combine hardware, disposables, and remote monitoring capabilities. Abbott Laboratories occupies a position representing premium imaging specialization through optical coherence tomography platforms. These three entities anchor the competitive structure, with their respective strategic postures shaping procurement negotiations across US integrated delivery networks and European hospital systems.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Abbott Laboratories |
| Edwards Lifesciences Corporation |
| B. Braun SE |
| Terumo Corporation |
| Koninklijke Philips N.V. |
| BIOTRONIK SE & Co. KG |
| Cook Group |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in German nitinol wire drawing facilities is compressing alloy availability and forcing stent manufacturers into premium sourcing arrangements that transmit directly to device pricing. This utilization squeeze tightens margins across guidewire and scaffold production while amplifying negotiation leverage for Ruhr corridor metallurgical suppliers.
Pricing Analysis
Aftermarket service revenue tiers—spanning preventive maintenance contracts, probe refurbishment, and remote technical support—drive lifetime value capture for imaging system vendors. Device pricing stratifies across premium imaging consoles, standard physiology platforms, and economy bare-metal stent tiers differentiated by FDA approval pathway and polymer sophistication. Cost compression in economy stent categories intensifies as Indian domestic manufacturers scale bare-metal production for public procurement. Ambulatory surgical centers exhibit acute price sensitivity for capital equipment, while integrated US health systems extract volume concessions through centralized GPO contracts.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts catheter component flows and accelerates sourcing diversification into Mexico and Costa Rica. Superelastic nitinol wire drawing concentrates in Germany and Japan, with polylactic acid polymer feedstocks anchored in US and European chemical corridors. Single-source vulnerability pervades specialty guidewire core wire supply, where three metallurgical houses control superelastic alloy specifications. Distribution runs through diversified device distributors and direct hospital contracting channels, with regional warehousing in Singapore and Rotterdam serving Asia-Pacific and European cath lab networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through southeastern US health system consolidation around Atlanta and Charlotte, where centralized cath lab purchasing authority extracts unbundled service pricing and multi-year volume commitments from device vendors.
For Market Incumbents: Pre-empt service contract fragmentation by embedding field engineering teams directly within high-volume superlab accounts, locking in multi-year preventive maintenance relationships before independent service organizations capture probe refurbishment revenue. Accelerate backward integration into nitinol wire drawing capacity to neutralize Ruhr corridor supply vulnerability and stabilize alloy cost structures against metallurgical supplier pricing power.
For New Entrants and Emerging Players: Establish a beachhead in India's below-the-knee intervention segment, where CDSCO quality standard tightening creates entry barriers for unqualified competitors while public hospital procurement demands cost-adapted limb salvage platforms. Penetrate the ambulatory surgical center channel through compact imaging-physiology convergence devices that reduce cath lab footprint and inventory complexity for leaner superlab environments.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among imaging system vendors with installed IVUS and OCT fleets, where disposable catheter pull-through and service contract renewals generate predictable cash flow streams insulated from stent pricing volatility. Target acquisition profiles center on bioabsorbable scaffold specialists with EU MDR-compliant PMCF study infrastructure and polymer science IP. The signal to watch is FDA breakthrough device designation velocity for next-generation degradation-controlled platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Post-Market Surveillance Buildout | Extended PMCF study infrastructure satisfies CE marking requirements for Class III implantable scaffolds. |
| Integrated Physiology-Imaging Convergence | Single-catheter IVUS-iFR platforms reduce hardware footprint and disposable inventory for ambulatory surgical centers. |
| Ambulatory Surgical Center Partnership | Direct contracting with physician-owned superlabs captures Medicare site-of-service reimbursement shifts. |
| Bioabsorbable Polymer Science Investment | Controlled degradation timeline improvements expand treatable lesion complexity ranges for polylactic acid scaffolds. |
| Aftermarket Service Unbundling Defense | Embedded field engineering teams preempt independent service organization capture of probe refurbishment revenue. |
Study Parameters
Operator-level perspectives from interventional cardiologists, cath lab administrators, biomedical engineers, and GPO contracts managers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against FDA premarket approval filings, CMS Medicare reimbursement databases, EU MDR notified body guidance documents, and hospital procurement system records. Bottom-up demand modeling across stent, balloon, catheter, and guidewire categories triangulated with top-down market sizing from installed cath lab base estimates.
Scenario bracketing around CMS site-of-service reimbursement differentials, EU MDR approval timeline extensions, and nitinol alloy supply disruptions framed the forecast sensitivity envelope. Segmentation dimensions spanned product type, application, technology tier, and end-user setting, with regional adoption patterns calibrated against country-specific regulatory pathway velocities. CAGRs derived from procedure volume growth trajectories, device utilization per case, and pricing trajectory assumptions across the projection horizon.
Sensitivities concentrate around FDA breakthrough device designation velocity, EU notified body capacity constraints, and nickel-titanium alloy supply disruptions from German metallurgical facilities. Forecasts reflect documented assumptions regarding reimbursement stability, polymer science advancement timelines, and ambulatory surgical center migration rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Lower Limb Arterial Stents Market
Cardiovascular Devices
Global Pediatric Interventional Cardiology Market
Cardiovascular Devices
Global Embolotherapy Market
Cardiovascular Devices
Cardiac Assist Devices Market
Cardiovascular Devices
Tricuspid Valve Repair Market
Cardiovascular Devices
Abdominal Aortic Aneurysm (AAA) Repair Devices Market
Cardiovascular Devices
Bioresorbable Coronary Stents Market
Cardiovascular Devices
Middle East and Africa Heart Valve Repair and Replacement Market
Cardiovascular Devices
Cardiac Ablation Technologies Market
Cardiovascular Devices
Cardiovascular Surgical Devices Market
Cardiovascular Devices
Cardiovascular and Soft Tissue Repair Patches Market
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market
Cardiovascular Devices
Cardiac Cryoablation Device Market
Cardiovascular Devices
3D Cardiac Mapping Systems Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market
Cardiovascular Devices
Cardiovascular Needle Market