
 3D Printed Medical Devices Market | 2026-2036
3D Printed Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printed Medical Devices Market Analysis
The trained biomedical engineering workforce is collapsing across Western Europe and North America, forcing device manufacturers to automate qualification protocols or relocate technical centers. Materialise NV anchors regulatory software and surgical planning tools across European hospital networks. EOS GmbH dominates industrial metal powder-bed systems for titanium orthopedic implants. Stratasys competes in polymer-based surgical guides and anatomical models through its hospital-direct service model.
3D printed medical devices are patient-matched or batch-customized instruments, implants, and tissue scaffolds fabricated through layer-by-layer additive processes using biocompatible polymers, titanium alloys, or resorbable ceramics with pore architectures engineered between 100 and 600 micrometers for osseointegration. Their primary purpose is to eliminate geometric constraints of conventional machining and reduce operative time through anatomically conforming designs. Implants and surgical instruments command the deepest margin pools where patient-specific geometry justifies premium reimbursement. Fused Deposition Modeling and Selective Laser Sintering occupy divergent growth trajectories, with metals sintering expanding faster in orthopedic load-bearing applications while polymer extrusion sustains volume in dental and surgical guide production.
FDA 510(k) and De Novo pathways shape United States market access timelines for novel device geometries, while EMA Medical Device Regulation and ISO 13485 quality management standards govern European commercialization and post-market surveillance obligations. The EU MDR's tightened clinical evidence requirements for implantable devices is forcing manufacturers to consolidate technical documentation or exit certain product categories. Stakeholders must monitor evolving reimbursement decisions by CMS and analogous national health technology assessment bodies, as coverage determination for patient-specific implants remains the decisive gate for hospital procurement scale.
Market Dynamics
Patient-specific implant demand is compressing traditional five-to-seven-year product lifecycles into eighteen-month refresh cycles as hospital procurement teams prioritize anatomical conformance over brand loyalty.
Growth Catalysts
- FDA 510(k) pathway maturation:Streamlined premarket notification for additively manufactured titanium implants accelerates commercialization timelines for orthopedic device developers.
- Polymer surgical guide adoption:Ambulatory surgical centers in the United States integrate patient-matched cutting guides to reduce operative time and instrument sterilization burdens.
- Titanium powder-bed fusion:Load-bearing orthopedic applications expand as pore architectures between 100 and 600 micrometers demonstrate validated osseointegration performance.
Market Restraints
- Biomedical engineering talent scarcity:Western Europe and North America face collapsing trained workforce availability, forcing automation of qualification protocols.
- Titanium powder supply concentration:Industrial metal powder-bed systems depend on limited qualified suppliers for spherical Ti-6Al-4V feedstock.
- EU MDR clinical evidence requirements:Tightened post-market surveillance obligations for implantable devices force technical documentation consolidation or category exits.
Strategic Opportunities
- Resorbable ceramic scaffolds:Tissue engineering applications in craniomaxillofacial reconstruction represent underpenetrated white space beyond metallic implants.
- Hospital-direct service models:Point-of-care manufacturing partnerships bypass traditional distributor markups in academic medical centers.
- CMS reimbursement determination:Coverage expansion for patient-specific implants unlocks procurement scale in United States hospital systems.
Industry Challenges
- ISO 13485 quality management implementation:Small manufacturers struggle with documentation rigor for batch-customized production workflows.
- Biocompatibility certification timelines:Cytotoxicity and sensitization testing for novel polymer formulations extend time-to-market by twelve to eighteen months.
- Legacy PACS integration:Surgical planning software requires costly interoperability upgrades with hospital imaging infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printed Medical Devices Market |
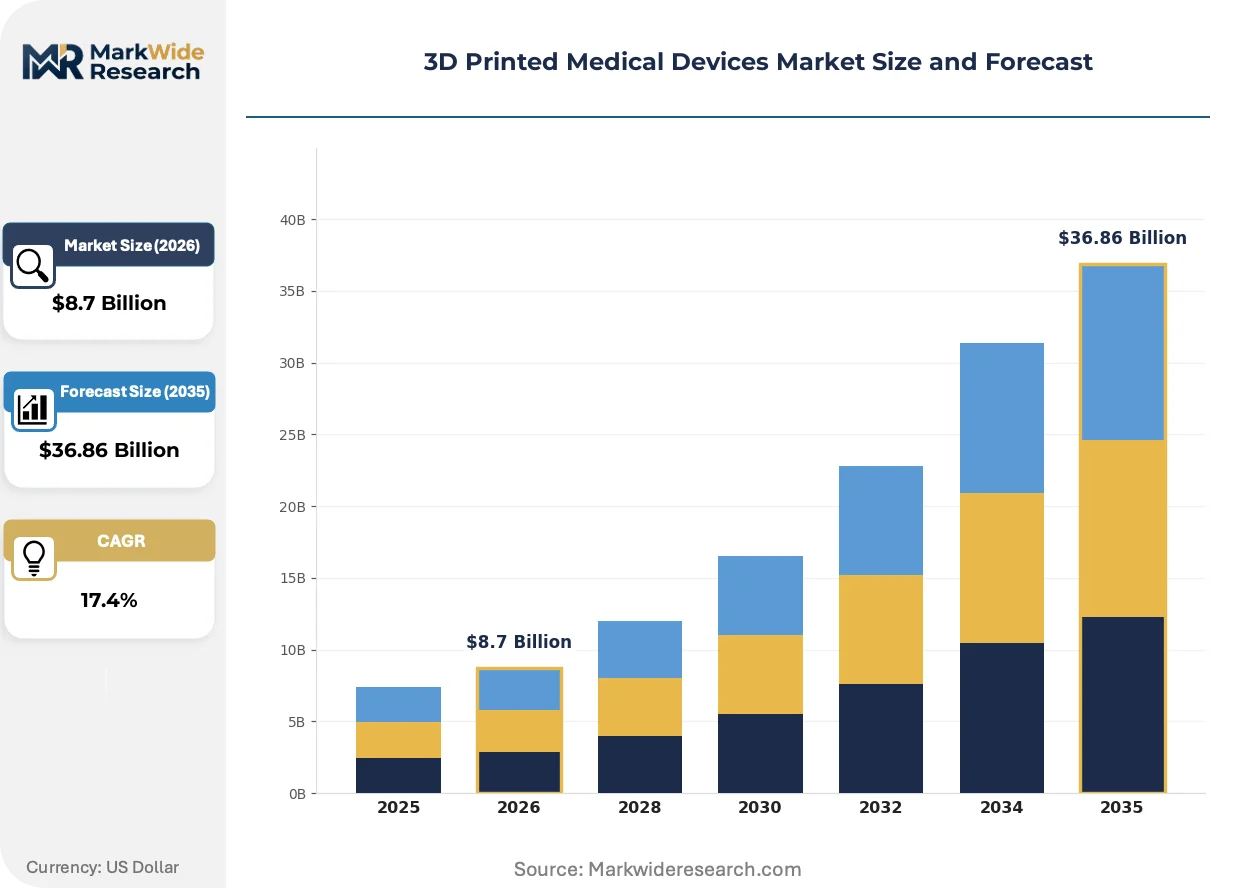
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $36.86 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Prosthetics, Surgical Instruments, Bioprinted Tissues End User: Hospitals, Clinics, Research Centers, Dental Practices Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing Material: Polymers, Metals, Ceramics, Composites |
| Companies Covered | EnvisionTEC, EOS GmbH, 3D Systems, LimaCorporate, Renishaw, Stratasys, Arcam AB, Formlabs, Materialise NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printed Medical Devices Market Emerging Trajectories
Digital surgical planning is dissolving the boundary between diagnostic imaging and manufacturing execution, enabling same-week turnaround from scan to sterilized implant.
Multi-material extrusion systems are bifurcating the surgical guide market into high-temperature engineering polymer tiers for autoclave compatibility versus disposable PLA alternatives. Academic medical centers in Boston and Cleveland adopt the premium tier for reusable instrument sets. This technology is compressing price differentiation between sterilization-durable and single-use categories.
The EU Medical Device Regulation's 2021 implementation deadline forced manufacturers to reclassify custom-made device exemptions. European notified bodies now demand clinical evaluation reports for patient-matched implants previously exempt from formal review. Small orthopedic specialists face consolidation pressure as technical documentation costs exceed product line revenue.
Hospital supply chain directors now require vendor-managed inventory for surgical guides rather than consignment models. Device manufacturers absorb sterilization and logistics costs to secure exclusive contracts with high-volume orthopedic service lines. This shift is most visible in United States metropolitan markets where integrated delivery networks centralize procurement authority.
3D Printed Medical Devices Market Segmentation
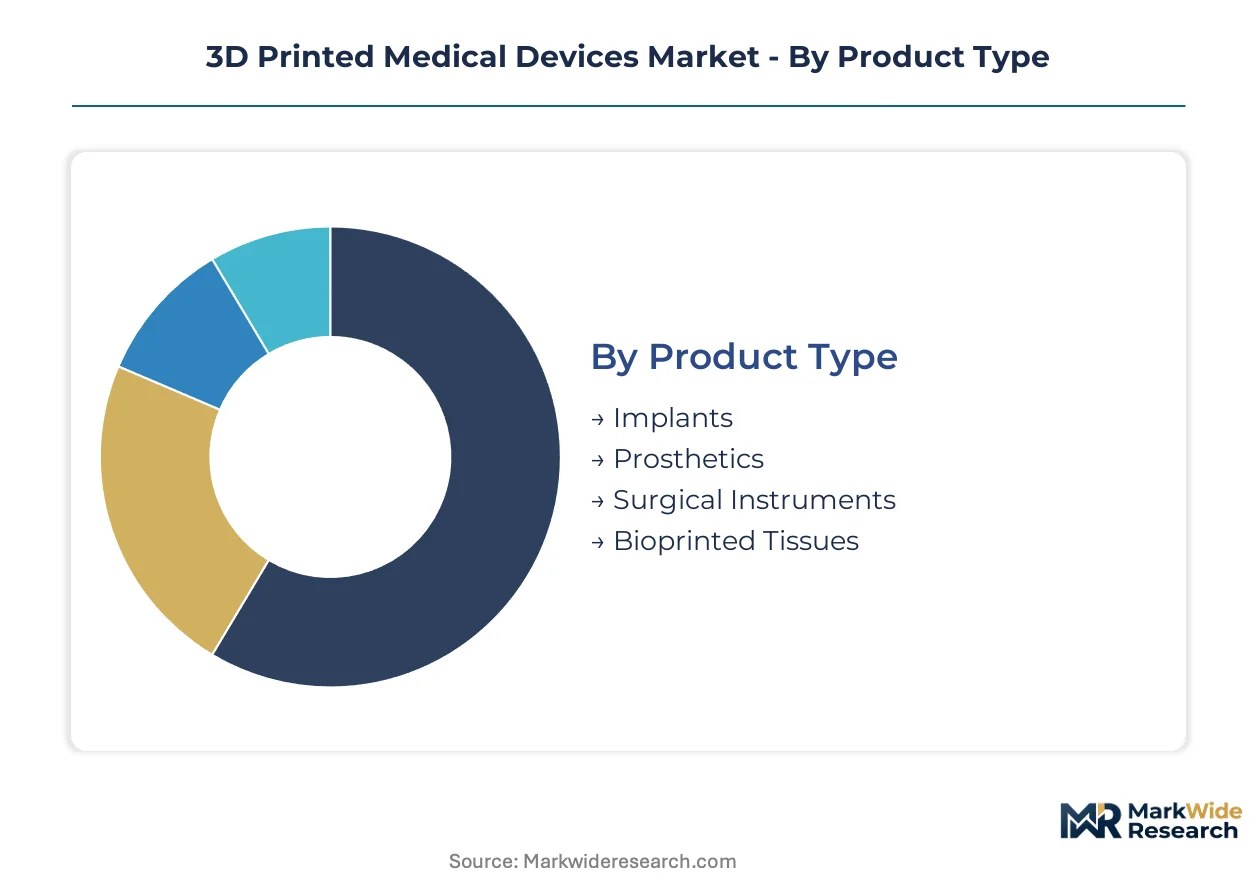
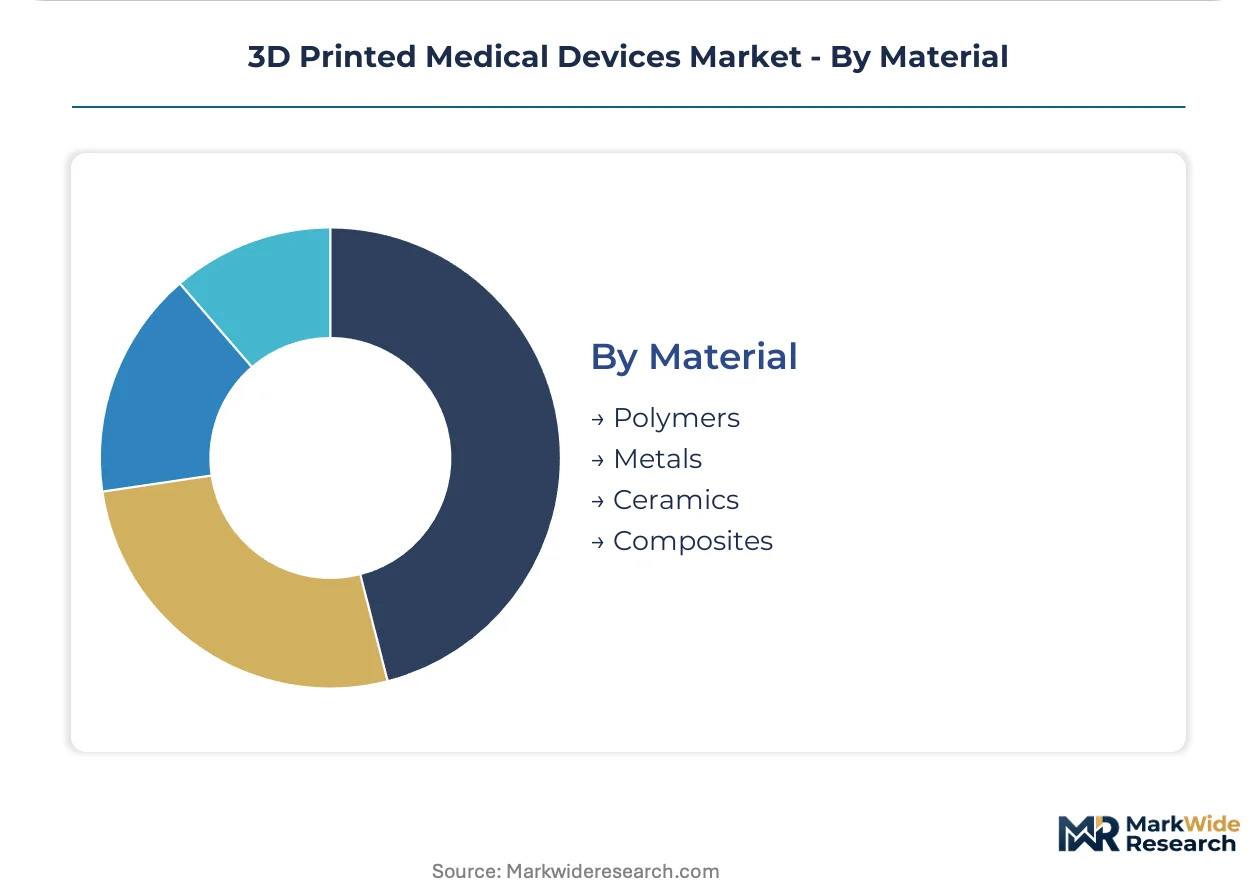
3D printed medical devices segment across four intersecting dimensions that determine reimbursement pathways, regulatory burden, and manufacturing economics. Product type governs FDA 510(k) versus De Novo classification, while material selection dictates sterilization protocols and biocompatibility testing scope.
Product Type:
FDA pathway differentiation separates high-margin implantables from lower-classification instruments and models, with bioprinted tissues occupying an emergent regulatory gray zone.
- Implants:Patient-matched titanium and cobalt-chrome constructs for orthopedic and craniomaxillofacial reconstruction carry Class II 510(k) or Class III PMA obligations. Academic medical centers in Boston and Cleveland drive procurement concentration as these institutions absorb premium pricing for anatomical conformance.
- Prosthetics:Socket interfaces and limb components fabricated from nylon-12 or carbon-fiber-reinforced polymers reduce weight and improve fit compared to thermoformed alternatives. Demand concentrates in United States veterans' health networks and German statutory insurance reimbursement pools.
- Surgical Instruments:Patient-specific cutting guides and drill templates streamline operative workflows in ambulatory surgical centers.
- Bioprinted Tissues:Collagen and alginate scaffolds for wound healing and drug screening occupy pre-commercial development phases.
Implants handle the majority of throughput; bioprinted tissues are gaining share fastest as tissue engineering protocols mature.
End User:
Procurement authority and sterilization infrastructure separate institutional buyers from smaller practice settings, with reimbursement determination varying sharply by care setting.
- Hospitals:Integrated delivery networks in United States metropolitan markets centralize implant procurement through value-analysis committees. These institutions mandate vendor-managed inventory and absorb sterilization costs to secure exclusive orthopedic service line contracts.
- Clinics:Outpatient surgical facilities prioritize polymer surgical guides for same-day procedures, selecting disposable PLA alternatives over autoclave-durable engineering polymers to eliminate reprocessing overhead.
- Research Centers:Academic institutions drive bioprinting protocol development and regulatory science for novel scaffold architectures.
- Dental Practices:Chairside milling and printing adoption concentrates in Germany, Switzerland, and United States cosmetic dentistry markets.
Hospitals command the deepest procurement volume; clinics are expanding most quickly as ambulatory migration accelerates.
Technology:
Resolution, material compatibility, and throughput speed segment additive platforms across clinical applications, with metals-capable systems requiring substantially higher capital investment.
- Selective Laser Sintering:Titanium and cobalt-chrome powder-bed fusion dominates load-bearing orthopedic applications. Pore architectures between 100 and 600 micrometers demonstrate validated osseointegration performance in FDA-cleared devices.
- Fused Deposition Modeling:Polymer extrusion systems sustain volume production in dental models and surgical guides through lower equipment costs and simplified facility requirements.
- Stereolithography:Resin-based photopolymerization delivers superior surface finish for dental aligner molds and anatomical models.
- Digital Light Processing:Mask-projection systems accelerate batch production of surgical planning models with reduced layer artifacts.
Selective Laser Sintering anchors high-value implant production; Digital Light Processing is climbing the fastest on dental throughput expansion.
Material:
Biocompatibility certification timelines and supply chain concentration differentiate material categories, with titanium feedstock dependence creating strategic vulnerability.
- Metals:Spherical Ti-6Al-4V and cobalt-chrome powders from limited qualified suppliers feed industrial powder-bed systems. FDA 510(k) clearance for additively manufactured titanium implants has matured, compressing commercialization timelines.
- Polymers:PEEK, nylon-12, and photopolymer resins dominate surgical guides and dental applications with twelve-to-eighteen-month biocompatibility testing cycles for novel formulations.
- Ceramics:Resorbable hydroxyapatite and tricalcium phosphate scaffolds target craniomaxillofacial reconstruction white space.
- Composites:Carbon-fiber-reinforced polymers and PEEK-ceramic blends occupy niche high-strength, radiolucent applications.
Metals generate the steepest margin pools; ceramics represent the most underpenetrated expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital procurement prioritizes patient-specific titanium implants for orthopedic reconstruction, while Germany emphasizes industrial powder-bed systems for export manufacturing. China concentrates on domestic dental guide production at lower price points. Consumption patterns diverge sharply by regulatory maturity and reimbursement infrastructure.
United States
FDA 510(k) pathway maturation accelerates commercialization for additively manufactured titanium implants. CMS coverage determination for patient-specific devices remains the decisive procurement gate for hospital systems. Academic medical centers in Boston and Cleveland anchor clinical adoption through exclusive vendor-managed inventory contracts.
Germany
German statutory insurance pools reimburse premium socket interfaces and limb components for prosthetic applications. EU MDR implementation forces manufacturers to consolidate technical documentation for implantable devices. Industrial clusters in Bavaria and North Rhine-Westphalia host EOS GmbH and concentrated metal powder-bed production capacity.
China
Domestic dental practices drive volume demand for chairside polymer guides and aligner molds. NMPA regulatory frameworks for additively manufactured medical devices continue evolving toward alignment with international standards. Yangtze River Delta manufacturing zones specialize in cost-competitive photopolymer resin systems for export markets.
Japan
PMDA quality management requirements shape commercialization timelines for novel implant geometries. METI industrial policy supports domestic titanium powder supply chain resilience. Kansai region academic hospitals pioneer craniomaxillofacial reconstruction applications with resorbable ceramic scaffolds.
Switzerland
Swissmedic oversight maintains stringent clinical evidence requirements for Class III implantable devices. Cosmetic dentistry markets in Zurich and Geneva sustain premium stereolithography throughput for dental aligner production. Precision manufacturing heritage supports high-margin surgical instrument specialization.
3D Printed Medical Devices Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with powder-bed metal system providers commanding premium positioning against polymer extrusion competitors. The vendor base separates into three strategic archetypes: industrial hardware OEMs with captive materials supply, software-centric surgical planning platforms, and hospital-direct service operators. Consolidation pressure intensifies as EU MDR documentation costs force smaller orthopedic specialists toward acquisition or exit. Dominant competitive moves include backward integration into spherical titanium feedstock production and exclusive point-of-care manufacturing partnerships with academic medical centers.
Within the integrated hardware tier, EOS GmbH exemplifies European industrial metal system leadership, while Materialise NV anchors regulatory software and surgical planning tools across hospital networks. Stratasys occupies a position within the hospital-direct polymer service model, competing on ambulatory surgical center penetration. These three entities represent divergent strategic vectors: captive powder supply, software-enabled surgical workflow integration, and distributed manufacturing logistics.
| Leading Market Players |
|---|
| EnvisionTEC |
| EOS GmbH |
| 3D Systems |
| LimaCorporate |
| Renishaw |
| Stratasys |
| Arcam AB |
| Formlabs |
| Materialise NV |
| Others |
Supply Flow & Price Mechanics
Capital intensity in industrial powder-bed systems creates scale thresholds that concentrate titanium feedstock purchasing power among German and Belgian equipment operators, compressing margin structures for smaller orthopedic specialists while elevating price floors for patient-matched implants. Hospital procurement teams exploit this concentration through vendor-managed inventory contracts that shift sterilization and logistics costs upstream.
Pricing Analysis
Long-term offtake agreements dominate titanium powder procurement, with spherical Ti-6Al-4V feedstock contracted on eighteen-to-twenty-four-month cycles to qualified suppliers. Price differentiation hinges on FDA 510(k) clearance tier and pore architecture certification grade, with validated osseointegration performance commanding substantial premiums over unvalidated geometries. Cost compression in polymer surgical guides is intensifying because ambulatory surgical centers prioritize disposable PLA alternatives over autoclave-durable engineering polymers. Academic medical centers in Boston and Cleveland exhibit lowest price sensitivity, absorbing premium positioning for anatomical conformance, while outpatient clinics drive pricing softness through volume aggregation of single-use instruments.
Supply Chain Analysis
Inventory lead times for qualified titanium powder extend substantially beyond polymer resin cycles, tethering orthopedic implant production to German, Belgian, and limited Japanese spherical feedstock suppliers. The supply chain draws from concentrated rare earth processing for powder atomization equipment, photopolymer resin synthesis in Yangtze River Delta zones, and precision nozzle manufacturing in Switzerland. Single-source vulnerability permeates the qualified Ti-6Al-4V supplier base, where FDA material master file documentation creates switching friction. Distribution runs through hospital-direct service partnerships for implants and surgical guides, bypassing traditional distributor markups in integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory moat story, where FDA 510(k) pathway maturity and EU MDR technical documentation requirements create entrenched switching costs that protect incumbent positioning.
For Market Incumbents: Shield market position by accelerating backward integration into spherical titanium feedstock production to neutralize powder supply concentration risk. Deepen hospital-direct service partnerships with academic medical centers in Cleveland and Boston to lock in exclusive vendor-managed inventory contracts before emerging polymer specialists achieve ISO 13485 certification scale.
For New Entrants and Emerging Players: Point-of-care manufacturing software gaps in ambulatory surgical centers present immediate service-layer entry points where incumbent hardware OEMs under-serve workflow integration needs. Target craniomaxillofacial reconstruction applications with resorbable ceramic scaffolds, the most underpenetrated white space beyond metallic implants. Pursue GPO contract penetration through disposable PLA surgical guide offerings that eliminate reprocessing overhead for outpatient facilities.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-centric surgical planning platforms with regulatory workflow integration over capital-intensive hardware manufacturers facing titanium powder supply volatility. Long-term viability across the projection horizon rests on EU MDR technical documentation consolidation plays, where documentation cost burdens force smaller orthopedic specialists toward acquisition. Monitor CMS national coverage determination signals for patient-specific implants as the decisive inflection indicator for United States hospital procurement scale.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined premarket notification compresses commercialization timelines for titanium orthopedic developers. |
| CE Marking Pathway Investment | EU MDR clinical evidence requirements force technical documentation consolidation or category exit decisions. |
| Hospital System Partnership | Exclusive vendor-managed inventory contracts with academic medical centers lock in orthopedic service line procurement. |
| Software Companion Development | Digital surgical planning integration dissolves boundaries between diagnostic imaging and manufacturing execution. |
| Reimbursement Strategy | CMS coverage determination for patient-specific implants unlocks procurement scale in United States hospital systems. |
Methodological Framework
The analysis maps titanium orthopedic implants, polymer surgical guides, resorbable ceramic scaffolds, and bioprinted tissue constructs, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and FDA regulatory consultants. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EMA MDR submission records, CMS Medicare reimbursement filings, and hospital procurement contract disclosures. Bottom-up volume modeling and top-down market sizing triangulated across segmentation dimensions.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon, with analytical frameworks modeling product type, material category, end-user setting, and technology platform dimensions. CAGRs derived from installed base growth, replacement cycle compression, and reimbursement pathway maturation. Forecast inputs incorporated titanium powder supply elasticity, EU MDR documentation cost trajectories, and CMS coverage determination probabilities without year-specific anchoring.
Material uncertainties — regulatory pathway delays, titanium powder supply disruptions, and reimbursement determination reversals — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Canada Contraceptive Devices Market
Medical Devices
United States Implantable Medical Devices Market
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
Italy Minimally Invasive Surgery Devices Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
Occlusion Balloon Catheter Market
Medical Devices
Leadless Cardiac Pacemaker Market
Medical Devices
Global Occlusion Devices Market
Medical Devices
Global on-Body Injectors Market
Medical Devices
Pipette Controllers Market
Medical Devices
Global Surgical Tourniquets Market
Medical Devices
United Kingdom Ultrasound Devices Market
Medical Devices
Volumetric Arc Therapy Market
Medical Devices
Digital Medical Thermometers Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
Medical Devices Vigilance Market