
 Biodegradable Stents Market | 2026-2036
Biodegradable Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Stents Market Analysis
Modular stent-platform bundling is shifting buyer choice toward configurable delivery systems that pair biodegradable scaffolds with specialized catheters. Abbott Laboratories leverages its integrated vascular portfolio to sustain premium positioning across coronary and peripheral segments. Boston Scientific Corporation anchors North American hospital contracts through dedicated cardiac center partnerships. Medtronic plc competes by extending its endovascular infrastructure into ambulatory surgical channels.
Biodegradable stents are implantable vascular scaffolds engineered from absorbable polymers or corrodible metals such as magnesium or iron, designed to provide temporary luminal support before complete resorption within 12-24 months. Coronary stents dominate current revenue as interventional cardiologists prioritize complete restoration of vessel vasomotion, while peripheral stents represent the fastest-expanding application due to rising diabetic limb-salvage procedures. Polymer-based materials, notably poly-L-lactic acid formulations, occupy the largest material share, though metal-based alternatives are gaining traction where radial strength requirements exceed polymer capabilities.
FDA pre-market approval pathways and the EU Medical Device Regulation impose stringent biocompatibility and degradation-kinetic standards that shape R&D investment priorities and timeline-to-market for manufacturers. Japan's PMDA maintains distinct clinical evidence requirements for absorbable metal scaffolds, creating a dual-track regulatory environment that favors companies with parallel submission capabilities across jurisdictions. Stakeholders must monitor evolving degradation-rate specifications as regulatory bodies recalibrate safety thresholds based on long-term patient outcome data.
Market Dynamics
The EU Medical Device Regulation's recalibration of biocompatibility thresholds is compressing clinical trial timelines and forcing manufacturers to front-load degradation-kinetic evidence before market authorization.
Growth Catalysts
- Polymer formulation advances:Poly-L-lactic acid variants with tunable resorption rates are expanding treatable lesion complexity in coronary interventions.
- Japan's PMDA parallel-track framework:Absorbable metal scaffold approvals are accelerating through distinct clinical evidence pathways that reward localized manufacturing investment.
- Diabetic limb-salvage protocols:Peripheral artery disease programs in cardiac centers are creating dedicated reimbursement codes for biodegradable below-the-knee scaffolds.
Market Restraints
- Magnesium alloy supply concentration:Primary smelter capacity clusters in China, creating input vulnerability for metal-based stent producers.
- Degradation rate variability:Patient-specific metabolic conditions produce unpredictable scaffold resorption timelines that complicate long-term outcome studies.
- Balloon-expandable platform substitution:Drug-eluting metal stents with thinner strut profiles retain cost advantages in price-sensitive hospital purchasing.
Strategic Opportunities
- Pediatric congenital heart defect repair:Growing valve and vessel applications for absorbable scaffolds in pediatric cardiac centers lack established device alternatives.
- Ambulatory surgical center catheterization labs:Same-day discharge protocols are creating demand for simplified delivery systems with reduced antiplatelet dependency.
- EU Green Deal medical device circularity mandates:Bioresorbable implants align with emerging sustainability procurement criteria for hospital supply chains.
Industry Challenges
- Biomaterial characterization expertise scarcity:Interdisciplinary teams combining polymer chemistry and vascular biology remain difficult to assemble at scale.
- ISO 10993 extended testing timelines:Degradation product toxicology studies add 18-24 months to pre-market certification compared with permanent implants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Stents Market |
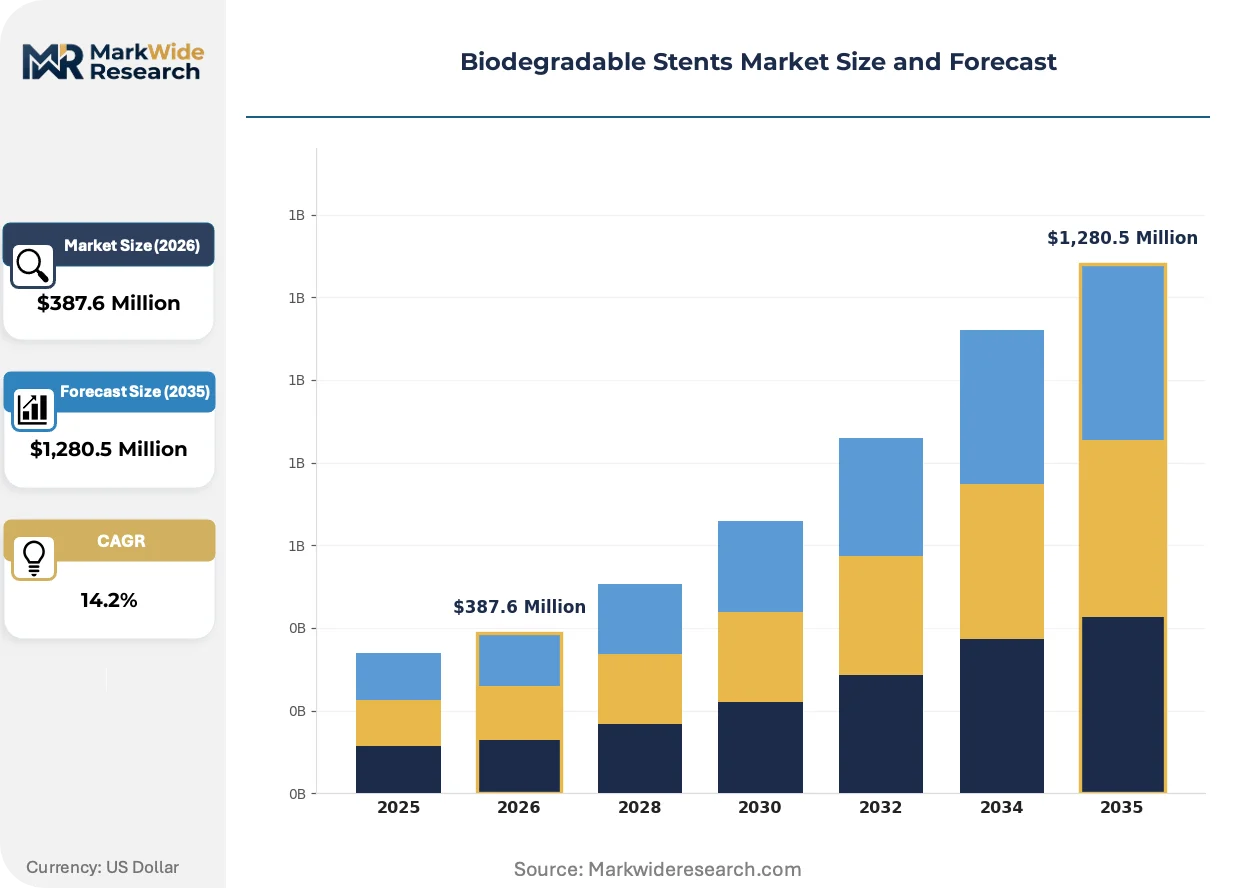
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coronary Stents, Peripheral Stents, Urological Stents, Gastrointestinal Stents Material: Polymer-based, Metal-based, Composite Materials, Natural Polymers End User: Hospitals, Cardiac Centers, Ambulatory Surgical Centers, Specialty Clinics Delivery Mode: Transluminal, Endoscopic, Laparoscopic, Percutaneous |
| Companies Covered | Abbott Laboratories, Biotronik SE & Co. KG, Boston Scientific Corporation, Medtronic plc, Terumo Corporation, Kyoto Medical Planning Co., Ltd., REVA Medical, Elixir Medical Corporation, MicroPort Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Stents Market Emerging Trajectories
Modular platform architectures are displacing fixed-configuration delivery systems as interventional cardiologists demand procedure-specific customization without inventory proliferation.
Magnesium-alloy scaffold technology is consolidating around proprietary alloy compositions that modulate corrosion rates through rare-earth element doping. Cardiac centers in Germany and Japan are adopting these platforms for calcified lesion subsets where polymer radial strength proves inadequate. The technology is consolidating supplier ecosystems by tying stent procurement to captive catheter compatibility requirements.
The EU Medical Device Regulation's post-market surveillance obligations are mandating real-world evidence registries that track patient outcomes through complete scaffold resorption. Manufacturers must now fund 5-10 year follow-up studies as a condition of CE marking renewal. Peripheral stent segments face the steepest compliance burden due to limited historical long-term data.
Hospital purchasing consortiums are unbundling stent-procedure reimbursement from device acquisition costs, forcing manufacturers to demonstrate total episode-of-care savings. Cardiac centers in Japan are piloting risk-sharing arrangements where payment thresholds tie to target lesion revascularization rates at 12 months. This restructuring is most advanced in metropolitan Tokyo and Osaka health systems with integrated electronic health record infrastructure.
Biodegradable Stents Market Segmentation
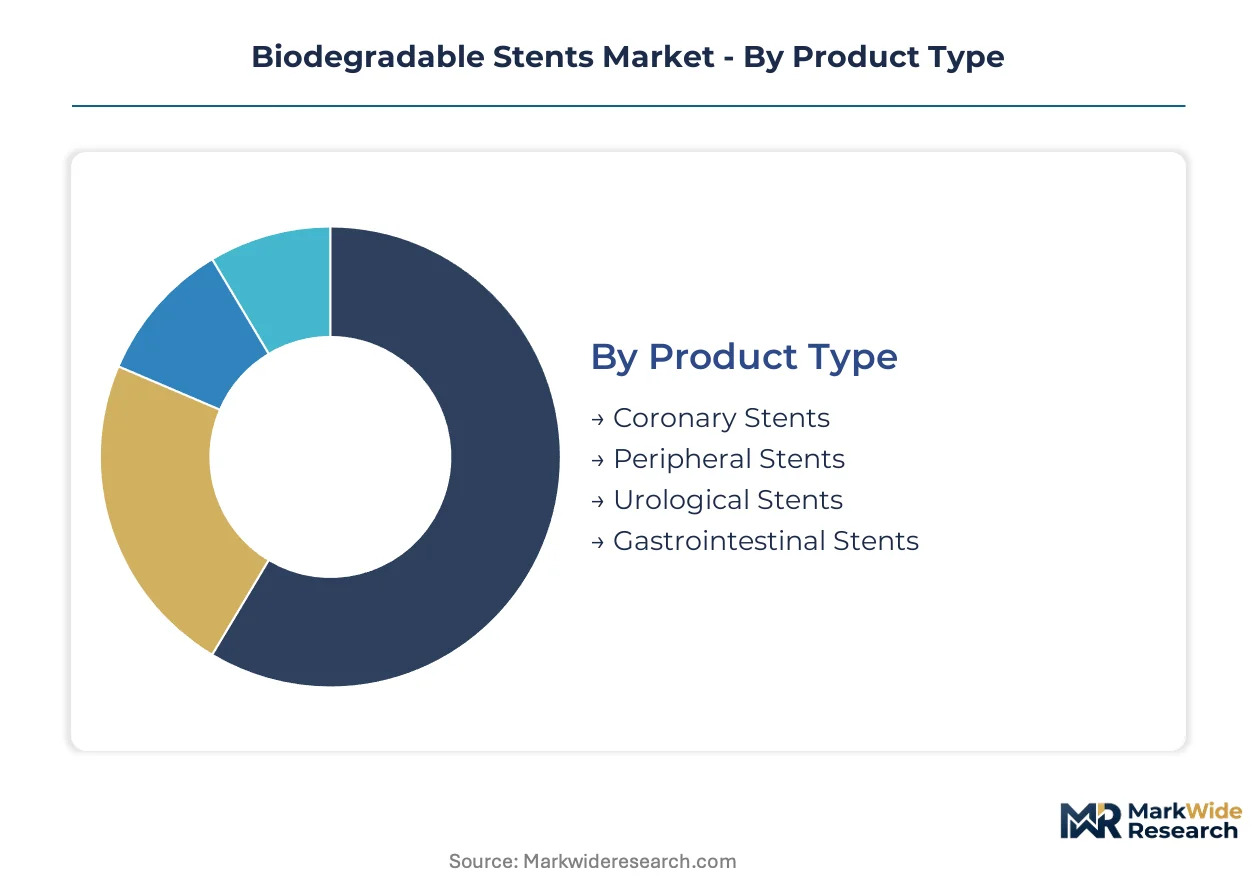
Segmentation in biodegradable stents reveals how clinical requirements, material science capabilities, and care delivery settings intersect to shape procurement decisions. Each dimension carries distinct regulatory, reimbursement, and technical specifications that manufacturers must navigate simultaneously.
Product Type:
Procedure complexity and lesion location drive fundamentally different scaffold engineering requirements across vascular and non-vascular applications.
- Coronary Stents:Poly-L-lactic acid scaffolds with 150-micron strut thickness dominate this segment, designed to restore vessel vasomotion after 12-18 months of luminal support. Demand clusters in German cardiac centers where reimbursement frameworks now explicitly cover bioresorbable coronary interventions under EU Medical Device Regulation pathways.
- Peripheral Stents:Magnesium-alloy platforms with enhanced radial strength address calcified femoropopliteal lesions and below-the-knee diabetic limb-salvage procedures. Japanese PMDA approvals for absorbable metal scaffolds have accelerated clinical adoption in Tokyo and Osaka metropolitan health systems.
- Urological Stents:Polyglycolic acid constructs provide temporary ureteral patency with reduced encrustation risk compared to permanent metal alternatives.
- Gastrointestinal Stents:Biodegradable esophageal and colonic scaffolds address malignant stricture palliation where permanent stent removal carries procedural risk.
Coronary stents lead volumes today; peripheral stents are gaining share fastest.
Material:
Degradation kinetics and mechanical property requirements split procurement between polymer chemistries and corrodible metallurgies.
- Polymer-based:Poly-L-lactic acid and polyglycolic acid formulations with tunable resorption rates constitute the largest installed base, particularly in coronary applications where radial strength demands remain moderate. FDA pre-market approval pathways have established extensive degradation-kinetic databases for these materials.
- Metal-based:Magnesium alloys doped with rare-earth elements modulate corrosion rates to match vascular healing timelines. Supply concentration in Chinese primary smelters creates input vulnerability for Western manufacturers despite superior performance in calcified lesions.
- Composite Materials:Hybrid polymer-metal laminates combine the processability of polymers with localized strength enhancement from metallic filaments.
- Natural Polymers:Collagen and chitosan scaffolds serve niche applications in pediatric congenital heart defect repair where synthetic material biocompatibility concerns persist.
Polymer-based materials dominate current procurement; metal-based alternatives show the steepest expansion trajectory as alloy engineering matures.
End User:
Capital intensity and procedure volume thresholds determine which care settings can support biodegradable stent programs.
- Hospitals:Academic medical centers with integrated catheterization laboratories and cardiac surgery backup maintain the deepest biodegradable stent inventories across all product categories. These institutions absorb the extended ISO 10993 testing timelines and real-world evidence registry obligations mandated by EU Medical Device Regulation post-market surveillance.
- Cardiac Centers:Dedicated interventional cardiology facilities in Germany and Japan concentrate coronary and peripheral biodegradable scaffold volumes through specialized physician training and streamlined reimbursement pathways.
- Ambulatory Surgical Centers:Same-day discharge protocols are creating demand for simplified delivery systems with reduced antiplatelet dependency, though capital equipment requirements limit penetration.
- Specialty Clinics:Urology and gastroenterology practices deploy biodegradable stents for outpatient stricture management where removal procedures would otherwise require hospital admission.
Hospitals capture the majority of biodegradable stent procurement value; cardiac centers are expanding their share fastest through procedure specialization.
Delivery Mode:
Access route selection constrains scaffold design parameters including flexibility, profile, and deployment mechanism compatibility.
- Transluminal:Balloon-expandable and self-expanding delivery systems for vascular applications represent the predominant deployment method, with catheter-stent platform bundling increasingly standard in coronary interventions.
- Endoscopic:Gastrointestinal and urological biodegradable stents deploy through flexible endoscope working channels, requiring scaffold compression and expansion characteristics distinct from vascular platforms.
- Laparoscopic:Surgical stent placement for complex anatomical configurations or failed endoscopic approaches utilizes biodegradable scaffolds in hybrid operating room environments.
- Percutaneous:Image-guided access for biliary and urinary applications enables minimally invasive biodegradable stent deployment without endoscopic or surgical visualization.
Transluminal delivery commands the largest procedure volume; endoscopic deployment is climbing the fastest as gastrointestinal applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biodegradable stent technology emerged from collaborative research between German interventional cardiology pioneers and Japanese materials scientists during the early 2000s, establishing dual innovation hubs that continue to shape clinical adoption patterns and regulatory frameworks worldwide.
Germany
Cardiac centers in Munich and Heidelberg drive polymer-based coronary scaffold demand as statutory health insurance expands coverage for bioresorbable interventions. The EU Medical Device Regulation's biocompatibility thresholds compress approval timelines, forcing manufacturers to front-load degradation-kinetic evidence. The Baden-Württemberg medical technology cluster around Stuttgart concentrates catheter-stent platform bundling expertise.
Japan
Tokyo and Osaka metropolitan health systems anchor regional absorbable metal scaffold adoption through PMDA's parallel-track approval framework. Kyoto Medical Planning and Terumo Corporation localize magnesium-alloy research programs, reducing import dependency. The Kansai region's integrated electronic health record infrastructure enables risk-sharing reimbursement pilots tied to target lesion revascularization rates.
United States
Cleveland Clinic and Mayo Clinic cardiac centers maintain deep biodegradable stent inventories across coronary and peripheral segments. FDA pre-market approval pathways demand extensive degradation-kinetic databases that extend certification timelines. The Minneapolis-St. Paul medical device corridor concentrates endovascular infrastructure expansion into ambulatory surgical channels.
China
Shanghai and Beijing tertiary hospitals pilot magnesium-alloy platforms for calcified lesion subsets where polymer radial strength proves inadequate. The national pharmaceutical regulator recalibrates safety thresholds based on long-term patient outcome data from domestic clinical trials. The Yangtze River Delta medical technology manufacturing base faces input vulnerability from domestic primary smelter capacity concentration.
Switzerland
Zurich and Geneva academic medical centers absorb extended ISO 10993 testing timelines for pediatric congenital heart defect applications. Swissmedic maintains distinct clinical evidence requirements that favor manufacturers with parallel submission capabilities across European jurisdictions. The Basel pharmaceutical-device convergence cluster supports interdisciplinary teams combining polymer chemistry and vascular biology.
Biodegradable Stents Market Vendor Landscape
Premium-margin players sit above commodity-margin players across integrated vascular portfolio depth and catheter-stent platform bundling capabilities. The vendor base stratifies into three tiers: diversified multinationals with captive catheter compatibility ecosystems, regional specialists with localized alloy research programs, and emerging entrants targeting pediatric or peripheral niche segments. Dominant competitive moves include strategic partnerships between scaffold manufacturers and catheter producers, plus backward integration into proprietary magnesium alloy supply.
Within the diversified multinational tier, Abbott Laboratories, Boston Scientific Corporation, and Medtronic plc exemplify integrated vascular portfolio positioning. Abbott's structure as a U.S.-based corporation anchors premium positioning across coronary segments. Boston Scientific's corporate form enables North American hospital contract concentration. Medtronic's plc designation supports endovascular infrastructure extension into ambulatory channels. These three entities represent the dominant archetype competing through bundled delivery system configurability rather than standalone scaffold pricing.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Biotronik SE & Co. KG |
| Boston Scientific Corporation |
| Medtronic plc |
| Terumo Corporation |
| Kyoto Medical Planning Co., Ltd. |
| REVA Medical |
| Elixir Medical Corporation |
| MicroPort Scientific Corporation |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal medical device circularity mandates gate qualified supply access and premium-tier pricing power for biodegradable stent manufacturers, as hospitals prioritize procurement from vendors with demonstrated sustainability credentials and complete degradation-kinetic documentation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by FDA pre-market approval tier and catheter-stent platform bundling depth. Premium tiers command positioning through proprietary magnesium-alloy compositions and integrated delivery system compatibility, while economy tiers face cost compression from balloon-expandable drug-eluting metal stent substitution. Academic medical centers with integrated catheterization laboratories exhibit lowest price sensitivity; ambulatory surgical centers with same-day discharge protocols drive hardest bargain negotiations.
Supply Chain Analysis
Dual-sourcing requirements from cardiac centers in Germany and Japan mandate multi-supplier qualification for magnesium alloy feedstock, forcing manufacturers to qualify secondary smelters beyond primary Chinese capacity. Raw material dependencies center on poly-L-lactic acid resin formulations, rare-earth element dopants, and specialized catheter balloon membranes. Single-source vulnerability concentrates in Yangtze River Delta primary smelter capacity. Distribution runs through hospital purchasing consortiums and GPO contracts with integrated electronic health record infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with the EU Medical Device Regulation's post-market surveillance obligations mandating real-world evidence registries that extend manufacturer commitment timelines and deepen competitive moats for prepared participants.
For Market Incumbents: Acquire proprietary magnesium alloy supply through backward integration into rare-earth element doping capabilities, insulating against Chinese smelter concentration risk while securing degradation-rate modulation intellectual property. Expand catheter-stent platform bundling through dedicated cardiac center partnerships in Tokyo and Osaka metropolitan health systems, defending against modular platform substitution threats from integrated vascular portfolio competitors. For New Entrants and Emerging Players: Catheter manufacturers with captive delivery system expertise represent the most viable channel partnership avenue for scaffold technology licensing. Pediatric congenital heart defect applications offer the most penetrable white-space target, lacking established device alternatives and carrying reduced regulatory evidence burdens compared to coronary segments. Pursue risk-sharing reimbursement pilots tied to target lesion revascularization rates as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with localized alloy research programs because PMDA's parallel-track approval framework rewards manufacturing investment with accelerated market access. The 5-10 year viability window favors targets with demonstrated ISO 10993 extended testing completion and active CE marking renewal trajectories. Watch for degradation-rate specification recalibration by regulatory bodies based on long-term patient outcome data as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU Medical Device Regulation compliance enables cardiac center procurement across German statutory health insurance frameworks. |
| Hospital System Partnership | Integrated electronic health record infrastructure in Kansai region supports risk-sharing reimbursement pilot participation. |
| Backward Integration into Alloy Supply | Rare-earth element doping capabilities reduce dependence on Chinese primary smelter concentration. |
| Software Companion Development | Real-world evidence registry platforms satisfy post-market surveillance obligations for CE marking renewal. |
| Reimbursement Strategy | Dedicated reimbursement codes for diabetic limb-salvage protocols unlock peripheral stent segment expansion. |
Methodological Framework
Bottom-up cardiac center and ambulatory surgical center modeling reconciled against top-down magnesium alloy and polymer resin supply tracking forms the analytical core. Primary interviews with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA pre-market approval filings, EMA CE marking databases, PMDA submission records, and hospital procurement databases. Triangulation across stakeholder perspectives and regulatory documentation ensures segmentation integrity.
Input-output matrices map biodegradable scaffold production capacity against procedure volume projections across coronary, peripheral, urological, and gastrointestinal applications throughout the forecast period. Segmentation dimensions include product type, material chemistry, end-user facility category, and delivery mode deployment method. CAGRs derive from procedure volume elasticity to reimbursement code expansion and degradation-kinetic evidence accumulation timelines. Forecast inputs incorporate EU Medical Device Regulation compliance cost trajectories and PMDA parallel-track approval velocity differentials.
Revisions become necessary when regulatory bodies recalibrate safety thresholds based on long-term patient outcome data, when magnesium alloy supply disruptions alter input cost structures, or when hospital purchasing consortiums unbundle stent-procedure reimbursement from device acquisition costs. Deviation in any trigger would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Brain Base Knife Package Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
Aneurysm Coiling & Embolization Devices Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Russia Viscosupplementation Market
Medical Devices
Pannus Retraction Device Market
Medical Devices
US Clear Aligners Market
Medical Devices
United States Small Bone and Joint Devices Market
Medical Devices
Transcranial Doppler Ultrasounds System Market
Medical Devices
Non-Rebreathing Oxygen Mask Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Medical Injection Molding Machine Market
Medical Devices
Anti-Fatigue Lenses Market
Medical Devices
Micro Balloon Catheter Market