
 Global Hernia Mesh Devices Market | 2026-2036
Global Hernia Mesh Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hernia Mesh Devices Market Foresight
Multi-source procurement of polypropylene and biosynthetic polymers is broadening supply options for mesh manufacturers. Medtronic leverages vertical integration in polymer sourcing to sustain cost advantages across its hernia portfolio. W. L. Gore & Associates anchors premium positioning through expanded polytetrafluoroethylene specialization. B. Braun competes on manufacturing scale, operating multiple sterilization facilities that control distribution timelines in European markets.
Hernia mesh devices are implantable medical constructs, typically woven or knitted from polypropylene, polyester, or biologic collagen matrices, designed to reinforce weakened abdominal wall fascia during defect closure. These devices function by providing tensile support that enables native tissue ingrowth while minimizing foreign body reaction and recurrence risk. Non-absorbable polypropylene meshes still occupy the largest installed base due to decades of clinical validation and favorable cost profiles, though biologic meshes command premium pricing in contaminated surgical fields where synthetic placement risks infection. Composite configurations pairing permanent polymers with absorbable barriers represent the fastest-expanding product category as they address adhesion formation concerns in laparoscopic ventral repairs.
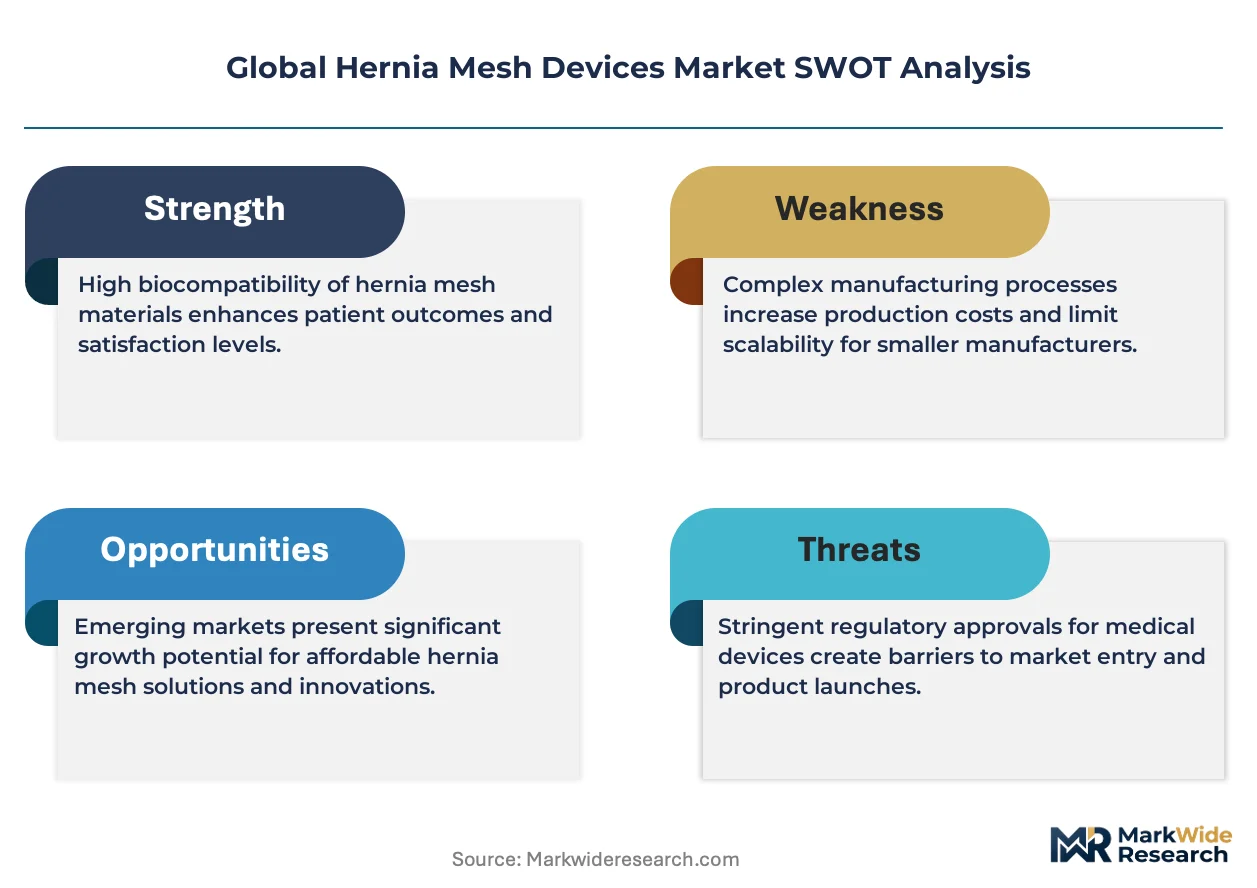
The FDA's 510(k) framework and the EU Medical Device Regulation impose biocompatibility and mechanical testing standards that filter smaller entrants from commercializing permanent implants. Japan's PMDA requires additional local clinical data for biologic meshes, extending market access timelines for foreign manufacturers. Surgeons, procurement committees, and product developers must monitor evolving reimbursement thresholds for robotic-assisted hernia repair, as these coverage decisions will reshape technology adoption curves and mesh consumption patterns across hospital systems.
Market Dynamics
Laparoscopic ventral repair protocols are displacing open surgical techniques across hospital systems, compressing demand toward composite mesh configurations that integrate permanent polymers with absorbable adhesion barriers.
Growth Catalysts
- EU Medical Device Regulation (MDR) harmonization:Streamlined conformity assessment pathways for permanent implant materials are accelerating product registration timelines across member states.
- Robotic-assisted surgical platforms:Operating room investments by United States health systems are expanding addressable volumes for precision mesh placement procedures.
- Polypropylene supply diversification:Multi-source procurement strategies among Japanese manufacturers are reducing input cost volatility and stabilizing production schedules.
Market Restraints
- Biologic mesh cost structure:Collagen matrix sourcing from porcine and bovine tissue processors commands premium pricing that limits adoption to contaminated surgical fields.
- PMDA clinical data requirements:Japan's pharmaceutical and medical device agency mandates local trial evidence for biologic meshes, extending foreign manufacturer market access timelines by 18-36 months.
- Chronic pain litigation exposure:Product liability frameworks in United States jurisdictions are elevating insurance costs for permanent synthetic mesh suppliers.
Strategic Opportunities
- Germany's ambulatory surgery center expansion:Outpatient hernia repair protocols are creating demand for sterilized, pre-packaged mesh kits optimized for same-day discharge.
- Biosynthetic polymer convergence:Hybrid materials combining synthetic scaffolds with resorbable biologics are opening premium positioning in ventral hernia repair applications.
- India's PLI scheme for medical devices:Production-linked incentive structures are attracting contract manufacturing investments that could reshape Asia-Pacific supply geography.
Industry Challenges
- Polymer sterilization validation:Gamma irradiation and ethylene oxide process qualification for permanent implants requires capital-intensive facility certification.
- Surgeon training pathway fragmentation:Laparoscopic mesh placement competency standards vary across United States, German, and Japanese residency programs, complicating product adoption support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hernia Mesh Devices Market |
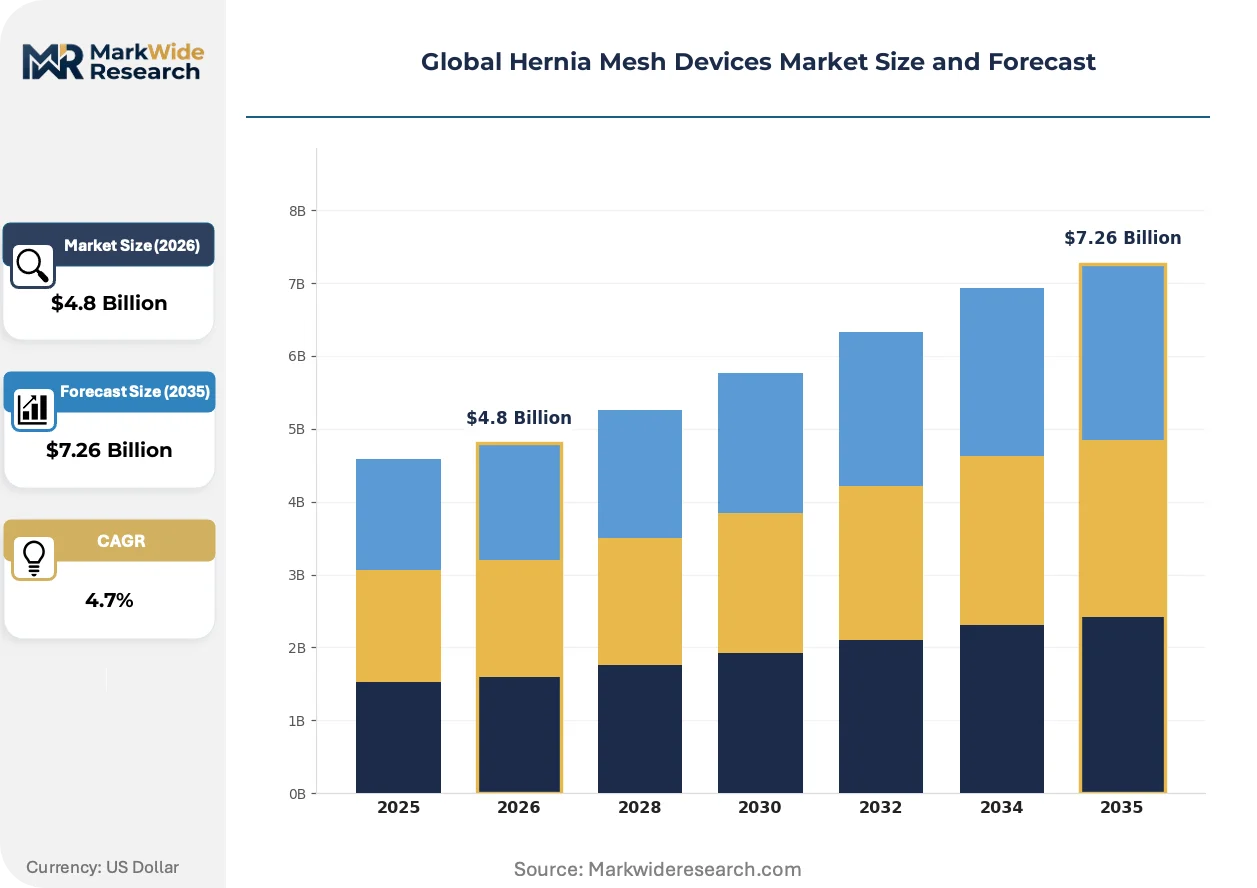
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable Mesh, Non-Absorbable Mesh, Composite Mesh, Biologic Mesh Application: Inguinal Hernia Repair, Ventral Hernia Repair, Femoral Hernia Repair, Incisional Hernia Repair End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Technology: Laparoscopic Repair, Open Surgery, Robotic Surgery, Tension-Free Repair |
| Companies Covered | B. Braun, AbbVie, Medtronic, Integra LifeSciences, Cook Group, Ethicon, W. L. Gore & Associates, TELA Bio, Becton Dickinson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hernia Mesh Devices Market Shifts & Advancements
Three intersecting forces are restructuring competitive positioning: materials science breakthroughs in composite architectures, regulatory recalibration of permanent implant safety frameworks, and procurement centralization within integrated delivery networks.
Composite mesh architectures pairing polypropylene substrates with absorbable barrier layers are converging with laparoscopic ventral repair protocols to enable intraperitoneal placement without adhesion formation. United States academic medical centers are adopting these configurations at accelerated rates for incisional hernia cases. This convergence is compressing demand for bare polypropylene meshes in premium surgical segments while expanding total addressable procedure volumes.
Japan's PMDA has tightened biocompatibility documentation requirements for permanent synthetic meshes, mandating extended follow-up data for foreign-manufactured devices. This regulatory recalibration is elevating compliance costs for imported products and creating structural advantages for domestic manufacturers with established clinical trial infrastructure. Biologic mesh categories face the steepest documentation burdens, reshaping competitive entry strategies.
Hospital procurement committees are consolidating vendor relationships through single-source contracts for mesh portfolios, displacing the previous multi-supplier model. Integrated delivery networks in Germany and the United States are negotiating multi-year agreements that bundle synthetic and biologic products with robotic platform service contracts. This concentration is most visible in United States metropolitan health systems where procurement authority has shifted from individual surgeons to supply chain executives.
Global Hernia Mesh Devices Market Segmentation
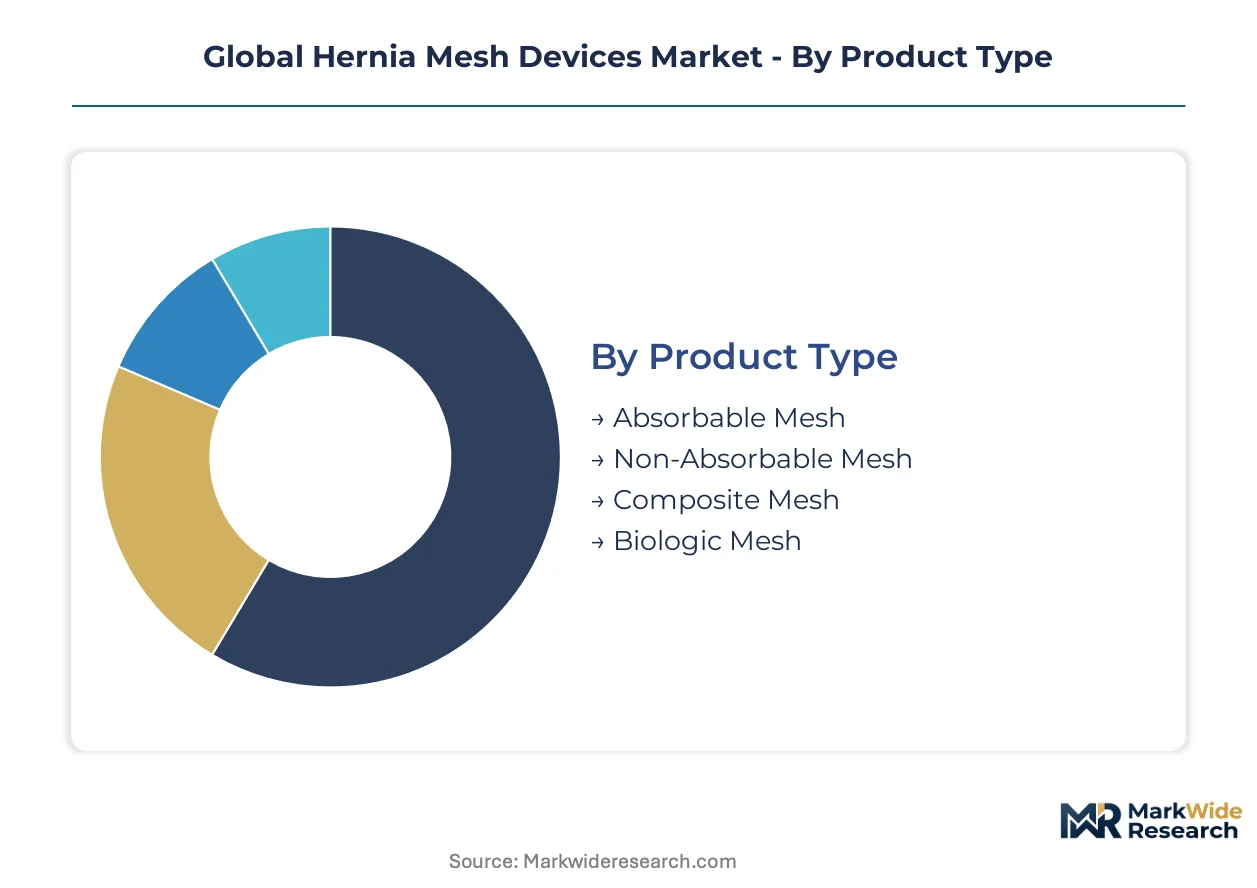
Segmentation in the hernia mesh market reveals how material science, surgical technique, and care setting economics intersect to determine purchasing patterns. Procurement committees weight mesh properties against procedure reimbursement rates when selecting portfolio configurations.
Product Type:
Supply concentration in polymer feedstocks and biologic tissue processors shapes competitive dynamics across material categories.
- Non-Absorbable Mesh:Polypropylene and polyester constructs provide permanent tensile reinforcement with decades of clinical validation. Hospitals in the United States and Germany standardize on these configurations for clean surgical fields where long-term durability outweighs foreign body considerations.
- Composite Mesh:Permanent polymer substrates bonded to absorbable adhesion barriers enable intraperitoneal placement without bowel attachment complications. Demand concentrates in academic medical centers performing laparoscopic ventral repairs, where adhesion prevention justifies premium positioning.
- Absorbable Mesh:Synthetic polymers engineered for gradual resorption suit pediatric applications and temporary bridging scenarios where permanent implantation carries elevated risk.
- Biologic Mesh:Porcine and bovine collagen matrices processed through decellularization protocols command specialized use in contaminated wounds where synthetic placement risks infection.
Today's leader: Non-Absorbable Mesh. Tomorrow's challenger: Composite Mesh.
Application:
Procedure volume distribution across hernia types determines manufacturing scale economics and inventory planning requirements.
- Inguinal Hernia Repair:The highest-volume procedure category globally, with synthetic mesh reinforcement now standard of care in Lichtenstein tension-free protocols across United States, German, and Japanese hospital systems.
- Ventral Hernia Repair:Complex abdominal wall reconstructions in obese and post-surgical patient populations drive demand for composite and biologic configurations with enhanced handling characteristics.
- Incisional Hernia Repair:Recurrence-prone defects at prior surgical sites require mesh reinforcement with extended overlap margins, favoring larger-format products with directional tensile properties.
- Femoral Hernia Repair:Lower-incidence procedures in specific patient demographics, often addressed with pre-shaped or plug configurations designed for narrow defect anatomy.
Volume concentrates in Inguinal Hernia Repair. Margin expansion tracks Ventral Hernia Repair.
End User:
Capital intensity and sterilization requirements create distinct supply chain configurations for each care setting.
- Hospitals:Integrated surgical departments with robotic platforms and open procedure capabilities maintain diversified mesh inventories spanning synthetic and biologic categories across all hernia types.
- Ambulatory Surgical Centers:Outpatient-focused facilities in Germany and the United States prioritize pre-packaged, sterilized kits optimized for same-day discharge protocols and rapid turnover.
- Specialty Clinics:Hernia-focused surgical practices concentrate on specific repair techniques, often maintaining preferred vendor relationships for consistent product familiarity.
- Research Institutions:Academic medical centers with residency programs drive adoption of novel configurations through training curriculum integration and clinical trial participation.
Procurement authority centralizes in Hospitals. Growth velocity favors Ambulatory Surgical Centers.
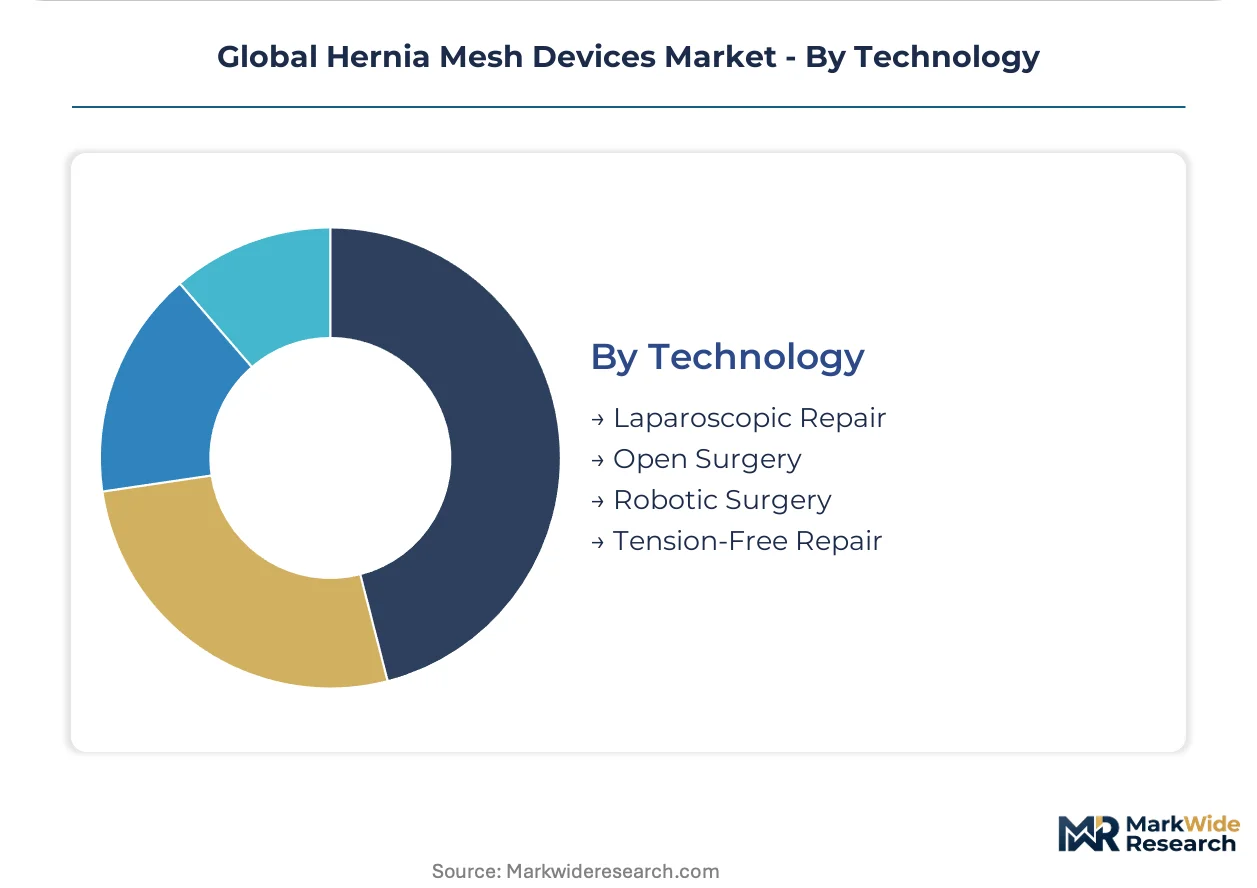
Technology:
Surgeon training pathways and equipment capital requirements segment addressable demand by procedural approach.
- Laparoscopic Repair:Minimally invasive techniques with mesh placement through trocar ports require specialized composite configurations with rolled or folded delivery profiles.
- Open Surgery:Traditional approaches with direct visualization accommodate broader mesh formats and enable hand-sewn fixation techniques still prevalent in resource-constrained settings.
- Robotic Surgery:United States health system investments in da Vinci platforms create demand for mesh products compatible with robotic graspers and suturing instruments.
- Tension-Free Repair:Lichtenstein and similar protocols emphasizing mesh bridging without sutured closure stress remain foundational to inguinal hernia standard of care.
Installed base dominance belongs to Open Surgery. Capital deployment accelerates Robotic Surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investments toward jurisdictions with streamlined implant approval pathways. The FDA's updated 510(k) framework and Japan's PMDA clinical data requirements create divergent cost-of-compliance profiles that reshape production geography decisions.
United States
Robotic-assisted surgical platform deployments in academic medical centers are expanding addressable volumes for precision mesh placement. The FDA's 510(k) clearance pathways for permanent implant materials filter smaller entrants from commercializing synthetic meshes. Minneapolis-based Medtronic leverages vertical integration in polymer sourcing to sustain cost advantages across its hernia portfolio.
Germany
Ambulatory surgery center expansion is creating demand for sterilized, pre-packaged mesh kits optimized for same-day discharge protocols. The EU Medical Device Regulation harmonizes conformity assessment pathways for permanent implant materials across member states. Aesculap, the B. Braun subsidiary headquartered in Tuttlingen, operates multiple sterilization facilities that control distribution timelines in European markets.
Japan
Laparoscopic surgery adoption is deepening in metropolitan hospital systems, concentrating demand for composite mesh configurations. PMDA mandates local clinical trial evidence for biologic meshes, extending foreign manufacturer market access timelines by 18-36 months. Tokyo-based domestic manufacturers with established clinical trial infrastructure capture structural advantages from tightened biocompatibility documentation requirements.
India
Production-linked incentive schemes for medical devices are attracting contract manufacturing investments that reshape Asia-Pacific supply geography. CDSCO regulatory pathways for Class C and D implants require local testing but offer accelerated review for quality-certified facilities. Gujarat and Karnataka industrial clusters are emerging as sterilization and packaging hubs for export-oriented mesh production.
Switzerland
Swissmedic's alignment with EU MDR standards enables streamlined market access for premium implant manufacturers serving both jurisdictions. Precision polymer processing capabilities in the Basel-Land region support specialized mesh substrate production. The country's medical technology cluster concentrates sterile manufacturing competencies that serve German and French hospital procurement networks.
Global Hernia Mesh Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biosynthetic hybrid configurations and regional manufacturing partnerships. The vendor base concentrates around diversified medical device conglomerates with captive polymer supply chains and specialized materials science firms with barrier-layer expertise. Three archetypes dominate: vertically integrated conglomerates controlling raw material through distribution, premium-positioned specialists in expanded polytetrafluoroethylene, and contract manufacturers leveraging India's PLI incentives. Competitive moves center on sterilization facility certification for gamma and ethylene oxide processes, plus multi-year procurement contracts bundling synthetic and biologic portfolios with robotic platform service agreements.
Within the vertically integrated tier, Medtronic and B. Braun exemplify scale-driven positioning through captive supply chain control. W. L. Gore & Associates occupies a premium-specialist position anchored in fluoropolymer expertise. Among biologic-focused entrants, TELA Bio represents the convergence archetype combining resorbable matrices with synthetic scaffolds. These three companies illustrate how material science specialization, manufacturing scale, and regulatory navigation capabilities segment competitive positioning across the hernia mesh value chain.
| Leading Market Players |
|---|
| B. Braun |
| AbbVie |
| Medtronic |
| Integra LifeSciences |
| Cook Group |
| Ethicon |
| W. L. Gore & Associates |
| TELA Bio |
| Becton Dickinson |
| Others |
Supply & Pricing Matrix
Captive polymer sourcing through backward integration into polypropylene and biosynthetic feedstocks anchors cost-position advantages for diversified conglomerates while compressing margin structures for contract-dependent competitors across the hernia mesh value chain.
Pricing Analysis
Distributor margins on biologic mesh categories absorb the steepest compression as hospital procurement committees consolidate vendor relationships through single-source contracts. Three-tier pricing structure across premium composite, standard non-absorbable, and economy bare polypropylene configurations stratifies by certification burden and sterilization validation status. Pricing pressure stems from chronic pain litigation exposure elevating insurance costs for permanent synthetic mesh suppliers in United States jurisdictions. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement protocols, while academic medical centers with robotic platforms tolerate premium positioning for adhesion-barrier configurations.
Supply Chain Analysis
Specialized polymer chemists and sterilization technicians concentrate in Basel-Land region clusters and Tuttlingen manufacturing corridors, constraining capacity expansion timelines for gamma irradiation and ethylene oxide process qualification. Mesh manufacturing draws from polypropylene resin suppliers in Germany and the United States, decellularized collagen processors in Switzerland, and precision weaving equipment fabricators in Japan. Single-source vulnerability runs through concentrated biologic tissue processors supplying porcine and bovine matrices. Distribution runs through hospital procurement committees and integrated delivery network supply chain executives displacing surgeon-driven purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on composite mesh premiumization and sterilization facility scale economies compressing per-unit validation costs across expanding procedure volumes.
For Market Incumbents: Lock in multi-year procurement contracts bundling synthetic and biologic portfolios with robotic platform service agreements before ambulatory surgery center expansion accelerates price transparency. Deepen backward integration into polymer feedstocks to defend position against Japanese manufacturers leveraging PMDA clinical data requirements as structural barriers. Prioritize gamma irradiation facility certification to capture sterilization bottleneck premiums in European markets. For New Entrants and Emerging Players: Launch via contract manufacturing partnerships leveraging India's PLI scheme for medical devices to bypass capital-intensive sterilization infrastructure requirements. Target biosynthetic polymer convergence white space where hybrid materials combining synthetic scaffolds with resorbable biologics command premium positioning in ventral hernia repair applications. Pursue hospital system partnership models with integrated delivery networks seeking second-source diversification for composite mesh categories. For Investors and Strategic Acquirers: Roll-up economics work for specialized barrier-layer technology firms because adhesion prevention intellectual property concentrates in fragmented materials science boutiques lacking distribution scale. Five-to-ten year viability favors acquisition targets with established PMDA clinical trial infrastructure navigating Japan's tightened biocompatibility documentation requirements. Monitor FDA 510(k) clearance velocity for composite configurations as inflection indicator for technology adoption curves reshaping mesh consumption patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Sterilization Facility Certification | Gamma and ethylene oxide qualification controls distribution timelines in EU MDR markets. |
| Hospital System Partnership | Integrated delivery network contracts displace surgeon-driven purchasing authority. |
| CE Marking Pathway | EU MDR harmonization accelerates product registration timelines across member states. |
| Biologic Mesh PMDA Submission | Local clinical trial evidence extends foreign manufacturer market access timelines. |
| Reimbursement Strategy | Coverage decisions for robotic-assisted repair reshape technology adoption curves. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with surgeons, hospital purchasing committees, biomedical engineers, and GPO contracts managers alongside secondary validation through FDA 510(k) filings, EU MDR conformity assessment databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data across the analysis window.
Segment-weighting approaches modeled material type, hernia application, end-user setting, and surgical technology dimensions throughout the forecast period. CAGRs derived from procedure volume trajectories, reimbursement rate evolution, and technology substitution curves. Forecast inputs incorporated laparoscopic adoption rates in United States academic medical centers and ambulatory surgery center expansion protocols in Germany.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PMDA regulatory recalibration or chronic pain litigation settlement waves. Practitioners should monitor robotic platform deployment rates and biologic mesh local trial completion timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brain-On-Chip Model Market
Medical Devices
Guide Extension Catheter Market
Medical Devices
Global Vitreoretinal Surgery Devices Market
Medical Devices
Neurothrombectomy Devices Market
Medical Devices
Pectus Bar Market
Medical Devices
Asia-Pacific Intraoral Scanners Market
Medical Devices
Pharmaceutical Filtration Devices Market
Medical Devices
Epilepsy Treatment Devices Market
Medical Devices
Pre-Owned Medical Devices Market
Medical Devices
Appendage Management Market
Medical Devices
LASIK Eye Surgery Devices Market
Medical Devices
Neuro Ablation Devices Market
Medical Devices
Global Bowel Management System Market
Medical Devices
Global Cardiopulmonary Bypass Accessory Equipment Market
Medical Devices
Silastic Implant Market
Medical Devices
Global Cardiac Resuscitation Device Market