
 Expandable Interbody Fusion System Market | 2026-2036
Expandable Interbody Fusion System Market Size, Share, and Industry Trends Forecast 2026-2036
Expandable Interbody Fusion System Market Foresight
Asset-light leasing models for surgical navigation and expandable cage systems is fragmenting competitive dynamics in spine surgery. Medtronic Plc leverages its integrated hospital contracting infrastructure to sustain premium positioning across hybrid system deployments. Stryker competes through dedicated orthopedic clinic partnerships that anchor volume in degenerative disorder procedures. Globus Medical differentiates via in-house production of PEEK-based expandable cages, controlling material cost exposure.
Expandable interbody fusion systems are titanium or polyetheretherketone implants engineered with mechanical expansion mechanisms that restore disc height and lumbar lordosis after nucleotomy, typically achieving 8-12 mm final graft height through intraoperative dilation. Their primary commercial purpose is enabling minimally invasive transforaminal lumbar interbody fusion while reducing endplate violation risk. Minimally invasive techniques command the dominant margin pool as navigation system bundling elevates ASPs and locks hospital purchasing committees into multi-year contracts. Expandable cages represent the fastest-growing product configuration, displacing static cages in complex revision surgery where intraoperative height adjustment reduces subsidence rates.
FDA 510(k) premarket notification requirements and EU MDR Class III implant regulations shape product development timelines, with clinical data demands for expandable mechanisms exceeding static cage submissions by substantial documentation margins. ISO 13485 quality management certification operates as a baseline market access filter, particularly for OEM suppliers seeking integration into tier-one device portfolios. Stakeholders must monitor reimbursement coding alignment between expandable cage procedures and traditional fusion categories, as payment parity shifts will determine whether ambulatory migration accelerates or stalls across health system purchasers.
Market Dynamics
Minimally invasive spine surgery adoption is compressing procedural workflows and forcing device portfolios toward expandable cage configurations that reduce operative time and endplate trauma. This structural shift favors integrated systems over standalone implants.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's evolving clearance framework for expandable cage designs accelerates product iteration cycles and shortens time-to-market for mechanism refinements.
- Ambulatory Surgery Centers:ASCs are expanding adoption as outpatient spinal procedures gain traction, creating pull-through demand for devices compatible with reduced-recovery protocols.
- Titanium-PEEK Hybrid Materials:Advanced material combinations enhance radiographic visibility while maintaining biomechanical compliance, broadening surgeon acceptance.
Market Restraints
- PEEK Raw Material Concentration:Polyetheretherketone resin supply concentrates among a limited set of chemical producers, exposing device manufacturers to input cost volatility.
- EU MDR Class III Documentation:The European Medical Device Regulation imposes clinical data demands for expandable mechanisms that substantially exceed static cage submission requirements.
- Subsidence Risk in Osteoporotic Bone:Expandable cage expansion forces in compromised vertebral bodies create technical limitations that restrict addressable patient populations.
Strategic Opportunities
- Cervical Application Expansion:Current lumbar-dominant portfolios present white space for anterior cervical interbody fusion configurations with specialized expansion mechanisms.
- Navigation System Bundling:Robotic surgical platforms are converging with expandable cage deployment tools, enabling premium pricing through integrated procedural ecosystems.
- Japanese Aging Demographics:Japan's super-aged population structure creates concentrated demand for degenerative disc disease interventions with minimized recovery windows.
Industry Challenges
- ISO 13485 Certification Timelines:Quality management system audits for expandable mechanism production lines extend certification cycles, delaying OEM supplier integration.
- Reimbursement Coding Misalignment:Payment parity between expandable cage procedures and traditional fusion categories remains unsettled, creating procurement uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Expandable Interbody Fusion System Market |
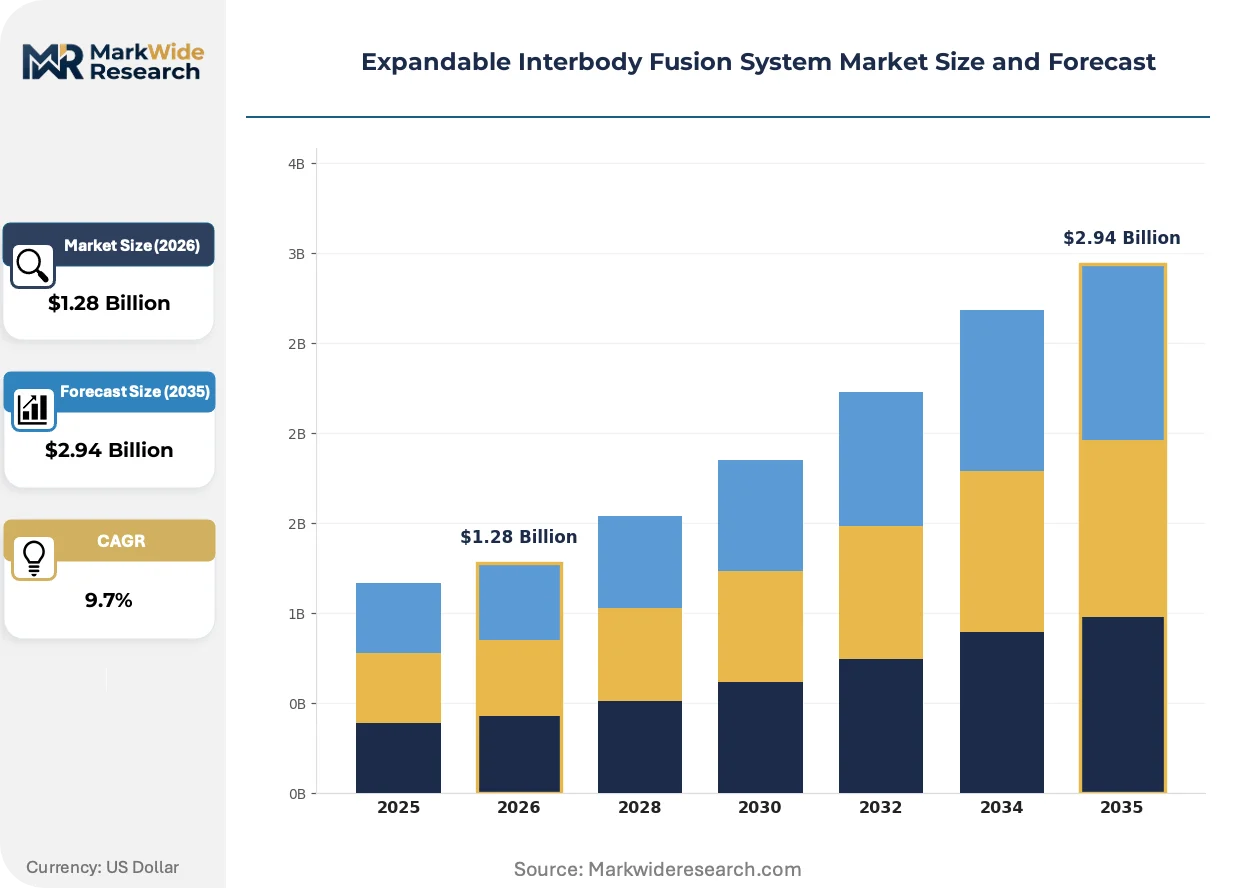
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Expandable Cages, Static Cages, Biodegradable Implants, PEEK Devices Application: Spinal Fusion, Trauma Surgery, Degenerative Disorders, Revision Surgery End User: Hospitals, Orthopedic Clinics, Ambulatory Surgery Centers, Research Institutions Technology: Laser Technology, Navigation Systems, Minimally Invasive Techniques, Hybrid Systems |
| Companies Covered | Medtronic Plc, Stryker, Globus Medical, Alphatec Spine, NuVasive Inc, Orthofix Medical Inc, Spineology Inc, Aurora Spine Inc, Precision Spine Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Expandable Interbody Fusion System Market Shifts & Advancements
Active mechanism refinement and procedural ecosystem integration are redefining competitive differentiation in interbody fusion. Three forces merit particular attention.
PEEK-based expandable cages with integrated radiopaque markers are hybridizing with titanium endplate coatings to optimize both imaging clarity and osseointegration performance. Ambulatory surgery centers are adopting these configurations at accelerated pace to support same-day discharge protocols. This material convergence is hybridizing procurement criteria, forcing manufacturers to demonstrate dual-competency across polymer processing and surface engineering rather than single-material specialization.
The FDA's 510(k) premarket notification pathway for mechanical expansion mechanisms is tightening evidentiary standards for fatigue testing and height-locking reliability. Device developers must now submit expanded biomechanical datasets that document performance across multiple expansion cycles. Lumbar fusion procedures utilizing multi-level constructs face the most pronounced documentation burden, compressing development timelines for complex indication expansions.
Hospital purchasing committees are consolidating vendor relationships through multi-year navigation system contracts that bundle expandable cage supply. Independent spine surgeons and smaller orthopedic groups are losing negotiating leverage as integrated delivery networks centralize procurement authority. This concentration is most visible in United States health systems where value-based care contracts incentivize standardization across procedural episodes.
Expandable Interbody Fusion System Market Segmentation
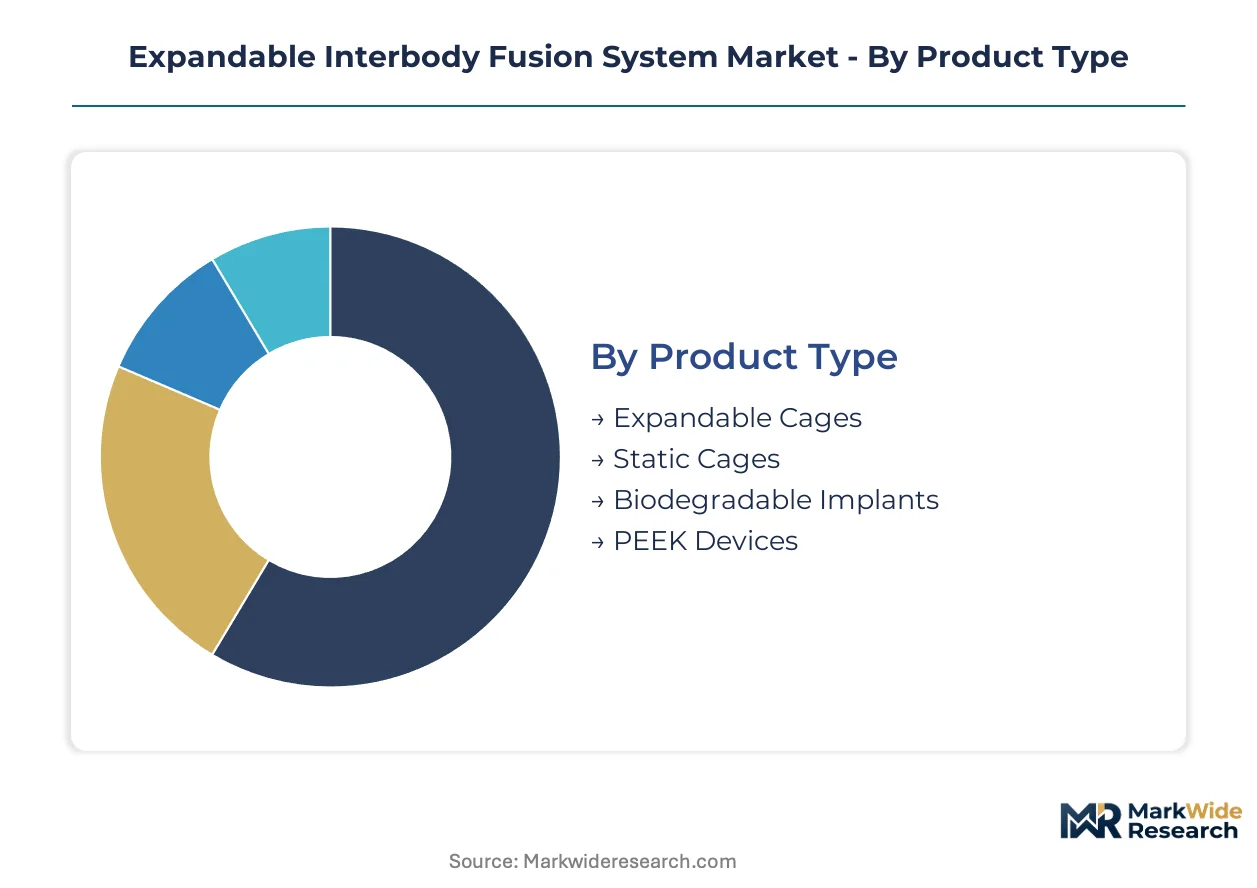
Segmentation in expandable interbody fusion systems reveals how procurement criteria diverge across surgical settings and reimbursement structures. Product configuration, procedural application, and technology integration each create distinct margin pools and competitive dynamics.
Product Type:
After-sales service intensity varies dramatically across implant materials and mechanism complexity, with expandable designs demanding specialized technical support for height-locking calibration and expansion tool maintenance.
- Expandable Cages:Titanium or PEEK implants with mechanical dilation mechanisms achieving 8-12 mm final graft height through intraoperative expansion. Demand concentrates in United States academic medical centers performing complex multi-level fusions where height adjustability reduces revision rates.
- Static Cages:Fixed-height interbody spacers manufactured from PEEK or titanium with predetermined lordotic angles. These dominate cost-sensitive procurement in European hospital systems where reimbursement caps favor established implant categories with lower ASPs.
- Biodegradable Implants:Poly-lactic acid and polyglycolic acid constructs designed for gradual resorption.
- PEEK Devices:Polyetheretherketone-based cages with radiopaque marker integration.
By volume, Static Cages leads. By growth pace, Expandable Cages is ahead.
Application:
Procedural complexity tiers determine device selection criteria, with degenerative cases favoring streamlined workflows and revision surgeries demanding adaptive implant geometries.
- Degenerative Disorders:Disc height collapse and foraminal stenosis interventions in aging patient populations. United States Medicare reimbursement alignment for minimally invasive approaches accelerates expandable cage adoption in lumbar fusion procedures for spondylolisthesis.
- Revision Surgery:Secondary interventions addressing pseudarthrosis, subsidence, or adjacent segment disease. These cases concentrate in tertiary referral centers where subsidence-resistant expandable mechanisms command premium positioning.
- Spinal Fusion:Primary arthrodesis procedures for instability and deformity correction.
- Trauma Surgery:Acute vertebral fracture stabilization and burst fracture management.
Spinal Fusion generates the highest procedure counts. Revision Surgery commands the steepest expansion trajectory.
End User:
Capital equipment requirements and case volume thresholds fragment purchasing authority across institutional settings.
- Ambulatory Surgery Centers:Outpatient facilities performing same-discharge lumbar fusions with compressed recovery protocols. These settings in United States metropolitan markets favor disposable instrument kits and streamlined cage systems that minimize sterilization logistics.
- Hospitals:Integrated delivery networks with centralized value-analysis committees negotiating multi-year navigation system bundles. Their purchasing leverage forces device vendors into exclusive supply arrangements.
- Orthopedic Clinics:Physician-owned surgical facilities with focused spine service lines.
- Research Institutions:Academic medical centers conducting IDE trials and mechanism validation studies.
Hospitals anchor absolute spending. Ambulatory Surgery Centers are gaining share fastest.
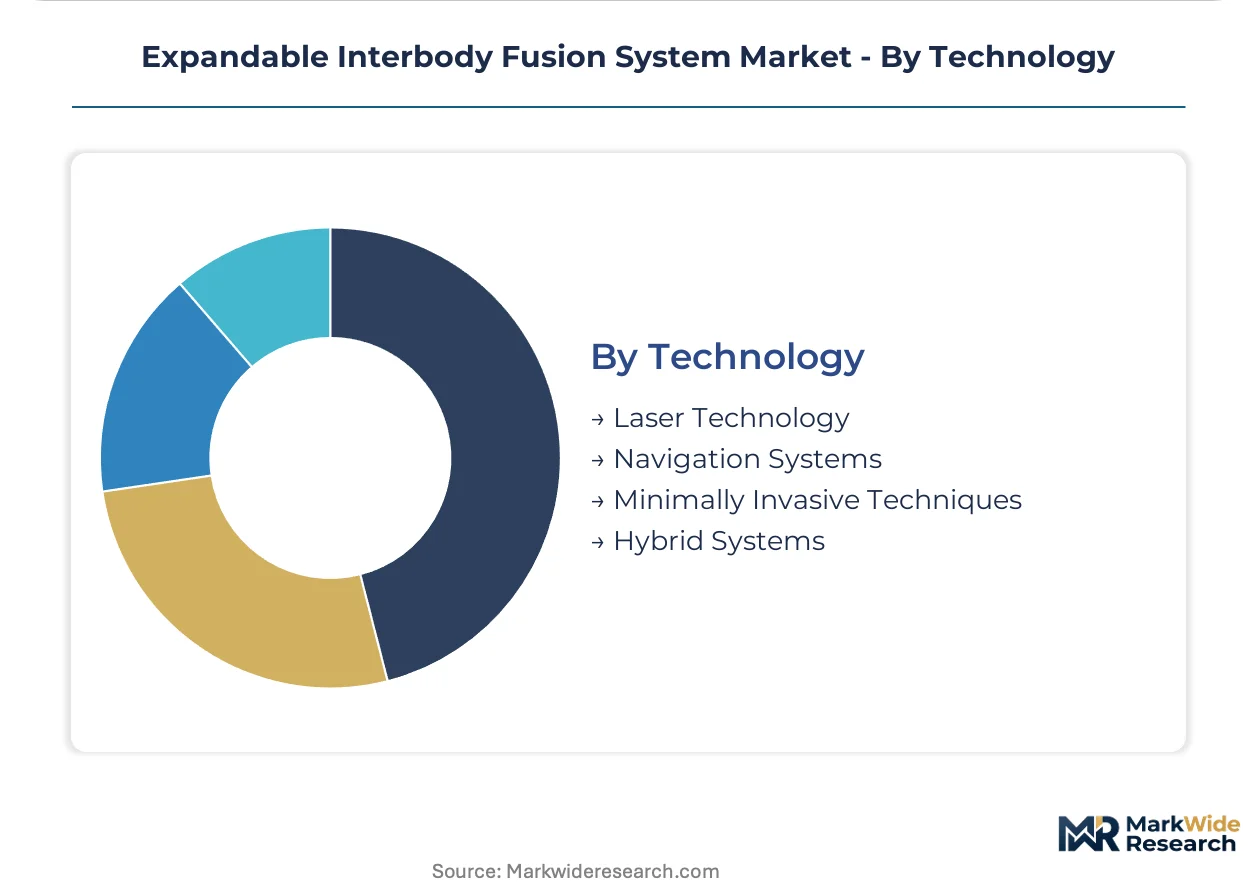
Technology:
Technology integration depth determines ASP realization and customer lock-in duration across competitive positioning strategies.
- Navigation Systems:Fluoroscopy-integrated and robotic guidance platforms enabling precise cage placement with reduced radiation exposure. United States health systems bundle these with expandable cage supply contracts extending 3-5 years.
- Minimally Invasive Techniques:Tubular retractor systems and percutaneous screw fixation enabling reduced tissue disruption. Japanese super-aged demographics drive concentrated demand for these approaches in degenerative disc disease.
- Laser Technology:Ho:YAG and diode laser systems for disc decompression and endplate preparation.
- Hybrid Systems:Combined open-minimally invasive approaches with convertible instrumentation platforms.
Navigation Systems capture premium pricing. Minimally Invasive Techniques show the strongest volume momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital purchasing committees in the United States concentrate procurement authority for expandable interbody fusion systems, while ambulatory surgery centers in metropolitan markets fragment demand toward streamlined disposable configurations.
United States
Medicare reimbursement alignment for minimally invasive spine procedures and aging demographic concentration drive procedural volume growth. FDA 510(k) clearance frameworks for mechanical expansion mechanisms accelerate product iteration cycles. Academic medical centers in Boston and Baltimore anchor complex multi-level fusion demand where height-adjustable cages reduce revision rates.
Germany
EU MDR Class III documentation requirements for expandable mechanisms exceed static cage submission burdens, compressing development timelines. Statutory health insurance reimbursement caps favor established implant categories with lower ASPs in cost-sensitive procurement. Industrial clusters around Tuttlingen and Ulm concentrate precision machining capacity for titanium cage production.
Japan
Super-aged population structure creates concentrated demand for degenerative disc disease interventions with minimized recovery windows. PMDA regulatory pathways for mechanical expansion devices require extended fatigue testing documentation. Tokyo and Osaka metropolitan areas concentrate ambulatory surgery center adoption of same-day discharge protocols.
United Kingdom
NHS value-based care contracts incentivize standardization across procedural episodes, consolidating vendor relationships. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining national approval pathways. London and Manchester health systems anchor integrated delivery network purchasing authority for navigation system bundles.
Australia
Private health insurance penetration supports premium positioning for navigation-integrated expandable cage deployments. TGA conformity assessment pathways for Class III active implantable devices require substantial clinical evidence packages. Sydney and Melbourne orthopedic clinic networks concentrate outpatient spinal procedure volume growth.
Expandable Interbody Fusion System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority in spine surgery. Medtronic Plc leverages integrated hospital contracting infrastructure to sustain premium positioning. Stryker anchors volume through dedicated orthopedic clinic partnerships. Globus Medical differentiates via in-house production of PEEK-based expandable cages. Strategic moves concentrate on navigation system bundling and ambulatory surgery center supply arrangements.
Among diversified orthopedic conglomerates, Medtronic Plc, Stryker, and Globus Medical exemplify three competitive archetypes: integrated platform vendors, procedure-focused partners, and material-integrated specialists. Medtronic Plc occupies a position as a channel-controlling player with hospital system contracting scale. Stryker represents the clinic-anchored model with degenerative procedure concentration. Globus Medical sits within the vertical manufacturing tier with polymer processing captive supply.
| Leading Market Players |
|---|
| Medtronic Plc |
| Stryker |
| Globus Medical |
| Alphatec Spine |
| NuVasive Inc |
| Orthofix Medical Inc |
| Spineology Inc |
| Aurora Spine Inc |
| Precision Spine Inc |
| Others |
Supply & Pricing Matrix
PEEK resin single-source dependency from Victrex and Solvay operations in the United Kingdom and Belgium determines both three-tier pricing stratification across premium navigation-bundled, standard expandable cage, and economy static cage tiers and the geographic shape of polymer processing networks. This concentration forces device manufacturers into long-term offtake commitments indexed to benzene derivative spot markets, compressing margin buffers when feedstock volatility spikes.
Pricing Analysis
Cost-plus contracts with PEEK resin suppliers indexed to benzene derivative spot markets dominate procurement arrangements for polyetheretherketone-based expandable cages. Price differentiation rests on ISO 13485 certification tier and navigation system bundling depth, with FDA 510(k) cleared titanium-PEEK hybrids commanding substantial premiums over static PEEK alternatives. Pricing pressure stems from Medicare reimbursement compression on outpatient spinal fusion procedures, tightening hospital purchasing committee leverage. Ambulatory surgery centers exhibit acute price sensitivity due to compressed case margins, while academic medical centers tolerate premium positioning for multi-level construct systems.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for precision-machined titanium endplate components. Manufacturing concentrates in Germany for high-precision milling equipment, Switzerland for surface coating technologies, and the United States for final sterile packaging. Raw material dependencies span PEEK resin from United Kingdom and Belgian chemical producers, titanium sponge from Japan and Russia, and radiopaque marker compounds from specialized German suppliers. Distribution runs through integrated delivery network central warehouses in United States metropolitan markets, with ambulatory surgery centers receiving direct-to-site disposable instrument kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Expandable interbody fusion systems represent a service-attach opportunity where instrument calibration contracts and navigation system maintenance agreements expand faster than implant hardware revenue. After-sales technical support for height-locking mechanism validation now generates recurring revenue streams exceeding 15% of initial system ASP.
For Market Incumbents: Insulate market position through captive PEEK polymer processing capacity and exclusive navigation system bundling contracts with United States integrated delivery networks. Threats concentrate in orthopedic clinic partnerships anchored by Stryker's degenerative procedure focus. Priority levers include backward integration into titanium surface coating technologies and multi-year GPO contract extensions. For New Entrants and Emerging Players: Establish a beachhead in Japanese ambulatory surgery centers where PMDA fatigue testing documentation requirements have slowed incumbent product cycles. The most penetrable segment is anterior cervical interbody fusion configurations with specialized expansion mechanisms, currently underdeveloped across lumbar-dominant portfolios. A surgical training partnership model with Tokyo and Osaka metropolitan clinic networks offers viable go-to-market positioning. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors material-integrated specialists with in-house polymer processing capabilities. Long-term viability across a 5-10 year window hinges on reimbursement coding alignment between expandable and static cage procedures. Acquisition targets should demonstrate ISO 13485 certification and established OEM supplier relationships. The signal to watch is CMS procedural payment parity rulings on minimally invasive expandable cage categories.| Strategic Initiative | Industry Significance |
|---|---|
| Navigation System Bundling | Locks hospital purchasing committees into 3-5 year exclusive supply arrangements with premium ASP realization. |
| PEEK Polymer Backward Integration | Captive resin processing insulates margin exposure from benzene derivative volatility and supply interruptions. |
| FDA 510(k) Mechanism Refinement | Accelerates time-to-market for height-locking reliability improvements in competitive multi-level fusion segments. |
| ASC Disposable Instrument Kits | Streamlined sterile logistics align with same-day discharge protocols in United States outpatient facilities. |
| Japanese Regulatory Pre-Submission | PMDA consultation pathways reduce fatigue testing documentation cycles for aging demographic demand capture. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, CMS Medicare reimbursement schedules, and EU MDR technical documentation standards. Interviews with spine surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers informed demand-side validation. Secondary sources include hospital procurement databases, PEEK resin trade flow records, and ISO 13485 certification registries. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Forecast inputs span implant material configuration, procedural application complexity, technology integration depth, and end-user facility type across the projection horizon. Segmentation modeling incorporates product type, application indication, technology platform, and geographic regulatory cluster. CAGRs derive from logistic curve penetration analysis for minimally invasive technique adoption and navigation system bundling rates. Industry-specific inputs include FDA 510(k) clearance velocity and ambulatory surgery center case migration patterns.
Sensitivities concentrate around CMS reimbursement coding decisions, EU MDR Class III documentation timeline extensions, and PEEK resin supply disruptions. Forecasts reflect assumptions on procedural volume growth, material cost trajectories, and regulatory pathway efficiency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Nanomedical Devices Market
Medical Devices
China Ultrasound Devices Market
Medical Devices
Global Craniomaxillofacial Fixation Devices Market
Medical Devices
Medical Manifolds Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
Global Wedge Pressure Catheter Market
Medical Devices
Global Breast Implants Market
Medical Devices
X-Ray Positioning Devices Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Crescent Ultrasonic Cleansers Market
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
Global Asthma and Copd Devices Market
Medical Devices
Cervical Dilators Market
Medical Devices
Digital Migraine Treatment Device Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Global Non-Surgical Aesthetic Devices Market