
 Pressure Mapping Systems in Healthcare Market | 2026-2036
Pressure Mapping Systems in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Mapping Systems in Healthcare Market Intelligence
ISO 13485 certification cycles for medical device quality management is collapsing from thirty-six months to under eighteen months for established manufacturers, raising barriers for new entrants. Tekscan, Inc. leverages its captive piezoresistive sensor fabrication to sustain margin control across hospital procurement channels. XSENSOR Technology Corporation anchors its position in Canadian and US long-term care facilities through specialized mattress-integrated platforms. Sensor Products Inc. competes on turnkey pressure-indicating film kits that bypass electronic calibration requirements in cost-sensitive clinics.
Pressure mapping systems measure interface pressure distribution between a body surface and support surface using arrays of force-sensitive elements, typically resolving pressures from 0.1 to 200 mmHg with spatial densities exceeding one sensor per square centimeter, primarily to prevent tissue damage or optimize biomechanical function. Capacitive sensors dominate research and rehabilitation settings where drift tolerance and humidity resistance justify premium positioning, while electromagnetic sensors occupy the largest installed base in hospital beds owing to simpler sterilization protocols and lower per-unit replacement costs. Software Solutions capture expanding recurring revenue streams as facilities integrate pressure mapping data into electronic health record workflows and remote patient monitoring dashboards.
FDA 510(k) premarket notification requirements govern US commercialization, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence standards for Class IIa systems, lengthening conformity assessment intervals for manufacturers without notified body relationships. The country's national pharmaceutical regulator in India and CDSCO are developing parallel pathways for software-as-medical-device classifications that will determine whether cloud-based pressure analytics require separate licensing. Stakeholders must monitor evolving reimbursement coding for pressure mapping in preventive care protocols, as coverage decisions by CMS and analogous agencies will determine whether these systems shift from capital equipment to standard-of-care consumables.
Market Dynamics
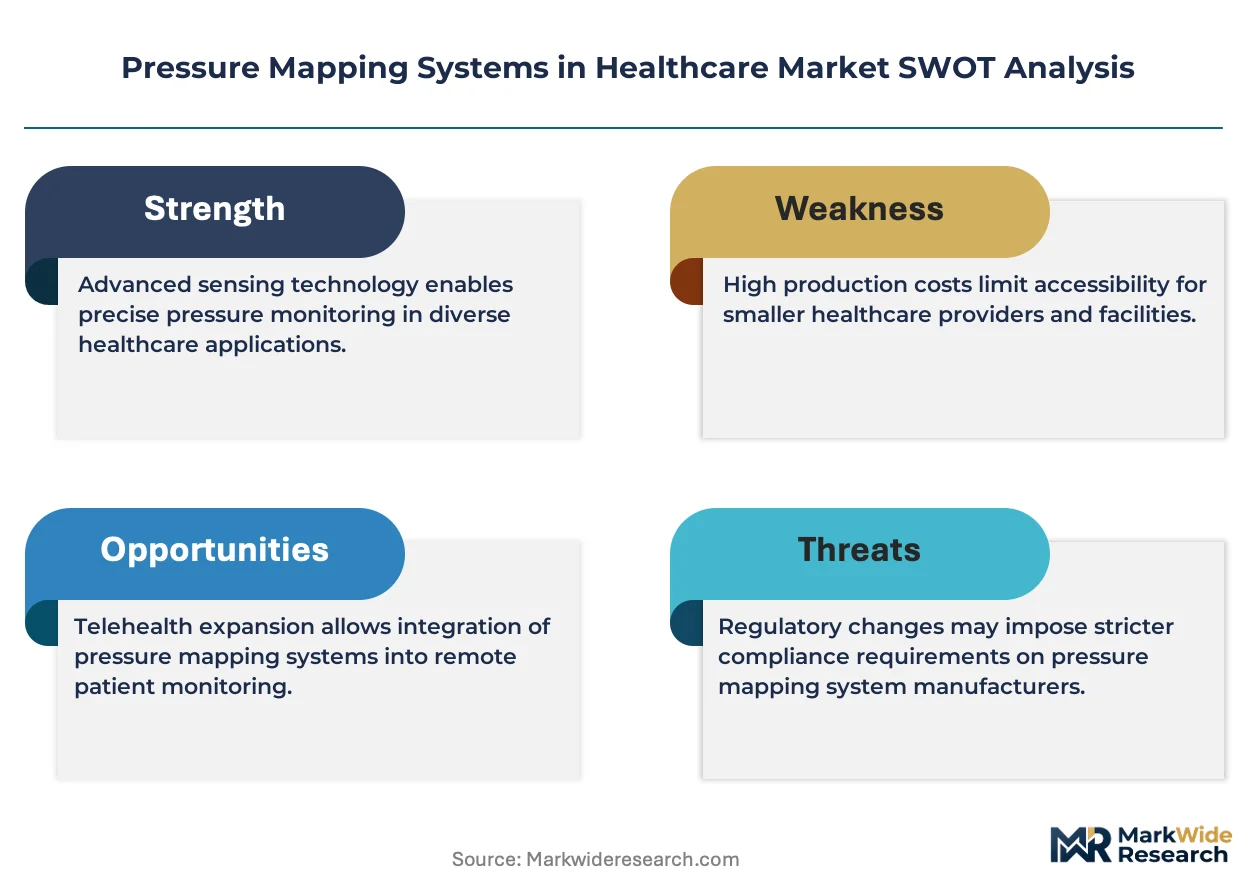
ISO 13485 certification compression from thirty-six to eighteen months for established manufacturers is intensifying competitive moats while excluding new entrants from premium procurement channels. This structural acceleration favors incumbents with captive sensor fabrication and existing notified body relationships.
Growth Catalysts
- Statutory health insurance reimbursement:Germany's wound care protocol coverage creates dedicated procurement channels for mattress-integrated systems in long-term care facilities.
- FDA 510(k) pathway compression:Digital health sensor premarket notification timelines are shortening commercialization cycles for US hospital procurement.
- Piezoresistive sensor arrays:Advances in force-sensitive element density enable sub-millimeter spatial resolution for pressure ulcer prevention programs.
Market Restraints
- Electromagnetic sensor sterilization costs:Hospital bed installations face recurring replacement expenses that strain capital equipment budgets.
- EU MDR clinical evidence requirements:Stricter conformity assessment intervals lengthen time-to-market for Class IIa systems without existing notified body relationships.
- Capacitive drift sensitivity:Humidity-dependent calibration requirements limit deployment in community care settings with variable climate control.
Strategic Opportunities
- Cloud-based pressure analytics:CDSCO software-as-medical-device pathways in India will determine licensing requirements for remote patient monitoring dashboards.
- Electronic health record integration:Software Solutions segment captures recurring revenue through API connectivity with Cerner and Epic workflows.
- Turnkey film kit channels:Cost-sensitive clinics bypass electronic calibration through single-use pressure-indicating consumables.
Industry Challenges
- Notified body capacity scarcity:EU MDR transition bottlenecks delay conformity assessments for sensor-software integrated systems.
- Biomedical engineer training gaps:Facilities lack personnel capable of interpreting spatial pressure distribution data for clinical decision-making.
- Legacy bed infrastructure incompatibility:Electromagnetic sensor retrofitting requires mechanical redesign of existing hospital mattress platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Mapping Systems in Healthcare Market |
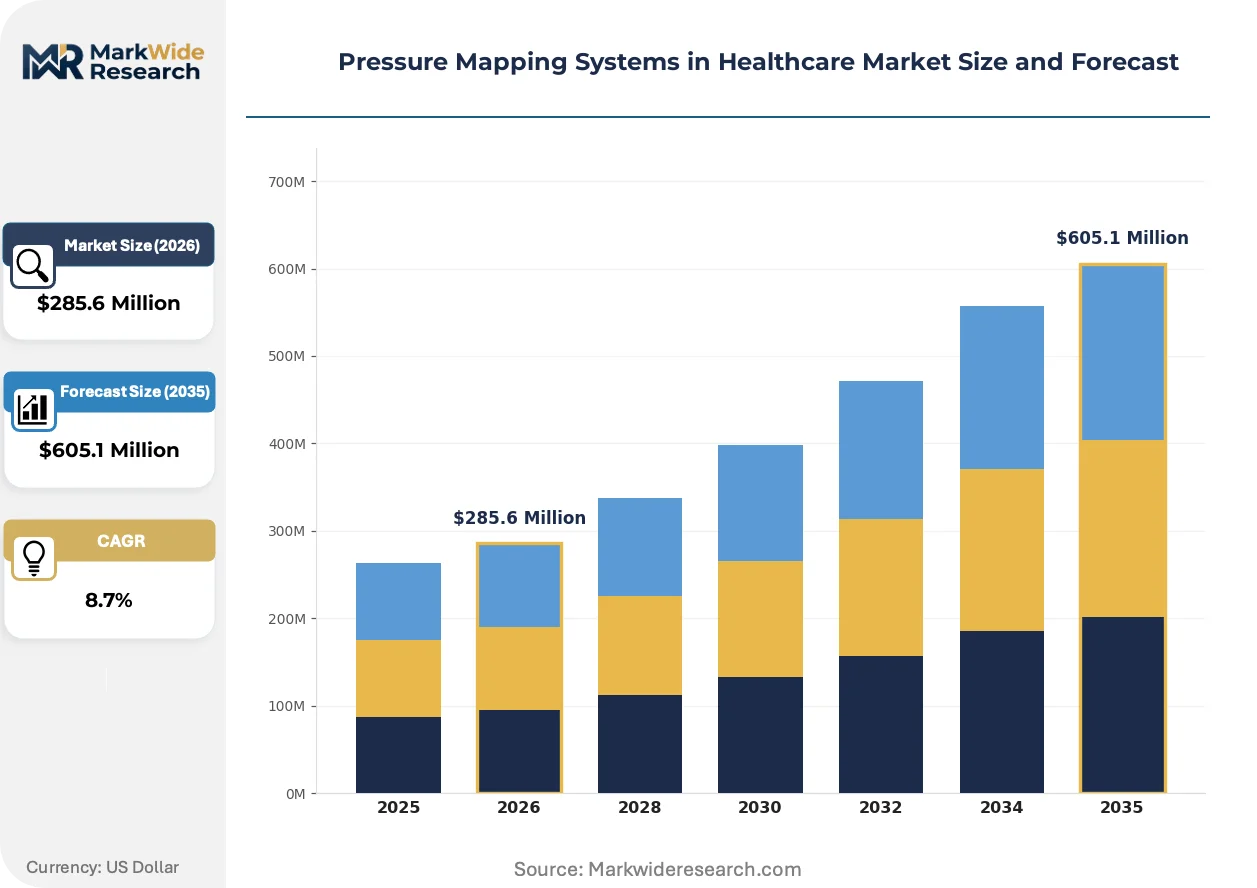
| Market Size in 2026 | $285.6 Million |
| Market Size in 2035 | $605.1 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Stationary Systems, Software Solutions, Sensor Arrays End User: Hospitals, Clinics, Nursing Homes, Home Care Technology: Electromagnetic Sensors, Capacitive Sensors, Optical Sensors, Ultrasound Technology Application: Pressure Ulcer Prevention, Medical Research, Rehabilitation, Gait Analysis |
| Companies Covered | Tekscan, Inc., Sensor Products Inc., PPS, XSENSOR Technology Corporation, Vista Medical, FSRTEK, Blue Chip Medical Products, Pressure Profile Systems, Xsensor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Mapping Systems in Healthcare Market Strategic Shifts & Innovations
Sensor array architectures and regulatory data pathways are converging to reshape how pressure mapping systems penetrate preventive care protocols. Three developments dominate this transformation.
Flexible printed circuit piezoresistive arrays are miniaturizing from centimeter-scale modules to millimeter-scale nodes that embed directly into textile surfaces. Rehabilitation centers and wheelchair seating clinics in the Netherlands and Sweden are piloting these substrate-integrated systems for continuous monitoring. This form factor compression is miniaturizing the boundary between diagnostic equipment and consumable medical supplies, collapsing traditional capital equipment depreciation cycles.
The EU Medical Device Regulation's post-market surveillance requirements are mandating real-world performance data collection for Class IIa sensor systems. Manufacturers must now maintain clinical follow-up registries that track pressure ulcer incidence outcomes across installed bases. German long-term care chains and French hospital networks are responding by demanding cloud-native analytics platforms with automated adverse event reporting pipelines.
Hospital procurement departments are unbundling hardware acquisition from software subscription licensing for pressure mapping platforms. This separates capital budget approvals from recurring operational expenditures, accelerating pilot deployments while extending vendor relationship timelines. The purchasing pattern is most pronounced in US academic medical centers and Canadian provincial health authorities consolidating vendor management under centralized digital health contracts.
Pressure Mapping Systems in Healthcare Market Segmentation
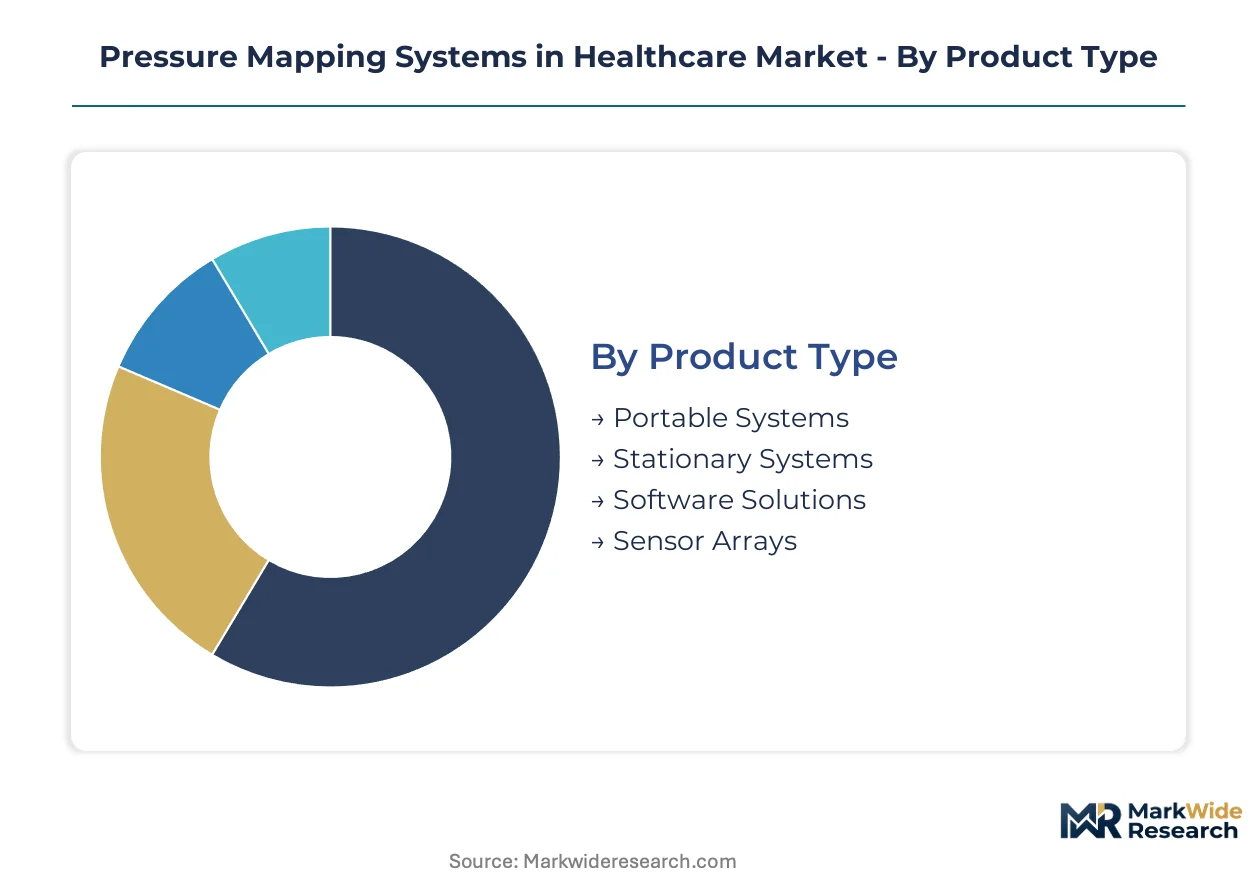
Pressure mapping systems fragment across hardware, software, and service layers that face diverging substitution threats from alternative wound monitoring technologies. Understanding segment boundaries reveals where pricing power concentrates and where commoditization pressure erodes margins.
Product Type:
Portable systems face the most acute substitution pressure from smartphone-connected force plates and wearable pressure monitors that bypass dedicated hardware procurement entirely.
- Portable Systems:Battery-powered units with wireless data transmission enable bedside assessments and wheelchair seating clinics without fixed infrastructure. Demand concentrates in US outpatient rehabilitation centers where Medicare reimbursement for pressure ulcer risk assessment drives portable unit procurement over capital-intensive installations.
- Stationary Systems:Fixed installations integrate directly into hospital beds and operating tables with continuous monitoring capabilities. German statutory health insurance reimbursement for mattress-integrated platforms sustains demand in long-term care facilities despite higher per-unit costs.
- Software Solutions:Cloud analytics platforms and EHR integration modules capture recurring subscription revenue.
- Sensor Arrays:Modular force-sensitive element configurations allow customization of spatial resolution and sensing area.
Stationary systems retain volume leadership; software solutions hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-rich hospital systems from budget-constrained community settings with diverging procurement patterns.
- Hospitals:Academic medical centers and tertiary care facilities deploy comprehensive pressure mapping across ICUs, operating rooms, and wound care units. US academic medical centers are unbundling hardware from software licensing to accelerate pilot deployments under centralized digital health contracts.
- Nursing Homes:Long-term care facilities in Germany and the Netherlands are expanding pressure ulcer prevention programs with mattress-integrated systems. Statutory reimbursement protocols in these markets create dedicated procurement channels distinct from discretionary capital budgets.
- Clinics:Outpatient wound care centers and rehabilitation clinics favor portable or disposable solutions.
- Home Care:Remote patient monitoring applications are emerging but face reimbursement coding uncertainties.
Hospitals dominate absolute spending; nursing homes are climbing the fastest as regulatory pressure ulcer prevention mandates expand.
Technology:
Supply concentration in sensor fabrication creates margin capture opportunities for manufacturers with captive production capabilities.
- Electromagnetic Sensors:Simpler sterilization protocols and lower replacement costs sustain the largest installed base in hospital bed applications. Humidity resistance and drift stability make these sensors suitable for climate-variable community care settings where capacitive alternatives fail.
- Capacitive Sensors:Superior spatial resolution and humidity-independent calibration justify premium positioning in research and rehabilitation settings. Netherlands and Swedish rehabilitation centers are piloting substrate-integrated capacitive arrays for continuous wheelchair seating monitoring.
- Optical Sensors:Camera-based pressure visualization offers non-contact measurement for specific research applications.
- Ultrasound Technology:Emerging modality for tissue perfusion assessment beneath pressure points.
Electromagnetic sensors retain volume leadership; capacitive sensors hold the steepest expansion curve.
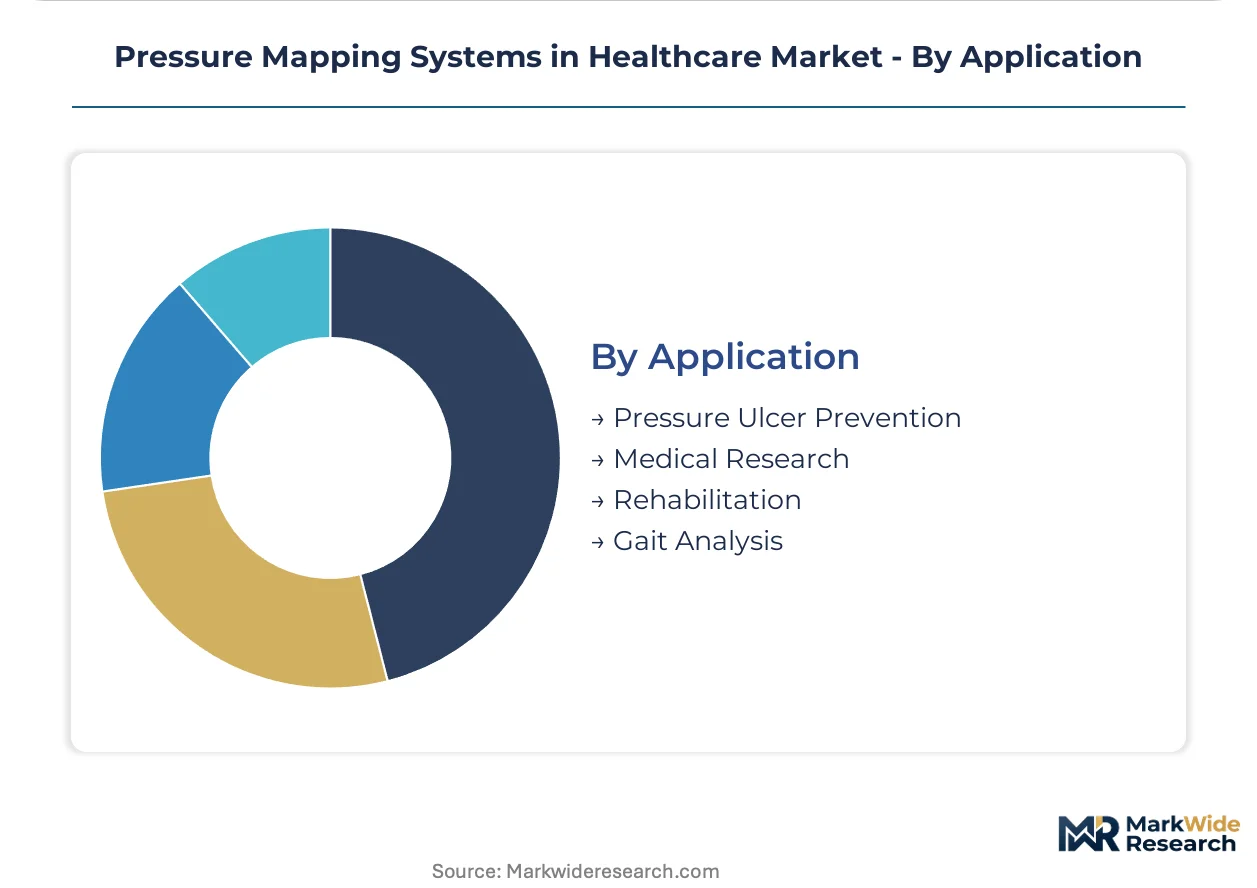
Application:
Maturity differentiation separates established clinical protocols from emerging research frontiers with diverging evidence requirements.
- Pressure Ulcer Prevention:The dominant clinical application with established reimbursement pathways in Germany, the US, and the Netherlands. CMS coverage decisions and statutory insurance protocols in European markets are shifting these systems from capital equipment toward standard-of-care consumables.
- Gait Analysis:Rehabilitation and sports medicine applications demand higher spatial resolution and temporal sampling rates. Research hospitals in Sweden and the Netherlands are deploying advanced pressure mapping for post-surgical mobility assessment and prosthetic fitting optimization.
- Medical Research:Biomechanics and tissue engineering studies drive demand for laboratory-grade precision.
- Rehabilitation:Wheelchair seating and pressure redistribution optimization in spinal cord injury units.
Pressure ulcer prevention retains volume leadership; gait analysis holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Statutory health insurance reimbursement protocols in Germany have established the most mature procurement channel for mattress-integrated pressure mapping systems. FDA 510(k) clearance compression in the United States is accelerating hospital procurement cycles for digital health sensors. CDSCO software-as-medical-device pathways in India will determine licensing frameworks for cloud-based pressure analytics platforms.
United States
Medicare reimbursement for pressure ulcer risk assessment drives portable unit procurement in outpatient rehabilitation centers. FDA 510(k) premarket notification pathways for digital health sensors are shortening commercialization timelines. Academic medical centers in Boston and the Research Triangle are unbundling hardware acquisition from software subscription licensing.
Germany
Statutory health insurance coverage for pressure mapping in wound care protocols creates dedicated procurement channels for long-term care facilities. EU Medical Device Regulation post-market surveillance requirements mandate real-world performance data collection for Class IIa sensor systems. Long-term care chains in North Rhine-Westphalia are demanding cloud-native analytics platforms with automated adverse event reporting.
Netherlands
Rehabilitation centers are piloting substrate-integrated capacitive arrays for continuous wheelchair seating monitoring. EU MDR conformity assessment intervals for sensor-software integrated systems face notified body capacity scarcity. Eindhoven Region medical technology clusters are developing millimeter-scale piezoresistive nodes that embed directly into textile surfaces.
Sweden
Research hospitals deploy advanced pressure mapping for post-surgical mobility assessment and prosthetic fitting optimization. EU MDR clinical evidence requirements lengthen time-to-market for manufacturers without existing notified body relationships. Stockholm and Gothenburg rehabilitation centers are testing continuous monitoring systems for spinal cord injury units.
India
The country's national pharmaceutical regulator and CDSCO are developing parallel pathways for software-as-medical-device classifications. Cloud-based pressure analytics licensing requirements remain undetermined for remote patient monitoring dashboards. Bangalore and Hyderabad health technology corridors are attracting pilot deployments for preventive care protocol integration.
Pressure Mapping Systems in Healthcare Market Key Industry Players
Player mix skews toward established sensor fabricators with captive manufacturing capabilities and ISO 13485 quality management certification. Market structure concentrates around three strategic archetypes: piezoresistive array specialists with in-house fabrication, turnkey consumable providers bypassing electronic calibration, and software-integrated platform vendors capturing recurring subscription revenue. Dominant competitive moves include backward integration into force-sensitive element production and strategic partnerships with electronic health record vendors for API connectivity.
Within the established manufacturer tier, Tekscan, Inc. and XSENSOR Technology Corporation exemplify sensor-fabrication-centric positioning, while Sensor Products Inc. occupies a distinct niche in calibration-free consumable solutions. Tekscan, Inc. represents the piezoresistive specialist archetype with Massachusetts-based operations. XSENSOR Technology Corporation anchors Canadian and US long-term care facility penetration. Sensor Products Inc. exemplifies the cost-sensitive clinic targeting strategy through pressure-indicating film kit channels.
| Leading Market Players |
|---|
| Tekscan, Inc. |
| Sensor Products Inc. |
| PPS |
| XSENSOR Technology Corporation |
| Vista Medical |
| FSRTEK |
| Blue Chip Medical Products |
| Pressure Profile Systems |
| Xsensor |
| Others |
Cost & Logistics Intelligence
Eighteen-month ISO 13485 certification cycles for established manufacturers concentrate pricing power with incumbents possessing captive sensor fabrication and existing notified body relationships, while compressing procurement timelines for compliant systems.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA 510(k)-cleared and EU MDR Class IIa-certified systems commanding substantial premiums over uncertified alternatives. Pricing stratifies across ISO 13485-certified premium systems, CE-marked standard platforms, and economy-grade unbundled sensor arrays. Cost compression in the economy tier intensifies because smartphone-connected force plates and wearable monitors bypass dedicated hardware procurement entirely. Nursing homes and community clinics exhibit the highest price sensitivity, while German long-term care chains with statutory reimbursement coverage show the least.
Supply Chain Analysis
Massachusetts and Alberta anchor piezoresistive sensor fabrication and mattress-integrated platform assembly respectively, with Taiwan supplying specialized flexible printed circuit substrates. Force-sensitive element arrays, textile-embedding substrates, and cloud analytics infrastructure constitute critical input dependencies. Single-source vulnerability concentrates in notified body relationships for EU MDR conformity assessments, where capacity scarcity delays market entry. Distribution runs through hospital procurement departments unbundling hardware from software subscriptions, GPO contracts for long-term care chains, and direct sales to rehabilitation clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized biomedical engineering talent capable of interpreting spatial pressure distribution data for clinical decision-making remains scarce, constraining facility adoption regardless of hardware availability.
For Market Incumbents: Shield installed base relationships by deepening backward integration into millimeter-scale piezoresistive node production and accelerating ISO 13485 certification cycles below eighteen months to exclude emerging competitors. Prioritize API connectivity investments with Cerner and Epic to lock in EHR-integrated recurring revenue streams before software-as-medical-device pathways mature in India. For New Entrants and Emerging Players: Anchor in cost-sensitive clinic segments with calibration-free pressure-indicating film kits that bypass electronic complexity and electromagnetic sensor sterilization costs. Target India's CDSCO software-as-medical-device classification window for cloud-based pressure analytics licensing before requirements solidify. Pursue turnkey consumable positioning rather than capital equipment competition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial sensor manufacturers with dormant healthcare divisions possessing captive fabrication but lacking regulatory relationships. Five-to-ten-year viability hinges on reimbursement coding shifts from capital equipment to preventive care consumables. Monitor CMS coverage decisions and German statutory insurance protocol expansions as inflection indicators for standard-of-care reclassification.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | Eighteen-month cycles compress competitive moats and exclude new entrants from premium procurement channels. |
| EHR API Integration Partnership | Cerner and Epic connectivity locks in recurring software subscription revenue across US academic medical centers. |
| CDSCO SaMD Pathway Navigation | Early licensing for cloud-based pressure analytics in India establishes regulatory precedent before requirements solidify. |
| Millimeter-Scale Node Miniaturization | Textile-embedded piezoresistive arrays collapse capital equipment depreciation cycles into consumable supply models. |
| Post-Market Surveillance Registry | EU MDR-mandated real-world performance data collection satisfies German long-term care chain procurement requirements. |
Research Approach
Desk research of FDA 510(k) clearance databases, EU MDR notified body registration records, and German statutory health insurance reimbursement protocols preceded structured interviews with hospital procurement managers, biomedical engineers, long-term care facility administrators, and GPO contracts specialists. Secondary validation drew from CMS Medicare coverage determinations, CDSCO software-as-medical-device consultation papers, and ISO 13485 certification body disclosure filings. Bottom-up unit shipment estimates across portable systems, stationary installations, and software subscriptions triangulated against top-down healthcare capital expenditure surveys.
Variance decomposition across product type, end user, technology, and application dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs included pressure ulcer incidence reporting data from Dutch and Swedish rehabilitation pilots, US nursing home staffing ratio correlations with prevention program adoption, and EU MDR transition timelines affecting conformity assessment bottlenecks.
Material uncertainties — reimbursement coding revisions by CMS and analogous agencies, notified body capacity constraints for EU MDR Class IIa assessments, and CDSCO final SaMD classification determinations — sit outside the modeled envelope. Forecasts reflect assumptions regarding statutory insurance protocol stability and digital health sensor regulatory pathway continuity. Recalibration cycles align with material shifts in preventive care coverage decisions and software-as-medical-device licensing frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
Wrist Fixator Procedure Kit Market
Medical Devices
Hearing Devices 3D Printing Market
Medical Devices
Expandable Interbody Fusion System Market
Medical Devices
Germanium-68/Gallium-68 Generators Market
Medical Devices
Respiratory Oxygen Delivery Devices Market
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market
Medical Devices
Digital Intraoral Sensors and Consumables Market
Medical Devices
Europe Ambulatory Infusion Pumps Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Non-Invasive Brain Trauma Monitoring Devices Market
Medical Devices
Artificial Retina Market
Medical Devices
Software As a Medical Device Market
Medical Devices
Specimen Retrieval Nets Market
Medical Devices
Neonatal Hearing Screening Devices Market