
 Smart Wheelchairs Market | 2026-2036
Smart Wheelchairs Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Wheelchairs Market Intelligence
Lithium-ion battery packs are rebalancing cost structures against legacy lead-acid systems in powered mobility. Permobil AB leverages Scandinavian manufacturing scale to dominate premium electric wheelchair supply chains. Drive DeVilbiss Healthcare anchors North American distribution through durable medical equipment networks. Ottobock specializes in mechatronic seating systems that integrate pressure-mapping sensors for pressure-ulcer prevention.
Smart wheelchairs are motorized mobility platforms incorporating microprocessor-controlled drive systems, obstacle-detection arrays, and connectivity modules for remote diagnostics and fleet management. These platforms typically operate on 24-volt DC architectures with brushless hub motors rated for 200-400 watts continuous output, enabling terrain-adaptive propulsion for users with spinal cord injury, multiple sclerosis, or age-related ambulatory limitation. Electric wheelchairs command the dominant revenue share due to reimbursement alignment and institutional procurement patterns, while autonomous navigation technology represents the fastest-expanding capability segment as computer-vision costs decline. Home care end users generate concentrated margin pools because direct-to-consumer channels bypass distributor markups and enable subscription-based remote monitoring services.
FDA 510(k) pathways and ISO 7176 standards jointly govern electromechanical safety, electromagnetic compatibility, and crash-test performance for powered wheelchairs in the United States. The EU Medical Device Regulation requires notified-body certification for Class I and II mobility aids, while Japan's PMDA enforces JIS T 9203 structural integrity benchmarks. Stakeholders must monitor how FDA software-as-a-medical-device guidance applies to over-the-air firmware updates for autonomous navigation algorithms.
Market Dynamics
Computer-vision cost compression is dismantling the price barrier between powered mobility and autonomous navigation, forcing manufacturers to restructure R&D allocation toward sensor fusion and edge-computing architectures.
Growth Catalysts
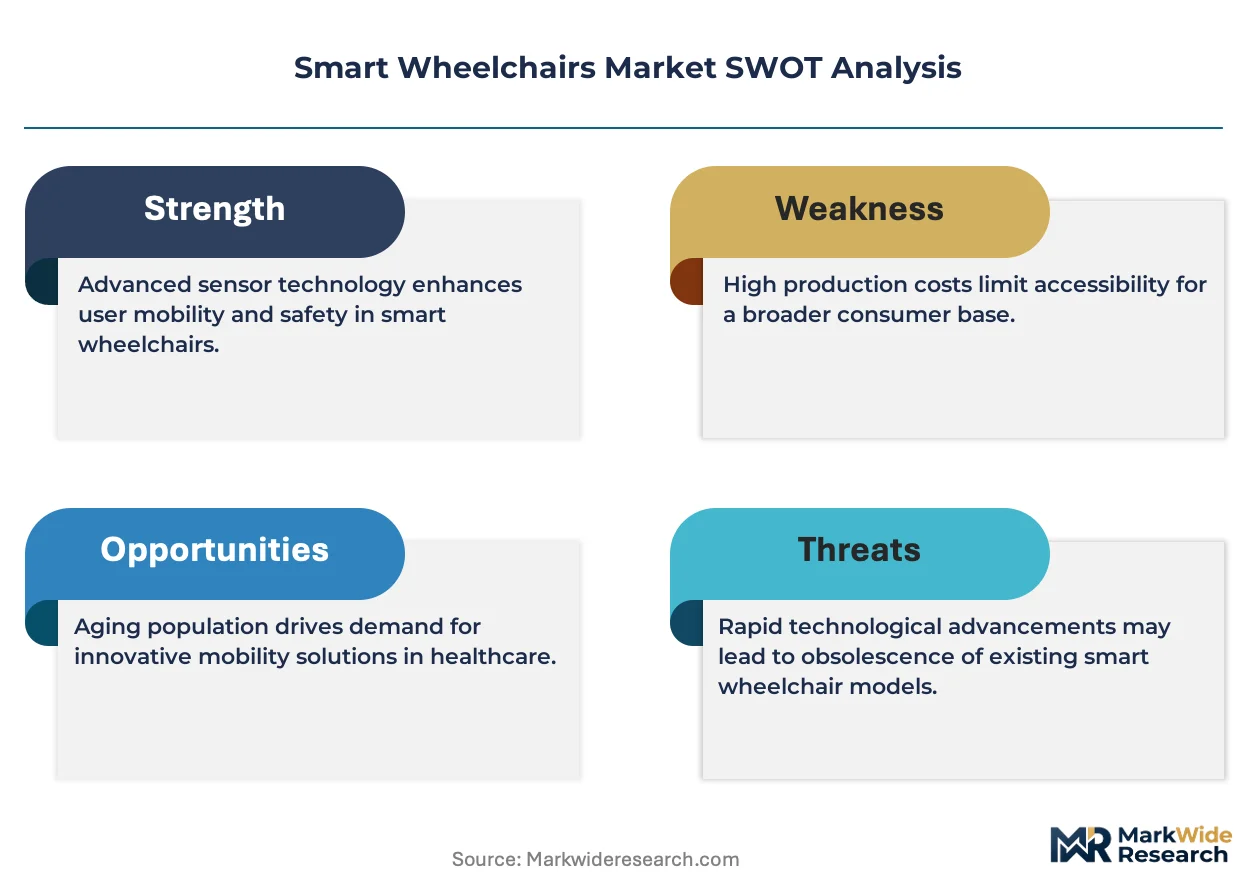
- ISO 7176 crash-test harmonization:Unified electromechanical safety benchmarks across export markets reduce recertification costs for manufacturers scaling production.
- Home care transition acceleration:Clinic-to-home discharge protocols in Japan's elderly care infrastructure expand addressable demand for remote-monitoring-enabled platforms.
- Lithium-ion chemistry maturation:Energy density improvements in battery packs extend range-per-charge specifications while reducing weight penalties against legacy lead-acid systems.
Market Restraints
- Brushless motor supply concentration:Hub motor fabrication capacity clusters in East Asian manufacturing zones, exposing procurement to logistics volatility.
- FDA software-as-a-medical-device friction:Over-the-air firmware update protocols for autonomous navigation algorithms trigger extended premarket review timelines.
- Manual wheelchair substitution:Lightweight carbon-fiber frame alternatives satisfy ambulatory-limited users without powered assist requirements at lower reimbursement thresholds.
Strategic Opportunities
- Subscription-based remote diagnostics:Direct-to-consumer telemetry services bypass durable medical equipment distributor markups and capture recurring revenue streams.
- METI robotics funding alignment:Japanese Ministry of Economy, Trade and Industry grants for elderly care automation subsidize sensor-equipped platform adoption in residential settings.
- Pressure-mapping sensor convergence:Integration of mechatronic seating with ulcer-prevention algorithms opens reimbursement codes in wound-care management verticals.
Industry Challenges
- Firmware validation competency gaps:Embedded systems engineering talent scarcity delays autonomous navigation certification submissions.
- EU MDR notified-body bottlenecks:Class II mobility aid certification queue lengths extend time-to-market for electromechanical safety submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Wheelchairs Market |
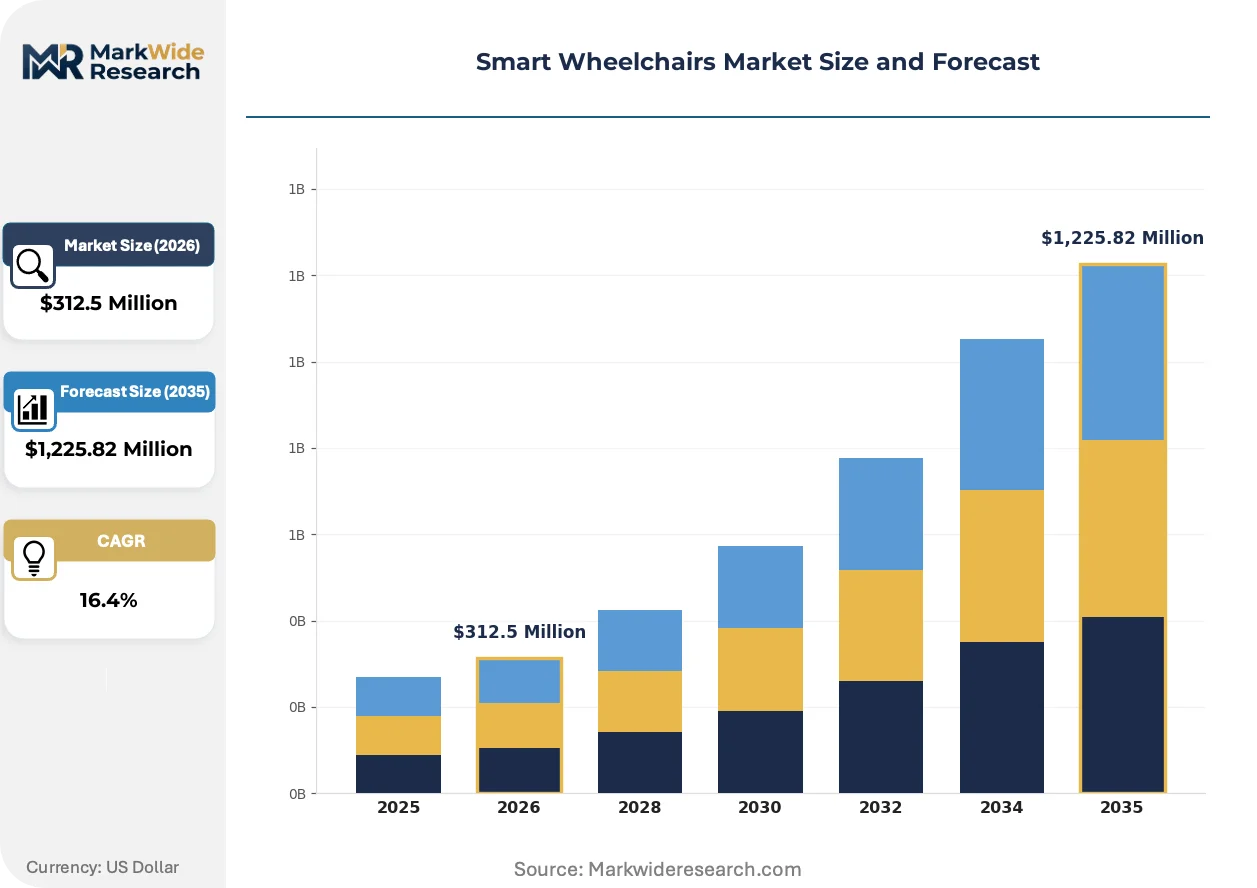
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,225.82 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Wheelchairs, Manual Wheelchairs, Powered Assist Devices, Hybrid Models Technology: IoT Integration, Sensor-Based Control, Autonomous Navigation, Voice Control End User: Healthcare Facilities, Home Care, Rehabilitation Centers, Elderly Users Application: Mobility Assistance, Accessibility Solutions, Rehabilitation Support, Daily Activities |
| Companies Covered | Permobil AB, Drive DeVilbiss Healthcare, Pride Mobility Products, Karman Healthcare, Ottobock, Invacare Corporation, Sunrise Medical, Satcon Medical, Golden Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Wheelchairs Market Strategic Shifts & Innovations
Autonomous navigation capability is migrating from premium tier to mid-market specification through component cost deflation and reimbursement code expansion.
Lidar arrays paired with depth-sensing cameras are integrating into 24-volt DC drive architectures to enable real-time obstacle classification and path planning without caregiver intervention. Rehabilitation centers in Germany are piloting these sensor fusion platforms for spinal cord injury patient cohorts. The technology is integrating fleet management APIs that compress service dispatch costs for institutional procurement officers.
Japan's PMDA has tightened JIS T 9203 structural integrity enforcement for powered wheelchairs with over-the-air update capability, treating navigation algorithm revisions as design changes requiring supplemental review. Manufacturers are responding by segregating hardware and software certification tracks to isolate firmware volatility from base platform approvals. This regulatory posture most affects Class II mobility aids targeting clinic-to-home transition use cases.
Institutional buyers are consolidating vendor relationships around platforms offering unbundled after-sales telemetry subscriptions rather than bundled maintenance contracts. Durable medical equipment networks in North America are losing volume to manufacturer-direct channels that capture margin through remote diagnostics recurring fees. This channel disintermediation is most pronounced in home care end-use segments where reimbursement flexibility permits direct purchasing authority.
Smart Wheelchairs Market Segmentation
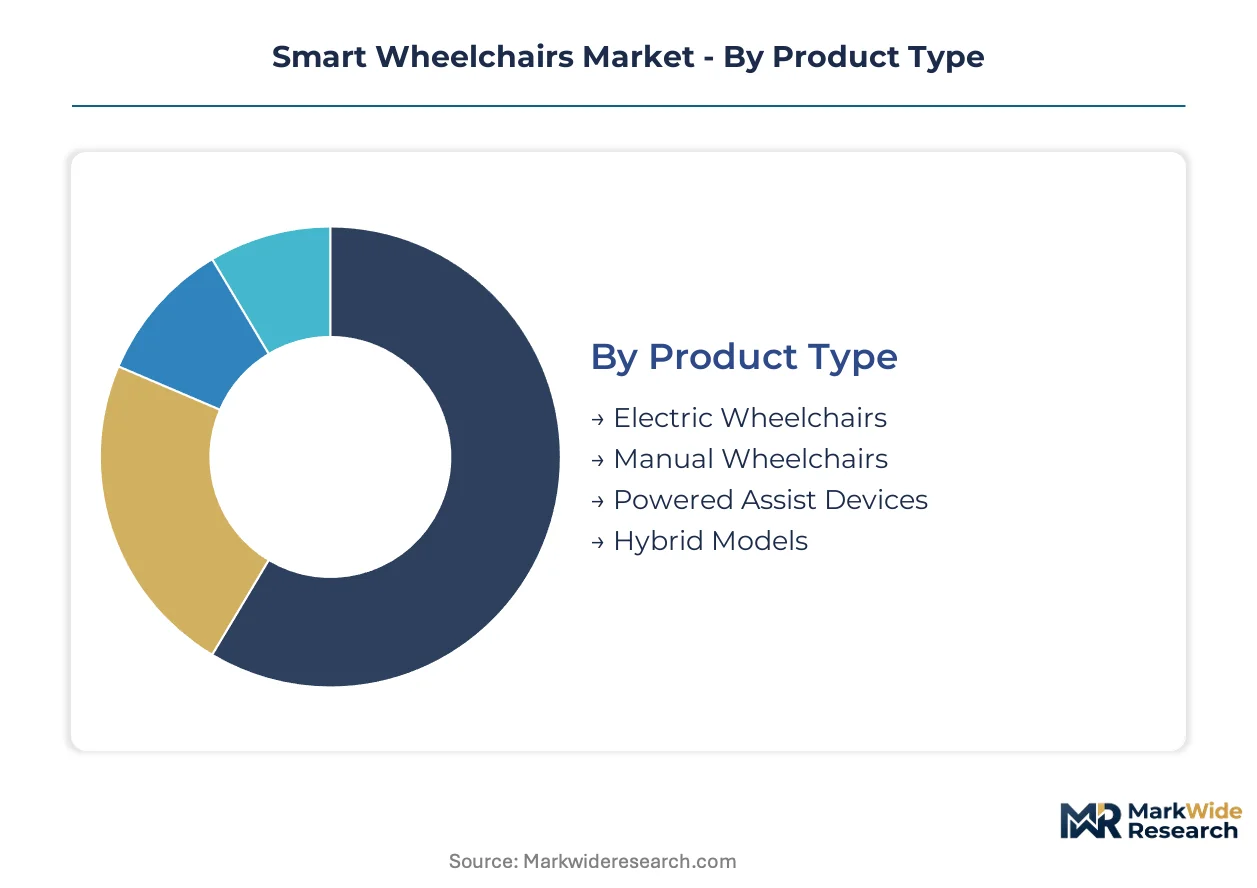
Segmentation in smart wheelchairs determines reimbursement pathways, manufacturing scale requirements, and R&D allocation across electromechanical platforms. Product architecture and technology integration level dictate pricing tiers and regulatory classification, while end-user concentration shapes channel strategy and service model design.
Product Type:
Standardization dominates at the base with electric propulsion systems, while customization intensifies toward sensor-fusion and hybrid architectures that blend powered and manual operation.
- Electric Wheelchairs:24-volt DC brushless hub motor platforms with microprocessor-controlled drive systems and programmable seating configurations. Rehabilitation centers in Germany concentrate procurement of these units for spinal cord injury cohorts, driven by ISO 7176 crash-test harmonization reducing cross-border certification costs.
- Manual Wheelchairs:Lightweight carbon-fiber or aluminum frame structures without powered assist, satisfying ambulatory-limited users at lower reimbursement thresholds. Home care demand in Japan favors these for clinic-to-home transitions where METI robotics funding does not extend to full electromechanical platforms.
- Powered Assist Devices:Add-on motor systems converting manual frames to hybrid operation.
- Hybrid Models:Dual-mode architectures switching between manual propulsion and electric assist.
Leading the category by volume: Electric Wheelchairs. Growing fastest: Hybrid Models.
Technology:
Maturity gradients separate established connectivity modules from emerging autonomous stacks requiring firmware validation competencies and extended regulatory review.
- Autonomous Navigation:Lidar arrays paired with depth-sensing cameras enabling real-time obstacle classification and path planning without caregiver intervention. Rehabilitation centers in Germany pilot these sensor fusion platforms, with PMDA in Japan treating algorithm revisions as design changes requiring supplemental review.
- IoT Integration:Connectivity modules transmitting telemetry for remote diagnostics and fleet management API access. Institutional buyers in North America consolidate vendor relationships around unbundled subscription services rather than bundled maintenance contracts.
- Sensor-Based Control:Pressure-mapping and tilt sensors integrated into mechatronic seating systems.
- Voice Control:Natural language interfaces for hands-free operation of drive and seating functions.
Autonomous Navigation commands premium pricing tiers. IoT Integration expands most quickly through direct-to-consumer channel disintermediation.
End User:
Procurement authority and reimbursement flexibility create divergent margin structures across institutional and residential settings.
- Home Care:Direct-to-consumer purchasers bypassing durable medical equipment distributor markups through manufacturer-direct channels. Japan's elderly care infrastructure accelerates clinic-to-home discharge protocols, expanding addressable demand for remote-monitoring-enabled platforms.
- Healthcare Facilities:Hospital and long-term care procurement officers consolidating around fleet management APIs that compress service dispatch costs. FDA 510(k) pathways govern electromechanical safety submissions for institutional deployment.
- Rehabilitation Centers:Specialized facilities requiring terrain-adaptive propulsion for spinal cord injury and multiple sclerosis patient cohorts.
- Elderly Users:Age-related ambulatory limitation demographic with concentrated demand in Japan's residential automation subsidies.
Home Care generates concentrated margin pools. Rehabilitation Centers drive technology specification for terrain-adaptive capabilities.
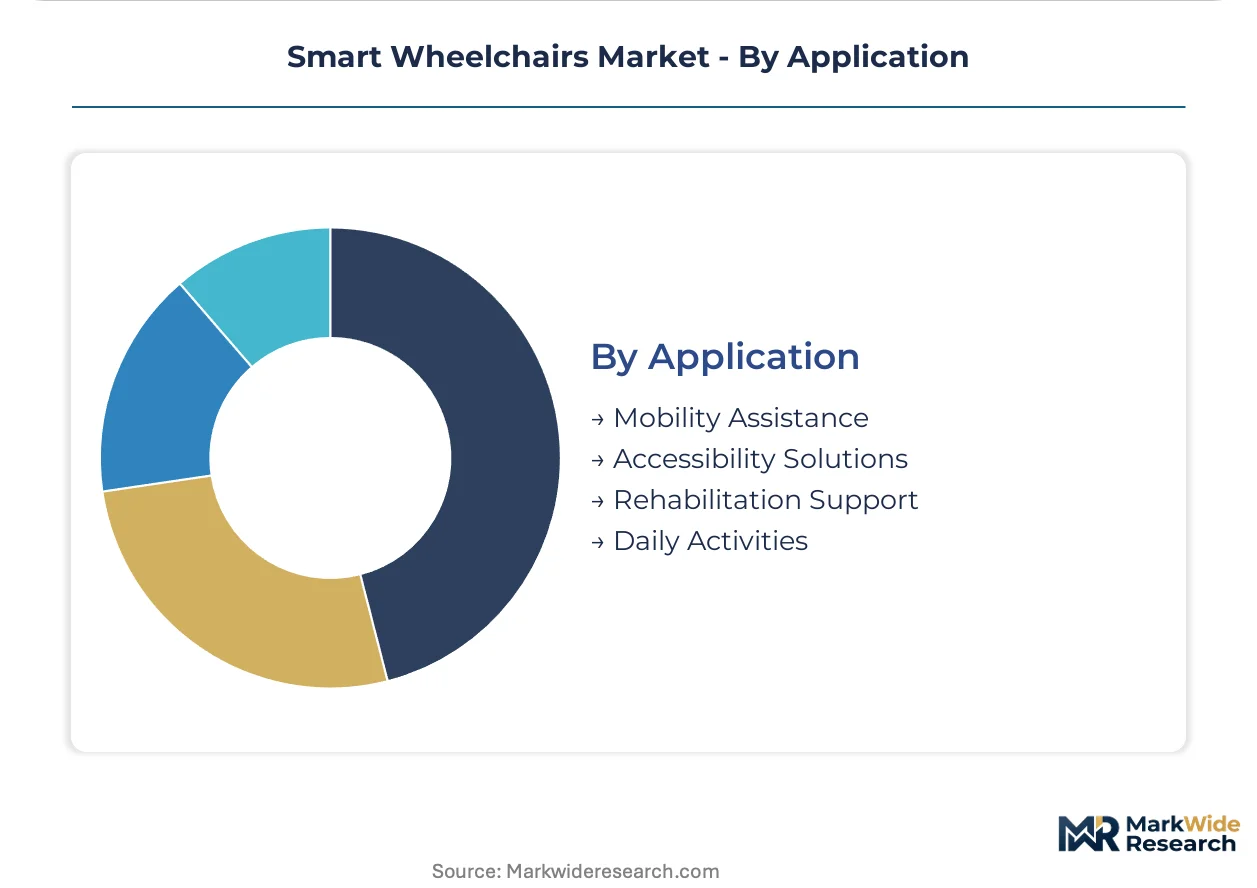
Application:
Functional scope ranges from basic mobility to integrated wound-care management verticals opening additional reimbursement codes.
- Mobility Assistance:Core propulsion and seating functions addressing spinal cord injury, multiple sclerosis, and age-related ambulatory limitation. Lithium-ion chemistry maturation extends range-per-charge specifications while reducing weight penalties against legacy lead-acid systems.
- Rehabilitation Support:Clinic-to-home transition protocols incorporating telemetry for post-discharge monitoring. Japan's METI funding for elderly care robotics accelerates adoption of sensor-equipped platforms in residential settings.
- Accessibility Solutions:Environmental navigation and barrier mitigation for built environment compliance.
- Daily Activities:Task-specific configurations for domestic and community participation.
Mobility Assistance anchors baseline demand. Rehabilitation Support climbs the fastest through pressure-mapping sensor convergence with ulcer-prevention algorithms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan concentrates demand through METI robotics funding for elderly care automation, while Germany and the United States anchor institutional procurement volumes for sensor-equipped mobility platforms. Regulatory divergence across FDA, EU MDR, and PMDA frameworks shapes certification strategies for manufacturers targeting multiple jurisdictions.
United States
Home care transitions and direct-to-consumer channel expansion drive procurement of remote-monitoring-enabled platforms. FDA 510(k) pathways govern electromechanical safety submissions, with software-as-a-medical-device guidance applying to over-the-air firmware updates. Greater Boston and Pacific Northwest clusters host rehabilitation centers piloting terrain-adaptive propulsion systems for spinal cord injury cohorts.
Germany
Rehabilitation centers expand procurement of lidar-equipped sensor fusion platforms for post-discharge monitoring. EU Medical Device Regulation requires notified-body certification for Class II mobility aids, compressing time-to-market for electromechanical safety submissions. Bavaria's medical technology corridor concentrates R&D activity for pressure-mapping seating systems.
Japan
Clinic-to-home discharge protocols accelerate demand for telemetry-enabled residential platforms among elderly users. PMDA enforces JIS T 9203 structural integrity benchmarks, treating navigation algorithm revisions as design changes requiring supplemental review. Kanto region rehabilitation facilities pilot autonomous navigation systems with fleet management API integration.
United Kingdom
NHS procurement consolidation favors platforms offering unbundled after-sales telemetry subscriptions over bundled maintenance contracts. MHRA alignment with EU MDR transitional provisions governs Class I and II mobility aid certification. London-Southeast medical device clusters concentrate distribution networks for durable medical equipment channels.
South Korea
Aging demographic profiles expand addressable demand for powered assist devices in residential settings. MFDS enforces medical device quality management system requirements for electromechanical safety validation. Seoul Capital Area rehabilitation hospitals pilot hybrid-model platforms switching between manual propulsion and electric assist.
Smart Wheelchairs Market Key Industry Players
Strategic partnerships dominate the current landscape as manufacturers seek to compress development timelines for autonomous navigation capabilities. The vendor base stratifies across Scandinavian-scale producers, North American distribution anchors, and German mechatronic specialists. Three archetypes define positioning: premium-tier integrated platform builders, mid-market volume distributors, and seating-system component specialists. M&A activity and technology licensing agreements represent the primary competitive moves as computer-vision costs decline.
Among Scandinavian-origin integrated platform builders, Permobil AB exemplifies scale-driven manufacturing concentration. Drive DeVilbiss Healthcare and Ottobock occupy distinct positions within the competitive map—one anchoring North American distribution density, the other representing German mechatronic specialization in sensor-integrated seating systems. These three entities collectively illustrate how geographic manufacturing heritage and channel control differentiate positioning across reimbursement-aligned and direct-to-consumer segments.
| Leading Market Players |
|---|
| Permobil AB |
| Drive DeVilbiss Healthcare |
| Pride Mobility Products |
| Karman Healthcare |
| Ottobock |
| Invacare Corporation |
| Sunrise Medical |
| Satcon Medical |
| Golden Technologies |
| Others |
Cost & Logistics Intelligence
Captive battery pack production in East Asian manufacturing zones anchors both component supply security and gross margin stability for powered wheelchair assemblers. Scandinavian and German manufacturers leverage in-house lithium-ion cell integration to offset distributor markups in North American home care channels.
Pricing Analysis
Volume concentration in electric wheelchair procurement by German rehabilitation centers compresses per-unit margins, while autonomous navigation tiers command premium positioning through FDA software-as-a-medical-device certification overhead. Three-tier pricing structure across premium sensor-fusion, standard electric propulsion, and economy manual alternatives reflects reimbursement code stratification. Cost compression in computer-vision components is intensifying because lidar array prices are declining faster than brushless motor costs. Home care direct-to-consumer purchasers exhibit lowest price sensitivity due to subscription telemetry bundling, whereas institutional procurement officers in durable medical equipment networks face rigid reimbursement ceilings.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States operate hub-and-spoke patterns to compress service dispatch costs for fleet-managed institutional accounts. Brushless hub motor fabrication concentrates in China, South Korea, and Taiwan, creating single-source vulnerability for 24-volt DC drive architectures. Raw material dependencies span lithium carbonate for battery cells, rare-earth magnets for motor assemblies, and semiconductor wafers for sensor fusion processors. Tariff exposure on Chinese-sourced electronics components threatens margin stability for mid-market assemblers lacking captive cell production. Distribution runs through durable medical equipment networks in North America, direct-to-consumer manufacturer portals in Japan, and specialized rehabilitation equipment dealers in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA software-as-a-medical-device guidance and EU MDR notified-body certification create barrier-to-entry moats for players with embedded systems validation competencies.
For Market Incumbents: Cement firmware validation capabilities through acquisition of embedded systems engineering talent pools to isolate autonomous navigation volatility from base platform approvals. Deepen backward integration into lithium-ion cell assembly to offset East Asian motor supply concentration. Threats from lightweight carbon-fiber manual wheelchair substitution demand defensive certification investment in pressure-mapping seating convergence with wound-care reimbursement codes. For New Entrants and Emerging Players: Durable medical equipment distributors represent the most accessible channel partner type for bypassing incumbent fleet management API lock-in at German rehabilitation centers. White-space targets concentrate in METI-funded Japanese home care transitions where telemetry subscription bundling penetrates faster than institutional procurement cycles. The penetrable segment is hybrid-model platforms for South Korean aging demographics. Go-to-market execution should prioritize unbundled remote diagnostics service design over bundled maintenance contract replication. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by Scandinavian-scale integrated platform builders seeking North American distribution density. Long-term viability hinges on software-as-a-medical-device regulatory capacity rather than hardware manufacturing scale. Acquisition target archetype: mid-cap seating-system specialists with pressure-mapping sensor convergence and existing ISO 7176 crash-test harmonization. The inflection indicator to watch is PMDA supplemental review timeline compression for firmware update protocols, signaling regulatory maturation that rewards pre-positioned compliance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Over-the-air navigation algorithm updates require premarket review under FDA guidance for autonomous capabilities. |
| EU MDR Notified-Body Certification | Class II mobility aid approval through EU Medical Device Regulation unlocks German rehabilitation center procurement. |
| Hospital System Partnership | Fleet management API integration with NHS procurement consolidation captures recurring telemetry subscription revenue. |
| Software Companion Development | Remote diagnostics platforms bypass durable medical equipment distributor markups in North American home care. |
| Reimbursement Strategy | Pressure-mapping sensor convergence with ulcer-prevention algorithms opens wound-care management vertical codes. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this smart wheelchairs analysis. Primary interviews with rehabilitation center procurement officers, biomedical engineers, GPO contracts managers, and durable medical equipment distributors combined with FDA 510(k) databases, EU MDR notified-body certification registries, PMDA submission records, and METI robotics funding disclosures. Bottom-up unit shipment estimates triangulated against top-down reimbursement expenditure data.
Data-stream reconciliation across product type, technology integration level, end-user procurement authority, and application functional scope generated volume and value outputs. Segmentation dimensions modeled spanned electric versus manual versus hybrid architectures, autonomous navigation versus IoT connectivity versus sensor-based control, home care versus institutional settings, and mobility assistance versus rehabilitation support applications. CAGRs derived from trend extrapolation of lithium-ion chemistry maturation curves, computer-vision cost deflation rates, and clinic-to-home discharge protocol adoption across Japanese elderly care infrastructure.
Caveats apply where FDA software-as-a-medical-device guidance revisions, EU MDR notified-body queue extensions, or PMDA structural integrity enforcement shifts could materially shift the outlook for autonomous navigation certification timelines. Forecasts reflect stated assumptions regarding reimbursement code stability and battery chemistry cost curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Incontinence Devices and Ostomy Market
Medical Devices
Europe Nurse Call Systems Market
Medical Devices
Microscope Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Bronchial Thermoplasty Catheter Market
Medical Devices
Global Angioplasty Balloons Market
Medical Devices
Asia Pacific Apheresis Market
Medical Devices
Disposable Thermometer Market
Medical Devices
Surgical Display Market
Medical Devices
PDA Closure Devices Market
Medical Devices
Global Vertebral Compression Fracture Devices Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
South America C-Arms Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Global Pneumatic Tourniquets Market