
 Global Lyophilized Injectable Drugs Market | 2026-2036
Global Lyophilized Injectable Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lyophilized Injectable Drugs Market Foresight
Hospital group purchasing organization consolidation is realigning contract structures for lyophilized injectables toward fewer, larger volume agreements. Pfizer Inc. leverages its integrated sterile manufacturing network to secure multi-year supply contracts with these consolidated buyers. Novartis AG anchors its position through specialized oncology lyophilization capacity in European and North American facilities. Fresenius competes by extending its hospital dialysis and infusion therapy relationships into parallel injectable drug procurement channels.
Lyophilized injectable drugs are biopharmaceutical formulations dehydrated through freeze-drying to achieve chemical stability, typically requiring reconstitution with sterile diluent before parenteral administration, with residual moisture specifications below 3% to preserve protein integrity across ambient temperature distribution. Monoclonal antibodies dominate product type value pools due to high unit costs and complex stability requirements that mandate lyophilization, while vaccines represent the fastest-expanding category driven by mRNA platform adaptation to freeze-dried formats. Oncology leads therapy area allocation as checkpoint inhibitors and antibody-drug conjugates require lyophilized presentation to maintain potency through extended shelf life.
FDA current good manufacturing practice enforcement and EMA Annex 1 sterile product manufacturing requirements are elevating barrier technology and automated filling investments for lyophilized drug production. Japan's PMDA imposes additional local stability testing protocols that shape market entry sequencing for foreign manufacturers. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP chapters governing container closure integrity and reconstitution performance standards.
Market Dynamics
Hospital purchasing consolidation is compressing supplier margins while simultaneously demanding longer contract terms, forcing lyophilized injectable manufacturers to restructure capacity investments around predictable multi-year volume commitments rather than spot-market flexibility.
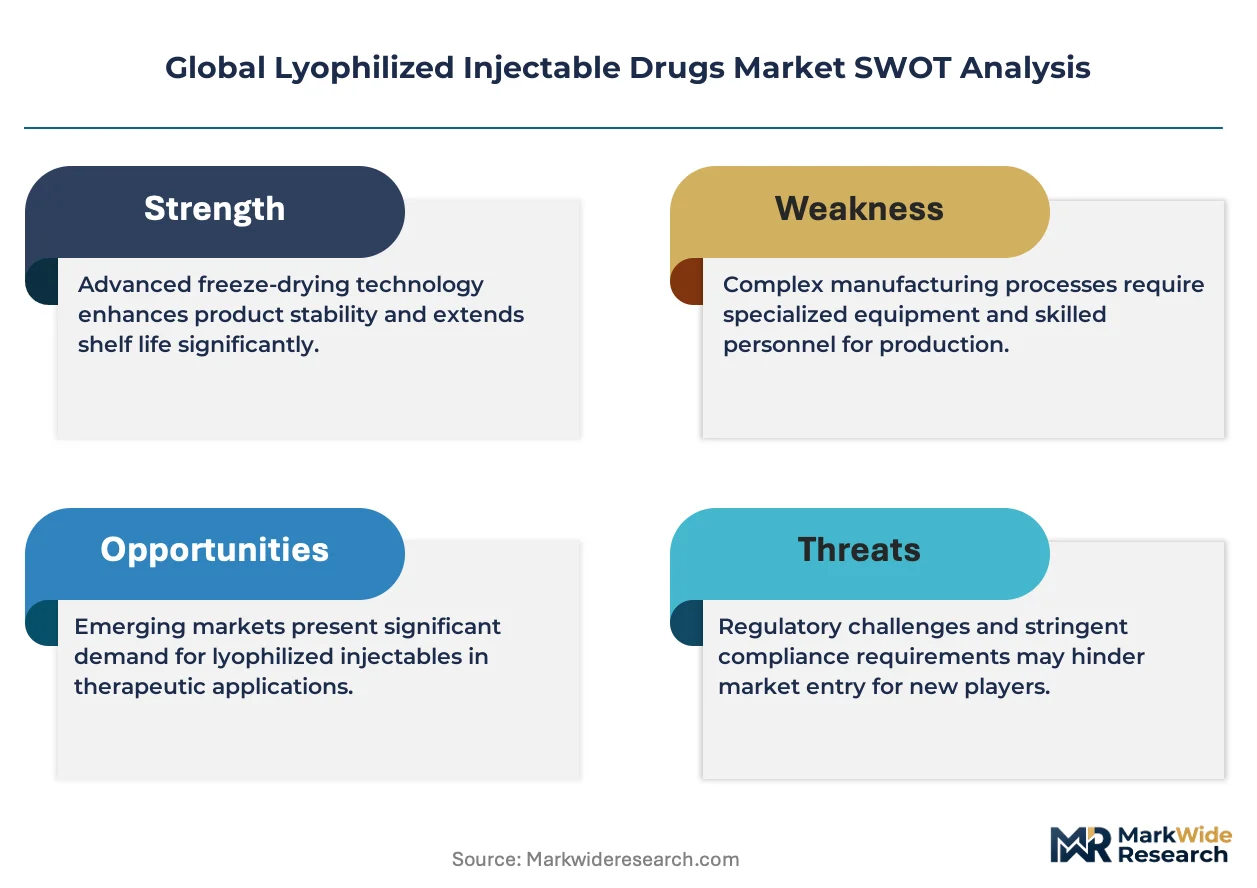
Growth Catalysts
- mRNA vaccine platform expansion:Freeze-dried mRNA formulations eliminate cold-chain infrastructure requirements, opening distribution to regions lacking ultra-low temperature logistics. Regulatory pathways in the United States and European Union are streamlining platform approvals for lyophilized presentations.
- FDA sterility guidance enforcement:Tighter aseptic processing standards are accelerating barrier technology adoption across contract manufacturing organizations, creating demand for upgraded lyophilization capacity that meets current good manufacturing practice expectations.
- Antibody-drug conjugate pipeline density:Oncology biologics with complex stability profiles require lyophilized presentation to achieve commercially viable shelf life, concentrating manufacturing investment in specialized European and North American facilities.
Market Restraints
- WFI (Water for Injection) supply volatility:Energy-intensive WFI production creates input cost instability, particularly affecting European facilities exposed to natural gas price fluctuations.
- Single-source vial and stopper concentration:West Pharmaceutical Services and Schott AG dominate elastomer and glass primary packaging, creating supply concentration risk for lyophilized drug manufacturers.
- EMA Annex 1 revision compliance timeline:The 2023 sterile manufacturing overhaul imposes barrier technology and contamination control strategy requirements that compress implementation windows for legacy facilities.
Strategic Opportunities
- India biosimilar manufacturing scale-up:CDSCO streamlined approval pathways and PLI scheme incentives are attracting lyophilization capacity investment for export-oriented monoclonal antibody production.
- Prefilled syringe reconstitution systems:Dual-chamber devices that integrate lyophilized drug and diluent are displacing traditional vial-and-needle administration in emergency medicine and military applications.
- Continuous manufacturing integration:Convergence of freeze-drying with continuous bioprocessing is compressing batch cycle times and enabling real-time release testing for high-volume oncology products.
Industry Challenges
- Aseptic processing technician scarcity:Specialized cleanroom operator training programs cannot match retirement-driven attrition rates in Germany and Japan, constraining capacity expansion timelines.
- Container closure integrity validation complexity:USP Chapter 1207 probabilistic methods require extensive method development and regulatory consultation, extending product launch timelines by 12-18 months for novel presentations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lyophilized Injectable Drugs Market |
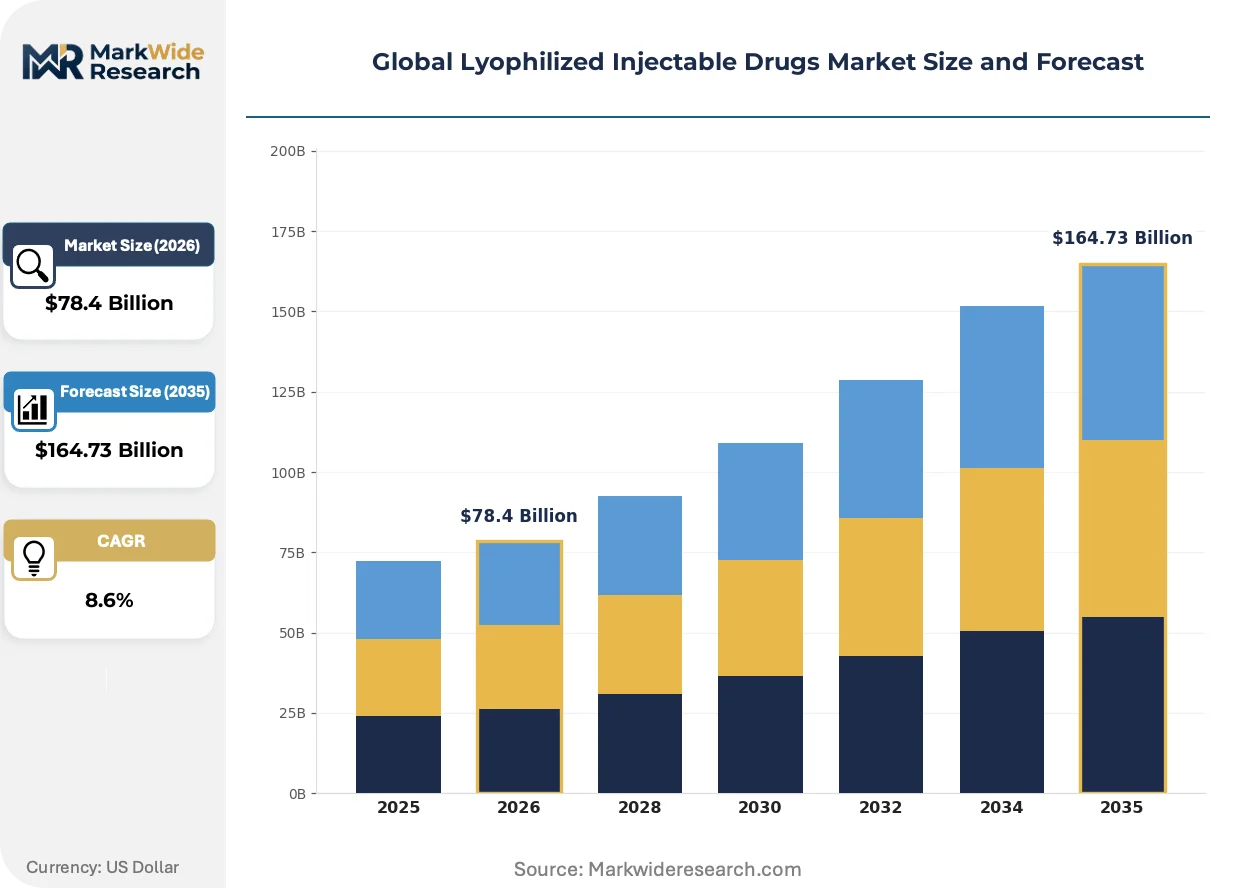
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Antibiotics, Hormones, Proteins, Enzymes Therapy Area: Oncology, Immunology, Infectious Diseases, Endocrinology, Neurology, Hematology End User: Hospitals, Specialty Clinics, Research Laboratories, Pharmacies, Clinical Trial Centers Packaging Type: Vials, Cartridges, Ampoules, Pre-filled Syringes, Bottles |
| Companies Covered | Pfizer Inc., Novartis AG, Roche Holding AG, Johnson & Johnson, Sanofi S.A., Merck & Co., Inc., Fresenius, Baxter, Vetter Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lyophilized Injectable Drugs Market Shifts & Advancements
Lyophilization technology is absorbing digital and materials science advances that compress cycle development timelines while expanding the range of biologics amenable to freeze-dried presentation.
Controlled nucleation technology is absorbing process analytical technology sensors that enable real-time ice crystal formation monitoring. Contract manufacturers in Switzerland and Germany are adopting these systems to reduce primary drying time by 30-40% for high-value oncology products. The structural consequence is absorbing smaller batch sizes into economically viable production, enabling personalized medicine applications previously excluded from lyophilization economics.
EMA Annex 1 revisions mandate barrier isolation technology for all new lyophilized sterile product installations. This is forcing restricted access barrier system and isolator investments across European manufacturing networks. Oncology and vaccine fill-finish operations are most affected, with facilities in Ireland and Belgium accelerating automation retrofits to meet compliance deadlines.
Group purchasing organizations are consolidating formulary control across United States health systems. Three national GPOs now manage procurement for over 70% of acute care beds, compressing supplier negotiation leverage and extending contract duration requirements. This concentration is most visible in oncology injectable purchasing, where multi-hospital systems demand decade-long supply guarantees with inflation-indexed pricing.
Global Lyophilized Injectable Drugs Market Segmentation
Segmentation in lyophilized injectables reveals how regulatory complexity and manufacturing constraints concentrate value across distinct product categories. Each dimension carries specific certification burdens that determine market entry sequencing and margin structure.
Product Type:
FDA biologics license applications and EMA marketing authorization procedures impose tiered approval timelines across product categories, with protein-based therapies facing the most extensive immunogenicity validation requirements.
- Monoclonal Antibodies:Complex glycoprotein structures with molecular weights exceeding 150 kDa require lyophilization to prevent aggregation and preserve binding affinity through multi-year shelf life. Demand concentrates in United States academic medical centers and German university hospitals where checkpoint inhibitor administration protocols are most established. EMA Annex 1 barrier technology mandates are extending facility qualification timelines for new mAb lyophilization capacity.
- Vaccines:mRNA and viral vector platforms are adapting to freeze-dried presentations to eliminate ultra-cold distribution infrastructure. Japanese PMDA stability testing protocols and FDA platform technology guidance are shaping parallel submission strategies for lyophilized COVID-19 and influenza candidates. This segment is expanding most quickly as tropical market access drives formulation investment.
- Antibiotics:Beta-lactam and aminoglycoside formulations leverage lyophilization for extended stability in hospital emergency stockpiles.
- Hormones:Peptide hormones including insulin analogs and growth factors require precise moisture control below 2% residual.
- Proteins:Recombinant clotting factors and enzyme replacement therapies depend on freeze-dried presentation for patient home administration.
- Enzymes:Industrial-scale thrombolytics and digestive enzyme formulations serve specialized intensive care applications.
Leading the category by volume: Monoclonal Antibodies. Growing fastest: Vaccines.
Therapy Area:
Reimbursement intensity and treatment duration vary sharply across indications, concentrating manufacturing investment in chronic disease categories with predictable demand profiles.
- Oncology:Antibody-drug conjugates and immune checkpoint inhibitors dominate lyophilized injectable value pools due to high unit dosing and temperature-sensitive payloads. United States National Cancer Institute-designated centers and French comprehensive cancer centers anchor demand. USP Chapter 797 compounding standards and EMA sterile manufacturing requirements impose overlapping compliance burdens.
- Infectious Diseases:Broad-spectrum antivirals and antifungal injectables serve hospital-acquired infection protocols with surge capacity requirements. Indian CDSCO export-oriented manufacturing incentives and Brazilian ANVISA local production mandates are reshaping supply geography. This segment is climbing the fastest as pandemic preparedness funding expands strategic stockpiles.
- Immunology:Autoimmune biologics including TNF-alpha inhibitors require patient-specific dosing flexibility.
- Endocrinology:Diabetes and osteoporosis injectables serve ambulatory care settings with reconstitution training requirements.
- Neurology:Multiple sclerosis and migraine therapeutics concentrate in specialty infusion centers.
- Hematology:Coagulation factor concentrates and hematopoietic growth factors serve hemophilia treatment centers.
Volume leadership sits with Oncology. Steepest expansion trajectory: Infectious Diseases.
End User:
Procurement centralization and clinical complexity determine which customer types command manufacturer attention and customized service models.
- Hospitals:Integrated delivery networks and group purchasing organizations in the United States, Germany, and Japan consolidate procurement for lyophilized oncology and anti-infective injectables. FDA drug shortage reporting requirements and EMA supply chain verification systems impose traceability obligations. Formulary committees in these systems demand multi-year supply guarantees with inflation-adjusted pricing.
- Specialty Clinics:Rheumatology, gastroenterology, and neurology infusion centers administer biologic therapies with cold-chain-independent lyophilized presentations. Outpatient reimbursement codes in France and Italy are expanding site-of-care flexibility. This channel is gaining share fastest as biosimilar competition drives cost-conscious site migration.
- Research Laboratories:Phase I-III clinical trial supplies require patient-specific batch sizing and blinding capabilities.
- Pharmacies:Compounding pharmacies under USP 797 oversight prepare reconstituted doses for same-day administration.
- Clinical Trial Centers:Academic research organizations manage investigational lyophilized drug stability across multi-site protocols.
Hospitals dominate procurement volume. Specialty Clinics represent the fastest-growing channel.
Packaging Type:
Container closure integrity standards and administration workflow requirements segment packaging demand across clinical settings.
- Vials:Borosilicate glass vials with butyl rubber stoppers remain the default for high-value biologics requiring vacuum-sealed moisture protection. West Pharmaceutical Services and Schott AG supply concentration creates qualification dependencies for new product launches. German and Swiss fill-finish facilities specialize in high-speed vial lyophilization for oncology products.
- Pre-filled Syringes:Dual-chamber designs integrating lyophilized drug and diluent are displacing traditional vial systems in emergency medicine and military applications. FDA combination product regulations and EMA device-drug consultation procedures add regulatory layers. This format is expanding most rapidly as point-of-care reconstitution errors drive safety investment.
- Cartridges:Pen-injector compatible formats serve chronic disease self-administration.
- Ampoules:Single-use glass containers persist in cost-sensitive antibiotic markets.
- Bottles:Multi-dose presentations serve compounding pharmacy and clinical trial bulk requirements.
Vials command the highest shipment volumes. Pre-filled Syringes show the steepest growth curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation and biologics infrastructure maturity concentrate demand in the United States, Germany, and Japan. Regulatory stringency from FDA, EMA, and PMDA shapes manufacturing investment patterns. Emerging markets in India and Brazil are attracting contract manufacturing capacity.
United States
Academic medical centers and National Cancer Institute-designated centers drive checkpoint inhibitor consumption. FDA sterility guidance enforcement accelerates barrier technology adoption across fill-finish networks. The Greater Boston and San Francisco Bay Area biotech clusters anchor specialized lyophilization capacity for antibody-drug conjugates.
Germany
University hospitals and comprehensive cancer centers concentrate oncology biologics demand. EMA Annex 1 revisions mandate isolator retrofits across existing sterile manufacturing facilities. The Rhine-Main and Upper Bavaria regions host specialized contract manufacturing organizations serving European monoclonal antibody supply.
Japan
PMDA stability testing protocols and aging demographics sustain demand for home-administered freeze-dried biologics. Local manufacturing requirements shape foreign market entry sequencing. The Kanto and Kansai metropolitan areas concentrate domestic fill-finish capacity and regulatory expertise.
India
CDSCO export-oriented approval pathways and PLI scheme incentives attract biosimilar lyophilization investment. Cost-competitive sterile manufacturing serves European and North American contract demand. The Hyderabad-Pune corridor and Ahmedabad cluster scale monoclonal antibody production for emerging market access.
Switzerland
Specialized oncology manufacturing and precision medicine applications sustain premium-tier capacity utilization. Swissmedic alignment with EMA procedures streamlines multi-jurisdiction product launches. The Basel region and Lake Geneva area concentrate high-value biologics fill-finish operations.
Global Lyophilized Injectable Drugs Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue dual-chamber device integration and continuous manufacturing convergence. The market structure reflects consolidated biopharma ownership of proprietary lyophilization networks alongside specialized contract manufacturing organizations. Three archetypes dominate: integrated pharmaceutical manufacturers with captive sterile capacity, dedicated contract fill-finish providers, and emerging platform technology specialists. Competitive positioning hinges on multi-year supply contract capture and EMA Annex 1 compliance timeline adherence.
Within the integrated pharmaceutical tier, Pfizer Inc. and Novartis AG exemplify archetypes of multi-year hospital supply contract holders. Pfizer leverages its sterile manufacturing network across North American and European facilities to anchor consolidated group purchasing organization relationships. Novartis occupies a position in specialized oncology lyophilization through European and North American facility concentration. Fresenius represents the diversified healthcare conglomerate archetype, extending hospital dialysis relationships into parallel injectable procurement channels.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Roche Holding AG |
| Johnson & Johnson |
| Sanofi S.A. |
| Merck & Co., Inc. |
| Fresenius |
| Baxter |
| Vetter Pharma |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between EMA Annex 1-compliant barrier facilities and legacy aseptic operations splits both contract structures and supplier margins. Premium-tier manufacturers command multi-year hospital supply agreements with inflation-indexed pricing, while standard-tier competitors absorb spot-market volatility and compressed terms.
Pricing Analysis
Volume-margins separate sharply across contract archetypes. High-volume monoclonal antibody supply agreements to United States group purchasing organizations run on decade-long offtake structures with price escalation clauses tied to WPI indices. Standard-tier antibiotics and emergency stockpile products trade on shorter spot-market terms vulnerable to Indian CDSCO export pricing. Three-tier pricing stratification across premium barrier-certified, standard isolator, and economy legacy facilities reflects EMA compliance investment recovery timelines. Hospital procurement consolidation intensifies cost compression in the standard tier as formulary committees demand supply guarantees without premium qualification premiums.
Supply Chain Analysis
Cleanroom technician scarcity in Germany and Japan constrains capacity expansion timelines regardless of capital availability. Manufacturing gravity centers on Switzerland, Ireland, and the United States for high-value oncology fill-finish, with India scaling biosimilar capacity under PLI scheme incentives. Lyophilization cycles draw from WFI production, borosilicate glass vial supply, and elastomer stopper qualification—each tethered to West Pharmaceutical Services and Schott AG concentration. Single-source primary packaging vulnerability creates qualification bottlenecks for new product launches. Distribution runs through hospital group purchasing organization warehouses and specialty clinic direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier technology capacity scarcity props contract pricing power for qualified manufacturers, with EMA Annex 1 retrofit timelines extending effective supply constraints.
For Market Incumbents: Acquire isolator-equipped fill-finish capacity in European regulatory jurisdictions before compliance deadlines harden. Consolidate multi-year hospital supply contracts with inflation-indexed pricing to lock in margin recovery from barrier technology investments. Defend against Indian biosimilar entrants by accelerating proprietary antibody-drug conjugate pipeline lyophilization capacity in captive Swiss and North American facilities. For New Entrants and Emerging Players: Specialty clinic infusion centers represent the most penetrable channel as reimbursement codes expand site-of-care flexibility in France and Italy. Target dual-chamber prefilled syringe formats for emergency medicine applications where reconstitution error reduction commands safety premiums. Partner with contract manufacturing organizations holding existing EMA Annex 1 qualification to bypass facility investment timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in platform technology specialists with continuous manufacturing integration capabilities. Five-to-ten year viability hinges on regulatory qualification moats rather than scale alone. Watch FDA sterility guidance enforcement intensity as the signal for barrier technology valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Annex 1 Compliance Retrofit | Isolator and restricted access barrier system investments preserve European market access for oncology fill-finish operations. |
| Dual-Chamber Prefilled Syringe Development | Integrated lyophilized drug and diluent formats capture emergency medicine procurement specifications from military and civilian buyers. |
| India Biosimilar Manufacturing Scale-Up | CDSCO streamlined pathways and PLI incentives enable cost-competitive monoclonal antibody export capacity. |
| Continuous Manufacturing Integration | Real-time release testing convergence with freeze-drying compresses batch cycle times for high-volume oncology products. |
| Controlled Nucleation Technology Adoption | Process analytical technology-enabled ice crystal monitoring reduces primary drying time by 30-40% in Swiss and German facilities. |
Research Methodology
FDA filings, EMA marketing authorization procedures, and ClinicalTrials.gov registry data formed the secondary backbone for pipeline and approval timeline validation. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors supplied qualitative calibration on manufacturing capacity constraints and contract structure evolution. Bottom-up product-level volume builds triangulated against top-down therapeutic category spending patterns from hospital procurement databases and GPO contract disclosures.
Historical trendline analysis of biologics license application approvals and sterile manufacturing capacity investments anchored growth trajectory assumptions across the projection horizon. Segmentation modeling spanned product type, therapy area, end user channel, and packaging format dimensions with regional regulatory cluster overlays. CAGRs derived from fitted growth curves applied to baseline volume estimates, with specific adjustment for mRNA vaccine platform lyophilization adoption curves and EMA Annex 1 compliance timeline impacts on effective supply availability.
Caveats apply where FDA sterility guidance enforcement intensity, WFI production cost volatility, or single-source primary packaging supply disruption could materially shift the outlook. Forecasts reflect documented assumptions on regulatory timeline adherence and hospital procurement consolidation velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Fibroblast Growth Factor Receptor Inhibitor Market
Pharmaceuticals
Cancer Immunotherapy Drug Discovery Outsourcing Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Global Oxytocin Market
Pharmaceuticals
Antithrombin Market
Pharmaceuticals
Atorvastatin Diepoxide Calcium Salt Market
Pharmaceuticals
Hyperphosphatemia Drugs Market
Pharmaceuticals
Europe Novel Drug Delivery System (NDDS) Market
Pharmaceuticals
Gastrointestinal OTC Drugs Market
Pharmaceuticals
Global Two Piece Empty Hard Capsule Market
Pharmaceuticals
Cognitive and Memory Enhancer Drugs Market
Pharmaceuticals
Thin Film Drug Manufacturing Market
Pharmaceuticals
Germany Pharmaceutical 3PL Market
Pharmaceuticals
Isoflurane Market
Pharmaceuticals
Optic Nerve Disorders Drugs Market
Pharmaceuticals
Triamcinolone Ointment Chlorofluorocarbons Market