
 Global Oxytocin Market | 2026-2036
Global Oxytocin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oxytocin Market Foresight
Synthetic peptide formulations are rebalancing raw material economics as recombinant DNA methods displace traditional extraction from animal pituitary glands. Pfizer leverages vertical integration across active pharmaceutical ingredient synthesis to sustain cost leadership in injectable vials. Ferring Pharmaceuticals anchors European supply through specialized fermentation capabilities. Fresenius Kabi competes in institutional tender markets with concentrated parenteral solutions.
Oxytocin is a nonapeptide hormone (C43H66N12O12S2) synthesized in the hypothalamus and administered exogenously to stimulate uterine smooth muscle contraction; recombinant production in engineered Escherichia coli or yeast systems now yields 98.5% purity grades suitable for intravenous infusion. Injectable formulations dominate hospital procurement due to immediate bioavailability and dose titration requirements during labor induction. Nasal spray delivery occupies niche lactation support applications where non-invasive administration improves patient compliance. Lyophilized powder formats are gaining traction in tropical distribution channels where cold chain reliability remains variable.
FDA enforces Current Good Manufacturing Practice for sterile peptide injectables through facility inspections and batch release testing. EMA's Guideline on Production and Quality Control of Medicinal Products Derived by Recombinant DNA Technology mandates host-cell protein limits below 0.1%. WHO prequalification programs shape procurement eligibility for developing-country health systems. Stakeholders must monitor biosimilar peptide filings and regional essential-medicines tender schedules to anticipate pricing compression in institutional channels.
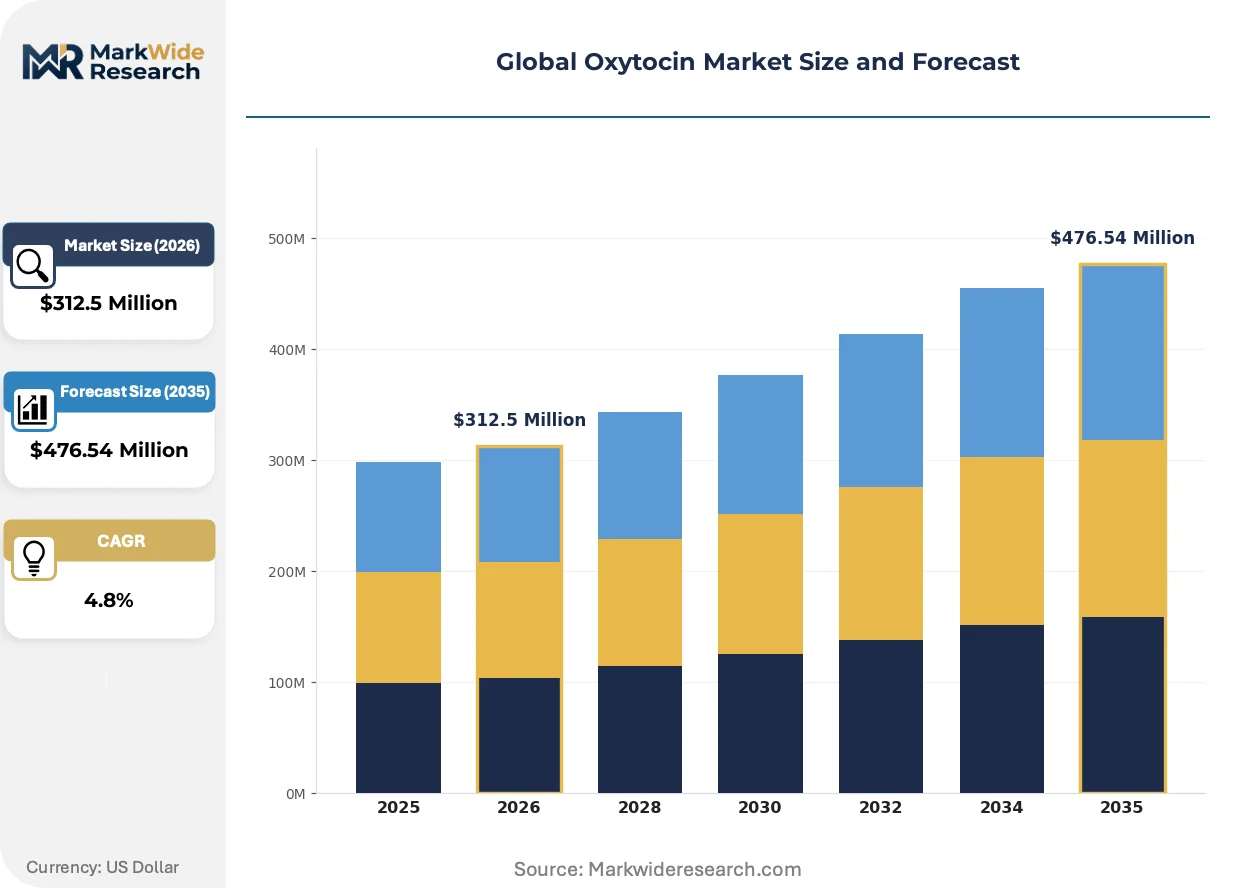
Market Dynamics
Recombinant DNA production methods are compressing cost structures for synthetic oxytocin while tightening purity specifications reshape supplier qualification thresholds across hospital procurement networks.
Growth Catalysts
- WHO Essential Medicines Listing:Inclusion on the WHO Model List drives volume procurement through government-funded maternal health programs in developing economies.
- India:Central government schemes for institutional deliveries expand tender volumes for generic injectable formulations through public sector supply chains.
- Lyophilization:Powder formats enable distribution in tropical climates where cold chain infrastructure remains unreliable, opening previously inaccessible health facilities.
Market Restraints
- Fermentation Input Costs:Specialized culture media and engineered Escherichia coli strain maintenance create sustained cost pressure for recombinant producers.
- EMA Host-Cell Protein Limits:The 0.1% ceiling on residual proteins mandates costly purification investments that disproportionately burden smaller manufacturers.
- Intramuscular Administration:Route limitations for emergency obstetric applications restrict adoption in pre-hospital settings where intravenous access is unavailable.
Strategic Opportunities
- Sub-Saharan Africa:Underpenetrated institutional birth coverage creates whitespace for pre-qualified generic suppliers meeting WHO procurement standards.
- Community Midwifery:Expansion of skilled birth attendant programs in rural Indonesia and Philippines generates demand for portable, heat-stable presentations.
- PLI Scheme:India's production-linked incentive framework for active pharmaceutical ingredients offers capital subsidy offsets for domestic peptide synthesis capacity.
Industry Challenges
- Peptide Synthesis Expertise:Scarce fermentation technologists and purification specialists constrain scale-up timelines for recombinant production facilities.
- Batch Release Testing:Extended sterility and endotoxin validation cycles delay inventory turnover for injectable vial manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oxytocin Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Nasal Spray, Oral Tablets, Lyophilized Powder Therapy Area: Postpartum Hemorrhage, Labor Induction, Lactation Support, Uterine Atony, Miscarriage Management End User: Hospitals, Birthing Centers, Obstetric Clinics, Maternity Nursing Homes Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Institutional Buyers |
| Companies Covered | Pfizer, Ferring Pharmaceuticals, Fresenius Kabi, Novartis, GlaxoSmithKline, Teva Pharmaceutical Industries, Hikma Pharmaceuticals, Grindeks, EVER Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oxytocin Market Shifts & Advancements
Biomanufacturing platform shifts and delivery format diversification are reconfiguring competitive requirements across institutional and community care channels.
Solid-state peptide synthesis is converging with continuous flow chemistry to enable modular, distributed production units that reduce batch-to-batch variability. Mid-tier contract manufacturers in Eastern Europe and Southeast Asia are piloting these systems to serve regional hospital networks. The technology is converging with quality-by-design frameworks to compress regulatory filing timelines for abbreviated new drug applications.
EMA's Guideline on Production and Quality Control of Medicinal Products Derived by Recombinant DNA Technology now mandates extended characterization of post-translational modifications. European manufacturers have invested in mass spectrometry suites and peptide mapping capabilities to demonstrate comparability with reference standards. Injectable vial suppliers serving EMA-regulated markets face the steepest compliance cost escalation, driving consolidation among fermentation-dependent producers.
Hospital purchasing consortia are consolidating tender specifications around pre-qualified supplier lists with demonstrated cold chain integrity. Group purchasing organizations in Brazil and Mexico now require temperature excursion documentation across last-mile distribution. This concentration is most visible in Latin American public sector procurement, where centralized ministry-level contracting displaces fragmented municipal purchasing patterns.
Global Oxytocin Market Segmentation
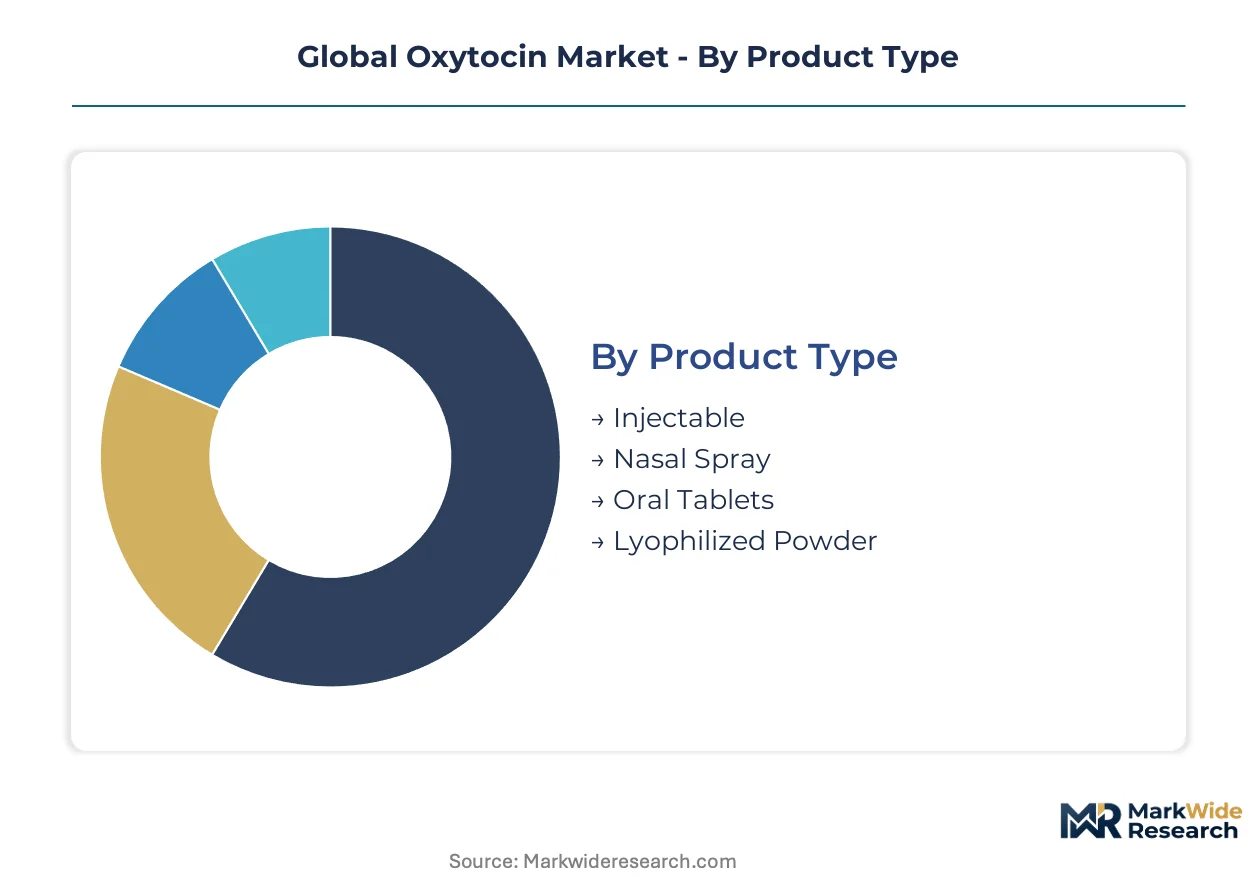
Oxytocin procurement splits across delivery formats, clinical indications, and institutional channels with sharply divergent regulatory burdens. Each segment carries distinct WHO prequalification, FDA sterile injectable, or EMA recombinant DNA compliance requirements that reshape supplier economics.
Product Type:
Certification intensity varies by sterility assurance and cold chain dependency, with parenteral formats facing FDA Current Good Manufacturing Practice inspections while solid-state alternatives navigate lighter stability documentation.
- Injectable:Intravenous and intramuscular solutions in ampoules or vials require endotoxin testing and batch release validation per FDA sterile peptide guidelines. Hospital obstetric units in India and Brazil concentrate procurement through centralized ministry tenders, driven by WHO Essential Medicines List inclusion for labor induction protocols.
- Lyophilized Powder:Freeze-dried formulations reconstituted with sterile diluent achieve thermal stability above 25°C, eliminating refrigeration requirements. Demand concentrates in Nigerian and Indonesian public health systems where cold chain infrastructure remains unreliable, opening previously inaccessible rural facilities to institutional delivery programs.
- Nasal Spray:Non-invasive administration for lactation support carries lighter sterility documentation than parenteral routes.
- Oral Tablets:Sublingual absorption formats face bioavailability challenges and limited clinical adoption in acute obstetric settings.
Leading the category by volume: Injectable. Expanding most quickly: Lyophilized Powder.
Therapy Area:
Clinical indication determines reimbursement tier and procurement urgency, with emergency hemorrhage protocols commanding premium pricing against elective lactation support.
- Postpartum Hemorrhage:Acute uterine bleeding prevention and treatment represents the highest-stakes application, with immediate intravenous administration protocols in hospital emergency departments. Nigerian and Ethiopian maternal health programs drive volume through WHO prequalified generic procurement, constrained by EMA host-cell protein limits below 0.1% for recombinant formulations.
- Labor Induction:Scheduled cervical ripening and augmentation in hospital obstetric units requires precise dose titration with continuous fetal monitoring. India's Janani Suraksha Yojana scheme expands tender volumes for institutional deliveries, with state-level medical services corporations consolidating supplier lists around demonstrated cold chain integrity.
- Lactation Support:Nasal spray administration for milk ejection reflex occupies niche outpatient channels with lower regulatory scrutiny.
- Uterine Atony:Post-delivery contraction failure management overlaps with hemorrhage protocols but carries distinct coding for reimbursement purposes.
- Miscarriage Management:Incomplete abortion uterine evacuation support faces restricted access in jurisdictions with regulatory barriers to pregnancy termination pharmaceuticals.
Postpartum Hemorrhage commands the steepest pricing premiums. Labor Induction generates the greatest absolute procurement volumes across government-funded programs.
End User:
Facility type determines procurement modality, with tertiary hospitals leveraging group purchasing organization leverage against fragmented municipal clinic purchasing.
- Hospitals:Tertiary and district-level institutions with operating theater capacity dominate injectable oxytocin consumption through centralized pharmacy formularies. Brazilian hospital purchasing consortia now require temperature excursion documentation across last-mile distribution, consolidating tender awards around pre-qualified suppliers with validated cold chain systems.
- Birthing Centers:Midwife-led facilities with limited emergency surgical backup favor heat-stable lyophilized presentations for rural deployment. Philippine Department of Health expansion of skilled birth attendant programs generates demand for portable, ambient-temperature storage formats in archipelago settings.
- Obstetric Clinics:Urban outpatient facilities concentrate lactation support nasal spray dispensing with lighter inventory turnover requirements.
- Maternity Nursing Homes:Private sector low-risk delivery facilities in Indian metropolitan areas compete on amenity differentiation rather than emergency pharmaceutical readiness.
Hospitals absorb the majority of procurement spend. Birthing Centers represent the steepest volume growth trajectory as community midwifery expands.
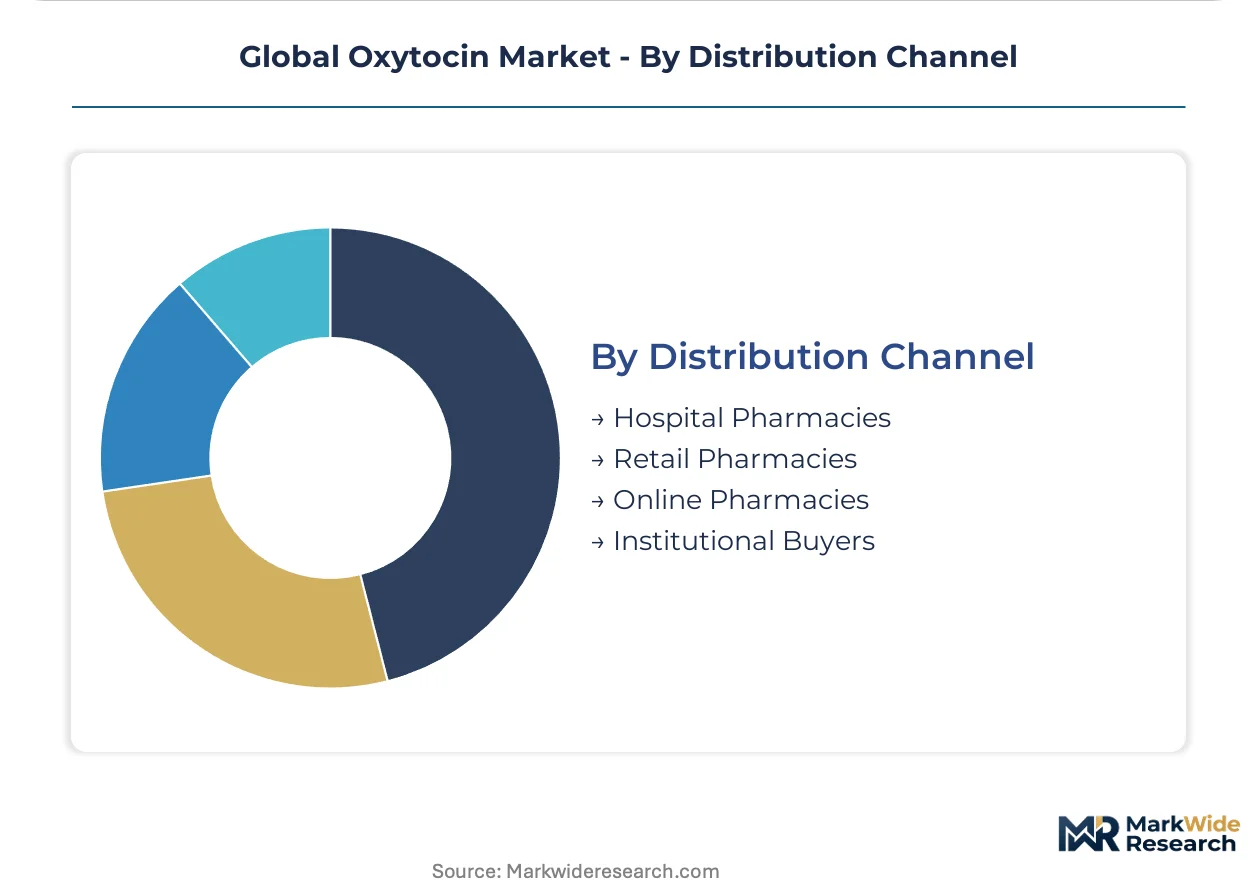
Distribution Channel:
Channel selection reflects institutional purchasing power concentration versus fragmented retail accessibility, with public sector buyers extracting steepest price concessions.
- Hospital Pharmacies:Captive dispensing within tertiary institutions captures the highest-margin injectable formulations through formulary lock-in. Mexico's Instituto Mexicano del Seguro Social consolidates peptide hormone procurement at federal level, displacing fragmented state-level contracting.
- Institutional Buyers:Ministry of health and development agency procurement desks drive lowest-unit-cost generic sourcing through WHO prequalification requirements. India's Tamil Nadu Medical Services Corporation exemplifies state-level tender consolidation with mandatory supplier qualification against CDSCO manufacturing standards.
- Retail Pharmacies:Community dispensaries serve lactation support and limited outpatient prescription demand with higher per-unit pricing.
- Online Pharmacies:E-commerce channels face regulatory constraints on controlled temperature product shipping and prescription verification.
Institutional Buyers command the deepest price discounts. Hospital Pharmacies retain the highest absolute revenue contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Pharmaceutical Export Promotion Council zones and special economic areas for active pharmaceutical ingredient production concentrate recombinant peptide manufacturing capacity. Tax holidays and duty exemptions on fermentation equipment imports anchor cost-competitive supply bases serving institutional tender markets across Africa and Southeast Asia.
India
Central government schemes for institutional deliveries expand tender volumes for generic injectable formulations. CDSCO manufacturing standards and WHO prequalification requirements shape supplier eligibility for export-oriented production. Hyderabad and Ahmedabad clusters host fermentation facilities supplying pre-qualified oxytocin to Nigerian and Ethiopian maternal health programs.
United States
Hospital-based obstetric units drive procurement for labor induction protocols with immediate bioavailability requirements. FDA Current Good Manufacturing Practice inspections enforce sterility assurance for parenteral peptide injectables. New Jersey and North Carolina pharmaceutical corridors concentrate sterile vial manufacturing serving domestic hospital purchasing consortia.
Germany
Specialized fermentation capabilities anchor European supply for recombinant DNA-derived formulations. EMA's Guideline on Production and Quality Control of Medicinal Products Derived by Recombinant DNA Technology mandates host-cell protein limits below 0.1%. Baden-Württemberg biotechnology clusters invest in mass spectrometry suites for extended characterization of post-translational modifications.
Brazil
Hospital purchasing consortia consolidate tender specifications around pre-qualified supplier lists with demonstrated cold chain integrity. ANVISA registration requirements and temperature excursion documentation mandates reshape last-mile distribution. São Paulo and Minas Gerais medical services corporations displace fragmented municipal contracting with centralized ministry-level procurement.
Nigeria
Postpartum hemorrhage prevention protocols drive volume through WHO prequalified generic procurement in underpenetrated institutional birth coverage. Federal Ministry of Health programs expand skilled birth attendant deployment to previously inaccessible rural facilities. Lagos and Kano distribution hubs pilot heat-stable lyophilized powder formats where cold chain infrastructure remains unreliable.
Global Oxytocin Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fermentation-dependent producers facing steeper compliance cost escalation than solid-state formulation specialists. The supplier base concentrates around three archetypes: vertically integrated pharmaceutical majors with captive active pharmaceutical ingredient synthesis, specialized peptide houses with recombinant DNA platforms, and institutional tender specialists with concentrated parenteral solutions. Competitive moves center on backward integration into fermentation capacity and geographic expansion through WHO prequalification.
Among established pharmaceutical majors, Pfizer and Novartis occupy positions as scale-driven anchors with in-house production of synthetic peptides. Ferring Pharmaceuticals exemplifies the specialized peptide house archetype with European fermentation capabilities. Fresenius Kabi represents the institutional tender specialist model competing in hospital pharmacy and group purchasing organization channels.
| Leading Market Players |
|---|
| Pfizer |
| Ferring Pharmaceuticals |
| Fresenius Kabi |
| Novartis |
| GlaxoSmithKline |
| Teva Pharmaceutical Industries |
| Hikma Pharmaceuticals |
| Grindeks |
| EVER Pharma |
| Others |
Supply & Pricing Matrix
Captive fermentation capacity in Indian and German manufacturing clusters anchors both supply security and pricing power for recombinant oxytocin producers, with backward integration into engineered Escherichia coli strain maintenance insulating against raw material volatility while enabling tiered pricing based on purity grades.
Pricing Analysis
Volume-margins split sharply across procurement tiers: institutional buyers extract deepest discounts through WHO prequalified generic tenders, while hospital pharmacies retain premium pricing for cold-chain-validated injectables. Price differentiation hinges on EMA host-cell protein certification status and demonstrated temperature excursion documentation. Cost compression in standard-grade formulations intensifies as Indian state medical services corporations consolidate supplier lists. Government-funded maternal health programs exhibit highest price sensitivity; tertiary hospital obstetric units with formulary lock-in show lowest.
Supply Chain Analysis
Fermentation technologist scarcity in Hyderabad and Ahmedabad clusters constrains recombinant peptide scale-up timelines, with purification specialist availability emerging as the binding constraint for EMA-compliant production. Active pharmaceutical ingredient synthesis draws from specialized culture media, engineered bacterial strains, and chromatography resin inputs. Single-source vulnerability concentrates in sterile vial finishing capacity. Distribution runs through ministry-level procurement desks and hospital purchasing consortia with validated cold chain systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
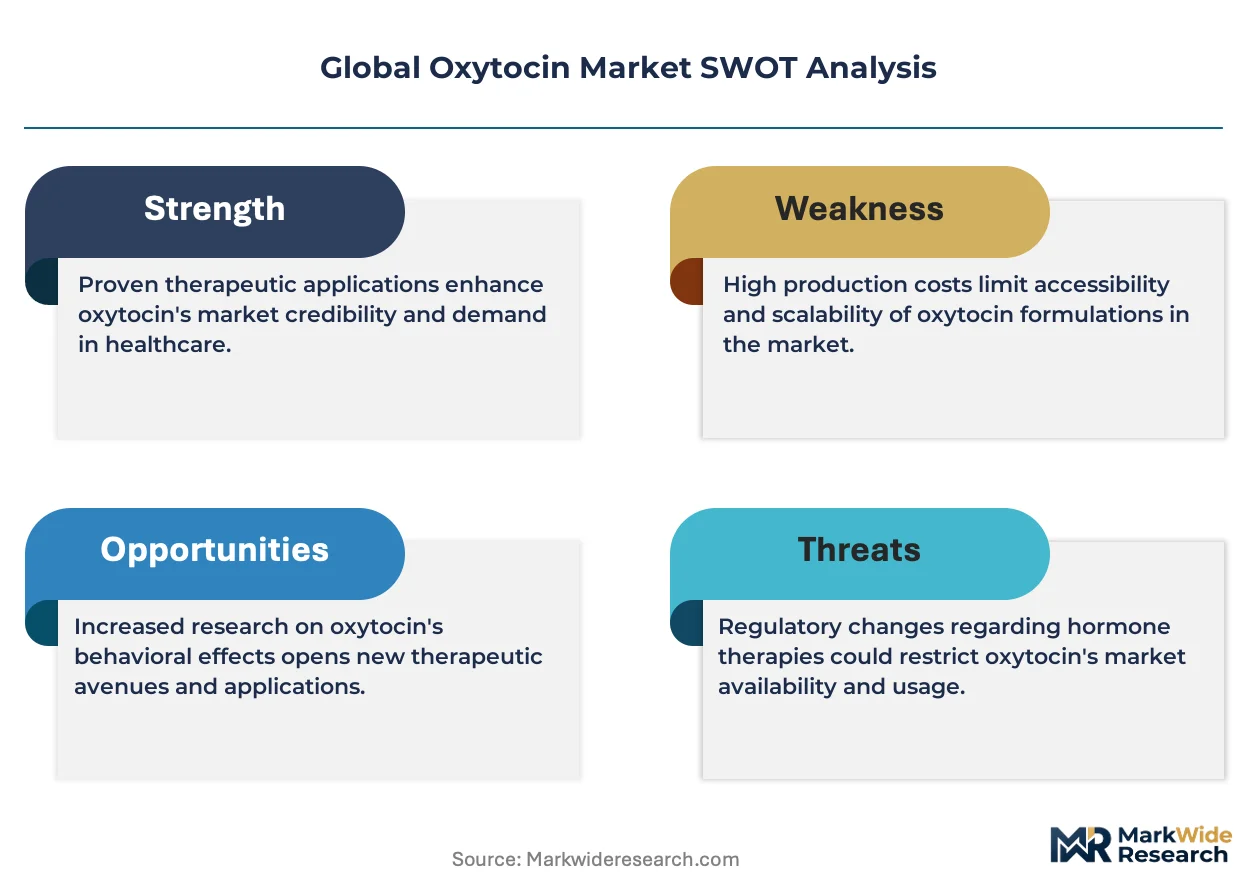
This market reads as a cost-of-compliance story: EMA's 0.1% host-cell protein limit constructs a barrier-to-entry moat that rewards fermentation-capable incumbents while filtering smaller manufacturers from institutional tender eligibility.
For Market Incumbents: To counter biosimilar peptide filings from Indian contract manufacturers, deepen captive fermentation capacity in tax-advantaged special economic zones and secure WHO prequalification status for lyophilized powder formats targeting African distribution channels.
For New Entrants and Emerging Players: Enter via Sub-Saharan African institutional birth coverage gaps, where underpenetrated skilled birth attendant programs create whitespace for heat-stable presentations. Target Nigerian federal ministry tenders with ambient-temperature storage solutions as the most penetrable entry point.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized peptide houses with demonstrated EMA compliance and existing WHO prequalification portfolios. Long-term viability favors fermentation-dependent producers with mass spectrometry characterization capabilities. Watch Indian PLI scheme subsidy disbursements as inflection indicator for domestic API synthesis capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | WHO prequalification unlocks procurement eligibility across Nigerian and Ethiopian maternal health programs. |
| Manufacturing Scale-Up | Fermentation capacity additions in Hyderabad special economic zones reduce batch-to-batch variability for export markets. |
| Backward Integration | In-house engineered Escherichia coli strain development insulates against specialized culture media supply disruptions. |
| Product Format Diversification | Lyophilized powder development enables penetration of Indonesian archipelago birthing centers with unreliable cold chain. |
| Long-term Supply Agreement | Centralized ministry-level contracting with Brazilian hospital purchasing consortia secures volume commitments against price erosion. |
Research Methodology
Independent corroboration across primary interviews with regulatory affairs leads, hospital procurement managers, and fermentation operations directors, combined with secondary validation through FDA filings, EMA submission databases, WHO prequalification lists, and CDSCO manufacturing standards, underwrites the qualitative findings. Bottom-up demand modeling from institutional tender volumes and top-down market sizing from trade flow data complete the triangulation.
Comparable-period anchoring to historical WHO Essential Medicines List procurement volumes and hospital obstetric unit admission trends structures the forecast window. The analytical framework segments by delivery format, clinical indication, and end-user facility type, with regional regulatory clusters as an additional dimension. CAGRs derive from volume trajectory analysis across government-funded maternal health program expansion curves and recombinant production capacity buildout schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EMA guideline revision scenarios or sudden cold chain infrastructure investment in tropical distribution channels. A small set of triggers—Indian PLI scheme implementation pace, WHO prequalification backlog clearance, and host-cell protein detection technology advancement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Dermatological Drugs Market
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
Germany Pharmaceuticals Market
Pharmaceuticals
Bendamustin Market
Pharmaceuticals
Dextromethorphan Market
Pharmaceuticals
Global Human Rabies Vaccine Market
Pharmaceuticals
Cyclosporine Drugs Market
Pharmaceuticals
Cancer Immunotherapy Drug Discovery Outsourcing Market
Pharmaceuticals
Nicotine Replacement Therapy (NRT) Market
Pharmaceuticals
Global Shingles Vaccine Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Global Tetanus Toxoid Vaccine Market
Pharmaceuticals
Iodine Deficiency Drug Market
Pharmaceuticals
Antiepileptic Drugs (AED) Market
Pharmaceuticals
Renal Drugs Market
Pharmaceuticals
Pregabalin Market