
 AI in Pharma Market | 2026-2036
AI in Pharma Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Pharma Market Analysis
The EU AI Act is shifting compliance burdens for algorithmic drug-discovery platforms entering European markets. Roche leverages its diagnostic-data reservoirs to anchor predictive modeling pipelines across oncology portfolios. Insilico Medicine specializes in generative chemistry, sustaining end-to-end discovery timelines that compress traditional research cycles.
AI in Pharma encompasses machine-learning systems, natural-language-processing engines, and computer-vision tools trained on molecular, clinical, and real-world datasets to predict compound behavior, optimize trial design, and personalize therapeutic regimens. Deep learning dominates current deployment, with neural-network architectures capturing the largest share of R&D expenditure; natural language processing is the fastest-growing product type as sponsors automate regulatory submission drafting and literature surveillance. Drug discovery commands the widest application footprint, while personalized medicine represents the emerging margin pool where predictive modeling intersects with biomarker-stratified cohorts.
FDA, EMA, and the EU AI Act collectively shape market access through divergent validation standards for clinical-decision algorithms and transparency mandates for training-data provenance. The FDA's emerging framework for adaptive trial designs rewards sponsors that embed AI-driven patient-selection tools, while EMA's reflection papers on big data nudge developers toward explainable model architectures. Stakeholders must decide whether to architect single compliance stacks or maintain parallel regulatory pipelines as jurisdictional requirements diverge.
Market Dynamics
FDA guidance on AI-enabled medical devices is forcing sponsors to re-architect validation pipelines before commercial entry, compressing development timelines while elevating compliance spend across therapeutic categories.
Growth Catalysts
- Adaptive Trial Frameworks:The FDA rewards sponsors embedding AI-driven patient-selection tools with expedited review pathways, accelerating oncology and rare-disease programs.
- Generative Chemistry Platforms:Machine-learning architectures trained on molecular datasets compress hit-to-lead timelines from years to months across neurodegenerative and metabolic targets.
- Boston-San Francisco Biotech Density:Venture deployment concentrates in these coastal clusters, creating talent reservoirs and specialized CRO ecosystems for algorithmic drug discovery.
Market Restraints
- Training Data Provenance Requirements:The EU AI Act mandates exhaustive documentation of dataset lineage, imposing documentation burdens that extend European market entry timelines.
- Computational Infrastructure Costs:GPU clusters and cloud-native storage for billion-parameter molecular models consume capital that mid-cap biotechs struggle to secure.
- Model Explainability Constraints:EMA reflection papers on big data nudge developers toward interpretable architectures, limiting deployment of black-box deep learning in regulatory submissions.
Strategic Opportunities
- Real-World Evidence Integration:Electronic health record networks and wearable biomarker streams enable post-market surveillance models that expand label indications without new trials.
- Japan's PMDA Digital Transformation:METI incentives for AI-native pharmaceutical development create a regulatory sandbox for predictive toxicology and patient digital twins.
- Regulatory Submission Automation:Natural language processing engines trained on FDA and EMA precedent documents automate CMC and clinical summary drafting, freeing scientific staff for hypothesis generation.
Industry Challenges
- Computational Biology Talent Scarcity:The intersection of medicinal chemistry, machine learning, and regulatory science commands premiums that stretch R&D staffing budgets.
- Legacy System Integration Friction:Enterprise LIMS and CTMS platforms require API-layer middleware to ingest AI-generated predictions, slowing pilot-to-production transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Pharma Market |
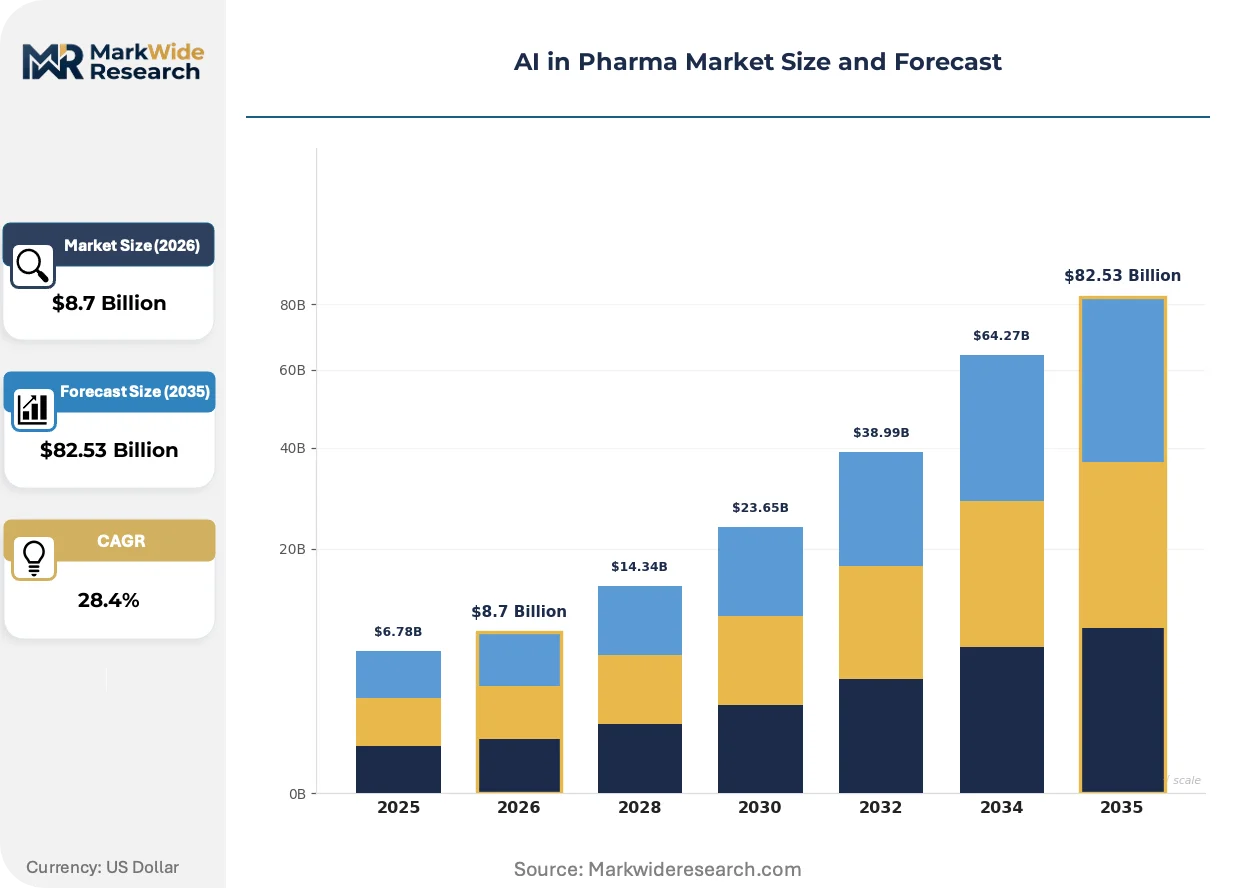
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Machine Learning, Natural Language Processing, Robotics, Computer Vision Application: Drug Discovery, Clinical Trials, Personalized Medicine, Patient Monitoring End User: Pharmaceutical Companies, Research Institutions, Healthcare Providers, Biotechnology Firms Technology: Deep Learning, Neural Networks, Data Analytics, Predictive Modeling |
| Companies Covered | Eli Lilly, Merck KGaA, Roche, Bayer, Recursion Pharmaceuticals, Insilico Medicine, insitro, Exscientia, Atomwise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Pharma Market Emerging Trajectories
Foundation models trained on molecular, clinical, and textual data are unifying previously siloed discovery workflows, compressing the handoffs between target identification and lead optimization that historically stalled programs.
Multimodal neural architectures are unifying sequence, structure, and property prediction into single inference pipelines. Mid-cap biotechs and large-cap pharmas adopt these platforms at accelerating cadence, bypassing traditional docking and QSAR workflows. This convergence is unifying computational and experimental teams under shared model governance frameworks.
The EU AI Act's risk-classification system for clinical-decision algorithms is reshaping European market access protocols. Developers must now submit conformity assessments before placing high-risk diagnostic tools on the market. Oncology and cardiovascular AI applications face the steepest compliance ramps, with sponsors restructuring quality management systems to satisfy notified body scrutiny.
Biopharma procurement of AI discovery platforms is shifting from perpetual licenses toward consumption-based pricing tied to validated compound outputs. This displaces upfront seven-figure commitments with milestone-triggered payments. The model is most visible among Boston and San Francisco venture-backed biotechs, where cash runway sensitivity favors operational expenditure structures.
AI in Pharma Market Segmentation
Segmentation in AI-enabled pharmaceutical development reveals how technology specialization maps to distinct value capture mechanisms. Each dimension—product architecture, therapeutic application, customer archetype, and underlying computational method—carries unique deployment economics and regulatory exposure.
Product Type:
Standardized algorithmic platforms compete against bespoke molecular engines across this spectrum, with customization premiums widening as therapeutic targets become more specialized.
- Machine Learning:Ensemble and supervised learning architectures trained on biochemical assay data predict ADMET properties with quantified confidence intervals. Demand concentrates among large-cap pharmas in the United States seeking to de-risk lead optimization portfolios against FDA validation standards.
- Natural Language Processing:Transformer-based models extract mechanistic insights from patent corpora, clinical-trial registries, and regulatory precedent documents. Research institutions in Boston and San Francisco deploy these engines to automate hypothesis generation and competitive intelligence surveillance.
- Robotics:Laboratory automation systems integrate liquid-handling workstations with AI-guided experimental design.
- Computer Vision:Convolutional neural networks classify histopathology slides and cell-morphology phenotypes.
Most installed capacity flows through Machine Learning. Expansion is steepest in Natural Language Processing.
Application:
Revenue concentration shifts upstream toward discovery-phase deployment, though post-approval applications command superior margin profiles per validated patient outcome.
- Drug Discovery:Generative chemistry platforms and target-identification algorithms compress discovery timelines from target validation to candidate nomination. Biotechnology firms in San Francisco leverage these tools against neurodegenerative and rare-disease targets where traditional screening fails.
- Clinical Trials:Patient-selection algorithms and site-optimization engines reduce enrollment timelines and protocol amendments. Pharmaceutical companies deploy these systems to satisfy FDA adaptive-trial frameworks and minimize rescue-study expenditures.
- Personalized Medicine:Biomarker-stratified dosing algorithms and companion-diagnostic integration.
- Patient Monitoring:Wearable-derived digital biomarkers and adherence-prediction models.
Drug Discovery captures the majority of current R&D expenditure. Personalized Medicine is gaining share fastest as companion-diagnostic reimbursement stabilizes.
End User:
Procurement authority and technical sophistication diverge sharply across this category, with enterprise buyers demanding model explainability that venture-backed startups cannot yet deliver.
- Pharmaceutical Companies:Integrated discovery-and-development organizations with dedicated computational biology divisions. These buyers in the United States and Switzerland negotiate enterprise licenses spanning target identification through regulatory submission.
- Biotechnology Firms:Asset-centric developers with platform-technology ambitions. Cash-constrained operations in Boston favor consumption-based pricing tied to validated compound progression.
- Research Institutions:Academic medical centers and nonprofit institutes with access to longitudinal patient cohorts.
- Healthcare Providers:Hospital systems and integrated delivery networks piloting clinical-decision support.
Pharmaceutical Companies account for the dominant share of platform revenue. Biotechnology Firms are expanding most quickly as venture deployment concentrates in algorithmic discovery.
Technology:
Computational intensity and interpretability trade-offs define competitive positioning, with black-box architectures facing EMA scrutiny while transparent methods sacrifice predictive accuracy.
- Deep Learning:Multi-layer neural architectures capturing non-linear relationships in high-dimensional molecular and clinical datasets. United States-based sponsors deploy these systems where FDA guidance permits adaptive validation frameworks.
- Neural Networks:Feedforward and recurrent architectures for property prediction and sequence modeling. Research institutions favor these methods for their balance of performance and mechanistic inspectability.
- Data Analytics:Statistical and machine-learning methods emphasizing interpretability and regulatory defensibility.
- Predictive Modeling:Bayesian and frequentist approaches to trial outcome forecasting and portfolio optimization.
Deep Learning dominates current capital allocation. Data Analytics is climbing the fastest as EU AI Act explainability mandates reshape European procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Computational biology talent pools anchor AI pharmaceutical development across four distinct national markets, each shaped by divergent regulatory frameworks and investment concentrations.
United States
FDA adaptive-trial pathways and venture capital deployment drive platform adoption among Boston and San Francisco biotech clusters. The agency's emerging guidance on AI-enabled medical devices accelerates compliance investments across therapeutic categories. Roche leverages diagnostic-data reservoirs from its South San Francisco operations to anchor predictive modeling pipelines.
Switzerland
Large-cap pharma headquarters and specialized CRO ecosystems concentrate algorithmic discovery investment around Basel and Zurich. Swissmedic maintains alignment with EMA reflection papers on big data while preserving flexibility for exploratory model architectures. Novartis and Roche anchor enterprise procurement of machine-learning platforms for oncology portfolios.
United Kingdom
Exscientia and other AI-native developers cluster around Oxford and Cambridge, supported by MHRA innovation pathways for adaptive clinical designs. The UK's divergence from EU AI Act timelines creates parallel compliance considerations for European market entry. London-based venture funds concentrate Series A deployment in generative chemistry startups.
China
NMPA digital transformation initiatives and domestic cloud infrastructure expansion accelerate AI-native pharmaceutical development in Shanghai and Beijing. Insilico Medicine maintains headquarters operations in Hong Kong with mainland R&D facilities. Local champions deploy deep learning for traditional Chinese medicine compound screening alongside Western small-molecule programs.
Japan
METI incentives for AI-native pharmaceutical development create regulatory sandboxes for predictive toxicology in Tokyo and Osaka. PMDA digital transformation programs reward sponsors embedding patient digital twins into trial designs. Domestic pharma incumbents partner with specialized AI vendors to compress discovery timelines against global competitors.
AI in Pharma Market Vendor Landscape
The competitive structure tilts toward technology-anchored biotech specialists rather than consolidated pharma incumbents. Fragmentation persists across the discovery-platform layer, with no single vendor capturing dominant share. Three archetypes define positioning: asset-centric AI natives with end-to-end chemistry engines, diagnostic-data incumbents repurposing clinical reservoirs, and algorithmic-tool vendors licensing modular capabilities. M&A activity concentrates on talent acquisition for computational biology teams, while strategic partnerships dominate technology access strategies.
Among AI-native biotech specialists, Recursion Pharmaceuticals, Insilico Medicine, and Exscientia exemplify the asset-centric archetype, each occupying positions that integrate generative chemistry with proprietary molecular databases. Recursion represents the scale-driven end of this tier, while Insilico Medicine anchors the generative-chemistry specialization vector. Exemplifying the diagnostic-data incumbent archetype, Roche leverages its Basel headquarters and South San Francisco operations to anchor predictive modeling pipelines. Traditional pharma players including Eli Lilly, Merck KGaA, and Bayer sit within the enterprise-adopter tier, licensing capabilities or building internal computational divisions. Atomwise and insitro represent the modular-tool and platform-technology vectors respectively.
| Leading Market Players |
|---|
| Eli Lilly |
| Merck KGaA |
| Roche |
| Bayer |
| Recursion Pharmaceuticals |
| Insilico Medicine |
| insitro |
| Exscientia |
| Atomwise |
| Others |
Supply Flow & Price Mechanics
GPU cluster costs cascade through AI pharma platform pricing tiers, with hyperscale cloud compute in the United States feeding consumption-based models for Boston biotechs while enterprise licenses for Basel pharmas absorb infrastructure overhead through amortized subscription structures.
Pricing Analysis
Bundled platform subscriptions encompassing model training, validation documentation, and regulatory support command premiums against unbundled per-inference API access. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated oncology pipelines from exploratory rare-disease screens and academic research licenses. Price differentiation hinges on model explainability certification and geographic data residency compliance. Pricing pressure stems from venture-backed biotechs demanding milestone-triggered payments rather than upfront commitments. Biotechnology firms exhibit the highest price sensitivity; large-cap pharmas in Switzerland and the United States negotiate least aggressively due to compliance risk aversion.
Supply Chain Analysis
Direct-to-enterprise channels handle pharmaceutical company procurement of validated discovery platforms, while API-layer middleware vendors serve biotechnology firms integrating AI outputs into legacy LIMS and CTMS systems. Supply concentrates in the United States, Switzerland, and the United Kingdom where computational biology talent pools anchor platform development. GPU hardware and cloud-native storage infrastructure draw from Taiwan Semiconductor Manufacturing and South Korean memory foundries. Single-source vulnerability in NVIDIA datacenter chip supply creates bottleneck risk for billion-parameter molecular model training. Distribution runs through specialized CRO ecosystems in Boston and San Francisco alongside direct enterprise sales teams targeting Basel and Zurich headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI pharma development functions as a geographic-arbitrage play, with EU AI Act compliance costs in Europe running substantially above FDA adaptive-trial pathway expenses in the United States.
For Market Incumbents: Deepen vertical integration into proprietary diagnostic-data reservoirs to anchor predictive modeling pipelines against AI-native biotech challengers. Roche's South San Francisco operations exemplify this defensive posture. Invest in explainable model architectures to preempt EMA scrutiny and capture European market share. Capacity expansion in Switzerland preserves regulatory flexibility while Basel headquarters maintain enterprise client relationships. For New Entrants and Emerging Players: Contract research organizations represent the most accessible channel partner type for algorithmic discovery platforms seeking rapid scale. White-space targets include Japan's PMDA sandbox for predictive toxicology and mid-cap biotechs in Boston demanding consumption-based pricing. The penetrable segment spans asset-centric developers with rare-disease portfolios where traditional screening fails. A regulatory submission automation angle using natural language processing engines unlocks formulary director budgets. For Investors and Strategic Acquirers: Roll-up economics work for modular AI tool vendors because enterprise pharmas increasingly prefer integrated platform suites over point-solution fragmentation. Long-term viability across the analysis window favors asset-centric AI natives with end-to-end chemistry engines and validated compound progressions. Acquisition target archetype: generative chemistry specialists with proprietary molecular databases and FDA engagement history. The signal to watch is PMDA sandbox expansion announcements indicating Japanese regulatory appetite for patient digital twins.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Submission Automation | NLP engines trained on FDA and EMA precedent documents accelerate CMC drafting timelines. |
| Real-World Evidence Integration | Electronic health record networks enable post-market surveillance models expanding label indications. |
| EU AI Act Compliance Investment | Conformity assessments for high-risk diagnostic tools satisfy notified body scrutiny requirements. |
| Generative Chemistry Platform Deployment | Machine-learning architectures compress hit-to-lead timelines from years to months. |
| Japan PMDA Sandbox Entry | METI incentives for AI-native development create regulatory safe harbors for predictive toxicology. |
Methodological Framework
Direct dialogue with drug development executives, regulatory affairs leads, formulary directors, and computational biology division heads grounded qualitative assessment of platform adoption drivers. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up and top-down triangulation reconciled platform revenue estimates against therapeutic pipeline valuations.
Bottom-up modeling segmented revenue by machine learning, natural language processing, and computer vision product architectures, then cross-referenced against drug discovery, clinical trial, and personalized medicine application spend. Top-down validation anchored total addressable market estimates to pharmaceutical R&D expenditure patterns across the United States, Switzerland, and the United Kingdom. CAGRs emerged from regression analysis of historical platform adoption curves and regulatory pathway acceleration effects. Treatment line stratification and regional regulatory cluster differentiation refined segment-level projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA guidance finalization timelines and EU AI Act enforcement consistency. Periodic stress-testing of base assumptions is recommended, particularly around GPU supply chain resilience and computational biology talent availability in Boston and San Francisco clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Canagliflozin Market
Pharmaceuticals
Global Psoriasis Drugs Market
Pharmaceuticals
Monkeypox Vaccine and Treatment Market
Pharmaceuticals
Anti-Obesity Drugs Market
Pharmaceuticals
Oral Contraceptive Pills Market
Pharmaceuticals
Global Anti-Suicide Drugs Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Cholera Vaccines Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Oral Thin Film Drugs Market
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Farm Animal Drugs Market
Pharmaceuticals
Global Hepatitis B Vaccines Market
Pharmaceuticals
Josamycin Market
Pharmaceuticals
Contraceptive Drugs Market
Pharmaceuticals
Gamma-Hydroxybutyric Acid Market