
 Vaccine Contract Development and Manufacturing Organization Market | 2026-2036
Vaccine Contract Development and Manufacturing Organization Market Size, Share, and Industry Trends Forecast 2026-2036
Vaccine Contract Development and Manufacturing Organization Market Insights
Single-use bioreactor systems are expanding their footprint in mammalian cell culture workflows, displacing traditional stainless-steel infrastructure across commercial vaccine manufacturing. Lonza Group leverages its Switzerland-based biologics network to anchor multi-product facility operations for viral vector programs. Samsung Biologics competes through aggressive capacity additions at its Songdo campus, while WuXi Biologics specializes in integrated discovery-to-commercial platforms spanning China and global markets.
Vaccine Contract Development and Manufacturing Organization denotes third-party service providers managing upstream process development, cell-line engineering, and downstream purification through to aseptic fill-finish and release testing for vaccine sponsors. These operations typically execute under cGMP conditions with batch sizes ranging from 2,000 to 20,000 liters depending on platform technology and indication scale. mRNA vaccines command premium outsourcing rates due to lipid nanoparticle formulation complexity and cold-chain stability requirements. Process development services capture expanding margin pools as sponsors push phase-appropriate validation earlier in clinical timelines.
FDA, EMA, and WHO prequalification standards collectively determine market access for contract-manufactured vaccines destined for national immunization programs and emergency stockpiles. The FDA's emerging technology program and EMA's quality-by-design guidelines are reshaping how CDMOs document process control strategies during regulatory submissions. Stakeholders must monitor how evolving WHO TRS guidelines for mRNA platform consistency will alter analytical testing burdens and facility qualification timelines across outsourced networks.
Market Dynamics
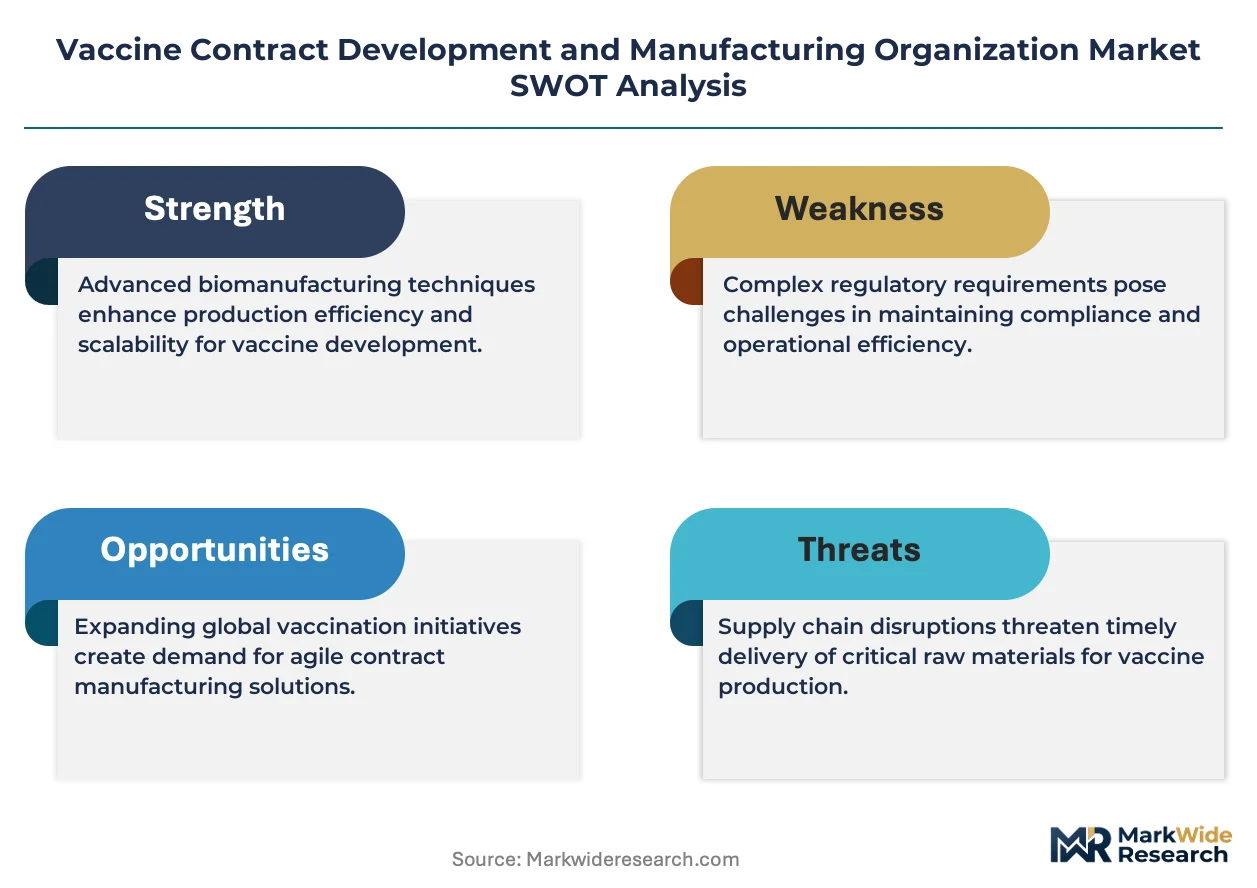
mRNA platform complexity and lipid nanoparticle formulation bottlenecks are concentrating sponsor demand on CDMOs with demonstrated cGMP sterile fill-finish capabilities, reshaping competitive positioning around regulatory track record rather than capacity alone.
Growth Catalysts
- EMA's ATMP classification pathway:Accelerated review frameworks for advanced therapy medicinal products reduce time-to-market for viral vector vaccines, incentivizing European sponsor outsourcing.
- Pandemic preparedness stockpiling:National immunization programs in the United States, Switzerland, and South Korea are locking in multi-year manufacturing contracts for emergency surge capacity.
- Continuous manufacturing adoption:Integrated perfusion bioreactor-to-purification workflows compress batch cycle times from weeks to days for mammalian cell culture processes.
Market Restraints
- Plasmid DNA supply concentration:Three specialized suppliers control high-quality GMP plasmid feedstock for mRNA templates, creating single-source vulnerability for CDMOs without backward integration into nucleic acid production.
- FDA sterility assurance expectations:Enhanced guidance on container closure integrity testing and visual inspection protocols extend facility qualification timelines by 8-14 months for new aseptic lines.
- Specialized talent scarcity:Cell-line engineering and process analytical technology expertise pools are insufficient relative to biologics capacity expansion rates across major manufacturing clusters.
Strategic Opportunities
- India's CDMO regulatory upgrade trajectory:CDSCO's phased alignment with ICH Q7 and Q10 standards positions Indian contract manufacturers for WHO prequalification entry into Gavi and UNICEF supplier networks.
- Personalized neoantigen vaccine workflows:Patient-specific mRNA cancer vaccines require distributed, rapid-turn manufacturing nodes rather than centralized bulk facilities, favoring regional CDMO networks.
- Japan's vaccine self-sufficiency mandate:METI's domestic biomanufacturing incentives and PMDA's accelerated consultation pathways attract CDMO joint ventures with Japanese pharmaceutical sponsors.
Industry Challenges
- Multi-product facility contamination control:Viral vector and mRNA campaigns in shared suites demand rigorous cleaning validation and environmental monitoring protocols that compress campaign scheduling flexibility.
- Technology transfer execution risk:Sponsor-to-CDMO knowledge gaps in lipid nanoparticle formulation scale-up generate batch failure rates above 15% during initial commercial runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaccine Contract Development and Manufacturing Organization Market |
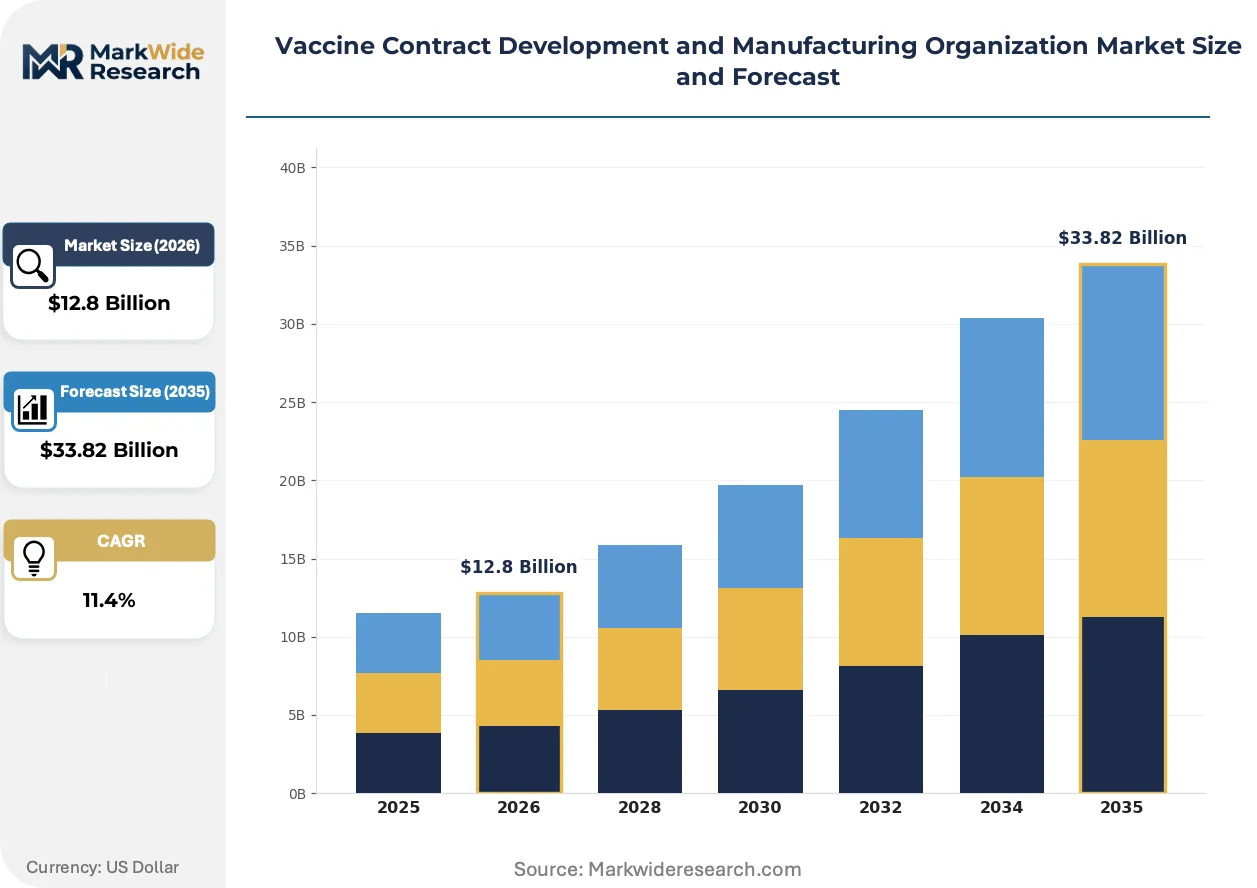
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
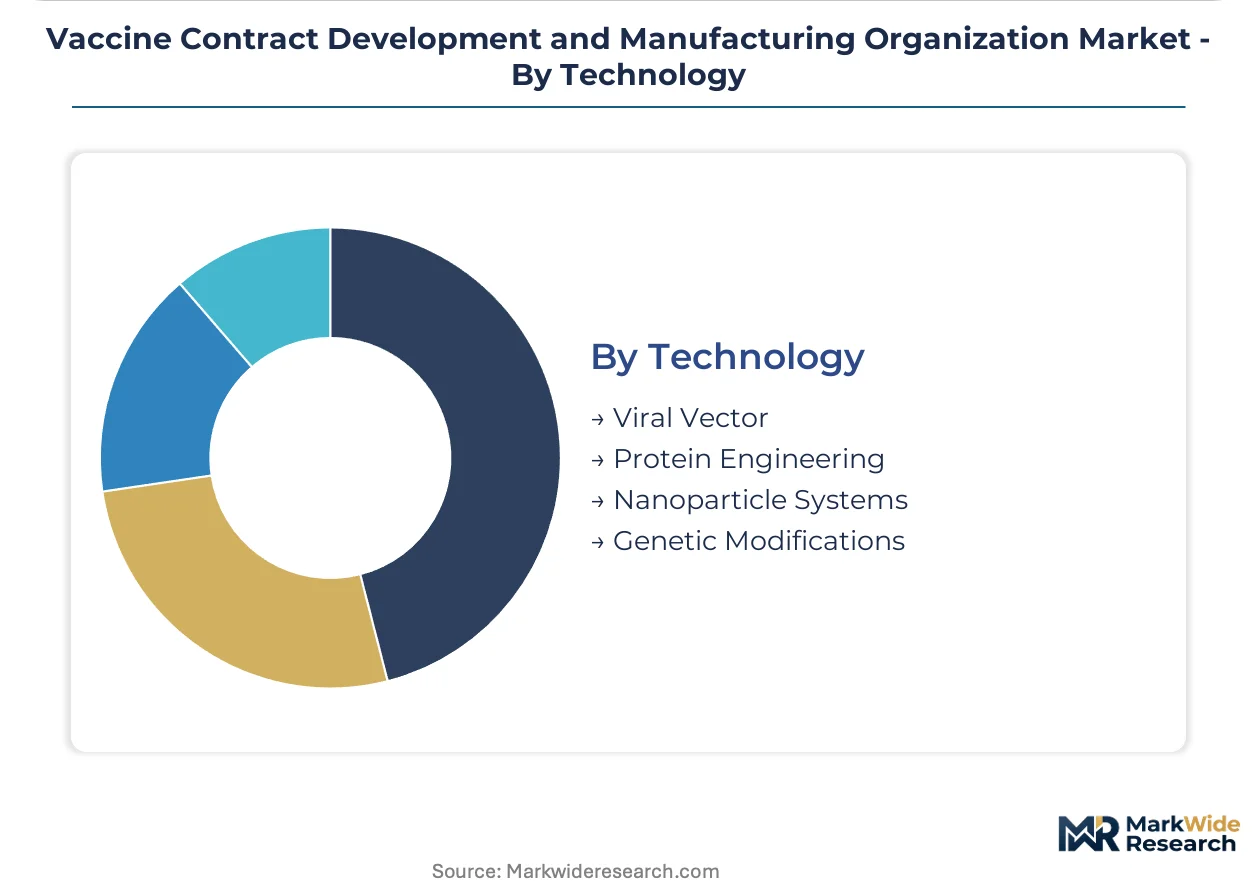
| Segmentation | Service Type: Process Development, Analytical Testing, Fill & Finish, Quality Control Product Type: Inactivated Vaccines, Live Attenuated Vaccines, Subunit Vaccines, mRNA Vaccines End User: Pharmaceutical Companies, Biotech Firms, Government Agencies, Research Institutions Technology: Viral Vector, Protein Engineering, Nanoparticle Systems, Genetic Modifications |
| Companies Covered | Lonza Group, Catalent, Thermo Fisher Scientific, Samsung Biologics, WuXi Biologics, Charles River Laboratories, FUJIFILM Diosynth Biotechnologies, Emergent BioSolutions, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaccine Contract Development and Manufacturing Organization Market Trends and Innovations
Process intensification and modular facility architectures are compressing the traditional boundaries between clinical and commercial manufacturing, enabling faster platform switches between vaccine modalities.
Single-use bioreactor systems are expanding into commercial-scale mammalian cell culture workflows, displacing stainless-steel infrastructure across viral vector and protein subunit vaccine production. Mid-cap biotech sponsors are adopting 2,000-liter single-use trains for phase III campaigns to avoid capital lock-in on dedicated assets. This technology shift is expanding into multi-product facility designs that reduce changeover downtime from weeks to days.
EMA's quality-by-design guidelines and FDA's emerging technology program are converging on real-time release testing expectations for critical quality attributes. CDMOs must now demonstrate process analytical technology integration prior to commercial license approval. Viral vector programs face the steepest compliance burden, with regulators demanding enhanced adventitious agent detection and replication-competent virus clearance validation.
Biotech sponsors are consolidating supplier relationships around integrated discovery-to-commercial platforms rather than fragmented service procurement. Large pharmaceutical sponsors now require CDMO partners to maintain dedicated project teams spanning cell-line development through commercial release. This concentration is most visible in the United States, where top-ten vaccine sponsors have reduced their active CDMO rosters by 40% since 2022.
Vaccine Contract Development and Manufacturing Organization Market Segmentation
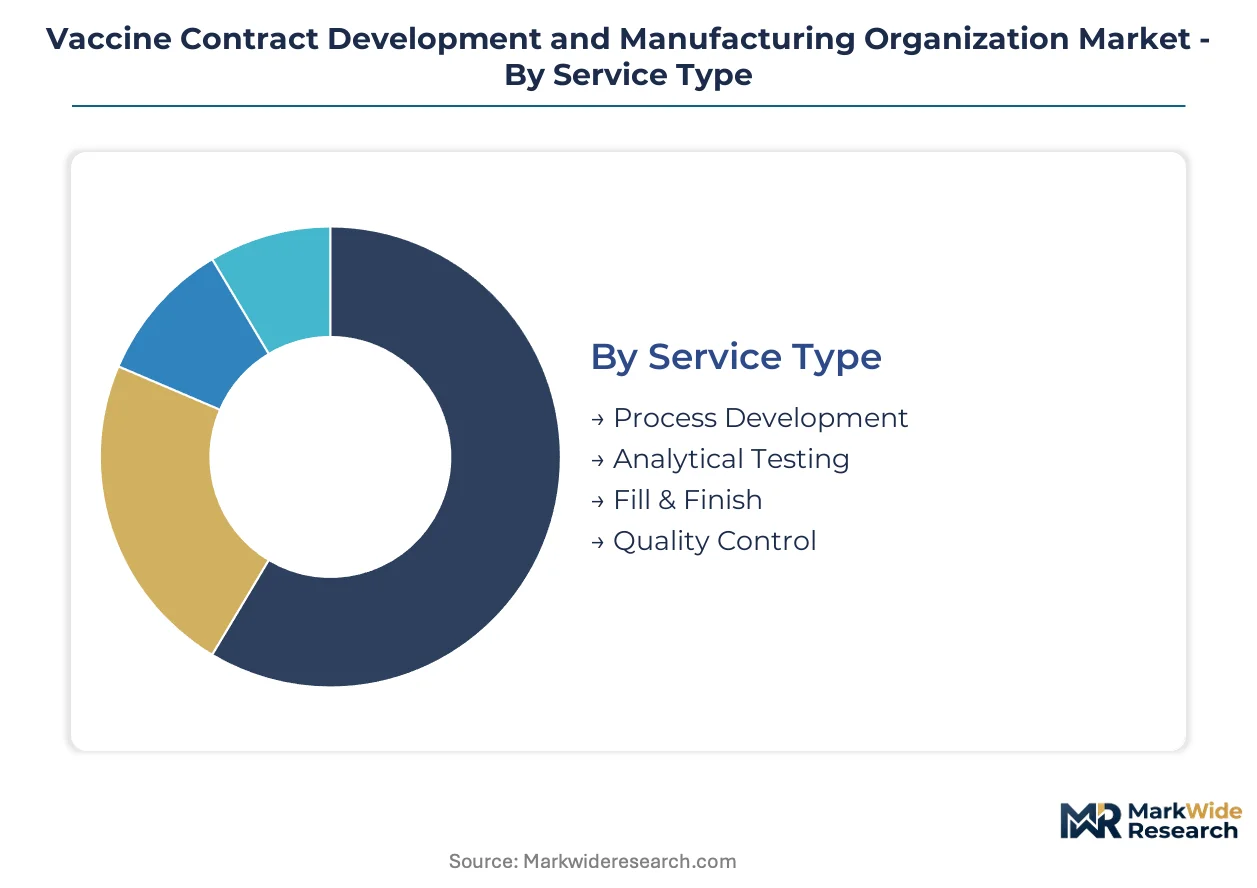
CDMO procurement patterns diverge sharply across sponsor types and technology platforms, with mRNA workflows commanding fundamentally different capability bundles than traditional viral or bacterial vaccine manufacturing. Understanding these fault lines clarifies where margin pools concentrate and which service lines justify capacity expansion.
Service Type:
Biotech sponsors select service tiers based on internal manufacturing maturity and regulatory submission timelines rather than molecule type alone.
- Process Development:Cell-line engineering, perfusion optimization, and scale-up validation for 2,000-20,000 liter campaigns. Sponsors in South Korea and Switzerland outsource entire upstream packages to compress IND-to-PPQ timelines by 30-40%.
- Analytical Testing:Identity, purity, potency, and stability assays under ICH Q2(R1) guidelines. Demand concentrates with CDMOs holding FDA and EMA dual-site inspection histories for real-time release testing adoption.
- Fill & Finish:Aseptic vial filling, lyophilization, and automated visual inspection for sterile injectables. Capacity bottlenecks in lipid nanoparticle handling are reshaping sponsor location decisions toward CDMOs with dedicated isolator lines.
- Quality Control:Batch release, environmental monitoring, and regulatory documentation. Government agencies in the United States require dedicated QC suites for emergency stockpile manufacturing under 21 CFR 211.
Volume sits with Fill & Finish; growth tilts toward Process Development.
Product Type:
Platform complexity and cold-chain requirements create four distinct outsourcing economics that sponsors match to CDMO capability matrices.
- mRNA Vaccines:Lipid nanoparticle encapsulation and ultra-cold storage logistics. EMA's ATMP classification pathway accelerates European sponsor reliance on specialized CDMOs with demonstrated sterile fill-finish track records for nucleic acid products.
- Subunit Vaccines:Recombinant protein purification and adjuvant formulation. Manufacturing in India targets WHO prequalification for Gavi and UNICEF supply networks under CDSCO's evolving ICH alignment.
- Inactivated Vaccines:Pathogen cultivation, chemical inactivation, and alum adjuvant blending. Established technology with stable demand from government pandemic preparedness programs in the United States and South Korea.
- Live Attenuated Vaccines:Cold-adapted strain production and potency titration. Containment infrastructure requirements limit viable CDMO partners to facilities with BSL-3 capabilities and dedicated viral suites.
Revenue concentrates in mRNA; expansion velocity favors Subunit Vaccines.
End User:
Contract structures and technical engagement depth vary substantially across sponsor organizational types and funding mechanisms.
- Pharmaceutical Companies:Multi-product, multi-year master service agreements with dedicated project teams. Large sponsors in the United States have consolidated active CDMO rosters by 40% since 2022, favoring integrated discovery-to-commercial platforms.
- Biotech Firms:Milestone-based contracts with heavy phase-appropriate validation requirements. Early-stage sponsors prioritize CDMOs offering rapid cell-line development and single-use bioreactor flexibility for clinical campaigns.
- Government Agencies:Cost-plus contracts with surge capacity clauses and technology transfer obligations. BARDA and equivalent bodies in Switzerland lock in multi-year manufacturing commitments for emergency stockpiling.
- Research Institutions:Fee-for-service arrangements for preclinical and Phase I material production. Academic sponsors generate demand for smaller batch sizes and expedited analytical turnaround.
Contract value aggregates with Pharmaceutical Companies; deal flow velocity runs highest among Biotech Firms.
Technology:
Platform selection determines facility capital intensity, regulatory pathway, and the specific process analytical technology stacks CDMOs must deploy.
- Viral Vector:Adeno-associated virus and lentivirus production for gene-therapy-derived vaccines. FDA sterility assurance expectations extend facility qualification timelines by 8-14 months for new aseptic lines handling replication-deficient vectors.
- Protein Engineering:Yeast and mammalian expression systems with glycoengineering optimization. Samsung Biologics and comparable facilities in South Korea anchor commercial-scale production for export markets.
- Nanoparticle Systems:Self-assembling protein scaffolds and lipid-based delivery vehicles. Process development margins expand as sponsors push formulation robustness studies earlier into clinical timelines.
- Genetic Modifications:Plasmid DNA templates and mRNA synthesis for nucleic acid platforms. Three specialized suppliers control high-quality GMP plasmid feedstock, creating single-source vulnerability for CDMOs without backward integration into nucleic acid production.
Installed capacity favors Protein Engineering; capability investment prioritizes Viral Vector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for vaccine contract development and manufacturing services concentrates in jurisdictions with dense biopharmaceutical clusters and stringent regulatory oversight. The United States, Switzerland, and South Korea host the dominant manufacturing footprints, while emerging capacity investments in India and Japan reshape supply geography.
United States
BARDA and ASPR lock in multi-year surge capacity contracts for pandemic preparedness stockpiles, anchoring demand for sterile fill-finish infrastructure. FDA's emerging technology program accelerates process analytical technology adoption timelines for commercial license holders. The Greater Boston and San Francisco Bay Area clusters concentrate viral vector and mRNA platform development, with CDMOs operating dedicated multi-product facilities under 21 CFR 211.
Switzerland
Swissmedic's alignment with EMA quality-by-design guidelines attracts European sponsor outsourcing for advanced therapy medicinal products. The Basel-Zurich corridor anchors Lonza Group's biologics network, hosting multi-product viral vector campaigns for international pharmaceutical sponsors. Cantonal economic development agencies co-finance facility expansions targeting lipid nanoparticle formulation capabilities.
South Korea
MFDS accelerated consultation pathways compress IND-to-PPQ timelines for biotech sponsors targeting Asian regulatory submissions. Samsung Biologics' Songdo campus drives capacity additions exceeding 600,000 liters of mammalian cell culture volume. Government biomanufacturing incentives under the K-Bio Lab initiative attract CDMO joint ventures with domestic pharmaceutical groups.
India
CDSCO's phased ICH Q7 and Q10 alignment positions contract manufacturers for WHO prequalification entry into Gavi and UNICEF supplier networks. The Hyderabad-Bengaluru corridor concentrates recombinant protein and subunit vaccine production for export markets. Domestic sponsors leverage cost structures 40-60% below Western benchmarks while upgrading to cGMP standards for regulated market access.
Japan
METI's vaccine self-sufficiency mandate redirects government procurement toward domestic biomanufacturing capacity. PMDA's accelerated consultation pathways for novel platform technologies attract CDMO partnerships with Japanese pharmaceutical sponsors. The Kanto and Kansai regions host emerging viral vector and mRNA manufacturing investments targeting regional supply security.
Vaccine Contract Development and Manufacturing Organization Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers commanding premium positioning in mRNA workflows while regional fabricators compete on cost and turnaround velocity. Market structure tilts toward consolidation among top-ten sponsors, who have reduced active CDMO rosters by 40% since 2022. Three strategic archetypes dominate: integrated discovery-to-commercial platforms, capacity-heavy mammalian cell culture specialists, and niche viral vector boutiques. Competitive moves concentrate on multi-year master service agreements with dedicated project teams and backward integration into plasmid DNA and lipid feedstock production.
Within the integrated platform tier, Lonza Group and Thermo Fisher Scientific exemplify archetypes spanning cell-line development through commercial release, while Samsung Biologics occupies a position as a capacity-driven Asian anchor. WuXi Biologics represents the China-based discovery-to-commercial model with global facility networks. These four entities sit within distinct geographic and capability clusters rather than direct overlap, reducing head-to-head confrontation while intensifying sponsor consolidation pressure.
| Leading Market Players |
|---|
| Lonza Group |
| Catalent |
| Thermo Fisher Scientific |
| Samsung Biologics |
| WuXi Biologics |
| Charles River Laboratories |
| FUJIFILM Diosynth Biotechnologies |
| Emergent BioSolutions |
| Merck KGaA |
| Others |
Pricing and Supply Chain Analysis
mRNA sterile fill-finish capability gaps versus commoditized protein subunit manufacturing bifurcate contract economics across the Vaccine Contract Development and Manufacturing Organization landscape, concentrating pricing power with FDA-validated nucleic acid specialists while compressing margins for undifferentiated bulk biologics producers in India and China.
Pricing Analysis
Volume aggregates with standard mammalian cell culture campaigns while margins concentrate in lipid nanoparticle formulation and real-time release testing services. Three-tier pricing structure across premium, standard, and economy levels separates mRNA platform specialists with EMA ATMP classification track records from multi-product viral vector fabricators and cost-driven Indian subunit vaccine manufacturers. Pricing pressure stems from sponsor consolidation reducing active CDMO rosters by 40% since 2022. Biotech firms exhibit highest price sensitivity due to milestone-dependent funding, while BARDA cost-plus contracts anchor premium tier stability.
Supply Chain Analysis
Plasmid DNA feedstock rests on three specialized GMP suppliers in the United States and Europe, creating single-source vulnerability for mRNA template production. Lipid excipients and cholesterol derivatives draw from Swiss and German specialty chemical producers, while single-use bioreactor bags hinge on thermoplastic elastomer supply from South Korean and Japanese polymer specialists. Tariff exposure runs through cross-border technology transfer of cell-line engineering know-how. Distribution runs through sponsor-directed logistics with cold-chain custody validation for ultra-cold mRNA storage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated discovery-to-commercial platforms, with FDA sterility assurance timeline extensions of 8-14 months forcing smaller viral vector boutiques into distressed exits or acquisition.
For Market Incumbents: Deepen backward integration into plasmid DNA and lipid nanoparticle feedstock production to neutralize single-source supply risk from the three dominant GMP template suppliers. Lock in multi-year master service agreements with dedicated project teams spanning cell-line development through commercial release to defend against sponsor roster consolidation. Prioritize isolator line capacity additions in Switzerland and South Korea where cantonal and K-Bio Lab incentives co-finance facility expansion. For New Entrants and Emerging Players: Biotech sponsors in Japan offer the most penetrable entry point given METI's vaccine self-sufficiency mandate and PMDA's accelerated consultation pathways for novel platforms. Target distributed manufacturing nodes for personalized neoantigen cancer vaccines, which require rapid-turn regional capacity rather than centralized bulk facilities. Pursue CDSCO alignment consulting services to position Indian contract manufacturers for WHO prequalification into Gavi and UNICEF networks. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap viral vector specialists possessing BSL-3 containment infrastructure and EMA quality-by-design documentation, given EMA's ATMP classification pathway acceleration and the scarcity of replication-competent virus clearance validation expertise. Long-term viability favors assets with demonstrated sponsor-to-CDMO technology transfer execution below 15% batch failure rates. Watch lipid nanoparticle formulation robustness study timing as the signal indicating which CDMOs can compress IND-to-PPQ timelines for mRNA sponsors.| Strategic Initiative | Industry Significance |
|---|---|
| Plasmid DNA Backward Integration | Captive supply of GMP template feedstock neutralizes single-source concentration risk from three dominant suppliers. |
| Isolator Line Capacity Expansion | Dedicated aseptic infrastructure for lipid nanoparticle handling commands premium sponsor location decisions under FDA sterility guidance. |
| EMA ATMP Classification Track Record | Demonstrated advanced therapy medicinal product pathway expertise accelerates European sponsor outsourcing decisions. |
| Single-Use Bioreactor Modular Deployment | 2,000-liter train flexibility reduces biotech sponsor capital lock-in while enabling rapid platform switches between modalities. |
| WHO Prequalification Alignment Consulting | CDSCO ICH Q7 and Q10 upgrade support positions Indian manufacturers for Gavi and UNICEF supplier network entry. |
Research Methodology
Multi-period observation of CDMO capacity announcements, regulatory inspection outcomes, and sponsor outsourcing contract structures anchored the trend analysis, supplemented by interviews with biopharmaceutical development executives, regulatory affairs leads at FDA and EMA, formulary directors at national immunization programs, and hospital procurement managers managing emergency stockpiles. Secondary validation drew from FDA emerging technology program filings, EMA quality-by-design submission assessments, ClinicalTrials.gov protocol registrations, and WHO prequalification inspection reports. Bottom-up facility capacity modeling triangulated against top-down sponsor spend allocation surveys.
Input-output matrices mapped bioreactor utilization rates, batch cycle times, and technology transfer success frequencies across service type, product platform, and geographic manufacturing clusters to generate volume and value projections. Segmentation dimensions spanned process development depth, fill-finish isolator configuration, viral vector versus mRNA platform specialization, and regional regulatory cluster alignment. CAGRs were derived from sponsor pipeline conversion rates and capacity absorption curves. Forecast inputs incorporated MFDS accelerated consultation pathway adoption rates and CDSCO ICH alignment implementation phases.
Caveats apply where FDA sterility assurance guidance revisions, plasmid DNA supplier consolidation, or sponsor technology platform shifts could materially shift the outlook. Forecasts assume sustained BARDA and ASPR multi-year surge capacity commitments, EMA ATMP classification pathway stability, and continued biotech funding access for milestone-dependent outsourcing contracts. A small set of named triggers—WHO TRS mRNA platform consistency guideline finalization, lipid excipient tariff escalations, and BSL-3 containment facility approval delays—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Lansoprazole API Market
Pharmaceuticals
Indapamide Market
Pharmaceuticals
South Africa Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Cervical Cancer Drugs Market
Pharmaceuticals
Anthrax Treatment Market
Pharmaceuticals
Live Attenuated Vaccines Market
Pharmaceuticals
Latin America Meglitinide Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Nicotine Replacement Product Market
Pharmaceuticals
Croatia Pharmaceutical Market
Pharmaceuticals
Alprazolam Powder Market
Pharmaceuticals
Structured Product Label Management Market
Pharmaceuticals
OTC Dry Eye Drops Market
Pharmaceuticals
GCC Generic Injectables Market
Pharmaceuticals
Respiratory Disease Vaccine Market
Pharmaceuticals
Antiviral Immunoglobulin Market