
 Acetylspiramycin Market | 2026-2036
Acetylspiramycin Market Size, Share, and Industry Trends Forecast 2026-2036
Acetylspiramycin Market Insights
China's active pharmaceutical ingredient corridor is reshaping acetylspiramycin supply dynamics. CSPC leverages backward integration into fermentation feedstocks to secure cost advantages. Guangzhou Baiyunshan Pharm anchors southern distribution networks through hospital direct-sales agreements. Lukang Pharm differentiates via specialized powder formulation capacity for pediatric applications.
Acetylspiramycin is a 16-membered macrolide antibiotic synthesized through Streptomyces ambofaciens fermentation followed by acetylation at the 3"- and 4"-hydroxyl positions, yielding improved acid stability and oral bioavailability for gram-positive and atypical pathogen coverage. The injectable segment dominates hospital procurement due to severe infection protocols, while oral formulations sustain retail pharmacy volumes through outpatient respiratory therapy. Therapy area concentration favors infectious diseases applications where macrolide resistance profiles remain favorable, with dental infections representing a narrower but stable niche.
China's NMPA enforces GMP Annex 2 biological product standards that constrain fermentation batch consistency for export qualification. The FDA maintains macrolide cardiac safety labeling requirements that shape formulation development priorities for US-bound manufacturers. India's CDSCO import testing protocols for finished antibiotics add regulatory friction to cross-border trade. Stakeholders must monitor evolving pharmacovigilance databases for QT prolongation signal accumulation that could trigger class-wide restriction reviews.
Market Dynamics
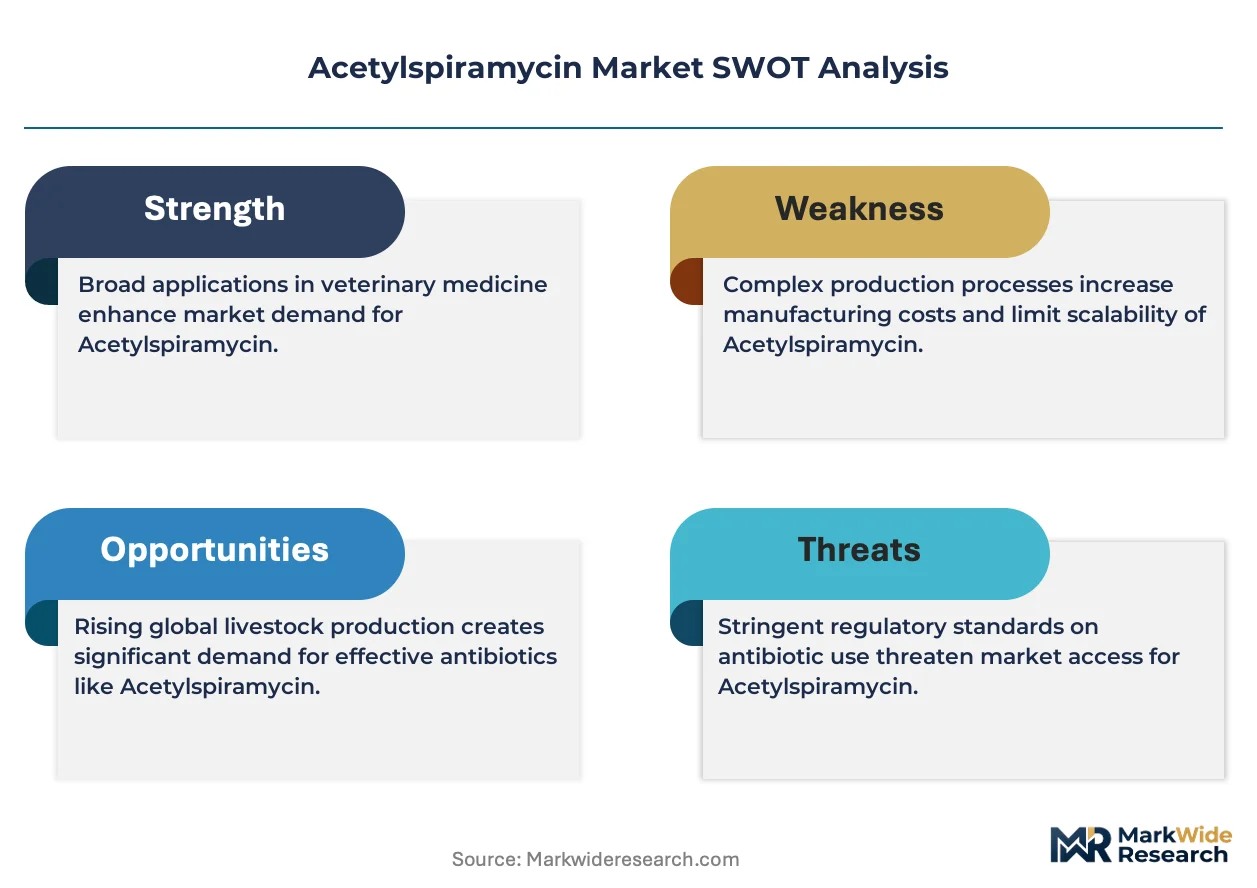
China's NMPA pharmacovigilance tightening for macrolide antibiotics is compressing manufacturing flexibility while hospital procurement consolidation for injectable formulations concentrates demand power among state-owned medical distributors.
Growth Catalysts
- Respiratory infection protocols:Hospital procurement of injectable acetylspiramycin for severe community-acquired pneumonia sustains volume pull through centralized tender systems in Jiangsu province.
- Fermentation feedstock control:Backward integration into Streptomyces ambofaciens cultivation secures batch consistency for export qualification under biological product GMP Annex 2 standards.
- CDSCO import protocols:India's finished antibiotic testing requirements create qualified supplier status premiums for manufacturers achieving documentation compliance.
Market Restraints
- Macrolide cardiac safety labeling:FDA QT prolongation warnings constrain formulation development priorities and limit US market access for new entrants.
- Fermentation batch variability:Biological synthesis inconsistency raises rejection rates at NMPA inspection checkpoints, elevating cost structures for smaller producers.
- Azithromycin substitution:Generic azithromycin price erosion in retail pharmacy channels displaces oral acetylspiramycin for outpatient respiratory therapy.
Strategic Opportunities
- Pediatric powder formulations:Specialized dosing flexibility for children under 12 years opens differentiated positioning against standard tablet presentations.
- Dental infection protocols:Gram-positive coverage advantages in odontogenic abscess protocols sustain niche demand outside respiratory therapy concentration.
- East China manufacturing corridor:Shanghai-Jiangsu pharmaceutical cluster density enables logistics cost advantages for domestic distribution reach.
Industry Challenges
- Fermentation specialist scarcity:Industrial microbiology talent gaps constrain scale-up velocity for biological antibiotic production.
- Pharmacovigilance database integration:QT signal monitoring requirements demand real-world evidence infrastructure that mid-tier manufacturers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetylspiramycin Market |
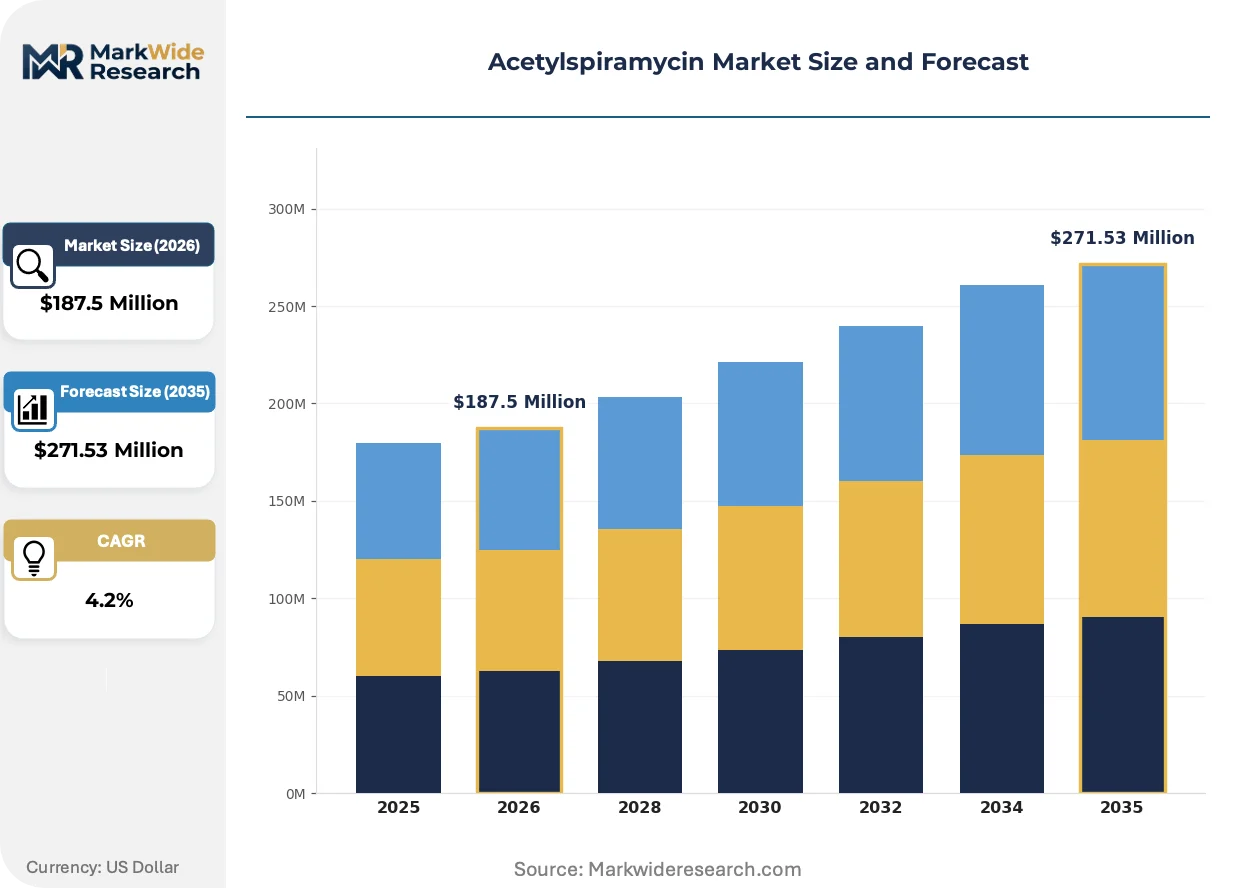
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $271.53 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral, Topical, Powder Therapy Area: Infectious Diseases, Respiratory Infections, Dental Infections, Gynecological Infections End User: Hospitals, Clinics, Pharmacies, Homecare Settings Distribution Channel: Direct Sales, Online Pharmacies, Retail Pharmacies, Wholesalers |
| Companies Covered | Guangzhou Baiyunshan Pharm, CSPC, Lukang Pharm, Tongda Pharm, Zhongxin Pharm, Shantou Jinshi Pharm, HPGC, Top Fond, Bailu Pharm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetylspiramycin Market Trends and Innovations
Continuous processing technology is collapsing traditional batch fermentation economics while regulatory data integrity requirements reshape documentation systems. These forces compress legacy manufacturing margins and elevate capital barriers simultaneously.
Single-use bioreactor systems are collapsing stainless-steel fermentation infrastructure economics. CSPC and Guangzhou Baiyunshan Pharm deploy disposable vessel technology for rapid product changeover. Hospital procurement tenders now favor suppliers demonstrating 20% faster batch turnaround through continuous processing adoption.
China's NMPA GMP Annex 2 biological product standards enforce real-time release testing protocols. Fermentation facilities must install automated in-process control systems to qualify for export certification. Injectable formulation lines in Jiangsu province face the steepest compliance retrofit requirements.
Direct-to-hospital procurement contracts are displacing traditional pharmaceutical distributor intermediation. State-owned hospital groups in East China consolidate antibiotic purchasing through centralized e-tender platforms. This channel compression squeezes distributor margins while rewarding manufacturers with captive logistics capabilities.
Acetylspiramycin Market Segmentation
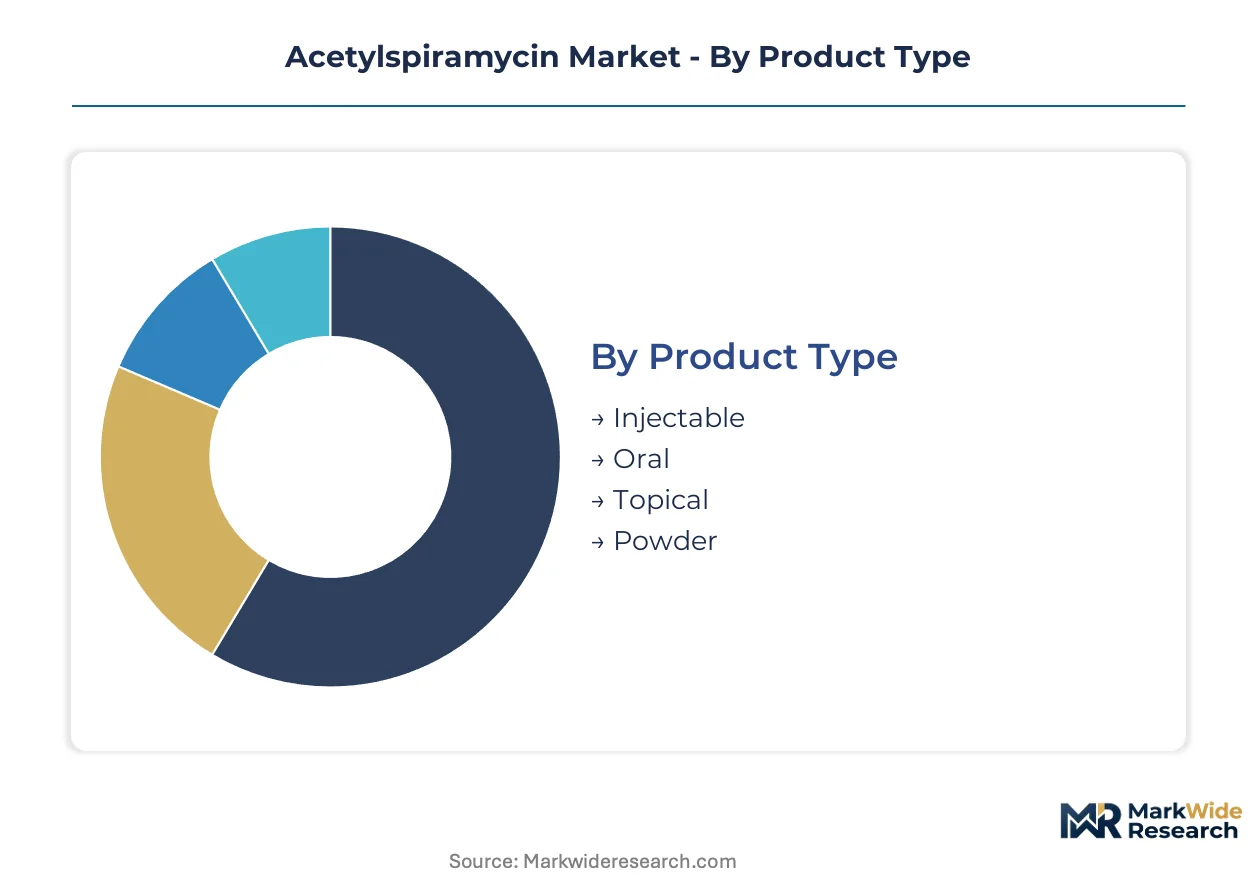
Acetylspiramycin demand fragments across formulation technologies, clinical applications, and procurement channels that each carry distinct regulatory burdens and margin profiles. Understanding these segment boundaries reveals where fermentation batch economics intersect with hospital tender mechanics and retail substitution pressures.
Product Type:
Cycle times vary sharply across formulation categories, with sterile injectable batches requiring extended validation protocols while oral solid doses turn inventory faster through continuous processing lines.
- Injectable:Sterile solution formulations for intravenous or intramuscular administration demand terminal sterilization validation and aseptic filling infrastructure that stretches batch release timelines. Hospital procurement tenders in Jiangsu province concentrate demand for this segment through centralized e-platforms serving severe respiratory infection protocols.
- Oral:Tablet and capsule presentations leverage acetylated molecular stability for gastric acid resistance, enabling outpatient therapy expansion. Retail pharmacy displacement by generic azithromycin constrains volume retention in this category despite broader patient access.
- Topical:Dermatological preparations exploit gram-positive coverage for localized skin infections with reduced systemic exposure.
- Powder:Reconstitutable dry formulations for pediatric dosing flexibility require specialized particle engineering and humidity-controlled packaging.
Injectable formulations anchor the volume base while Powder gains share at the steepest rate through pediatric protocol differentiation.
Therapy Area:
Clinical application segmentation tracks resistance surveillance patterns and guideline positioning that determine formulary inclusion durability across infection types.
- Infectious Diseases:Broad-spectrum gram-positive and atypical pathogen coverage sustains hospital antibiotic stewardship program inclusion where macrolide resistance rates remain favorable relative to alternative classes.
- Respiratory Infections:Community-acquired pneumonia and atypical pneumonia protocols drive the largest absolute prescription volumes through both inpatient injectable and outpatient oral pathways.
- Dental Infections:Odontogenic abscess management exploits tissue penetration advantages for anaerobic coverage in narrower but stable procedural niches.
- Gynecological Infections:Pelvic inflammatory disease protocols utilize atypical pathogen spectrum against Chlamydia and Mycoplasma species in specialized outpatient settings.
Respiratory Infections generates the largest revenue pool while Dental Infections delivers the most defensible margin position against azithromycin substitution.
End User:
Customer type segmentation maps directly to procurement authority concentration and reimbursement pathway complexity that shapes pricing negotiation leverage.
- Hospitals:State-owned medical groups in East China consolidate antibiotic purchasing through direct e-tender platforms that compress distributor intermediation and reward captive logistics capabilities.
- Clinics:Outpatient diagnostic and treatment centers access acetylspiramycin through regional distributor networks with lighter formulary controls than tertiary institutions.
- Pharmacies:Retail channel volumes face accelerating generic azithromycin price erosion that displaces oral acetylspiramycin for self-limiting respiratory presentations.
- Homecare Settings:Post-acute and long-term care environments utilize oral and powder formulations for extended therapy completion outside institutional boundaries.
Hospitals command the procurement volume concentration while Homecare Settings expand most quickly through post-acute therapy protocol extension.
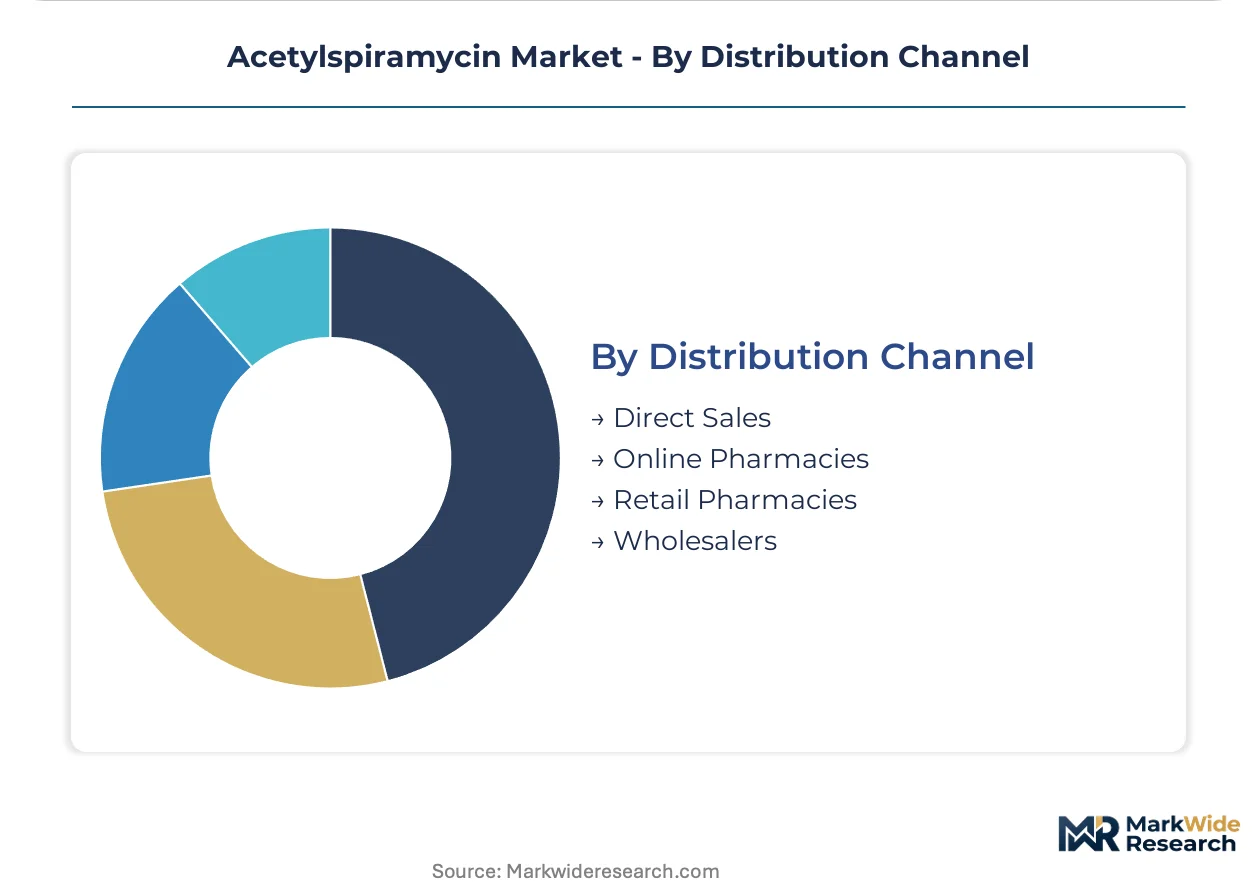
Distribution Channel:
Channel structure segmentation reflects the ongoing compression of pharmaceutical intermediation as manufacturers build direct hospital relationships and digital platforms capture outpatient prescription flow.
- Direct Sales:Manufacturer-to-hospital contracts eliminate distributor margins for large-volume accounts with proven cold-chain logistics performance.
- Online Pharmacies:Digital prescription platforms aggregate outpatient demand with price transparency that accelerates generic substitution dynamics.
- Retail Pharmacies:Brick-and-mortar networks retain walk-in respiratory infection traffic despite share erosion to digital alternatives.
- Wholesalers:Regional distributors maintain relevance for fragmented clinic and small-hospital accounts lacking direct procurement scale.
Direct Sales captures the steepest volume trajectory while Wholesalers defend position through clinic segment service density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA pharmacovigilance standards anchor manufacturing compliance across East Asia, while CDSCO import protocols and FDA cardiac safety labeling shape cross-border trade dynamics for macrolide antibiotics.
China
Hospital procurement consolidation through Jiangsu province e-tender platforms drives injectable formulation demand. NMPA GMP Annex 2 biological product standards enforce real-time release testing for fermentation facilities. The Shanghai-Jiangsu pharmaceutical corridor concentrates acetylspiramycin API production with backward integration into Streptomyces ambofaciens feedstock cultivation.
India
Finished antibiotic import testing requirements under CDSCO protocols create qualified supplier premiums for documentation-compliant manufacturers. The country's national pharmaceutical regulator maintains batch consistency verification for macrolide APIs sourced from East Asian fermentation facilities. Mumbai and Hyderabad-based formulation houses serve as distribution hubs for respiratory therapy demand across South Asian markets.
United States
FDA QT prolongation warnings constrain macrolide formulation development priorities and limit market access for new antibiotic entrants. The agency's cardiac safety labeling requirements shape clinical trial endpoints for US-bound manufacturers. New Jersey and Massachusetts pharmaceutical clusters focus on niche dental infection applications where gram-positive coverage advantages sustain formulary inclusion.
Japan
PMDA antibiotic stewardship guidelines favor macrolide classes with favorable resistance profiles for community-acquired pneumonia protocols. METI industrial policy supports domestic fermentation capacity for critical antibiotic APIs. The Kansai region around Osaka maintains specialized sterile injectable manufacturing for hospital procurement networks.
Brazil
ANVISA import registration requirements for finished antibiotics add documentation friction to cross-border trade from Asian suppliers. The national health surveillance agency enforces stability testing protocols for tropical climate distribution. São Paulo state anchors South American distribution networks for respiratory infection therapy demand.
Acetylspiramycin Market Competitive Landscape
State-affiliated pharmaceutical groups and specialized fermentation houses split the market through divergent scale advantages. The vendor base concentrates around three strategic archetypes: integrated API-to-formulation operators with captive fermentation infrastructure, regional distributors with hospital direct-sales agreements, and pediatric formulation specialists with powder engineering capabilities. Competitive dynamics center on backward integration into biological feedstocks and procurement channel compression through state-owned medical group tenders.
Within the integrated operator tier, CSPC and Guangzhou Baiyunshan Pharm occupy positions exemplifying fermentation feedstock control and southern distribution network density respectively. Lukang Pharm represents the specialized formulation archetype with differentiated powder capacity positioning. These three anchors demonstrate how strategic archetype alignment determines competitive resilience against regulatory tightening and generic substitution pressures.
| Leading Market Players |
|---|
| Guangzhou Baiyunshan Pharm |
| CSPC |
| Lukang Pharm |
| Tongda Pharm |
| Zhongxin Pharm |
| Shantou Jinshi Pharm |
| HPGC |
| Top Fond |
| Bailu Pharm |
| Others |
Pricing and Supply Chain Analysis
NMPA pharmacovigilance tightening for macrolide antibiotics compresses manufacturing flexibility and elevates batch rejection costs, widening spreads between GMP-certified premium tiers and standard-grade formulations while concentrating supply chain investment in East China's Shanghai-Jiangsu corridor.
Pricing Analysis
Domestic procurement in Jiangsu province commands price premiums against export-bound inventory facing CDSCO documentation friction and FDA cardiac safety labeling constraints. Three-tier pricing structure separates NMPA GMP Annex 2 certified injectables from oral solid doses and economy-grade API bulk. Cost compression in oral formulations intensifies as generic azithromycin substitution erodes retail pharmacy volumes. Hospital procurement managers exhibit lowest price sensitivity due to formulary lock-in for severe respiratory protocols.
Supply Chain Analysis
CSPC and Guangzhou Baiyunshan Pharm anchor fermentation capacity through captive Streptomyces ambofaciens cultivation infrastructure in Hebei and Guangdong provinces. API production draws from Chinese fermentation feedstocks, Indian formulation tolling partnerships, and Japanese sterile fill-finish capabilities for PMDA-compliant export. Single-source vulnerability concentrates in NMPA-certified biological product facilities facing real-time release testing retrofit requirements. Distribution runs through state-owned hospital group e-tender platforms compressing traditional pharmaceutical wholesaler intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement platform consolidation transforms acetylspiramycin commercialization into a winner-take-most dynamic where direct e-tender participation determines volume access, rewarding manufacturers with integrated logistics capabilities and real-world evidence infrastructure for pharmacovigilance compliance.
For Market Incumbents: Entrench position through backward integration into fermentation feedstock cultivation securing batch consistency for export qualification, while deploying continuous processing technology to compress 20% faster batch turnaround for hospital tender competitiveness against azithromycin substitution pressure. For New Entrants and Emerging Players: Pursue pediatric powder formulation white space where specialized particle engineering requirements create defensible positioning against tablet commoditization, targeting regional hospital groups in East China with humidity-controlled packaging capabilities for reconstitutable dry formulations. For Investors and Strategic Acquirers: NMPA GMP Annex 2 enforcement reshapes the acquisition landscape toward fermentation specialists with installed biological product capacity and automated in-process control systems. Long-term viability hinges on QT prolongation signal monitoring infrastructure for cardiac safety database integration. The inflection indicator to track is NMPA inspection checkpoint rejection rate trends for macrolide API facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captive Streptomyces ambofaciens cultivation secures batch consistency for NMPA export certification. |
| Continuous Processing Adoption | Single-use bioreactor deployment enables 20% faster batch turnaround for hospital tender competitiveness. |
| Pediatric Formulation Development | Specialized powder engineering creates differentiated positioning against azithromycin retail substitution. |
| Direct Hospital Procurement Integration | E-tender platform participation compresses distributor margins and secures state-owned medical group volume. |
| Pharmacovigilance Infrastructure Investment | Real-time QT signal monitoring satisfies NMPA biological product GMP Annex 2 compliance requirements. |
Research Methodology
The analysis maps injectable, oral, powder, and topical formulation segments, each validated through fermentation process engineers, hospital procurement managers, regulatory affairs specialists, and pediatric formulary directors. Primary interviews with Jiangsu province tender platform administrators and East China distributor network heads combined with secondary validation from NMPA GMP inspection records, CDSCO import testing protocols, FDA macrolide safety labeling archives, and hospital antibiotic stewardship program databases. Bottom-up volume triangulation across therapy areas and top-down value reconciliation against fermentation capacity utilization rates anchored forecast construction.
Assumptions held NMPA pharmacovigilance enforcement trajectory and azithromycin generic substitution pace constant while varying hospital procurement consolidation speed and continuous processing adoption rates across the projection horizon. Segmentation dimensions modeled include formulation technology, therapy area concentration, end-user procurement authority, and distribution channel structure. CAGRs derived from fermentation batch economics extrapolation and tender volume trajectory analysis, with sensitivity to macrolide resistance surveillance patterns and cardiac safety signal accumulation in real-world evidence databases.
Sensitivities concentrate around NMPA inspection checkpoint stringency escalation, QT prolongation class-wide restriction reviews, and hospital procurement platform interoperability standardization. Forecasts reflect documented assumptions regarding fermentation feedstock cost stability and regulatory documentation burden trajectories. Quarterly review of NMPA GMP Annex 2 facility certification rates and CDSCO qualified supplier list updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Bispecific Antibody Therapeutics Contract Manufacturing Market
Pharmaceuticals
Skin Cancer Drugs Market
Pharmaceuticals
Cough Syrup Market
Pharmaceuticals
Global Alpha-Blocker Market
Pharmaceuticals
Unfractionated Heparin Market
Pharmaceuticals
Global Contraceptive Drugs and Devices Market
Pharmaceuticals
Global Antiemetic Drugs Market
Pharmaceuticals
North America Over the Counter Drugs Market
Pharmaceuticals
India Pharmaceutical Contract Sales Organizations Market
Pharmaceuticals
Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Global Cyclosporine Market
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Europe Diabetes Drugs Market
Pharmaceuticals
Mitochondrial-Based Therapeutics Market
Pharmaceuticals
Global Meningitis Vaccine Market
Pharmaceuticals
Sporanox Market