
 Herpes Labialis Treatment Market | 2026-2036
Herpes Labialis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Herpes Labialis Treatment Market Outlook
EMA's tightened bioequivalence standards for topical antiviral generics is rebalancing the cost-of-entry calculus for European manufacturers. Pfizer Inc. leverages its legacy brand equity in antiviral therapies to sustain premium positioning across retail channels. Sun Pharmaceuticals anchors its competitive stance through aggressive geographic expansion into emerging markets where patent cliffs have opened access. Teva Pharmaceuticals Industries Ltd. differentiates via vertically integrated API-to-finished-dose manufacturing that insulates margin pools from raw material volatility.
Herpes labialis treatment encompasses pharmaceutical interventions targeting recurrent oral HSV-1 lesions, with topical formulations typically containing acyclovir or penciclovir at concentrations between five and ten percent to inhibit viral DNA polymerase and accelerate lesion healing. These therapies serve both aesthetic and pain-management functions for immunocompetent patients experiencing episodic outbreaks. Oral tablets containing valacyclovir occupy the highest-margin tier due to superior bioavailability and patient compliance profiles relative to topical alternatives. Transdermal patch delivery systems represent the fastest-growing administration route segment, driven by innovations in mucoadhesive polymer technology that prolong drug residence time at lesion sites.
FDA bioequivalence requirements, EMA quality guidelines, and WHO prequalification standards collectively shape product development priorities and market access trajectories for generic and innovator manufacturers. The FDA's ANDA review timelines directly determine competitive entry sequencing, while EMA centralized procedures govern pan-European commercialization pathways. Stakeholders must monitor evolving pharmacovigilance obligations and emerging gene-editing therapeutic candidates that could eventually displace conventional antiviral maintenance regimens.
Market Dynamics
Transdermal patch delivery systems are compressing treatment timelines and reshaping patient compliance expectations across oral antiviral therapy categories. Mucoadhesive polymer innovations are enabling sustained drug release at lesion sites, fundamentally altering the competitive calculus between topical and systemic administration routes.
Growth Catalysts
- FDA ANDA Streamlining:The FDA's abbreviated new drug application review pathway compresses generic antiviral time-to-market, accelerating competitive entry for acyclovir and penciclovir formulations.
- Direct-to-Consumer Advertising:Prescription and over-the-counter brand awareness campaigns in the United States drive patient-initiated treatment seeking and expand addressable patient pools.
- Retail Pharmacy Expansion:North American pharmacy chains are dedicating incremental shelf space to cold sore therapies, improving product accessibility and impulse purchase conversion.
Market Restraints
- EMA Bioequivalence Standards:Tightened European Medicines Agency requirements for topical antiviral generics elevate development costs and extend validation timelines for European manufacturers.
- API Supply Concentration:Active pharmaceutical ingredient production for nucleoside analogs concentrates in select Asian manufacturing clusters, exposing finished-dose producers to geopolitical and logistics disruptions.
- Gene-Editing Substitution Threat:Emerging CRISPR-based HSV-1 suppression therapies in clinical pipelines threaten long-term displacement of maintenance antiviral regimens.
Strategic Opportunities
- Patent Cliff Access:Emerging markets where brand-name antiviral patents have expired present white-space expansion potential for generic manufacturers with cost-optimized production.
- Telehealth Channel Integration:Virtual consultation platforms enable direct prescription fulfillment for episodic outbreak management, bypassing traditional physician office visits.
- WHO Prequalification Pathway:World Health Organization standards alignment opens procurement access to multilateral health programs in low-income country markets.
Industry Challenges
- Pharmacovigilance Talent Scarcity:Post-market surveillance for rare adverse events in antiviral therapies requires specialized regulatory affairs expertise that commands premium compensation.
- Cold Chain Integrity:Temperature-sensitive polymer formulations in advanced transdermal patches necessitate capital-intensive distribution infrastructure that smaller manufacturers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herpes Labialis Treatment Market |
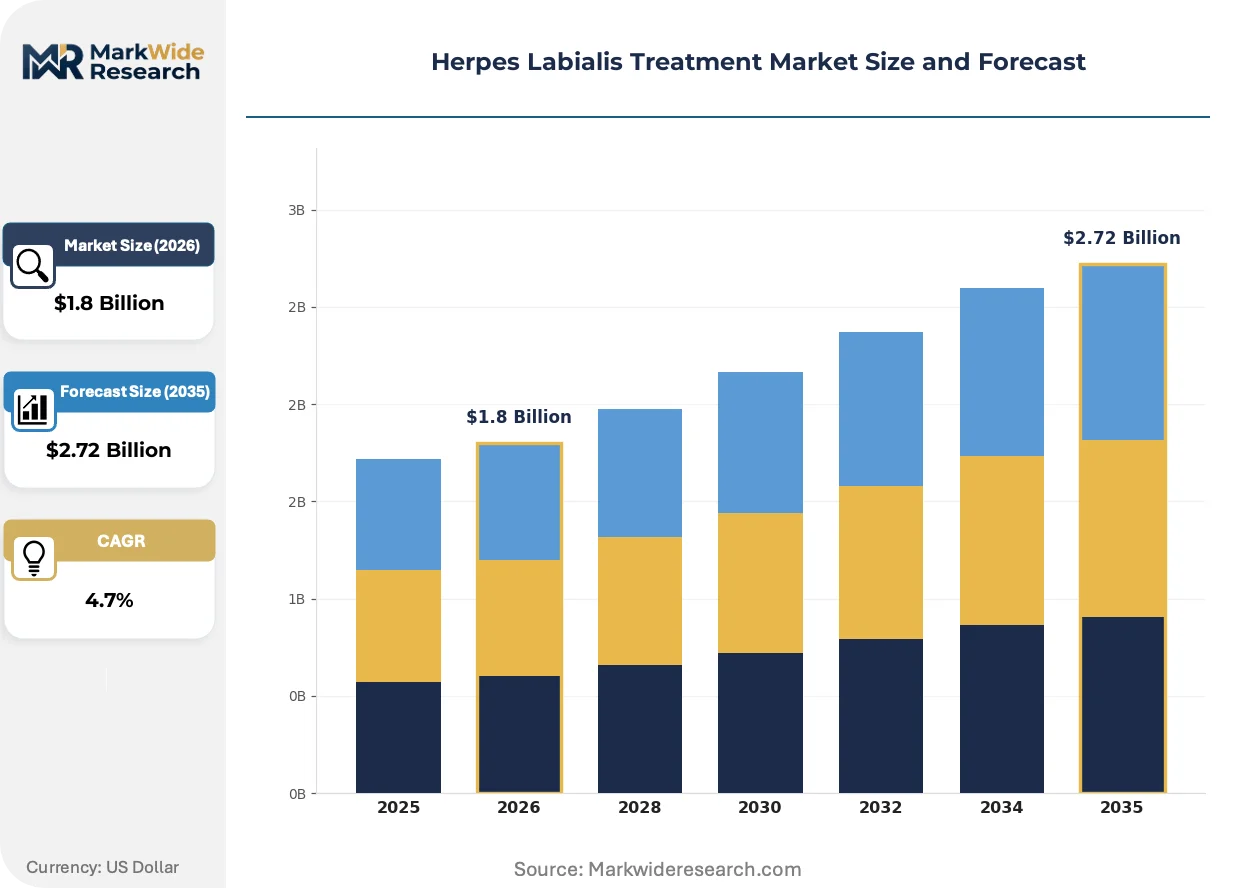
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Creams, Oral Tablets, Ointments, Patches Active Ingredient: Acyclovir, Valacyclovir, Penciclovir, Famciclovir Administration Route: Topical, Oral, Intravenous, Transdermal End User: Hospitals, Clinics, Pharmacies, Homecare |
| Companies Covered | Bayer AG, Abbott Laboratories, Novartis AG, Mylan N.V., Amneal Pharmaceuticals, Bausch Health, Sun Pharmaceuticals, Pfizer Inc., Teva Pharmaceuticals Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herpes Labialis Treatment Market Strategic Shifts
Patient-administered episodic care models are displacing clinic-dependent treatment protocols across immunocompetent populations. Technology convergence between materials science and pharmaceutical formulation is producing administration routes that extend therapeutic residence time at lesion sites.
Mucoadhesive polymer matrices embedded with acyclovir or penciclovir are automating sustained-release kinetics previously achievable only through systemic dosing. Immunocompetent patients experiencing recurrent outbreaks adopt these patches at accelerating rates due to discreet application and reduced dosing frequency. The technology is automating compliance optimization and compressing the competitive advantage window for conventional cream formulations.
EMA centralized procedure harmonization is consolidating pan-European commercialization pathways for topical antiviral generics. Manufacturers now navigate a single regulatory gateway rather than fragmented national approvals, reducing compliance overhead. Generic developers targeting European Union member states restructure submission strategies around this centralized framework.
Subscription-based replenishment models for episodic outbreak management are displacing reactive pharmacy visits among chronically affected patient segments. Direct-to-consumer platforms capture recurring revenue streams while traditional retail channels lose foot traffic. The United States exhibits the most pronounced channel migration as telehealth-integrated prescription services gain patient preference.
Herpes Labialis Treatment Market Segmentation
Herpes labialis treatment markets fragment across administration preferences, reimbursement pathways, and patient self-management capabilities. Understanding these divides reveals where formulation innovation concentrates versus where commoditization pressures dominate.
Product Type:
Patient convenience and outbreak severity drive product selection, with episodic users prioritizing discretion and chronic sufferers demanding efficacy speed.
- Topical Creams:Formulations containing five to ten percent acyclovir or penciclovir deliver localized viral DNA polymerase inhibition directly to lesion sites. Demand clusters among first-time outbreak patients in US retail pharmacy channels where FDA-approved OTC options eliminate prescription friction.
- Oral Tablets:Systemic valacyclovir and famciclovir achieve superior bioavailability through hepatic first-pass metabolism, compressing healing timelines versus topical alternatives. Prescription volumes concentrate in telehealth-integrated platforms serving recurrent outbreak patients seeking rapid symptom resolution without clinic visits.
- Ointments:Petroleum-based vehicles with suspended antiviral actives provide occlusive barriers prolonging drug-skin contact. Preference persists among pediatric populations and patients with compromised skin barrier function.
- Patches:Mucoadhesive polymer matrices enable sustained-release kinetics and discreet application. Momentum is accelerating fastest among working-age adults prioritizing cosmetic concealment during professional interactions.
Oral tablets lead on scale; patches lead on momentum.
Active Ingredient:
Patent status and generic availability reshape procurement economics across health system formularies and retail channels.
- Acyclovir:The foundational nucleoside analog with established safety profiles across immunocompetent and immunocompromised populations. Generic saturation has compressed US pricing to commodity levels.
- Valacyclovir:L-valyl ester prodrug of acyclovir delivering three to five times improved oral bioavailability through enhanced intestinal absorption. Preferred by US physicians for episodic suppression regimens requiring less frequent dosing.
- Penciclovir:Topical nucleoside analog with prolonged intracellular half-life enabling less frequent application schedules than acyclovir creams. EMA quality guidelines govern European manufacturing standards.
- Famciclovir:Oral prodrug of penciclovir with enhanced bioavailability for systemic HSV management. Prescription volumes trail valacyclovir due to later generic entry and higher acquisition costs.
Acyclovir dominates volume; valacyclovir commands premium positioning.
Administration Route:
Route selection hinges on outbreak frequency, lesion location accessibility, and patient dexterity for self-application.
- Topical:Direct lesion application with minimal systemic exposure. Preferred for immunocompetent patients with isolated facial outbreaks.
- Oral:Systemic distribution achieving therapeutic levels at mucosal and neural ganglia sites. Dominates recurrent suppression protocols.
- Intravenous:Hospital-administered acyclovir for disseminated HSV in immunocompromised patients or severe primary infections. Confined to inpatient settings.
- Transdermal:Emerging polymer-based patches combining sustained release with cosmetic discretion. Expanding most quickly among professional workforce demographics.
Oral administration anchors revenue; transdermal delivery is gaining share fastest.
End User:
Channel economics and reimbursement structures determine where manufacturers concentrate promotional investment versus price competition.
- Hospitals:Inpatient settings managing severe primary HSV or immunocompromised patients requiring IV acyclovir. Procurement governed by group purchasing organization formularies.
- Clinics:Outpatient dermatology and infectious disease practices prescribing oral antivirals for recurrent cases. Volume is migrating toward telehealth alternatives.
- Pharmacies:Retail chains and independent dispensaries handling both prescription fulfillment and OTC topical sales. Shelf space allocation increasingly favors patch formats.
- Homecare:Direct-to-consumer channels including subscription replenishment and telehealth-integrated prescription services. US patients exhibit strongest channel migration here.
Pharmacies retain volume leadership; homecare channels show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The herpes labialis treatment industry traces its commercial origins to Burroughs Wellcome's 1982 acyclovir approval in the United Kingdom, establishing nucleoside analog therapy as the foundation for modern antiviral intervention. Subsequent FDA approvals in the United States and EMA harmonization across continental Europe transformed episodic outbreak management into a standardized pharmaceutical category spanning prescription and over-the-counter channels.
United States
Direct-to-consumer advertising expenditure and telehealth platform integration drive patient-initiated prescription seeking for valacyclovir and topical therapies. FDA ANDA pathway streamlining accelerates generic entry timelines for acyclovir formulations. New Jersey-based pharmaceutical clusters concentrate finished-dose manufacturing and regulatory affairs expertise serving North American distribution networks.
Germany
EMA centralized procedure harmonization and statutory health insurance reimbursement stability sustain consistent demand for prescription antivirals. The country's national pharmaceutical regulator enforces tightened bioequivalence standards for topical generic formulations. Rhine-Ruhr industrial corridors host active pharmaceutical ingredient synthesis operations supplying European finished-dose producers.
Japan
Aging demographics and elevated HSV-1 seroprevalence among elderly populations expand the addressable patient pool for episodic suppression regimens. PMDA review timelines and post-market surveillance requirements shape product development priorities for domestic and multinational manufacturers. Osaka-Kobe pharmaceutical clusters concentrate formulation R&D and regional headquarters operations for Asia-Pacific market coordination.
India
Patent cliff openings for brand-name antivirals and cost-optimized generic manufacturing capabilities attract multinational licensing agreements. CDSCO manufacturing facility inspections and WHO prequalification alignment determine export eligibility to multilateral procurement programs. Hyderabad-Visakhapatnam pharmaceutical corridors specialize in nucleoside analog API production and contract research services.
Brazil
Expanding private health insurance coverage and pharmacy retail chain consolidation improve patient access to prescription oral antivirals. ANVISA bioequivalence study requirements and import licensing protocols govern generic product registration timelines. São Paulo state concentrates commercial operations, clinical trial infrastructure, and distribution logistics serving Latin American markets.
Herpes Labialis Treatment Market Competitive Environment
The competitive structure tilts toward vertically integrated multinational pharmaceutical conglomerates with established antiviral portfolios and generic specialists exploiting patent expirations. Market concentration remains moderate, with prescription oral therapies showing greater consolidation than commoditized topical segments. Three archetypes dominate: legacy innovators leveraging brand equity, generic manufacturers optimizing cost structures, and emerging market specialists capturing volume through geographic expansion. Dominant competitive moves include strategic partnerships for API supply security and portfolio diversification into novel delivery formats.
Among North American and European pharmaceutical conglomerates, Pfizer Inc. and Bayer AG exemplify legacy innovator positioning through sustained brand equity in antiviral therapeutic categories. Teva Pharmaceuticals Industries Ltd. occupies the generic specialist archetype, with corporate structure indicating vertically integrated manufacturing capabilities spanning active pharmaceutical ingredient through finished-dose production. Sun Pharmaceuticals represents emerging market expansion specialists, with geographic naming signaling Indian operational origins and competitive positioning anchored in cost-optimized production for patent-expired markets.
| Leading Market Players |
|---|
| Bayer AG |
| Abbott Laboratories |
| Novartis AG |
| Mylan N.V. |
| Amneal Pharmaceuticals |
| Bausch Health |
| Sun Pharmaceuticals |
| Pfizer Inc. |
| Teva Pharmaceuticals Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Telehealth-integrated prescription fulfillment preference in the United States is compressing traditional pharmacy margins and forcing manufacturers to restructure channel economics around direct-to-patient models that alter pricing power distribution.
Pricing Analysis
The bundled-versus-unbundled service split separates subscription-based replenishment models from transactional pharmacy purchases. Three-tier pricing structure across premium, standard, and economy levels tracks formulation complexity, with transdermal patches commanding premium positioning against commoditized acyclovir creams. Price differentiation hinges on FDA approval tier and brand heritage, with innovator brands insulated from generic erosion in oral tablet categories. Cost compression in topical segments is intensifying because retail pharmacy chains consolidate procurement leverage, while oral systemic therapies show lower price sensitivity among telehealth-integrated patient cohorts seeking rapid outbreak resolution.
Supply Chain Analysis
WHO prequalification and FDA bioequivalence certification gating determines export eligibility and formulary access for finished-dose producers. Active pharmaceutical ingredient synthesis concentrates in India and China, with nucleoside analog production anchored in Hyderabad-Visakhapatnam corridors and select Asian manufacturing clusters. Finished-dose formulation draws from New Jersey-based pharmaceutical clusters and Rhine-Ruhr industrial corridors. Single-source vulnerability in API supply exposes producers to geopolitical disruption and logistics congestion. Distribution runs through retail pharmacy chains, telehealth-integrated direct fulfillment platforms, and hospital group purchasing organization networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The herpes labialis treatment market functions as a stable compounder, with recurrent outbreak epidemiology ensuring persistent demand replenishment regardless of macroeconomic cyclicality.
For Market Incumbents: Deepen backward integration into nucleoside analog API production to insulate margin pools from raw material volatility and Asian supply concentration risk. Fortify telehealth platform partnerships to defend prescription volume share against emerging direct-to-consumer entrants. Gene-editing substitution threats in clinical pipelines demand accelerated patch formulation R&D to extend competitive moats beyond conventional antiviral mechanisms. For New Entrants and Emerging Players: Telehealth-integrated subscription services represent the most penetrable channel white-space, particularly for episodic outbreak management among working-age professional demographics. Target emerging markets where patent cliffs have opened access to generic valacyclovir and penciclovir formulations. A cost-optimized manufacturing footprint aligned with WHO prequalification standards enables multilateral procurement program access. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated generic specialists possessing captive API supply and emerging market licensing networks. Long-term viability over the five-to-ten year horizon rests on delivery format innovation rather than molecular patent exclusivity. The signal to watch is CRISPR-based HSV-1 suppression therapy clinical trial readouts that could accelerate antiviral maintenance regimen displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Mucoadhesive Patch R&D Investment | Polymer innovation extends drug residence time and commands premium pricing in professional workforce segments. |
| Telehealth Platform Partnership | Direct prescription fulfillment bypasses traditional pharmacy channels and captures recurring subscription revenue. |
| WHO Prequalification Alignment | Standards compliance opens procurement access to multilateral health programs in low-income country markets. |
| API Supply Security Agreement | Long-term nucleoside analog sourcing contracts mitigate geopolitical disruption exposure from Asian concentration. |
| EMA Centralized Procedure Submission | Single regulatory gateway reduces compliance overhead versus fragmented national approval pathways across Europe. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs leads, formulary directors at group purchasing organizations, telehealth platform executives, and retail pharmacy category managers with secondary validation against FDA ANDA filings, EMA centralized procedure submissions, ClinicalTrials.gov pipeline tracking, and WHO prequalification status databases. Bottom-up patient volume modeling and top-down pharmaceutical expenditure reconciliation ensured cross-methodological consistency.
Segment-weighting approaches distributed value and volume projections across administration route, active ingredient patent status, patient outbreak frequency, and regional regulatory cluster typologies. CAGRs were derived from epidemiological trend extrapolation, pricing trajectory assumptions, and channel shift elasticity modeling. Forecast inputs incorporated HSV-1 seroprevalence demographic shifts, telehealth adoption curves, and transdermal patch technology diffusion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to gene-editing therapeutic clinical progress and API supply chain reconfiguration. Projections reflect documented assumptions regarding regulatory pathway stability and patient self-management behavior continuity. A model refresh is warranted upon material change in CRISPR-based HSV-1 suppression therapy phase transition timing or EMA bioequivalence standard revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Anticholinergic Drugs Market
Pharmaceuticals
Global Cyclosporine Market
Pharmaceuticals
Oncology Adjuvants Market
Pharmaceuticals
Germany Pneumococcal Vaccines Market
Pharmaceuticals
Latin America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
OX40 Receptor Agonist Market
Pharmaceuticals
Drug Allergy Market
Pharmaceuticals
Carbapenem Market
Pharmaceuticals
Ampicillin Drugs Market
Pharmaceuticals
Depression Drugs Market
Pharmaceuticals
Europe Veterinary Pharmaceuticals Market
Pharmaceuticals
Small Volume Parenteral Market
Pharmaceuticals
Global Manidipine Hydrochloride Market
Pharmaceuticals
Triamcinolone Ointment Chlorofluorocarbons Market
Pharmaceuticals
Hydroxycarbamide Market
Pharmaceuticals
Optic Nerve Disorders Drugs Market