
 LAMEA Breast Pumps Market | 2026-2036
LAMEA Breast Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Breast Pumps Market Insights
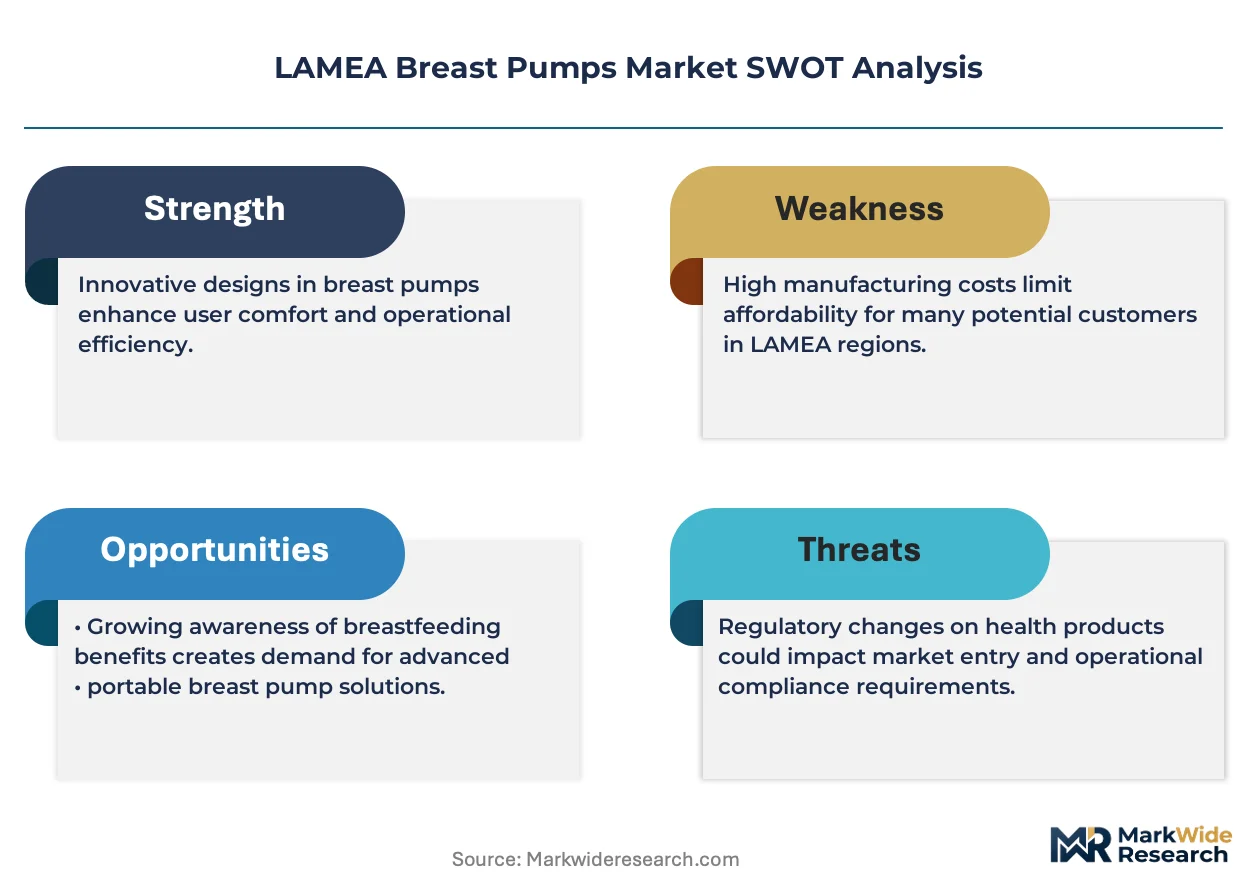
CE marking under the EU Medical Device Regulation is expanding compliance costs for manufacturers exporting from Latin America into European-aligned markets. Medela AG leverages its Swiss manufacturing heritage to sustain premium positioning across Middle Eastern duty-free channels. Koninklijke Philips NV anchors volume through hospital group purchasing contracts in Saudi Arabia and the UAE. Pigeon Corporation differentiates via compact electric designs tailored to Southeast Asian distributor specifications.
A breast pump is a mechanical or electrical device that extracts milk from lactating breasts through rhythmic suction cycles typically operating at 30-50 cycles per minute with vacuum levels between 100-250 mmHg, serving the primary purpose of enabling infant feeding when direct nursing is impractical. Electric pumps dominate hospital procurement budgets across the LAMEA region due to clinical throughput requirements, while wearable pumps capture premium segments among employed professionals in Gulf Cooperation Council cities. Manual pumps retain cost-sensitive volume in rural Nigeria and Kenya, though margin pools concentrate in battery-operated and hospital-grade electric categories.
Brazil's national health regulator ANVISA governs medical device registration timelines that shape product launch sequencing for foreign manufacturers. South Africa's South African Health Products Regulatory Authority enforces device quality standards that filter low-cost Asian imports from public tender participation. Saudi Arabia's SFDA alignment with Gulf Standardization Organization medical device directives creates a harmonized access corridor across Gulf states. Stakeholders must monitor reimbursement list updates in national health insurance schemes to anticipate volume shifts between personal-use and hospital-grade segments.
Market Dynamics
Wearable pump technology is fragmenting demand across the LAMEA region, splitting procurement between hospital-grade electric systems and discrete personal-use devices that employed professionals in Gulf cities now prioritize for workplace lactation.
Growth Catalysts
- South Africa's National Health Insurance expansion:Public sector procurement of hospital-grade electric pumps is accelerating as maternal health coverage broadens. Public tenders now specify clinical throughput requirements that favor electric over manual categories.
- Wearable suction technology:Battery-integrated wearable designs are capturing employed professional segments in Saudi Arabia and UAE urban centers. These devices enable workplace lactation without infrastructure dependency.
- ANVISA regulatory harmonization:Brazil's streamlined medical device registration timelines are reducing foreign manufacturer entry barriers. Shorter approval cycles compress product launch sequencing for electric pump portfolios.
Market Restraints
- Import duty structures:High tariffs on finished electric pumps in Nigeria and Kenya inflate landed costs for foreign manufacturers. Local assembly requirements remain underdeveloped.
- Lithium battery supply concentration:Battery cell sourcing concentrates in East Asian suppliers, exposing wearable pump manufacturers to input cost volatility and logistics disruption.
- Manual pump substitution persistence:Cost-sensitive rural segments in Nigeria and Kenya retain manual pump preference due to electricity access gaps and price elasticity.
Strategic Opportunities
- Underpenetrated Nigerian hospital infrastructure:Public maternity facility electrification programs are expanding addressable demand for hospital-grade electric pumps. Federal health infrastructure investment is accelerating.
- SFDA-GSO harmonized corridor:Saudi Arabia's alignment with Gulf Standardization Organization directives creates single-registration access across UAE, Kuwait, Qatar, and Oman. Manufacturers can leverage one approval for five markets.
- Pharmacy-distributor channel integration:Direct-to-pharmacy distribution partnerships are bypassing traditional medical device importer markups in Brazil and South Africa. Margin capture shifts toward manufacturers.
Industry Challenges
- Biomedical technician scarcity:Hospital-grade pump maintenance and calibration capacity concentrates in major urban centers. Rural facility service coverage gaps extend equipment downtime.
- CE marking compliance cost escalation:EU Medical Device Regulation requirements for manufacturers exporting from Latin America are inflating certification timelines and testing expenditures. Smaller manufacturers face resource strain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Breast Pumps Market |
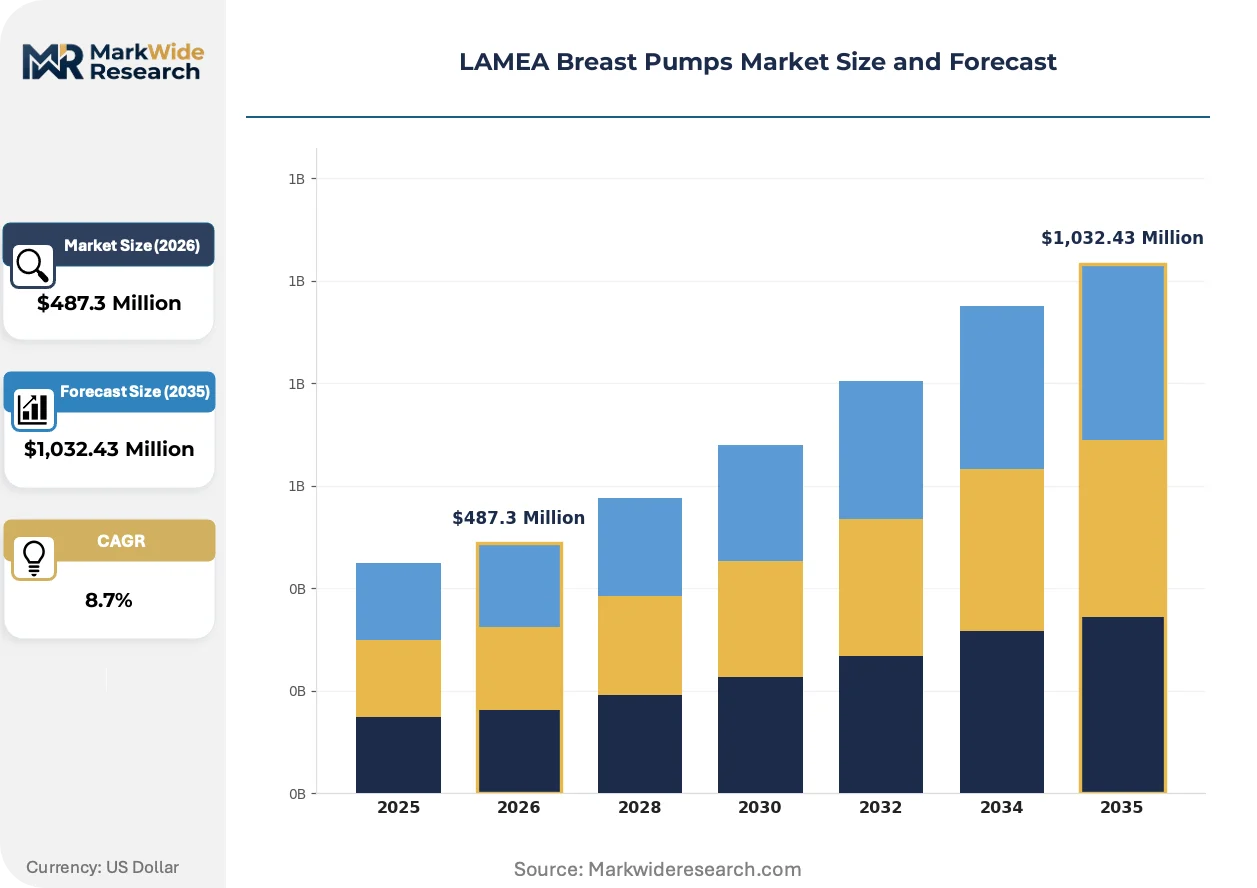
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Pumps, Electric Pumps, Battery-operated Pumps, Wearable Pumps Delivery Mode: Hospital Grade, Personal Use, Portable, Electric End User: New Mothers, Hospitals, Lactation Consultants, Healthcare Providers Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | Medela AG, Koninklijke Philips NV, Pigeon Corporation, Spectra Baby USA, Ameda Inc, Willow Innovations Inc, Lansinoh Laboratories Inc, Ardo Medical AG, Motif Medical, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Breast Pumps Market Trends and Innovations
Three interconnected developments are restructuring competitive positioning across the LAMEA breast pumps landscape: hardware modularization, regulatory convergence, and procurement centralization through hospital group purchasing.
Portable suction hardware is modularizing across the wearable pump segment. Discrete motor units now separate from collection vessels and power systems, enabling component replacement rather than full device retirement. Employed professionals in Dubai, Riyadh, and Johannesburg are adopting these systems for workplace flexibility. This architecture is compressing replacement cycles while expanding aftermarket attachment revenue pools.
South Africa's South African Health Products Regulatory Authority is tightening device quality standards for public tender participation. Quality filtering mechanisms are excluding low-cost Asian imports that previously dominated price-sensitive segments. Hospital procurement departments are responding by consolidating supplier relationships with manufacturers holding documented quality certifications.
Hospital group purchasing organizations are concentrating procurement authority in Brazil and Saudi Arabia. Individual facility purchasing autonomy is contracting as multi-hospital systems negotiate volume-based contracts directly with manufacturers. This consolidation is most visible in São Paulo's private hospital networks and Riyadh's Ministry of Health-affiliated facilities, where standardized electric pump specifications now dominate capital expenditure planning.
LAMEA Breast Pumps Market Segmentation
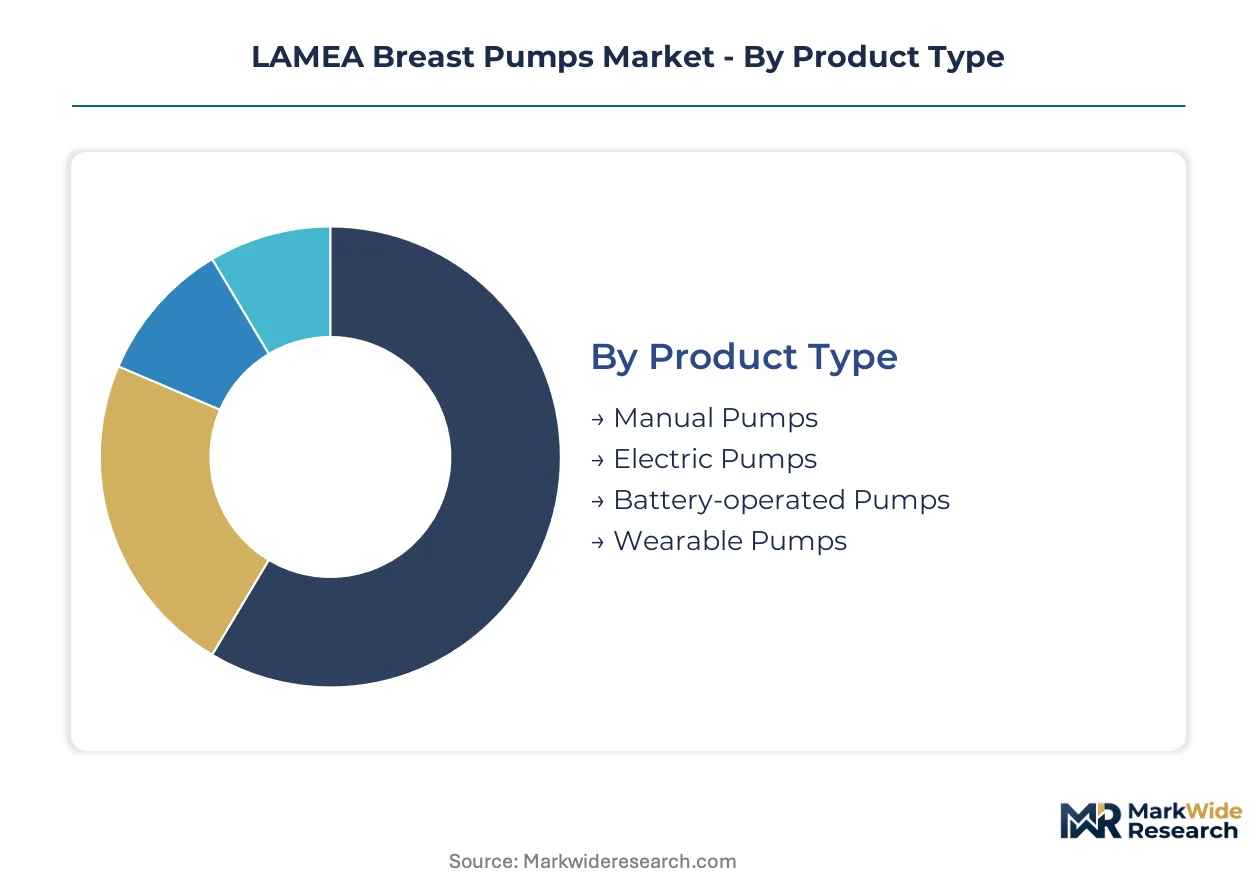
Segmentation in the LAMEA breast pumps market reveals divergent procurement logics across public health systems, private employers, and individual consumers. Each dimension—product technology, clinical specification, user context, and channel access—carries distinct margin profiles and regulatory exposure that shape manufacturer portfolio strategy.
Product Type:
Purchase decisions across LAMEA markets pivot on electricity access reliability and employment status of the lactating mother.
- Electric Pumps:Mains-powered devices operating at 30-50 cycles per minute with vacuum levels between 100-250 mmHg dominate hospital procurement in Brazil and South Africa. ANVISA and SAHPRA registration requirements filter out uncertified competitors from public tender participation.
- Wearable Pumps:Battery-integrated discrete motor units with component-modular architecture are capturing employed professional segments in Dubai, Riyadh, and Johannesburg. Workplace lactation infrastructure gaps in Gulf Cooperation Council cities accelerate adoption of these infrastructure-independent systems.
- Manual Pumps:Hand-operated suction devices retain cost-sensitive volume in rural Nigeria and Kenya where electricity access remains intermittent.
- Battery-operated Pumps:Portable units bridging manual and electric categories serve semi-urban segments with unreliable grid access.
Electric pumps lead on scale; wearable pumps lead on momentum.
Delivery Mode:
Clinical throughput requirements and reimbursement eligibility create tiered demand separation across facility types and insurance coverage.
- Hospital Grade:Multi-user capable systems with closed-system hygiene engineering satisfy South Africa's National Health Insurance maternal health procurement specifications. Public sector tenders now mandate clinical durability standards that exclude personal-use devices.
- Personal Use:Single-user devices dominate out-of-pocket purchases in Brazil's pharmacy-distributor channel where direct-to-consumer distribution partnerships are displacing traditional importer markups.
- Portable:Lightweight battery-powered units serve mobile lactation consultant practices across Nigeria's expanding federal maternity facility network.
- Electric:Mains-dependent systems anchor Saudi Arabia's Ministry of Health-affiliated facility standardization programs.
Hospital grade commands procurement volume; personal use captures margin expansion.
End User:
User type determines price sensitivity, technical support requirements, and channel access patterns across the LAMEA region.
- Hospitals:Institutional procurement concentrates in São Paulo's private hospital networks and Riyadh's government-affiliated facilities where group purchasing organizations negotiate volume-based contracts directly with manufacturers.
- New Mothers:Individual purchasers in Gulf Cooperation Council urban centers prioritize wearable discretion for workplace compatibility.
- Lactation Consultants:Independent practitioners in South Africa and Nigeria require portable equipment for facility-to-facility service delivery.
- Healthcare Providers:Clinic-based physicians in Brazil's Sistema Único de Saúde network specify electric pump integration into maternal care protocols.
Hospitals dominate procurement scale; new mothers drive technology substitution.
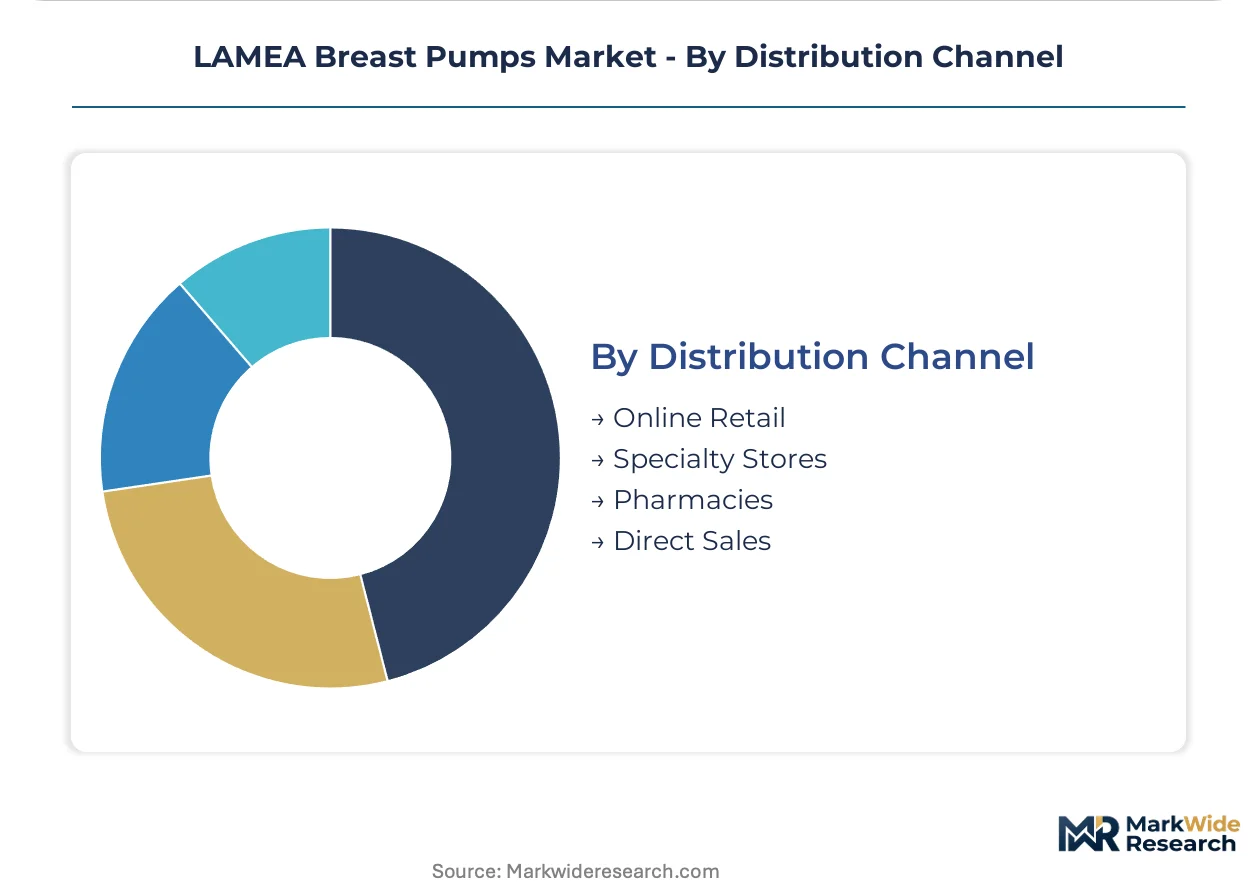
Distribution Channel:
Channel structure determines margin capture allocation between manufacturers, importers, and retail intermediaries.
- Pharmacies:Direct-to-pharmacy distribution partnerships in Brazil and South Africa are bypassing traditional medical device importer markups, shifting margin capture toward manufacturers.
- Online Retail:E-commerce platforms serve wearable pump demand in UAE and Saudi Arabia where employed professionals prioritize purchase convenience.
- Specialty Stores:Maternity-focused retailers in Nigeria's urban centers provide product demonstration for first-time manual pump purchasers.
- Direct Sales:Manufacturer-led contracting with hospital group purchasing organizations dominates Saudi Arabia and Brazil's private hospital procurement.
Pharmacies anchor volume throughput; online retail expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employed professional concentrations in Gulf Cooperation Council urban centers and Brazil's metropolitan healthcare corridors anchor demand generation across the LAMEA breast pumps landscape. Workforce lactation infrastructure gaps in Riyadh, Dubai, and São Paulo drive wearable pump adoption among working mothers. Public health procurement expansion in South Africa and Nigeria reshapes hospital-grade electric pump volumes.
Brazil
ANVISA medical device registration harmonization compresses foreign manufacturer entry timelines for electric pump portfolios. São Paulo's private hospital networks consolidate procurement through group purchasing organizations that negotiate standardized specifications directly with suppliers. Pharmacy-distributor channel integration in Southeast Brazil bypasses traditional importer markups.
South Africa
National Health Insurance maternal health coverage expansion accelerates public sector tenders for clinical-grade electric pumps. SAHPRA quality standard enforcement filters low-cost Asian imports from government procurement participation. Johannesburg's urban professional workforce drives wearable pump demand for workplace lactation compatibility.
Saudi Arabia
SFDA alignment with Gulf Standardization Organization directives creates single-registration market access across five Gulf states. Riyadh's Ministry of Health-affiliated facilities standardize electric pump specifications through centralized procurement. Employed professionals in Jeddah and Dammam prioritize discrete wearable designs for infrastructure-independent workplace use.
Nigeria
Federal maternity facility electrification programs expand addressable demand for hospital-grade electric pumps in public infrastructure. Import duty structures on finished electric devices inflate landed costs and complicate foreign manufacturer market entry. Lagos and Abuja urban centers concentrate lactation consultant practices requiring portable equipment mobility.
United Arab Emirates
Dubai's employed professional demographic prioritizes wearable pump convenience through e-commerce retail channels. MOHAP medical device regulations align with Gulf Standardization Organization harmonization frameworks. Abu Dhabi's hospital procurement centralization mirrors Saudi volume-based contracting structures.
LAMEA Breast Pumps Market Competitive Landscape
The competitive structure tilts toward diversified medical device conglomerates with hospital procurement relationships and specialist maternity care innovators with wearable technology portfolios. Market participation splits between Swiss and European heritage manufacturers leveraging premium positioning and Asian specialists optimizing compact electric designs. Dominant competitive moves include pharmacy-distributor channel integration bypassing traditional importer networks and regulatory harmonization exploitation across Gulf Standardization Organization corridors.
Within the heritage medical device tier, Medela AG exemplifies Swiss manufacturing positioning sustaining premium access across Middle Eastern duty-free channels. Koninklijke Philips NV anchors volume through hospital group purchasing contracts in Saudi Arabia and UAE facilities. Pigeon Corporation occupies a compact design specialization tailored to Southeast Asian distributor specifications and price-accessible segments.
| Leading Market Players |
|---|
| Medela AG |
| Koninklijke Philips NV |
| Pigeon Corporation |
| Spectra Baby USA |
| Ameda Inc |
| Willow Innovations Inc |
| Lansinoh Laboratories Inc |
| Ardo Medical AG |
| Motif Medical |
| Others |
Pricing and Supply Chain Analysis
Biomedical technician scarcity across South Africa and Nigeria widens labor-cost differentials between urban service hubs and rural deployment zones, compressing pricing-tier spreads for hospital-grade electric pumps while inflating aftermarket service premiums.
Pricing Analysis
The bundled-vs-unbundled service split separates procurement contracts in Saudi Arabia and Brazil from retail transactions in Nigeria and Kenya. Three-tier pricing structure across premium wearable, standard electric, and economy manual levels stratifies by certification grade and after-sales coverage. Cost compression in the manual tier is intensifying because import duty structures inflate landed costs for finished electric devices. Public hospital procurement committees in South Africa exhibit lowest price sensitivity due to National Health Insurance reimbursement guarantees, while rural individual purchasers in Nigeria demonstrate highest elasticity.
Supply Chain Analysis
Workforce-availability constraints in Swiss and German precision manufacturing hubs limit hospital-grade pump production scaling relative to East Asian assembly capacity for wearable components. Lithium battery cell sourcing concentrates in China, South Korea, and Japan, with medical-grade motor assemblies anchored in Switzerland and Germany. Single-source vulnerability in East Asian battery supply exposes wearable pump manufacturers to input cost volatility and logistics disruption. Distribution runs through hospital group purchasing organizations in Brazil and Saudi Arabia, pharmacy-distributor partnerships in South Africa, and e-commerce platforms in UAE urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Component modularization in wearable pumps and battery cost curves create margin-expansion headroom as premium-tier adoption accelerates among employed professionals in Gulf Cooperation Council cities.
For Market Incumbents: Lock in hospital group purchasing organization relationships across São Paulo private networks and Riyadh Ministry of Health facilities before wearable technology substitutes erode electric pump procurement volumes. Deepen backward integration into battery cell sourcing to mitigate East Asian supply concentration risk. Prioritize CE marking compliance investment to sustain European-aligned market access as EU Medical Device Regulation timelines extend.
For New Entrants and Emerging Players: Wearable suction miniaturization offers a technology-first wedge into Dubai and Johannesburg professional segments where workplace lactation infrastructure gaps persist. Target underpenetrated Nigerian federal maternity facilities electrifying through federal health infrastructure investment. Deploy direct-to-pharmacy distribution partnerships in Southeast Brazil to bypass legacy importer markups and capture manufacturer margin.
For Investors and Strategic Acquirers: Diversified medical device conglomerates with hospital procurement relationships are the most active acquirers in this space, seeking wearable technology portfolios to complement electric pump volume positions. Acquisition target archetypes include compact-design specialists with Southeast Asian distributor networks and modular-component innovators with aftermarket attachment revenue streams. Monitor SAHPRA quality standard enforcement tightening as inflection indicator for import filtration intensity and domestic manufacturing opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU Medical Device Regulation compliance sustains access to European-aligned procurement channels for Latin American exporters. |
| Hospital System Partnership | Group purchasing organization contracts in São Paulo and Riyadh concentrate procurement authority and standardize specifications. |
| Software Companion Development | Mobile application integration for wearable pumps enables suction cycle tracking and workplace discretion optimization. |
| Reimbursement Strategy | National Health Insurance list positioning in South Africa determines public sector volume allocation between device tiers. |
| Backward Integration | In-house battery assembly capacity reduces East Asian supply concentration exposure for wearable pump portfolios. |
Research Methodology
Coverage spans Latin America, Middle East, and Africa, with primary inputs from each regional cluster combining structured interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and pharmacy distribution heads with secondary validation. Regulatory filings from ANVISA, SAHPRA, SFDA, and MOHAP anchor compliance timeline analysis. Hospital procurement databases, GPO contract disclosures, and customs import records provide volume and pricing benchmarks. Bottom-up facility-level demand estimates triangulate against top-down national health expenditure projections.
Granularity-level modeling disaggregates volume and value across product type, delivery mode, end user, and distribution channel dimensions, with additional segmentation by regional regulatory cluster and electrification infrastructure tier. CAGRs derive from fitted growth curves calibrated to historical procurement data and policy implementation schedules. Battery cost curve trajectories and maternal health coverage expansion timelines feed wearable pump adoption assumptions across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to National Health Insurance implementation pacing in South Africa and federal electrification program execution in Nigeria. Forecasts reflect documented assumptions regarding regulatory harmonization progress and battery supply chain stability. Material deviation in Gulf Standardization Organization alignment timelines or lithium cell sourcing disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wearable Breast Pumps Market
Medical Devices
Disposable Needle Guides Market
Medical Devices
Asia-Pacific Biosurgery Market
Medical Devices
United Kingdom Neonatal and Prenatal Devices Market
Medical Devices
Ventilation Devices Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
Global Glaucoma Surgery Devices Market
Medical Devices
Global Micro Guide Catheters Market
Medical Devices
Global Abdominal Surgical Robot Market
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Global Syringe Pumps Market
Medical Devices
Sphincterotomes Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
IoT Medical Devices Market
Medical Devices
Stethoscope Hygiene Devices Market