
 Global Seasonal Influenza Vaccines Therapeutics Market | 2026-2036
Global Seasonal Influenza Vaccines Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Seasonal Influenza Vaccines Therapeutics Market Foresight
European biomanufacturing capacity is broadening as cell-culture facilities replace legacy egg-dependent infrastructure. Sanofi leverages its transcontinental production footprint to supply both trivalent and quadrivalent formulations. GlaxoSmithKline anchors its position through adjuvant technology leadership and long-term procurement contracts with public health agencies. CSL Seqirus specializes in cell-based and recombinant platforms, differentiating its output from conventional egg-derived stocks.
Seasonal influenza vaccines therapeutics encompass prophylactic biologics formulated to elicit adaptive immunity against circulating influenza A and B strains, typically manufactured through egg-based propagation, cell culture, or recombinant DNA methods with hemagglutinin content standardized at 15 micrograms per strain per dose. These products serve to reduce infection incidence, severity, and transmission within populations, with annual reformulation driven by WHO strain selection recommendations. Inactivated vaccines dominate commercial volume due to established safety profiles and broad age-label approvals, while recombinant vaccines capture premium positioning through egg-free manufacturing and faster scale-up timelines. Intramuscular injection remains the standard delivery modality, though intranasal spray and microneedle patch formats are gaining traction in pediatric and needle-averse segments.
FDA, EMA, and WHO collectively govern strain selection, potency testing, and post-market surveillance for seasonal influenza vaccines, with FDA's accelerated approval pathways and EMA's adaptive licensing frameworks shaping development timelines and market entry strategies. National immunization technical advisory groups in countries including the United States, Germany, and Japan convert regulatory licensure into procurement volumes through inclusion recommendations. Stakeholders must monitor mRNA platform durability data and cell-based capacity buildouts to calibrate portfolio allocation between established and emerging manufacturing modalities.
Market Dynamics
Cell-based manufacturing technology is overtaking egg-based production as the dominant platform across major supply networks, driven by strain mismatch risks and faster production timelines that reshape capacity allocation decisions.
Growth Catalysts
- Pediatric Immunization Expansion:National immunization technical advisory groups in the United States, Germany, and Japan are expanding age-label indications, converting regulatory licensure into procurement volumes through inclusion recommendations.
- EMA Adaptive Licensing:The European Medicines Agency's adaptive licensing frameworks compress development timelines, accelerating market entry for novel formulations and enabling faster response to strain drift.
- Cell-Culture Platform Maturation:Cell-based manufacturing technology reduces production lead times from six months to approximately twelve weeks, enabling closer alignment with WHO strain selection recommendations.
Market Restraints
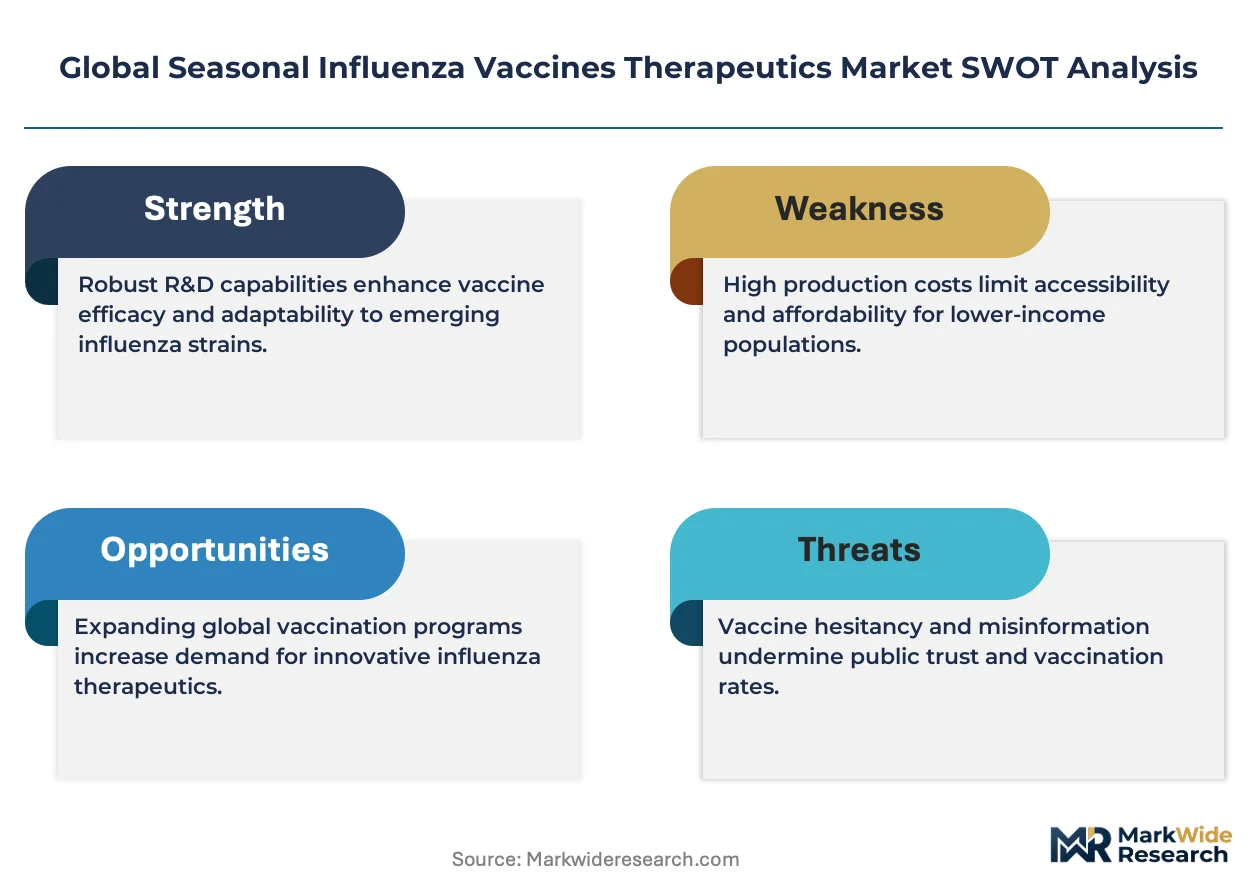
- Egg-Derived Strain Mismatch:Antigenic drift during egg adaptation produces vaccine strains that diverge from circulating wild-type viruses, reducing effectiveness against H3N2 subtypes in particular.
- European Manufacturing Concentration:Cell-culture facility buildouts concentrate in Belgium, the Netherlands, and Germany, creating geographic supply vulnerability and transit-dependent distribution networks.
- Adjuvant Raw Material Volatility:Squalene sourcing from shark liver oil and synthetic alternatives faces price instability and sustainability scrutiny, compressing margin structures for adjuvanted formulations.
Strategic Opportunities
- Chinese Market Penetration:China's national immunization program expansion and NMPA regulatory pathway streamlining create white space for recombinant and cell-based entrants outside legacy egg-based supply relationships.
- Microneedle Patch Distribution:Intradermal delivery systems enable pharmacy-based and retail clinic administration, bypassing traditional healthcare facility dependency and capturing needle-averse adult segments.
- WHO Prequalification Acceleration:The World Health Organization's prequalification program for influenza vaccines opens procurement channels to Gavi-eligible countries and UN agency purchasing mechanisms.
Industry Challenges
- Cell-Culture Technical Talent Scarcity:Bioprocess engineering expertise for large-scale mammalian cell culture remains concentrated among specialists in Basel, Boston, and Melbourne, constraining facility staffing and technology transfer.
- Strain Selection Timing Compression:The six-month lag between WHO strain recommendation and Southern Hemisphere campaign launch forces manufacturers to commit capacity before final potency data confirms antigenic match.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Seasonal Influenza Vaccines Therapeutics Market |
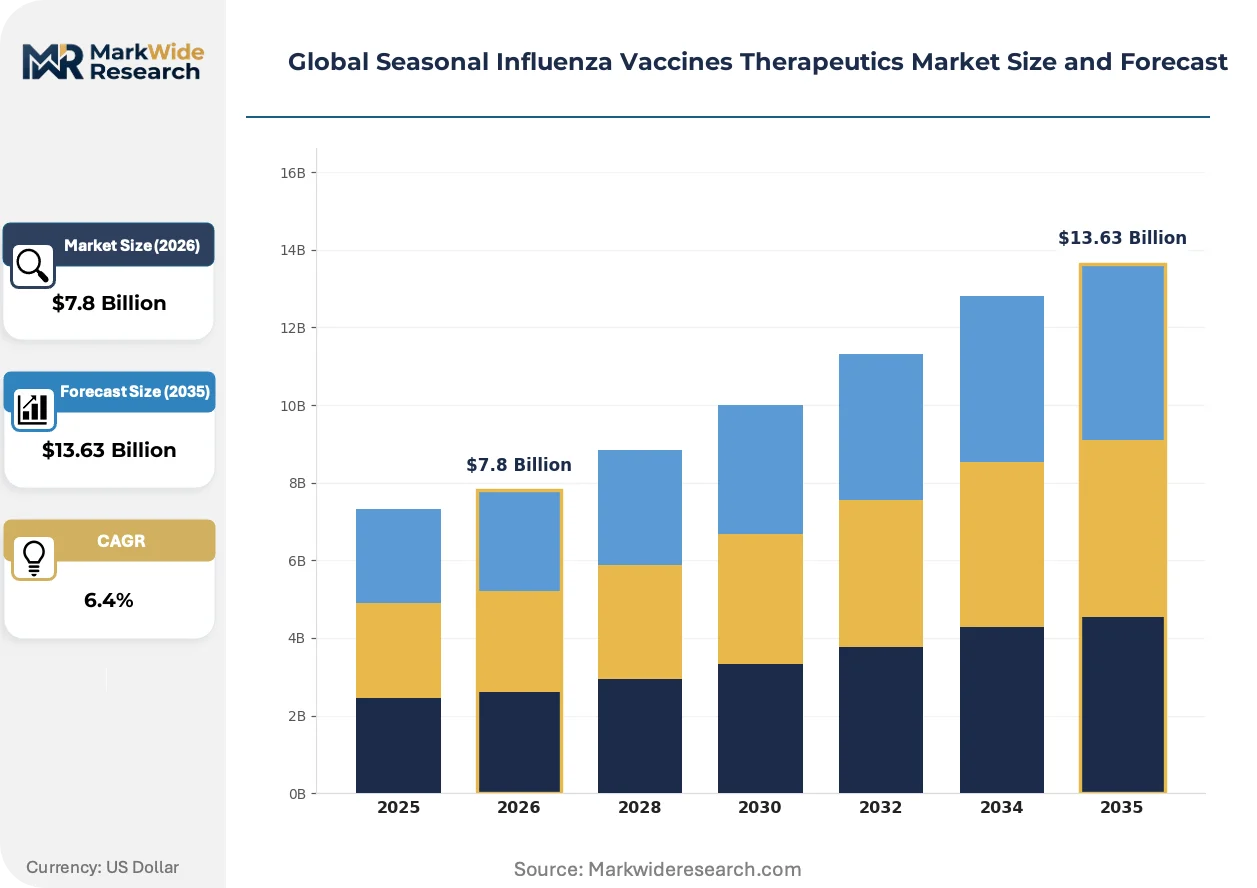
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inactivated Vaccines, Live Attenuated Vaccines, Recombinant Vaccines, Adjuvanted Vaccines, Cell-Based Vaccines Application: Immunization Programs, Post-Exposure Prophylaxis, Pediatric Use, Geriatric Use, High-Risk Population Protection End User: Hospitals, Primary Care Clinics, Public Health Agencies, Travel Clinics, Occupational Health Providers Delivery Technology: Intramuscular Injection, Intranasal Spray, Microneedle Patch, Oral Formulation, Jet Injector |
| Companies Covered | Sanofi, GlaxoSmithKline, CSL Seqirus, Pfizer, AstraZeneca, Merck, Novartis, SINOVAC, Moderna, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Seasonal Influenza Vaccines Therapeutics Market Shifts & Advancements
Manufacturing modality diversification and delivery format innovation are restructuring competitive positioning, with mRNA platform durability data and recombinant protein advances creating parallel development tracks alongside established inactivated formulations.
Cell-based manufacturing technology is overtaking egg-based propagation across commercial supply networks. The platform eliminates egg-adaptation mutations that compromise H3N2 vaccine effectiveness. Pediatric immunization programs and adult campaigns in the United States and Germany are prioritizing cell-derived stocks where available. This shift is compressing the effective production window and enabling later strain selection decisions that improve antigenic match.
EMA's adaptive licensing frameworks are reshaping development timelines for seasonal reformulations. The pathway permits rolling review of manufacturing data prior to final strain identification, reducing regulatory lag between WHO recommendation and market authorization. Quadrivalent formulations with novel adjuvant systems are capturing disproportionate benefit, with public health agencies in France and Italy accelerating procurement decisions for licensed adaptive-pathway products.
Retail pharmacy networks are capturing administration volume from traditional physician office settings. CVS Health, Walgreens Boots Alliance, and supermarket pharmacy chains in the United States are deploying standing-order protocols that eliminate individual prescription requirements. This channel migration is most pronounced in suburban and rural counties where primary care access constraints intersect with employer-sponsored vaccination mandates, compressing the effective campaign window and favoring single-dose presentation formats.
Global Seasonal Influenza Vaccines Therapeutics Market Segmentation
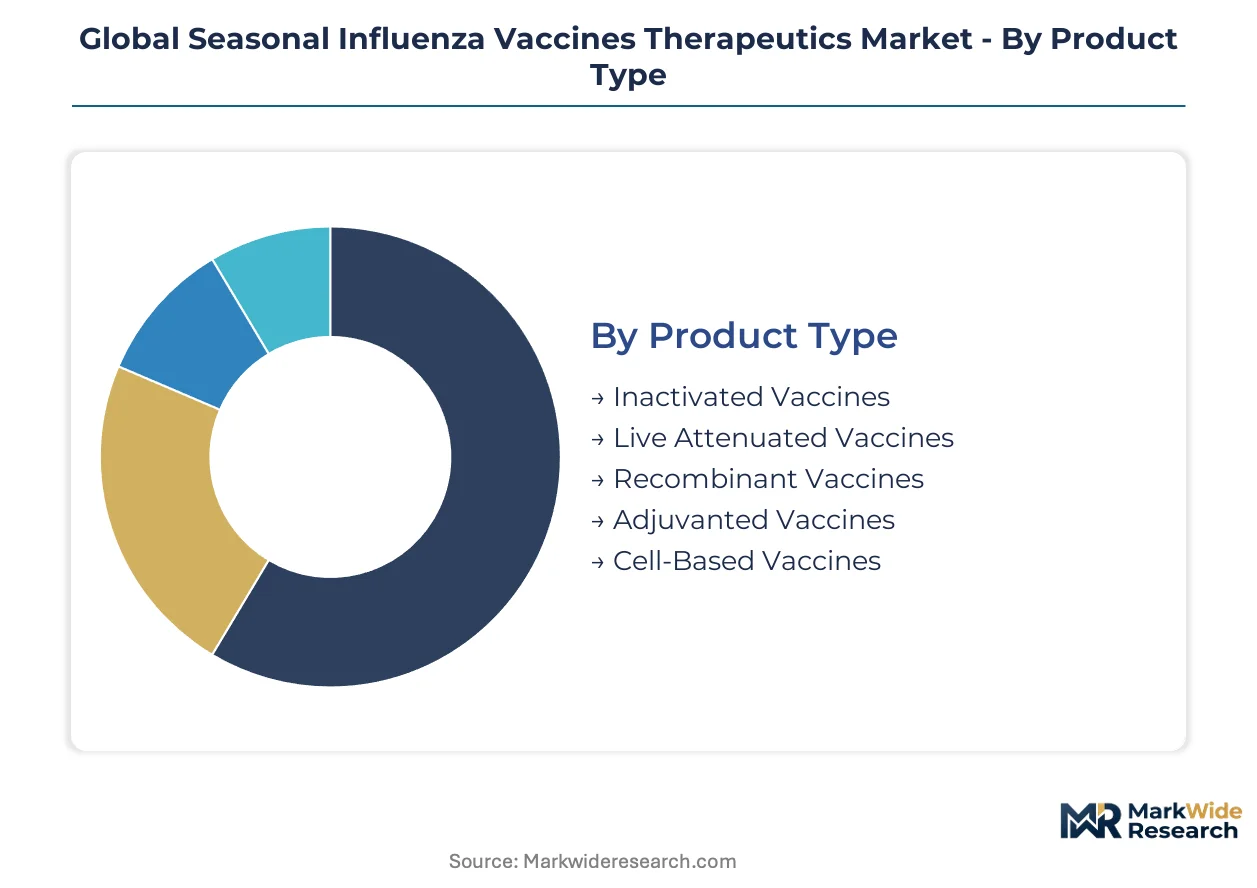
Segmentation in seasonal influenza vaccines therapeutics reveals how manufacturing modality, patient population, and delivery format intersect to determine procurement patterns and margin structures. Manufacturers calibrate portfolio allocation across these dimensions based on regulatory pathway speed, cold chain requirements, and reimbursement tier positioning.
Product Type:
Standardization dominates inactivated platforms while customization accelerates across recombinant and cell-based alternatives.
- Inactivated Vaccines:Viral particles inactivated by formalin or β-propiolactone retain immunogenicity while eliminating replication risk. Demand concentrates in United States and Germany where public health agencies prioritize established safety profiles for broad age-label campaigns. Egg-based manufacturing still supplies the majority of this volume, though cell-culture conversion is underway.
- Recombinant Vaccines:Baculovirus expression systems produce hemagglutinin proteins without egg-adaptation mutations, preserving antigenic fidelity to wild-type strains. Pediatric immunization programs in Japan and high-risk population protocols in France are expanding procurement of these premium-priced formulations.
- Live Attenuated Vaccines:Cold-adapted viral strains replicate in nasopharyngeal mucosa without systemic spread.
- Adjuvanted Vaccines:MF59 or AS03 emulsions boost immunogenicity in elderly recipients with immunosenescence.
- Cell-Based Vaccines:Madin-Darby canine kidney (MDCK) or PER.C6 platforms eliminate egg supply dependencies.
Most installed capacity flows through Inactivated Vaccines. Expansion is steepest in Cell-Based Vaccines.
Application:
Volume scale separates national immunization programs from targeted prophylaxis, with reimbursement intensity inversely correlated with population coverage breadth.
- Immunization Programs:Seasonal campaigns administered through public health infrastructure target 30-60% population coverage depending on national strategy. United States CDC and Germany's STIKO drive procurement volumes through standing recommendations that convert to reimbursed administration.
- Pediatric Use:Expanded age indications and school-based delivery protocols are reshaping formulation demand toward reduced-antigen presentations and needle-free options. China's national program expansion and Japan's routine infant schedule are accelerating volume growth in this segment.
- Post-Exposure Prophylaxis:Household and institutional outbreak containment drives smaller-volume, rapid-turnaround orders.
- Geriatric Use:High-dose and adjuvanted formulations address immunosenescence in adults over 65.
- High-Risk Population Protection:Chronic disease and immunocompromised patient protocols require inactivated-only formulations.
Procurement volume concentrates in Immunization Programs. Margin expansion is fastest in Pediatric Use.
End User:
Channel fragmentation between institutional procurement and retail access is restructuring distribution economics and cold chain requirements.
- Hospitals:Inpatient and emergency department administration captures high-risk and immunocompromised patients requiring medical supervision. United States health systems and Germany's university hospital networks anchor demand for adjuvanted and high-dose presentations.
- Public Health Agencies:Centralized procurement with national tender mechanisms drives price transparency and volume concentration. China's CDC provincial branches and Japan's local health centers are expanding direct-purchase arrangements that bypass distributor markups.
- Primary Care Clinics:Physician office administration remains significant in rural United States counties and small-town Germany.
- Travel Clinics:Pre-departure vaccination for international travelers generates premium pricing.
- Occupational Health Providers:Employer-mandated programs in manufacturing and healthcare sectors drive corporate contract volumes.
Contract value aggregates in Hospitals. Procurement reform is advancing fastest through Public Health Agencies.
Delivery Technology:
Patient acceptance and cold chain simplicity are displacing clinical tradition as primary selection criteria for delivery format innovation.
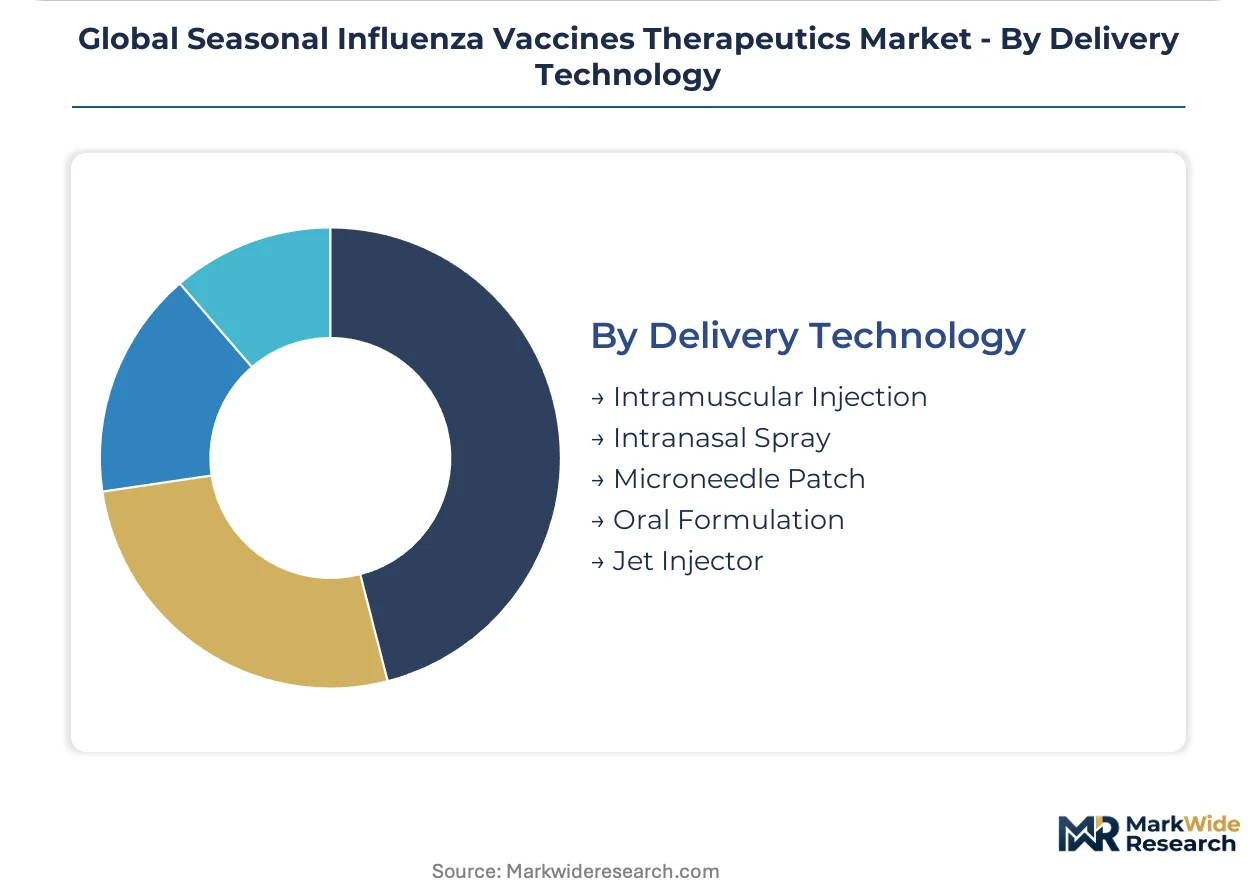
- Intramuscular Injection:Standard 15-microgram dose delivery via deltoid injection dominates commercial volume with established reimbursement codes. United States retail pharmacy chains and Germany's physician practices still process the majority of annual doses through this modality.
- Microneedle Patch:Dissolvable polymer arrays containing vaccine-coated projections enable painless intradermal delivery without sharps disposal. Pediatric segments in Japan and needle-averse adult populations in United States suburban markets are driving pilot procurement programs.
- Intranasal Spray:Live attenuated formulation delivered to nasal mucosa suits healthy non-pregnant adults and children over two.
- Oral Formulation:Mucosal adjuvant research is advancing enteric-coated tablet candidates.
- Jet Injector:Needle-free liquid stream penetration suits mass vaccination campaigns and needle-phobic populations.
Administration volume runs through Intramuscular Injection. Technology transition is accelerating around Microneedle Patch.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA pathway streamlining contrasts with Germany's STIKO deliberative inclusion process, revealing how regulatory velocity shapes market entry timing across major demand centers.
United States
CDC standing recommendations and employer mandate expansion drive procurement volume through retail pharmacy networks. FDA accelerated approval pathways compress development timelines for novel formulations. Manufacturing clusters in Massachusetts and North Carolina anchor cell-culture facility buildouts.
Germany
STIKO age-label expansions convert regulatory licensure into reimbursed immunization volumes across pediatric and geriatric segments. EMA adaptive licensing frameworks enable faster market authorization for quadrivalent reformulations. The Rhine-Ruhr corridor concentrates biomanufacturing infrastructure alongside Basel-linked supply chains.
China
National immunization program expansion creates procurement white space for recombinant and cell-based entrants outside legacy supply relationships. NMPA regulatory pathway streamlining accelerates local manufacturing partnerships. Provincial CDC branches in Guangdong and Jiangsu are expanding direct-purchase arrangements.
Japan
Routine infant schedule expansion and elderly high-dose protocols reshape formulation demand toward adjuvanted presentations. PMDA review timelines for seasonal reformulations align with Southern Hemisphere campaign windows. The Kanto region anchors distribution logistics for Asia-Pacific supply coordination.
United Kingdom
NHS England pharmacy-based administration protocols capture volume from traditional GP settings. MHRA rolling review mechanisms parallel EMA adaptive pathways for faster authorization. The Oxford-Cambridge arc concentrates recombinant platform research alongside contract manufacturing scale-up.
Global Seasonal Influenza Vaccines Therapeutics Market Competitive Landscape
European producers anchor the established platform tier; North American specialists hold the emerging modality vector. The vendor base stratifies across three tiers: integrated pharmaceutical conglomerates with transcontinental manufacturing footprints, cell-culture platform specialists with recombinant capabilities, and regional suppliers serving national immunization programs. Three strategic archetypes dominate: adjuvant technology leaders, egg-free manufacturing innovators, and public health contract aggregators. Capacity expansion and technology licensing represent the dominant competitive moves reshaping supply allocation.
Within the integrated conglomerate tier, Sanofi and GlaxoSmithKline occupy positions spanning trivalent through quadrivalent formulation portfolios. CSL Seqirus represents the cell-culture specialist archetype with recombinant platform capabilities. These three entities exemplify how manufacturing modality diversification and transcontinental production footprints anchor competitive positioning across divergent regulatory environments.
| Leading Market Players |
|---|
| Sanofi |
| GlaxoSmithKline |
| CSL Seqirus |
| Pfizer |
| AstraZeneca |
| Merck |
| Novartis |
| SINOVAC |
| Moderna |
| Others |
Supply & Pricing Matrix
Conglomerate-owned manufacturing networks with captive bioprocessing infrastructure anchor supply-side discipline, converting vertical control over MDCK cell lines and adjuvant formulation into pricing power that resists commoditization pressures from tender-based public procurement.
Pricing Analysis
Capacity additions in Belgium and the Netherlands are reshaping price floors for cell-derived formulations, compressing premiums previously commanded by egg-free manufacturing. Three-tier pricing structure across premium recombinant, standard cell-based, and economy egg-derived levels stratifies procurement tiers, with adjuvanted presentations capturing brand premiums in Germany and Japan. Pricing pressure stems from China's provincial CDC direct-purchase arrangements that bypass distributor markups. Public health agencies exhibit highest price sensitivity, while travel clinics and occupational health programs absorb premium positioning.
Supply Chain Analysis
Dual-sourcing requirements mandated by the United States CDC and Germany's STIKO force manufacturers to qualify multiple cell-culture facilities, fragmenting production across Belgium, the Netherlands, and Germany. Squalene adjuvant feedstock draws from shark liver oil and synthetic alternatives, creating raw material dependencies. Single-source vulnerability concentrates in European cell-culture facility concentration, with transit-dependent distribution amplifying cold chain risk. Distribution runs through centralized public health agency procurement with seasonal surge logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EMA adaptive licensing frameworks and FDA accelerated approval pathways converting strain selection timing into procurement volume capture.
For Market Incumbents: Acquire recombinant platform capabilities to defend against mRNA entrants encroaching on premium positioning. Consolidate backward integration into squalene sourcing to buffer adjuvant raw material volatility. Expand cell-culture capacity in the United States to offset European manufacturing concentration risk. For New Entrants and Emerging Players: The price-point gap between premium recombinant and economy egg-derived tiers creates white-space targeting for mid-priced cell-based formulations. China's NMPA-streamlined pathways offer the most penetrable regulatory entry, with pediatric immunization programs providing volume anchor. Pursue WHO prequalification to unlock Gavi-eligible country procurement channels. For Investors and Strategic Acquirers: Valuations sit cheapest among regional suppliers with national immunization program contracts but limited cell-culture technology. Five-to-ten year viability hinges on manufacturing modality transition completion. Watch cell-based capacity utilization rates as the inflection signal for portfolio reallocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-Culture Facility Buildout | CSL Seqirus and Sanofi expand MDCK capacity in Massachusetts and North Carolina to displace egg-based stocks. |
| EMA Adaptive Licensing Pathway | Rolling review mechanisms compress regulatory lag between WHO strain recommendation and quadrivalent market authorization. |
| Microneedle Patch Development | Intradermal delivery pilots in Japan and United States suburban markets bypass traditional healthcare facility dependency. |
| WHO Prequalification Acceleration | Prequalified status opens Gavi-eligible procurement channels and UN agency purchasing mechanisms for novel entrants. |
| Adjuvant Technology Licensing | MF59 and AS03 emulsion partnerships with public health agencies in France and Italy secure long-term offtake commitments. |
Research Methodology
Bottom-up immunization program modeling reconciled against top-down manufacturing capacity tracking forms the analytical core. Primary interviews with vaccine development executives, regulatory affairs leads, formulary directors at Germany's STIKO, and hospital procurement managers combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and WHO strain selection records. Triangulation between demand-side procurement data and supply-side facility utilization ensures cross-verified volume estimates.
Historical trendline analysis of seasonal campaign coverage rates and formulation mix shifts anchored the projection framework. Segmentation dimensions span manufacturing modality, patient population, delivery technology, and regional regulatory cluster. CAGRs derive from modeled strain mismatch frequency, cell-culture conversion velocity, and pediatric program expansion trajectories across the projection horizon. Forecast inputs incorporate adjuvant raw material cost trajectories and retail pharmacy channel migration patterns.
Caveats apply where WHO strain selection timing compression or antigenic drift severity could materially shift the outlook. Forecasts reflect assumptions around EMA adaptive licensing uptake and NMPA pathway streamlining continuity. Deviation in cell-based manufacturing yield rates or squalene supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Omeprazole Market
Pharmaceuticals
Gastric Cancer Drugs Market
Pharmaceuticals
Acetylcholine Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Atopic Dermatitis Drugs Market
Pharmaceuticals
Critical Care Antiarrhythmic Drugs Market
Pharmaceuticals
Global Diphenhydramine Market
Pharmaceuticals
Narcotic Analgesics Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market
Pharmaceuticals
Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Theophylline and Aminophylline Market
Pharmaceuticals
Global Intravenous Immunoglobulin Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Global Autism Spectrum Disorder Therapeutics Market
Pharmaceuticals
Europe Pharmaceutical Market
Pharmaceuticals
Compounding Chemotherapy Market