
 Global Cytotoxic Drugs Market | 2026-2036
Global Cytotoxic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cytotoxic Drugs Market Foresight
Asian contract manufacturing organizations is restructuring cytotoxic active pharmaceutical ingredient capacity to serve Western markets. Pfizer Inc. leverages integrated biologics-cytotoxic portfolios across North American and European distribution channels. F. Hoffmann-La Roche AG anchors its position through high-potency compound manufacturing scale in Switzerland. Bristol-Myers Squibb Company differentiates via immunotherapy-cytotoxic combination pipelines.
Cytotoxic drugs are cell-killing pharmaceutical compounds, typically nitrogen mustards or platinum-based alkylating agents, that disrupt DNA replication in rapidly dividing malignant cells. These agents require containment engineering with air pressure differentials below 15 Pascals and dedicated high-efficiency particulate air filtration during compounding. Alkylating agents occupy the largest revenue share due to decades of clinical validation across leukemia and lymphoma protocols. Oral administration routes represent the fastest-expanding delivery mode segment as patient preference shifts toward outpatient cancer management. Intravenous infusion retains margin concentration in hospital-based cancer treatment centers where reimbursement rates support premium pricing.
FDA enforces current Good Manufacturing Practice standards for cytotoxic production under 21 CFR Parts 210 and 211, while EMA mandates sterile handling through the EU Good Manufacturing Practice Annex 1 revision. REACH and OSHA guidelines govern occupational exposure limits for healthcare workers handling antineoplastic agents. Stakeholders must monitor biosimilar erosion timelines for legacy cytotoxic molecules and calibrate pipeline investments toward antibody-drug conjugate payloads with differentiated toxicity profiles.
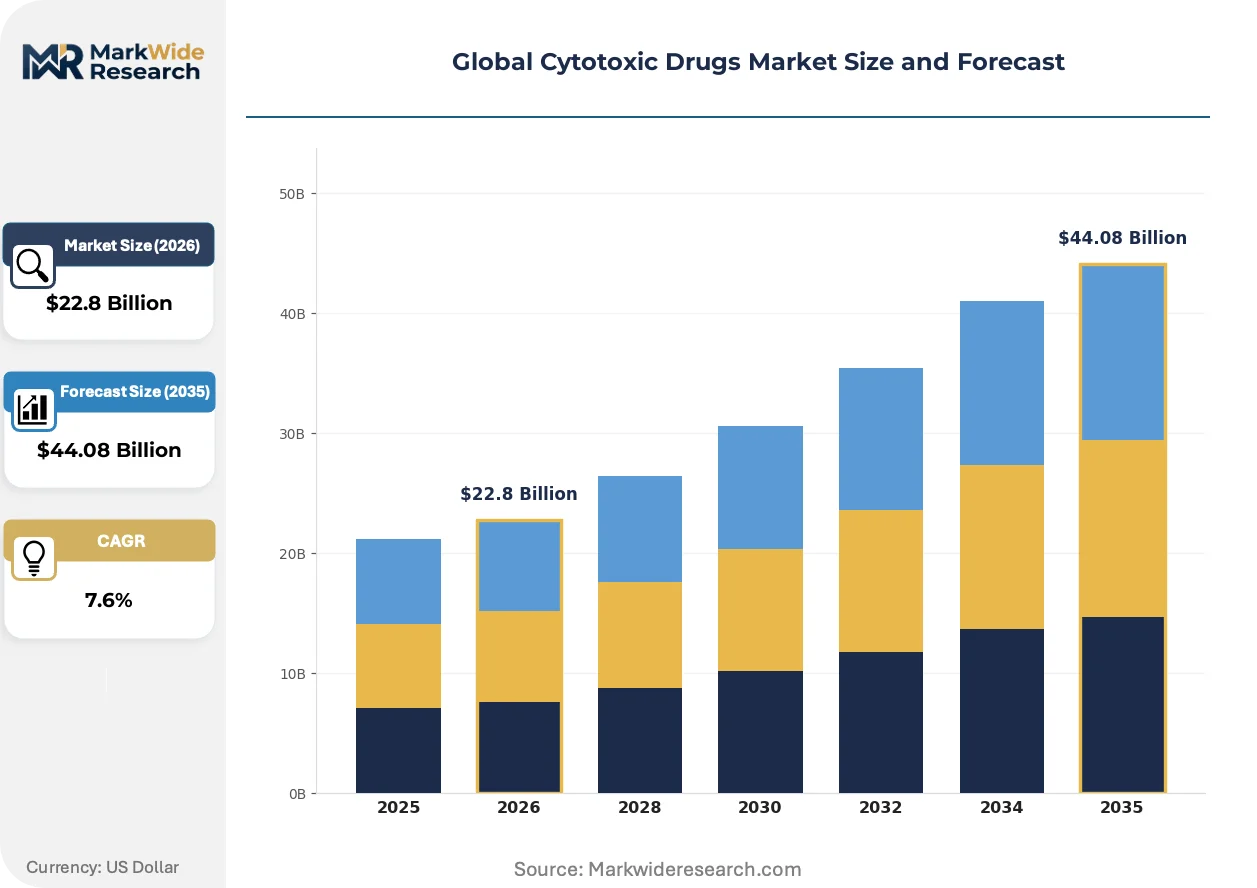
Market Dynamics
The cytotoxic drugs market is consolidating around containment engineering capabilities as hospital networks and contract manufacturers race to meet escalating demand for high-potency compound handling. FDA and EMA sterility mandates are compressing vendor qualification timelines while simultaneously raising capital barriers to entry.
Growth Catalysts
- Accelerated Approval Pathways:FDA's breakthrough therapy and EMA's priority medicines designations compress clinical development timelines for novel antineoplastics. These frameworks enable earlier commercialization of cytotoxic payloads in antibody-drug conjugates.
- Japan's Aging Demographics:Patient pools for hematologic malignancies are expanding rapidly across Japanese prefectures. PMDA reimbursement incentives for outpatient oral chemotherapy reinforce demand for non-infusion delivery formats.
- Containment Automation:Robotics-enabled isolator technology reduces occupational exposure risk during high-potency compounding. Hospital pharmacies in Germany and Switzerland are retrofitting cleanrooms with closed-system transfer devices.
Market Restraints
- Platinum Supply Concentration:Over 70% of platinum group metal refining occurs in South Africa and Russia. Geopolitical disruptions to these supply corridors directly threaten cisplatin and carboplatin production economics.
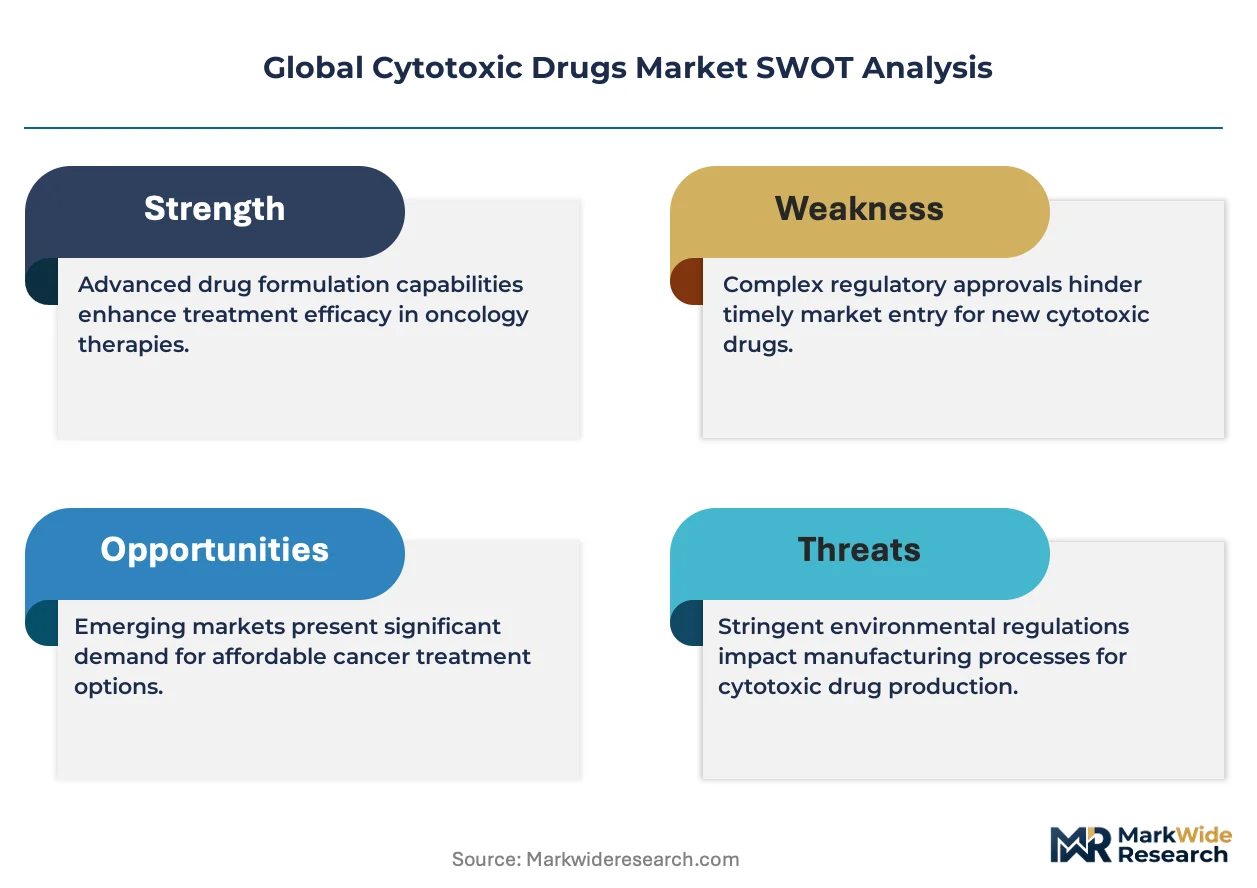
- EMA Annex 1 Compliance Costs:The 2022 revision mandates continuous viable and non-viable monitoring in Grade A/B environments. Small-batch cytotoxic manufacturers face facility write-offs or contract manufacturing abandonment.
- Biosimilar Erosion:Generic paclitaxel and docetaxel formulations have collapsed pricing power for legacy taxanes. Originators are reallocating R&D toward proprietary linker-payload technologies with differentiated toxicity profiles.
Strategic Opportunities
- Indian CDMO Expansion:CDSCO manufacturing license reforms and PLI scheme incentives are attracting Western cytotoxic outsourcing. Hyderabad and Ahmedabad clusters are building dedicated high-potency API blocks with OECD-equivalent standards.
- Subcutaneous Administration:Halozyme-enabled hyaluronidase formulations enable rapid subcutaneous delivery of traditionally infused cytotoxics. Outpatient cancer centers in the United States are prioritizing these protocols for patient throughput gains.
- EU Green Deal Alignment:REACH-registered green chemistry solvents and continuous flow manufacturing reduce environmental liability. ECHA authorization processes favor manufacturers with closed-loop waste recovery systems.
Industry Challenges
- Containment Engineering Talent Scarcity:Qualified industrial hygienists and pharmaceutical isolator technicians command premium compensation. Training pipelines at Swiss Federal Institutes and German Fachhochschulen cannot match demand velocity.
- Legacy ERP Integration:Track-and-trace serialization requirements under the US Drug Supply Chain Security Act collide with decades-old manufacturing execution systems. Validation timelines for combined hardware-software upgrades extend 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cytotoxic Drugs Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $44.08 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkylating Agents, Antimetabolites, Natural Products, Topoisomerase Inhibitors, Mitotic Inhibitors Therapy Area: Leukemia, Lymphoma, Breast Cancer, Lung Cancer, Multiple Myeloma End User: Specialty Clinics, Research Laboratories, Cancer Treatment Centers, Home Care Providers, Diagnostic Labs Delivery Mode: Intravenous Infusion, Oral Administration, Subcutaneous Injection, Intraperitoneal Delivery, Transdermal Patches |
| Companies Covered | Pfizer Inc., Johnson & Johnson, F. Hoffmann-La Roche AG, Bristol-Myers Squibb Company, Novartis AG, Sanofi, Merck & Co. Inc., AbbVie Inc., Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cytotoxic Drugs Market Shifts & Advancements
Antibody-drug conjugate payload engineering is fragmenting the traditional cytotoxic value chain as specialized bioconjugation capabilities separate from bulk API manufacturing. This specialization is creating new vendor categories and reshaping procurement criteria.
Linker chemistry optimization is modularizing payload-release kinetics for tumor-specific activation. Oncology biotechs in Boston and Basel are licensing cleavable linker platforms from specialized chemistry houses rather than developing in-house. This technology partitioning enables faster clinical iteration but compresses margins for undifferentiated payload suppliers.
EMA's 2023 revision to the Good Manufacturing Practice Annex 1 imposes stricter environmental monitoring and rapid microbial detection requirements. Sterile cytotoxic manufacturers must deploy continuous viable particle counters and validated rapid microbiological methods. German and Swiss production facilities are absorbing six-figure capital costs per filling line to maintain EudraGMDP compliance and EU market access.
Hospital procurement committees are consolidating vendor relationships around integrated supply agreements that bundle cytotoxic APIs with companion diagnostics and reimbursement support services. United States cancer center networks are awarding sole-source contracts to manufacturers offering real-world evidence generation partnerships. This bundling displaces traditional price-per-vial negotiations with outcome-contingent contracting frameworks.
Global Cytotoxic Drugs Market Segmentation
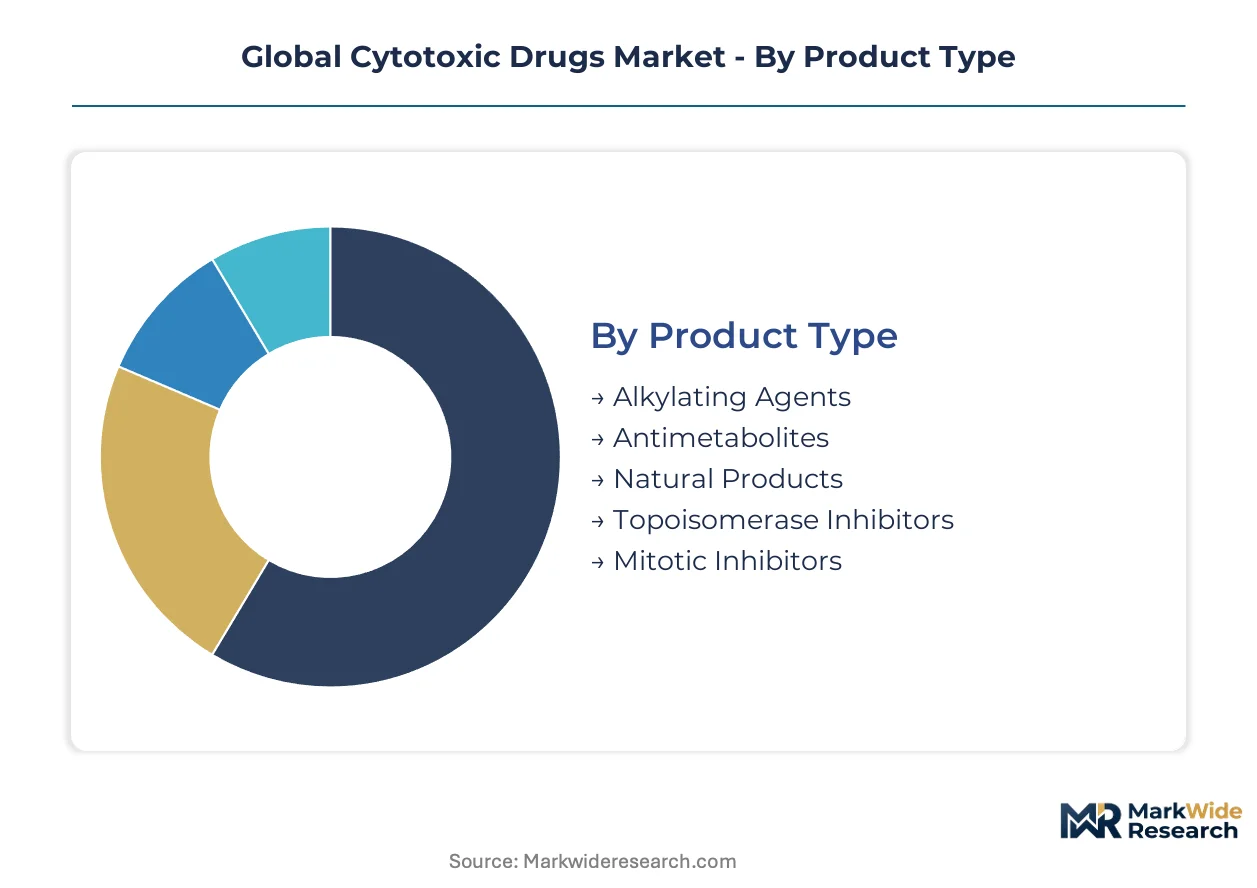
Cytotoxic drug procurement patterns diverge sharply across molecular classes and care settings. Hospital pharmacies calibrate inventory around therapy-specific protocols while manufacturing investments concentrate where containment engineering capabilities align with regulatory stringency.
Product Type:
Supply concentration for active pharmaceutical ingredients varies dramatically across mechanistic classes, dictating procurement risk profiles and manufacturing partner selection.
- Alkylating Agents:Nitrogen mustards and platinum-based compounds constitute the foundational DNA-crosslinking arsenal. Manufacturing concentrates in Swiss and German facilities where containment engineering meets EMA Annex 1 Grade A/B standards. Cisplatin and carboplatin supply chains remain vulnerable to South African platinum refining disruptions.
- Antimetabolites:Folate antagonists and pyrimidine analogs disrupt nucleic acid synthesis through competitive enzyme inhibition. Demand clusters in United States outpatient oncology networks where oral capecitabine protocols reduce infusion center burden. Pemetrexed manufacturing scales through North American contract manufacturing organizations serving lung cancer protocols.
- Natural Products:Taxane and vinca alkaloid derivatives extracted or semisynthesized from plant precursors.
- Topoisomerase Inhibitors:Camptothecin and podophyllotoxin derivatives targeting DNA unwinding enzymes.
- Mitotic Inhibitors:Tubulin-binding agents disrupting cellular division machinery.
Today's leader: Alkylating Agents. Tomorrow's challenger: Antimetabolites.
Therapy Area:
Clinical protocol standardization across hematologic and solid tumor indications determines batch sizing and formulation diversity requirements for cytotoxic manufacturers.
- Breast Cancer:Taxane-anthracycline combination regimens dominate adjuvant and neoadjuvant protocols. United States cancer center networks drive demand for dose-dense scheduling with granulocyte colony-stimulating factor support. Oral cyclophosphamide alternatives are gaining traction in metastatic settings.
- Lung Cancer:Platinum-doublet chemotherapy remains the backbone for non-small cell histologies despite immunotherapy displacement in first-line settings. Pemetrexed maintenance therapy sustains manufacturing volumes for mesothelioma and nonsquamous populations.
- Leukemia:Acute myeloid and lymphoblastic protocols requiring intensive induction regimens.
- Lymphoma:R-CHOP and BEACOPP variants for Hodgkin and non-Hodgkin classifications.
- Multiple Myeloma:Alkylating agent combinations with proteasome inhibitors and immunomodulatory drugs.
Breast Cancer commands current manufacturing capacity allocation. Lung Cancer presents the steepest expansion trajectory as screening programs widen addressable populations.
End User:
Site-of-care migration from inpatient infusion to ambulatory administration is reshaping packaging configurations and cold chain logistics requirements.
- Cancer Treatment Centers:Hospital-based infusion suites with dedicated pharmacy cleanrooms and oncology nursing specialization. United States NCI-designated comprehensive cancer centers maintain captive compounding capabilities with USP <800> compliance. Reimbursement rates support premium pricing for intravenous formulations.
- Specialty Clinics:Community oncology practices with limited pharmacy infrastructure relying on external compounding pharmacies. German onkologische Schwerpunktpraxen aggregate patient volumes across rural catchment areas. Oral chemotherapy dispensing protocols are expanding their therapeutic scope.
- Research Laboratories:Academic medical centers conducting early-phase cytotoxic combination trials.
- Home Care Providers:Nursing services administering subcutaneous or oral regimens in residential settings.
- Diagnostic Labs:Companion diagnostic providers coordinating therapeutic selection with biomarker testing.
Cancer Treatment Centers anchor current revenue concentration. Specialty Clinics are climbing the fastest as site-of-care economics favor ambulatory migration.
Delivery Mode:
Formulation technology investments track patient preference shifts and reimbursement incentives for reduced healthcare utilization.
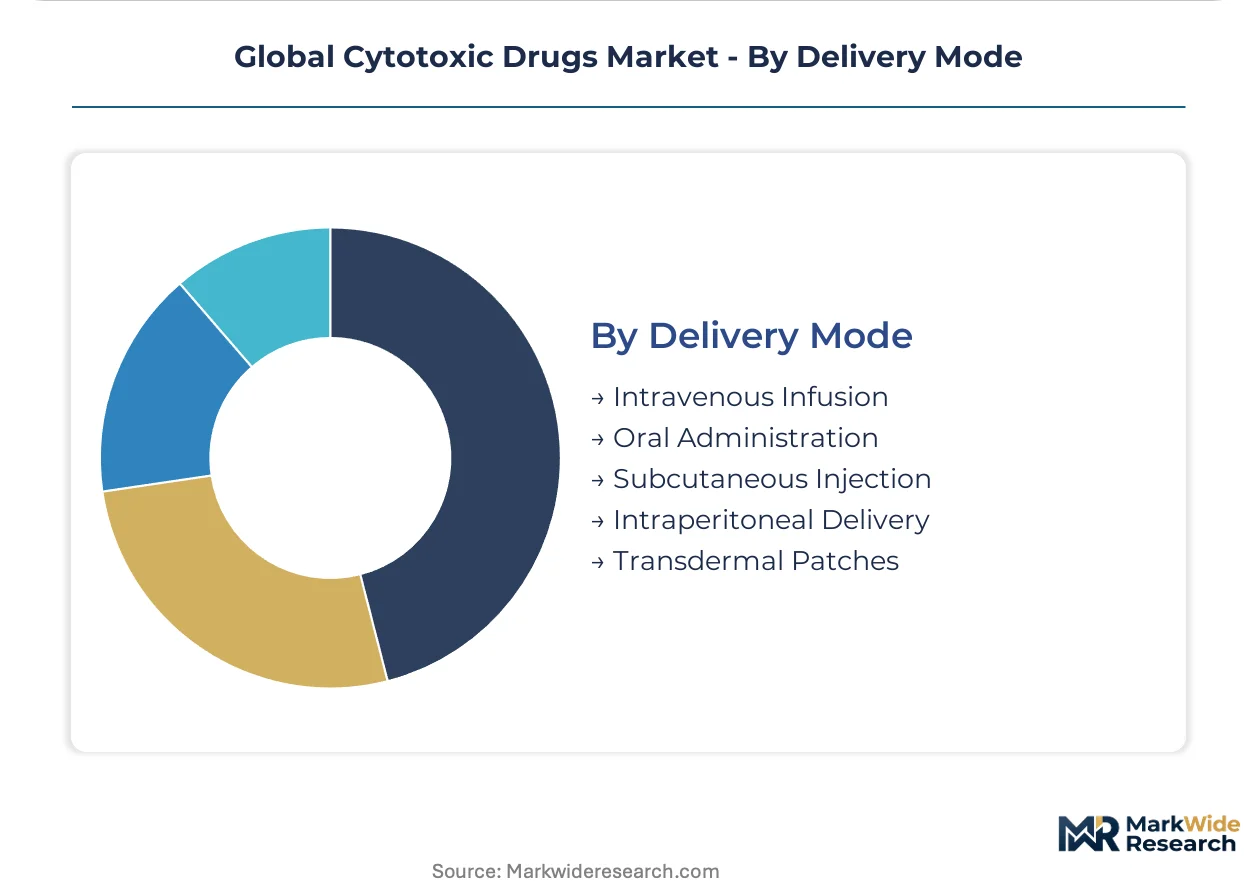
- Oral Administration:Capecitabine, temozolomide, and cyclophosphamide tablets enable outpatient cancer management without infusion center dependency. Japanese PMDA reimbursement pathways explicitly favor oral chemotherapy to reduce hospitalization burden. United States oral parity legislation mandates equivalent insurance coverage for self-administered regimens.
- Intravenous Infusion:Continuous or bolus delivery of cytotoxic agents requiring vascular access devices and cardiac monitoring. Retains margin concentration in hospital-based settings where facility fees supplement drug reimbursement. German Klinikums maintain centralized pharmacy compounding for multi-patient protocols.
- Subcutaneous Injection:Halozyme-enabled hyaluronidase formulations reducing administration duration for traditionally infused agents.
- Intraperitoneal Delivery:Regional chemotherapy administration for ovarian and gastric malignancies with peritoneal involvement.
- Transdermal Patches:Investigational delivery systems for continuous low-dose cytotoxic exposure.
Intravenous Infusion retains present revenue dominance. Oral Administration presents the most aggressive displacement potential as formulation science advances bioavailability solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States cancer centers command premium procurement volumes while German hospital networks enforce stricter containment engineering standards. Japanese outpatient reimbursement policies accelerate oral chemotherapy migration faster than Western counterparts.
United States
NCI-designated comprehensive cancer centers drive demand for high-potency compound handling with USP <800> compliance mandates. FDA breakthrough therapy designations compress development timelines for novel antineoplastics. Boston and San Francisco biotech clusters specialize in antibody-drug conjugate payload engineering.
Germany
Klinikums maintain centralized pharmacy compounding for multi-patient protocols with stringent EMA Annex 1 Grade A/B environmental monitoring. The 2022 Annex 1 revision mandates continuous viable particle counting in sterile suites. Basel-adjacent Baden-Württemberg facilities absorb six-figure capital costs per filling line for EudraGMDP compliance.
Japan
PMDA reimbursement incentives explicitly favor oral chemotherapy to reduce hospitalization burden in aging prefectures. METI industrial policy supports domestic high-potency API manufacturing capacity. Osaka and Tokyo oncology practices aggregate patient volumes across rural catchment areas through onkologische Schwerpunktpraxen equivalents.
Switzerland
Swissmedic oversees high-potency compound manufacturing scale with integrated biologics-cytotoxic portfolios. REACH-registered green chemistry solvents reduce environmental liability for Basel-region production facilities. Swiss Federal Institutes train industrial hygienists and pharmaceutical isolator technicians at premium compensation rates.
India
CDSCO manufacturing license reforms and PLI scheme incentives attract Western cytotoxic outsourcing to Hyderabad and Ahmedabad clusters. These dedicated high-potency API blocks adopt OECD-equivalent standards for contract manufacturing organization expansion. Domestic demand concentrates in Maharashtra and Gujarat tertiary cancer centers.
Global Cytotoxic Drugs Market Competitive Landscape
United States producers anchor one tier with integrated biologics-cytotoxic portfolios; Swiss and German specialists hold containment engineering scale. The vendor base concentrates around three strategic archetypes: diversified pharmaceutical conglomerates with oncology divisions, dedicated high-potency contract manufacturers, and bioconjugation technology licensors. Competitive moves center on antibody-drug conjugate payload partnerships and isolator technology retrofitting for EMA compliance.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and F. Hoffmann-La Roche AG exemplify the integrated portfolio archetype spanning North American and European distribution channels. Bristol-Myers Squibb Company occupies a position within the immunotherapy-cytotoxic combination development tier. These three entities represent distinct competitive positioning strategies without implying specific market share claims.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| F. Hoffmann-La Roche AG |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Sanofi |
| Merck & Co. Inc. |
| AbbVie Inc. |
| Amgen Inc. |
| Others |
Supply & Pricing Matrix
Continuous flow manufacturing adoption in Swiss and German facilities simultaneously compresses per-batch production costs and concentrates high-potency API supply among EMA Annex 1-compliant manufacturers with capitalized containment infrastructure. This technological transition rewards scaled operators while marginalizing small-batch compounders facing facility retrofitting burdens.
Pricing Analysis
Capacity additions in India and Switzerland are reshaping price floors for alkylating agent APIs as CDSCO-licensed Hyderabad clusters compete with Basel-region incumbents. Three-tier pricing structure across containment-certified, standard-grade, and non-sterile tiers differentiates supply based on EMA Grade A/B certification status and isolator technology deployment. Cost compression in legacy taxane formulations intensifies as Indian biosimilar manufacturers expand OECD-equivalent production. Hospital procurement committees demonstrate lowest price sensitivity for antibody-drug conjugate payloads with proprietary linker chemistry, while community oncology practices in Germany exhibit highest sensitivity to oral generic substitution.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and Japan's METI industrial policy are reshaping sourcing patterns for Western pharmaceutical conglomerates seeking supply diversification. Platinum group metal refining concentrates in South Africa and Russia, while high-potency API manufacturing clusters in Switzerland, Germany, and India provide finished cytotoxic compounds. The supply chain rests on platinum ore availability, specialized isolator equipment, and qualified industrial hygienist labor pools. Single-source vulnerability around South African platinum refining threatens cisplatin and carboplatin production economics. Distribution runs through hospital pharmacy compounding networks in the United States and centralized Klinikum pharmacies in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Containment automation investments and oral formulation shifts are expanding margin capture for manufacturers with EMA-compliant infrastructure and outpatient reimbursement partnerships.
For Market Incumbents: Deploy isolator technology retrofitting as the priority lever to defend EudraGMDP compliance positions against emerging Indian CDMOs with OECD-equivalent standards. Consolidate vendor relationships through integrated supply agreements bundling cytotoxic APIs with companion diagnostics and real-world evidence generation partnerships. Accelerate backward integration into platinum group metal sourcing to mitigate South African supply corridor disruptions threatening alkylating agent production economics. For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms offer the fastest route to bypass established distributor relationships in United States cancer center networks. Target German onkologische Schwerpunktpraxen and Japanese prefectural oncology practices with limited captive compounding capabilities as the most penetrable end-user segment. Pursue subcutaneous formulation partnerships with hyaluronidase technology licensors to capture outpatient administration migration away from infusion-dependent competitors. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap contract manufacturers with EMA Annex 1 compliance gaps requiring capital injection. Long-term viability hinges on containment engineering talent access and antibody-drug conjugate payload specialization rather than undifferentiated bulk API scale. Watch CDSCO manufacturing license reform implementation velocity as the inflection signal indicating Indian cluster competitiveness against Swiss and German incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Annex 1 Compliance Upgrade | Grade A/B environmental monitoring investments secure EU market access for sterile cytotoxic manufacturers. |
| Antibody-Drug Conjugate Payload Partnership | Specialized bioconjugation capabilities separate high-margin vendors from commoditized bulk API suppliers. |
| Oral Formulation Development | Outpatient chemotherapy protocols in Japan and the United States reduce infusion center dependency. |
| Indian CDMO Capacity Expansion | Hyderabad and Ahmedabad clusters attract Western outsourcing through PLI scheme incentives and OECD-equivalent standards. |
| Platinum Supply Security Initiative | Backward integration into South African and Russian refining corridors mitigates cisplatin production disruption risk. |
Research Methodology
Bottom-up cancer treatment center procurement modeling reconciled against top-down API manufacturing capacity tracking forms the analytical core of this study. Primary interviews with hospital pharmacy directors, regulatory affairs specialists at EMA-compliant manufacturers, oncology formulary managers, and contract manufacturing organization executives combined with secondary validation from FDA 483 inspection databases, EudraGMDP manufacturing authorization records, ClinicalTrials.gov cytotoxic protocol registrations, and USP <800> compliance audit reports. Triangulation across these sources ensures demand-side consumption patterns align with supply-side production volumes.
Input-output matrices model cytotoxic drug consumption across therapy area, molecular class, delivery mode, and regional regulatory cluster dimensions over the projection horizon. CAGRs derive from segmented demand elasticity analysis calibrated against containment engineering capacity expansion timelines and reimbursement policy shifts. Forecast inputs incorporate PMDA oral chemotherapy incentive trajectories, EMA Annex 1 compliance cost absorption curves, and platinum group metal price volatility assumptions.
The model assumes a particular technology adoption path for continuous flow manufacturing and isolator automation; alternative pathways for containment engineering would alter the outlook for small-batch manufacturer survival. Forecasts reflect assumptions regarding CDSCO regulatory convergence speed, REACH green chemistry solvent adoption rates, and biosimilar erosion timelines for legacy taxane molecules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Two Piece Empty Hard Capsule Market
Pharmaceuticals
Immunoglobulin Market
Pharmaceuticals
Thin Film Drug Manufacturing Market
Pharmaceuticals
Depression and Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
In-Silico Drug Discovery Market
Pharmaceuticals
Antiviral Immunoglobulin Market
Pharmaceuticals
Antibiotic-Associated Diarrhea Treatment Market
Pharmaceuticals
Systemic Antibiotics Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
North America Meglitinide Market
Pharmaceuticals
OTC Cough, Cold & Allergy Medicine Market
Pharmaceuticals
Global Anti-Fungal Drugs Market
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
Antimetabolite Drugs Market
Pharmaceuticals
Filgrastim Market