
 North America Adenomyosis Drugs Market | 2026-2036
North America Adenomyosis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
North America Adenomyosis Drugs Market Analytics
CE marking alignment for cross-border therapeutic access is reorganizing competitive entry requirements for North American pharmaceutical developers. Boehringer Ingelheim International GmbH leverages its established gynecology R&D infrastructure to sustain pipeline momentum across the region. Hikma Pharmaceuticals PLC anchors its position through generic hormonal therapy manufacturing scale, while Ferring B.V. differentiates via specialized reproductive health formulations.
Adenomyosis drugs comprise pharmaceutical agents targeting ectopic endometrial tissue within the myometrium, primarily administered as oral progestins, intrauterine hormone-releasing systems, or injectable GnRH analogues that modulate estrogen-driven proliferation and reduce inflammatory pain signaling. Hormonal Therapies command the dominant revenue share due to sustained prescription volume for progesterone-based management protocols. Intrauterine delivery modes represent the fastest-expanding category as clinicians prioritize localized hormone release with reduced systemic exposure. Pain Management applications within the therapy area classification attract concentrated R&D investment from manufacturers seeking non-opioid alternatives for chronic pelvic pain.
FDA oversight through its Center for Drug Evaluation and Research governs new molecular entity approvals and label expansions for adenomyosis indications, while Health Canada and PMRA establish parallel efficacy benchmarks that shape cross-border commercialization timelines. HIPAA compliance requirements influence how patient data from real-world hormonal therapy studies can inform post-market surveillance and prescriber education programs. Stakeholders must monitor evolving FDA guidance on long-term endocrine safety endpoints as this will determine which formulation platforms secure preferred reimbursement status across U.S. and Canadian formularies.
Market Dynamics
Intrauterine hormone-releasing systems are compressing oral progestin volumes as clinicians prioritize localized endometrial suppression with reduced systemic metabolic exposure. FDA label expansions for non-contraceptive pain indications are rewriting formulary placement rules across U.S. pharmacy benefit managers.
Growth Catalysts
- HIPAA-compliant real-world evidence frameworks:Post-market surveillance data from academic medical centers in Massachusetts and New York now directly informs prescriber education protocols, accelerating protocol adoption for hormonal therapies.
- Specialized women's health center clustering:Academic medical hubs in Boston, Philadelphia, and Toronto concentrate patient volume and specialist expertise, creating referral density that sustains high prescription throughput for advanced delivery systems.
- Health Canada PMRA parallel review pathways:Streamlined cross-border regulatory alignment reduces time-to-market for new hormonal formulations seeking simultaneous U.S. and Canadian commercialization.
Market Restraints
- Synthetic progestin API concentration:Three contract manufacturers in the U.S. Northeast control bulk production of levonorgestrel acetate, creating supply vulnerability for generic oral therapy producers.
- FDA long-term endocrine safety endpoint requirements:Extended cardiovascular and bone density study mandates inflate clinical trial costs for novel GnRH analogue development programs.
- Non-pharmacologic pain management substitution:Transcutaneous electrical nerve stimulation devices and pelvic floor physical therapy protocols capture mild-to-moderate adenomyosis cases before pharmaceutical intervention.
Strategic Opportunities
- Underpenetrated Canadian Prairie provinces:Manitoba and Saskatchewan maintain specialist-to-patient ratios below one-tenth of Ontario levels, representing whitespace for telemedicine-enabled hormonal therapy initiation.
- Biodegradable intrauterine platform convergence:Combination of polymer science advances with micro-dose hormone engineering enables next-generation systems eliminating extraction procedures.
- U.S. Inflation Reduction Act Medicare negotiation provisions:Price transparency mechanisms create entry windows for novel formulations demonstrating superior cost-effectiveness against incumbent oral therapies.
Industry Challenges
- Gynecologic endocrinology specialist shortages:Fellowship programs in reproductive endocrinology produce fewer than 50 new specialists annually across the United States, constraining prescriber base expansion for complex hormonal protocols.
- Legacy electronic health record integration:Pain scoring algorithms and menstrual tracking modules require costly customization to capture adenomyosis-specific outcomes data for payor contract negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Adenomyosis Drugs Market |
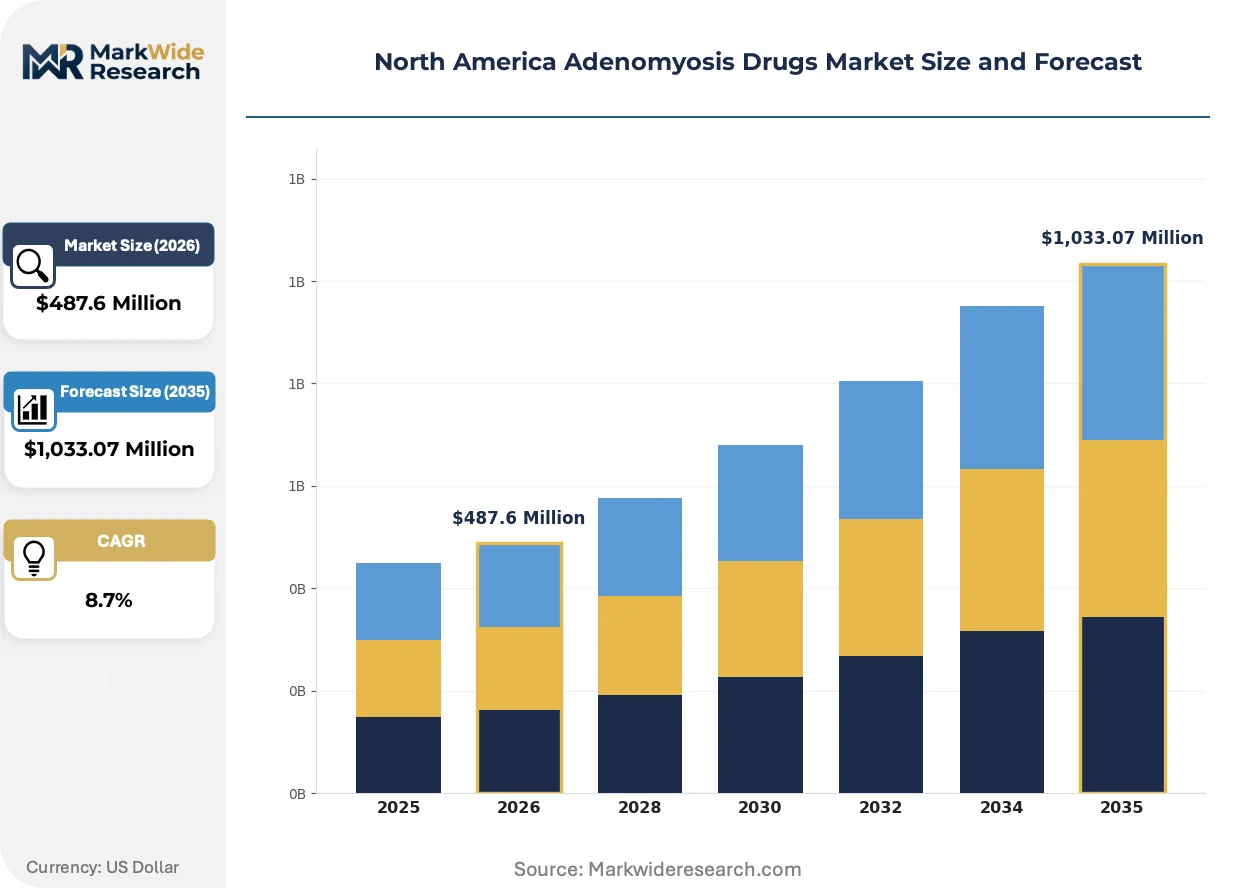
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapies, NSAIDs, Gonadotropin-Releasing Hormone Agonists, Antidepressants Delivery Mode: Oral, Injectable, Transdermal, Intrauterine End User: Hospitals, Clinics, Home Care, Ambulatory Surgical Centers Therapy Area: Gynecology, Pain Management, Reproductive Health, Women's Health |
| Companies Covered | Mayne Pharma Group Limited, Accord Healthcare, Tolmar Pharmaceuticals, Inc., Boehringer Ingelheim International GmbH, TerSera Therapeutics LLC, Ferring B.V., Lannett, Hikma Pharmaceuticals PLC, Context Therapeutics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Adenomyosis Drugs Market Evolving Landscape
Selective progesterone receptor modulators are fragmenting the hormonal therapy landscape by offering tissue-specific antagonism without systemic progestin exposure. Manufacturers now engineer molecular platforms that distinguish between endometrial, myometrial, and breast tissue receptor populations.
SPRM-based oral therapies are decomposing the historical trade-off between efficacy and metabolic side effects that constrained long-term progestin adherence. Academic medical centers in Chicago and Houston pilot these agents for patients with prior thromboembolic contraindications to estrogen-progestin combinations. The technology is decomposing patient discontinuation curves, extending average therapy duration from eight months toward multi-year maintenance protocols.
FDA draft guidance on patient-reported outcome measures for chronic pelvic pain now mandates digital diary integration in pivotal trials, reshaping endpoint validation requirements. Sponsors must demonstrate correlation between daily pain scores and quality-of-life instruments to secure priority review designation. Oral progestin manufacturers with legacy paper-based outcome collections face retrospective data reconciliation costs to maintain label competitiveness.
Direct-to-patient pharmacy fulfillment is displacing traditional retail dispensing for maintenance hormonal therapies, with specialty pharmacies capturing prescription volume through automated refill synchronization. This channel shift concentrates patient data capture with pharmacy benefit managers, who leverage adherence metrics for formulary tier placement negotiations. The behavioral shift is most visible in California and Washington state markets where integrated delivery networks own both prescriber and dispenser functions.
North America Adenomyosis Drugs Market Segmentation
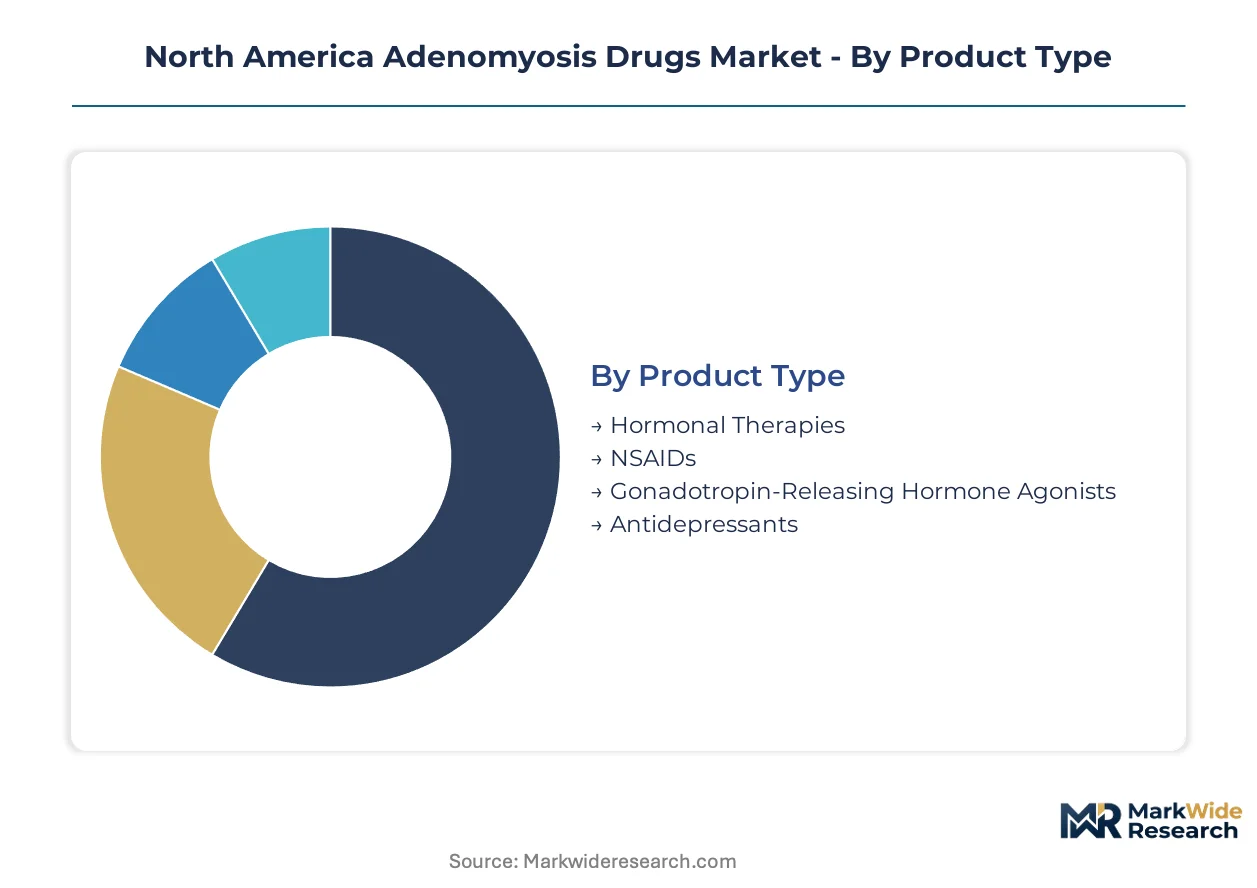
Segmentation in the North America adenomyosis drugs market reveals how formulation choices, delivery technologies, and care settings redistribute patient volume and profitability across the value chain. Manufacturers calibrate portfolio investments against these divisions to capture recurring prescription revenue versus one-time procedural income.
Product Type:
Margin pools concentrate in hormonal therapies where chronic administration protocols generate sustained refill revenue and formulary placement premiums.
- Hormonal Therapies:Progesterone-based agents including oral progestins, levonorgestrel-releasing systems, and selective progesterone receptor modulators suppress ectopic endometrial proliferation. Massachusetts and New York academic medical centers drive prescription volume for extended-cycle regimens that reduce menstrual frequency.
- NSAIDs:Non-steroidal anti-inflammatory drugs address breakthrough pain flares in combination protocols. Demand clusters in ambulatory settings across Ontario and Quebec where patients seek same-day symptomatic relief without hormonal side effect profiles.
- Gonadotropin-Releasing Hormone Agonists:Injectable GnRH analogues induce medical menopause for severe cases refractory to first-line therapy.
- Antidepressants:Off-label SNRIs modulate central pain processing in patients with comorbid mood disorders.
Hormonal Therapies hold installed capacity. NSAIDs is rotating up the share rankings.
Delivery Mode:
Reimbursement differentials across U.S. pharmacy benefit managers and Canadian provincial formularies reshape which delivery technologies capture profitable patient months.
- Oral:Tablet and capsule formulations of progestins and NSAIDs dominate initial prescriptions due to prescriber familiarity and patient autonomy. California integrated delivery networks are consolidating maintenance therapy fulfillment through specialty pharmacy channels that synchronize automated refills.
- Intrauterine:Hormone-releasing systems deliver localized levonorgestrel with minimized systemic exposure. Texas and Illinois health systems are expanding same-day insertion capacity to capture patients with thromboembolic contraindications to oral estrogen-progestin combinations.
- Injectable:Depot formulations and GnRH agonists require clinical administration.
- Transdermal:Patch-based delivery remains limited for adenomyosis-specific indications.
Oral formulations command current prescription volume. Intrauterine systems are climbing the fastest as clinicians prioritize localized efficacy.
End User:
Patient acuity and procedural complexity determine where high-value hormonal therapy initiation concentrates versus commodity refill capture.
- Clinics:Gynecology and reproductive health clinics manage stable patients on maintenance hormonal protocols. Boston and Philadelphia specialist clusters generate referral density that sustains high-throughput prescription practices for advanced delivery systems.
- Hospitals:Academic medical centers handle complex cases requiring surgical coordination or multidisciplinary pain management. Toronto and Houston facilities integrate adenomyosis care within broader endometriosis centers of excellence.
- Ambulatory Surgical Centers:Same-day procedural settings for intrauterine system placement.
- Home Care:Self-administered oral and transdermal therapies.
Clinics hold installed capacity. Hospitals are gaining share fastest through center-of-excellence consolidation.
Therapy Area:
Clinical outcome metrics and FDA label expansion pathways determine which therapeutic positioning commands premium formulary tier placement.
- Gynecology:Core specialty managing disease-specific hormonal suppression and fertility preservation counseling. U.S. Northeast women's health centers cluster diagnostic and treatment expertise that accelerates protocol adoption for novel selective progesterone receptor modulators.
- Pain Management:Multidisciplinary approaches addressing chronic pelvic pain through non-opioid alternatives. Chicago and Seattle health systems pilot SPRM-based regimens for patients with prior thromboembolic events.
- Reproductive Health:Fertility-sparing treatment pathways for patients desiring future conception.
- Women's Health:Integrated primary and preventive care settings.
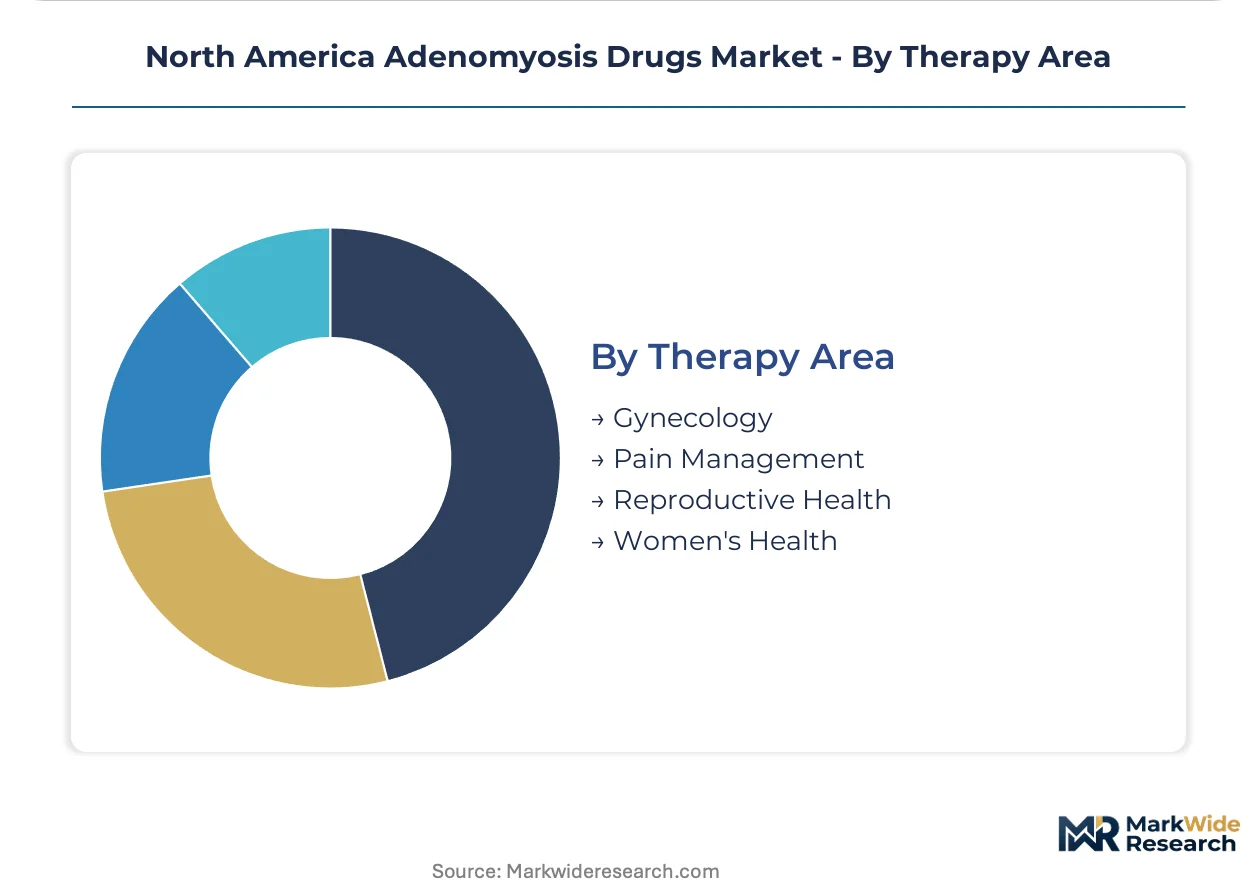
Gynecology holds installed capacity. Pain Management is rotating up the share rankings through non-opioid positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Inflation Reduction Act's Medicare negotiation provisions reshape pharmaceutical pricing dynamics across North America, while Health Canada PMRA parallel review pathways compress cross-border commercialization timelines for hormonal therapy developers.
United States
Massachusetts and New York academic medical centers concentrate specialist expertise and patient volume for advanced intrauterine system protocols. FDA Center for Drug Evaluation and Research governs new molecular entity approvals and label expansions for adenomyosis indications. Boston's women's health center clustering generates referral density that sustains high-throughput prescription practices for selective progesterone receptor modulators.
Canada
Ontario and Quebec drive demand for same-day symptomatic relief through ambulatory NSAID protocols outside hormonal side effect profiles. Health Canada PMRA establishes efficacy benchmarks that shape commercialization timelines for cross-border entrants. Toronto's integrated endometriosis centers of excellence coordinate adenomyosis care within broader reproductive health frameworks.
Northeastern United States
Philadelphia and Boston specialist clusters anchor the region's dominance in extended-cycle hormonal regimen adoption. HIPAA compliance requirements influence how real-world evidence from academic medical centers informs post-market surveillance programs. Pennsylvania and Massachusetts health systems pilot SPRM-based therapies for patients with prior thromboembolic contraindications.
Canadian Prairie Provinces
Manitoba and Saskatchewan present whitespace opportunity with specialist-to-patient ratios below one-tenth of Ontario levels. Provincial formulary placement negotiations for hormonal therapies lag Ontario and Quebec timelines by 12-18 months. Telemedicine-enabled hormonal therapy initiation programs target these underpenetrated markets for expanded access.
South-Central United States
Texas and Illinois health systems expand same-day intrauterine system insertion capacity for thromboembolic-contraindicated patients. State Medicaid program variations create reimbursement complexity for long-acting reversible contraceptive cross-label use. Houston's multidisciplinary pain management programs integrate adenomyosis care within broader chronic pelvic pain protocols.
North America Adenomyosis Drugs Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with established gynecology R&D infrastructure alongside generic hormonal therapy manufacturers competing on API scale and cost position. Market structure exhibits moderate consolidation with three to four entities commanding disproportionate formulary placement leverage. Strategic archetypes include research-intensive innovators developing selective progesterone receptor modulators, high-volume generic producers of levonorgestrel-based systems, and specialty reproductive health formulators. Dominant competitive moves center on portfolio diversification into localized delivery technologies and strategic partnerships with academic medical centers for real-world evidence generation.
Within the research-intensive tier, Boehringer Ingelheim International GmbH exemplifies the archetype of established gynecology R&D infrastructure sustaining pipeline momentum. Hikma Pharmaceuticals PLC occupies a position representing generic hormonal therapy manufacturing scale, while Ferring B.V. anchors the specialty reproductive health formulation segment. These three entities collectively illustrate the competitive spectrum spanning innovation-driven, scale-driven, and niche-specialist positioning strategies.
| Leading Market Players |
|---|
| Mayne Pharma Group Limited |
| Accord Healthcare |
| Tolmar Pharmaceuticals, Inc. |
| Boehringer Ingelheim International GmbH |
| TerSera Therapeutics LLC |
| Ferring B.V. |
| Lannett |
| Hikma Pharmaceuticals PLC |
| Context Therapeutics Inc. |
| Others |
Value Network & Pricing Analysis
Ninety-day API inventory cycles at U.S. Northeast contract manufacturers directly shape pricing leverage for generic oral progestin producers, concentrating cost negotiation power with the three dominant levonorgestrel acetate suppliers and compressing margins for downstream formulators lacking backward integration into active pharmaceutical ingredient production.
Pricing Analysis
FDA approval tier creates the primary spread between premium innovator formulations and commodity generic substitutes, with selective progesterone receptor modulators commanding formulary placement premiums against standard oral progestins. Certification investment for Health Canada PMRA parallel review adds cross-border pricing complexity that disadvantages single-market players. Pricing pressure stems from Medicare negotiation transparency requirements under U.S. Inflation Reduction Act provisions, intensifying cost-effectiveness scrutiny for maintenance hormonal therapies. Hospital procurement committees exhibit highest price sensitivity due to bundled reimbursement constraints, while specialty gynecology clinics prioritize clinical outcomes over unit cost.
Supply Chain Analysis
API inventory cycles stretching toward 120 days for synthetic progestin precursors expose formulators to working capital strain and margin volatility during supply disruptions. Active pharmaceutical ingredient production concentrates in India and China for hormonal raw materials, with U.S. Northeast facilities handling final formulation and packaging. Supply chain vulnerability hinges on single-source dependencies for micronized progesterone and specialty polymer substrates for intrauterine system manufacturing. Distribution runs through specialty pharmacy channels for maintenance therapies, with direct-to-patient fulfillment displacing traditional retail dispensing in California and Washington integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American adenomyosis therapeutics sit in early-cycle expansion, with intrauterine delivery mode adoption still below 40% of addressable patient months despite superior clinical profiles.
For Market Incumbents: Compound formulary placement advantages through Health Canada PMRA parallel review investments that accelerate cross-border label harmonization, while securing captive supply agreements with the three dominant levonorgestrel acetate API producers to neutralize raw material cost volatility threatening generic oral therapy margins. For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-tracks offer the most penetrable regulatory pathway for selective progesterone receptor modulators seeking priority review timelines, with Canadian Prairie provinces presenting whitespace for telemedicine-enabled hormonal therapy initiation where specialist density lags Ontario by an order of magnitude. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates with underutilized gynecology R&D infrastructure, where reproductive health assets trade at valuation discounts to oncology portfolios despite comparable patent runway. Watch FDA draft guidance finalization on chronic pelvic pain patient-reported outcomes as the inflection signal for next-generation formulation platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada PMRA Parallel Review Pathway | Compresses cross-border commercialization timelines for hormonal therapy developers seeking simultaneous U.S. and Canadian market entry. |
| Biodegradable Intrauterine Platform Development | Eliminates extraction procedure requirements, addressing patient discontinuation barriers that constrain long-acting reversible contraceptive cross-label adoption. |
| Specialty Pharmacy Channel Partnership | Captures patient adherence data for formulary tier placement negotiations with pharmacy benefit managers consolidating maintenance therapy fulfillment. |
| Academic Medical Center Real-World Evidence Collaboration | Generates HIPAA-compliant post-market surveillance data that directly informs prescriber education protocols and accelerates protocol adoption. |
| Selective Progesterone Receptor Modulator Pipeline Advancement | Addresses thromboembolic-contraindicated patient populations currently underserved by estrogen-progestin combination therapies. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, formulary directors at major pharmacy benefit managers, and hospital procurement managers provided ongoing calibration throughout the research process. Primary fieldwork combined structured interviews with secondary validation against FDA filings, Health Canada PMRA submissions, ClinicalTrials.gov protocol registries, and provincial formulary databases. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical expenditure tracking to ensure segment-level consistency.
Consistency checks validated volume and value outputs against external benchmarks including CMS Medicare Part D claims patterns and Canadian Institute for Health Information pharmaceutical utilization data. The analytical framework segmented the market across treatment line, dosage form, administration route, and regional regulatory cluster throughout the projection horizon. CAGRs derived from patent expiry modeling, biosimilar entry assumptions, and prescriber adoption curve analysis for novel delivery technologies.
Decision-makers should treat outputs as directional under assumptions of stable FDA-Health Canada regulatory alignment and continued specialty pharmacy channel consolidation; material deviation in Medicare negotiation implementation timelines or API supply disruption severity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Sporanox Market
Pharmaceuticals
Gemcitabine Hydrochloride Market
Pharmaceuticals
Japanese Encephalitis Vaccine Market
Pharmaceuticals
Extended Oral Antibiotics Market
Pharmaceuticals
Japan Diabetes Drugs Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Cancer Immunotherapy Drug Discovery Outsourcing Market
Pharmaceuticals
Bendamustin Market
Pharmaceuticals
Europe Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
China Human Papillomavirus Vaccine Market
Pharmaceuticals
Immunosuppressive Drugs Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Nicorandil Market
Pharmaceuticals
Antiviral Drugs Market
Pharmaceuticals
Asia-Pacific Gastrointestinal Drugs Market