
 Vaginal Antifungals Market | 2026-2036
Vaginal Antifungals Market Size, Share, and Industry Trends Forecast 2026-2036
Vaginal Antifungals Market Analytics
The EPA's Safer Choice program and state-level pharmaceutical disposal mandates are shifting formulation priorities toward biodegradable excipients and reduced environmental persistence. Pfizer Inc. leverages its manufacturing scale to sustain supply chain reliability across multiple dosage platforms. Bayer AG anchors its position through brand strength in over-the-counter intravaginal segments. Mycovia Pharmaceuticals, Inc. specializes in novel polyene and azole combinations, differentiating its pipeline from conventional generic offerings.
Vaginal antifungals comprise azole derivatives, polyene macrolides, and allylamine compounds formulated as creams, suppositories, tablets, or sustained-release inserts designed to eradicate Candida species and restore vaginal microbiome balance. These agents typically achieve therapeutic concentrations through direct mucosal application or systemic absorption, with bioavailability and residence time governing efficacy against recurrent infections. The clotrimazole and miconazole segments dominate current volume due to extensive genericization and established OTC status, while sustained-release delivery modes represent the fastest-expanding category as patient compliance requirements intensify. Intravaginal formulations command premium positioning relative to oral fluconazole where drug interaction profiles restrict prescribing flexibility.
The FDA oversees OTC monograph modernization and prescription-to-switch pathways, while the EPA regulates active pharmaceutical ingredient discharge limits affecting manufacturing site location decisions. EMA's MDR and REACH compliance requirements constrain excipient sourcing for suppliers serving European markets, elevating documentation burdens. Stakeholders must monitor evolving pharmacovigilance signal detection requirements and antimicrobial resistance surveillance thresholds that could trigger restrictive labeling or scheduled status revisions.
Market Dynamics
Self-treatment behavior among reproductive-age women is compressing the traditional prescription-to-pharmacy interval, forcing manufacturers to optimize for direct retail shelf presence and telehealth platform integration rather than clinician-mediated distribution.
Growth Catalysts
- OTC Monograph Modernization:The FDA's streamlined reform is collapsing classification timelines, enabling faster prescription-to-switch pathways for established azole formulations.
- Retail Clinic Expansion:MinuteClinic and similar urgent-access models are embedding diagnostic confirmation into pharmacy visits, validating self-selected therapy.
- Sustained-Release Platforms:Polymeric insert technologies are extending dosing intervals from daily to weekly, capturing non-compliant patients who abandon conventional cream regimens.
Market Restraints
- Active Ingredient Concentration:Generic miconazole and clotrimazole oversupply has collapsed unit margins below sustainable R&D recovery thresholds.
- European Excipient Sourcing:REACH documentation burdens and ECHA substance restrictions are disqualifying Asian excipient suppliers from EMA-compliant formulations.
- Oral Fluconazole Substitution:Single-dose oral therapy retains physician preference for uncomplicated cases, capping intravaginal volume in managed care settings.
Strategic Opportunities
- Direct-to-Consumer Platforms:Ro Pharmacy and Hims & Hers are creating subscription-based recurrence prevention programs that bypass traditional retail markup structures.
- Biodegradable Formulation Mandates:The EPA's Safer Choice program is creating first-mover advantage for manufacturers reformulating with plant-derived suppository bases.
- Recurrent Infection Protocols:Maintenance dosing regimens for chronic Candida patients represent an underserved segment between acute OTC and prescription-managed care.
Industry Challenges
- Antifungal Resistance Surveillance:CDC tracking of azole-resistant Candida glabrata strains threatens to trigger restrictive labeling that would reclassify frontline products.
- Cross-Functional Talent Scarcity:Formulation chemists with combined expertise in mucosal bioadhesion and sustained-release polymer science command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaginal Antifungals Market |
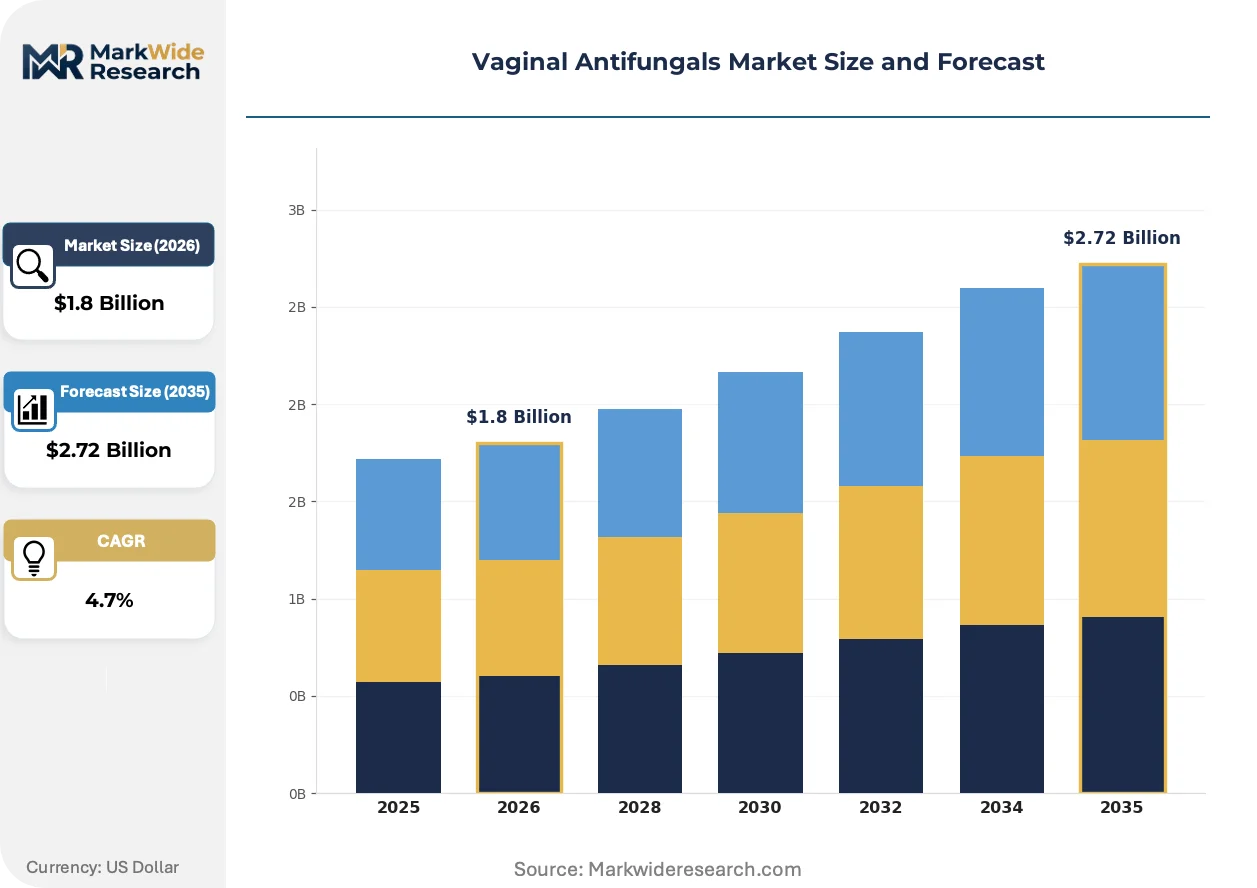
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clotrimazole, Miconazole, Terconazole, Fluconazole Therapy Area: Candidiasis, Bacterial Vaginosis, Fungal Infections, Mycotic Disorders Delivery Mode: Topical, Oral, Intravaginal, Sustained Release End User: Hospitals, Pharmacies, Clinics, Homecare |
| Companies Covered | Pfizer Inc., Astellas Pharma Inc, Mycovia Pharmaceuticals, Inc., Scynexis, Inc., Bayer AG, Basilea Pharmaceutica Ltd, Bausch Health Companies Inc., ANI Pharmaceuticals, Inc., Grupo Ferrer Internacional S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaginal Antifungals Market Evolving Landscape
Formulation science and distribution architecture are diverging from the standard cream-and-suppository paradigm toward patient-controlled, digitally supported therapy management that minimizes clinical touchpoints.
Bioadhesive polymer systems incorporating carbomer and polycarbophil matrices are rewriting residence time expectations for intravaginal delivery. Women with recurrent infections are adopting these platforms at three times the rate of conventional formulations. Extended mucosal contact is compressing relapse rates and enabling maintenance dosing protocols that were previously impractical.
REACH compliance requirements for excipient traceability are forcing European manufacturers to regionalize supply chains away from Asian chemical intermediates. Documentation burdens for novel suppository bases now extend eighteen to twenty-four months. Small-volume specialty suppliers in Germany and Switzerland are capturing premium positioning through pre-certified ingredient portfolios.
Telehealth-integrated diagnostic confirmation is displacing blind self-selection in urban markets. Patients initiate therapy through app-based symptom checkers with pharmacy fulfillment. This channel shift is most visible in United States metropolitan corridors where retail clinic density overlaps with same-day delivery infrastructure.
Vaginal Antifungals Market Segmentation
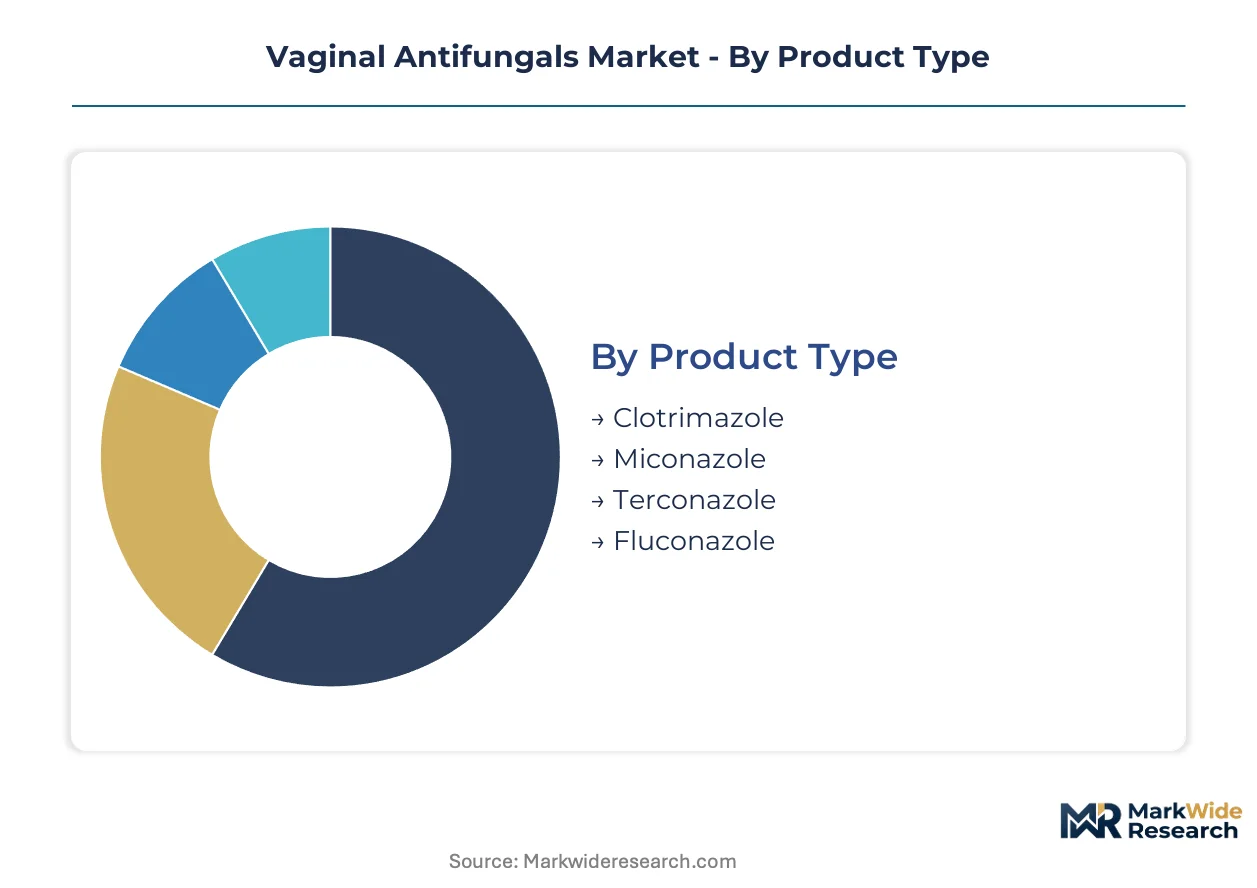
Segmentation in the vaginal antifungals market determines manufacturing scale requirements, regulatory pathway selection, and channel strategy. Product type and delivery mode classifications govern capital allocation decisions, while therapy area and end user dimensions shape commercialization priorities.
Product Type:
Capital intensity varies sharply across azole chemistry platforms, with manufacturing complexity dictating facility investment thresholds.
- Clotrimazole:This imidazole derivative requires crystallization and micronization capabilities to achieve intravaginal bioavailability specifications. Demand concentrates in United States retail pharmacy chains where FDA OTC monograph status enables direct shelf placement without prescription intermediation.
- Miconazole:Synthetic routes demand specialized azole ring closure reactors with corrosion-resistant linings. United States direct-to-consumer platforms and expanded retail clinic access are accelerating category penetration for this established generic.
- Terconazole:Triazole synthesis involves multi-step stereoselective chemistry with tight temperature control.
- Fluconazole:Systemic azole with oral bioavailability requires GMP-compliant tablet compression and coating lines.
Clotrimazole absorbs the bulk of installed capacity; sustained-release miconazole formulations are expanding most quickly.
Therapy Area:
Clinical indication determines reimbursement coding, prescription volume, and the competitive intensity of generic substitution.
- Candidiasis:Candida albicans and non-albicans species drive the majority of symptomatic presentations. United States metropolitan corridors with retail clinic density overlapping same-day delivery infrastructure show highest self-treatment conversion rates.
- Bacterial Vaginosis:Gardnerella vaginalis and anaerobic polymicrobial infections require differential diagnostic confirmation.
- Fungal Infections:Broad diagnostic category encompassing dermatophyte and yeast colonization beyond Candida species.
- Mycotic Disorders:Systemic or recurrent presentations with immunocompromised patient profiles.
Candidiasis commands the greatest prescription volume; recurrent infection protocols for mycotic disorders are gaining share fastest.
Delivery Mode:
Patient compliance requirements and manufacturing process complexity create divergent margin structures across administration routes.
- Topical:Cream and ointment formulations employ standard emulsion technology with established excipient supply chains. United States pharmacy channel uptake is rising as reproductive-age women embrace self-treatment behaviors that compress the traditional prescription-to-pharmacy interval.
- Intravaginal:Suppository and tablet formats demand specialized mold tooling and controlled-release matrix development.
- Oral:Tablet and capsule production leverages conventional solid-dose manufacturing with high throughput rates.
- Sustained Release:Polymeric insert technologies with carbomer and polycarbophil matrices extend dosing intervals from daily to weekly, capturing non-compliant patients who abandon conventional cream regimens.
Topical manufacturing lines represent the greatest cumulative investment; sustained-release platforms show the steepest expansion trajectory.
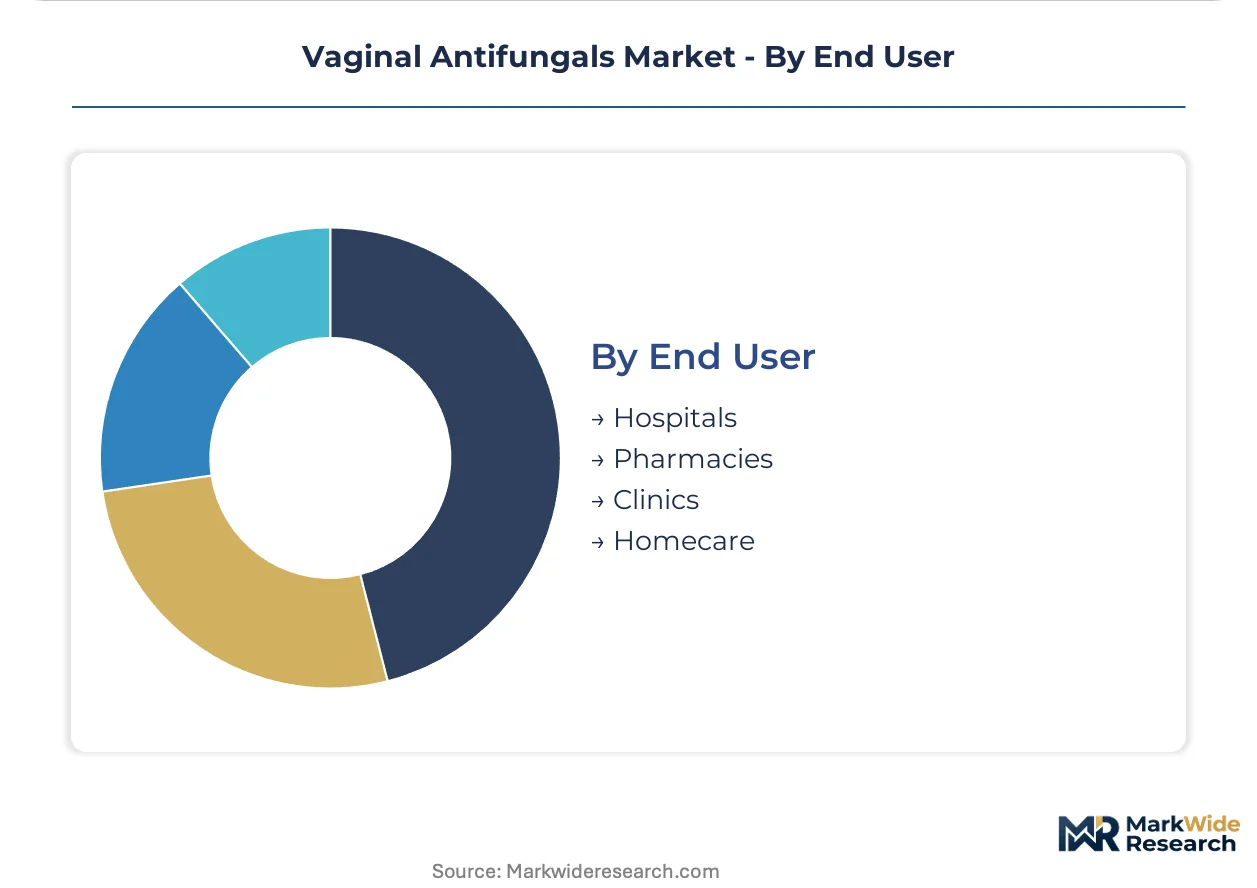
End User:
Channel selection governs pricing architecture, with institutional procurement favoring volume contracts and direct-to-consumer platforms enabling subscription-based recurrence prevention.
- Pharmacies:Retail and community dispensing locations with OTC and prescription fulfillment capabilities. United States direct-to-consumer health platforms are accelerating category penetration through telehealth-integrated diagnostic confirmation.
- Hospitals:Inpatient and emergency department settings managing complicated or recurrent presentations.
- Clinics:Outpatient and urgent-access models including MinuteClinic and similar retail clinic expansions that embed diagnostic confirmation into pharmacy visits.
- Homecare:Direct patient administration with minimal clinical supervision, enabled by app-based symptom checkers and same-day delivery infrastructure.
Pharmacies process the highest transaction volume; homecare channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States metropolitan corridors with retail clinic density overlapping same-day delivery infrastructure anchor commercial activity. The FDA's OTC monograph modernization and EPA discharge mandates shape formulation priorities. Regional variations reflect divergent regulatory timelines and channel access models.
United States
Direct-to-consumer health platforms and expanded retail clinic access accelerate category penetration. The FDA oversees OTC monograph modernization and prescription-to-switch pathways. MinuteClinic models in urban corridors embed diagnostic confirmation into pharmacy visits, validating self-selected therapy.
Germany
REACH documentation burdens and ECHA substance restrictions disqualify Asian excipient suppliers from EMA-compliant formulations. The EMA's MDR compliance requirements constrain excipient sourcing for suppliers serving European markets. Small-volume specialty suppliers in Bavaria and Baden-Württemberg capture premium positioning through pre-certified ingredient portfolios.
United Kingdom
Telehealth-integrated diagnostic confirmation displaces blind self-selection in London and Southeast England. The MHRA aligns with EMA pharmacovigilance signal detection requirements. Pharmacy chains in Greater Manchester and Birmingham optimize for direct retail shelf presence.
India
Domestic manufacturers leverage cost advantages in API synthesis for export markets. The CDSCO regulates active pharmaceutical ingredient quality standards affecting manufacturing site approvals. Formulation clusters in Maharashtra and Gujarat supply generic azole derivatives to regulated markets.
Japan
Sustained-release polymeric insert technologies gain traction among compliance-focused patient segments. The PMDA maintains stringent bioequivalence requirements for generic intravaginal formulations. Osaka-based manufacturers specialize in carbomer matrix development for extended mucosal contact.
Vaginal Antifungals Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with manufacturing scale advantages. Consolidation pressure intensifies as generic miconazole and clotrimazole oversupply collapses unit margins. Three archetypes dominate: multinational OTC brand owners, specialty antifungal developers, and generic API-to-formulation integrators. Capacity rationalization and strategic partnerships represent the dominant competitive moves as R&D recovery thresholds erode.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Bayer AG exemplify scale-driven archetypes with manufacturing reliability across multiple dosage platforms. Mycovia Pharmaceuticals, Inc. occupies a position within the specialty developer tier, differentiating through novel polyene and azole combinations. These three companies represent the structural spectrum from mass-market OTC penetration to pipeline-driven clinical differentiation.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Astellas Pharma Inc |
| Mycovia Pharmaceuticals, Inc. |
| Scynexis, Inc. |
| Bayer AG |
| Basilea Pharmaceutica Ltd |
| Bausch Health Companies Inc. |
| ANI Pharmaceuticals, Inc. |
| Grupo Ferrer Internacional S.A. |
| Others |
Value Network & Pricing Analysis
Azole active pharmaceutical ingredient synthesis costs cascade through three distinct pricing tiers as material moves from Indian and Chinese bulk manufacturers through European formulation sites to United States retail shelves. Energy-intensive triazole ring closure reactions and corrosion-resistant reactor requirements anchor upstream cost structures, while REACH-compliant excipient documentation and FDA OTC monograph compliance layer downstream premiums.
Pricing Analysis
Value-based pricing anchored to clinical outcome differentiation separates sustained-release polymeric inserts from commodity cream formulations. Three-tier pricing structure across premium, standard, and economy levels reflects bioadhesive polymer sophistication, FDA registration tier, and brand heritage. Cost compression in generic miconazole and clotrimazole segments intensifies as oversupply collapses unit margins below sustainable R&D recovery thresholds. Price-sensitive independent pharmacies gravitate toward economy-tier generics, while least-sensitive hospital procurement systems prioritize premium-tier sustained-release platforms for recurrent infection protocols.
Supply Chain Analysis
Single-source vulnerability sits with Chinese azole intermediate suppliers feeding Indian API manufacturers. Concentrated production draws from India, China, and Germany for active ingredients, formulation, and certified excipients respectively. Carbomer and polycarbophil polymer supplies hinge on petrochemical feedstock volatility and ECHA substance restriction timelines. Tariff exposure on Chinese chemical intermediates threatens margin stability across generic manufacturers. Distribution runs through wholesale pharmacy networks and direct-to-consumer platforms with divergent markup structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized corrosion-resistant reactor capacity for azole synthesis constrains supply elasticity, propping pricing power for manufacturers with secured manufacturing slots. Capacity bottlenecks in REACH-compliant excipient certification extend lead times eighteen to twenty-four months.
For Market Incumbents: Extend manufacturing scale advantages by securing long-term azole intermediate offtake agreements with Indian API suppliers before capacity constraints tighten. Invest in backward integration into carbomer matrix production to capture margin from sustained-release formulation growth. Vertical integration into polymer science capabilities defends against emerging specialty developers with novel bioadhesive platforms. For New Entrants and Emerging Players: Direct-to-consumer subscription channels represent the most penetrable route for bypassing entrenched retail pharmacy markups and capturing recurrent infection protocol demand. Target underserved maintenance dosing segments between acute OTC and prescription-managed care with telehealth-integrated diagnostic confirmation. White-space exists in biodegradable suppository base formulations responding to EPA Safer Choice program mandates. For Investors and Strategic Acquirers: FDA prescription-to-switch approvals for novel azole formulations are the leading indicator that category expansion will outpace generic erosion. Five-to-ten year viability favors acquisition of specialty developers with differentiated polyene-azole combination pipelines and established EMA MDR documentation capabilities. Monitor CDC antifungal resistance surveillance thresholds as the signal triggering restrictive labeling and scheduled status revisions that would reclassify competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Prescription-to-Switch Pathway | FDA OTC monograph modernization collapses classification timelines for established azole formulations. |
| Sustained-Release Platform Development | Carbomer and polycarbophil matrix investments capture non-compliant patients abandoning conventional cream regimens. |
| REACH-Compliant Excipient Regionalization | Pre-certified ingredient portfolios from German and Swiss suppliers secure EMA MDR market access. |
| Direct-to-Consumer Channel Integration | Telehealth platform partnerships bypass traditional retail markup structures for recurrence prevention programs. |
| Biodegradable Formulation Transition | Plant-derived suppository base development creates first-mover advantage under EPA Safer Choice program criteria. |
Research Methodology
Independent corroboration across regulatory affairs specialists, pharmaceutical manufacturing executives, and formulary access directors underwrites the qualitative findings on pathway timelines and procurement priorities. Secondary validation draws from FDA OTC monograph filings, EMA MDR submission databases, EPA Safer Choice certified product listings, and pharmaceutical customs trade records. Bottom-up capacity assessments triangulate with top-down prescription volume modeling across the analysis window.
Rate-of-change decomposition separates volume expansion from mix-shift effects across product type, delivery mode, therapy area, and end user segmentation dimensions. CAGRs derive from fitted growth curves applied to normalized baseline data across the projection horizon. Forecast inputs incorporate FDA prescription-to-switch probability assessments, retail clinic expansion trajectories, and azole resistance surveillance trend projections.
The model holds under stable regulatory classification and reimbursement coding; deviation in CDC resistance threshold triggers or ECHA substance restriction expansions would shift trajectory assumptions. Forecasts reflect documented assumptions on patient compliance improvement rates and channel migration patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
High Potency API Contract Manufacturing Market
Pharmaceuticals
North America Hormone Replacement Therapy Market
Pharmaceuticals
Global Anti-Fungal Drugs Market
Pharmaceuticals
China Human Papillomavirus Vaccine Market
Pharmaceuticals
Sulfonylureas Market
Pharmaceuticals
Gastrointestinal OTC Drugs Market
Pharmaceuticals
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market
Pharmaceuticals
Asia-Pacific Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
Hepatitis Therapeutics Market
Pharmaceuticals
North America Anesthesia Drugs Market
Pharmaceuticals
Global Tetanus Toxoid Vaccine Market
Pharmaceuticals
Oral Vaccines Market
Pharmaceuticals
Global Pharmaceutical Warehousing Market
Pharmaceuticals
Global Oxytocin Market
Pharmaceuticals
Global Inhaled Antibiotics Market