
 Anti-Inflammatory Analgesic and Antipyretic Drugs Market | 2026-2036
Anti-Inflammatory Analgesic and Antipyretic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Inflammatory Analgesic and Antipyretic Drugs Market Insights
Biologic manufacturing platforms is reconfiguring how anti-inflammatory APIs are synthesized, shifting batch processes toward continuous bioproduction that cuts impurity profiles. Novartis AG leverages its biosimilar infrastructure to anchor injectable NSAID supply chains across European hospital networks. AbbVie Inc. competes through its immunology R&D pipeline, while Pfizer Inc. dominates oral solid dose capacity with backward integration into active pharmaceutical ingredient sourcing.
Anti-inflammatory analgesic and antipyretic drugs comprise small-molecule compounds that modulate cyclooxygenase enzyme activity, with molecular weights typically below 500 Daltons and standardized purity thresholds exceeding 99.5 percent for pharmaceutical-grade formulations. These agents serve to suppress prostaglandin-mediated inflammation, elevate pain thresholds, and reset hypothalamic thermoregulatory setpoints in clinical and over-the-counter settings. The therapy area dimension shows inflammatory disorders commanding the deepest margin pools due to chronic dosing requirements, while transdermal delivery mode is gaining fastest as patients seek alternatives to first-pass hepatic metabolism. Paracetamol retains volume leadership in homecare channels, though naproxen prescription growth in arthritis treatment reflects an aging demographic profile.
The FDA's REMS programs for extended-release opioid-sparing alternatives shape NSAID prescribing patterns, while the EMA's pharmacovigilance requirements for cardiovascular safety signal drive post-market surveillance investments. India's CDSCO accelerates approval timelines for fixed-dose combinations under its streamlined pathway, altering competitive entry sequencing. Stakeholders must monitor how pharmacogenomic testing for CYP2C9 polymorphisms redirects product development toward stratified patient populations.
Market Dynamics
The FDA's tightened cardiovascular risk labeling for COX-2 inhibitors is redirecting development toward selective formulations, while hospital procurement of injectable NSAIDs accelerates as surgical volumes recover post-pandemic. This dual pressure is compressing R&D timelines and reshaping competitive positioning across formulation types.
Growth Catalysts
- Post-pandemic surgical volume recovery:Hospital systems in the United States are expanding formulary access to injectable NSAIDs for perioperative pain management, driving procurement of parenteral formulations.
- EMA pharmacovigilance requirements:The European Medicines Agency's cardiovascular safety signal mandates are forcing manufacturers to invest in post-market surveillance infrastructure, creating competitive moats for compliant suppliers.
- Continuous bioproduction platforms:Biologic manufacturing technologies are cutting impurity profiles in anti-inflammatory API synthesis, enabling higher purity thresholds for pharmaceutical-grade formulations.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for ibuprofen and naproxen concentrates in Chinese and Indian manufacturing clusters, exposing buyers to geopolitical and logistics disruption risks.
- Hepatic metabolism limitations:First-pass liver processing of oral NSAIDs restricts dosing flexibility in patients with compromised liver function, limiting addressable populations for standard formulations.
- Cardiovascular safety labeling:The FDA's REMS programs for extended-release opioid-sparing alternatives impose additional compliance burdens on manufacturers seeking to position NSAIDs as primary analgesics.
Strategic Opportunities
- Transdermal delivery innovation:Patients seeking alternatives to first-pass hepatic metabolism are driving demand for patch-based and topical NSAID formulations, opening white space in homecare channels.
- Pharmacogenomic stratification:CYP2C9 polymorphism testing is enabling development of genetically targeted dosing protocols, creating premium positioning for precision-formulated products.
- India's streamlined approval pathway:The Central Drugs Standard Control Organization's accelerated timelines for fixed-dose combinations are altering competitive entry sequencing for combination analgesic products.
Industry Challenges
- Continuous manufacturing retrofit costs:Transitioning from batch to continuous bioproduction requires substantial capital investment in process analytical technology and real-time release testing infrastructure.
- Multijurisdictional compliance complexity:Manufacturers must simultaneously satisfy FDA cardiovascular safety requirements, EMA pharmacovigilance mandates, and CDSCO stability testing protocols, stretching regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Inflammatory Analgesic and Antipyretic Drugs Market |
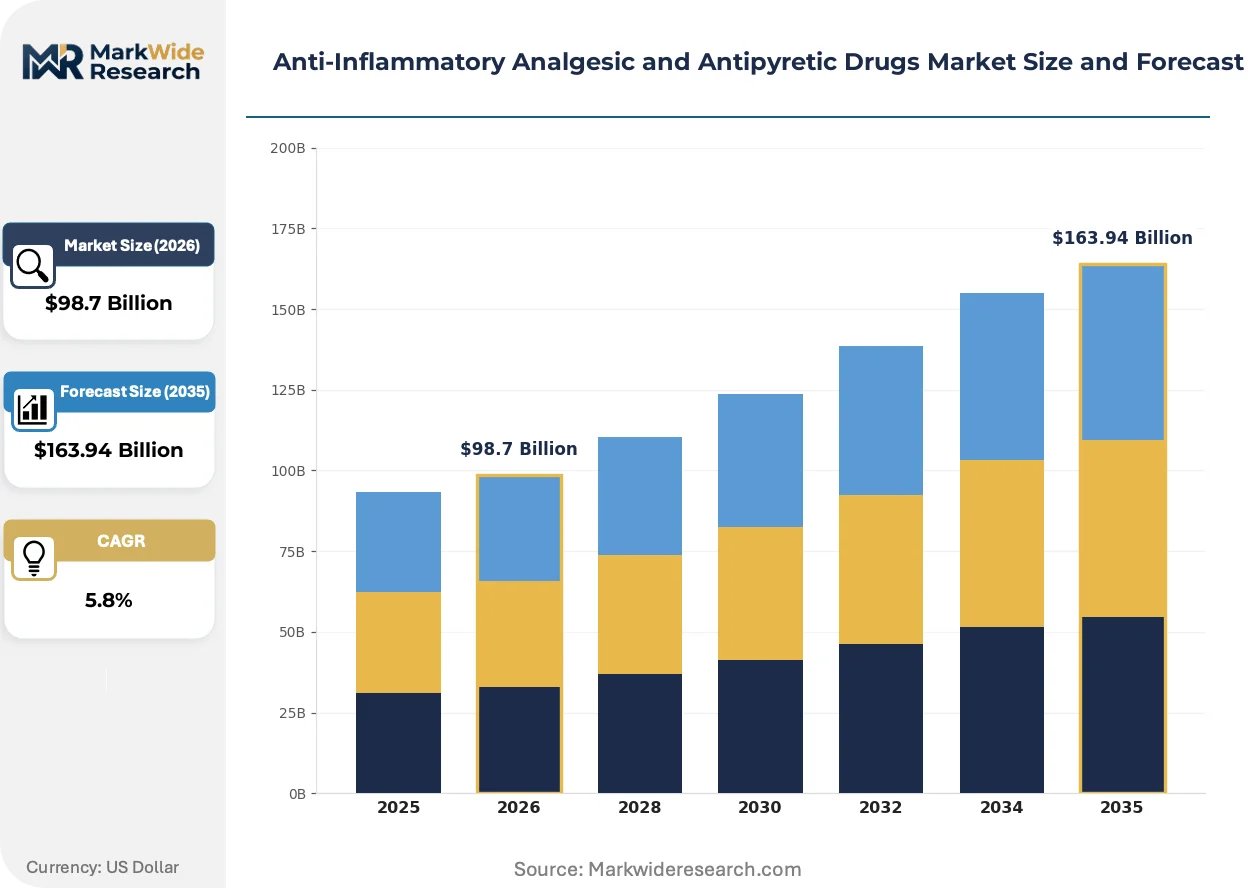
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $163.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aspirin, Ibuprofen, Paracetamol, Naproxen Therapy Area: Fever Management, Pain Relief, Arthritis Treatment, Inflammatory Disorders End User: Pharmacies, Hospitals, Clinics, Homecare Delivery Mode: Oral, Injectable, Topical, Transdermal |
| Companies Covered | Novartis AG, AbbVie Inc., Pfizer Inc., Eli Lilly and Company, Sanofi S.A., Johnson & Johnson, Bayer AG, Reckitt Benckiser Group plc, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Inflammatory Analgesic and Antipyretic Drugs Market Trends and Innovations
Formulation science and delivery mechanisms are undergoing fundamental restructuring as manufacturers respond to metabolic limitations and patient preference shifts. Three converging developments are redefining competitive advantage in this therapy area.
Process analytical technology is digitizing quality control workflows in API manufacturing facilities. Pharmaceutical manufacturers deploying PAT systems achieve real-time impurity detection and release testing, compressing batch review cycles from weeks to hours. This capability is digitizing compliance documentation and enabling continuous manufacturing scale-up for high-volume NSAID production.
REACH authorization requirements for solvent use in European manufacturing are restricting traditional organic synthesis pathways for small-molecule anti-inflammatory production. The European Chemicals Agency's substance evaluation program is forcing reformulation of existing products to eliminate classified hazardous intermediates. Generic API suppliers serving the European market are investing in aqueous-based synthesis routes and supercritical fluid extraction to maintain market access.
Direct-to-consumer advertising patterns in the United States are conditioning patients to request specific NSAID brands by name, shifting pharmacy dispensing dynamics. Retail chains are responding with private-label substitution protocols and pharmacist-led therapeutic interchange programs. This behavioral shift is most visible in arthritis treatment segments, where naproxen prescription growth reflects aging demographic profiles and brand awareness campaigns.
Anti-Inflammatory Analgesic and Antipyretic Drugs Market Segmentation
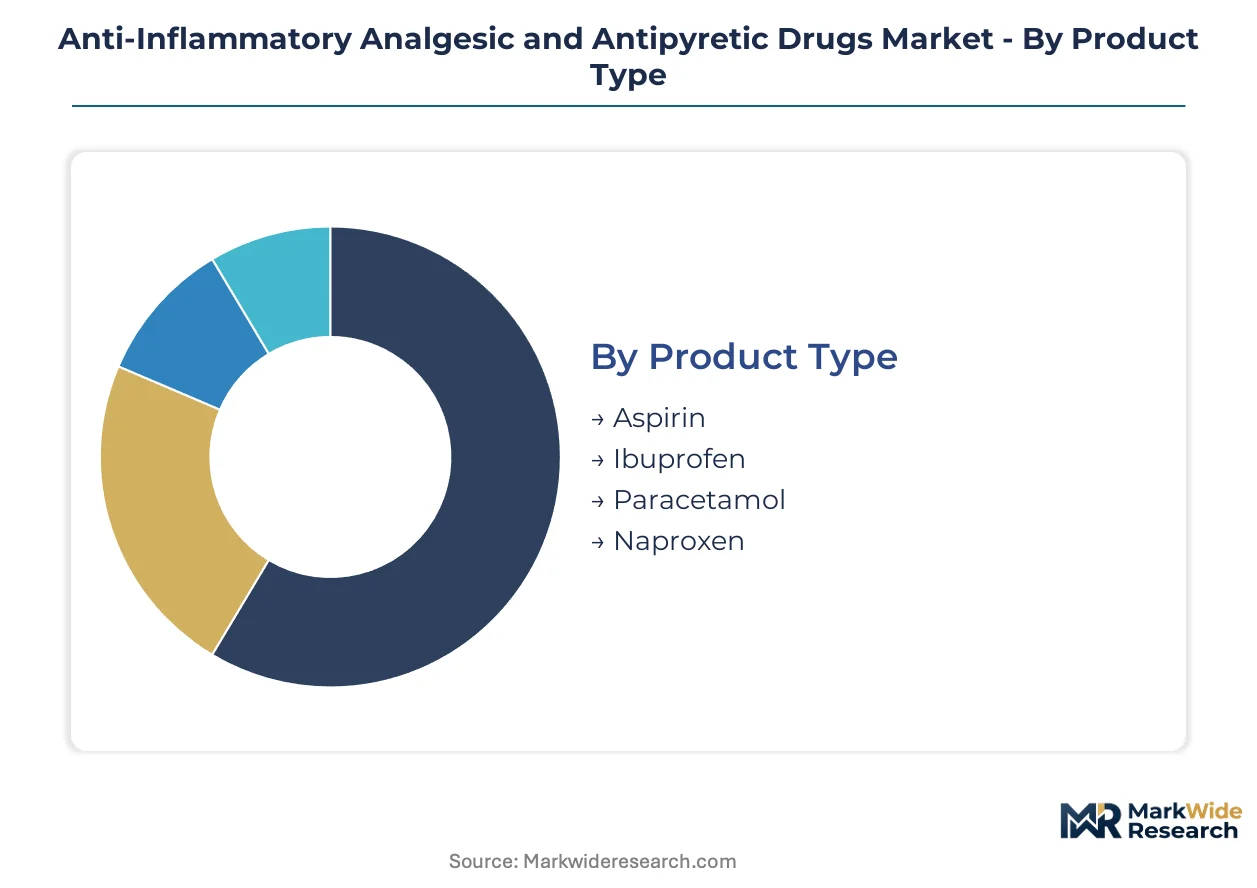
Segmentation in this market reveals how formulation choices, clinical settings, and patient mobility requirements create distinct competitive arenas. Manufacturers must align R&D investments and distribution strategies to the specific technical and regulatory demands of each slice.
Product Type:
The use-case spectrum spans acute symptom relief through chronic disease management, with molecular architecture determining metabolic pathways and safety profiles.
- Paracetamol:Centrally acting antipyretic with minimal COX inhibition and favorable hepatic safety window at therapeutic doses. Demand concentrates in United States homecare channels where direct-to-consumer advertising sustains brand recognition and pharmacy substitution protocols.
- Ibuprofen:Non-selective COX inhibitor with established efficacy in inflammatory pain states and OTC accessibility across retail networks. Manufacturing gravity centers on Chinese and Indian API clusters, exposing procurement to logistics disruption risks from geopolitical friction.
- Aspirin:Irreversible COX-1 inhibitor with antiplatelet applications in cardiovascular prophylaxis.
- Naproxen:Longer half-life enables twice-daily dosing in arthritis regimens, with prescription growth reflecting aging demographic profiles.
The dominant share belongs to Paracetamol, while Naproxen is closing the gap fastest.
Therapy Area:
Margin structures diverge sharply between episodic acute care and chronic maintenance protocols.
- Inflammatory Disorders:Rheumatoid arthritis and autoimmune conditions requiring sustained immunomodulation generate recurring revenue streams through chronic dosing requirements. Hospital systems in Germany and France expand formulary access to biologic-sparing NSAID combinations.
- Arthritis Treatment:Osteoarthritis management in aging populations drives prescription volume for extended-release formulations. United States Medicare reimbursement patterns favor generic substitution, compressing branded pricing power.
- Pain Relief:Postoperative and trauma-related analgesia spans acute care settings.
- Fever Management:Pediatric and infectious disease applications prioritize safety margins over potency.
Inflammatory Disorders command the deepest margin pools, while Arthritis Treatment is expanding most quickly.
End User:
Procurement authority and reimbursement mechanisms reshape competitive dynamics across the care continuum.
- Hospitals:Parenteral NSAID procurement accelerates as surgical volumes recover, with formulary committees prioritizing cost-per-dose metrics and contract bundling. Injectable ketorolac and diclofenac dominate perioperative protocols in United States academic medical centers.
- Homecare:Self-administered oral and transdermal formulations bypass institutional markup structures. Retail pharmacy chains in India deploy private-label substitution to capture margin from branded OTC requests.
- Pharmacies:Community dispensing faces therapeutic interchange pressure from payer formularies.
- Clinics:Ambulatory settings balance convenience against specialist prescribing authority.
Hospitals anchor institutional volume, though Homecare is gaining share fastest as patient preference shifts toward outpatient management.
Delivery Mode:
First-pass metabolism constraints and patient compliance requirements drive innovation in administration routes.
- Transdermal:Patch-based delivery circumvents hepatic CYP2C9 metabolism, enabling use in liver-compromised populations. EMA pharmacovigilance requirements for cardiovascular safety signals are accelerating post-market surveillance investments for novel topical formulations.
- Injectable:Parenteral NSAIDs achieve rapid onset for acute postoperative pain, with hospital procurement expanding as surgical backlogs clear. Novartis AG leverages biosimilar infrastructure to supply European hospital networks.
- Oral:Tablet and capsule formulations dominate volume through manufacturing scale and patient familiarity.
- Topical:Gels and creams address localized musculoskeletal pain with reduced systemic exposure.
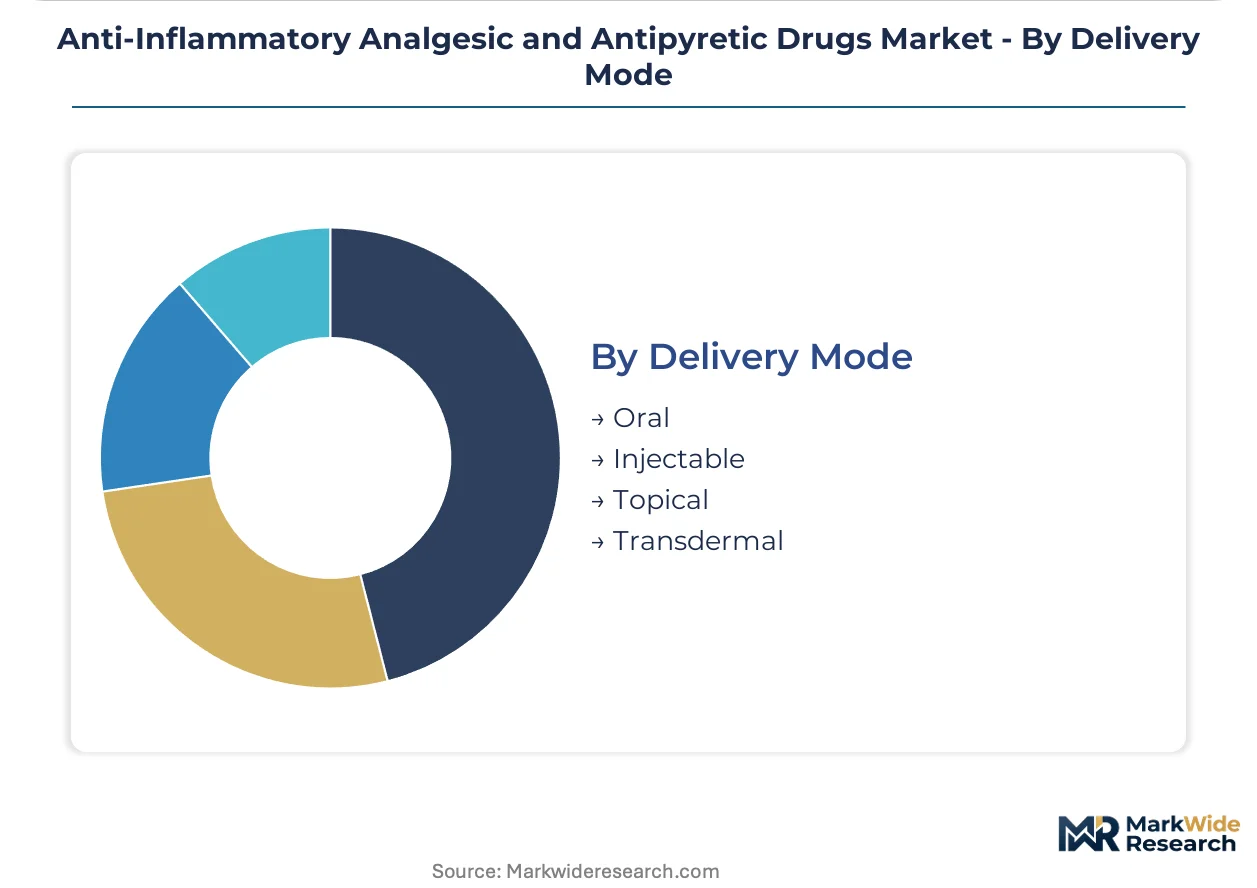
Oral delivery retains volume leadership, yet Transdermal is climbing the fastest as patients seek alternatives to first-pass hepatic metabolism.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports active pharmaceutical ingredients for ibuprofen and naproxen to formulation manufacturers in the United States and Germany, creating a trade-flow dependency that shapes procurement strategies across both markets.
United States
Chronic pain prevalence and direct-to-consumer advertising sustain high per-capita NSAID consumption. FDA REMS programs for extended-release opioid-sparing alternatives reshape prescribing patterns toward NSAID-first protocols. Hospital systems in Boston and New York expand formulary access to injectable ketorolac for perioperative pain management.
Germany
Hospital networks prioritize cost-per-dose metrics in parenteral NSAID procurement as surgical volumes recover. EMA pharmacovigilance requirements for cardiovascular safety signals mandate post-market surveillance infrastructure investments. The Rhine-Ruhr pharmaceutical cluster houses formulation facilities serving European hospital networks.
India
CDSCO accelerates approval timelines for fixed-dose combinations under its streamlined pathway, altering competitive entry sequencing. API manufacturing concentrates in Gujarat and Maharashtra, with Ahmedabad and Mumbai anchoring ibuprofen and naproxen production for export markets. Domestic retail pharmacy chains deploy private-label substitution to capture margin from branded OTC requests.
China
NMPA oversight of pharmaceutical manufacturing quality drives consolidation among API suppliers serving both domestic and export markets. The Yangtze River Delta region hosts synthesis facilities that supply intermediates to formulation manufacturers across Asia-Pacific. Environmental compliance upgrades are forcing capacity rationalization among smaller producers.
Japan
PMDA requirements for cardiovascular safety data extend development timelines for novel COX-2 selective formulations. Aging demographics drive prescription volume for extended-release naproxen in osteoarthritis management. The Kansai region maintains formulation capacity serving domestic hospital and retail pharmacy channels.
Anti-Inflammatory Analgesic and Antipyretic Drugs Market Competitive Landscape
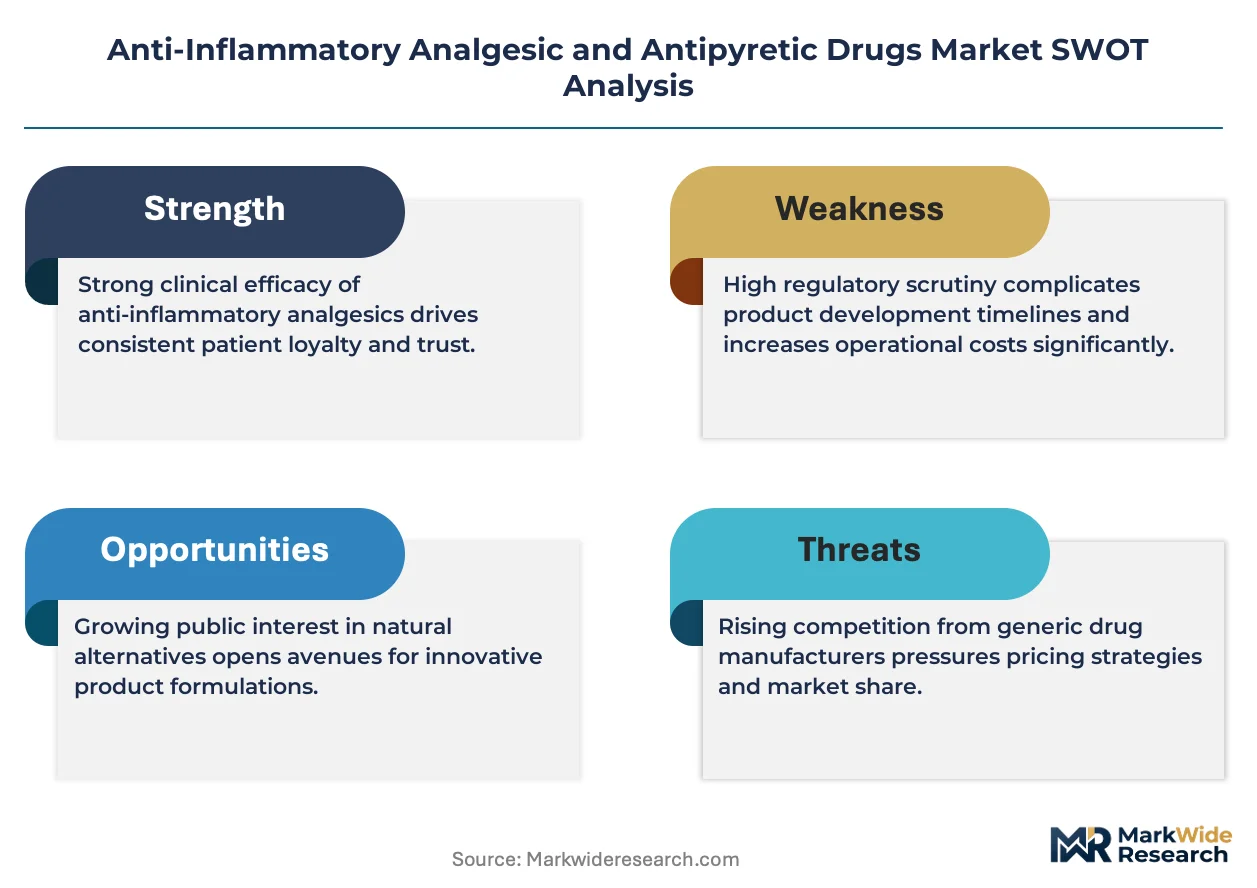
Channel-controlling players compete with product-specialist players across distinct competitive arenas. Hospital procurement committees and retail pharmacy chains exercise pricing leverage through volume commitments and formulary placement. Three archetypes dominate: diversified pharmaceutical conglomerates with immunology pipelines, generic API suppliers with backward integration into active ingredient sourcing, and consumer health specialists with OTC brand equity. M&A activity targets biosimilar infrastructure and transdermal delivery capabilities.
Within the diversified pharmaceutical tier, Novartis AG leverages its biosimilar infrastructure to anchor injectable NSAID supply chains, while AbbVie Inc. competes through immunology R&D positioning. Pfizer Inc. exemplifies scale-driven oral solid dose manufacturing with captive API sourcing. These three entities represent contrasting strategic postures: biologic platform deployment, pipeline depth, and manufacturing integration.
| Leading Market Players |
|---|
| Novartis AG |
| AbbVie Inc. |
| Pfizer Inc. |
| Eli Lilly and Company |
| Sanofi S.A. |
| Johnson & Johnson |
| Bayer AG |
| Reckitt Benckiser Group plc |
| GlaxoSmithKline plc |
| Others |
Pricing and Supply Chain Analysis
Chinese and Indian API manufacturing clusters for ibuprofen and naproxen feed directly into margin pools captured by European hospital formulary committees and United States retail pharmacy chains. This upstream concentration grants procurement leverage to downstream buyers while exposing formulation manufacturers to logistics disruption risks.
Pricing Analysis
Generational pricing gaps separate legacy batch-process APIs from continuous bioproduction grades and next-generation transdermal formulations. Three-tier pricing structure across premium, standard, and economy levels reflects purity thresholds, FDA cardiovascular safety labeling tiers, and volume scale. Cost compression in standard oral solid doses is intensifying because Medicare reimbursement patterns favor generic substitution. Homecare channels show highest price sensitivity; hospital procurement committees demonstrate lowest sensitivity due to bundled contract structures.
Supply Chain Analysis
Toll manufacturing capacity for parenteral NSAID formulations concentrates with Lonza, Catalent, and Samsung Biologics serving European and North American markets. Active pharmaceutical ingredient production draws from China, India, and Italy; excipient supply rests on German and Japanese chemical specialists. Single-source vulnerability runs through Yangtze River Delta intermediate suppliers facing environmental compliance upgrades. Distribution runs through regional hospital GPOs in the United States, EMA-authorized wholesalers in Europe, and CDSCO-licensed stockists in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from pandemic-depressed surgical volumes, with hospital procurement expansion for injectable NSAIDs marking the cyclical upswing.
For Market Incumbents: Pre-empt biosimilar infrastructure deployment by Novartis AG through captive transdermal delivery capacity additions in Germany or the United States. Secure EMA pharmacovigilance compliance certification ahead of cardiovascular safety signal mandates to create formulary lock-in. Defend against private-label substitution in United States retail channels through direct-to-consumer advertising maintenance. For New Entrants and Emerging Players: India's underpenetrated fixed-dose combination segment offers fastest regulatory pathway through CDSCO's streamlined approval mechanism. Target transdermal patch formulations for liver-compromised populations in European homecare channels. Pursue pharmacist-led therapeutic interchange partnerships with retail chains rather than direct hospital formulary competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed generic API suppliers holding backward integration into Chinese and Indian manufacturing clusters. Five-to-ten-year viability hinges on continuous bioproduction retrofit completion and REACH authorization compliance for European market access. Monitor FDA REMS program expansion for extended-release opioid-sparing alternatives as demand inflection signal for NSAID-first prescribing protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Scale-Up | Process analytical technology deployment cuts impurity profiles for EMA compliance. |
| Transdermal Delivery Development | Patch-based formulations bypass hepatic CYP2C9 metabolism in liver-compromised patients. |
| Regulatory Approval Pathway | CDSCO streamlined fixed-dose combination reviews accelerate Indian market entry sequencing. |
| Hospital System Partnership | Formulary placement contracts with United States academic medical centers anchor injectable volume. |
| Backward Integration | Captive API sourcing from Gujarat and Maharashtra clusters insulates against logistics disruption. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA REMS documentation, EMA pharmacovigilance safety signal databases, CDSCO approval records, and ClinicalTrials.gov NSAID protocol registrations. Interviews with hospital formulary directors, regulatory affairs leads at diversified pharmaceutical manufacturers, procurement managers at European hospital networks, and payer access specialists informed demand-side assumptions. Top-down market sizing from macroeconomic healthcare expenditure data triangulates against bottom-up prescription volume analysis across oral, injectable, and transdermal delivery modes.
Forecast inputs include surgical volume recovery trajectories, pharmacogenomic testing adoption curves for CYP2C9 stratification, and continuous bioproduction capacity expansion timelines. Segmentation dimensions span product type, therapy area, end user, and delivery mode with regional regulatory cluster differentiation. CAGRs derive from weighted average growth across these segments applied to base-year value estimates. Industry-specific inputs incorporate EMA cardiovascular safety surveillance cost burdens and FDA labeling revision probabilities.
The forecast holds incumbent behavior within observed patterns; aggressive moves by biosimilar infrastructure deployers or transdermal delivery specialists would shift outcomes beyond modeled ranges. Quarterly review of hospital surgical backlog clearance rates, CDSCO fixed-dose combination approval velocity, and REACH authorization timelines for solvent reformulation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Injectable Targeted Therapy Market
Pharmaceuticals
Italy Opioids Market
Pharmaceuticals
Throat Sprays Market
Pharmaceuticals
Iceland Pharmaceutical Market
Pharmaceuticals
Global Vero Cell Rabies Vaccine Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Pharmacovigilance (PV) Market
Pharmaceuticals
United States Pharmaceutical 3PL Market
Pharmaceuticals
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Global Hepatitis a Vaccine Market
Pharmaceuticals
Global Heparin Sodium Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
GCC Generic Injectables Market
Pharmaceuticals
North America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Croatia Pharmaceutical Market