
 Xanthine Oxidase Inhibitors Market | 2026-2036
Xanthine Oxidase Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Xanthine Oxidase Inhibitors Market Analytics
Next-generation urate-lowering specifications is reorganizing competitive dynamics in xanthine oxidase inhibition. Takeda Pharmaceutical Company Limited leverages its heritage in metabolic disease R&D to sustain formulation leadership. Horizon Therapeutics plc anchors the premium biologics-adjacent segment through specialized access programs. Teva Pharmaceutical Industries competes on oral generic allopurinol scale across hospital and retail channels.
Xanthine oxidase inhibitors are pharmaceutical compounds that block the xanthine oxidase enzyme responsible for converting hypoxanthine to xanthine and subsequently to uric acid, with allopurinol functioning as a purine analog and febuxostat as a non-purine selective inhibitor, both administered to prevent urate crystal deposition in gout and protect renal and cardiovascular tissues from oxidative damage. The allopurinol segment dominates prescription volume due to decades of clinical familiarity and formulary inclusion, while febuxostat commands margin concentration in refractory cases despite cardiovascular safety labeling. Oral delivery mode leads in patient adherence and pharmacy dispensing efficiency, though hospital settings remain critical for acute gout management and initial dose titration.
FDA guidelines on cardiovascular risk evaluation shape febuxostat prescribing constraints, while EMA pharmacovigilance requirements enforce post-market safety monitoring across the European Union. The FDA, EMA, and Japan's PMDA collectively determine approval pathways, label restrictions, and generic substitution rules that govern market access. Stakeholders must monitor evolving cardiology-outcome data and biosimilar entry timelines to align portfolio investments with shifting prescriber confidence and payer reimbursement criteria.
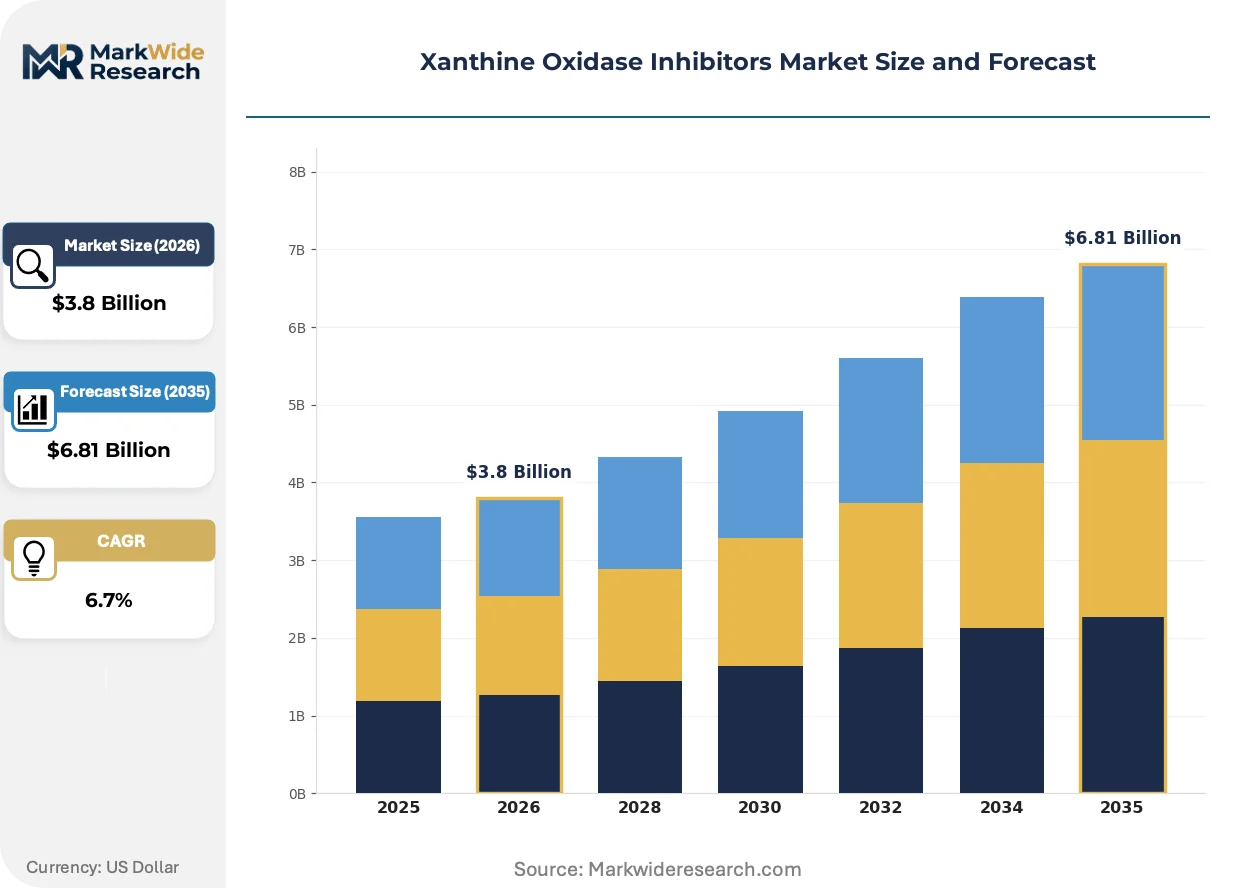
Market Dynamics
Cardiovascular safety labeling for febuxostat is fragmenting prescriber confidence and redirecting volume toward allopurinol generics, compressing margin pools across the xanthine oxidase inhibitor class while hospital procurement tightens formulary controls.
Growth Catalysts
- FDA orphan drug incentives:Developers targeting rare pediatric hyperuricemia indications receive tax credits and extended exclusivity, accelerating pipeline investment in metabolic disorders.
- Japan's aging demographic concentration:PMDA fast-track pathways for geriatric-friendly formulations expand addressable patient pools in Tokyo and Osaka metropolitan corridors.
- Hospital pharmacy consolidation:Integrated delivery networks centralize chronic gout management protocols, standardizing xanthine oxidase inhibitor protocols across emergency and ambulatory settings.
Market Restraints
- Active pharmaceutical ingredient concentration:Febuxostat intermediate synthesis depends on Chinese specialty chemical suppliers, exposing formulation partners to export license volatility.
- EMA cardiovascular risk evaluation:Post-authorization safety studies for febuxostat impose multi-year surveillance obligations that delay label expansion and indication broadening.
- Allopurinol hypersensitivity syndrome liability:HLA-B*5801 screening requirements in Asian populations add diagnostic cost layers that constrain first-line prescribing in Taiwan and South Korea.
Strategic Opportunities
- Germany's DMP disease management programs:Structured care contracts for gout create reimbursement premiums for urate-lowering therapy adherence monitoring technologies.
- Combination fixed-dose formulations:Pairing xanthine oxidase inhibitors with uricosuric agents addresses refractory cases through single-pill compliance enhancement.
- Telepharmacy channel expansion:Remote prescriber consultations for chronic gout maintenance enable direct-to-patient delivery models bypassing traditional retail pharmacy networks.
Industry Challenges
- Cardiovascular outcome trial design complexity:Demonstrating non-inferiority against allopurinol requires large patient populations and extended follow-up periods that strain development budgets.
- Generic substitution protocol fragmentation:State-level pharmacy benefit manager rules in the United States create prescribing friction between branded febuxostat and authorized allopurinol generics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Xanthine Oxidase Inhibitors Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Allopurinol, Febuxostat, Benzbromarone, Other Application: Gout Treatment, Cardiovascular Protection, Kidney Protection, Other Delivery Mode: Oral, Injectable, IV Infusion, Other End User: Hospitals, Clinics, Pharmacies, Homecare |
| Companies Covered | Takeda Pharmaceutical Company Limited, Horizon Therapeutics plc, AstraZeneca plc, Viatris, Lupin Limited, Teva Pharmaceutical Industries, Sun Pharmaceutical Industries, Dr. Reddy's Laboratories, Ipca Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Xanthine Oxidase Inhibitors Market Evolving Landscape
Next-generation urate-lowering mechanisms are diversifying the therapeutic landscape beyond traditional enzyme inhibition, with novel modalities entering clinical evaluation and reshaping competitive positioning across chronic and acute gout management.
Extended-release allopurinol formulations are supplanting immediate-release tablets in maintenance therapy protocols. Rheumatology practices in the United States and Germany are adopting once-daily dosing regimens to improve adherence metrics in elderly populations with polypharmacy burdens. This formulation shift is compressing market share for standard allopurinol while creating premium pricing corridors for modified-release technologies.
REACH compliance requirements for pharmaceutical manufacturing residues are tightening effluent treatment standards across European Union production facilities. EMA environmental risk assessments now mandate biodegradability thresholds for active pharmaceutical ingredients in xanthine oxidase inhibitor synthesis. Contract manufacturers in Ireland and the Netherlands are investing in advanced oxidation process upgrades to meet these discharge criteria.
Hospital-at-home programs are reconfiguring acute gout management pathways, with infusion centers and mobile nursing services displacing traditional inpatient admissions for severe flares. Medicare Advantage plans in Florida and Arizona are piloting bundled payment models that incentivize outpatient parenteral therapy administration. This care model migration is concentrating volume in specialized infusion networks while compressing emergency department utilization for crystal arthritis episodes.
Xanthine Oxidase Inhibitors Market Segmentation
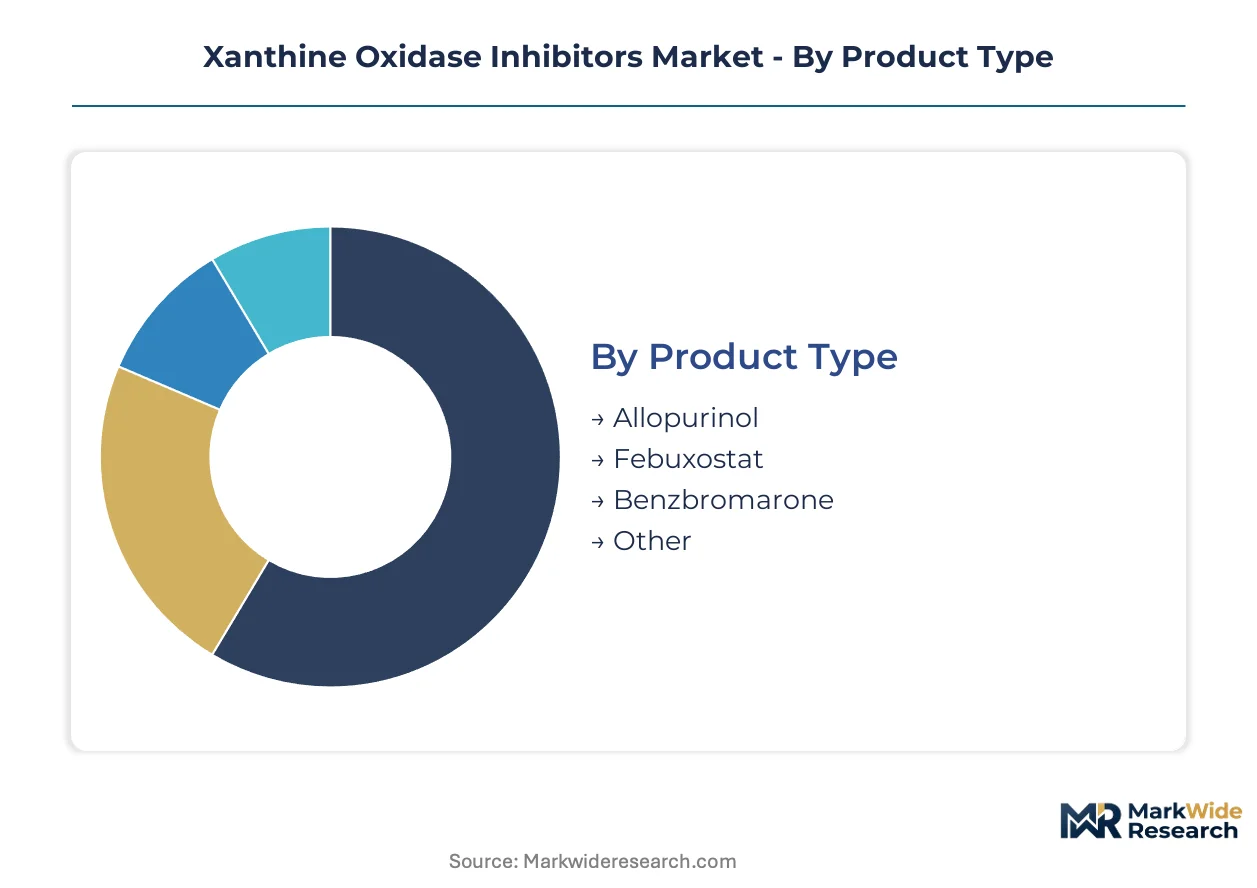
Xanthine oxidase inhibitor portfolios require precise segment targeting to align formulation investments with prescriber protocols and reimbursement pathways. Manufacturers must balance generic allopurinol scale against febuxostat premium positioning while tracking delivery mode shifts that reshape pharmacy dispensing economics.
Product Type:
Margin pools concentrate in branded non-purine inhibitors where cardiovascular safety labeling creates prescribing barriers that protect pricing power, while generic purine analogs compete on formulary inclusion and hospital procurement volume.
- Allopurinol:The purine analog mechanism blocks xanthine oxidase through competitive substrate inhibition, with decades of clinical familiarity driving formulary dominance across United States Medicare Part D formularies and Germany's statutory health insurance catalogs. Demand concentrates in maintenance therapy protocols for chronic gout, though HLA-B*5801 screening requirements in Asian populations constrain first-line prescribing in Taiwan and South Korea.
- Febuxostat:This non-purine selective inhibitor binds the enzyme's active site with higher affinity, commanding premium positioning in refractory cases where allopurinol intolerance or inadequate response occurs. Prescription volume clusters in Japan's metropolitan corridors where PMDA fast-track pathways expanded geriatric-friendly access, though FDA cardiovascular safety warnings have fragmented prescriber confidence in United States cardiology practices.
- Benzbromarone:The uricosuric-adjunct mechanism finds niche utilization in European Union markets where EMA hepatotoxicity monitoring permits restricted prescribing.
- Other:Emerging enzyme inhibitors and combination molecules occupy pipeline-stage development with orphan drug designations for rare pediatric hyperuricemia.
Allopurinol holds installed capacity across chronic maintenance protocols. Febuxostat is rotating up the share rankings in refractory case management despite safety label constraints.
Application:
Volume distribution tracks rheumatology prescribing patterns, with acute flare prevention commanding larger patient pools than organ-protection indications that require cardiology-nephrology cross-specialty adoption.
- Gout Treatment:Urate crystal deposition prevention represents the core therapeutic target, with serum uric acid reduction below saturation thresholds driving clinical outcomes. Demand concentrates in United States hospital emergency departments and Germany's disease management program networks where structured care contracts incentivize adherence monitoring technologies.
- Cardiovascular Protection:Oxidative stress reduction through xanthine oxidase inhibition targets endothelial dysfunction in hyperuricemic patients with concurrent heart failure risk. Prescription volume clusters in Japanese geriatric populations where metabolic comorbidity clustering creates polypharmacy protocols combining urate-lowering with statin therapy.
- Kidney Protection:Renal tissue preservation indications target chronic kidney disease progression attenuation through uric acid-driven inflammatory pathway suppression.
- Other:Tumor lysis syndrome prophylaxis and rare metabolic disorder management occupy pediatric oncology and genetic medicine protocols with orphan drug pricing structures.
Gout treatment anchors prescription volume across retail and hospital channels. Cardiovascular protection is climbing the fastest as outcome trial data reshapes prescriber confidence in metabolic-cardiology integration.
Delivery Mode:
Patient adherence economics and pharmacy dispensing efficiency determine channel selection, with oral formulations dominating maintenance therapy while acute settings retain parenteral capabilities for severe flares.
- Oral:Tablet and capsule formulations enable self-administered chronic therapy with once-daily or twice-daily regimens. Extended-release technologies are supplanting immediate-release tablets in United States rheumatology practices seeking polypharmacy burden reduction in elderly populations.
- Injectable:Subcutaneous and intramuscular routes serve hospital-at-home programs and mobile nursing services displacing traditional inpatient admissions for severe gout flares in Florida and Arizona Medicare Advantage networks.
- IV Infusion:Intravenous administration concentrates in emergency department settings and specialized infusion centers for acute crystal arthritis episodes requiring rapid urate lowering.
- Other:Transdermal patches and buccal films occupy development-stage pipelines targeting geriatric swallowing difficulty segments.
Oral delivery holds installed capacity across maintenance therapy populations. Injectable formats are rotating up the share rankings through hospital-at-home program expansion.
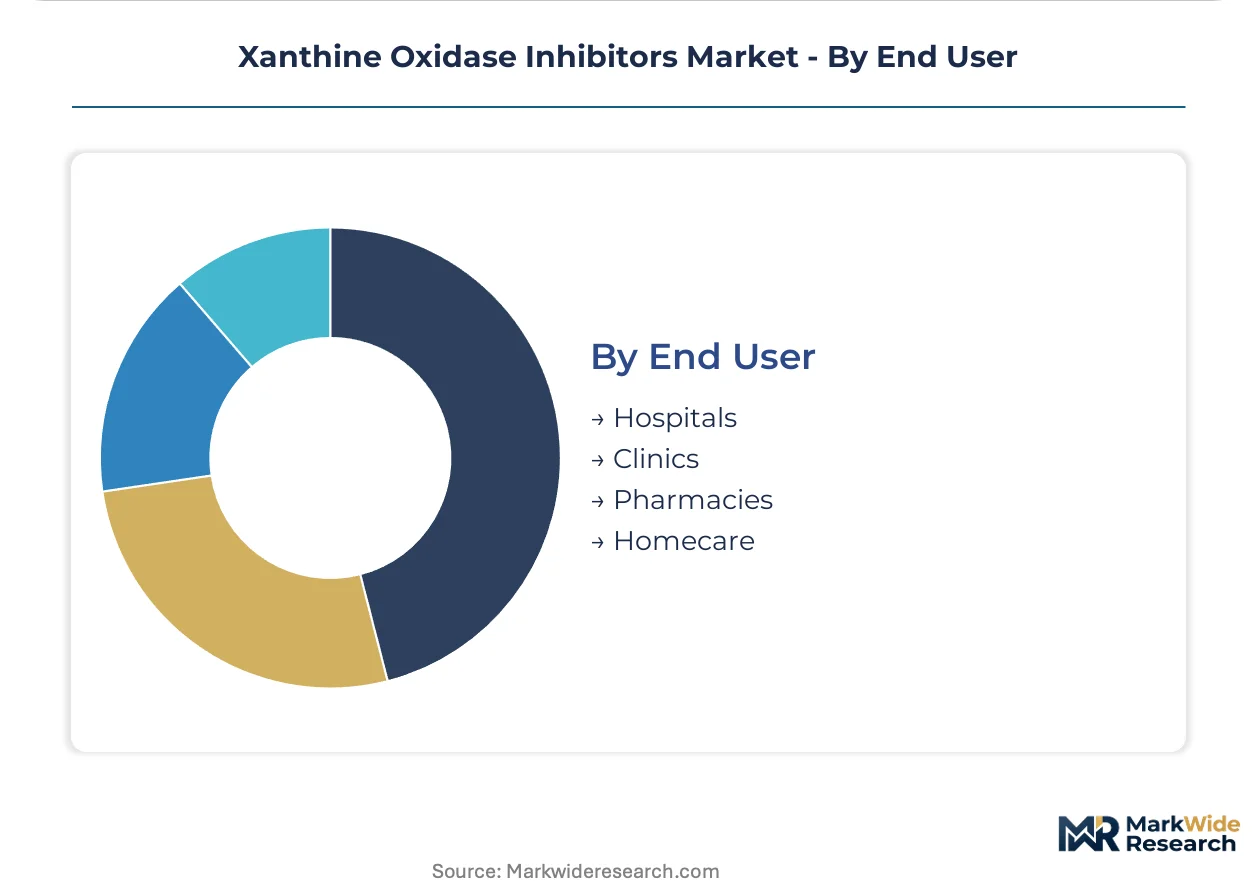
End User:
Procurement authority and reimbursement pathway structure determine segment economics, with integrated delivery networks centralizing volume while retail pharmacy fragmentation creates generic substitution friction.
- Hospitals:Inpatient and emergency department settings manage acute gout flares and initial dose titration protocols, with pharmacy and therapeutics committees enforcing formulary controls that standardize xanthine oxidase inhibitor selection across emergency and ambulatory settings.
- Clinics:Outpatient rheumatology and nephrology practices drive maintenance therapy prescribing with electronic health record-integrated decision support for urate target monitoring.
- Pharmacies:Retail and specialty pharmacy channels handle chronic prescription fulfillment, with telepharmacy expansion in rural United States markets enabling remote prescriber consultation and direct-to-patient delivery.
- Homecare:Infusion nursing services and patient self-administration programs support hospital-at-home transitions and long-term maintenance adherence.
Hospitals hold installed capacity across acute episode management. Homecare is rotating up the share rankings through bundled payment model adoption and telepharmacy channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient synthesis for xanthine oxidase inhibitors clusters in Chinese specialty chemical corridors, while formulation and commercialization concentrate in United States, German, and Japanese markets where aging demographics sustain prescription volume.
United States
Medicare Part D formularies drive allopurinol generic substitution at scale, with hospital pharmacy consolidation tightening procurement controls across integrated delivery networks. FDA cardiovascular safety warnings for febuxostat reshape prescriber confidence in cardiology practices. Florida and Arizona Medicare Advantage networks pilot hospital-at-home bundled payments for acute gout management.
Germany
Statutory health insurance catalogs maintain allopurinol formulary dominance, with disease management program contracts creating reimbursement premiums for urate-lowering adherence technologies. EMA pharmacovigilance requirements enforce post-authorization safety monitoring across the European Union. Rheumatology practices in Bavaria and North Rhine-Westphalia adopt extended-release formulations for elderly polypharmacy populations.
Japan
PMDA fast-track pathways for geriatric-friendly formulations expand addressable patient pools in Tokyo and Osaka metropolitan corridors. Metabolic comorbidity clustering drives polypharmacy protocols combining urate-lowering with statin therapy. Febuxostat prescription volume concentrates in Kanto and Kansai regions where cardiovascular protection indications gain traction.
India
CDSCO regulatory frameworks govern generic allopurinol manufacturing for export markets, with contract research organizations supporting bioequivalence studies for ANDA submissions. Active pharmaceutical ingredient production clusters in Gujarat and Maharashtra supply formulation partners globally. Domestic prescription volume rises with urban diabetes-gout comorbidity recognition.
United Kingdom
NICE guidelines on gout management standardize xanthine oxidase inhibitor first-line prescribing across NHS trusts. Hospital pharmacy and therapeutics committees enforce formulary controls that favor generic allopurinol over branded alternatives. London and Southeast England rheumatology networks integrate electronic health record decision support for urate target monitoring.
Xanthine Oxidase Inhibitors Market Competitive Landscape
Concentration sits with diversified pharmaceutical conglomerates commanding hospital formulary access and generic scale manufacturing. The market structures around three tiers: research-intensive innovators with metabolic disease heritage, mid-cap generic manufacturers with API-to-formulation integration, and specialty biologics-adjacent players with rare disease focus. Competitive moves center on portfolio diversification into extended-release technologies and geographic expansion through emerging market distribution partnerships.
Within the research-intensive tier, Takeda Pharmaceutical Company Limited anchors Japanese market presence through metabolic disease R&D heritage. Horizon Therapeutics plc occupies the specialty biologics-adjacent position with rare disease program infrastructure. Teva Pharmaceutical Industries represents the generic scale archetype with hospital and retail channel penetration across North American and European markets.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Horizon Therapeutics plc |
| AstraZeneca plc |
| Viatris |
| Lupin Limited |
| Teva Pharmaceutical Industries |
| Sun Pharmaceutical Industries |
| Dr. Reddy's Laboratories |
| Ipca Laboratories |
| Others |
Value Network & Pricing Analysis
Extended-release allopurinol formulations replacing immediate-release tablets are simultaneously relocating manufacturing toward Irish and Dutch contract manufacturers facing REACH effluent standards and compressing margin pools for standard generics across United States Medicare Part D formularies. This substitution dynamic concentrates pricing power with modified-release technology holders while eroding commodity tablet economics.
Pricing Analysis
FDA cardiovascular safety warnings dictate the pricing tier structure for xanthine oxidase inhibitors, stratifying value across three levels: premium branded febuxostat for refractory cases, mid-tier extended-release allopurinol for adherence-focused protocols, and economy immediate-release generics for scale procurement. Price differentiation hinges on formulation technology and HLA-B*5801 screening bundling in Asian populations. Cost compression in the generic tier is intensifying because hospital pharmacy consolidation enforces formulary standardization. Retail pharmacy channels exhibit highest price sensitivity, while integrated delivery networks prioritize clinical outcome metrics over unit cost.
Supply Chain Analysis
Port congestion on Shanghai-Rotterdam trade lanes is elevating inbound logistics costs for febuxostat intermediate shipments, exposing formulation partners to scheduling volatility. Active pharmaceutical ingredient synthesis clusters in China, India, and Ireland, with specialty chemical production in Gujarat and Maharashtra feeding global generic manufacturing. Febuxostat production rests on Chinese 2-cyanopyrimidine intermediates and European contract finishing capabilities. Single-source vulnerability concentrates in Shanghai specialty chemical corridors. Distribution runs through hospital procurement consortia and retail pharmacy chains, with telepharmacy channels emerging for direct-to-patient fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against novel urate-lowering biologics and uricosuric combination therapies that threaten to displace traditional enzyme inhibition. Incumbents must fortify positioning around adherence technologies and cardiovascular outcome data.
For Market Incumbents: Shield formulation portfolios by securing backward integration into extended-release manufacturing capabilities and investing in HLA-B*5801 diagnostic bundling for Asian market defense. The priority lever centers on hospital formulary lock-in through integrated adherence monitoring technologies that generic competitors cannot replicate. For New Entrants and Emerging Players: Differentiate on geriatric-friendly delivery formats, specifically transdermal patches and buccal films targeting polypharmacy burden reduction in Japan's metropolitan corridors. The most penetrable white space sits in telepharmacy-enabled direct-to-patient models for rural United States maintenance therapy, with Medicare Advantage bundled payment alignment as the go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty pharmaceutical platforms possessing hospital channel infrastructure but lacking metabolic disease R&D depth. Long-term viability hinges on cardiovascular outcome trial positioning and biosimilar defense capabilities. The signal to watch is febuxostat label revision timing as an inflection indicator for class-wide pricing power. Recalibration cycles align with FDA advisory committee outcomes and EMA pharmacovigilance updates.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Cardiovascular outcome studies reshape prescriber confidence in metabolic-cardiology integration. |
| Regulatory Approval Pathway | FDA orphan drug incentives accelerate pediatric hyperuricemia pipeline investment timelines. |
| Manufacturing Scale-Up | REACH-compliant Irish facilities capture extended-release formulation contract manufacturing volume. |
| Pipeline Diversification | Combination fixed-dose uricosuric pairings address refractory case compliance enhancement. |
| Strategic Partnership | Telepharmacy platform alliances enable direct-to-patient delivery bypassing retail networks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Conversations with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists inform demand-side dynamics. Bottom-up prescription volume modeling triangulates against top-down pharmaceutical expenditure tracking across national health systems.
Segmentation dimensions modeled include product type, application, delivery mode, end user, and regional regulatory cluster across the projection horizon. CAGRs derive from patient population epidemiology, patent expiration timelines, and generic substitution elasticity. Forecast inputs incorporate PMDA fast-track pathway utilization rates and Medicare Advantage bundled payment adoption curves.
Material uncertainties — cardiovascular safety label revisions, API export license volatility, biosimilar entry sequencing — sit outside the modeled envelope. Forecasts reflect assumptions about prescriber behavior stability and reimbursement pathway continuity. Recalibration cycles align with material shifts in regulatory guidance and outcome trial readouts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Herbal Drugs Market
Pharmaceuticals
Topical Corticosteroids Market
Pharmaceuticals
Global Hepatitis a Vaccine Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Acetylcholine Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Compound Diclofenac Sodium and Chlorphenamine Maleate Tablets Market
Pharmaceuticals
Europe Laxative Market
Pharmaceuticals
Anticoagulants Market
Pharmaceuticals
Asia-Pacific Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Global Desmopressin Market
Pharmaceuticals
Palonosetron Hydrochloride Market
Pharmaceuticals
Zoledronic Acid Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
Global Recombinant Vaccines Market