
 Germany Pharmaceutical Warehousing Market | 2026-2036
Germany Pharmaceutical Warehousing Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Pharmaceutical Warehousing Market Insights
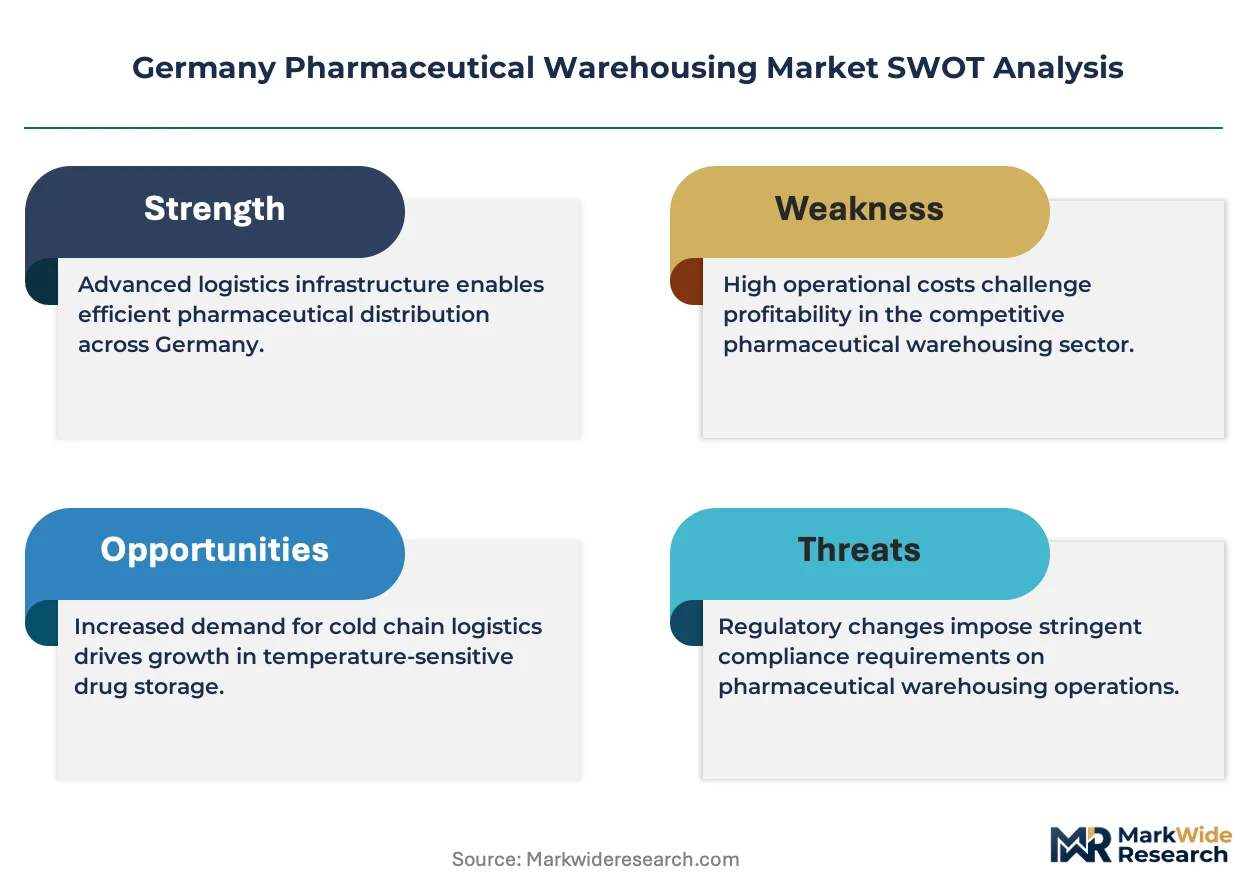
Biologics distribution is repositioning Germany's pharmaceutical warehousing landscape toward temperature-sensitive infrastructure. DHL Supply Chain leverages its pan-European cold-chain network to anchor large-molecule logistics across southern Germany. Rhenus SE and Co. KG specializes in pharma-compliant cross-docking facilities near the Rhine corridor. GEODIS SA competes through automated storage investments that reduce temperature excursion risks during peak demand periods.
Germany pharmaceutical warehousing encompasses the receipt, climate-controlled storage, inventory tracking, and dispatch of medicinal products under strict regulatory protocols, typically requiring validated systems that maintain 2-8°C or 15-25°C ranges depending on product stability profiles. Its primary purpose is to preserve therapeutic efficacy while enabling compliant distribution to pharmacies, hospitals, and wholesale depots. Cold chain services capture the dominant margin pool as biologics and vaccine volumes expand, while warehouse management systems represent the fastest-growing technology segment as operators replace legacy software with real-time visibility platforms. Temperature-controlled packaging is maturing as a segment, with primary and secondary packaging tiers consolidating around standardized solutions that reduce qualification overhead.
The Bundesinstitut für Arzneimittel und Medizinprodukte enforces EU Good Distribution Practice standards that mandate continuous temperature monitoring and documented deviation protocols for all licensed warehouses. The EU Falsified Medicines Directive, implemented through Germany's national verification system, requires serialization infrastructure that reshapes warehouse layout and IT architecture. Stakeholders must monitor how the EU AI Act and evolving CSRD reporting obligations will layer algorithmic accountability and carbon disclosure requirements onto warehouse operations.
Market Dynamics
The EU Good Distribution Practice revision is compressing compliance timelines for German pharmaceutical warehouses, forcing simultaneous upgrades to temperature-monitoring infrastructure and serialization systems that strain capital allocation decisions across the sector.
Growth Catalysts
- Biologics volume surge:Cell and gene therapies require validated 2-8°C and ultra-low temperature storage, pulling investment into specialized cold-chain infrastructure across Bavaria and Baden-Württemberg.
- EU Falsified Medicines Directive:Germany's national verification system mandates end-to-end traceability, creating mandatory demand for warehouse management system upgrades and serialized inventory tracking.
- Outsourcing acceleration:Mid-sized pharmaceutical manufacturers are divesting captive warehousing assets, transferring volume to third-party logistics operators with established pharma-compliant networks.
Market Restraints
- Energy cost volatility:Natural gas and electricity price fluctuations in Germany directly compress margins for temperature-controlled facilities operating 24/7 validated environments.
- Specialized construction capacity:Qualified contractors capable of building EU-GDP-compliant warehouses with integrated cold rooms are concentrated in southern Germany, extending project timelines.
- Qualification burden:Each temperature zone requires separate validation protocols under BfArM oversight, multiplying documentation overhead for multi-client facilities.
Strategic Opportunities
- Eastern Germany expansion:Saxony and Thuringia offer lower land and labor costs for new-build pharma warehouses serving Berlin-Brandenburg hospital networks.
- CSRD carbon disclosure:Early adoption of emissions-tracking warehouse management systems positions operators for preferred supplier status with ESG-mandated pharmaceutical procurement teams.
- AI Act algorithmic accountability:Predictive inventory systems that document decision transparency can capture compliance-premium contracts from risk-averse biologics manufacturers.
Industry Challenges
- Qualified personnel scarcity:Pharmacy technicians with GDP certification and cold-chain handling experience are concentrated in Munich and Frankfurt labor markets, constraining facility expansion.
- Legacy system integration:ERP connections between decades-old pharmaceutical inventory platforms and new real-time temperature monitoring architectures create data integrity risks during audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Pharmaceutical Warehousing Market |
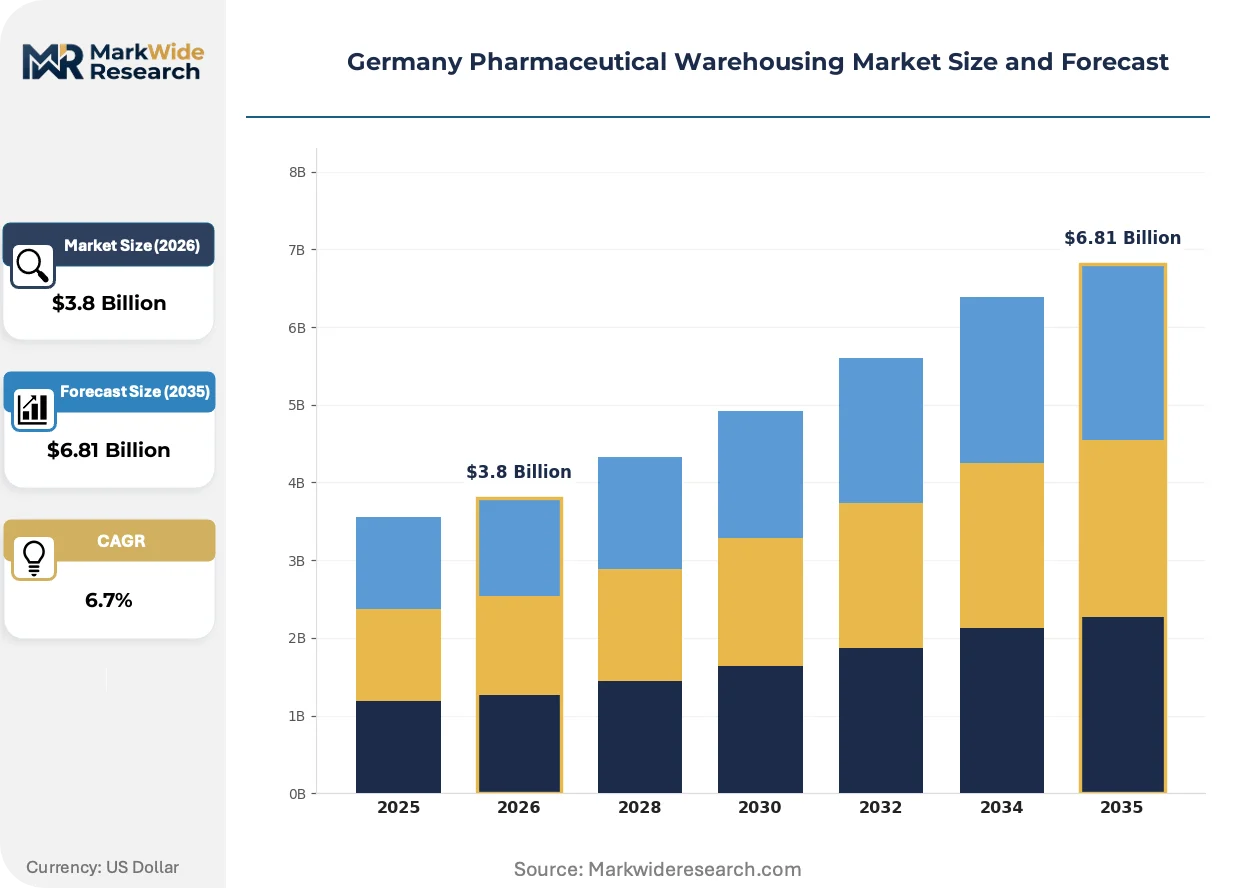
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cold Chain, Inventory Management, Order Fulfillment, Cross-Docking Technology: Warehouse Management System, Automated Storage, Robotics, IoT Integration Packaging Type: Primary Packaging, Secondary Packaging, Tertiary Packaging, Temperature-Controlled Packaging End User: Pharmaceutical Companies, Distributors, Retail Pharmacies, Hospitals |
| Companies Covered | XPO Logistics Inc., GXO Logistics, GEODIS SA, DB Schenker, CDS Hackner GmbH, Wagner Group GmbH, Rhenus SE and Co. KG, CEVA Logistics, DHL Supply Chain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Pharmaceutical Warehousing Market Trends and Innovations
Automation and regulatory technology are converging to reshape how German pharmaceutical warehouses validate compliance, manage energy, and interface with downstream healthcare distribution networks.
Robotic picking systems are expanding into ambient and cold-chain zones previously reserved for manual handling due to product sensitivity concerns. Large-molecule distributors in the Rhine-Main region are deploying collaborative robots for secondary packaging operations, compressing order fulfillment cycles while maintaining BfArM-required documentation trails. This hardware shift is expanding into mid-tier facilities that previously deferred capital investment, narrowing the capability gap between national operators and regional specialists.
The EU AI Act's risk classification framework is forcing warehouse operators to document algorithmic decision-making in inventory allocation and demand forecasting systems. German pharmaceutical logistics providers must now maintain technical files for automated temperature excursion response protocols, adding compliance overhead but creating differentiation for transparent system architectures. Bavaria-based facilities serving vaccine distribution networks are earliest affected, retrofitting audit trails into existing warehouse management platforms.
Hospital procurement consolidation is compressing vendor lists and extending contract durations for pharmaceutical warehousing services. University hospital networks in North Rhine-Westphalia are migrating from transactional spot purchasing to multi-year integrated logistics agreements that bundle storage, distribution, and compliance reporting. This pattern is most visible in oncology and rare disease therapeutic categories where supply security outweighs unit cost considerations.
Germany Pharmaceutical Warehousing Market Segmentation
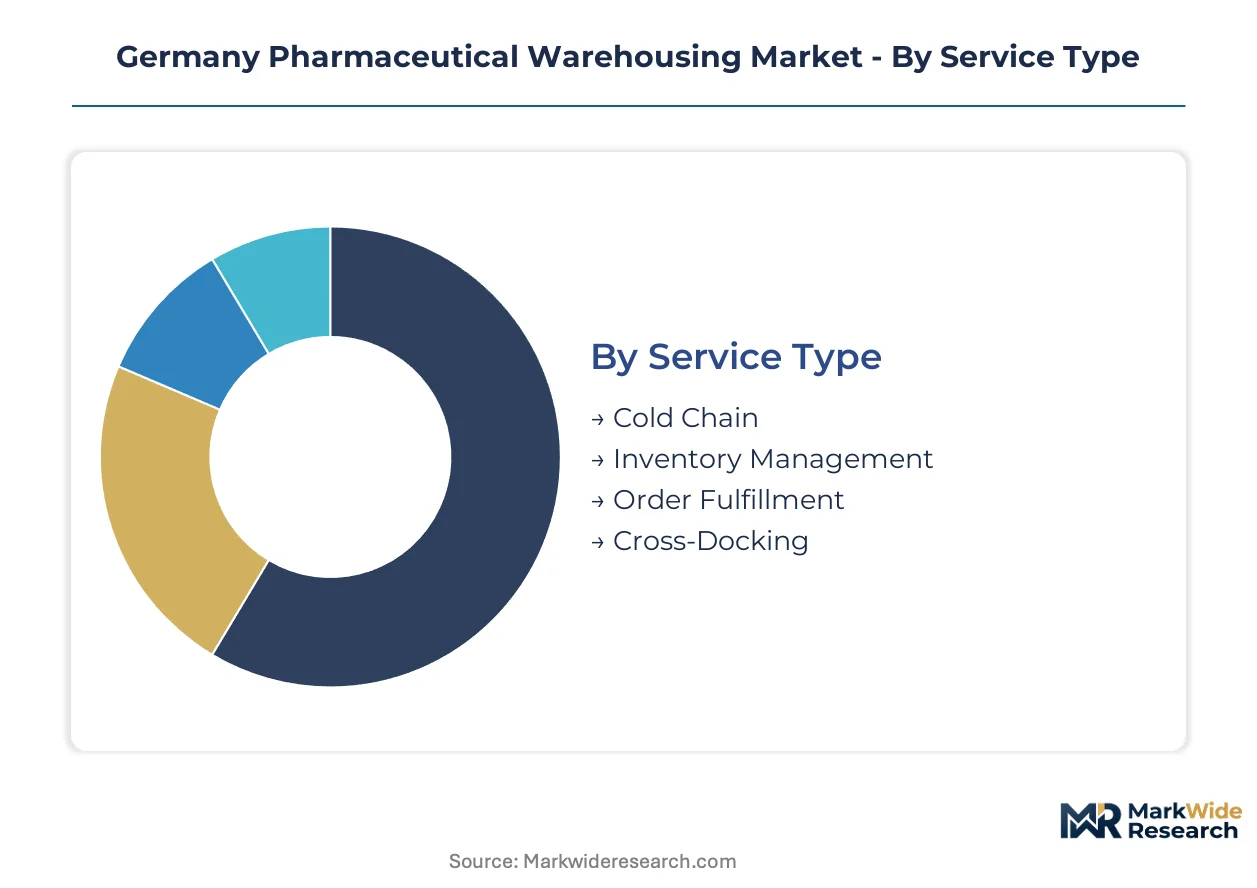
Segmentation in Germany's pharmaceutical warehousing market reveals how regulatory pressure and product complexity fragment service requirements. Each dimension carries distinct margin profiles and capital intensity that shape operator specialization strategies.
Service Type:
Cold Chain commands premium pricing while Order Fulfillment drives transaction volume across Bavaria and Baden-Württemberg facilities.
- Cold Chain:Validated 2-8°C and ultra-low temperature storage with continuous monitoring infrastructure. Demand concentrates in Munich-Nuremberg biologics corridors where BfArM oversight mandates redundant backup systems for cell therapy distribution.
- Inventory Management:Real-time stock visibility with EU Falsified Medicines Directive serialization integration. Rhine-Main hospital networks are consolidating procurement around vendors offering predictive analytics for oncology drug availability.
- Order Fulfillment:Same-day dispatch capabilities for emergency pharmaceutical supplies. Berlin-Brandenburg pharmacy cooperatives prioritize speed over cost for critical care medications.
- Cross-Docking:Minimal-touch transfer of temperature-sensitive products between transport modes. Rhine corridor facilities leverage proximity to Rotterdam port for import distribution.
Today's leader: Cold Chain. Tomorrow's challenger: Inventory Management.
Technology:
Automation investments separate margin leaders from commodity operators as labor scarcity intensifies across German pharmaceutical logistics.
- Warehouse Management System:Cloud-native platforms replacing legacy ERP connections. Saxony-based operators are adopting these systems fastest to attract ESG-mandated procurement contracts.
- Automated Storage:Vertical lift modules and shuttle systems for high-density pharmaceutical storage. Thuringia new-build facilities deploy these to minimize temperature excursion risks during retrieval.
- Robotics:Collaborative picking arms for secondary packaging in cold-chain environments. Bavaria vaccine distributors lead deployment as BfArM documentation requirements favor machine-generated audit trails.
- IoT Integration:Sensor networks feeding real-time temperature and location data to centralized dashboards. North Rhine-Westphalia hospital networks require this capability for supplier qualification.
Warehouse Management System claims current investment share. Robotics shows steepest expansion trajectory.
Packaging Type:
Regulatory qualification burden is consolidating supplier tiers around standardized solutions that reduce validation overhead.
- Primary Packaging:Direct drug-contact materials requiring stability testing. Biologics manufacturers in southern Germany are sourcing pre-qualified formats to accelerate batch release timelines.
- Secondary Packaging:Carton and labeling systems with serialization integration. Distributors serving retail pharmacy chains prioritize this segment for EU Falsified Medicines Directive compliance.
- Tertiary Packaging:Pallet-level containment for bulk pharmaceutical shipments. Generic drug wholesalers in eastern Germany favor standardized tertiary formats to minimize handling costs.
- Temperature-Controlled Packaging:Insulated shippers with phase-change materials for 2-8°C and frozen distribution. Hospital networks are mandating reusable systems to meet CSRD carbon disclosure requirements.
Secondary Packaging dominates current qualification spend. Temperature-Controlled Packaging is gaining share fastest.
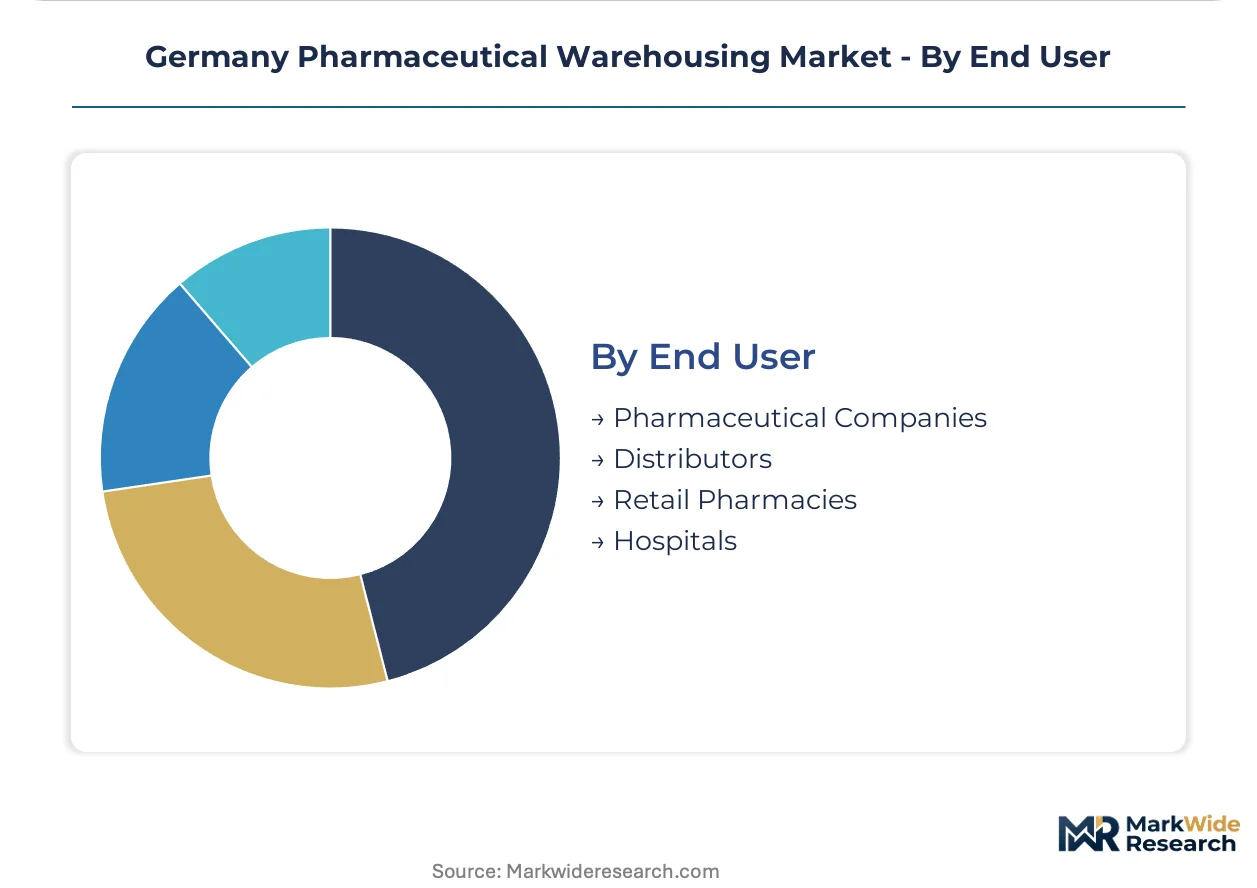
End User:
Procurement consolidation is extending contract durations and bundling compliance reporting requirements across user categories.
- Pharmaceutical Companies:Captive and outsourced warehousing for finished goods and clinical supplies. Mid-sized manufacturers in Baden-Württemberg are divesting assets to third-party operators with established GDP networks.
- Distributors:Wholesale depots serving pharmacy and hospital networks. Bavaria-based specialists are integrating forward logistics to capture margin from direct-to-pharmacy delivery.
- Retail Pharmacies:Hub-and-spoke distribution from central warehouses to storefronts. Berlin cooperatives are consolidating vendor lists around multi-year integrated logistics agreements.
- Hospitals:On-site and near-site storage for high-value therapeutics. University hospital networks in North Rhine-Westphalia require 24/7 validated environments for CAR-T cell therapies.
Pharmaceutical Companies anchor current revenue. Hospitals are climbing the fastest as procurement shifts toward supply security premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's pharmaceutical corridor between Munich and Nuremberg anchors German demand for temperature-controlled warehousing infrastructure. The state's biologics manufacturing density drives specialized cold-chain facility construction unmatched elsewhere in the country. Regional fragmentation across Germany's federal structure creates distinct regulatory and cost environments that shape operator location decisions.
North Rhine-Westphalia
University hospital networks in Cologne and Düsseldorf are consolidating procurement around multi-year integrated logistics agreements. The EU Falsified Medicines Directive implementation through Germany's national verification system mandates serialization infrastructure upgrades across Rhine-Ruhr distribution hubs. DHL Supply Chain anchors large-scale operations in this region to serve hospital networks requiring 24/7 validated environments for CAR-T cell therapies.
Baden-Württemberg
Mid-sized pharmaceutical manufacturers in Stuttgart and Mannheim are divesting captive warehousing assets to third-party operators. BfArM oversight enforces continuous temperature monitoring protocols that strain legacy facilities in the region. Heidelberg and Freiburg biotech clusters are pulling investment into ultra-low temperature storage infrastructure for cell and gene therapy distribution.
Berlin-Brandenburg
Pharmacy cooperatives in the capital region prioritize same-day dispatch capabilities for critical care medications over cost minimization. The Bundesinstitut für Arzneimittel und Medizinprodukte maintains direct regulatory presence in Berlin, accelerating compliance timeline enforcement. Potsdam and surrounding areas are attracting new-build facilities serving the expanded hospital networks in eastern Germany.
Hesse
The Rhine-Main logistics corridor leverages Frankfurt's air cargo connectivity for temperature-sensitive pharmaceutical imports. GEODIS SA and CEVA Logistics maintain significant footprints here to capitalize on multimodal distribution advantages. Wiesbaden and Mainz pharmaceutical wholesalers are integrating forward logistics capabilities to capture margin from direct-to-pharmacy delivery models.
Lower Saxony
Generic drug distribution networks in Hanover and Braunschweig favor standardized tertiary packaging formats to minimize handling costs. Energy cost volatility hits this region's temperature-controlled facilities particularly hard given 24/7 validated environment requirements. The Port of Hamburg proximity supports cross-docking operations for import pharmaceuticals entering northern European markets.
Germany Pharmaceutical Warehousing Market Competitive Landscape
Capacity expansion dominates the current landscape as operators race to capture biologics volume growth before specialized construction capacity tightens further. The market structures around three tiers: pan-European networks with GDP-certified cold-chain infrastructure, regional specialists with deep BfArM relationship histories, and mid-sized operators consolidating through facility upgrades. Strategic archetypes include temperature-control purists, serialization-integrated full-service providers, and hospital-dedicated niche operators. M&A activity and strategic partnerships represent the dominant competitive moves as capital requirements for compliant infrastructure outpace organic growth capabilities.
Within the pan-European network tier, DHL Supply Chain, GEODIS SA, and Rhenus SE and Co. KG exemplify scale-driven positioning. DHL Supply Chain represents the integrated logistics archetype with established pharma-compliant networks spanning southern German biologics corridors. GEODIS SA occupies a position emphasizing automated storage investments that reduce temperature excursion risks. Rhenus SE and Co. KG anchors the Rhine corridor specialization vector through pharma-compliant cross-docking facilities. These three operators collectively demonstrate how capital intensity and regulatory relationship depth create defensive positioning against mid-tier challengers.
| Leading Market Players |
|---|
| XPO Logistics Inc. |
| GXO Logistics |
| GEODIS SA |
| DB Schenker |
| CDS Hackner GmbH |
| Wagner Group GmbH |
| Rhenus SE and Co. KG |
| CEVA Logistics |
| DHL Supply Chain |
| Others |
Pricing and Supply Chain Analysis
Pharmacy technicians with GDP certification and cold-chain handling experience concentrated in Munich and Frankfurt labor markets create wage-cost differentials that widen pricing-tier spreads between premium validated facilities and standard ambient warehouses across Germany.
Pricing Analysis
Natural gas and electricity input-cost pass-through directly compresses margins for temperature-controlled facilities operating 24/7 validated environments. Contract-based long-term offtake dominates as hospital networks lock in multi-year agreements for CAR-T cell therapy storage. Price differentiation hinges on BfArM certification tier and geographic proximity to biologics manufacturing clusters. Pricing pressure stems from energy cost volatility hitting Bavaria cold-chain operators hardest, while generic drug distributors in eastern Germany show highest price sensitivity and university hospital networks show lowest.
Supply Chain Analysis
Reverse-logistics flows for temperature-controlled packaging returns are gaining structure as hospital networks mandate reusable shipper systems to meet CSRD carbon disclosure requirements. Active pharmaceutical ingredient supply concentrates in India, China, and Switzerland. German warehouse operators draw from specialized cold-room construction capacity concentrated in southern Germany, phase-change material suppliers in the Benelux region, and serialization hardware from Nordic vendors. Single-source vulnerability in qualified GDP-certified labor pools creates structural risk. Distribution runs through pan-European logistics networks anchored at Rotterdam port and Frankfurt air cargo hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's pharmaceutical warehousing market offers margin-expansion potential through automation-driven labor cost reduction and premium-tier positioning around EU AI Act-compliant algorithmic accountability.
For Market Incumbents: Lock in BfArM relationship depth through proactive technical file documentation for automated temperature excursion response protocols. Add ultra-low temperature capacity in Heidelberg and Freiburg biotech corridors before qualified construction capacity tightens further. Vertical integration into predictive inventory software development captures compliance-premium contracts from risk-averse biologics manufacturers facing emerging competition from digital-native logistics platforms. For New Entrants and Emerging Players: Cloud-native warehouse management system deployment routes offer lowest barrier to entry for mid-sized pharmaceutical manufacturers divesting captive assets in Baden-Württemberg. Target Saxony and Thuringia for greenfield facilities serving Berlin-Brandenburg hospital networks with lower land costs. Penetrate through ESG-mandated procurement channels by front-loading emissions-tracking platform investments. For Investors and Strategic Acquirers: Pan-European logistics networks with established pharma-compliant cold-chain infrastructure are the most active acquirer in this space, consolidating regional specialists to capture biologics volume growth. Long-term viability centers on facilities with redundant backup systems and documented BfArM audit histories. Monitor EU AI Act implementation timelines in Bavaria as early signal for algorithmic accountability compliance premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Ultra-Low Temperature Capacity Expansion | Heidelberg and Freiburg clusters pull investment into cell therapy storage infrastructure. |
| Cloud-Native WMS Platform Deployment | Saxony operators adopt fastest to attract ESG-mandated pharmaceutical procurement contracts. |
| AI Act Technical File Documentation | Bavaria vaccine distributors retrofit audit trails for algorithmic decision transparency. |
| Reusable Temperature-Controlled Packaging | Hospital networks mandate systems to meet CSRD carbon disclosure requirements. |
| Multi-Year Integrated Logistics Agreements | North Rhine-Westphalia university hospitals bundle storage, distribution, and compliance reporting. |
Research Methodology
Multiple input streams — structured interviews with cold-chain operations directors, regulatory affairs leads at BfArM-licensed facilities, and hospital procurement managers — were reconciled against secondary validation from EU GDP guidance documents, BfArM inspection reports, and pharmaceutical trade customs data. Bottom-up facility capacity modeling and top-down market sizing triangulated volume estimates. Primary fieldwork captured operational constraints in temperature-controlled construction and qualified personnel availability.
Historical capacity expansion patterns cross-referenced against panel input from logistics real estate developers and pharmaceutical manufacturer divestiture timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, technology tier, packaging format, and end-user category with regional regulatory cluster differentiation. CAGRs derived from facility investment pipelines and biologics volume growth trajectories. Forecast inputs incorporated EU AI Act implementation schedules and CSRD reporting obligation phase-ins.
Energy cost volatility, qualified construction capacity constraints, and BfArM inspection backlog delays are the dominant revision risks to warehouse capacity expansion timelines. Forecasts reflect assumptions around outsourcing acceleration rates and automation adoption curves. Practitioners should monitor natural gas futures, southern Germany contractor availability, and BfArM staffing levels for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Teriflunomide Market
Pharmaceuticals
OTC Topical Drugs Market
Pharmaceuticals
Estonia Pharmaceutical Market
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
Direct Oral Anticoagulants Market
Pharmaceuticals
Global Blood Plasma Derivatives Market
Pharmaceuticals
Plasma Protein Therapeutics Market
Pharmaceuticals
Bisphosphonates Market
Pharmaceuticals
Korea Pharmaceutical Market
Pharmaceuticals
Global Rheumatoid Arthritis Therapeutics Market
Pharmaceuticals
Global Contraceptive Drugs and Devices Market
Pharmaceuticals
Topical Corticosteroids Market
Pharmaceuticals
Anticoagulants Market
Pharmaceuticals
Endocarditis Drugs Market
Pharmaceuticals
Thin Film Drug Manufacturing Market
Pharmaceuticals
Global Viral Vaccines Market