
 Injectable Cocoa Fillings Market | 2026-2036
Injectable Cocoa Fillings Market Size, Share, and Industry Trends Forecast 2026-2036
Injectable Cocoa Fillings Market Foresight
Belgian cocoa processing capacity is hardening around specialized fat fractionation and tempering infrastructure purpose-built for pumpable filling formulations. Barry Callebaut leverages its integrated bean-to-filling pipeline to secure preferential cocoa butter access across European confectionery accounts. Puratos Group sustains formulation leadership through dedicated R&D centers in Brussels and São Paulo that focus on rheology optimization for industrial depositing lines. Cargill competes through backward integration into West African sourcing networks, ensuring traceable mass-balance cocoa for filling applications.
Injectable cocoa fillings denote pumpable, fat-continuous emulsions formulated with cocoa solids, refined vegetable fats, and emulsifiers, engineered to viscosity ranges between 5,000 and 25,000 cP for automated depositing and injection equipment in industrial bakeries and confectionery plants. Their primary commercial purpose is to deliver consistent flavor distribution, shelf stability, and clean mold release in enrobed and filled products without manual handling. Dark chocolate formulations anchor the premium tier due to higher cocoa content and clean-label positioning among artisan producers, while milk chocolate variants dominate volume in mass-market confectionery and ice cream inclusions where cost efficiency governs procurement. Flexible pouches command share in food manufacturing channels for their compatibility with pneumatic pumping systems and reduced storage footprint versus rigid tubs.
EU REACH and F-Gas Regulation constrain solvent-based extraction methods and refrigerant choices in cocoa butter processing facilities, elevating compliance costs for European suppliers while creating technical barriers for non-compliant imports. FDA food additive regulations and GRAS determinations govern lecithin and polyglycerol polyricinoleate usage levels in U.S.-destined fillings, shaping formulation recipes for multinational producers serving dual markets. BIS standards in India and evolving FSSAI labeling mandates for vegetable fat declarations in chocolate products are tightening product classification rules across Asia-Pacific export destinations. Stakeholders must monitor regulatory divergence on cocoa butter equivalence definitions and clean-label emulsifier approvals to anticipate reformulation cycles and regional sourcing reallocations.
Market Dynamics
EU F-Gas Regulation and REACH compliance are compressing processing equipment standards and ingredient sourcing protocols, forcing European manufacturers to retool extraction and tempering infrastructure while non-compliant imports face technical barriers at the border.
Growth Catalysts
- Artisan bakery channel expansion:Premium confectionery producers in Belgium and Switzerland are scaling pumpable ganache volumes for filled viennoiserie and praline applications, creating dedicated filling lines that demand consistent rheology specifications.
- REACH-compliant emulsifier approvals:ECHA authorizations for clean-label lecithin alternatives are enabling reformulation cycles that reduce additive declarations while maintaining fat-continuous emulsion stability in high-shear depositing environments.
- Industrial automation retrofit cycles:Pneumatic injection systems with viscosity-tuned pumping heads are penetrating mid-scale bakeries in France and Germany, converting manual filling operations to continuous production.
Market Restraints
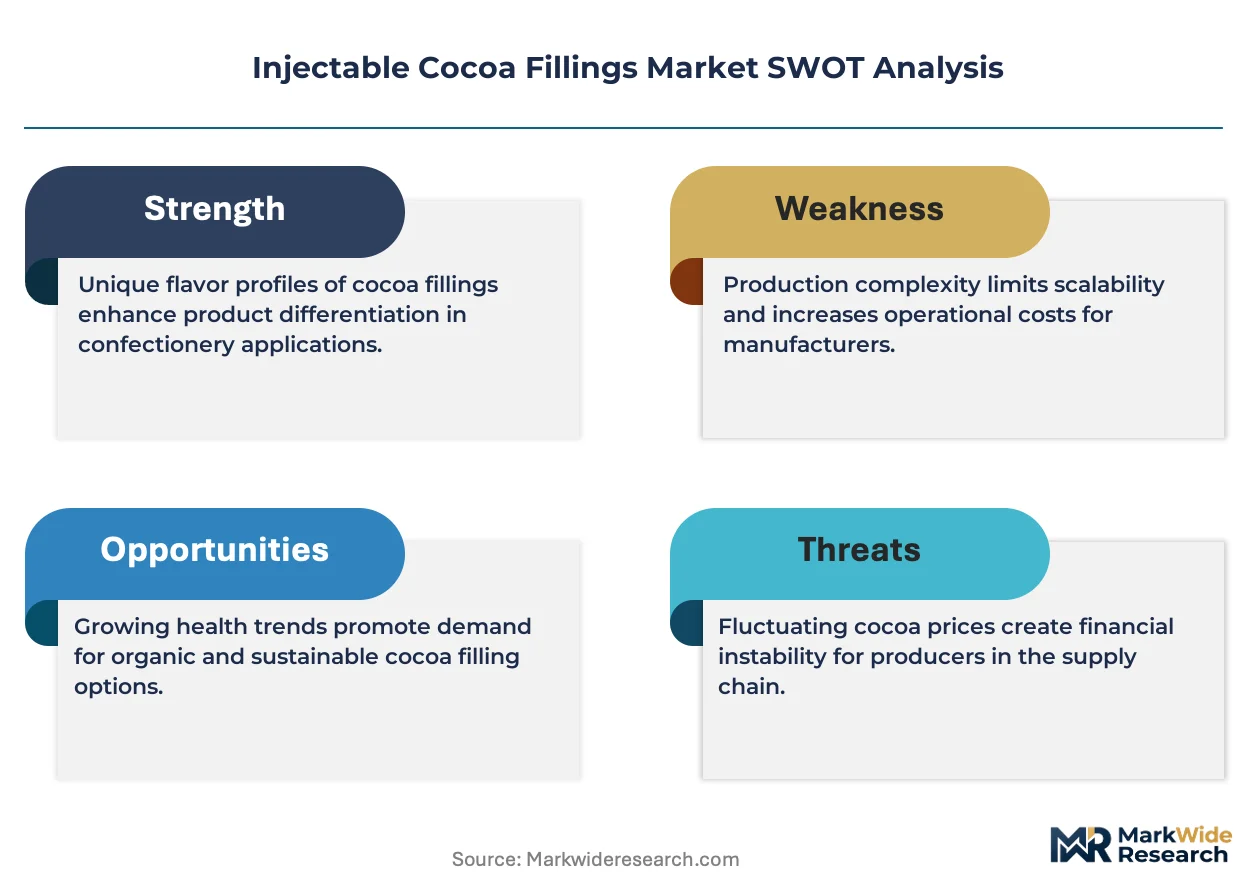
- Cocoa butter price volatility:West African supply concentration and currency fluctuations in Côte d'Ivoire and Ghana transmit directly to filling cost structures, compressing margins for processors without captive bean sourcing.
- F-Gas equipment compliance costs:Refrigerant phase-down mandates under EU Regulation 517/2014 are forcing capital-intensive chiller replacements in tempering tunnels, disadvantaging smaller European processors against integrated multinationals.
- Technical viscosity ceiling:Current pumpable formulations top out at 25,000 cP, excluding high-solids dark chocolate recipes above 70% cocoa content from automated lines without dilution or fat adjustment.
Strategic Opportunities
- Indian FSSAI labeling convergence:Evolving vegetable fat declaration mandates are creating first-mover advantage for traceable mass-balance fillings that preempt stricter chocolate product classification rules in Asia-Pacific export channels.
- Plant-based fat fractionation:Converging enzymatic interesterification and precision fermentation technologies are enabling cocoa butter equivalents with matching polymorphism for clean-label vegan praline formulations.
- Flexible pouch channel penetration:Aseptic bag-in-box formats for pneumatic systems are displacing rigid tubs in industrial bakery procurement, reducing storage footprint and enabling just-in-time inventory models.
Industry Challenges
- Rheology technician scarcity:Industrial bakeries lack personnel trained in fat crystallization kinetics and shear-rate calibration for pumpable emulsion troubleshooting on high-speed depositing lines.
- Dual-market formulation complexity:Multinational producers must maintain parallel recipes to satisfy FDA GRAS lecithin limits and EU additive ceilings, complicating production scheduling and inventory segmentation.
- Legacy tempering integration:Existing enrobing tunnels with fixed cooling curves require mechanical retrofit or software override to accommodate new filling viscosity ranges without bloom defects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injectable Cocoa Fillings Market |
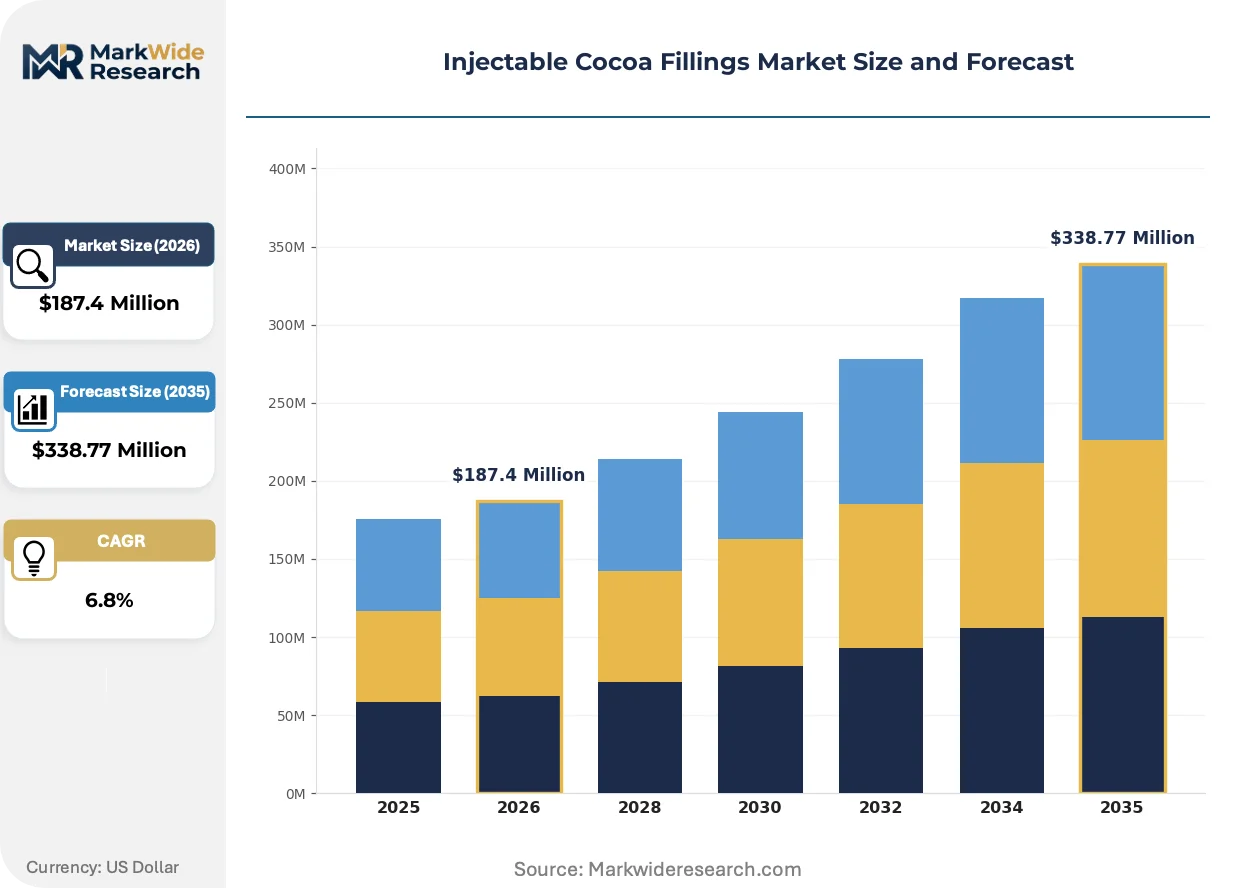
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Vegan Chocolate Application: Confectionery, Bakery, Dairy Products, Ice Cream End User: Food Manufacturers, Retailers, HORECA, Artisan Producers Packaging Type: Flexible Pouches, Tubs, Sachets, Bottles |
| Companies Covered | Puratos Group, Barry Callebaut, Cargill, Norte Eurocao, Alpezzi, Nestlé, ADM, Bunge Limited, Ghirardelli Chocolate Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injectable Cocoa Fillings Market Shifts & Advancements
Processing infrastructure and procurement protocols are converging around automation compatibility and regulatory pre-certification, compressing the gap between artisan formulation complexity and industrial throughput requirements.
Precision fat fractionation technology is unifying cocoa butter crystallization control across bean origins, enabling consistent polymorphic stability in pumpable fillings regardless of harvest variability. Artisan producers in Belgium and Switzerland are adopting these systems fastest, converting small-batch expertise into scalable recipes that industrial accounts can replicate without reformulation. This unification is compressing the traditional divide between premium positioning and mass-market volume, as identical fat-phase engineering now serves both segments.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transitions in cocoa butter pressing and tempering facilities, elevating capital requirements for compliant equipment retrofits. European processors face compressed payback periods on chiller investments as hydrofluorocarbon quotas tighten through 2030. Dark chocolate filling specialists with legacy enrobing tunnels are most exposed, as their higher melting-point requirements demand more intensive cooling capacity.
Buyer concentration among industrial bakery groups is consolidating procurement authority, displacing fragmented distributor networks with direct technical partnerships. Category managers at major frozen dough producers now specify viscosity ranges and shear stability certificates upfront, shifting supplier selection toward integrated formulators with in-house analytical capabilities. This pattern is most visible in France and Germany, where co-manufacturing relationships dominate the premium viennoiserie channel.
Injectable Cocoa Fillings Market Segmentation
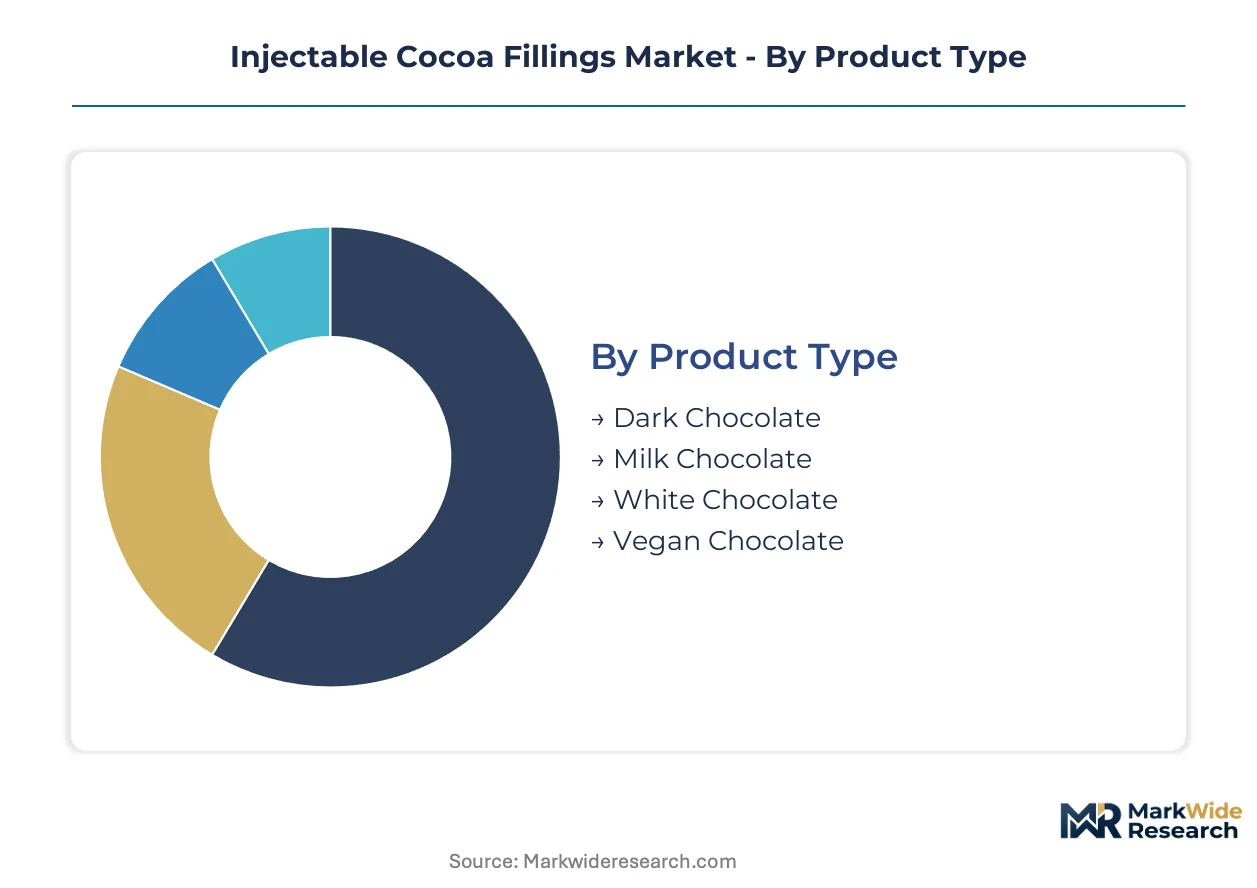
Pumpable cocoa filling procurement varies sharply by viscosity requirements, regulatory exposure, and automation compatibility across end-use channels. Segment-specific formulation expertise determines supplier selection more than commodity pricing in this technically constrained market.
Product Type:
Buyers differentiate primarily by cocoa butter content thresholds and clean-label positioning requirements in their finished goods.
- Dark Chocolate:Formulations with 50-70% cocoa solids deliver pronounced bitterness and premium positioning for artisan praline producers in Belgium. Demand concentrates among bean-to-bar confectioners seeking single-origin cocoa butter with traceable Ghana and Côte d'Ivoire sourcing.
- Milk Chocolate:Lower cocoa butter ratios and added dairy solids optimize cost efficiency for mass-market ice cream inclusion applications. European industrial bakeries in France and Germany specify this grade for high-throughput depositing lines where viscosity stability governs throughput.
- White Chocolate:Cocoa butter-dominant recipes without cocoa solids require precise tempering curves to prevent fat bloom in enrobed applications.
- Vegan Chocolate:Plant-based fat fractions from enzymatic interesterification are displacing dairy-laden alternatives in clean-label confectionery channels.
Milk chocolate leads volumes today; vegan chocolate is gaining share fastest.
Application:
Processing equipment compatibility and shelf-stability requirements create divergent procurement specifications across end-use categories.
- Confectionery:Praline and enrobed product manufacturers demand tight viscosity control between 5,000-15,000 cP for clean mold release and glossy finish. Swiss and Belgian producers anchor this segment with specialized tempering infrastructure.
- Bakery:Viennoiserie and filled pastry applications require freeze-thaw stable emulsions that resist syneresis through distribution cold chains. French industrial bakeries drive specification authority here.
- Dairy Products:Spoonable and drinkable applications need lower viscosity ranges with enhanced water-binding capacity.
- Ice Cream:Rapid crystallization resistance during freezing governs formulation design for inclusion and variegate systems.
Confectionery commands the largest revenue pool; bakery applications are climbing the fastest.
End User:
Scale of operation and technical staffing depth determine whether buyers prioritize formulation partnership or commodity pricing.
- Food Manufacturers:Multinational frozen dough and confectionery producers specify viscosity certificates and shear-stability documentation upfront. Direct technical partnerships with integrated formulators are displacing fragmented distributor networks in Germany and France.
- Retailers:Private-label program managers demand mass-balance certification and flexible packaging formats for just-in-time inventory models.
- HORECA:Hotel and restaurant chains prioritize portion-controlled sachets with extended ambient stability.
- Artisan Producers:Small-batch Belgian chocolatiers seek pumpable ganache bases that replicate hand-tempered quality without skilled labor dependency.
Food manufacturers dominate procurement volume; artisan producers are expanding most quickly.
Packaging Type:
Storage footprint constraints and pneumatic system compatibility shape format selection across manufacturing environments.
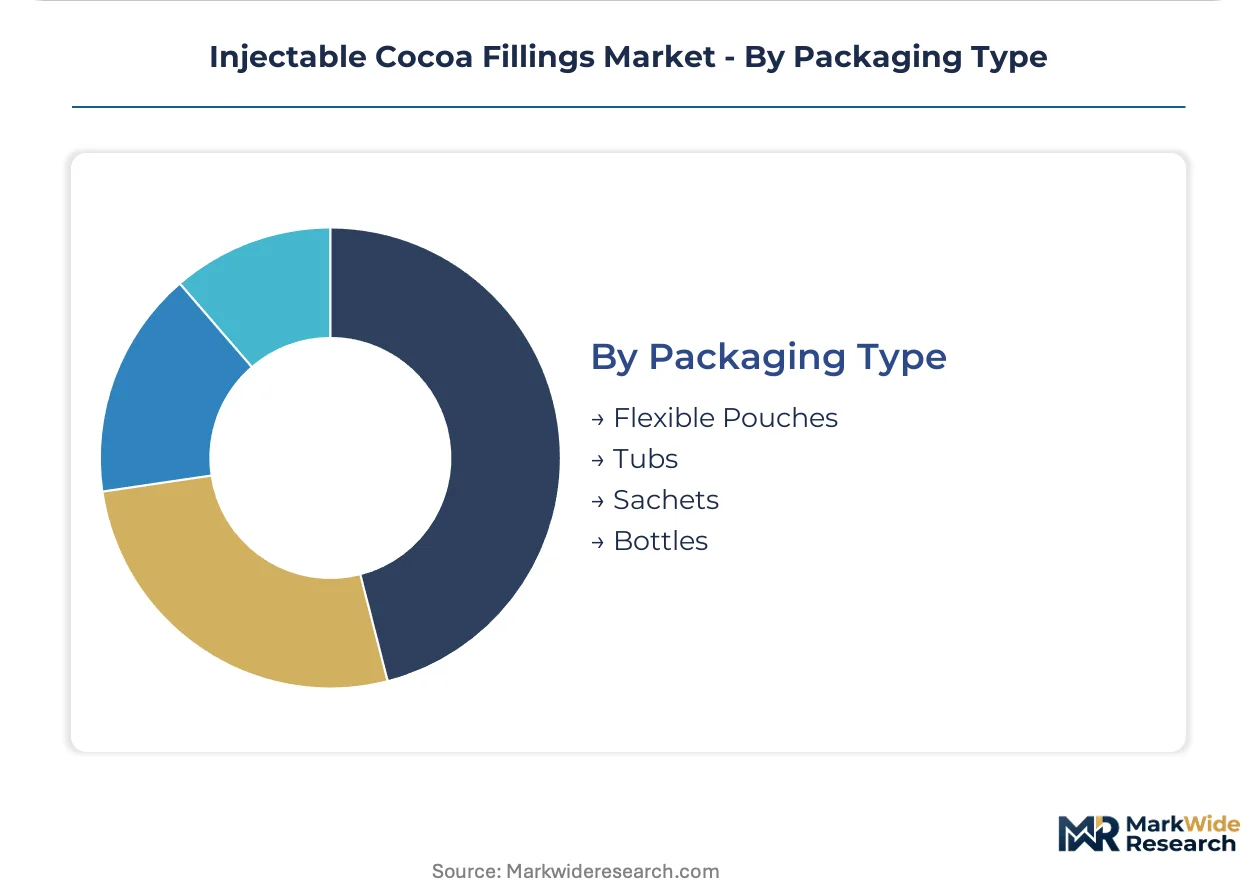
- Flexible Pouches:Aseptic bag-in-box configurations reduce warehouse space requirements by 60% versus rigid alternatives and integrate seamlessly with pneumatic pumping heads. Industrial bakery groups in France and Germany are converting procurement to this format fastest.
- Tubs:Rigid polypropylene containers retain share among artisan producers with manual handling workflows and small-batch requirements.
- Sachets:Single-serve portions serve HORECA and airline catering channels where portion control and waste reduction are paramount.
- Bottles:Squeeze formats persist in retail consumer channels and small-scale foodservice applications.
Flexible pouches lead industrial channel adoption; sachets are expanding fastest in foodservice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as EU F-Gas and REACH compliance costs widen the cost-of-compliance gap between European processors and emerging alternatives. Manufacturers without integrated bean-to-bar infrastructure face margin compression that redirects investment toward jurisdictions with lighter environmental enforcement.
Belgium
Artisan praline producers in Brussels and Ghent are scaling pumpable ganache volumes for viennoiserie applications, demanding consistent rheology specifications. EU F-Gas Regulation mandates refrigerant phase-downs through 2030, forcing capital-intensive chiller replacements in tempering tunnels. The Flanders cluster around Puratos Group and Barry Callebaut anchors Europe's densest concentration of cocoa processing expertise and industrial chocolate innovation.
Germany
Industrial bakery groups in Bavaria and North Rhine-Westphalia are converting manual filling operations to pneumatic injection systems with viscosity-tuned pumping heads. ECHA authorizations for clean-label lecithin alternatives enable reformulation cycles that reduce additive declarations. The Stuttgart-Rhine corridor hosts specialized equipment fabricators retrofitting legacy enrobing tunnels for new filling viscosity ranges.
France
Premium viennoiserie channels in Île-de-France and Auvergne-Rhône-Alpes drive specification authority for freeze-thaw stable emulsions that resist syneresis through distribution cold chains. REACH-compliant emulsifier approvals govern ingredient sourcing protocols for export-bound production. Lyon-based co-manufacturing relationships dominate procurement, displacing fragmented distributor networks with direct technical partnerships.
Switzerland
Bean-to-bar confectioners in Zurich and Geneva seek single-origin cocoa butter with traceable Ghana and Côte d'Ivoire sourcing for dark chocolate formulations. Swissmedic food safety standards and cantonal environmental regulations shape processing equipment standards. The Lake Geneva basin sustains specialized tempering infrastructure purpose-built for pumpable filling formulations with tight viscosity control.
India
Mass-balance certification demand is accelerating among exporters preparing for FSSAI labeling convergence on vegetable fat declarations in chocolate products. BIS standards and evolving national food safety mandates tighten product classification rules for Asia-Pacific destinations. Maharashtra and Gujarat industrial zones are attracting formulation partnerships that preempt stricter regulatory requirements.
Injectable Cocoa Fillings Market Competitive Landscape
Belgian producers anchor the premium formulation tier; Swiss specialists hold precision tempering expertise; American agricultural conglomerates compete through backward integration into sourcing networks. The market structure concentrates around integrated bean-to-filling pipelines that secure preferential cocoa butter access, with smaller processors disadvantaged by capital requirements for compliant equipment. Three archetypes dominate: integrated multinationals with captive sourcing, regional formulators with specialized rheology capabilities, and agricultural traders diversifying into value-added processing. Competitive moves center on direct technical partnerships with industrial bakery groups and retrofit capacity expansion for pneumatic system compatibility.
Within the integrated multinational tier, Puratos Group and Barry Callebaut exemplify archetypes combining formulation leadership with regional production density, while Cargill occupies a position representing agricultural-trader diversification into pumpable filling applications. These three entities anchor the competitive landscape through their collective presence in Belgian processing clusters and their representation of distinct strategic approaches to cocoa butter security and industrial automation alignment.
| Leading Market Players |
|---|
| Puratos Group |
| Barry Callebaut |
| Cargill |
| Norte Eurocao |
| Alpezzi |
| Nestlé |
| ADM |
| Bunge Limited |
| Ghirardelli Chocolate Company |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation refrigerant phase-down mandates gate qualified supply access and premium-tier pricing power for European processors, compressing margins for non-compliant imports while elevating capital recovery requirements for tempering tunnel retrofits in Belgium and Germany.
Pricing Analysis
Distributor margin compression in industrial bakery channels is forcing direct technical partnerships between formulators and multinational frozen dough producers. Three-tier pricing structure across premium single-origin, standard mass-balance, and economy untraceable grades separates artisan praline accounts from high-throughput viennoiserie lines. Pricing pressure stems from cocoa butter price volatility transmitted through West African supply concentration, with mass-market ice cream inclusion buyers exhibiting highest price sensitivity and Belgian bean-to-bar confectioners least.
Supply Chain Analysis
Single-source vulnerability sits with West African bean supply from Côte d'Ivoire and Ghana, where currency fluctuations and harvest variability transmit directly to European processing costs. Cocoa butter, refined vegetable fats, and clean-label emulsifiers constitute critical input dependencies. Regulatory restriction through REACH compliance and F-Gas equipment mandates poses structural supply chain risk. Distribution runs through integrated formulator direct sales to industrial bakery groups, displacing fragmented distributor networks in France and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a geographic-arbitrage play where EU compliance costs widen the cost-of-manufacturing gap against Indian and Southeast Asian alternatives preparing for FSSAI labeling convergence.
For Market Incumbents: Deploy precision fat fractionation capacity expansion in Belgian processing clusters to defend formulation leadership against plant-based CBE entrants. Deepen backward integration into traceable West African sourcing networks to secure cocoa butter preferential access. Capture artisan bakery channel expansion through dedicated rheology optimization R&D centers.
For New Entrants and Emerging Players: Launch via flexible pouch aseptic bag-in-box formats targeting mid-scale French and German industrial bakeries converting from rigid tubs. Penetrate the vegan chocolate filling white space where enzymatic interesterification technology enables clean-label praline formulations without dairy solids. Target co-manufacturing partnerships with frozen dough producers seeking freeze-thaw stable emulsion specifications.
For Investors and Strategic Acquirers: Roll-up economics work for regional formulators with specialized rheology capabilities because buyer consolidation among industrial bakery groups is consolidating procurement authority toward technical partners. Acquire mid-cap specialists with in-house analytical capabilities and pneumatic system compatibility. Watch for FSSAI vegetable fat declaration mandate enforcement as inflection signal for Asia-Pacific export channel reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into West African Sourcing | Cargill's traceable mass-balance networks secure preferential cocoa butter access for European filling accounts. |
| Precision Fat Fractionation Capacity Expansion | Barry Callebaut's integrated bean-to-filling pipeline enables consistent polymorphic stability across harvest variability. |
| Flexible Pouch Format Conversion | Puratos Group's aseptic bag-in-box configurations reduce warehouse footprint and enable just-in-time inventory models. |
| Clean-Label Emulsifier Reformulation | ECHA REACH-compliant lecithin alternatives reduce additive declarations while maintaining shear stability in depositing lines. |
| Pneumatic System Retrofit Partnerships | Stuttgart-Rhine equipment fabricators adapt legacy tempering tunnels for new viscosity ranges without bloom defects. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cocoa processing plant managers, industrial bakery procurement leads, confectionery R&D directors, and flexible packaging channel partners with secondary validation from customs trade data, FAO cocoa statistics, ECHA substance authorization databases, and SEC processor filings. Bottom-up capacity estimates and top-down demand aggregation triangulated market sizing across the analysis window.
Historical reference periods anchored volume and value projections through the forecast horizon, with segmentation modeling across product type tiers, application channels, end-user scale categories, and packaging format compatibility. CAGRs derived from elasticity-adjusted demand curves incorporating cocoa butter price volatility coefficients, automation retrofit penetration rates, and regulatory compliance cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden F-Gas quota acceleration or West African supply disruption scenarios. Projections reflect documented assumptions on emulsifier approval timelines and equipment replacement cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Packaged Salad Market
Packaged Foods
Iraq Dried Pasta Market
Packaged Foods
Wet Food Pouch Market
Packaged Foods
Global Food Spread Market
Packaged Foods
Europe Breakfast Cereals Market
Packaged Foods
US Packaged Food Market
Packaged Foods
Global Popping Candy Market
Packaged Foods
Fruit Filling Market
Packaged Foods
India Breakfast Cereals Market
Packaged Foods
Pasta and Noodles Market
Packaged Foods
Middle-East and Africa Ready-To-Eat Food Market
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
Europe Noodles and Pasta Market
Packaged Foods
Middle East and Africa Energy Bar Market
Packaged Foods
Cereal Flakes Market
Packaged Foods
Iran Breakfast Cereals Market