
 Europe Breakfast Cereals Market | 2026-2036
Europe Breakfast Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Breakfast Cereals Market Foresight
The EU Green Deal is hardening sustainability benchmarks for packaged food across Europe. PepsiCo Inc. leverages its pan-European distribution network to meet these requirements. Nestle SA anchors its portfolio reformulation around reduced-sugar commitments. Associated British Foods Plc differentiates through heritage brand positioning in the United Kingdom and Ireland.
Breakfast cereals comprise processed grain formulations—typically corn, wheat, oats, or rice—flaked, puffed, or extruded into ready-to-eat products, often fortified with vitamins and minerals for nutritional enhancement. The manufacturing process involves cooking, drying, and toasting grains at controlled moisture levels to achieve shelf-stable crispness. Muesli and granola segments capture premium margin pools as consumers prioritize clean-label ingredients. Corn flakes retain volume leadership through mass-market penetration and price accessibility. The health-conscious consumer end-user segment commands the fastest trajectory, reshaping product development priorities across manufacturers.
EFSA nutrition and health claims regulation shapes permissible front-of-pack messaging, while the EU Green Deal mandates packaging sustainability transitions. REACH compliance governs chemical safety in processing aids and food contact materials. Stakeholders must monitor evolving EFSA guidance on novel ingredient approvals and packaging recyclability thresholds to secure market access and avoid reformulation delays.
Market Dynamics
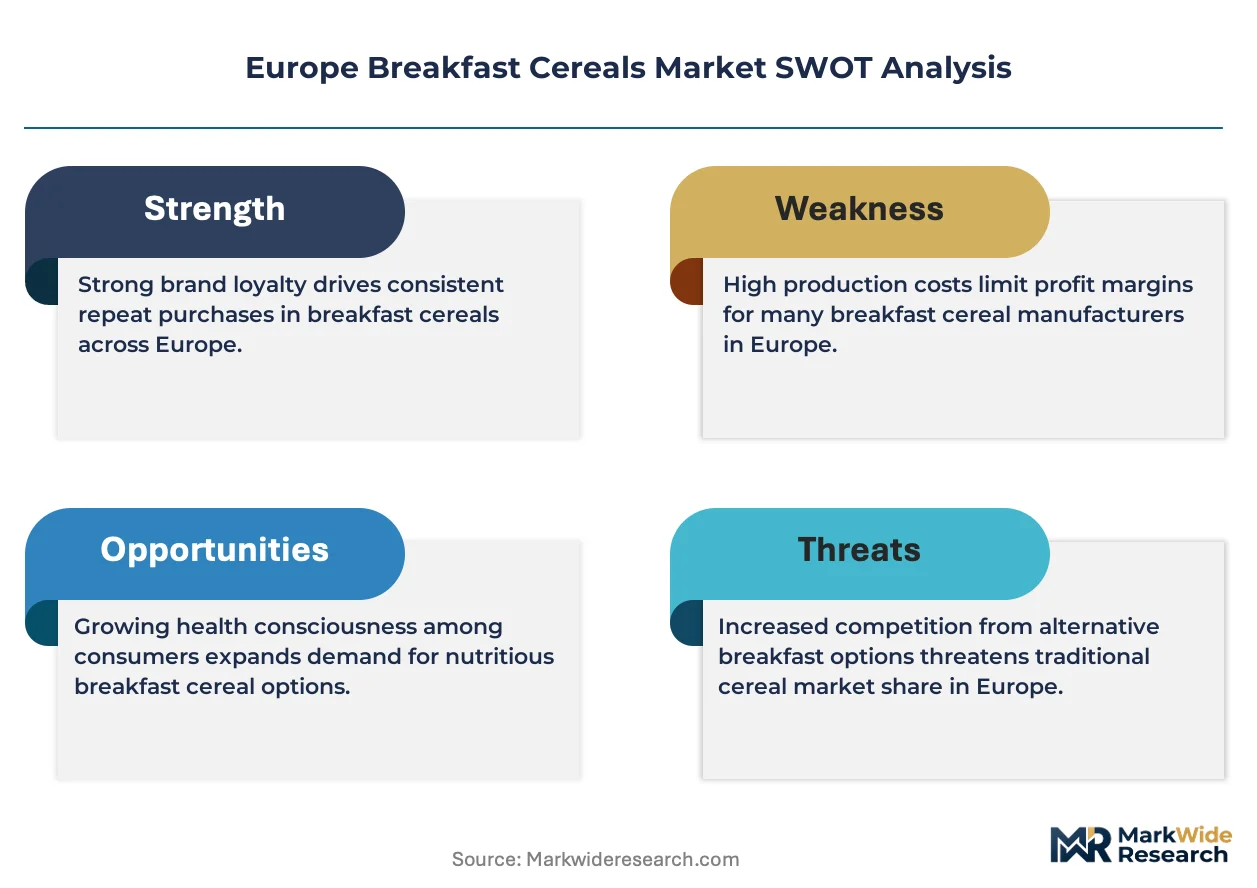
EFSA nutrition claims regulation and the EU Green Deal are compressing permissible health messaging while mandating packaging sustainability transitions, forcing simultaneous reformulation and supply chain reconfiguration across European breakfast cereal manufacturers.
Growth Catalysts
- Clean-label ingredient demand:Health-conscious adults in Germany, France, and the United Kingdom are prioritizing muesli and granola segments with transparent sourcing and minimal processing, pulling premium volume away from conventional formulations.
- EFSA novel ingredient pathway:The regulator's evolving guidance on novel ingredient approvals is opening routes for protein fortification and fiber enhancement claims that previously faced barriers.
- Fortification technology:Advanced microencapsulation methods for vitamin and mineral stability during high-temperature extrusion are expanding permissible nutrient loadings without taste degradation.
Market Restraints
- Grain input volatility:Wheat and oat price swings tied to Black Sea supply disruptions are compressing margin predictability for extruded and flaked product lines.
- REACH chemical compliance:Processing aid approvals and food contact material certifications face extended ECHA evaluation timelines, delaying new packaging introductions.
- Private-label substitution:Retailer-owned brands in the United Kingdom and Ireland are capturing price-sensitive volume through heritage-mimicking formulations at 30-40% discount tiers.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania exhibit per-capita breakfast cereal consumption gaps versus Western European benchmarks, creating white space for mass-market corn flake and puffed rice introductions.
- CSRD sustainability reporting:The Corporate Sustainability Reporting Directive is creating first-mover advantage for manufacturers with verified Scope 3 grain sourcing data and recyclable packaging credentials.
- E-commerce direct-to-consumer:Subscription-based personalized muesli blending is bypassing traditional retail slotting fee structures in Scandinavian markets.
Industry Challenges
- Extrusion engineering talent scarcity:Specialized knowledge in controlled moisture cooking and twin-screw extruder optimization is concentrating among aging technical workforces in Germany and Switzerland.
- Legacy packaging asset stranding:Multi-layer flexible film lines require capital-intensive retooling to meet EU Green Deal recyclability thresholds by mandated transition dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Breakfast Cereals Market |
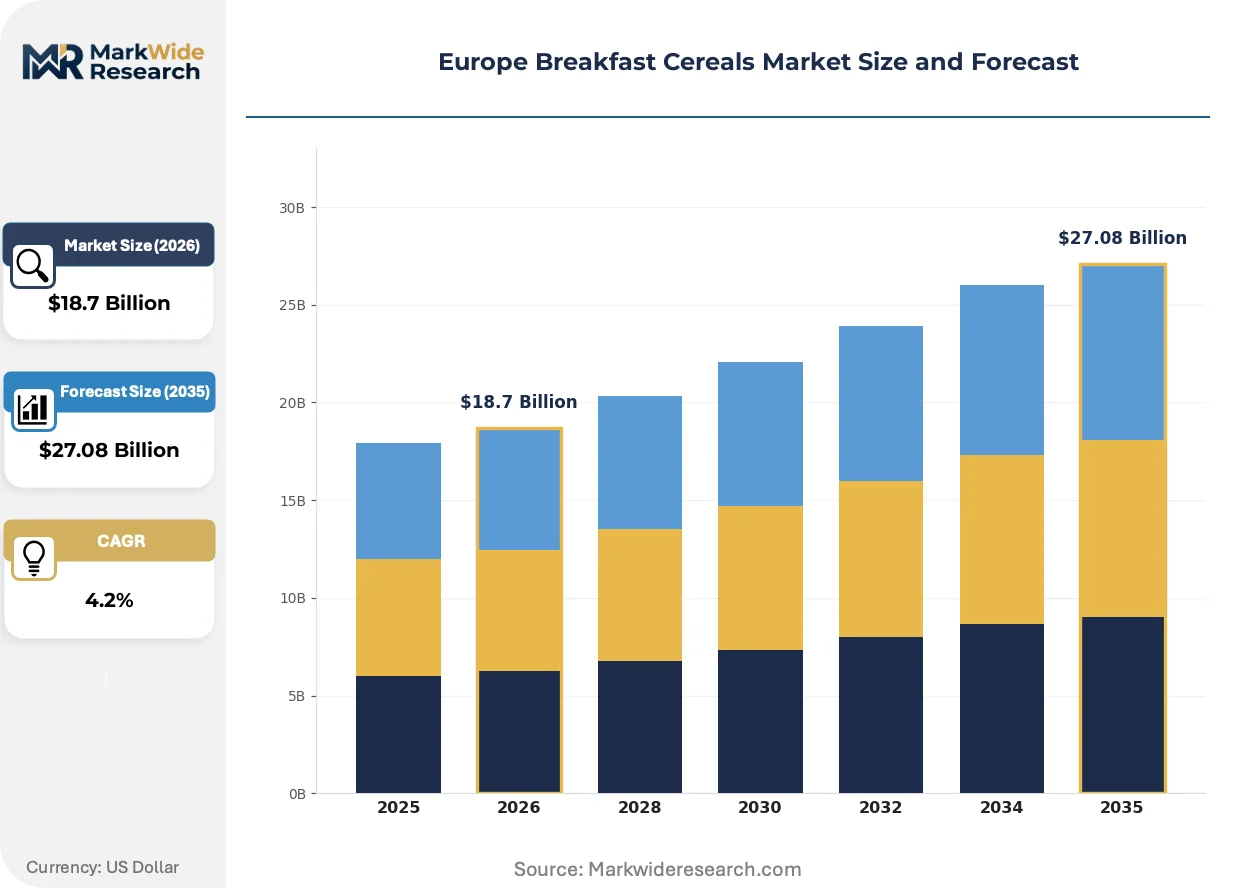
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola, Muesli, Corn Flakes, Oatmeal Customer Type: Households, Restaurants, Cafés, Supermarkets Packaging Type: Box, Bag, Cereal Bar, Bulk End User: Children, Adults, Seniors, Health-Conscious Consumers |
| Companies Covered | PepsiCo Inc., Associated British Foods Plc, Nestle SA, Cerealto Siro Foods S.L, Mars Incorporated, General Mills Inc., Post Holdings Inc., Weetabix Food Company, Kellogg Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Breakfast Cereals Market Shifts & Advancements
Processing technology, regulatory stringency, and channel fragmentation are simultaneously reshaping how breakfast cereals are formulated, certified, and reaching European consumers.
Pulse protein extrusion is absorbing significant R&D investment as manufacturers seek to displace wheat and corn bases with lentil, chickpea, and fava bean formulations that deliver complete amino acid profiles. Health-focused millennials in France and the Netherlands are driving trial adoption at rates outpacing conventional grain introductions. This ingredient shift is compressing the traditional dominance of corn flakes and puffed rice in the premium tier, forcing established brands to accelerate NPD cycles or cede shelf space.
REACH chemical safety assessments are tightening scrutiny of processing aids and food contact substances used in high-temperature extrusion and toasting operations. ECHA's expanded substance evaluation workload is extending approval timelines for novel antioxidants and release agents, forcing manufacturers to maintain legacy formulations longer than planned. Corn flake and wheat flake segments face the highest compliance burden due to their reliance on specific emulsifier systems for texture consistency.
Discounter channel expansion is fragmentizing traditional grocery dominance across Germany, Austria, and the Netherlands. Aldi and Lidl are capturing breakfast cereal volume through exclusive supplier arrangements that bypass branded manufacturer distribution networks. This channel rotation is most pronounced in standard-tier puffed and flaked products, where price elasticity exceeds brand loyalty and private-label quality perception has converged with national brands.
Europe Breakfast Cereals Market Segmentation
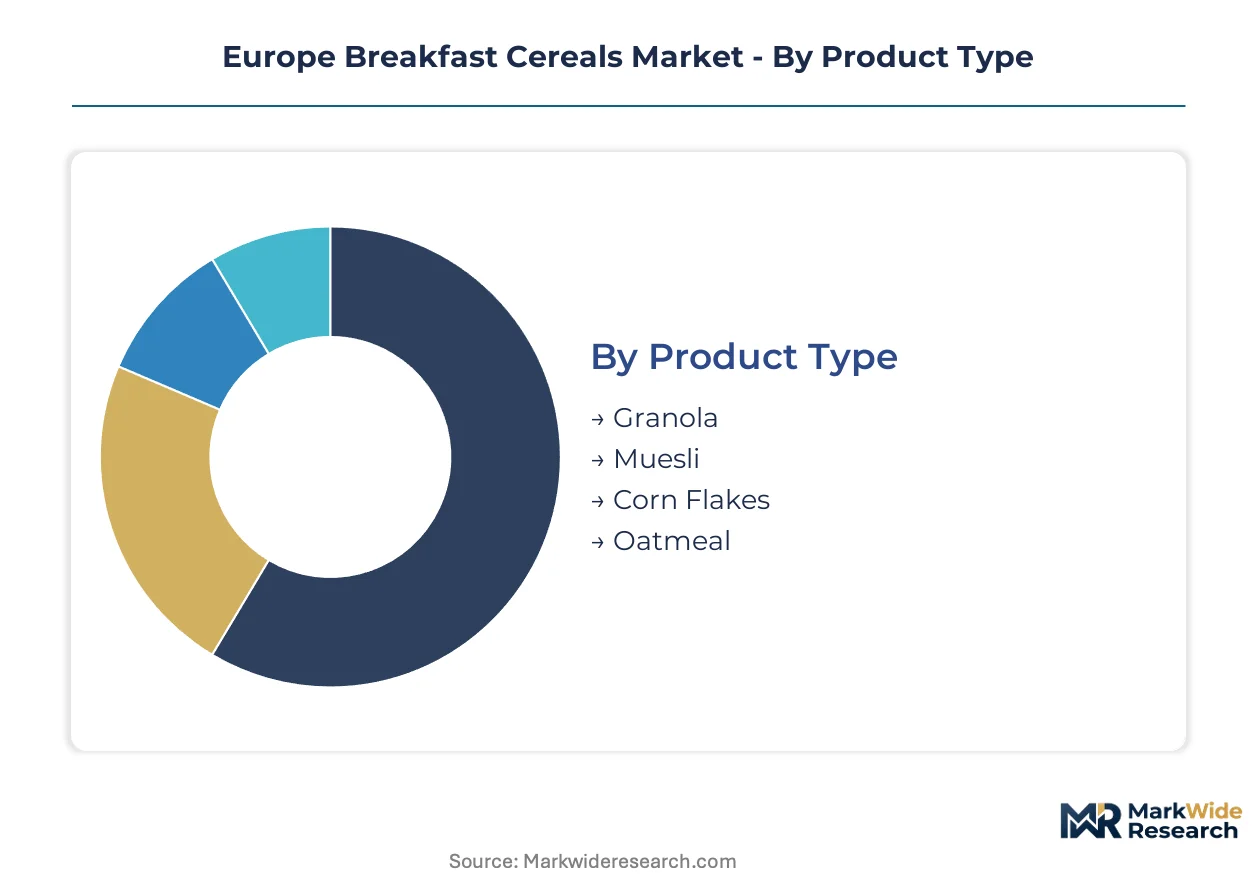
Segmentation in the Europe Breakfast Cereals Market reveals how supply-side specialization and regulatory pressure fragment manufacturing priorities across product formats and customer channels. Manufacturers must align extrusion capabilities, fortification technologies, and packaging compliance with distinct margin and volume profiles.
Product Type:
Supply concentration for grain inputs and processing equipment varies sharply across these four categories, with premium muesli and granola production clustering in Alpine-region facilities while mass-market extrusion dominates in Germany and the United Kingdom.
- Muesli:Unbaked mixtures of rolled oats, dried fruits, nuts, and seeds requiring minimal heat processing. Demand concentrates in Germany, Switzerland, and Austria where heritage brands command shelf space, though EFSA sugar-reduction targets are forcing reformulation of fruit-inclusion ratios.
- Granola:Baked oat clusters bound with sweeteners and oils, produced through rotary oven or fluidized bed roasting. French and Dutch health-conscious millennials are pulling volume fastest, displacing conventional puffed cereals in urban premium retail.
- Corn Flakes:Extruded and toasted corn grit formulations processed through high-pressure flaking mills. Mass-market penetration in the United Kingdom and Ireland sustains volume leadership despite margin compression from private-label substitution.
- Oatmeal:Rolled, steel-cut, or instant oat formats requiring hydrothermal stabilization before milling. Scottish and Nordic sourcing corridors dominate supply, with EFSA fiber claims supporting repositioning toward cholesterol-management positioning.
Today's leader: Corn Flakes. Tomorrow's challenger: Granola.
Customer Type:
Channel cost structures and procurement scale separate these four customer categories, with supermarkets and households driving divergent packaging and formulation requirements.
- Households:Individual and family-sized purchases through retail and e-commerce channels. German and French consumers prioritize clean-label ingredients, pulling manufacturers toward shorter ingredient lists and recyclable box formats under EU Green Deal mandates.
- Restaurants:Foodservice bulk procurement for breakfast buffet and à la carte applications. United Kingdom hospitality recovery is stabilizing demand for individually portioned sachets and ambient-stable muesli dispensers.
- Cafés:Specialty coffee shop and bakery chains sourcing premium granola and muesli for parfait and bowl applications. Scandinavian urban markets show fastest adoption of branded single-serve pouches.
- Supermarkets:Hypermarket and grocery chains controlling slotting fees and private-label development. Aldi and Lidl in Germany and Austria are capturing volume through exclusive supplier arrangements that bypass branded distribution networks.
Households anchor current revenue. Supermarkets are gaining procurement leverage fastest.
Packaging Type:
EU Green Deal recyclability thresholds and EFSA label visibility rules are forcing capital reallocation across these four formats, with flexible film retooling costs stranding legacy assets.
- Box:Paperboard cartons with inner liner bags, standard for flaked and puffed cereals. United Kingdom retailers are demanding FSC-certified board and mono-material liners to meet CSRD reporting requirements.
- Bag:Flexible stand-up pouches for muesli and granola, offering shelf differentiation and resealability. REACH compliance for multi-layer films is extending ECHA evaluation timelines for new sustainable material introductions.
- Cereal Bar:Individually wrapped on-the-go formats, requiring moisture barrier and structural rigidity. German convenience channel expansion is pulling investment toward flow-wrap and thermoform lines.
- Bulk:Large-format bags and totes for foodservice and ingredient supply. French and Italian industrial bakeries are sourcing oat and muesli bases for in-house granola production.
Box formats dominate volume. Bag formats face the steepest sustainability transition costs.
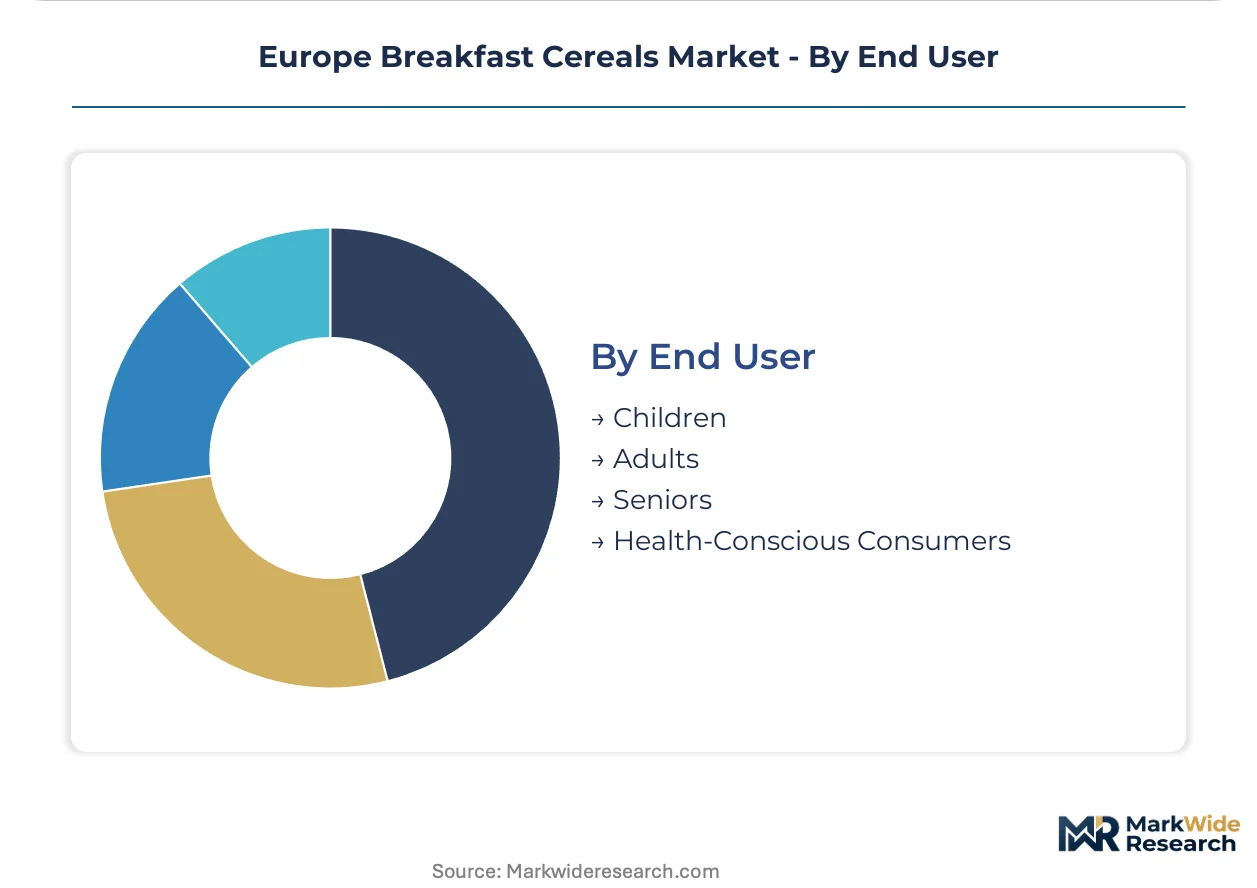
End User:
Demographic targeting determines fortification loadings, sweetness levels, and health claim strategies, with regulatory scrutiny varying by vulnerable population designations.
- Children:Vitamin-fortified, lower-fiber formulations with controlled sugar levels per EFSA nutrition claims regulation. United Kingdom advertising restrictions are compressing television and digital marketing reach.
- Adults:Balanced macronutrient profiles supporting convenience and satiety. German working-age consumers are shifting toward protein-fortified muesli for post-exercise consumption.
- Seniors:High-fiber, softer-texture options addressing chewing difficulty and digestive health. French and Italian aging populations are driving demand for prebiotic oat formulations.
- Health-Conscious Consumers:Clean-label, organic, and functional ingredient seekers prioritizing minimal processing. Netherlands and Belgium lead per-capita adoption of sprouted grain and pulse-protein cereals.
Adults represent the largest addressable base. Health-Conscious Consumers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Breakfast cereal manufacturing took root in Switzerland and Germany during the late nineteenth century, with muesli invented in Zurich and industrial flaking developed along the Rhine. European production corridors now stretch from the Alpine arc through the North European Plain.
Germany
Health-conscious adults in Bavaria and North Rhine-Westphalia are shifting toward protein-fortified muesli for post-exercise consumption. The EU Green Deal mandates FSC-certified board and mono-material liners for retail packaging. Cologne and Hamburg anchor extrusion engineering clusters where twin-screw equipment optimization knowledge concentrates among aging technical workforces.
United Kingdom
Heritage brand positioning commands shelf space in London and the Midlands, though private-label substitution at Aldi and Lidl captures price-sensitive volume. EFSA nutrition claims regulation compresses permissible health messaging on packaging. Manchester and Liverpool host legacy multi-layer flexible film lines requiring capital-intensive retooling for recyclability compliance.
France
Health-focused millennials in Paris and Lyon are driving trial adoption of pulse-protein cereals at rates outpacing conventional grain introductions. REACH chemical safety assessments extend ECHA evaluation timelines for novel antioxidants in high-temperature extrusion. The Auvergne-Rhône-Alpes region clusters rotary oven facilities for granola production serving urban premium retail.
Netherlands
Clean-label ingredient seekers in Amsterdam and Rotterdam lead per-capita adoption of sprouted grain formulations. CSRD sustainability reporting creates first-mover advantage for manufacturers with verified Scope 3 grain sourcing data. Subscription-based personalized muesli blending is bypassing traditional retail slotting fee structures in Scandinavian-adjacent markets.
Poland
Per-capita breakfast cereal consumption gaps versus Western European benchmarks create white space for mass-market corn flake introductions. EFSA novel ingredient pathway guidance opens routes for fiber enhancement claims previously facing barriers. Warsaw and Krakow are absorbing German extrusion technology transfer as Eastern European manufacturing capacity expands.
Europe Breakfast Cereals Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and distribution reach. The vendor base concentrates among multinational packaged food conglomerates with pan-European logistics networks and mid-sized regional specialists with heritage brand equity. Three archetypes dominate: diversified nutrition giants with reformulation capabilities, private-label manufacturers serving discounter channels, and artisanal muesli specialists with direct-to-consumer subscription models. Competitive moves center on portfolio diversification into pulse-protein formats and backward integration into certified sustainable grain sourcing.
Within the diversified nutrition tier, Nestle SA and PepsiCo Inc. exemplify scale-driven reformulation strategies, while Associated British Foods Plc anchors heritage positioning in the United Kingdom and Ireland. These three occupy positions across the premium-to-standard spectrum, with each representing distinct responses to EFSA sugar-reduction targets and EU Green Deal packaging mandates.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| Associated British Foods Plc |
| Nestle SA |
| Cerealto Siro Foods S.L |
| Mars Incorporated |
| General Mills Inc. |
| Post Holdings Inc. |
| Weetabix Food Company |
| Kellogg Co. |
| Others |
Supply & Pricing Matrix
Pulse protein extrusion technology is simultaneously elevating R&D cost structures and concentrating production expertise in Alpine-region facilities, compressing margin pools for manufacturers lacking twin-screw optimization capabilities while rewarding first movers with premium positioning leverage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates heritage muesli brands from private-label discounter offerings and mass-market corn flake staples. Price differentiation rests on clean-label certification status and EFSA-permitted health claim density, with organic and pulse-protein formulations commanding shelf-space premiums. Pricing pressure stems from Aldi and Lidl exclusive supplier arrangements in Germany and Austria that bypass branded distribution networks. Households in France and the Netherlands show lowest price sensitivity, while United Kingdom mass-market consumers exhibit highest elasticity.
Supply Chain Analysis
Extrusion engineering talent scarcity in Germany and Switzerland is tethering advanced production capacity to aging technical workforces nearing retirement. Grain supply concentrates in Black Sea corridors for wheat, Scottish Highlands for oats, and Alpine regions for heritage muesli inputs. Raw material dependencies include corn grits for flaking, rolled oats for muesli, and pulse proteins for fortification. Single-source vulnerability runs through Black Sea wheat corridors disrupted by geopolitical instability. Distribution runs through pan-European logistics networks anchored by PepsiCo and Nestle, with direct-to-consumer subscription channels fragmenting Scandinavian retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe breakfast cereals market operates as a regulatory compounder where EFSA sugar-reduction targets and EU Green Deal packaging mandates are accelerating premium-tier demand for compliant formulations.
For Market Incumbents: Cement defensible positioning through backward integration into certified sustainable grain sourcing corridors and captive production of mono-material packaging compliant with CSRD reporting requirements. Private-label substitution in the United Kingdom and Ireland threatens heritage brand volume; counter through exclusive retailer partnerships locking shelf space for reformulated reduced-sugar lines. For New Entrants and Emerging Players: Subscription-based personalized muesli blending offers a digital-channel route bypassing traditional retail slotting fee structures in Netherlands and Scandinavian markets. Target Poland and Romania for mass-market corn flake introductions where per-capita consumption gaps versus Western benchmarks create immediate white space. Lead with pulse-protein fortification claims enabled by EFSA novel ingredient pathway guidance. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized regional specialists with heritage brand equity but limited extrusion engineering depth. Long-term viability favors manufacturers with verified Scope 3 grain sourcing data and recyclable packaging credentials positioned for CSRD first-mover advantage. Watch ECHA evaluation timeline extensions for novel antioxidants as signal of compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Pulse Protein Formulation Launch | Displaces wheat and corn bases with lentil and chickpea extrusion meeting EFSA amino acid claim standards. |
| Mono-Material Packaging Transition | Retools multi-layer flexible film lines to meet EU Green Deal recyclability thresholds and CSRD reporting. |
| Eastern European Distribution Expansion | Establishes mass-market penetration in Poland and Romania through German extrusion technology transfer. |
| Direct-to-Consumer Subscription Platform | Bypasses Aldi and Lidl exclusive supplier arrangements with personalized muesli blending in Scandinavian markets. |
| Backward Integration into Certified Grain Sourcing | Captures Scope 3 verification for Scottish oat and Alpine heritage muesli supply corridors. |
Research Methodology
Direct dialogue with brand managers, category buyers at Aldi and Lidl, extrusion engineering directors, and EFSA regulatory affairs specialists grounded the qualitative foundation. Secondary validation drew from EFSA novel ingredient approval databases, ECHA REACH substance evaluations, Nielsen retail audit data for European breakfast cereal channels, and customs records for grain input trade flows. Bottom-up volume modeling triangulated against top-down macroeconomic consumption benchmarks.
Bottom-up segment modeling tracked muesli, granola, corn flakes, and oatmeal across household, restaurant, café, and supermarket channels, with packaging format and end-user demographic overlays. CAGRs derived from regression analysis against EFSA regulatory milestone implementation schedules and EU Green Deal compliance deadlines. Forecast inputs included Black Sea wheat price volatility indices and ECHA evaluation timeline projections for processing aid approvals.
The model assumes a particular technology adoption path; alternative pathways for pulse protein extrusion scale-up would alter the outlook if consumer trial rates in France and Netherlands decelerate. Forecasts reflect assumptions about EFSA guidance stability and REACH compliance cost trajectories. Material deviation in ECHA evaluation timelines or Black Sea grain corridor access warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
United Kingdom Food Spreads Market
Packaged Foods
Packaged Rice Market
Packaged Foods
Eco Bowls Market
Packaged Foods
Global Food Spread Market
Packaged Foods
Fat Free Pasta Market
Packaged Foods
Peanut Butter Market
Packaged Foods
Burritos Market
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market
Packaged Foods
Morning Goods Market
Packaged Foods
Reduced Salt Packaged Foods Market
Packaged Foods
On-The-Go Breakfast Cereals Market
Packaged Foods
Pre-Packaged Sandwich Market
Packaged Foods
Breakfast Food Market
Packaged Foods
Rice Noodles Market
Packaged Foods
Injectable Cocoa Fillings Market
Packaged Foods
Global Oven Bags Market