
 Fruit Filling Market | 2026-2036
Fruit Filling Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Filling Market Foresight
Artisan bakeries and premium dessert manufacturers is bifurcating demand away from mass-market retail channels as buyers prioritize clean-label formulations and customizable viscosity profiles. Puratos Group leverages its global R&D network to develop enzyme-stabilized fruit preparations that extend shelf life without artificial preservatives. Dawn Food Products anchors North American supply through controlled distribution to regional bakery chains. AGRANA Beteiligungs-AG dominates European fruit sourcing with backward integration into orchards across Austria and Hungary.
Fruit filling denotes a viscous preparation comprising fruit pulp, sugar, pectin, and acidulants, typically standardized to 65-72°Brix soluble solids content, manufactured through vacuum concentration or aseptic processing for thermal stability in downstream baking and dairy applications. Jam and compote categories lead volume due to their versatility across bakery and dairy applications, while blueberry and apple varieties capture accelerating demand from functional snack manufacturers seeking antioxidant positioning. The confectionery application segment sustains premium margin pools through specialized low-moisture fillings requiring precise water activity control below 0.85.
FDA standards for standardized fruit preserves under 21 CFR 150 govern identity and fill requirements in the United States, while EFSA and EU Regulation 1169/2011 mandate front-of-pack nutritional labeling that pressures sugar reduction across formulations. BIS certification requirements for processed fruit products in India create market access barriers for imported fillings lacking local laboratory verification. Stakeholders must monitor evolving clean-label definitions and sugar taxation schemes as these frameworks increasingly determine procurement eligibility and product reformulation priorities.
Market Dynamics
Clean-label reformulation pressure from EU Green Deal mandates is forcing fruit filling suppliers to eliminate artificial preservatives while maintaining 65-72°Brix stability standards for industrial bakery customers.
Growth Catalysts
- EU Green Deal sustainable sourcing mandates:Procurement eligibility now requires verified fruit origin documentation and sugar reduction pathways, accelerating supplier certification investments.
- Enzyme stabilization technology:Industrial bakeries adopt enzyme-based shelf-life extension to replace chemical preservatives without compromising thermal stability in downstream processing.
- Bavaria and North Rhine-Westphalia bakery clusters:Concentrated demand from German industrial bakeries and confectionery manufacturers anchors volume procurement for high-viscosity preparations.
Market Restraints
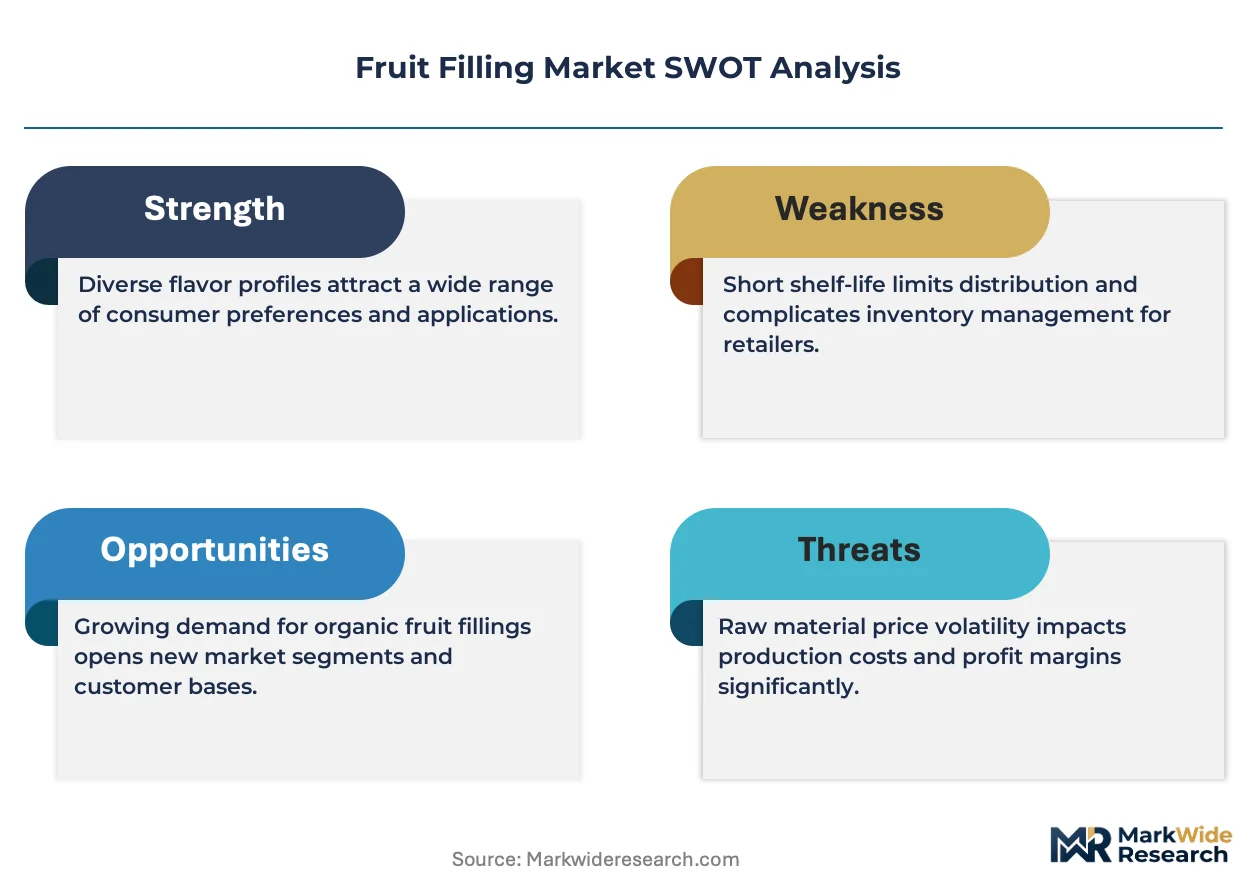
- Input cost volatility in pectin and acidulants:Citrus-derived pectin supply fluctuations create margin compression for standardized fruit preparation manufacturers.
- Supply concentration in Austrian and Hungarian orchards:Backward-integrated European suppliers control premium fruit sourcing, limiting new entrant access to verified origin raw materials.
- Technical limitation in low-moisture confectionery fillings:Precise water activity control below 0.85 requires specialized equipment that smaller producers cannot access.
Strategic Opportunities
- Underpenetrated functional snack segment:Blueberry and apple varieties with antioxidant positioning capture emerging demand from health-focused snack manufacturers seeking clean-label fruit inclusions.
- BIS certification pathway in India:Local laboratory verification requirements create first-mover advantage for suppliers establishing in-house testing capabilities ahead of import competitors.
- EU Regulation 1169/2011 front-of-pack labeling:Sugar taxation schemes and nutritional transparency mandates favor suppliers with existing reduced-sugar formulation portfolios.
Industry Challenges
- Reformulation timeline compression:FDA 21 CFR 150 identity standards and evolving EFSA clean-label definitions require simultaneous multi-jurisdiction compliance engineering.
- Legacy thermal processing integration:Aseptic processing upgrades for enzyme-stabilized systems demand capital deployment that mid-scale producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Filling Market |
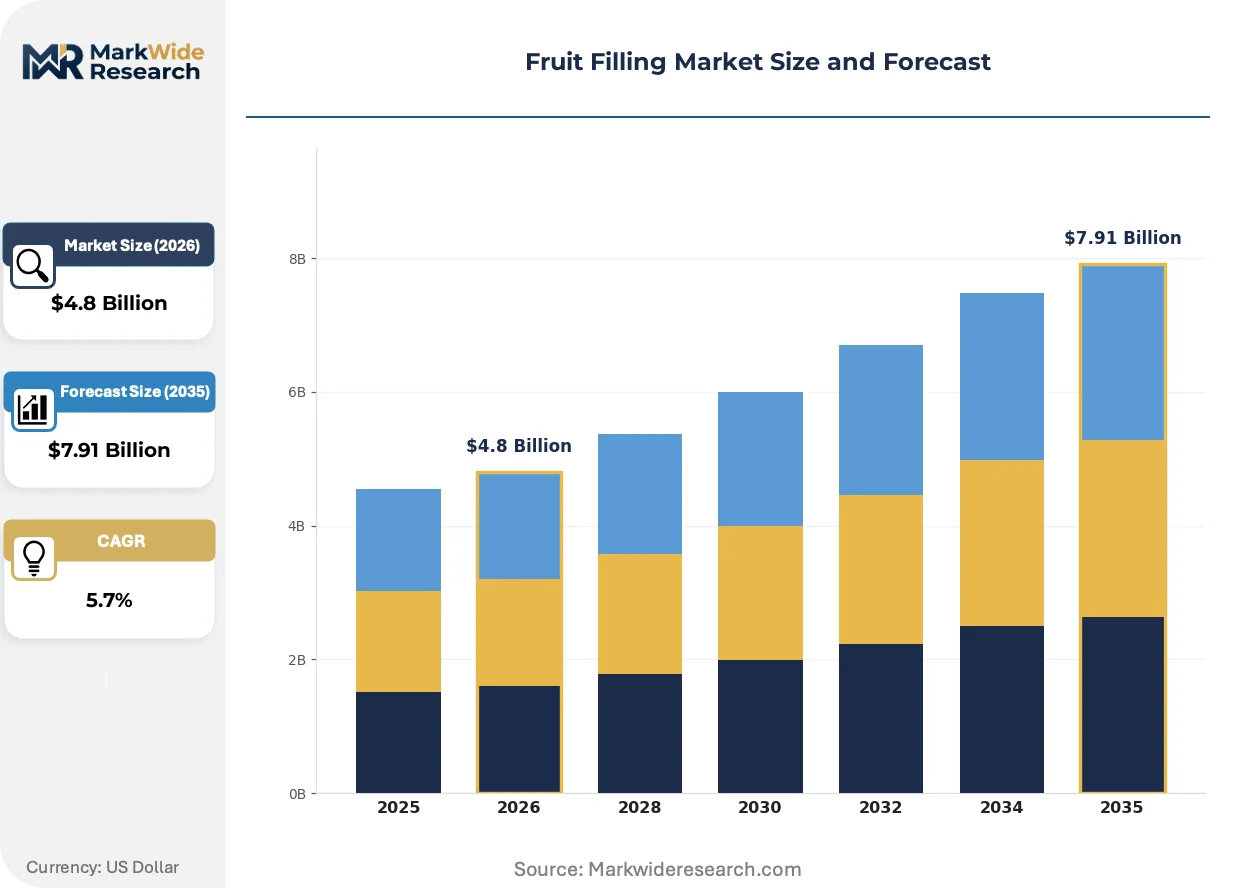
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jam, Jelly, Preserves, Compote, Marmalade Fruit Variety: Strawberry, Blueberry, Apple, Peach, Cherry, Apricot Application: Bakery, Confectionery, Dairy Products, Beverages, Snacks End User: Bakeries, Food & Beverage Manufacturers, Catering Services, Retailers |
| Companies Covered | Puratos Group, Dawn Food Products, AGRANA Beteiligungs-AG, The Barry Callebaut Group, Bakels Worldwide, Zentis GmbH & Co. KG, CSM Ingredients, Lyons Magnus, Baldwin Richardson Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Filling Market Shifts & Advancements
Active reformulation across preservative chemistry, regulatory compliance architecture, and procurement relationship structures is compressing traditional supplier-buyer contracting cycles.
Enzyme-stabilized fruit preparations are supplanting benzoate and sorbate preservation systems in premium dessert manufacturing. Artisan bakeries and clean-label-focused industrial buyers accelerate adoption timelines from pilot to volume procurement within single contract cycles. This substitution is compressing preservative supplier margins while elevating enzyme technology licensors and toll processors.
EU Green Deal sustainable sourcing mandates are reshaping supplier qualification protocols. Verified fruit origin documentation and carbon footprint disclosure requirements now precede price negotiation in German and French procurement processes. Industrial bakery clusters in Bavaria prioritize suppliers with orchard-level traceability systems already operational.
Direct procurement relationships between fruit filling manufacturers and regional bakery chains are displacing traditional distributor intermediaries in North American supply. Dawn Food Products anchors this channel compression through controlled distribution networks serving mid-scale bakery operations. This disintermediation concentrates volume commitments with fewer supplier relationships and extends payment term pressure upstream.
Fruit Filling Market Segmentation
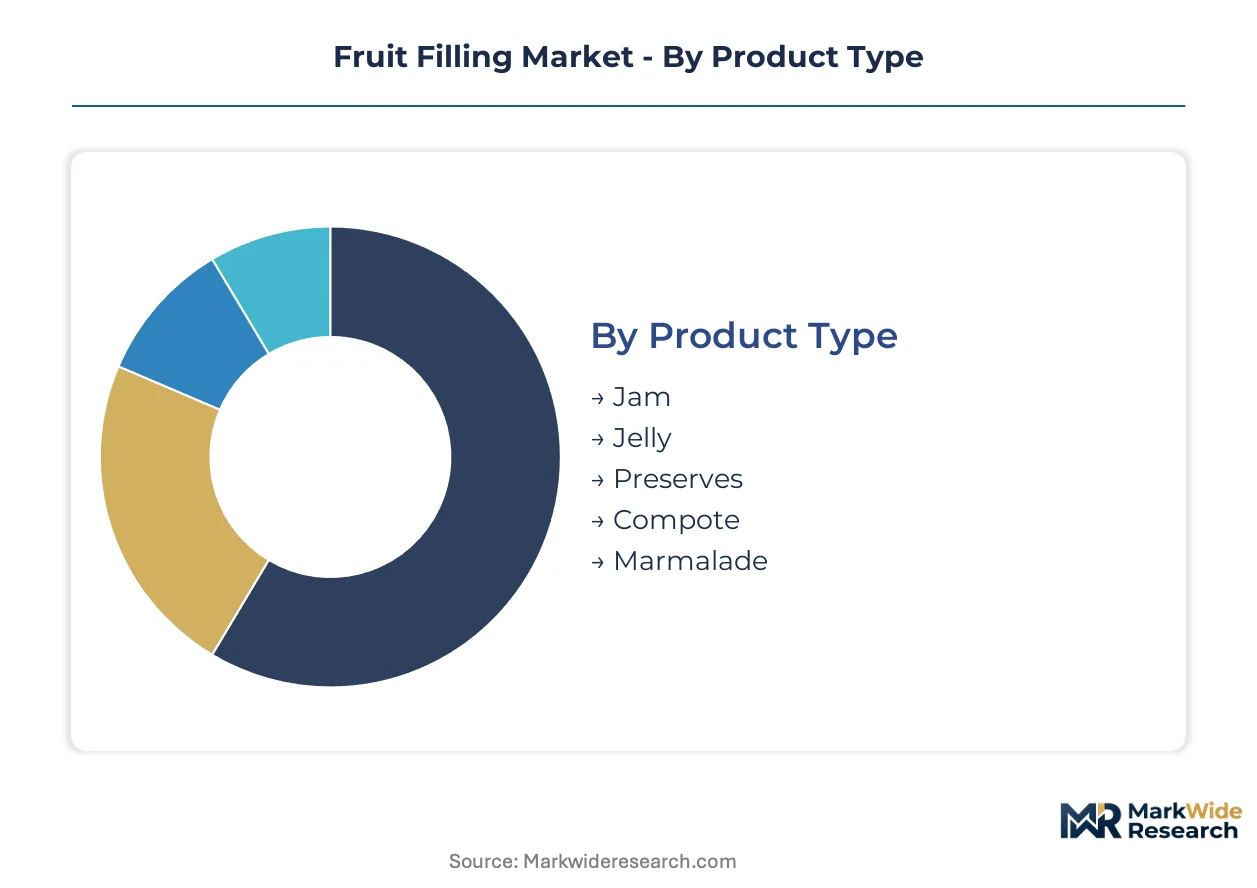
Fruit filling procurement channels diverge sharply by viscosity specification and shelf-life requirements. Industrial bakeries negotiate long-term contracts for standardized high-Brix preparations, while artisan buyers source smaller batches with customizable texture profiles.
Product Type:
Channel mix varies by water activity and preservation chemistry. Jam and compote flow through broad distribution to industrial bakeries, while marmalade and premium preserves concentrate in specialty foodservice and retail channels.
- Jam:A viscous preparation of crushed fruit and sugar standardized to 65-70°Brix, stabilized with pectin gelling networks. German industrial bakeries in Bavaria anchor procurement volumes for laminated pastry applications, driven by clean-label reformulation mandates from EU Green Deal procurement protocols.
- Compote:Chunky fruit preparation with reduced sugar content and higher fruit integrity, typically 45-55°Brix. Demand concentrates in French and Italian premium dessert manufacturing, where artisan producers prioritize recognizable ingredient lists over extended shelf stability.
- Jelly:Clear, strained fruit juice gel with uniform texture and no fruit particulates.
- Preserves:Whole fruit or large fruit pieces suspended in thick syrup, commanding premium positioning in specialty retail.
- Marmalade:Citrus-based preparation incorporating peel fragments, concentrated in UK and Mediterranean breakfast applications.
Jam dominates installed base. Compote is where expansion concentrates.
Fruit Variety:
Raw material sourcing geography dictates cost tier and supply security. Temperate-climate fruits from established European orchards command premium pricing, while berry varieties face seasonal volatility and antioxidant-driven demand spikes.
- Strawberry:The most widely procured filling variety, characterized by bright color stability and balanced acid-sugar profiles. Industrial bakery chains across Germany and Poland standardize procurement specifications around Polish and Spanish strawberry concentrates, constrained by EU Green Deal traceability documentation requirements.
- Blueberry:Anthocyanin-rich preparation with functional positioning in health-conscious snack applications. North American procurement from Maine and British Columbia operations is expanding most quickly as antioxidant claims drive reformulation in granola and nutrition bar segments.
- Apple:Cost-stable, high-yield variety with versatile acidity adjustment for multiple applications.
- Peach:Stone fruit preparation concentrated in Mediterranean dairy and dessert applications.
- Cherry:Tart and sweet varieties segmented by end-use, with sour cherry dominating Central European bakery traditions.
- Apricot:Premium positioning in Viennese pastry and Middle Eastern confectionery traditions.
Strawberry holds the largest volume position. Blueberry is climbing the fastest.
Application:
Margin structure varies by thermal processing requirements and formulation complexity. Bakery applications tolerate higher water activity, while confectionery demands precise moisture control that elevates technical barriers.
- Bakery:The foundational application segment encompassing laminated pastries, filled cookies, and cake layers. German and Austrian industrial bakeries specify high-viscosity, thermally stable preparations for automated depositing equipment, with procurement eligibility increasingly tied to reduced-sugar formulation capabilities.
- Confectionery:Specialized low-moisture fillings requiring water activity below 0.85 for shelf-stable chocolate and candy applications. Belgian and Swiss manufacturers concentrate demand here, constrained by capital-intensive processing equipment that limits supplier participation.
- Dairy Products:Fruit preparations for yogurt and ice cream inclusions, requiring controlled syneresis and freeze-thaw stability.
- Beverages:Pumpable fruit bases for smoothies and flavored drinks, emphasizing dispersibility over gel strength.
- Snacks:Emerging category for fruit inclusions in bars, cereals, and baked snacks, with clean-label positioning as primary specification driver.
Bakery commands the broadest supplier base. Confectionery holds the steepest expansion trajectory.
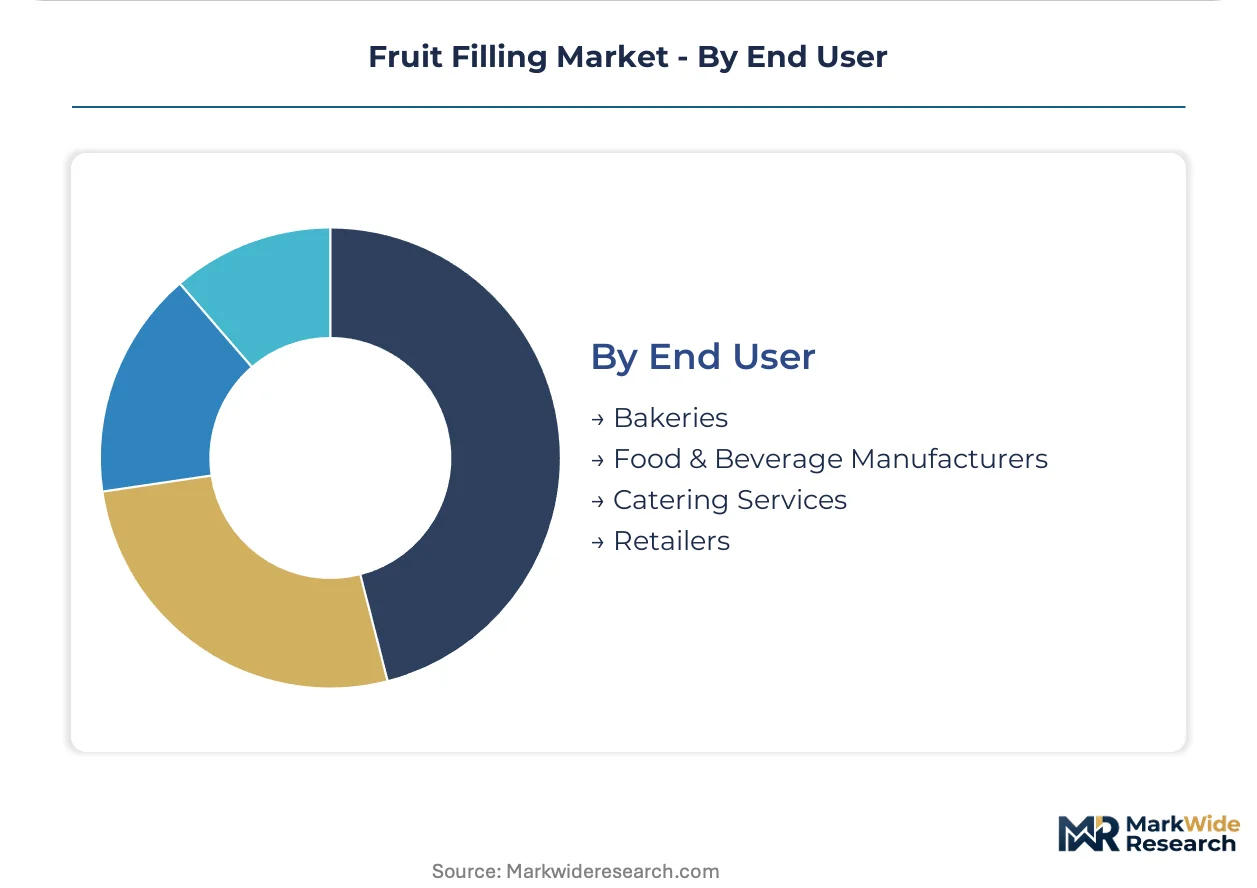
End User:
Customer scale determines contract structure and technical service intensity. Large-scale food manufacturers negotiate formula co-development agreements, while smaller buyers purchase from standardized catalogs.
- Bakeries:Spanning artisan single-location operations to multinational industrial chains. German bakery clusters in North Rhine-Westphalia consolidate procurement through group purchasing organizations, extracting volume pricing and dedicated R&D support from filling suppliers.
- Food & Beverage Manufacturers:Integrated producers with in-house product development capabilities, often requiring custom viscosity and flavor modulation for proprietary formulations.
- Catering Services:Foodservice distributors purchasing institutional-size formats with emphasis on portion control and labor reduction.
- Retailers:Private-label program operators specifying store-brand fruit fillings for bakery counters and packaged goods.
Bakeries represent the deepest established demand. Food & Beverage Manufacturers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial bakery clusters and confectionery manufacturers concentrate procurement in Germany, while artisan producers across France and Italy prioritize clean-label formulations. North American demand flows through controlled distribution networks serving regional bakery chains.
Germany
Bavaria and North Rhine-Westphalia anchor European procurement volumes for high-viscosity fruit preparations. EU Green Deal sustainable sourcing mandates pressure suppliers to document verified fruit origins and reduce sugar content. Industrial bakeries in Munich and Cologne consolidate purchasing through group organizations, extracting dedicated R&D support from filling manufacturers.
United States
Regional bakery chains and premium dessert manufacturers drive clean-label adoption timelines from pilot to volume procurement. FDA standards under 21 CFR 150 govern identity and fill requirements for standardized fruit preserves. Dawn Food Products anchors supply through controlled distribution networks concentrated in Midwest and Northeast manufacturing corridors.
France
Artisan producers and premium dessert manufacturers prioritize recognizable ingredient lists over extended shelf stability. EFSA and EU Regulation 1169/2011 mandate front-of-pack nutritional labeling that accelerates sugar reduction across formulations. Paris and Lyon-based confectionery specialists concentrate demand for low-moisture fillings requiring precise water activity control.
Italy
Premium dessert manufacturing clusters in Emilia-Romagna and Lombardy specify high-fruit-integrity compotes with reduced sugar profiles. EU Green Deal procurement protocols increasingly tie supplier eligibility to carbon footprint disclosure and orchard-level traceability systems. Verona and Bologna anchor specialty marmalade production for Mediterranean breakfast applications.
India
Processed fruit product manufacturers face BIS certification requirements creating market access barriers for imported fillings lacking local laboratory verification. FSSAI regulations govern food safety standards while import substitution policies favor domestic production capacity. Maharashtra and Gujarat industrial zones concentrate emerging demand from bakery and dairy processing facilities.
Fruit Filling Market Competitive Landscape
Player mix skews toward backward-integrated European orchard operators and North American controlled-distribution specialists. The vendor base separates into three tiers: multinational ingredient conglomerates with global R&D networks, regional specialists with captive fruit sourcing, and toll processors serving private-label programs. Two dominant competitive moves are reshaping positioning: direct procurement relationships displacing distributor intermediaries, and enzyme stabilization technology licensing replacing chemical preservative systems.
Among European orchard-integrated suppliers, AGRANA Beteiligungs-AG and Zentis GmbH & Co. KG exemplify the backward-integration archetype with upstream control over Austrian and Hungarian fruit sourcing. Puratos Group represents the technology-licensing tier, leveraging enzyme-stabilized preparation development to extend shelf life without artificial preservatives. These three entities occupy distinct competitive positions—captive raw material security, formulation technology leadership, and regional procurement consolidation—each defending margin through non-replicable capability depth rather than price competition alone.
| Leading Market Players |
|---|
| Puratos Group |
| Dawn Food Products |
| AGRANA Beteiligungs-AG |
| The Barry Callebaut Group |
| Bakels Worldwide |
| Zentis GmbH & Co. KG |
| CSM Ingredients |
| Lyons Magnus |
| Baldwin Richardson Foods |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day fruit concentrate inventory cycles in European industrial bakeries concentrate purchasing power with backward-integrated suppliers while compressing margins for toll-dependent processors. This lead-time band tightens during harvest windows, amplifying price volatility for pectin and acidulant inputs that determine formulation cost structures.
Pricing Analysis
Enzyme-stabilized preparation technology commands premium positioning over legacy benzoate-sorbate systems, while commodity jam formulations face persistent cost compression. Three-tier pricing structure across premium clean-label, standard industrial, and economy private-label levels stratifies by certification depth and orchard traceability documentation. Pricing pressure stems from EU Green Deal sugar reduction mandates that force reformulation investments without corresponding price recovery mechanisms. Industrial bakery chains in Germany exhibit highest price sensitivity due to consolidated group purchasing organization leverage, while artisan producers in France accept premium tiers for recognizable ingredient positioning.
Supply Chain Analysis
Container availability constraints on Black Sea-to-Rotterdam lanes elevate inbound logistics costs for citrus-derived pectin sourced from Mediterranean processors. Raw material security draws from Austrian and Hungarian orchard clusters for temperate fruits, Polish and Spanish strawberry concentrates, and North American blueberry anthocyanin extracts. Single-source vulnerability concentrates in AGRANA's captive Hungarian fruit supply, creating procurement risk for competing manufacturers lacking backward integration. Distribution runs through direct manufacturer-to-bakery relationships displacing traditional foodservice distributors, with Dawn Food Products anchoring controlled networks across Midwest and Northeast US manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label enzyme stabilization technology sits at early-cycle penetration with artisan bakeries accelerating adoption timelines from pilot to volume procurement within single contract cycles, indicating substantial runway before saturation.
For Market Incumbents: Fortify orchard-level traceability systems in Austrian and Hungarian sourcing regions to defend against EU Green Deal procurement eligibility requirements. Deepen captive pectin supply through backward integration into citrus processing to offset input cost volatility that threatens standardized preparation margins.
For New Entrants and Emerging Players: Lead with BIS certification pathway establishment in India, where local laboratory verification requirements create first-mover advantage ahead of import-dependent competitors. Target functional snack manufacturers seeking antioxidant-positioned blueberry inclusions, leveraging clean-label positioning as primary specification wedge against established bakery-focused suppliers.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational ingredient conglomerates seeking to divest non-core fruit preparation divisions lacking enzyme technology capabilities. Monitor enzyme stabilization patent filing velocity as inflection indicator for technology-licensing revenue potential in premium dessert manufacturing segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Operations | Captive Austrian and Hungarian fruit supply secures EU Green Deal traceability compliance ahead of procurement eligibility deadlines. |
| Enzyme Stabilization Technology Licensing | Puratos Group's R&D network extends shelf life without artificial preservatives, displacing benzoate-dependent competitors in premium channels. |
| Direct Distribution Network Expansion | Dawn Food Products' controlled Midwest and Northeast coverage compresses channel margins while locking in regional bakery chain volume commitments. |
| BIS Certification Infrastructure Investment | Local Indian laboratory capabilities overcome import substitution barriers that exclude unverified foreign filling suppliers from Maharashtra and Gujarat demand. |
| Reduced-Sugar Formulation Portfolio Development | Pre-positioned reduced-Brix preparations capture EU Regulation 1169/2011 front-of-pack labeling advantages as sugar taxation schemes expand across member states. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with procurement directors at German industrial bakery clusters, R&D leads at enzyme technology licensors, and regulatory affairs specialists navigating FDA 21 CFR 150 and EU Regulation 1169/2011 compliance; and secondary validation through customs records for fruit concentrate trade flows, SEC filings of publicly traded ingredient suppliers, and EFSA guidance document repositories. Bottom-up volume modeling from application-specific demand segments triangulated against top-down market sizing from trade association production statistics.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product viscosity specification, fruit variety sourcing geography, application thermal processing requirements, and end-user scale archetype. CAGRs were derived from regression analysis of historical procurement volume trends against regulatory mandate implementation schedules and technology substitution curves. Forecast inputs incorporated EU Green Deal sustainable sourcing compliance timelines and enzyme stabilization adoption rates in artisan bakery pilot programs.
The analysis sits within stated boundaries; outcomes outside sustained clean-label premiumization and regulatory enforcement consistency would require recalibration. Forecasts reflect documented assumptions regarding pectin supply stability, orchard yield predictability in Central European growing regions, and enforcement intensity of BIS certification requirements in Indian processed food markets. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Non-Fried Instant Noodles Market
Packaged Foods
Packaged Zhug Market
Packaged Foods
Fat Free Pasta Market
Packaged Foods
Canned Goods Market
Packaged Foods
Breakfast Food Market
Packaged Foods
Air-Dried Food Market
Packaged Foods
North America Ready-To-Eat Food Market
Packaged Foods
Pasta and Noodles Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
Cocoa Fillings Market
Packaged Foods
Hummus Market
Packaged Foods
Low Calorie Noodles Market
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
Club Store Packs Market
Packaged Foods
Middle East and Africa Energy Bar Market