
 Iraq Dried Pasta Market | 2026-2036
Iraq Dried Pasta Market Size, Share, and Industry Trends Forecast 2026-2036
Iraq Dried Pasta Market Intelligence
Premium durum wheat pasta is decoupling from commodity-grade flour-based alternatives across Iraqi retail channels. Al-Khazraji Group for Food Industries leverages backward integration into local milling operations to control input costs. Al-Sardar Group for Food Industries sustains brand recognition through heritage positioning in Baghdad's traditional souks. Al-Hayat Company for Pasta and Food Industries differentiates via fortified product lines aligned with national nutrition programs.
Dried pasta comprises durum wheat semolina extruded through bronze or Teflon dies, then dehydrated to below twelve percent moisture for shelf stability and rehydration performance. Spaghetti dominates household purchasing across Iraqi governorates due to cultural familiarity and versatile preparation methods. Macaroni and penne segments capture expanding restaurant demand, particularly among quick-service operators in Najaf and Karbala seeking faster plate turnaround. Vacuum-sealed packaging formats are gaining traction among institutional buyers prioritizing extended storage in climate-variable distribution environments.
Iraq's Central Organization for Standardization and Quality Control enforces wheat product specifications that manufacturers must satisfy for domestic market access. The country's national food fortification framework, administered through the Ministry of Health and Environment, mandates micronutrient enrichment in mass-market pasta categories. Wholesale distribution channels remain subject to municipal trade licensing requirements that vary across Baghdad, Basra, and Erbil jurisdictions. Stakeholders must monitor evolving import tariff structures on durum wheat and semolina, as these directly determine competitive positioning between domestic extruders and regional suppliers.
Market Dynamics
Baghdad and Basra households are accelerating purchases of convenient meal formats. The Iraqi Ministry of Health's fortification mandates are forcing manufacturers to reformulate wheat-based products. Restaurant procurement in southern governorates is concentrating demand for bulk-format spaghetti and penne.
Growth Catalysts
- Nutrition Policy Mandates:The Ministry of Health and Environment's national food fortification framework requires micronutrient enrichment in mass-market pasta categories. Domestic extruders gain compliance advantage over regional suppliers.
- Urban Household Expansion:Baghdad and Basra residents are expanding consumption of shelf-stable convenient meal formats. Dual-income households prioritize rehydration speed and storage efficiency.
- Food Service Procurement:Quick-service operators in Najaf and Karbala are concentrating demand for faster plate-turnaround pasta shapes. Bulk-format spaghetti and penne capture expanding restaurant volume.
Market Restraints
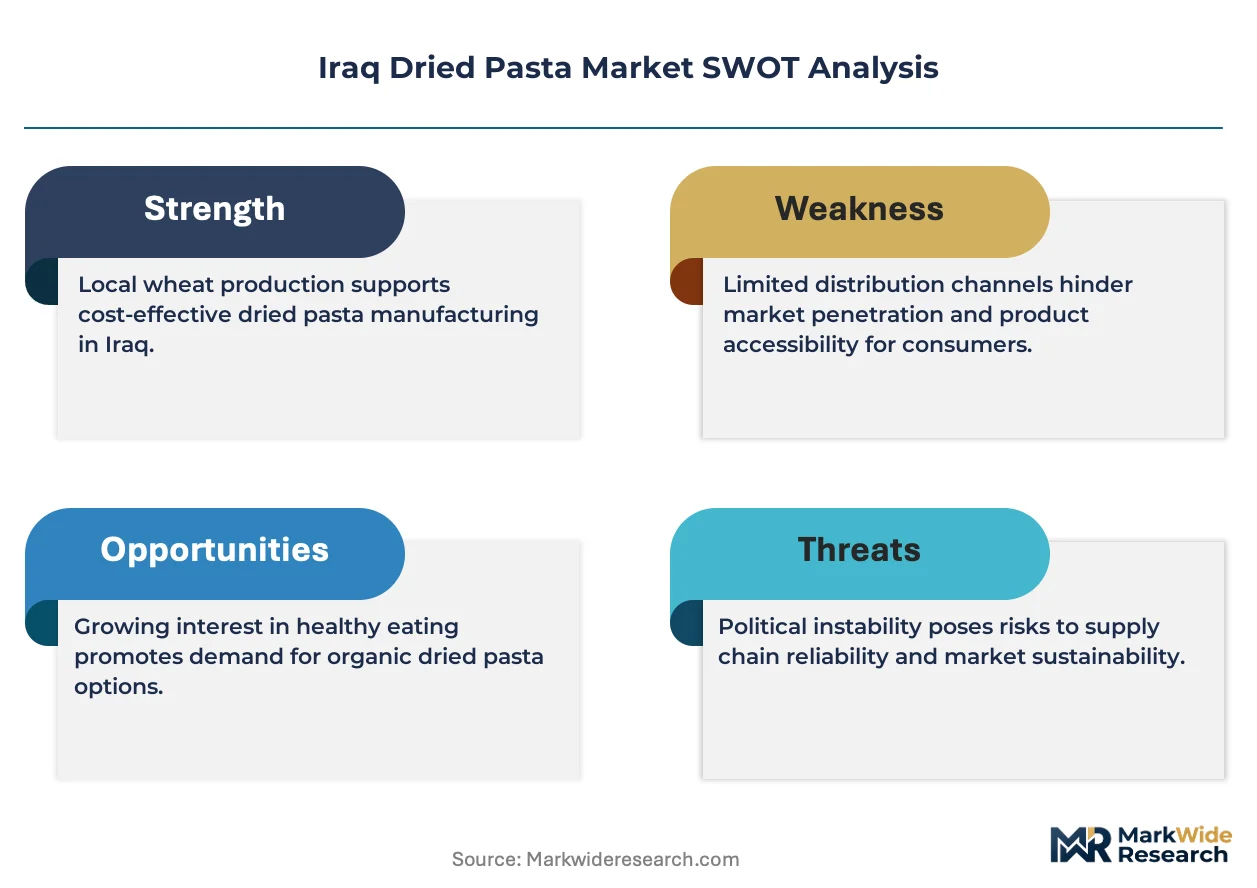
- Durum Wheat Import Dependency:Iraq's domestic milling capacity cannot satisfy semolina demand. Tariff volatility on imported durum wheat compresses margin predictability for extruders.
- Climate-Variable Distribution:Vacuum-sealed packaging requirements add cost layers for institutional buyers. Extended storage needs in southern governorates strain working capital cycles.
- Commodity-Grade Competition:Flour-based pasta alternatives trade at significant discounts to durum semolina products. Price-sensitive households in rural governorates substitute downward during cost spikes.
Strategic Opportunities
- Southern Governorate Expansion:Najaf and Karbala food service channels remain underpenetrated by fortified product lines. Aligned manufacturers capture procurement contracts from religious tourism operators.
- Bronze Die Positioning:Premium texture differentiation via traditional extrusion equipment is displacing Teflon-die commodity output. Heritage positioning commands shelf space in Baghdad's traditional souks.
- Institutional Channel Development:Municipal trade licensing variations across Baghdad, Basra, and Erbil create whitespace for compliant distributors. Wholesale consolidation favors licensed operators with multi-jurisdiction permits.
Industry Challenges
- Formulation Compliance Timelines:Central Organization for Standardization and Quality Control wheat product specifications require recertification cycles. Manufacturers face delays bringing reformulated fortified lines to market.
- Multi-Jurisdiction Licensing Complexity:Municipal trade licensing requirements vary across Baghdad, Basra, and Erbil. Distribution networks must maintain separate compliance documentation for each governorate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iraq Dried Pasta Market |
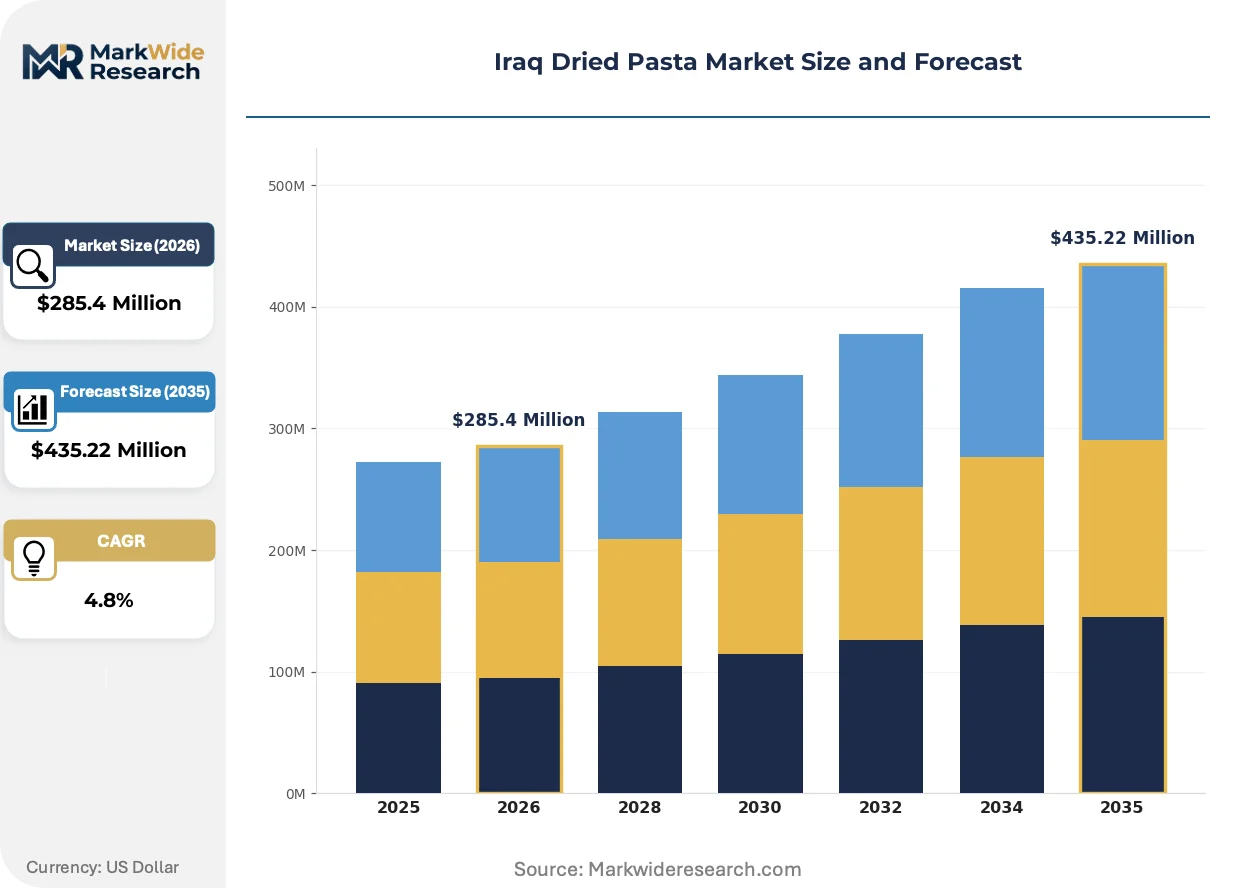
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spaghetti, Macaroni, Penne, Fettuccine Distribution Channel: Supermarkets, Grocery Stores, Online Retail, Wholesale End User: Households, Restaurants, Food Service, Institutions Packaging Type: Plastic Bags, Cardboard Boxes, Bulk Packaging, Vacuum Sealed |
| Companies Covered | Al-Khazraji Group for Food Industries, Al-Sardar Group for Food Industries, Al-Hayat Company for Pasta and Food Industries, Al-Sharq Group for Pasta and Food Industries, Al-Khateeb Group for Pasta and Food Industries, Al-Asala Group for Pasta, Al-Tahhan Group for Food Industries, DAS Food Industries, Al-Zaidi Group for Pasta and Food Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iraq Dried Pasta Market Strategic Shifts & Innovations
Bronze die extrusion and vacuum-sealed packaging formats are reshaping competitive positioning across Iraqi retail and institutional channels. Fortification compliance is becoming a baseline rather than differentiator.
Bronze die extrusion technology produces rougher pasta surfaces that absorb sauce more effectively than Teflon-die alternatives. Baghdad's traditional souk retailers and heritage-positioned manufacturers are adopting this equipment at accelerating rates. The technology is decentralizing texture-based premium positioning away from imported Italian brands toward domestic producers with backward-integrated milling operations.
The Iraqi Ministry of Health and Environment's national food fortification framework mandates iron, folic acid, and B-vitamin enrichment in wheat-based products. Domestic extruders must reformulate semolina blends and submit updated specifications to the Central Organization for Standardization and Quality Control. Mass-market spaghetti and macaroni segments face the steepest compliance timelines, with manufacturers prioritizing fortified line conversions over premium shape introductions.
Food service buyers in Najaf and Karbala are consolidating procurement around quick-turnover pasta shapes that reduce kitchen labor minutes. Quick-service operators are displacing traditional family-style restaurants in pilgrimage corridor locations. This concentration is most visible in religious tourism zones where plate-speed directly correlates with table turnover and revenue per square meter.
Iraq Dried Pasta Market Segmentation
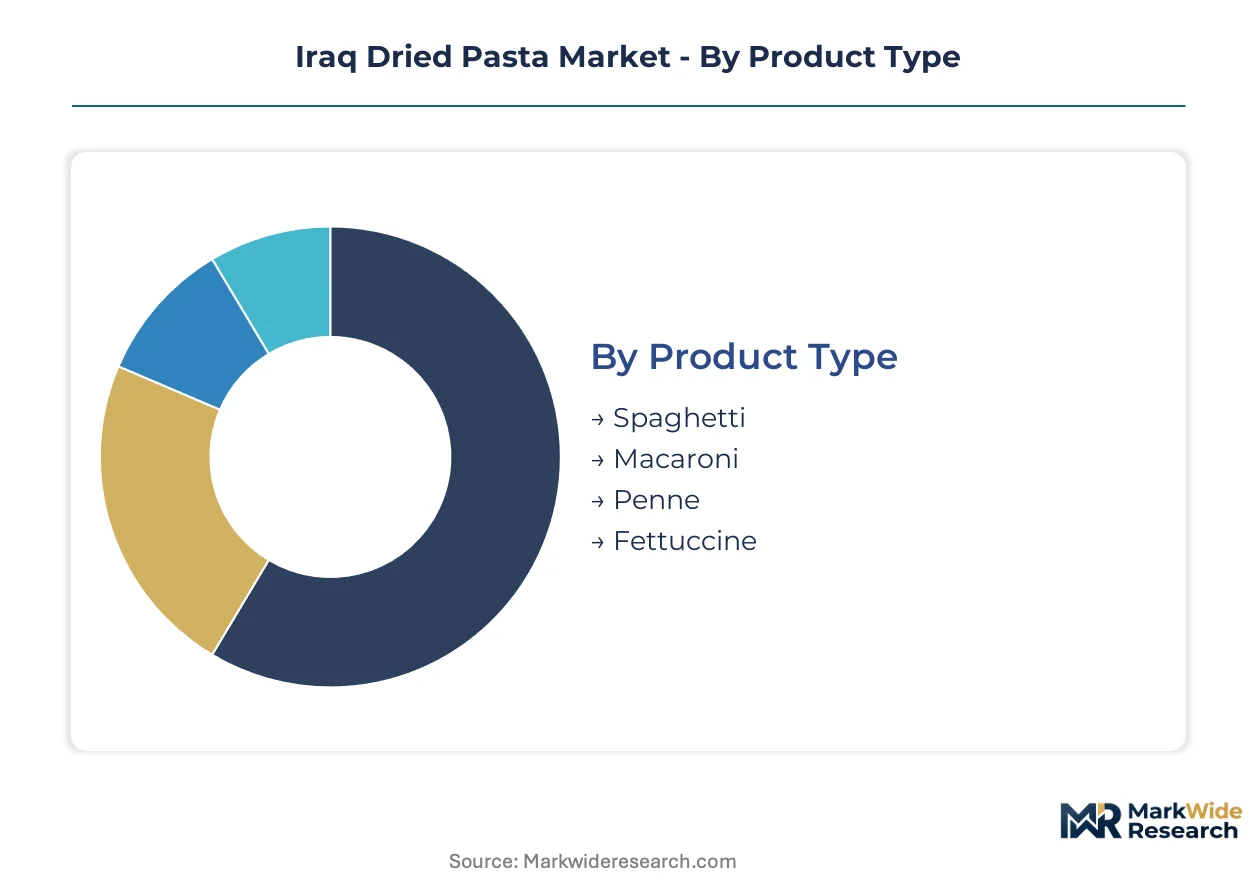
Iraq's dried pasta market segments along four distinct dimensions that shape procurement patterns and margin structures. Product type and distribution channel configurations dominate revenue concentration, while end-user and packaging specifications determine working capital requirements and compliance obligations.
Product Type:
The customization-vs-standardization spectrum runs from commodity long-cut shapes to specialized short-cut formats requiring distinct die configurations and drying protocols.
- Spaghetti:Long-cut durum wheat extrusions represent the baseline format across Iraqi retail and food service channels. Baghdad households purchase this shape for its rehydration predictability and sauce adhesion properties. Basra's quick-service operators specify bulk spaghetti for rapid plate assembly during peak dining periods.
- Macaroni:Curved short-cut tubes with hollow centers accelerate cooking time versus long-cut alternatives. Najaf and Karbala restaurants concentrate procurement around this shape for religious tourism corridor operations where kitchen throughput directly constrains revenue.
- Penne:Diagonal-cut cylinders with ridged exteriors capture sauce in angular grooves. Southern governorate food service buyers specify this format for premium positioning.
- Fettuccine:Flat ribbon extrusions require specialized cutting equipment and extended drying cycles. Limited domestic production capacity constrains volume expansion.
Leading the category by volume: Spaghetti. Expanding most quickly: Penne.
Distribution Channel:
Channel selection in this market maps directly to buyer scale and payment-term requirements, with institutional procurement running through fundamentally different logistics than household purchasing.
- Supermarkets:Baghdad and Basra hypermarket chains stock fortified SKUs in climate-controlled environments. These outlets enforce barcode traceability and expiration-date rotation protocols that strain smaller extruders' inventory systems.
- Grocery Stores:Neighborhood retailers across Iraqi governorates maintain 2-3 brand facings with high inventory turnover. Cash-based transactions dominate, eliminating receivables risk for suppliers.
- Online Retail:E-commerce penetration remains constrained by last-mile delivery reliability and payment infrastructure gaps. Urban Baghdad households experiment with platform ordering for bulk purchases.
- Wholesale:Municipal trade licensing variations across governorates create fragmented distributor landscapes. Licensed operators with multi-jurisdiction permits capture institutional volume from restaurant and food service buyers.
Supermarkets command the highest price realization per kilogram. Wholesale channels move the largest absolute tonnage.
End User:
User-type segmentation separates price-sensitive household consumption from procurement specifications that prioritize consistency and documentation.
- Households:Dual-income urban families in Baghdad and Basra prioritize rehydration speed and storage efficiency. These buyers substitute between durum semolina and flour-based alternatives based on monthly budget cycles.
- Restaurants:Quick-service operators in Najaf and Karbala pilgrimage corridors specify faster plate-turnaround shapes. Kitchen labor minutes directly correlate with table turnover and revenue per square meter.
- Food Service:Catering contractors for institutional clients require vacuum-sealed packaging for climate-variable distribution. Extended storage specifications add cost layers that compress margin structures.
- Institutions:Government procurement programs mandate micronutrient fortification compliance. Central Organization for Standardization and Quality Control certification requirements filter supplier eligibility.
Restaurants generate the steepest expansion trajectory. Households retain the largest share of absolute consumption volume.
Packaging Type:
Packaging specifications segment by shelf-life extension requirements and climate resilience, with institutional buyers demanding fundamentally different protection levels than household purchasers.
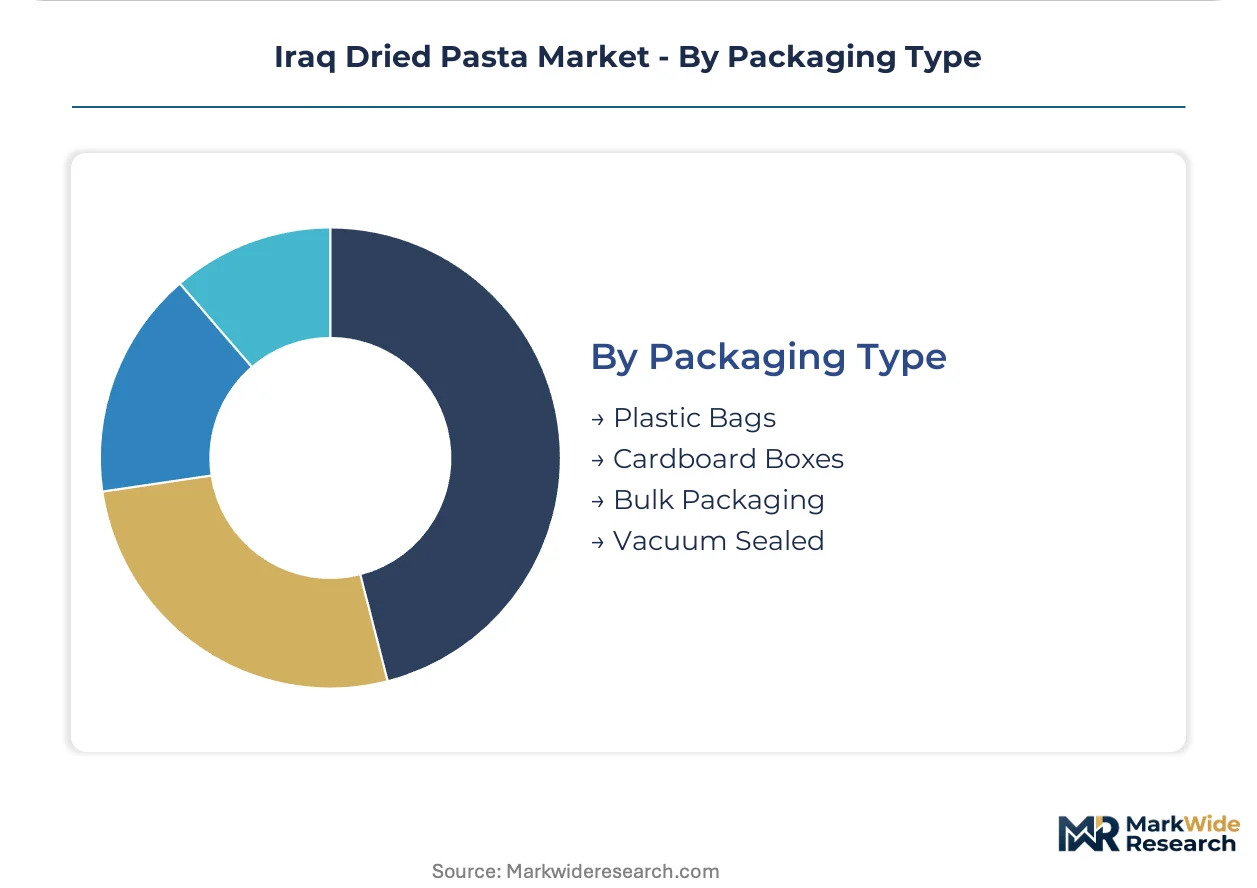
- Plastic Bags:Polyethylene film dominates household retail formats across Iraqi governorates. Cost efficiency supports price-competitive positioning against flour-based substitutes.
- Cardboard Boxes:Secondary packaging for multi-unit retail configurations protects against crushing in high-turnover grocery environments. Baghdad supermarkets specify this format for shelf-stackability.
- Bulk Packaging:Unpackaged or loosely bagged tonnage serves restaurant and food service procurement in southern governorates. Buyers assume responsibility for climate-controlled storage.
- Vacuum Sealed:Oxygen-extraction protocols extend shelf stability beyond standard dehydration specifications. Institutional buyers in climate-variable distribution environments concentrate demand here.
Plastic bags lead by unit volume. Vacuum sealed formats gain share fastest among institutional procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baghdad dominates Iraq's dried pasta consumption through dense urban household clusters and centralized food distribution infrastructure. Basra's port access shapes southern supply chain configurations. Erbil anchors northern procurement patterns through cross-border trade linkages.
Baghdad Governorate
Dual-income households in Baghdad's Sadr City and Karrada districts accelerate purchases of fortified spaghetti and macaroni formats. The Central Organization for Standardization and Quality Control enforces wheat product specifications that filter supplier eligibility for capital region distribution. Al-Khazraji Group and Al-Sardar Group maintain production facilities in Baghdad's industrial corridors to serve hypermarket and traditional souk channels.
Basra Governorate
Restaurant procurement in Basra's Ashar and Maqal districts concentrates demand for bulk-format penne and spaghetti. The Ministry of Health and Environment's fortification mandates apply uniformly across southern governorates, requiring micronutrient enrichment in mass-market categories. Port infrastructure at Umm Qasr enables durum wheat import flows that supply regional extrusion capacity.
Najaf and Karbala Governorates
Religious tourism operators in Najaf and Karbala quick-service corridors specify faster plate-turnaround pasta shapes. Kitchen throughput constraints directly correlate with revenue per square meter in pilgrimage zone locations. Al-Hayat Company and Al-Sharq Group position fortified product lines to capture institutional procurement from catering contractors.
Erbil Governorate
Cross-border trade linkages through Erbil's industrial zones expose northern markets to Turkish and Iranian pasta imports. Municipal trade licensing requirements in Kurdistan Region differ from federal jurisdictions, creating compliance complexity for multi-governorate distributors. Vacuum-sealed packaging formats gain traction among institutional buyers managing climate-variable storage in mountainous distribution environments.
Dhi Qar and Maysan Governorates
Rural household substitution between durum semolina and flour-based pasta intensifies during import cost spikes. Price-sensitive consumption patterns in southern agricultural zones favor commodity-grade alternatives over premium fortified lines. Wholesale distribution networks concentrate in Nasiriyah and Amara to serve dispersed grocery retail with polyethylene film packaged formats.
Iraq Dried Pasta Market Key Industry Players
Premium-margin players sit above commodity-margin players across fortification compliance and die technology dimensions. The vendor base organizes around three strategic archetypes: backward-integrated millers controlling semolina input costs, heritage-positioned brands commanding traditional retail shelf space, and fortification-compliant specialists capturing institutional procurement. Dominant competitive moves include bronze die equipment upgrades for texture differentiation and multi-jurisdiction trade licensing consolidation for wholesale channel access.
Among Baghdad-based integrated producers, Al-Khazraji Group for Food Industries, Al-Sardar Group for Food Industries, and Al-Hayat Company for Pasta and Food Industries occupy positions across the premium-to-standard tier spectrum. These entities exemplify archetype diversity through milling integration, heritage brand equity, and fortified product alignment respectively. Al-Sharq Group for Pasta and Food Industries and Al-Khateeb Group for Pasta and Food Industries represent additional domestic extrusion capacity concentrated in central and southern governorates. The competitive set remains exclusively domestic, with regional import competition filtered through tariff structures and fortification compliance requirements.
| Leading Market Players |
|---|
| Al-Khazraji Group for Food Industries |
| Al-Sardar Group for Food Industries |
| Al-Hayat Company for Pasta and Food Industries |
| Al-Sharq Group for Pasta and Food Industries |
| Al-Khateeb Group for Pasta and Food Industries |
| Al-Asala Group for Pasta |
| Al-Tahhan Group for Food Industries |
| DAS Food Industries |
| Al-Zaidi Group for Pasta and Food Industries |
| Others |
Cost & Logistics Intelligence
Backward integration into durum wheat milling anchors both supply security and pricing power for Baghdad-based extruders facing volatile import tariffs. Al-Khazraji Group's captive semolina production insulates margin structures from commodity cost spikes that compress purely extrusion-focused competitors.
Pricing Analysis
Throughput-based pricing for quick-service operators in Najaf and Karbala pilgrimage corridors rewards faster plate-turnaround shapes with volume discounts. Three-tier pricing structure across premium bronze-die, standard fortified, and economy flour-based levels segments buyer archetypes. Cost compression in commodity-grade tiers is intensifying because rural households substitute downward during wheat import price spikes. Food service procurement shows lowest price sensitivity due to kitchen labor minute constraints.
Supply Chain Analysis
Direct-to-institutional channels handle bulk-format tonnage for southern governorate restaurant networks. Durum wheat sourcing draws from Canada, Australia, and Black Sea origins to feed Iraqi milling capacity. Semolina supply rests on port infrastructure at Umm Qasr and overland routes through Turkey and Iran. Single-source vulnerability in vacuum-sealed packaging equipment creates bottleneck risk for climate-resilient institutional formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Iraqi Ministry of Health and Environment's fortification framework erects a compliance moat that filters regional import competition and rewards domestic recertification investment.
For Market Incumbents: Deploy bronze die equipment upgrades to capture texture-based premium positioning displacing Italian imports in Baghdad traditional souks. Consolidate multi-jurisdiction trade licensing across Baghdad, Basra, and Erbil to lock wholesale channel access against emerging distributors. Fortified line conversion timelines remain the critical vulnerability as recertification delays cede shelf space to compliant rivals. For New Entrants and Emerging Players: Launch via religious tourism corridor food service contracts in Najaf and Karbala where procurement consolidation around quick-turnover shapes outpaces supplier capacity. Target institutional vacuum-sealed packaging demand in climate-variable southern governorates where working capital requirements filter smaller competitors. Position through municipal licensing arbitrage in Erbil's differential regulatory environment. For Investors and Strategic Acquirers: Exit pathways concentrate in backward-integrated miller-extruders with captive semolina supply and fortification compliance already achieved. Long-term viability favors entities with Baghdad industrial corridor production assets and heritage brand equity in traditional retail channels. Watch tariff volatility on Canadian and Australian durum wheat as margin compression inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Bronze Die Equipment Upgrade | Rougher pasta surfaces capture sauce adhesion premium from Italian import displacement. |
| Fortification Compliance Investment | Micronutrient enrichment mandates from the Ministry of Health filter non-compliant regional suppliers. |
| Multi-Jurisdiction Licensing Consolidation | Municipal trade permits across Baghdad, Basra, and Erbil unlock institutional procurement scale. |
| Backward Integration into Milling | Captive semolina production insulates margin structures from durum wheat import tariff volatility. |
| Vacuum-Sealed Packaging Line Addition | Climate-resilient formats capture institutional buyers managing extended storage in southern governorates. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with extrusion plant managers, wholesale distribution license holders, food service procurement officers, and Central Organization for Standardization and Quality Control certification specialists combined with secondary validation from Ministry of Health fortification documentation, municipal trade registries, and durum wheat import manifests. Bottom-up production capacity estimates and top-down consumption surveys underwent cross-triangulation.
Reconciliation of production volume, import flows, and channel inventory data shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end-user category, and packaging specification. CAGRs derived from trend extrapolation of fortified product adoption rates and food service channel penetration patterns. Forecast inputs incorporated religious tourism volume trajectories and climate-variable storage demand elasticity.
Tariff volatility on durum wheat imports, fortification compliance timeline delays, and municipal licensing regime shifts are the dominant revision risks for projection accuracy. Forecasts reflect assumptions regarding pilgrimage corridor food service expansion and backward integration economics. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
US Canned Foods Market
Packaged Foods
Instant Rice Market
Packaged Foods
UAE Breakfast Cereals Market
Packaged Foods
Instant Cereals Market
Packaged Foods
Ready Meal Trays Market
Packaged Foods
South America Pasta and Noodles Market
Packaged Foods
Burritos Market
Packaged Foods
Australia Food Cans Market
Packaged Foods
Global Gluten-Free Breakfast Cereals Market
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
Prepared Flour Mixes Market
Packaged Foods
North America Ready-To-Eat Food Market
Packaged Foods
Instant Noodles Market
Packaged Foods
Instant Soup Market
Packaged Foods
Global Popping Candy Market
Packaged Foods
India Breakfast Cereals Market