
 Cocoa Solids Market | 2026-2036
Cocoa Solids Market Size, Share, and Industry Trends Forecast 2026-2036
Cocoa Solids Market Intelligence
Premium chocolate manufacturers is rotating demand away from mass-market confectionery buyers toward artisanal and bean-to-bar producers seeking traceable cocoa liquor. Barry Callebaut sustains vertical integration from bean sourcing to finished cocoa butter across multiple continents. Cargill dominates agricultural procurement networks that anchor its cocoa powder supply to North American and European food manufacturers. Olam International navigates sustainability certification requirements that differentiate its offerings in an increasingly regulated supply chain.
Cocoa solids comprise the non-fat components remaining after cocoa butter extraction, typically containing 10-12% residual fat and 20% protein, manufactured through hydraulic pressing, alkalization, or expeller processing for use as flavoring, coloring, and nutritional fortification agents. Cocoa powder occupies the largest volume share within product type segmentation due to its versatility across bakery and beverage applications, while cocoa liquor captures premium margins from single-origin and fine flavor demand. Within end user categories, confectionery remains mature with stable offtake, whereas nutritional products represents the fastest-growing application as protein fortification and polyphenol extraction gain traction in functional foods.
The EU Deforestation Regulation and FDA food safety standards collectively tighten traceability requirements across cocoa cake and butter imports, compelling processors to document farm-level origin data. EFSA guidelines on cadmium and ochratoxin A in cocoa products further constrain supply eligibility from specific growing regions, reshaping processor qualification protocols. Stakeholders must monitor evolving pesticide residue thresholds and carbon border adjustments that threaten to fragment certified versus conventional cocoa solid premiums.
Market Dynamics
The EU Deforestation Regulation's traceability mandates are restructuring procurement relationships across cocoa solids supply chains, compelling processors to rebuild origin documentation systems from farm gate onward.
Growth Catalysts
- Clean-label confectionery expansion:Western European artisanal bakeries and premium chocolate manufacturers are specifying alkalized cocoa powders with single-origin provenance for transparent ingredient statements.
- REACH and EFSA contaminant thresholds:Cadmium and ochratoxin A limits are disqualifying conventional suppliers from EU market access, concentrating demand among certified processors with laboratory verification capabilities.
- Expeller pressing technology:Cold-press extraction methods are preserving polyphenol content for functional food applications targeting sports nutrition and antioxidant fortification segments.
Market Restraints
- Cocoa bean price volatility:Weather-driven supply interruptions in Côte d'Ivoire and Ghana are compressing margins for cocoa cake processors locked into long-term powder contracts.
- West African supply concentration:Overreliance on Ivorian and Ghanaian bean origins creates systemic risk from political instability, port congestion, and sudden export restriction implementation.
- Butter extraction yield ceilings:Hydraulic pressing technology faces thermodynamic limits on fat recovery efficiency, constraining cocoa liquor economics relative to powder coproduct valuation.
Strategic Opportunities
- Indian functional food market:FSSAI approval pathways for polyphenol-rich cocoa extracts are opening nutritional supplement applications previously dominated by tea and berry antioxidants.
- EU Green Deal carbon border adjustments:Certified low-carbon cocoa butter imports will command premium positioning as Scope 3 emissions reporting becomes mandatory for confectionery manufacturers.
- Direct-to-bean sourcing platforms:Blockchain-integrated procurement systems are enabling micro-lot traceability for craft chocolate makers bypassing traditional commodity exchange structures.
Industry Challenges
- Origin documentation system integration:Farm-level geolocation data collection requires retrofitting supplier networks with GPS-enabled mobile applications and cloud-based chain-of-custody platforms.
- Alkalization chemistry expertise gap:pH-controlled dutching operations demand specialized process engineers scarce in emerging market processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocoa Solids Market |
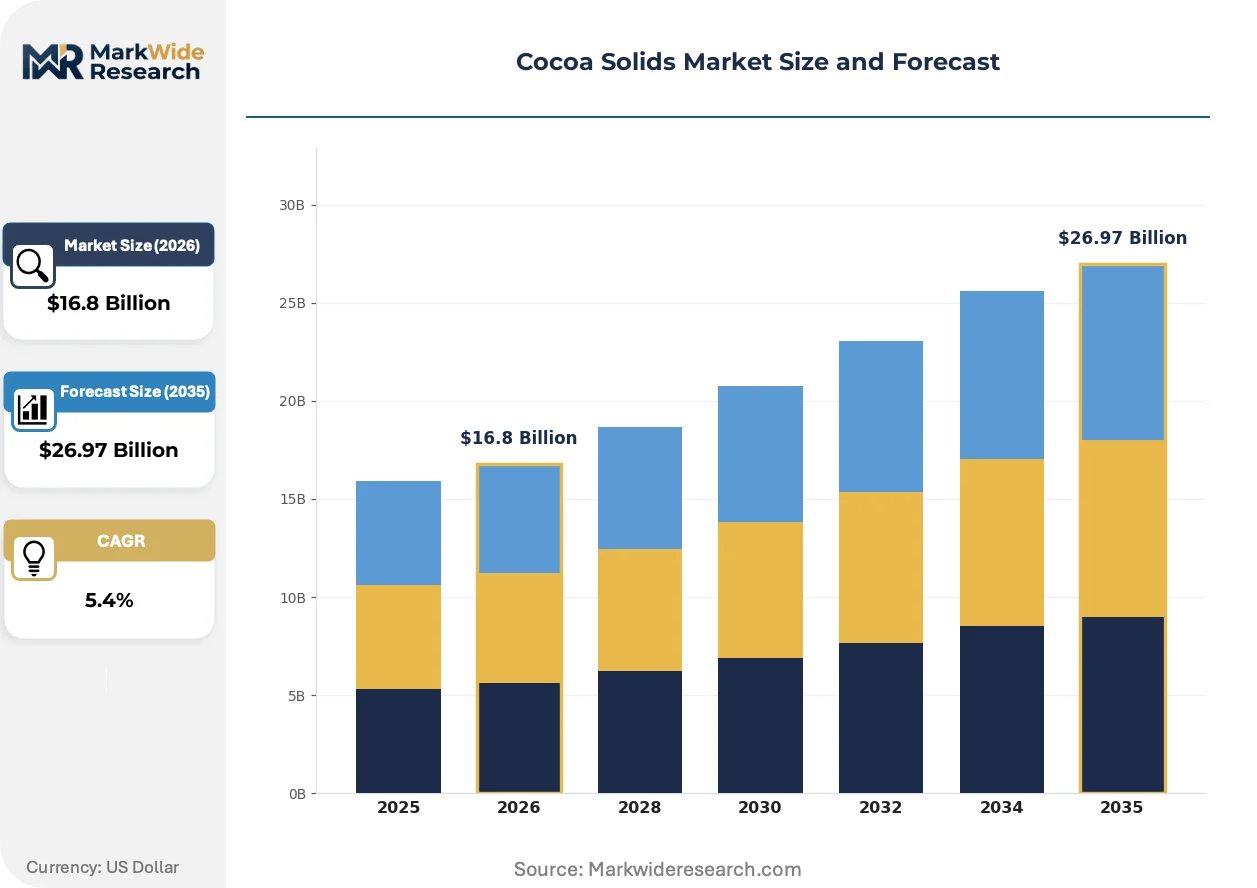
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $26.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cocoa Powder, Cocoa Liquor, Cocoa Butter, Cocoa Cake End User: Confectionery, Bakery, Beverages, Dairy Delivery Mode: Bulk, Packaged, Online, Direct Sales Application: Flavors, Colorants, Nutritional Products, Others |
| Companies Covered | Cargill, Barry Callebaut, Olam International, United Cocoa Processor, Guan Chong Berhad, Carlyle Cocoa, Jindal Cocoa, Puratos Group, Archer-Daniels-Midland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocoa Solids Market Strategic Shifts & Innovations
Processing technology and regulatory compliance requirements are converging to reshape how cocoa solids move from bean to finished ingredient, with traceability infrastructure now as critical as extraction efficiency.
Steam alkalization systems are displacing traditional gas-fired dutching methods in European processing facilities. Barry Callebaut and Cargill have both commissioned superheated steam installations at Belgian and Dutch plants to reduce acrylamide formation while achieving precise color standardization. This thermal approach is displacing legacy atmospheric roasting configurations that struggled to meet EFSA process contaminant benchmarks.
The EU Deforestation Regulation's December 2024 enforcement deadline is compelling processors to deploy satellite-verified farm polygon mapping. EFSA guidelines on heavy metal thresholds are simultaneously tightening laboratory testing protocols for cocoa cake imports from Latin American origins. German and French confectionery manufacturers are now requiring third-party-verified chain-of-custody documentation as a contract precondition, not a voluntary certification.
Bean-to-bar manufacturers are consolidating procurement relationships directly with cooperatives, compressing the traditional multi-tier commodity trading structure. This disintermediation is most pronounced in Ecuador and Madagascar fine flavor origins, where craft chocolate makers now represent material offtake previously absorbed by industrial liquor processors. The shift is visible in Quito and Antananarivo export patterns, where container volumes to small-scale North American and European roasters now rival traditional bulk shipments to Amsterdam and Hamburg.
Cocoa Solids Market Segmentation
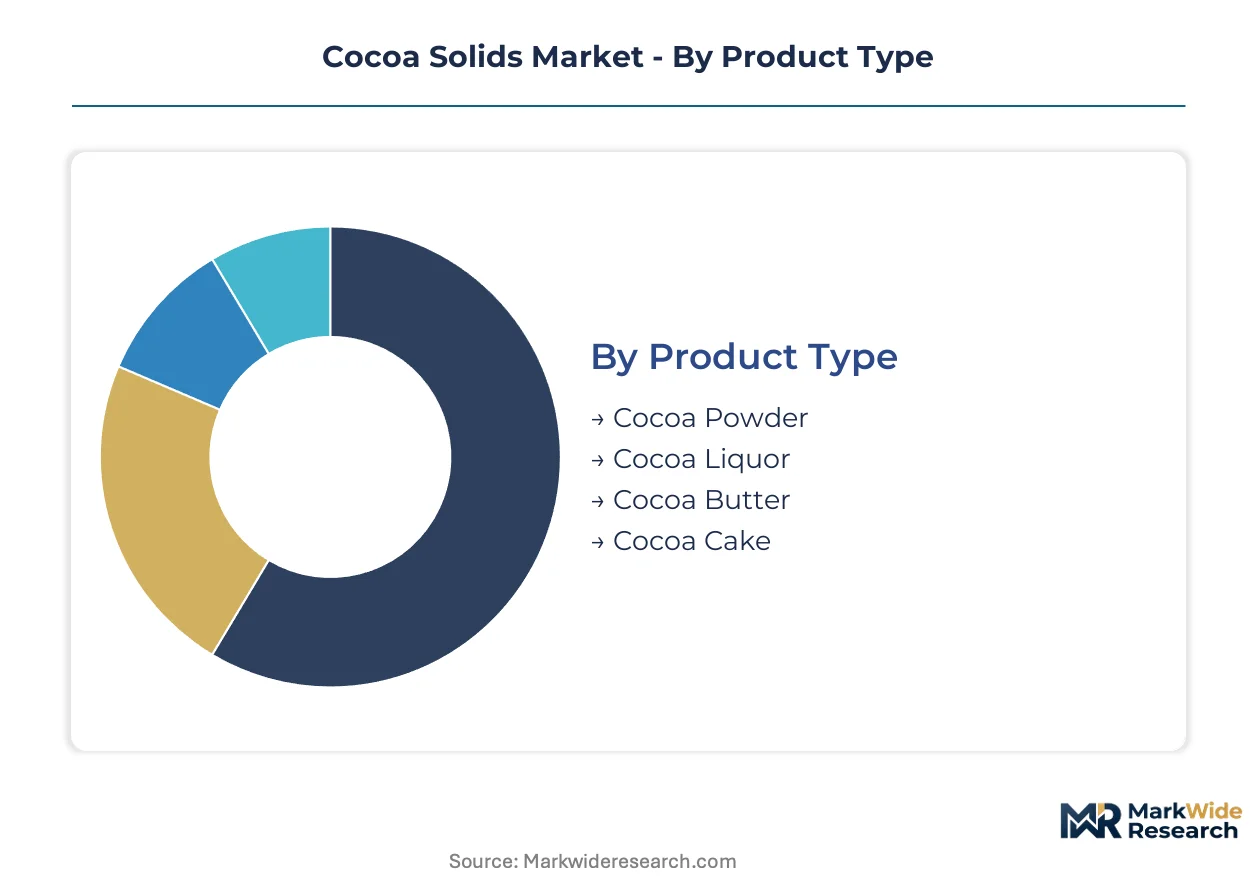
Cocoa solids segmentation reveals how extraction technology and end-use specifications fragment procurement economics. Product type determines margin structure through fat content and processing intensity, while application-driven demand concentrates in distinct regulatory and functional requirements.
Product Type:
Cocoa butter faces the strongest substitution pressure from shea and palm oil alternatives in cost-sensitive confectionery formulations, forcing premium positioning through traceability certification.
- Cocoa Powder:Alkalized and natural variants contain 10-12% residual fat after hydraulic pressing, serving as the workhorse ingredient across industrial bakery and beverage manufacturing. German and French artisanal bakeries are specifying single-origin powders for clean-label positioning under EFSA contaminant thresholds.
- Cocoa Liquor:Ground cocoa nibs retain full cocoa butter content, commanding premium margins from bean-to-bar chocolate makers seeking fine flavor origins. Craft producers in Ecuador and Madagascar now bypass traditional commodity exchanges through direct cooperative relationships.
- Cocoa Butter:Expeller-pressed and solvent-extracted grades supply confectionery fat requirements with distinct melting profiles for tempering applications.
- Cocoa Cake:The compressed solid residue from butter extraction feeds animal feed and low-grade cocoa powder production with limited value recovery.
Cocoa powder retains volume leadership across industrial applications; cocoa liquor holds the steepest expansion curve through premium chocolate demand.
End User:
Cost tier stratification separates commodity-scale buyers from specification-driven purchasers, with nutritional product manufacturers paying steepest premiums for polyphenol retention certification.
- Confectionery:Mature demand segment consuming cocoa liquor and butter for chocolate bar and praline production. EU Deforestation Regulation compliance costs are compressing margins for mass-market manufacturers lacking origin documentation systems.
- Nutritional Products:Sports nutrition and antioxidant supplement manufacturers specify cold-pressed cocoa extracts with preserved flavanol content. FSSAI approval pathways in India are opening functional food applications previously dominated by tea and berry extracts.
- Bakery:Industrial and artisanal bread, pastry, and biscuit producers utilize cocoa powder for color and flavor standardization across production runs.
- Beverages:Instant drink mixes and dairy applications demand specific particle size distributions for solubility and suspension stability.
- Dairy:Ice cream and flavored milk processors incorporate cocoa powder and liquor for chocolate flavoring in frozen and refrigerated applications.
Confectionery dominates absolute volume offtake; nutritional products are climbing the fastest as protein fortification and polyphenol extraction gain regulatory traction.
Delivery Mode:
Supply chain configuration determines which delivery modes capture margin, with bulk logistics favoring integrated processors and direct sales enabling micro-lot traceability premiums.
- Bulk:Tanker and container shipments of cocoa liquor and butter serve industrial confectionery manufacturers with continuous production requirements. Cargill and Barry Callebaut leverage vertical integration to anchor North American and European food manufacturer supply contracts.
- Packaged:Retail-format cocoa powder for artisanal and small-scale bakery operations commands distribution markups through food service wholesalers.
- Online:E-commerce platforms enable craft chocolate makers to source single-origin cocoa liquor directly from Ecuadorian and Madagascan cooperatives, compressing traditional trading tiers.
- Direct Sales:Blockchain-integrated procurement systems support bean-to-bar manufacturer relationships with farm-level geolocation verification.
Bulk delivery retains volume leadership through industrial concentration; online channels are gaining share fastest as disintermediation accelerates in fine flavor origins.
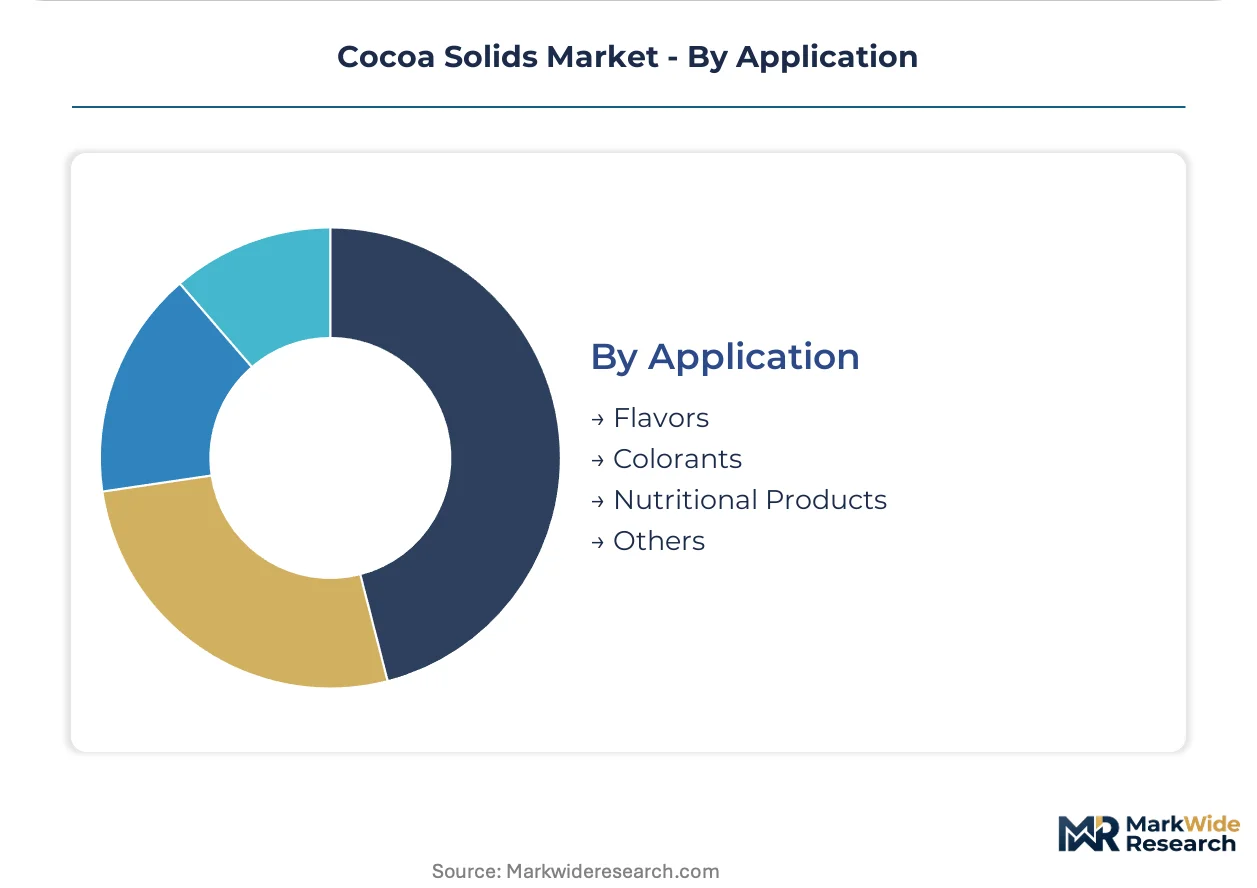
Application:
Functional specification intensity varies dramatically across applications, with colorant-grade powders facing commoditization while nutritional extracts command laboratory-verified premiums.
- Flavors:Cocoa liquor and high-fat powders provide chocolate taste profiles across confectionery, bakery, and dairy formulations. Steam alkalization systems at Belgian and Dutch processing facilities are displacing gas-fired dutching to meet EFSA acrylamide benchmarks.
- Nutritional Products:Polyphenol-rich extracts target sports nutrition and antioxidant fortification segments with cold-press processing preserving bioactive compounds. Expeller pressing technology is displacing solvent extraction for functional food applications.
- Colorants:Low-fat cocoa powders standardize brown coloration in baked goods and coatings with minimal flavor contribution requirements.
- Others:Cosmetic and pharmaceutical applications utilize cocoa butter for emollient and excipient functions outside food-grade specifications.
Flavor applications retain volume leadership across food manufacturing; nutritional products show the steepest expansion trajectory as functional food regulation matures in India and Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European cocoa solids logistics, processing bean arrivals from West African origins through integrated crushing and alkalization facilities serving confectionery manufacturers across the continent.
Germany
Artisanal bakeries in Munich and Cologne are specifying single-origin cocoa powders for clean-label positioning. EFSA cadmium thresholds are disqualifying conventional suppliers from market access. The Cologne-Bonn industrial corridor hosts steam alkalization facilities converting gas-fired dutching operations to meet acrylamide benchmarks.
France
Premium chocolate manufacturers in Paris and Lyon are rotating procurement toward traceable cocoa liquor for bean-to-bar production lines. REACH documentation requirements are reshaping import qualification protocols for cocoa cake processors. The Greater Paris region concentrates R&D investment for polyphenol extraction technologies targeting nutritional supplement applications.
Netherlands
Amsterdam's cocoa exchange infrastructure supports price discovery for powder and butter contracts across European food manufacturers. The EU Deforestation Regulation's December 2024 enforcement deadline is compelling satellite-verified farm polygon mapping for all imports. The Port of Rotterdam handles bulk cocoa liquor shipments feeding Belgian confectionery clusters.
United States
North American food manufacturers are locking into long-term powder contracts despite bean price volatility from Côte d'Ivoire supply interruptions. FDA food safety standards mandate laboratory verification for heavy metal content in cocoa cake imports. Chicago-based commodity traders are restructuring procurement relationships to document farm-level origin data.
India
Sports nutrition manufacturers in Mumbai and Bangalore are specifying cold-pressed cocoa extracts for antioxidant fortification formulations. FSSAI approval pathways for polyphenol-rich extracts are opening functional food applications previously dominated by tea and berry sources. The Maharashtra industrial belt hosts expeller pressing installations serving domestic nutritional product demand.
Cocoa Solids Market Key Industry Players
Concentration sits with integrated processors controlling bean sourcing through finished ingredient distribution. Three global agribusiness conglomerates dominate agricultural procurement networks and crushing capacity. Mid-tier regional specialists occupy alkalization and custom powder blending niches. Competitive moves center on backward integration into origin sourcing and certification infrastructure deployment for traceability compliance.
Among the integrated processor tier, Cargill, Barry Callebaut, and Olam International exemplify archetypes spanning agricultural procurement networks, vertical manufacturing footprints, and sustainability certification differentiation. Cargill represents the North American supply anchor with commodity-scale powder production. Barry Callebaut occupies the European processing center with Belgian and Dutch alkalization infrastructure. Olam International sits within the emerging market sourcing specialist category with cooperative network relationships in fine flavor origins.
| Leading Market Players |
|---|
| Cargill |
| Barry Callebaut |
| Olam International |
| United Cocoa Processor |
| Guan Chong Berhad |
| Carlyle Cocoa |
| Jindal Cocoa |
| Puratos Group |
| Archer-Daniels-Midland |
| Others |
Cost & Logistics Intelligence
EU Deforestation Regulation compliance gates both supply qualification and price differentiation, forcing processors to absorb traceability infrastructure costs that separate certified premiums from conventional commodity tiers. This regulatory filter concentrates purchasing power among vertically integrated handlers while disqualifying smaller traders from contract eligibility.
Pricing Analysis
Volume-discount tiering structures separate industrial-scale confectionery manufacturers from artisanal buyers, with alkalization grade and origin certification driving spreads between natural and dutched powder categories. Certified low-carbon cocoa butter commands positioning premiums as Scope 3 emissions reporting becomes mandatory for European confectionery manufacturers. Cost compression in standard-grade powder runs through West African supply interruptions and long-term contract rigidity. Mass-market chocolate manufacturers exhibit acute price sensitivity, while bean-to-bar producers prioritize traceability premiums over unit economics.
Supply Chain Analysis
Port congestion at Abidjan and Tema elevates inbound logistics costs for European processors dependent on Ivorian and Ghanaian bean arrivals. Supply concentrates in Côte d'Ivoire, Ghana, and Ecuador, with grinding capacity anchored in Amsterdam, Hamburg, and Singapore. Raw material flows draw from cocoa bean harvests, jute bagging supplies, and ocean freight container availability. Single-source vulnerability from West African political instability threatens systemic disruption. Distribution runs through integrated processor networks serving industrial manufacturers, with direct sales platforms disintermediating traditional commodity exchanges for craft chocolate segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized alkalization chemistry expertise and farm-level geolocation data infrastructure represent acute capability gaps that will determine competitive survival as regulatory enforcement tightens. Processors lacking laboratory verification capabilities or blockchain-integrated procurement systems face disqualification from premium contract tiers.
For Market Incumbents: Secure backward integration into Ecuadorian and Madagascan fine flavor origins before cooperative relationships crystallize around craft chocolate competitors. Invest in steam alkalization retrofits at Belgian and Dutch facilities to meet EFSA acrylamide benchmarks and defend positioning against certified processors with laboratory verification capabilities. For New Entrants and Emerging Players: Differentiate on cold-press polyphenol retention for Indian sports nutrition manufacturers seeking FSSAI-approved antioxidant alternatives to tea and berry extracts. Target nutritional product applications where functional food regulation creates qualification barriers for commodity-scale competitors lacking expeller pressing installations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across traceability infrastructure and laboratory certification capabilities, favoring processors with existing compliance systems over greenfield entrants. Acquisition targets should display integrated farm-polygon mapping and satellite verification deployment. The signal to watch is EU carbon border adjustment implementation scope for agricultural imports.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fine Flavor Origins | Direct cooperative relationships in Ecuador and Madagascar bypass commodity exchange premiums for craft chocolate supply. |
| Steam Alkalization Facility Retrofit | Belgian and Dutch processors reduce acrylamide formation while achieving EFSA-compliant color standardization. |
| Blockchain-Integrated Procurement Platform | Farm-level geolocation verification satisfies EU Deforestation Regulation documentation requirements for European buyers. |
| Cold-Press Expeller Installation | Polyphenol retention certification opens FSSAI-approved functional food applications in Indian sports nutrition. |
| Laboratory Verification Capability Buildout | In-house cadmium and ochratoxin A testing qualifies supply under REACH and EFSA contaminant thresholds. |
Research Approach
Findings reconcile primary fieldwork against secondary review of trade flow databases, regulatory filings, and commodity exchange records. Primary interviews engaged cocoa processing plant managers, confectionery procurement leads, cooperative export directors, and alkalization technology specialists across European and West African markets. Secondary validation drew from customs declarations, EFSA guidance documents, and EU Deforestation Regulation implementation notices. Bottom-up volume estimates from grinding capacity and origin production data triangulate against top-down demand aggregation across end-use segments.
Segmentation dimensions modeled include product type, end-user category, delivery mode, and application function across the analysis window. CAGRs derive from regression analysis against historical price-volume relationships and regulatory implementation timelines. Forecast inputs incorporate cocoa bean yield projections, alkalization capacity expansion announcements, and certification adoption curves.
Decision-makers should treat outputs as directional under assumptions of sustained EU regulatory enforcement and functional food approval pathway continuity; material deviation would warrant model refresh. Specific risks include sudden West African export restrictions, accelerated carbon border adjustment scope expansion, and FSSAI regulatory timeline delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Egg Replacement Ingredients Market
Ingredients
Low-Fat Cocoa Powder Market
Ingredients
China Beer Adjuncts Market
Ingredients
Bay Leaf Oil Market
Ingredients
Potato Starch Market
Ingredients
Omega Ingredients Market
Ingredients
Cooking Oils and Fats Market
Ingredients
Pea Starch Market
Ingredients
India Bakery Ingredients Market
Ingredients
Fucoidan Extract Market
Ingredients
Desiccated Coconut Market
Ingredients
Dried Distillers' Grains with Soluble Market
Ingredients
Xylooligosaccharide Market
Ingredients
Africa Fats and Oil Market
Ingredients
Bertholletia Excelsa Seed Oil Market
Ingredients
Fresh Yeast Market