
 Europe Noodles and Pasta Market | 2026-2036
Europe Noodles and Pasta Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Noodles and Pasta Market Foresight
The EU Green Deal is restructuring procurement priorities across European food manufacturing, pushing durum wheat suppliers and pasta processors toward verified lower-carbon agricultural practices. Barilla G. e R. F.lli S.p.A leverages its vertically integrated Italian supply chain to secure traceable semolina grades, while Ebro Foods anchors Iberian production capacity with extensive milling infrastructure. Nestle competes through portfolio breadth spanning ambient and chilled pasta formats.
Europe noodles and pasta encompass wheat-based, egg-enriched, and alternative-grain formulations extruded or sheeted for ambient, chilled, or frozen distribution, with durum wheat semolina defining premium dried quality through protein content above 12% and gluten strength metrics. Dried pasta occupies the largest value share given shelf stability and concentrated Italian export volumes, while gluten-free formulations represent the fastest-expanding form category as formulation science improves tapioca and legume-based texture profiles. Specialty pasta variants incorporating pulse flours command premium positioning in specialty stores and online retail channels.
EFSA gluten threshold standards and EU organic certification frameworks shape product composition claims and cross-border market access, with REACH compliance governing food-contact packaging across member states. ECHA chemical safety evaluations influence noodle seasoning additive approvals, particularly for instant noodle flavoring systems. Stakeholders must monitor evolving EU F-Gas Regulation impacts on chilled pasta refrigeration logistics and anticipate CSRD disclosure requirements affecting agricultural supplier reporting obligations.
Market Dynamics
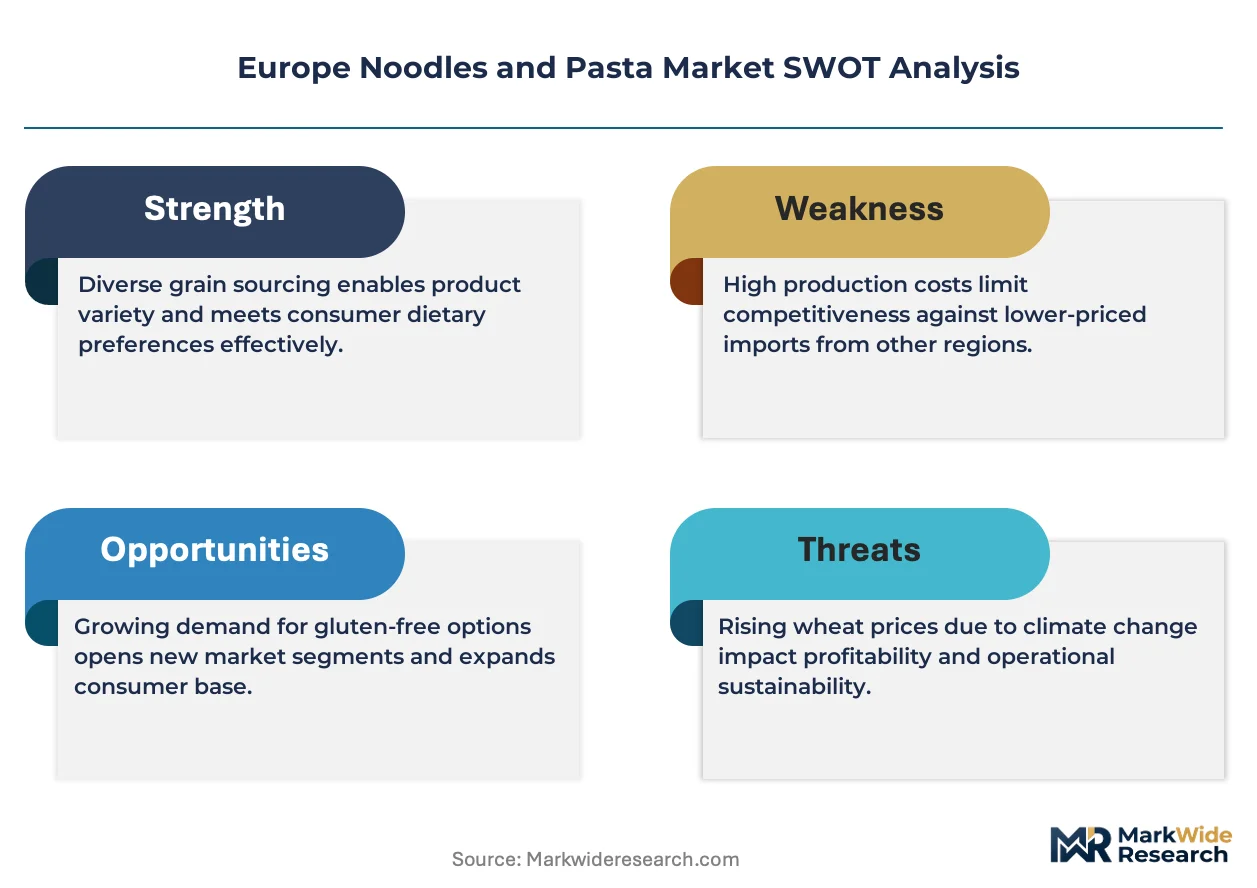
The EU Green Deal is forcing durum wheat suppliers and pasta processors to restructure procurement around verified lower-carbon agricultural practices, with EFSA gluten threshold standards and REACH compliance simultaneously tightening product composition and packaging requirements across member states.
Growth Catalysts
- EU Green Deal procurement mandates:Food service operators across Western Europe are expanding pasta-forward menu offerings to meet sustainability criteria for agricultural sourcing, creating pull-through demand for certified lower-carbon durum wheat.
- Italy:Italian durum wheat supply chains anchor premium dried pasta manufacturing through concentrated semolina production infrastructure and established export logistics.
- Gluten-free formulation science:Advances in tapioca and legume-based texture profiles are expanding addressable demand among celiac and flexitarian consumer segments.
Market Restraints
- Durum wheat input cost volatility:Climate-induced yield variability in Mediterranean growing regions creates margin pressure for semolina-dependent processors.
- Italian supply concentration:Premium dried pasta manufacturing relies heavily on Po Valley durum wheat, exposing buyers to localized weather and logistics disruptions.
- EFSA gluten threshold enforcement:Strict labeling and cross-contamination standards create compliance friction for manufacturers operating multiple product lines on shared extrusion equipment.
Strategic Opportunities
- Germany:Chilled pasta penetration remains below Southern European levels, creating expansion potential for ambient-to-chilled format migration.
- Pulse flour convergence:Blending legume and cereal proteins enables premium positioning in specialty retail and direct-to-consumer channels.
- CSRD disclosure requirements:Mandatory agricultural supplier reporting obligations will favor processors with captive traceability systems, creating competitive separation from commodity sourcing models.
Industry Challenges
- Extrusion technician scarcity:Specialized knowledge of high-moisture pasta forming and alternative-grain rheology is concentrated among aging workforces in Emilia-Romagna.
- F-Gas refrigeration retrofit costs:Chilled pasta cold chain operators face capital-intensive equipment upgrades to comply with phasedown schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Noodles and Pasta Market |
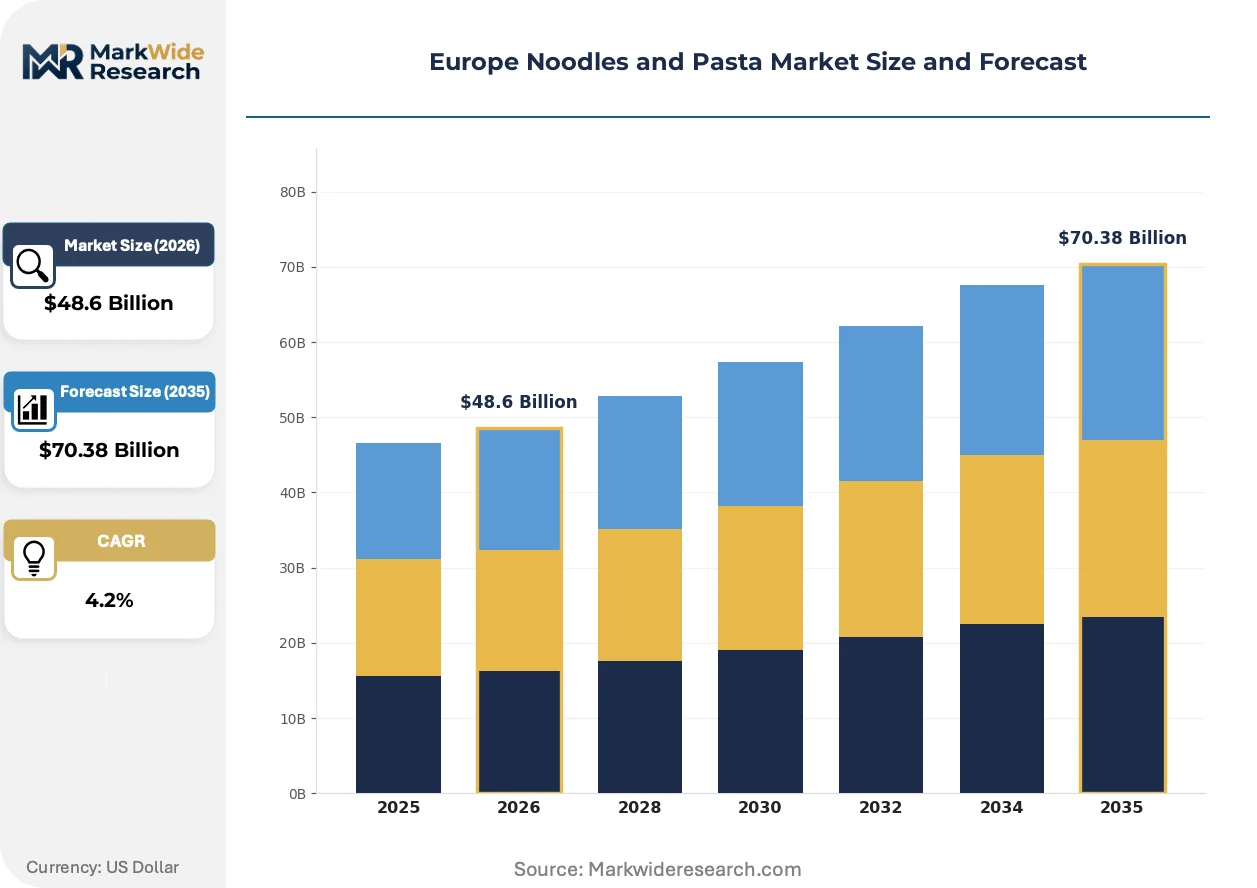
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $70.38 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Noodles, Dried Pasta, Fresh Pasta, Specialty Pasta End User: Restaurants, Supermarkets, Food Services, Households Distribution Channel: Online Retail, Hypermarkets, Convenience Stores, Specialty Stores Form: Whole Grain, Gluten-Free, Traditional, Organic |
| Companies Covered | Barilla G. e R. F.lli S.p.A, Ebro Foods, Nestle, Unilever, Nissin Food Products, The Kraft Heinz Company, F.lli De Cecco di Filippo, Pastificio Rana, Conagra Brands, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Noodles and Pasta Market Shifts & Advancements
Pulse flour integration and precision fermentation are rewriting formulation possibilities, while regulatory disclosure mandates and channel fragmentation are reshaping how processors compete for shelf space and procurement contracts.
Extrusion technology optimized for pulse-cereal blends is rewriting texture benchmarks in the gluten-free segment. Specialty pasta manufacturers in Northern Italy are adopting twin-screw systems capable of handling chickpea and lentil flours at industrial scale. The technology is rewriting quality thresholds that previously confined legume-based products to artisanal price tiers.
REACH compliance governing food-contact packaging is tightening additive approvals across member states. ECHA chemical safety evaluations are forcing noodle seasoning reformulations, particularly for instant noodle flavoring systems. Chilled pasta producers in France and Germany are responding by accelerating migration to mono-material films ahead of enforcement timelines.
Food service procurement is consolidating around verified origin claims as operators respond to EU Green Deal sustainability criteria. Large-scale contract catering in the Netherlands and Belgium is replacing commodity pasta with traceable semolina grades. Southern European institutional buyers are following, creating geographic contagion in sourcing standards.
Europe Noodles and Pasta Market Segmentation
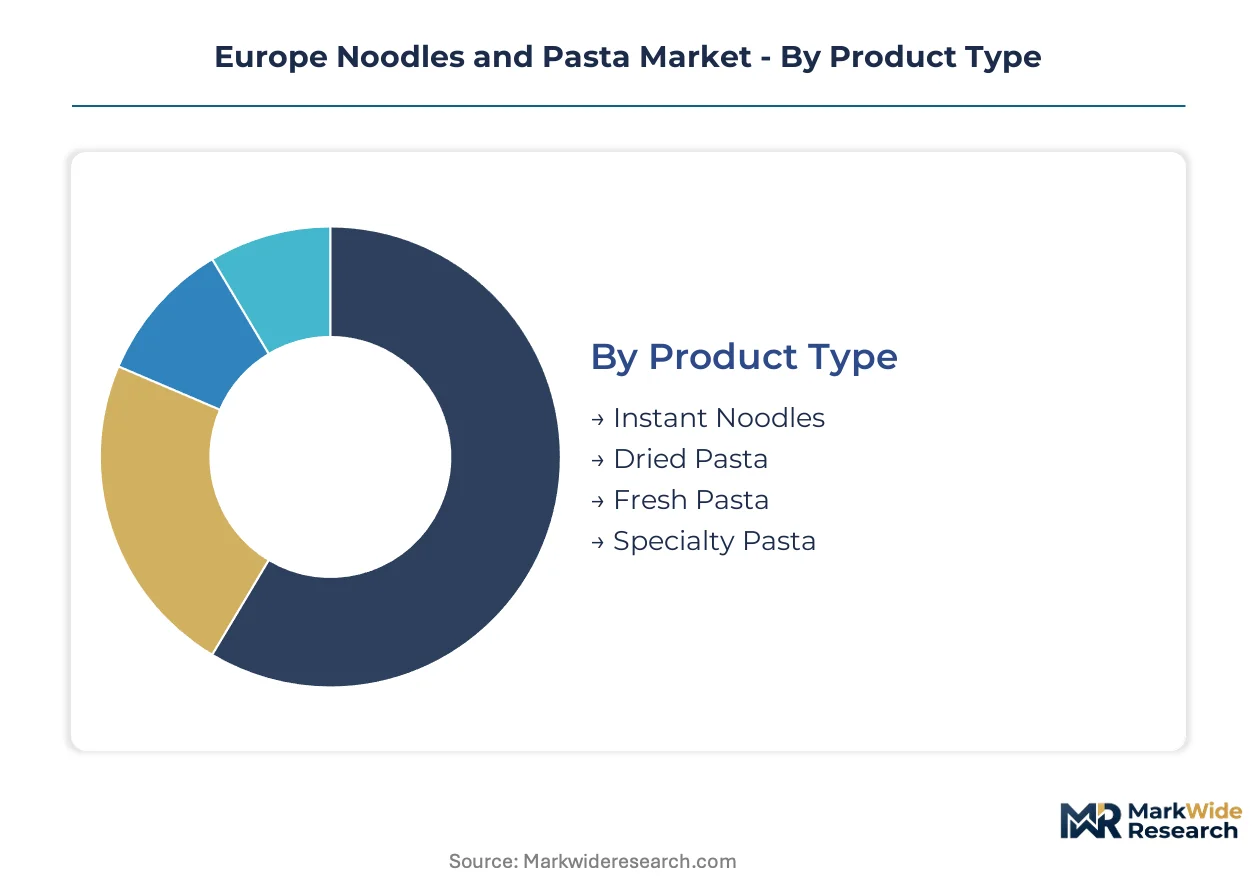
European noodles and pasta procurement patterns diverge sharply across product formats and channel structures, with sustainability certifications and format convenience driving divergent upgrade cycles across institutional and retail buyers.
Product Type:
Replacement cycles vary dramatically by moisture content and shelf stability, with ambient formats commanding longer purchase intervals than perishable alternatives.
- Dried Pasta:Durum wheat semolina extrusions with protein content exceeding 12% define quality benchmarks for this shelf-stable category. Italian export infrastructure and Po Valley semolina concentration sustain volume leadership across German and French retail channels, though climate-induced yield variability creates periodic supply friction.
- Instant Noodles:Pre-cooked, flash-fried or air-dried wheat strands with integrated seasoning systems target convenience-oriented demand. ECHA chemical safety evaluations under REACH are forcing seasoning reformulations across Central European manufacturing, particularly affecting flavoring additive approvals.
- Fresh Pasta:High-moisture egg-enriched formulations requiring chilled distribution. F-Gas Regulation compliance costs are accelerating cold chain equipment retrofits among French and German producers.
- Specialty Pasta:Pulse flour blends and alternative-grain formulations commanding premium positioning. Twin-screw extrusion adoption in Northern Italy is scaling chickpea and lentil-based production beyond artisanal volumes.
Dried Pasta sits at the top of the volume ranking, with Specialty Pasta climbing the fastest.
End User:
Procurement sophistication tiers separate institutional buyers with verified origin requirements from price-sensitive household purchasing.
- Food Services:Contract catering operators across the Netherlands and Belgium are replacing commodity pasta with traceable semolina grades to meet EU Green Deal sustainability criteria. Large-scale procurement consolidation favors processors with captive traceability systems.
- Supermarkets:Multi-format retail chains stock ambient, chilled, and frozen pasta across private-label and branded portfolios. Shelf-space allocation increasingly privileges gluten-free and organic variants with certified supply chains.
- Restaurants:Independent and chain operators source fresh and dried formats through regional distributors. Italian supply chain concentration exposes operators to localized logistics disruptions.
- Households:Individual consumers purchasing through retail and online channels. Flexitarian dietary shifts are expanding addressable demand for legume-enriched and alternative-grain formulations.
Food Services generates the steepest expansion trajectory as sustainability mandates reshape institutional procurement, while Households maintains the broadest volume base.
Distribution Channel:
Channel fragmentation is accelerating as mono-material packaging migrations and direct-to-consumer platforms reshape traditional retail hierarchies.
- Hypermarkets:Large-format retailers with extensive ambient and chilled pasta assortments. REACH compliance timelines are driving packaging material transitions ahead of enforcement dates.
- Online Retail:E-commerce platforms enabling direct-to-consumer sales of specialty and subscription pasta formats. Pulse flour convergence products command disproportionate share in this channel.
- Specialty Stores:Gourmet and health-focused retailers curating organic, gluten-free, and artisanal pasta selections. CSRD disclosure requirements will favor stocked brands with verified agricultural supplier reporting.
- Convenience Stores:Limited-assortment retail focused on instant noodles and single-serve ambient pasta. EFSA gluten threshold enforcement creates compliance friction for multi-line manufacturers.
Hypermarkets retain volume dominance, with Online Retail gaining share fastest through specialty format penetration.
Form:
Certification tier and ingredient provenance are becoming primary segmentation axes as regulatory disclosure mandates reshape competitive positioning.
- Traditional:Standard durum wheat semolina formulations without specialty certifications. Italian milling infrastructure and export logistics sustain cost competitiveness across mass-market retail.
- Gluten-Free:Tapioca, rice, and legume-based formulations meeting EFSA gluten threshold standards. Advances in texture science are expanding addressable demand among celiac and flexitarian segments.
- Organic:EU-certified organic wheat and alternative grain formulations with verified agricultural practices. EU Green Deal procurement mandates are pulling through institutional demand for certified organic supply chains.
- Whole Grain:Formulations retaining bran and germ layers for enhanced fiber content. German chilled pasta penetration below Southern European levels creates expansion potential for whole grain fresh formats.
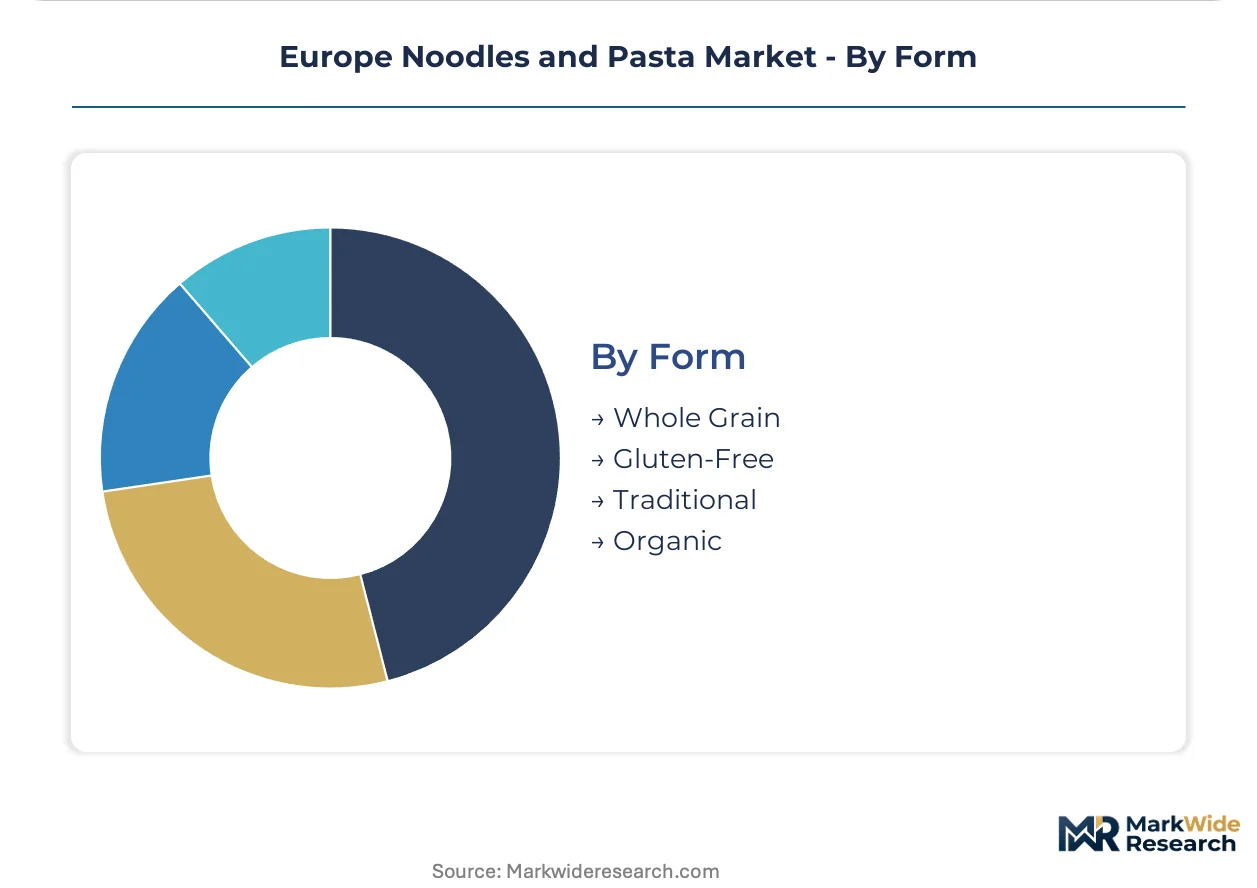
Traditional holds the volume lead, with Gluten-Free expanding most quickly as formulation science improves alternative-grain texture profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian pasta manufacturing traces its industrial lineage to 19th-century Parma and Naples, where semolina milling and bronze-die extrusion techniques scaled into export-oriented production. German and French processors later adopted these methods, adapting them to chilled distribution networks and alternative-grain formulations. Today, national procurement patterns diverge sharply across Mediterranean durum wheat dependence and Northern European sustainability mandates.
Italy
Emilia-Romagna and Campania host the densest concentration of premium dried pasta extrusion capacity, with Parma and Gragnano anchoring artisanal and industrial production clusters. EFSA gluten threshold enforcement shapes labeling compliance across shared manufacturing lines, while Po Valley durum wheat supply chains face mounting climate-induced yield pressure. Barilla G. e R. F.lli S.p.A exemplifies vertical integration from semolina milling through branded distribution.
Germany
Chilled pasta penetration in Bavaria and North Rhine-Westphalia trails Southern European consumption levels, creating format migration opportunities for fresh and whole-grain variants. F-Gas Regulation compliance timelines are accelerating refrigeration equipment retrofits among Stuttgart and Hamburg processors. Ebro Foods anchors Iberian-German distribution corridors through captive milling infrastructure.
France
Île-de-France contract catering operators are replacing commodity pasta with traceable semolina grades to satisfy EU Green Deal procurement criteria. REACH compliance is forcing mono-material packaging transitions ahead of enforcement dates, particularly affecting instant noodle seasoning systems. Lyon-based processors are adopting pulse-flour extrusion technology for institutional supply contracts.
Netherlands
Rotterdam and Amsterdam food service procurement is consolidating around verified origin claims as large-scale catering responds to CSRD disclosure requirements. Dutch distributors are prioritizing processors with captive agricultural traceability systems over commodity sourcing models. The Randstad logistics hub enables rapid chilled pasta distribution across Benelux institutional channels.
Spain
Catalonia and Valencia processors leverage Mediterranean durum wheat proximity while expanding into legume-enriched specialty formats for export markets. Ebro Foods anchors Iberian production capacity through extensive milling infrastructure concentrated in Zaragoza and Barcelona. Spanish operators are positioning pulse-flour convergence products for German and French retail penetration.
Europe Noodles and Pasta Market Competitive Landscape
Capital-heavy producers compete with asset-light brand licensors across divergent margin structures in the European noodles and pasta sector. Semolina-dependent millers with captive wheat supply chains face asset intensity pressures that seasoning-focused instant noodle assemblers avoid entirely. Three archetypes dominate: vertically integrated Italian miller-extruders, Iberian diversified grain processors, and Swiss-Dutch branded portfolio operators. Competitive separation hinges on backward integration depth and sustainability certification velocity rather than manufacturing scale alone.
Within the vertically integrated tier, Barilla G. e R. F.lli S.p.A and F.lli De Cecco di Filippo occupy positions defined by Emilia-Romagna production concentration and Po Valley supply chain control. Ebro Foods represents the diversified processor archetype, with Spanish milling infrastructure supporting format breadth across ambient and chilled categories. Nestle exemplifies the branded portfolio operator, spanning multiple moisture formats through licensed and owned production arrangements without direct agricultural asset exposure.
| Leading Market Players |
|---|
| Barilla G. e R. F.lli S.p.A |
| Ebro Foods |
| Nestle |
| Unilever |
| Nissin Food Products |
| The Kraft Heinz Company |
| F.lli De Cecco di Filippo |
| Pastificio Rana |
| Conagra Brands |
| Others |
Supply & Pricing Matrix
Large-scale contract catering operators in the Netherlands and Belgium concentrate procurement volume, anchoring a three-tier pricing structure across premium, standard, and economy levels that reflects sustainability certification tiers rather than commodity spot dynamics.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts, with EU organic certification and CSRD-compliant traceability commanding measurable premiums over conventional semolina grades. Price differentiation hinges on gluten threshold verification and durum wheat origin documentation, with climate-induced yield variability in Mediterranean growing regions compressing margins across standard tiers. Food service buyers exhibit lowest price sensitivity due to sustainability mandate compliance requirements, while convenience retail channels face acute pressure from private-label substitution.
Supply Chain Analysis
Reverse logistics for chilled pasta returns and temperature-compromised inventory flows through specialized cold chain operators in France and Germany, with F-Gas Regulation compliance costs reshaping equipment replacement cycles. Raw material supply draws from Italian Po Valley durum wheat concentration, Spanish milling infrastructure in Zaragoza and Barcelona, and emerging pulse flour sourcing from Dutch legume processors. Single-source vulnerability around Italian semolina concentration exposes buyers to localized weather disruptions. Distribution runs through hypermarket retail networks, contract catering procurement hubs, and direct-to-consumer specialty platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement cost differentials between Southern European durum wheat dependence and Northern European sustainability compliance investments create geographic-arbitrage opportunities for processors with cross-border supply chain flexibility.
For Market Incumbents: Cement backward integration into Po Valley semolina milling to defend against climate-induced supply volatility, while accelerating CSRD-compliant traceability system deployment to capture institutional procurement consolidation in the Netherlands and Belgium. Barilla's vertically integrated model demonstrates defensive positioning against commodity sourcing erosion. For New Entrants and Emerging Players: Pulse-flour extrusion technology offers a technology-first wedge into gluten-free and flexitarian segments where formulation science gaps persist, particularly in German chilled pasta penetration below Southern European levels. Target direct-to-consumer subscription models for legume-enriched specialty formats, leveraging online retail channel growth and bypassing hypermarket slotting fee barriers. For Investors and Strategic Acquirers: Diversified grain processors with Iberian milling infrastructure and Northern European distribution reach are the most active acquirer category in this space, with Ebro Foods exemplifying acquisition-ready format breadth across ambient and chilled categories. Monitor EU F-Gas Regulation enforcement timelines as capital expenditure inflection signals for chilled pasta cold chain valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semolina Milling | Captive supply of Po Valley durum wheat secures traceability premiums under EU Green Deal procurement mandates. |
| Pulse-Flour Extrusion Scale-Up | Twin-screw technology adoption in Northern Italy enables industrial-volume chickpea and lentil pasta production. |
| CSRD-Compliant Traceability Systems | Mandatory agricultural supplier reporting obligations favor processors with verified origin documentation over commodity sourcing. |
| Mono-Material Packaging Migration | REACH compliance timelines accelerate transitions ahead of enforcement, particularly affecting French instant noodle seasoning systems. |
| Chilled Pasta Cold Chain Retrofit | F-Gas Regulation phasedown schedules force capital-intensive refrigeration equipment upgrades among German and French producers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pasta manufacturing executives, durum wheat procurement leads at millers, food service category managers, and EFSA regulatory affairs specialists with secondary validation from EU trade customs data, ECHA chemical safety evaluations, and SEC filings of listed processors. Bottom-up volume modeling across product formats and end-use channels triangulated against top-down macroeconomic consumption indicators.
Segment-weighting approaches distributed value and volume projections across moisture content tiers, distribution channel structures, and certification categories throughout the forecast period. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points including EU Green Deal implementation pace and F-Gas Regulation enforcement schedules. Wheat yield volatility indices and gluten-free formulation patent filings informed alternative-grain adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Mediterranean climate patterns and EU agricultural subsidy restructuring. Practitioners should monitor EFSA gluten threshold enforcement actions and CSRD disclosure rollout timelines for early signals of procurement standard shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Singapore Ready-To-Eat Food Market
Packaged Foods
Protein Packed Foods Market
Packaged Foods
Convenience Food Market
Packaged Foods
Ready Meals Market
Packaged Foods
Spreads Market
Packaged Foods
Global Food Spread Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
Ready Meal Trays Market
Packaged Foods
Instant Ramen Market
Packaged Foods
Asia-Pacific Sweet Biscuits Market
Packaged Foods
Global Popping Candy Market
Packaged Foods
North America Chewing Gum Market
Packaged Foods
Low Calorie Noodles Market
Packaged Foods
Burritos Market
Packaged Foods
North America Instant Noodles Market
Packaged Foods
Freekeh Market