
 Middle-East and Africa Ready-To-Eat Food Market | 2026-2036
Middle-East and Africa Ready-To-Eat Food Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Ready-To-Eat Food Market Foresight
SFDA food safety modernization across Gulf Cooperation Council states is consolidating procurement standards for importers and domestic manufacturers alike. Nestlé S.A. leverages its Maggi and Nescafé distribution webs to anchor ready-to-eat penetration in Egyptian and Saudi retail channels. Almarai Company dominates dairy-based prepared meal segments through its captive chilled logistics network across the Arabian Peninsula. McCain Foods Limited extends its African frozen potato platform into complete meal kits for South African quick-service restaurants.
Ready-to-eat food comprises pre-cooked, packaged sustenance requiring minimal preparation beyond reheating or ambient consumption, typically formulated for shelf stability through retort processing, blast freezing, controlled-atmosphere packaging, or dehydration to moisture levels below water activity thresholds that inhibit microbial proliferation. Its primary commercial purpose is to reduce meal preparation labor and equipment dependency for time-constrained consumers, institutional feeders, and field-deployed organizations. Frozen meals command the largest value share given cold chain investments in South Africa and Gulf urban centers, while pouched formats are expanding fastest as flexible packaging lines multiply in Morocco and Egypt. Online retail channels are capturing disproportionate growth in Nigerian and Kenyan metropolitan markets where smartphone penetration enables direct-to-consumer fulfillment.
SFDA standards in Saudi Arabia, Egypt's EOS food safety protocols administered through the national food safety authority, and South Africa's Department of Health fortification regulations collectively determine permissible additives, labeling requirements, and import clearance protocols across the region's three largest national markets. These frameworks elevate compliance costs for entrants but simultaneously protect established operators with in-house laboratory and certification capabilities. Stakeholders must track evolving halal certification reciprocity agreements between Gulf national accreditation bodies and emerging African supply jurisdictions to anticipate sourcing advantage shifts.
Market Dynamics
Cold chain infrastructure investments across Nigeria, Kenya, and South Africa are compressing distribution timelines for frozen and chilled ready-to-eat formats, while Gulf Cooperation Council food safety harmonization is elevating compliance thresholds for cross-border suppliers.
Growth Catalysts
- Urban workforce expansion:Young professionals in Lagos and Nairobi office corridors are purchasing shelf-stable prepared meals for weekday consumption, creating sustained demand for retort-pouched formats.
- SFDA modernization:Saudi Arabia's consolidated food safety protocols are streamlining import clearance for compliant manufacturers, reducing time-to-shelf for validated suppliers.
- Flexible packaging scale-up:Moroccan and Egyptian production lines are multiplying capacity for vacuum-sealed and controlled-atmosphere pouches, enabling format diversification at lower unit costs.
Market Restraints
- Halal certification fragmentation:Non-reciprocal accreditation between Gulf national bodies and emerging African supply jurisdictions creates redundant audit costs for multi-market exporters.
- Refrigerated logistics dependency:Frozen meal distribution remains constrained outside South Africa's primary corridors and Gulf urban centers, limiting addressable population density.
- Input cost volatility:Wheat and palm oil price swings directly compress margins for pasta-based and fried-format producers operating on thin working capital.
Strategic Opportunities
- Direct-to-consumer channels:Smartphone-enabled fulfillment platforms in Nigerian and Kenyan metropolitan markets are capturing disproportionate volume growth versus traditional retail.
- Fortification mandates:South Africa's updated Department of Health regulations create formulation partnerships between packaged meal producers and micronutrient suppliers.
- Dairy-based meal extension:Chilled logistics networks across the Arabian Peninsula enable premium positioned protein-fortified formats for institutional catering contracts.
Industry Challenges
- Technical workforce scarcity:Retort processing and blast freezing operations require certified technicians that remain concentrated in South Africa and Gulf urban hubs.
- Multi-jurisdiction labeling compliance:Divergent Arabic-English bilingual requirements between Egypt's EOS protocols and Saudi SFDA standards necessitate SKU-specific packaging runs.
- Legacy cold storage integration:Third-party logistics providers in secondary Nigerian and Kenyan cities operate aging refrigeration assets with inconsistent temperature logging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Ready-To-Eat Food Market |
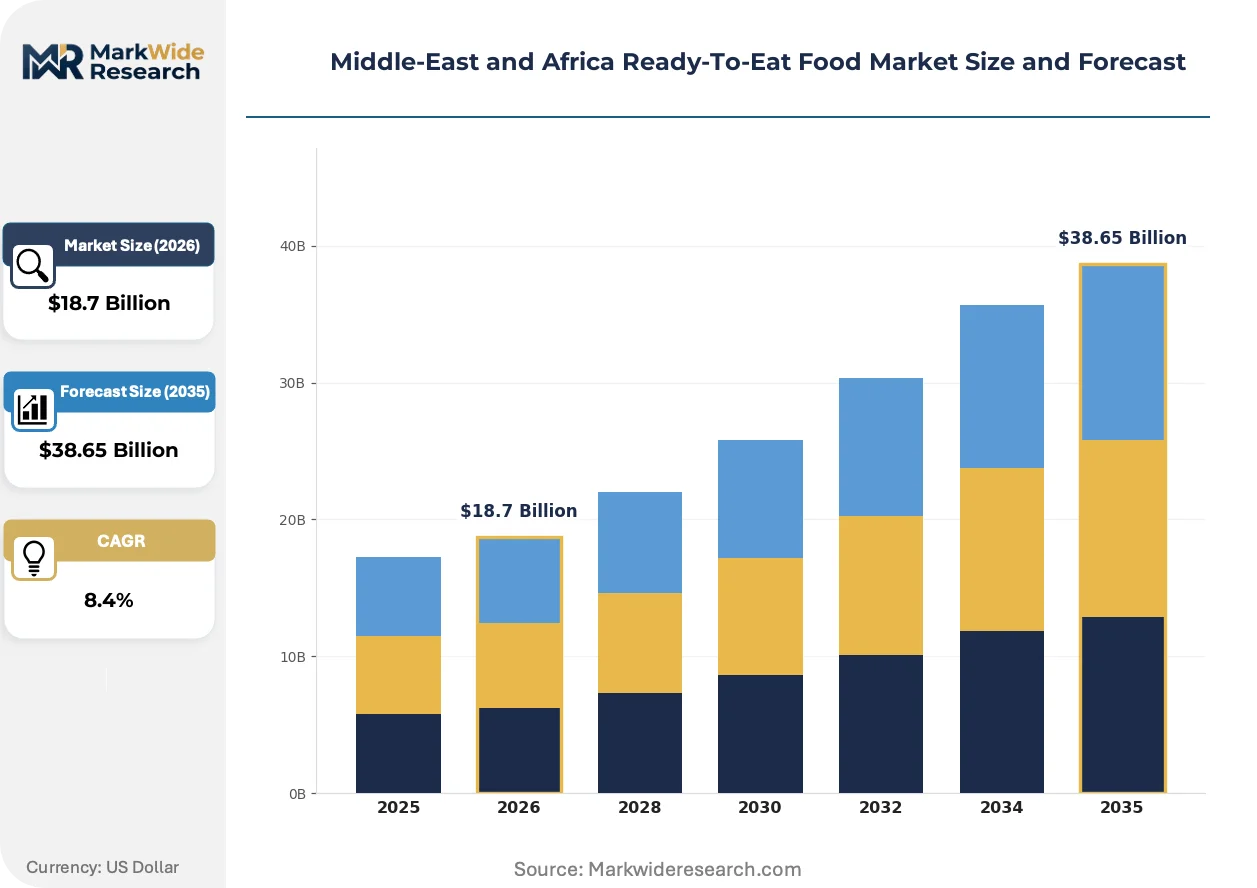
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Meals, Canned Foods, Dried Foods, Snacks Packaging Type: Plastic Containers, Pouches, Cans, Cartons Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service End User: Households, Offices, Educational Institutions, Military |
| Companies Covered | Mondelēz International, Inc., Conagra Brands, Inc., General Mills, Inc., McCain Foods Limited, Nestlé S.A., Unilever PLC, The Kraft Heinz Company, Grupo Bimbo, Almarai Company, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Ready-To-Eat Food Market Shifts & Advancements
Retort pouch technology and modified-atmosphere packaging are compressing shelf-life limitations while smartphone-enabled distribution models are disintermediating traditional wholesale layers across the region's major metropolitan corridors.
Modified-atmosphere packaging is integrating nitrogen-flush and oxygen-scavenger film technologies to extend ambient shelf stability for protein-centric meals without refrigeration dependency. Quick-service restaurant chains in Johannesburg and Cape Town are adopting these formats for back-of-house inventory reduction. The technology is integrating chilled and ambient supply chains into unified distribution networks, collapsing previous format-segregated logistics investments.
Egypt's EOS food safety protocols administered through the national food safety authority are mandating batch-level traceability and additive disclosure thresholds that exceed prior import-era standards. Domestic manufacturers are retrofitting production lines with automated coding systems to satisfy documentary requirements. Pouched seafood and poultry formats face the steepest compliance ramps, with several Egyptian processors pursuing parallel Gulf accreditation to maintain cross-border shipment eligibility.
Smartphone-enabled ordering is consolidating meal-kit procurement into consolidated weekly subscription models among Nairobi and Lagos households with reliable data connectivity. Traditional open-air market vendors and neighborhood convenience stores are losing prepared meal volume to direct-delivery platforms offering refrigerated last-mile fulfillment. Kenyan banking integration with mobile money rails is accelerating this channel shift faster than Nigerian markets where cash-on-delivery still dominates.
Middle-East and Africa Ready-To-Eat Food Market Segmentation
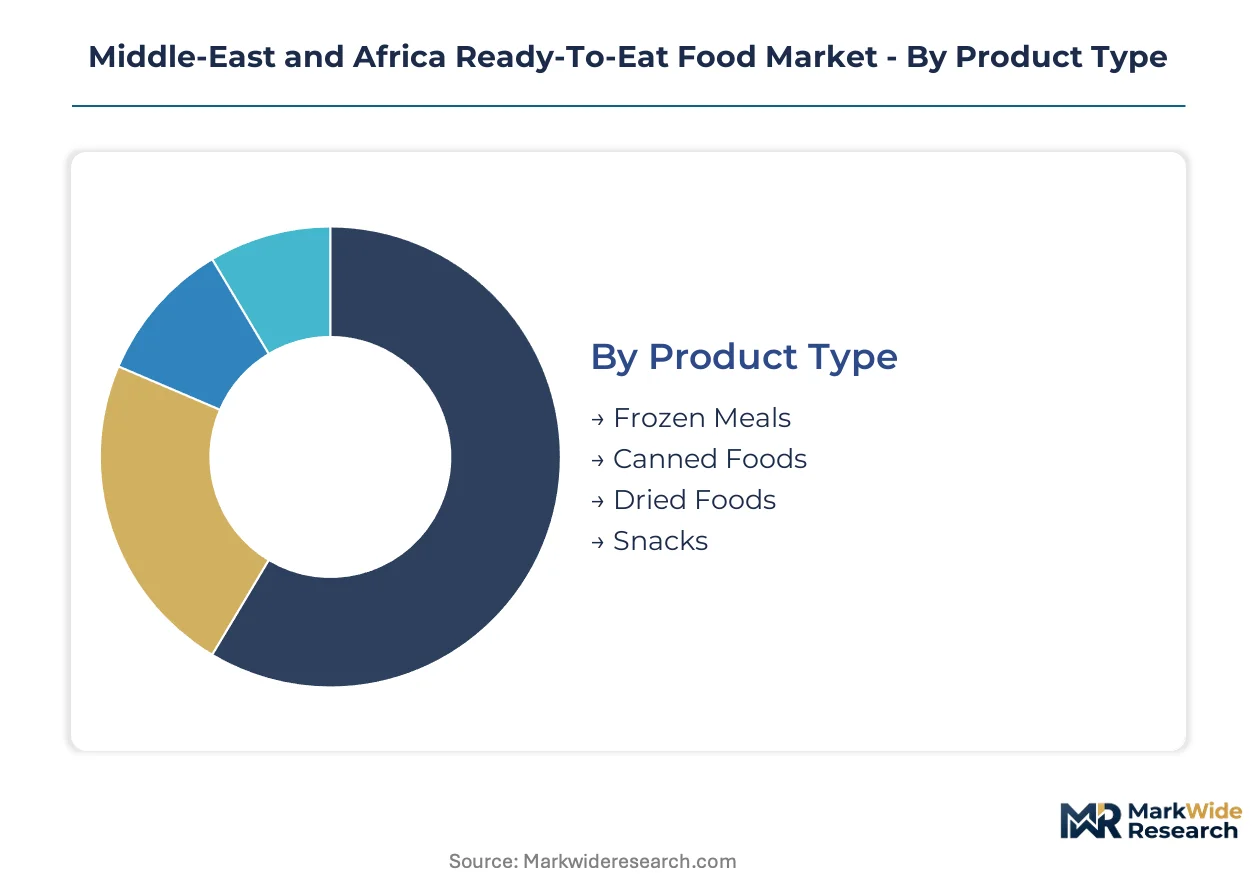
Ready-to-eat food segmentation in the Middle-East and Africa reveals distinct procurement patterns across temperature-controlled and shelf-stable formats. Understanding these divides clarifies where cold chain investments unlock premium positioning versus where ambient distribution achieves mass penetration.
Product Type:
Buyers differentiate primarily by kitchen equipment access and electricity reliability in their consumption environments.
- Frozen Meals:Complete protein-starch-vegetable combinations preserved through blast freezing and distributed via refrigerated logistics. Demand concentrates in South Africa's Gauteng corridor and Gulf urban centers where supermarket freezer density supports weekly stock-up behavior.
- Canned Foods:Retort-processed meals in metal containers offering multi-year ambient stability without cold chain dependency. Nigerian and Kenyan households with intermittent power supply rely on these formats for pantry stocking, particularly in Lagos-Ibadan corridor settlements beyond reliable grid coverage.
- Dried Foods:Dehydrated ingredients and complete meals reconstituted with hot water, favored by camping suppliers and institutional emergency stockpiles.
- Snacks:Single-serve savory and sweet items requiring no preparation, penetrating office vending channels and roadside retail in Moroccan and Egyptian urban clusters.
Frozen meals lead volumes today; pouched ambient formats are gaining share fastest.
Packaging Type:
Material selection tracks format compatibility, shelf-life requirements, and local recycling infrastructure maturity.
- Pouches:Flexible multilayer films with retort or vacuum capabilities enabling flat-pack logistics and microwave readiness. Moroccan and Egyptian production lines are scaling pouch capacity for export to Gulf markets seeking lightweight alternatives to rigid containers.
- Plastic Containers:Rigid polypropylene or polyethylene vessels with resealable lids, dominant in South African retail for multi-serve family formats where refrigerator storage follows purchase.
- Cans:Tinplate or aluminum cylinders with hermetic sealing, standard for fish-based and legume-heavy meal components across North African manufacturing.
- Cartons:Paperboard with polyethylene or aluminum barrier layers, emerging for shelf-stable liquid meals and breakfast cereals in Kenyan supermarket channels.
Pouches lead volumes today; cartons are expanding most quickly.
Distribution Channel:
Channel selection reflects buyer time constraints, digital payment penetration, and last-mile refrigeration availability.
- Online Retail:Smartphone-enabled platforms with refrigerated delivery fleets capturing Lagos and Nairobi professionals seeking subscription-based meal procurement. Kenyan M-Pesa integration accelerates this channel versus Nigerian cash-on-delivery friction.
- Supermarkets:Organized retail with dedicated freezer sections anchoring frozen meal distribution in South Africa and Gulf urban centers, where weekly shopping trips consolidate category purchases.
- Convenience Stores:Small-format neighborhood outlets stocking ambient and chilled grab-and-go items for immediate consumption, prevalent in Egyptian and Saudi dense urban districts.
- Food Service:Direct supply to quick-service restaurants, institutional caterers, and airline meal providers, requiring HACCP-compliant batch documentation under SFDA and EOS protocols.
Supermarkets lead volumes today; online retail is climbing the fastest.
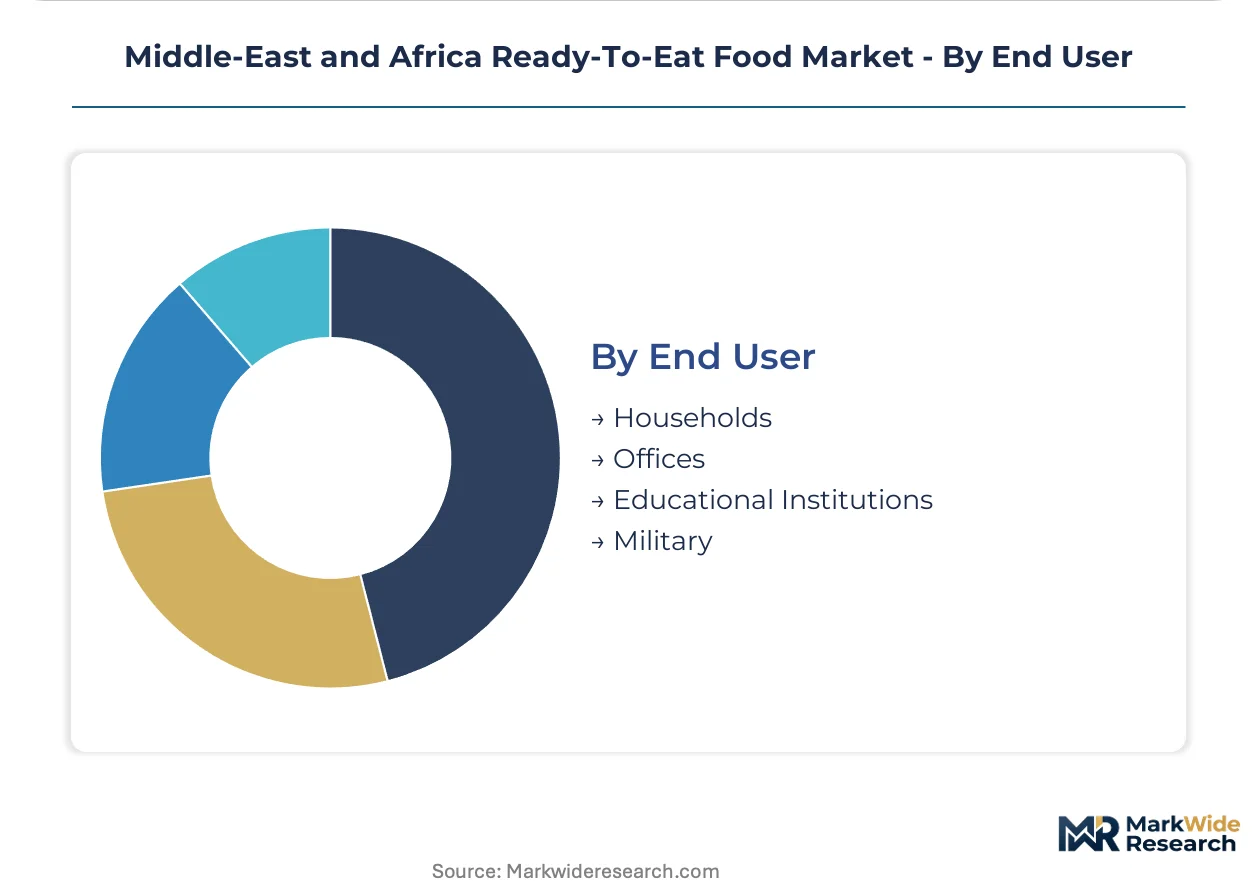
End User:
User segmentation isolates preparation time availability, group feeding scale, and nutritional specification stringency.
- Households:Individual and family units purchasing retail formats for home consumption, with Lagos and Nairobi dual-income households driving demand for reduced-preparation dinner solutions.
- Offices:Corporate facilities and co-working spaces procuring individual-serve lunches for employee cafeterias, concentrated in Johannesburg and Cape Town financial districts.
- Educational Institutions:School and university feeding programs requiring fortified, allergen-labeled formats compliant with South Africa's Department of Health micronutrient mandates.
- Military:Defense procurement agencies specifying extended-shelf-life rations with batch traceability for field deployment across varied climate conditions.
Households lead volumes today; offices are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ready-to-eat food industry traces its regional origins to South Africa's mid-20th century industrial food processing clusters, where blast freezing and retort technologies first achieved commercial scale for domestic distribution and export to neighboring markets.
South Africa
Johannesburg and Cape Town financial districts drive office catering procurement for individually packaged lunches, while Gauteng corridor supermarkets anchor weekly frozen meal stock-up behavior. The Department of Health's updated fortification mandates reshape formulation requirements for pasta-based and protein-fortified formats. Durban-Pinetown manufacturing zones concentrate retort processing capacity serving SADC export markets.
Saudi Arabia
Riyadh and Jeddah urban centers generate concentrated demand for chilled dairy-based prepared meals through captive supermarket networks. SFDA food safety modernization streamlines import clearance protocols for validated Gulf suppliers, compressing time-to-shelf for compliant manufacturers. Eastern Province industrial cities host flexible packaging production lines scaling vacuum-sealed pouch capacity for regional export.
Egypt
Cairo and Alexandria metropolitan households with intermittent power supply rely on canned and pouched ambient formats for pantry stocking beyond reliable grid coverage. EOS food safety protocols administered through the national food safety authority mandate batch-level traceability exceeding prior import-era standards. Nile Delta processing clusters retrofit automated coding systems to satisfy documentary requirements for cross-border Gulf shipments.
Nigeria
Lagos-Ibadan corridor settlements drive shelf-stable prepared meal purchases among young professionals in urban office complexes with limited kitchen equipment access. Cold chain infrastructure improvements enable wider frozen meal distribution into secondary cities previously constrained by refrigerated logistics gaps. Nigerian supermarket chains and smartphone-enabled direct-delivery platforms compete for meal-kit subscription volume in Lagos metropolitan markets.
United Arab Emirates
Dubai and Abu Dhabi expatriate populations sustain demand for multi-cuisine frozen and chilled formats through hypermarket freezer density. MOHAP food safety protocols align with broader Gulf harmonization trends, elevating compliance thresholds for cross-border suppliers. Jebel Ali free zone logistics hubs consolidate re-export distribution to emerging African markets with underdeveloped cold chain infrastructure.
Middle-East and Africa Ready-To-Eat Food Market Competitive Landscape
Capital-heavy producers with captive chilled logistics networks compete with asset-light brand licensors relying on third-party manufacturing and distribution partnerships. The market structure exhibits tiered consolidation: multinational FMCG conglomerates anchor premium retail shelf space, regional dairy processors dominate chilled segments through vertical cold chain control, and local specialists capture ambient format volume in price-sensitive markets. Three archetypes predominate: integrated food processors with in-house R&D and manufacturing, brand houses outsourcing production to contract manufacturers, and dairy-led players leveraging existing refrigerated distribution infrastructure. Dominant competitive moves include strategic partnerships with local logistics providers to extend cold chain reach and portfolio diversification into halal-certified and fortified format variants.
Within the multinational conglomerate tier, Nestlé S.A. and Unilever PLC exemplify brand-licensing strategies leveraging existing Maggi and Nescafé distribution webs to anchor ready-to-eat penetration in Egyptian and Saudi retail channels. Among regional integrated specialists, Almarai Company occupies a position representing dairy-based prepared meal dominance through captive chilled logistics networks across the Arabian Peninsula. McCain Foods Limited sits within the frozen platform extension archetype, exemplifying how African frozen potato infrastructure expands into complete meal kits for South African quick-service restaurant supply.
| Leading Market Players |
|---|
| Mondelēz International, Inc. |
| Conagra Brands, Inc. |
| General Mills, Inc. |
| McCain Foods Limited |
| Nestlé S.A. |
| Unilever PLC |
| The Kraft Heinz Company |
| Grupo Bimbo |
| Almarai Company |
| Others |
Supply & Pricing Matrix
Halal certification tier divergence separates Gulf-validated producers from single-market suppliers, compressing margins for the latter while granting accredited operators pricing power across Saudi SFDA and Egyptian EOS jurisdictions. This bifurcation manifests in supply chain configurations where multi-certified manufacturers consolidate cold chain assets across the Arabian Peninsula, while uncertified competitors remain trapped in spot-market ambient formats with thinner working capital buffers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the market, with halal certification grade and captive cold chain ownership as the primary differentiation drivers. Cost compression in economy-tier pouched formats is intensifying because Moroccan and Egyptian production lines are scaling flexible packaging capacity faster than brand premiumization can absorb. Quick-service restaurants in Johannesburg and Cape Town demonstrate the least price sensitivity due to back-of-house inventory reduction mandates, while Lagos-Ibadan corridor households with intermittent grid access remain acutely sensitive to per-unit packaging costs.
Supply Chain Analysis
Reverse-logistics flows remain underdeveloped for temperature-controlled formats, with expired frozen meal returns concentrated in South African supermarket chains that lack refurbishment partnerships. Supply concentrates in Egypt for retort-processed pouches, Saudi Arabia for chilled dairy-based meals, and South Africa for blast-frozen complete dinners. Wheat and palm oil price volatility constitutes the dominant structural risk, while distribution runs through Jebel Ali free zone hubs for re-export to secondary African markets with underdeveloped cold chain infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where Saudi SFDA food safety modernization and South Africa's Department of Health fortification mandates are elevating compliance costs that simultaneously protect validated incumbents and screen out undercapitalized entrants.
For Market Incumbents: Cement Gulf accreditation reciprocity by pursuing parallel Egyptian EOS and Saudi SFDA validation before African supply jurisdictions mature their halal certification frameworks. Expand captive chilled logistics into Nigeria's Lagos-Ibadan corridor ahead of supermarket freezer density improvements, as third-party cold storage providers in secondary cities operate aging assets with inconsistent temperature logging that threatens brand equity.
For New Entrants and Emerging Players: Enter via smartphone-enabled direct-to-consumer channels in Nairobi and Lagos metropolitan markets where M-Pesa integration and cash-on-delivery rails respectively reduce payment friction versus traditional retail. Target subscription-based meal-kit procurement among dual-income households with reliable data connectivity, leveraging refrigerated last-mile fulfillment partnerships rather than asset-heavy cold chain buildouts.
For Investors and Strategic Acquirers: Consolidation pressure builds where technical workforce scarcity for retort processing and blast freezing operations concentrates certified technicians in South Africa and Gulf urban hubs. Long-term viability favors acquisition targets with in-house laboratory capabilities and existing multi-jurisdiction halal certification, with early signals to monitor including reciprocity agreement announcements between Gulf national accreditation bodies and emerging African supply jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Reciprocity Investment | Parallel EOS and SFDA validation unlocks cross-border shipment eligibility across Gulf and North African markets. |
| Captive Cold Chain Expansion | Direct control over refrigerated logistics in Nigeria and Kenya reduces dependency on aging third-party storage assets. |
| Smartphone-Enabled DTC Launch | M-Pesa and mobile money integration in Kenyan and Nigerian markets disintermediates traditional wholesale layers. |
| Fortification Partnership Development | Collaboration with micronutrient suppliers satisfies South Africa's Department of Health formulation mandates. |
| Flexible Packaging Scale-Up | Vacuum-sealed and controlled-atmosphere pouch capacity expansion in Morocco and Egypt enables format diversification. |
Research Methodology
Coverage spans the Middle-East and Africa region, with primary inputs from each major national market combining structured interviews with retail category buyers, cold chain logistics operators, food safety compliance officers, and quick-service restaurant procurement managers alongside secondary validation. Trade customs data, national food safety authority disclosure filings, supermarket chain annual reports, and mobile money transaction aggregators were triangulated against bottom-up production capacity surveys and top-down consumption estimates.
Rate-of-change decomposition across the analysis window isolates volume drivers from price effects, with segmentation modeling across product type, packaging format, distribution channel, and end-user category. CAGRs were derived from fitted trend extrapolation adjusted for regulatory milestone impacts, incorporating cold chain infrastructure investment pipelines, halal certification reciprocity negotiation timelines, and smartphone penetration trajectories as industry-specific forecast inputs.
Inputs from retail audit databases and national regulator disclosure filings were available through the study window; gaps in real-time cold chain temperature logging data from secondary Nigerian and Kenyan cities introduce uncertainty bands around frozen meal distribution reach estimates. Practitioners should monitor Gulf Cooperation Council food safety harmonization announcements and African national accreditation body reciprocity agreements for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
United Arab Emirates Food Products Market
Packaged Foods
Instant Cereals Market
Packaged Foods
India Instant Noodles Market
Packaged Foods
Instant Ramen Market
Packaged Foods
Fat Free Pasta Market
Packaged Foods
US Packaged Salads Market
Packaged Foods
Dinner Ready-To-Eat (RTE) Food Market
Packaged Foods
Packaged Salad Market
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market
Packaged Foods
Packaged Food Market
Packaged Foods
Singapore Ready-To-Eat Food Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
India Packaged Food Products Market
Packaged Foods
Plant Focused Dips Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
North America Instant Noodles Market