
 Cereal Flakes Market | 2026-2036
Cereal Flakes Market Size, Share, and Industry Trends Forecast 2026-2036
Cereal Flakes Market Outlook
The health-conscious consumer segment is broadening its share of cereal flake consumption as protein-fortified and reduced-sugar formulations gain shelf space. Nestlé (Nestlé Cereals) leverages its European R&D network to develop clean-label recipes that meet tightening ingredient disclosure rules. General Mills sustains North American market presence through its supply chain scale and longstanding retail partnerships. Post Holdings differentiates via specialty and organic sub-lines that command premium positioning in conventional grocery channels.
Cereal flakes are processed, flattened grain products typically manufactured through steaming, rolling, and toasting operations, with moisture content and flake thickness calibrated to achieve target crispness and rehydration rates; they serve as ready-to-eat breakfast items and snack bases across retail and foodservice channels. Corn flakes occupy the largest volume share among product types due to established consumer familiarity and cost-efficient maize sourcing, while bran flakes capture expanding margin pools as fiber-content claims resonate with aging populations. Online retail distribution is growing fastest among channels, though supermarkets still control the majority of physical volume and promotional placement.
The FDA governs nutrition labeling and health claim substantiation for cereal products sold in the United States, while the EU Green Deal and EFSA standards push manufacturers toward reduced environmental footprints and verified ingredient provenance across European markets. India's FSSAI enforces fortification mandates and additive limits that shape local formulation decisions for domestic and export-bound production. Stakeholders must monitor evolving sugar taxation frameworks and front-of-pack labeling requirements as these regulatory instruments increasingly determine which formulations secure retail access and consumer preference.
Market Dynamics
Clean-label mandates from the EU Green Deal and EFSA standards are forcing cereal manufacturers to reformulate around reduced sugar, verified grain provenance, and additive transparency before products reach retail shelves.
Growth Catalysts
- Fortification mandates:India's FSSAI requires micronutrient enrichment in mass-market cereals, opening formulation service contracts to ingredient technology providers.
- Protein extraction advances:Extrusion and enzymatic processing now integrate legume and dairy proteins into flake matrices without compromising texture.
- Urban convenience demand:Working households in Germany and the United States prioritize single-serve and resealable packaging formats for morning consumption routines.
Market Restraints
- Maize price volatility:Corn flakes production depends on North American and Brazilian harvest cycles, exposing margin structures to commodity futures swings.
- Sugar taxation creep:The United Kingdom's Soft Drinks Industry Levy and similar frameworks in Mexico and South Africa threaten shelf placement for legacy formulations.
- Private-label concentration:Supermarket chains in France and Spain now control one-third of European volume, compressing branded pricing power.
Strategic Opportunities
- Clean-label premiums:EFSA-verified short ingredient lists command 15-40% price multiples in German and Dutch organic retail channels.
- Direct-to-consumer subscriptions:Customizable flavor and nutrition bundles bypass conventional grocery slotting fees while capturing recurring revenue.
- Upcycled grain streams:Brewers' spent grain and broken rice fractions from milling operations reduce raw material costs and waste footprints simultaneously.
Industry Challenges
- Reformulation timeline compression:Front-of-pack labeling deadlines in France and Belgium leave less than 18 months to reformulate and re-register existing SKUs.
- Extrusion equipment retrofit costs:Legacy flake lines require capital-intensive upgrades to handle alternative proteins and reduced moisture profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cereal Flakes Market |
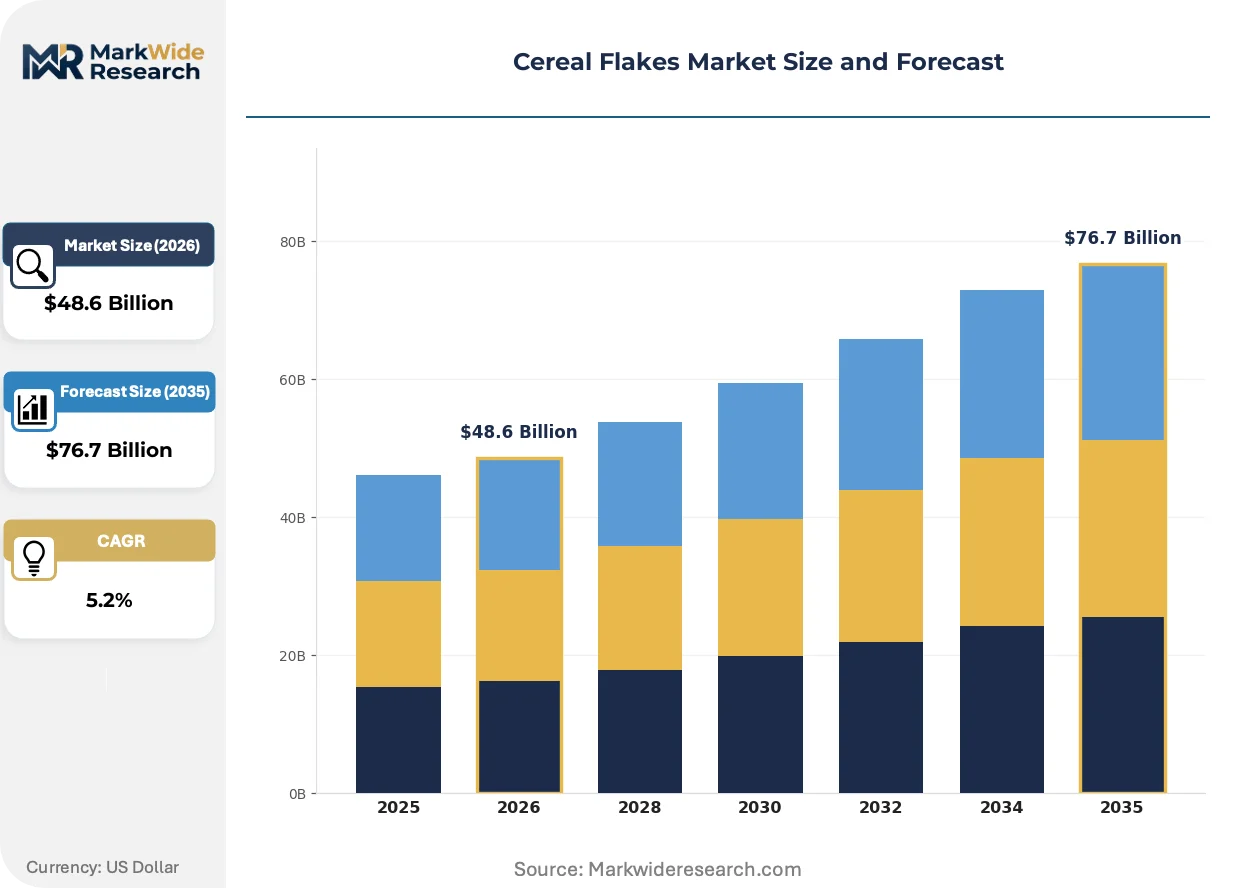
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $76.7 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn Flakes, Rice Flakes, Wheat Flakes, Bran Flakes End User: Children, Adults, Seniors, Health-Conscious Consumers Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers Packaging Type: Bags, Boxes, Tubs, Pouches |
| Companies Covered | Kellogg Company, Nestlé (Nestlé Cereals), General Mills, PepsiCo (Quaker Oats), Post Holdings, H. & J. BRÜGGEN KG, Bagrry India Pvt. Ltd., Calbee Inc., Marico Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cereal Flakes Market Strategic Shifts
Formulation science and distribution architecture are converging to redefine how cereal flakes reach consumers, with technology providers and regulatory frameworks racing to set the terms of next-generation product development.
Soluble fiber prebiotics and resistant starch technologies are expanding into mainstream flake formulations as gut-health positioning migrates from pharmacy supplements to breakfast aisles. European manufacturers in the Netherlands and Denmark lead adoption, integrating chicory root inulin and modified wheat starches into extruded bases. The structural consequence is a compression of the functional food boundary, with conventional cereal brands now competing directly against digestive health specialists.
EFSA's evolving guidance on nutrition and health claims is tightening evidentiary standards for fiber-related marketing statements across European markets. Manufacturers must now commission human intervention studies or withdraw specific benefit language from packaging and digital campaigns. Bran flake and whole-grain segments face the steepest compliance burden, as historical claims around cholesterol management and glycemic response require retrospective substantiation.
Subscription-based replenishment models are displacing conventional pantry stocking cycles among millennial and Generation Z households in the United States and United Kingdom. Direct-to-consumer platforms offer flavor rotation, portion calibration, and sustainability credentials that supermarket assortments cannot match. This behavioral pivot is most pronounced in coastal metropolitan clusters where delivery density supports unit economics and brand community building.
Cereal Flakes Market Segmentation
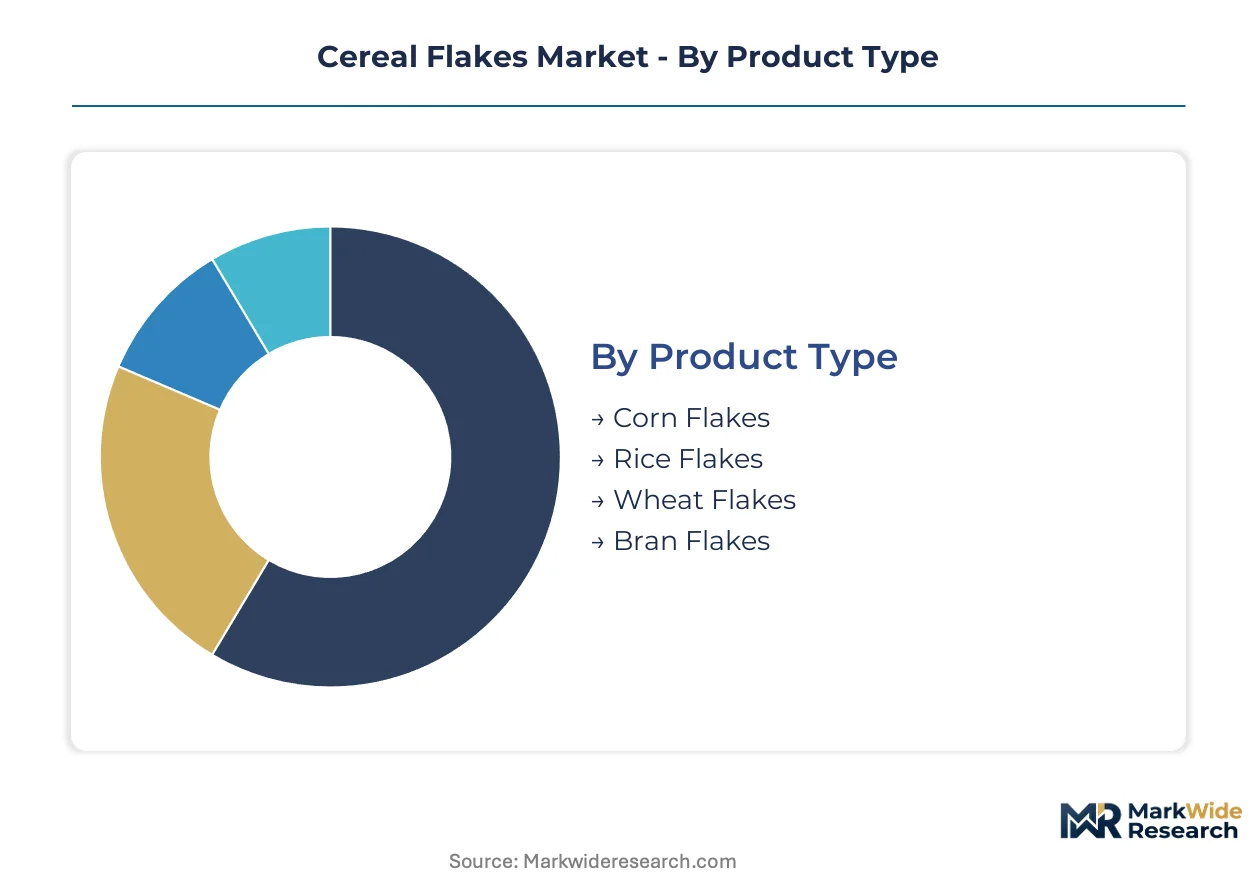
Segmentation in cereal flakes reveals how formulation choices, age-targeted nutrition, and channel economics fragment demand across distinct buyer profiles. Manufacturers calibrate moisture content, fortification levels, and packaging formats to match the consumption rituals and price sensitivity of each defined group.
Product Type:
Cost tier determines raw material sourcing and margin structure across flake varieties.
- Corn Flakes:Maize-based formulations achieve the lowest per-unit ingredient costs through established North American and Brazilian supply chains. Volume concentrates in the United States and Germany where price-sensitive households prioritize breakfast economy over nutritional density.
- Bran Flakes:Wheat bran and fiber-dense recipes command shelf space in aging European markets where digestive health claims drive purchase decisions. Dutch and Danish manufacturers lead clean-label integration of resistant starches and prebiotic fibers.
- Rice Flakes:Gluten-free positioning captures specialty diet adherence in urban Indian and German markets.
- Wheat Flakes:Whole-grain credentials serve mid-tier positioning between commodity corn and premium bran segments.
Volume sits with corn flakes; growth tilts toward bran flakes.
End User:
Application context shapes fortification intensity and flavor profiles.
- Adults:Working-age households in Germany and the United States drive single-serve and resealable format adoption. Protein integration and reduced-sugar mandates from EFSA and FDA reshape adult-targeted formulations.
- Health-Conscious Consumers:Chicory root inulin, resistant starch, and verified grain provenance command 15-40% price premiums in Dutch organic retail channels. Clean-label verification from EFSA-compliant short ingredient lists determines shelf access.
- Children:Fortification mandates from India's FSSAI require micronutrient enrichment in mass-market cereals bound for pediatric consumption.
- Seniors:Fiber density and low glycemic response positioning align with pharmacy-adjacent retail placement in aging European demographics.
Adult households generate baseline volume; health-conscious consumers are climbing the fastest.
Distribution Channel:
Customer type fragments between stock-up pantry loading and immediate consumption needs.
- Supermarkets:Control majority physical volume and promotional placement across the United States, Germany, and India. Slotting fees and category management agreements favor established brands with supply chain scale.
- Online Retail:Subscription replenishment models displace conventional stocking cycles among millennial and Generation Z households in coastal United States and United Kingdom metropolitan clusters.
- Convenience Stores:Single-serve impulse purchases concentrate in urban Indian and German transit corridors.
- Wholesalers:Bulk institutional supply serves foodservice and hospitality channels in price-sensitive developing markets.
Supermarkets anchor current volume; online retail shows steepest expansion trajectory.
Packaging Type:
Volume scale and resealability requirements differentiate format economics.
- Boxes:Standard rectangular cartons dominate pantry-stocking households in the United States and Germany. Structural rigidity protects flake integrity through multi-touch supply chains.
- Pouches:Flexible films with zip-lock closures command premium positioning in direct-to-consumer subscription channels. Reduced material weight aligns with EU Green Deal packaging waste directives.
- Bags:Value-oriented bulk formats serve price-sensitive Indian and German discount retail.
- Tubs:Rigid resealable containers target countertop convenience in high-frequency consumption households.
Boxes hold installed volume; pouches gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Gujarat and Maharashtra accelerate contract manufacturing concentration for export-bound cereal production. India's Production Linked Incentive scheme for food processing draws multinationals toward dedicated flake lines. Urban consumption corridors in Mumbai, Delhi-NCR, and Bangalore anchor domestic offtake velocity.
United States
Single-serve convenience formats dominate morning consumption rituals in working households across coastal metropolitan clusters. FDA nutrition labeling revisions force reformulation timelines for legacy sugar-heavy recipes. Chicago and Minneapolis-St. Paul anchor R&D and extrusion equipment manufacturing corridors serving North American supply networks.
Germany
Clean-label verification commands 15-40% price multiples in Dutch and German organic retail channels. EU Green Deal packaging waste directives accelerate pouch-format adoption against conventional box structures. Cologne and Hamburg concentrate contract manufacturing capacity for private-label penetration across French and Spanish discount chains.
India
FSSAI fortification mandates require micronutrient enrichment in mass-market cereals bound for pediatric and adult consumption. Production Linked Incentive schemes for food processing attract greenfield extrusion investments in Gujarat and Maharashtra. Bangalore and Delhi-NCR drive premium bran flake adoption among health-conscious urban professionals.
United Kingdom
Soft Drinks Industry Levy extension threatens shelf placement for legacy high-sugar formulations across conventional grocery. Subscription replenishment models displace pantry stocking cycles among millennial households in London and Manchester metropolitan clusters. Direct-to-consumer platforms capture recurring revenue through flavor rotation and sustainability credential bundling.
Netherlands
EFSA-verified short ingredient lists determine organic retail access across German and Dutch distribution networks. Chicory root inulin and resistant starch integration leads adoption in extruded base formulations. Rotterdam and Amsterdam anchor ingredient technology provider clusters serving European clean-label reformulation demand.
Cereal Flakes Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with multinational consumer goods conglomerates commanding supermarket slotting agreements while regional millers capture private-label volume. The vendor base organizes around three strategic archetypes: diversified food conglomerates with R&D scale, family-owned European millers with clean-label heritage, and Asian contract manufacturers with cost-optimized extrusion capacity. M&A activity concentrates on specialty organic lines and direct-to-consumer platform acquisitions. Geographic expansion into Indian and Southeast Asian urban corridors represents the dominant competitive move.
Within the diversified conglomerate tier, Kellogg Company and General Mills occupy positions defined by North American supply chain scale and longstanding retail partnership density. Nestlé anchors European clean-label development through its Switzerland-based R&D network and EFSA compliance infrastructure. Post Holdings exemplifies the specialty acquisition archetype, with portfolio diversification into organic and high-protein sub-lines commanding premium positioning. H. & J. BRÜGGEN KG represents the family-owned miller segment with German heritage in verified grain provenance and short-ingredient-list formulations.
| Leading Market Players |
|---|
| Kellogg Company |
| Nestlé (Nestlé Cereals) |
| General Mills |
| PepsiCo (Quaker Oats) |
| Post Holdings |
| H. & J. BRÜGGEN KG |
| Bagrry India Pvt. Ltd. |
| Calbee Inc. |
| Marico Ltd. |
| Others |
Value Chain & Pricing Dynamics
Extrusion equipment operators in the Cologne-Hamburg corridor command wage premiums that compress margin spreads between premium clean-label and economy corn flake tiers. Labor-cost differentials between German contract manufacturers and Indian greenfield facilities widen pricing-tier spreads by 15-40% across organic and conventional segments.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with German manufacturers extracting 15-40% markups for EFSA-verified clean-label formulations against spot-market Indian bulk supply. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and grain provenance verification. Pricing pressure stems from private-label concentration in French and Spanish supermarket chains. Price-sensitive volume buyers in Indian discount retail show highest elasticity, while Dutch organic channel purchasers exhibit lowest sensitivity.
Supply Chain Analysis
Maize supply rests on North American and Brazilian harvest cycles, with wheat bran sourcing anchored in European milling corridors. Corn grits, wheat bran, and rice broken fractions constitute the primary input dependencies. Single-source vulnerability concentrates in Brazilian maize exports exposed to climate volatility. Distribution runs through supermarket chain category management agreements in Germany and the United States, with direct-to-consumer subscription platforms capturing coastal metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cereal flakes sector sits in a formulation technology transition, with enzymatic protein integration and resistant starch extrusion displacing legacy high-sugar, low-fiber recipes.
For Market Incumbents: Acquire specialty organic flake lines and direct-to-consumer subscription platforms to preempt private-label erosion. Nestlé and General Mills should consolidate EFSA-compliant clean-label capacity in the Netherlands and Germany before front-of-pack labeling deadlines compress reformulation timelines. Vertical integration into chicory root inulin supply secures prebiotic fiber access against ingredient cost volatility. For New Entrants and Emerging Players: Direct-to-consumer channel partners in London and Manchester metropolitan clusters offer the most penetrable entry vector. White-space targets include customizable protein-fortified bundles for millennial households and upcycled grain formulations leveraging brewers' spent grain streams. A sustainability-credential-first go-to-market angle bypasses conventional grocery slotting fee barriers. For Investors and Strategic Acquirers: Re-rating potential sits with family-owned European millers with verified grain provenance heritage given EU Green Deal packaging waste directives accelerating clean-label premiums. Long-term viability favors asset-light subscription platform operators with recurring revenue models over capital-intensive extrusion equipment owners. Watch FSSAI fortification mandate enforcement in India as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | EFSA compliance infrastructure secures shelf access in German and Dutch organic retail channels. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models capture recurring revenue from millennial households in coastal United States clusters. |
| Alternative Protein Integration | Extrusion technology upgrades enable legume and dairy protein incorporation without texture compromise. |
| Upcycled Grain Supply Agreement | Brewers' spent grain contracts reduce raw material costs and align with EU Green Deal waste reduction targets. |
| Private-Label Manufacturing Expansion | Cologne and Hamburg contract capacity serves French and Spanish supermarket chain volume concentration. |
Study Parameters
Multi-period observation of FSSAI fortification compliance rates, EFSA clean-label certification volumes, and direct-to-consumer subscription growth anchored the trend analysis, supplemented by interviews with extrusion equipment manufacturers, cereal brand managers, supermarket category buyers, and ingredient technology providers. Secondary validation drew from Nielsen retail audit data, EU customs trade records, FDA nutrition labeling filings, and FSSAI additive registry updates. Bottom-up SKU-level volume aggregation and top-down category spend analysis provided triangulation.
Input-output matrices modeled maize and wheat bran price elasticity, extrusion capacity utilization, and channel mix shifts across the projection horizon. Segmentation dimensions included product type, end-user nutrition profile, distribution channel, and packaging format. CAGRs derived from historical volume trajectories adjusted for regulatory intervention timing and technology adoption S-curves. Forecast inputs incorporated India's PLI scheme investment flows and EU Green Deal packaging directive implementation schedules.
Caveats apply where sugar taxation framework extensions, front-of-pack labeling deadline accelerations, or maize harvest disruptions could materially shift the outlook. Forecasts reflect assumptions around reformulation cost pass-through rates and subscription model retention curves. A small set of named triggers—FSSAI enforcement intensity, EFSA health claim substantiation rulings, and Brazilian climate patterns—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
US Canned Foods Market
Packaged Foods
Brio Bowls Market
Packaged Foods
Global Packed Food Market
Packaged Foods
Japan Packaged Food Products Market
Packaged Foods
US Packaged Salads Market
Packaged Foods
Cocoa Fillings Market
Packaged Foods
Bangladesh Instant Noodles Market
Packaged Foods
Ready-To-Eat Food Market
Packaged Foods
Europe Food Spread Market
Packaged Foods
Fruit Filling Market
Packaged Foods
Packaged Sprouts Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
Tortilla Market
Packaged Foods
Instant Rice Market
Packaged Foods
Australia Food Cans Market
Packaged Foods
India Breakfast Cereals Market