
 Cocoa Fillings Market | 2026-2036
Cocoa Fillings Market Size, Share, and Industry Trends Forecast 2026-2036
Cocoa Fillings Market Outlook
Premium single-origin specification tiers is bifurcating the competitive landscape into craft-oriented and commodity-scale suppliers. Barry Callebaut leverages its bean-to-fillings infrastructure to control origin traceability across multiple continents. The Hershey Company anchors North American volume through proprietary milk chocolate filling formulations. Cargill Inc. competes on cocoa butter equivalent innovation for cost-optimized compound applications.
Cocoa fillings denote semi-fluid or pumpable preparations containing cocoa mass, cocoa butter, sugar, and emulsifiers, formulated to specific yield values and viscosity profiles for injection, depositing, or enrobing operations. Their primary purpose is to deliver standardized chocolate flavor and texture in industrial food manufacturing where whole chocolate would create processing inefficiencies. Dark chocolate fillings lead in premium positioning due to higher cocoa solids content and clean-label appeal among artisan chocolatiers. Milk chocolate formulations dominate volume in baked goods applications where milder flavor profiles and lower cost points align with mass-market bakery requirements. Compound chocolate segments occupy the value tier, substituting vegetable fats for cocoa butter to serve price-sensitive snack and confectionery channels.
FDA standards for chocolate identity and USDA organic certification govern product labeling and ingredient disclosure in the United States. The EU's REACH framework and EFSA food additive evaluations shape emulsifier approvals and migration limits for cocoa-based preparations sold across member states. Stakeholders must monitor evolving deforestation due diligence enforcement in both jurisdictions, as supply chain documentation requirements will determine market access for non-compliant sourcing origins.
Market Dynamics
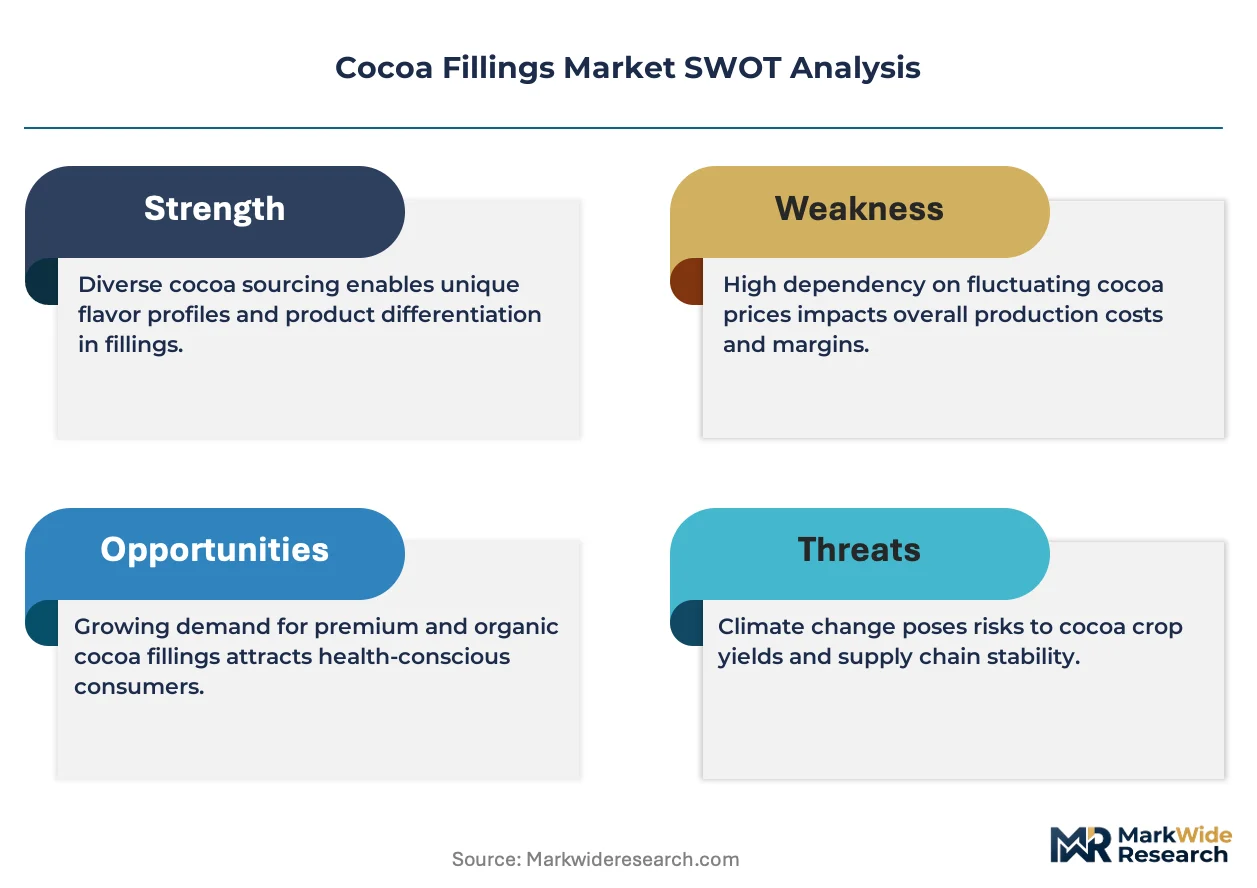
The EU Green Deal's due diligence rules on deforestation-free supply chains are forcing processors to rebuild procurement infrastructure around traceable bean-to-fillings documentation. This regulatory pressure concentrates compliance costs on mid-tier suppliers lacking integrated origin control.
Growth Catalysts
- EU Deforestation Regulation:Mandatory geolocation and traceability requirements for cocoa entering European markets are accelerating investment in certified supply chains. Industrial bakers in Germany's automated corridor now specify EUDR-compliant fillings as a procurement condition.
- Single-origin specification tiers:Artisan chocolatiers in Belgium and France are contracting directly with bean-to-bar processors for terroir-designated fillings. This vertical sourcing pattern pulls premium volumes away from commodity distributors.
- Clean-label emulsifier innovation:Lecithin-free and reduced-additive formulations are capturing shelf-space in organic retail channels. EFSA evaluations of novel emulsifiers are expanding the approved ingredient toolkit for clean-label positioning.
Market Restraints
- Cocoa butter price volatility:Futures markets for cocoa butter have exhibited extreme swings, compressing margin predictability for filling manufacturers locked into annual supply contracts with industrial bakery customers.
- West African supply concentration:Over seventy percent of global cocoa bean origination clusters in Côte d'Ivoire and Ghana, creating geopolitical and climate-exposure risk that no alternative origin has scaled to offset.
- Compound chocolate substitution:Vegetable-fat-based compounds are displacing cocoa butter fillings in price-sensitive snack applications, particularly in emerging markets where local processors optimize for cost per kilogram.
Strategic Opportunities
- Latin American origin expansion:Ecuador and Peru are developing fine-flavor cocoa volumes with established organic certification infrastructure. European premium brands are piloting direct-trade programs in these origins to diversify beyond West African dependence.
- Plant-based confectionery convergence:Dairy-free milk chocolate fillings formulated with oat or rice protein bases are capturing vegan and flexitarian demand in UK and German retail channels.
- Carbon accounting integration:The EU's Corporate Sustainability Reporting Directive is mandating Scope 3 emissions disclosure. Fillings suppliers with verified low-carbon bean sourcing can capture preferential positioning with ESG-committed food manufacturers.
Industry Challenges
- Traceability system integration:Mapping individual farm polygons to batch-lot fillings requires GPS-enabled cooperative management systems that many West African suppliers lack capital to deploy before EUDR enforcement deadlines.
- Viscosity calibration at scale:Automated enrobing lines in industrial baking demand yield-value consistency across temperature ranges. Achieving this precision with single-origin cocoa of varying fat content strains formulation teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocoa Fillings Market |
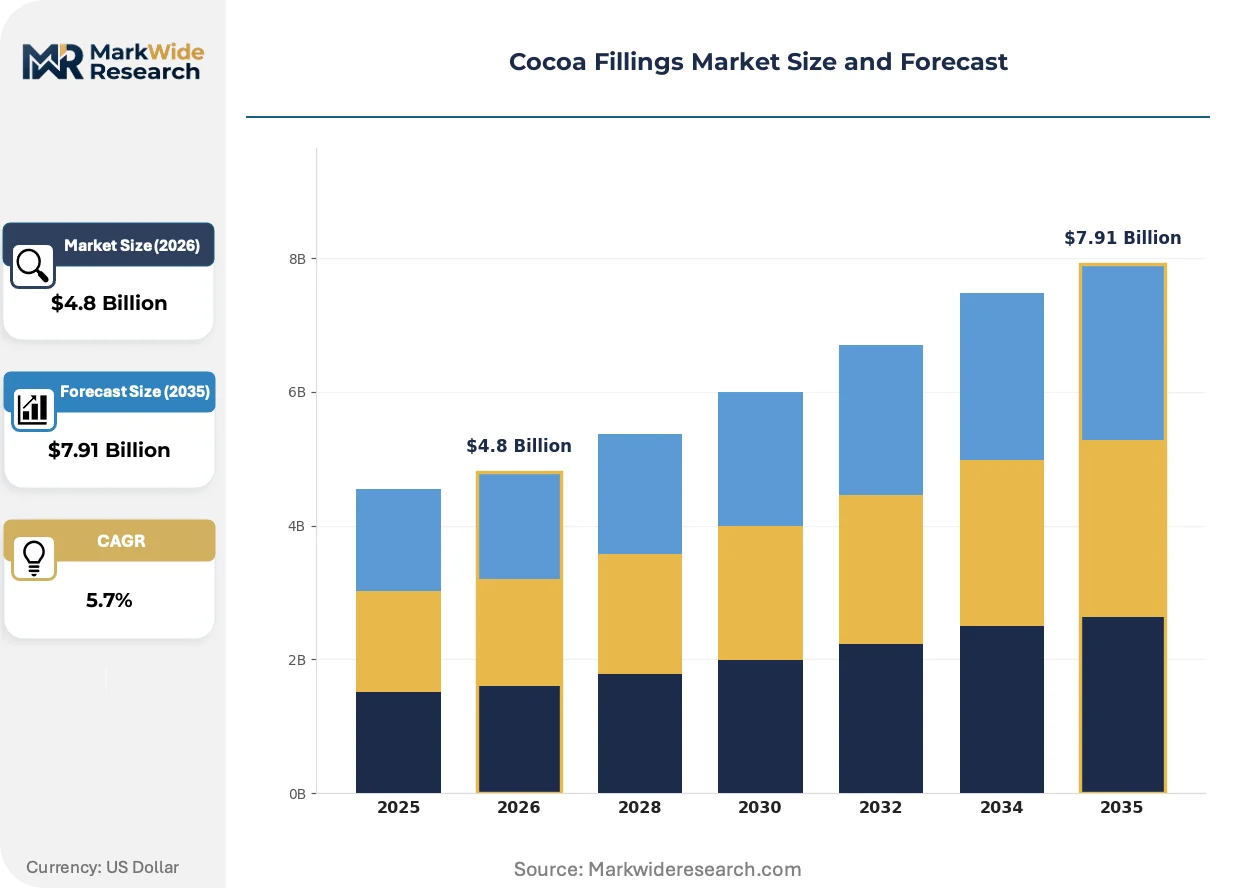
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Compound Chocolate Application: Creams, Confectionery, Baked Goods, Snacks End User: Bakeries, Chocolatiers, Food Manufacturers, Retail Outlets Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Tate & Lyle PLC, Nestlé S.A., Barry Callebaut, Ferrero Group, Mondelēz International, Archer Daniels Midland Company, Clasen Quality Coatings, The Hershey Company, Cargill Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocoa Fillings Market Strategic Shifts
Digital traceability infrastructure and precision fermentation are decomposing traditional boundaries between commodity and premium supply tiers. These forces are compressing the historical lag between origin innovation and industrial-scale adoption.
Precision fermentation-derived cocoa butter alternatives are decomposing the cost structure of premium filling formulations. Specialty ingredient startups in California and the Netherlands are scaling microbial lipid production that mimics cocoa butter's crystallization behavior. Industrial chocolatiers in Germany are trialing these alternatives for compound applications where cost optimization outweighs origin storytelling.
REACH framework updates on food contact migration limits are tightening emulsifier specifications for cocoa-based preparations sold across EU member states. ECHA evaluations of glycerol-based additives are creating compliance windows for novel stabilizer technologies. Swiss and Belgian processors are reformulating enrobing-grade fillings to preempt regulatory friction in their largest export market.
Direct-procurement contracts between artisan chocolatiers and origin cooperatives are shortening traditional distribution chains. Belgium's premium bonbon houses now specify harvest-lot traceability as a standard procurement term. This pattern concentrates volume with integrated bean-to-fillings processors capable of documenting farm-level provenance.
Cocoa Fillings Market Segmentation
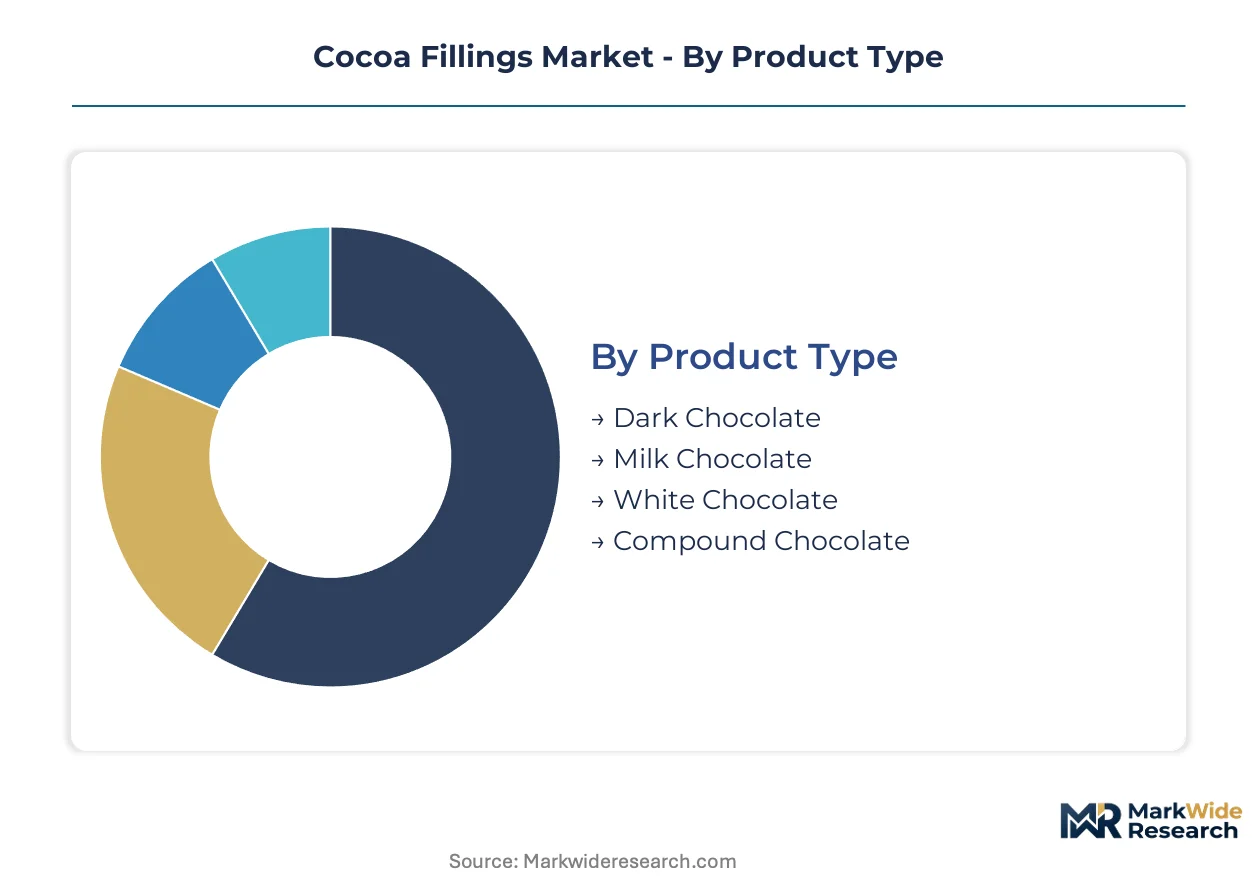
Cocoa fillings stratify across four critical dimensions that determine procurement patterns, margin structures, and regulatory exposure. Product type and application segments exhibit divergent geographic demand centers, while end-user and channel configurations reflect contrasting supply chain integration levels across industrial and artisan production modes.
Product Type:
Dark chocolate and milk chocolate formulations anchor export-led demand from European premium brands, while compound chocolate serves price-sensitive domestic markets in emerging economies. White chocolate occupies a narrower international niche tied to seasonal confectionery programs.
- Dark Chocolate:Higher cocoa solids content (45-70%) delivers pronounced terroir expression for single-origin bonbon lines. Belgian and French artisan chocolatiers specify harvest-lot traceability for EUDR-compliant dark fillings, though cocoa butter price volatility compresses formulation margins.
- Milk Chocolate:Proprietary milk powder ratios and reduced cocoa butter content optimize for industrial baking scale. Germany's automated enrobing corridor specifies viscosity-calibrated milk chocolate fillings where milder flavor profiles align with mass-market bakery requirements.
- White Chocolate:Cocoa butter-dominant composition with milk solids and vanilla positioning for premium confectionery applications.
- Compound Chocolate:Vegetable fat substitution for cocoa butter serves cost-optimized snack channels in price-sensitive markets.
Milk chocolate holds the largest share; momentum sits with dark chocolate as clean-label positioning accelerates premium procurement.
Application:
Cost tier differentiation separates high-specification enrobing applications from commodity snack coating, with baked goods occupying the mid-tier volume position.
- Creams:Pumpable viscosity profiles formulated for injection and depositing operations in layered dessert manufacturing.
- Confectionery:Tempered crystallization control for molded pralines and enrobed centers defines technical specifications. Swiss and Belgian processors dominate this premium segment through integrated bean-to-fillings infrastructure.
- Baked Goods:Yield-value stability across temperature ranges enables automated production lines. Industrial bakers in Germany's corridor specify annual supply contracts with viscosity guarantees, locking processors into margin compression during cocoa butter price spikes.
- Snacks:Compound-based coatings for cereal bars and biscuit enrobing prioritize cost per kilogram over origin documentation.
Baked goods command the greatest volume; confectionery delivers the steepest expansion trajectory as premiumization reshapes European procurement.
End User:
Customer type determines specification intensity, with food manufacturers driving standardization and chocolatiers demanding batch-level provenance.
- Bakeries:Industrial and artisan segments split between automated enrobing compatibility and hand-piping workability requirements.
- Chocolatiers:Direct-trade contracting with origin cooperatives now specifies harvest-lot documentation as standard procurement terms in Belgium and France.
- Food Manufacturers:Scale procurement through annual tenders prioritizes yield consistency and regulatory compliance documentation for EUDR and FDA submissions.
- Retail Outlets:Private-label fillings for in-house bakery and confectionery operations concentrate in supermarket chains with centralized procurement.
Food manufacturers absorb the largest volume; chocolatiers are gaining share fastest as vertical sourcing patterns disintermediate commodity distributors.
Distribution Channel:
Supply concentration varies dramatically by channel, with wholesale maintaining captive relationships to industrial processors and online retail fragmenting toward specialty ingredient platforms.
- Online Retail:Specialty ingredient platforms serve artisan chocolatiers and small-batch bakeries with minimum-order quantities and technical documentation portals.
- Supermarkets:Private-label filling programs for in-house bakery operations run through centralized procurement with standardized specifications.
- Specialty Stores:Gourmet food retailers stock single-origin and organic-certified fillings for home confectionery and professional kitchen segments.
- Wholesale:Industrial distributors maintain bulk tanker and intermediate bulk container logistics for food manufacturer accounts with just-in-time delivery requirements.
Wholesale retains dominant volume; online retail is climbing the fastest as direct-procurement platforms shorten traditional distribution chains for artisan end users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seventy percent of global cocoa bean origination clusters in Côte d'Ivoire and Ghana, yet industrial processing and premium consumption concentrate in Western Europe and North America. Regulatory divergence between EUDR-mandated traceability and FDA identity standards is fragmenting procurement infrastructure across jurisdictions.
Germany
Industrial bakers in Germany's automated corridor specify viscosity-calibrated fillings for enrobing lines. The EU Green Deal's due diligence rules are accelerating EUDR-compliant supply chain investments. Cologne and Hamburg host integrated bean-to-fillings processors serving annual contracts with yield-value guarantees.
United States
FDA standards for chocolate identity govern labeling while USDA organic certification drives clean-label procurement. The Hershey Company anchors North American volume through proprietary milk chocolate formulations. Pennsylvania and Illinois concentrate compound chocolate production for cost-optimized snack channels.
Belgium
Artisan chocolatiers in Brussels and Antwerp contract directly with bean-to-bar processors for terroir-designated fillings. EFSA evaluations of novel emulsifiers are expanding approved ingredient toolkits for clean-label positioning. Premium bonbon houses now specify harvest-lot traceability as standard procurement terms.
Switzerland
Swiss processors dominate premium confectionery segments through integrated bean-to-fillings infrastructure. REACH framework updates on food contact migration limits are tightening emulsifier specifications for EU-bound exports. Zurich and Geneva concentrate R&D facilities for precision viscosity control in enrobing applications.
France
Single-origin specification tiers are pulling premium volumes away from commodity distributors in Paris and Lyon. The EU Deforestation Regulation's geolocation requirements are reshaping procurement standards for cocoa derivatives. French artisan chocolatiers pilot direct-trade programs with Latin American cooperatives to diversify sourcing.
Cocoa Fillings Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the cocoa fillings market. Integrated processors with bean-to-fillings infrastructure control origin traceability and premium positioning, while commodity-scale suppliers compete on cocoa butter equivalent innovation and volume efficiency. The competitive landscape stratifies into three archetypes: integrated origin controllers, proprietary formulation specialists, and cost-optimized compound manufacturers. Dominant competitive moves include backward integration into cooperative management systems and portfolio diversification across dark, milk, and plant-based filling categories.
Among the integrated origin controllers, Barry Callebaut exemplifies the archetype with multi-continental bean-to-fillings infrastructure. Cargill Inc. sits within the cost-optimization tier, competing on cocoa butter equivalent innovation for compound applications. The Hershey Company anchors the proprietary formulation specialist position in North America through captive milk chocolate filling development.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Nestlé S.A. |
| Barry Callebaut |
| Ferrero Group |
| Mondelēz International |
| Archer Daniels Midland Company |
| Clasen Quality Coatings |
| The Hershey Company |
| Cargill Inc. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles at European processors compress margin buffers when cocoa butter futures swing, concentrating pricing power with integrated bean-to-fillings operators who control origin documentation and hedge physical supply. This lead-time exposure binds procurement costs to West African harvest variability, forcing mid-tier filling manufacturers into defensive contract structures with industrial bakery accounts.
Pricing Analysis
The EU Deforestation Regulation dictates the pricing tier structure across the cocoa fillings market. Three-tier pricing structure across premium, standard, and economy levels separates EUDR-compliant single-origin fillings from commodity-grade milk chocolate formulations and vegetable-fat compound alternatives. Price differentiation rests on certification grade and volume scale, with artisan chocolatiers in Belgium absorbing premiums for harvest-lot traceability while German industrial bakers negotiate annual contracts with viscosity guarantees. Pricing pressure stems from cocoa butter futures volatility, compressing margins for processors locked into fixed-price bakery supply agreements. Compound chocolate segments exhibit highest price sensitivity, substituting cocoa butter with palm and shea fractions to serve emerging-market snack manufacturers.
Supply Chain Analysis
Ninety-day inventory cycles expose processors to commodity price swings before EUDR-mandated documentation clears customs. Geographic supply concentrates in Côte d'Ivoire, Ghana, and Ecuador, with over seventy percent of global bean origination clustering in the first two. Raw material dependencies center on cocoa butter, cocoa mass, and emulsifier inputs sourced through futures markets and cooperative forward contracts. Supply chain risk hinges on single-source vulnerability in West African origins, where climate exposure and political instability disrupt harvest forecasts without scalable alternatives. Distribution runs through integrated bean-to-fillings processors for premium tiers, while commodity volumes flow via industrial distributors with bulk tanker logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in the disintermediation space between artisan chocolatiers and origin cooperatives, as EUDR traceability requirements dismantle traditional commodity distributor control over premium procurement channels.
For Market Incumbents: Fortify backward integration into cooperative management systems to preempt EUDR enforcement deadlines and lock in origin documentation capacity. Invest in GPS-enabled farm polygon mapping to capture artisan chocolatier contracts specifying harvest-lot traceability. Defend against precision fermentation substitutes by accelerating clean-label emulsifier R&D through EFSA pre-submission pathways. For New Entrants and Emerging Players: Differentiate on carbon-accounting integration to capture ESG-committed food manufacturer procurement mandates under the EU Corporate Sustainability Reporting Directive. Target plant-based confectionery convergence with oat and rice protein-based milk chocolate fillings for UK and German vegan retail channels. Pursue direct-trade platform models that shorten distribution chains for Belgium's premium bonbon houses seeking terroir-designated supply. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational food conglomerates divesting non-core cocoa processing assets amid EUDR compliance cost concentration. Long-term viability favors integrated origin controllers with established Latin American supplier relationships beyond West African dependence. Watch precision fermentation scale-up announcements as inflection indicators for microbial lipid substitution threat to cocoa butter economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperative Management | Secures EUDR-compliant farm polygon documentation for European premium brand contracts. |
| Clean-Label Emulsifier Reformulation | Captures organic retail shelf-space through EFSA-approved lecithin-free stabilizer technologies. |
| Latin American Origin Expansion | Diversifies supply beyond West African concentration through Ecuador and Peru direct-trade programs. |
| Plant-Based Filling Development | Addresses vegan and flexitarian demand in UK and German dairy-free confectionery channels. |
| Carbon Accounting Integration | Delivers Scope 3 emissions documentation for EU Corporate Sustainability Reporting Directive compliance. |
Study Parameters
Desk research of trade flow databases, EUDR regulatory filings, and cocoa futures market archives preceded structured interviews with bean-to-fillings processors, industrial bakery procurement directors, artisan chocolatier owners, and cooperative management system vendors. Primary fieldwork validated secondary data on viscosity calibration requirements and EFSA emulsifier approval timelines. Analysis combined bottom-up volume modeling by application segment with top-down value reconciliation across regional consumption clusters.
Variance decomposition across product type, application, end-user category, and distribution channel anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include dark-milk-white-compound formulations, enrobing-confectionery-baked-goods-snack applications, and wholesale-online retail-supermarket-specialty store channels. CAGRs derived from historical price-volume relationships adjusted for EUDR implementation phasing and precision fermentation substitution curves. Cocoa butter futures volatility bands and EFSA novel food approval timelines fed scenario-weighted outputs.
Material uncertainties — regulatory enforcement delays, cooperative GPS deployment shortfalls, and microbial lipid crystallization breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions on EUDR geolocation compliance rates and artisan chocolatier direct-trade adoption velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
South America Breakfast Cereals Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
Fat Free Pasta Market
Packaged Foods
US Packaged Salads Market
Packaged Foods
Chewing Gum Market
Packaged Foods
Iraq Dried Pasta Market
Packaged Foods
Iran Breakfast Cereals Market
Packaged Foods
Convenience Food Market
Packaged Foods
Dried Soup Market
Packaged Foods
Packaged Food Market
Packaged Foods
Pre-Packaged Sandwich Market
Packaged Foods
Packaged Zhug Market
Packaged Foods
Canned Pasta Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
Instant Ramen Market
Packaged Foods
United Kingdom Food Spreads Market