
 Cocoa Processing Market | 2026-2036
Cocoa Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Cocoa Processing Market Intelligence
EU Deforestation Regulation is hardening traceability mandates for cocoa entering European supply chains, forcing processors to document farm-level geolocation data. Barry Callebaut leverages its integrated grinding network across Belgium and Germany to sustain compliance advantages. Cargill anchors its West African operations through farmer certification programs that preempt regulatory exclusion. Olam Group competes by extending digital traceability platforms from bean origination through finished butter exports.
Cocoa processing transforms fermented and dried cocoa beans into cocoa butter, cocoa powder, cocoa liquor, and chocolate through mechanical pressing, alkalization, and conching sequences that typically reduce bean moisture below seven percent and separate fat fractions at controlled temperatures. The output serves confectionery manufacturers, beverage formulators, and cosmetic compounders as a functional fat source, flavor base, or emollient ingredient. Cocoa butter commands structural priority within product type segmentation due to its irreplaceable melting profile in tempered chocolate, while cocoa powder gains traction in protein fortification and clean-label dessert applications. Alkalization technology differentiates Dutch-processed powders with darker color and milder acidity, creating distinct margin pools from natural process alternatives.
FDA food safety standards govern cocoa imports into the United States through strict aflatoxin and salmonella thresholds, while EFSA and EU Green Deal sustainability criteria now layer climate and deforestation compliance onto product specifications. Ghana's COCOBOD and Côte d'Ivoire's Conseil du Café-Cacao administer minimum farmgate pricing mechanisms that directly reshape processor procurement economics across origin markets. Stakeholders must monitor how emerging African processing capacity and shifting European import rules simultaneously redraw competitive boundaries for established grinders.
Market Dynamics
The EU Deforestation Regulation is forcing processors to restructure supply chain traceability systems, creating a compliance-driven bifurcation between integrated operators with farm-level data capabilities and smaller grinders facing exclusion risk from European markets.
Growth Catalysts
- Single-origin cocoa liquor procurement:Premium chocolate brands and artisanal confectionery makers are expanding sourcing of traceable, terroir-specific inputs that command price premiums and support brand differentiation in high-end retail channels.
- FSSAI clean-label standards:India's food safety regulator is accelerating demand for natural-process cocoa powders in protein fortification and dessert applications, opening formulation opportunities for processors with alkalization alternatives.
- West African cooperative certification:Bean sourcing is gravitating toward established Côte d'Ivoire and Ghana cooperatives with verified sustainability credentials, reducing deforestation-linked supply risk for European-bound exports.
Market Restraints
- Farmgate price floor mechanisms:Ghana's COCOBOD and Côte d'Ivoire's Conseil du Café-Cacao administer minimum pricing that compresses processor margins during periods of elevated global cocoa futures.
- Aflatoxin contamination thresholds:FDA food safety standards enforce strict mycotoxin limits that disqualify non-compliant bean lots from US import eligibility, raising quality assurance costs.
- Shea butter substitution in cosmetics:Functional fat alternatives with comparable emollient properties are displacing cocoa butter in premium skincare formulations, narrowing traditional outlet expansion.
Strategic Opportunities
- Indian confectionery market penetration:Rising per-capita chocolate consumption and expanding modern retail formats create whitespace for cocoa butter and liquor suppliers establishing local technical service presence.
- EU Green Deal sustainability criteria:Climate compliance layering onto product specifications rewards early movers with verified carbon footprint data and regenerative agriculture partnerships.
- Blockchain-IoT traceability convergence:Digital platforms integrating geolocation verification with real-time shipment monitoring enable premium pricing for fully documented supply chains from farm to finished product.
Industry Challenges
- Farm-level geolocation data collection:Smallholder plot mapping at scale requires capital-intensive field operations and persistent farmer engagement that strains mid-size processor organizational capacity.
- Alkalization equipment retooling:Shifting powder production between natural and Dutch-process outputs demands flexible press and pH-control infrastructure that legacy facilities lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocoa Processing Market |
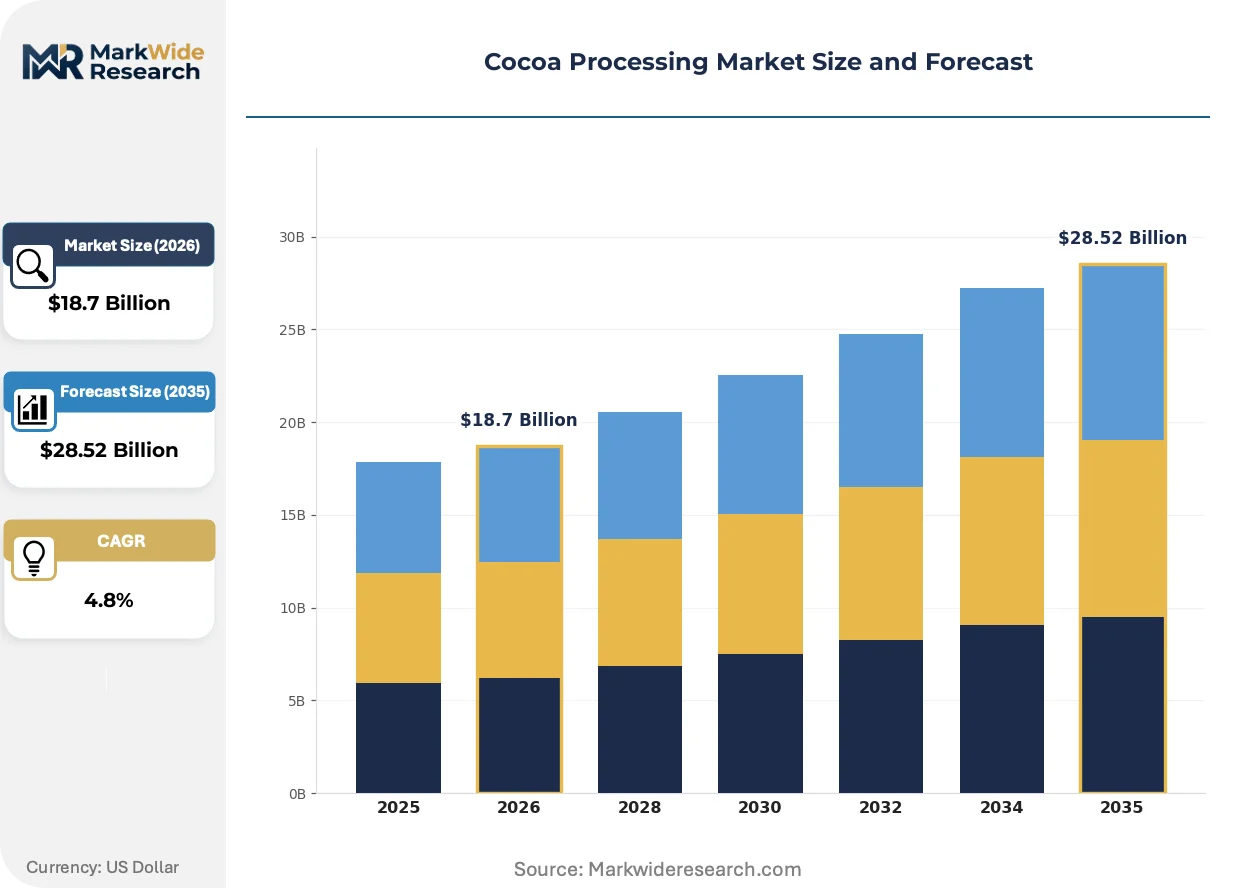
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cocoa Butter, Cocoa Powder, Cocoa Liquor, Chocolate End User: Food Manufacturers, Confectionery Companies, Beverage Industry, Bakery Technology: Pressing, Alkalization, Fermentation, Drying Application: Snacks, Desserts, Dietary Supplements, Cosmetics |
| Companies Covered | Mars Incorporated, Ferrero, Barry Callebaut, Cemoi Group, Olam Group, Cargill, Mondelēz International, TOUTON S.A., Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocoa Processing Market Strategic Shifts & Innovations
Processing technology is fragmenting into smaller-scale, flexible configurations that enable origin-country value addition, while regulatory pressure and procurement sophistication are compressing margins for undifferentiated commodity grinding.
Mechanical pressing systems with modular alkalization units are modularizing cocoa butter extraction workflows, allowing Ghanaian and Ivorian processors to install capacity in 5,000-tonne annual increments rather than 50,000-tonne legacy scales. Regional grinders are adopting these configurations to retain bean value locally. The technology is compressing the historical dominance of European and Asian mega-facilities by enabling viable smaller-batch production with comparable fat yield efficiency.
EFSA and EU Green Deal sustainability criteria are layering climate and deforestation compliance onto cocoa product specifications, forcing exporters to document carbon intensity and land-use change at the farm polygon level. Processors serving European confectionery manufacturers must now integrate third-party audit data into shipment documentation. Butter and liquor segments bound for EU markets face the steepest compliance cost escalation, driving consolidation toward integrated operators with captive farm extension networks.
Clean-label dessert applications are rotating procurement preferences toward natural-process cocoa powders with minimal chemical treatment, displacing traditional Dutch-process dominance in premium bakery and protein-fortified segments. North American and Western European formulators are reformulating around milder acidity and lighter color profiles. This shift is most visible in sports nutrition and plant-based dessert verticals where ingredient transparency commands shelf price realization.
Cocoa Processing Market Segmentation
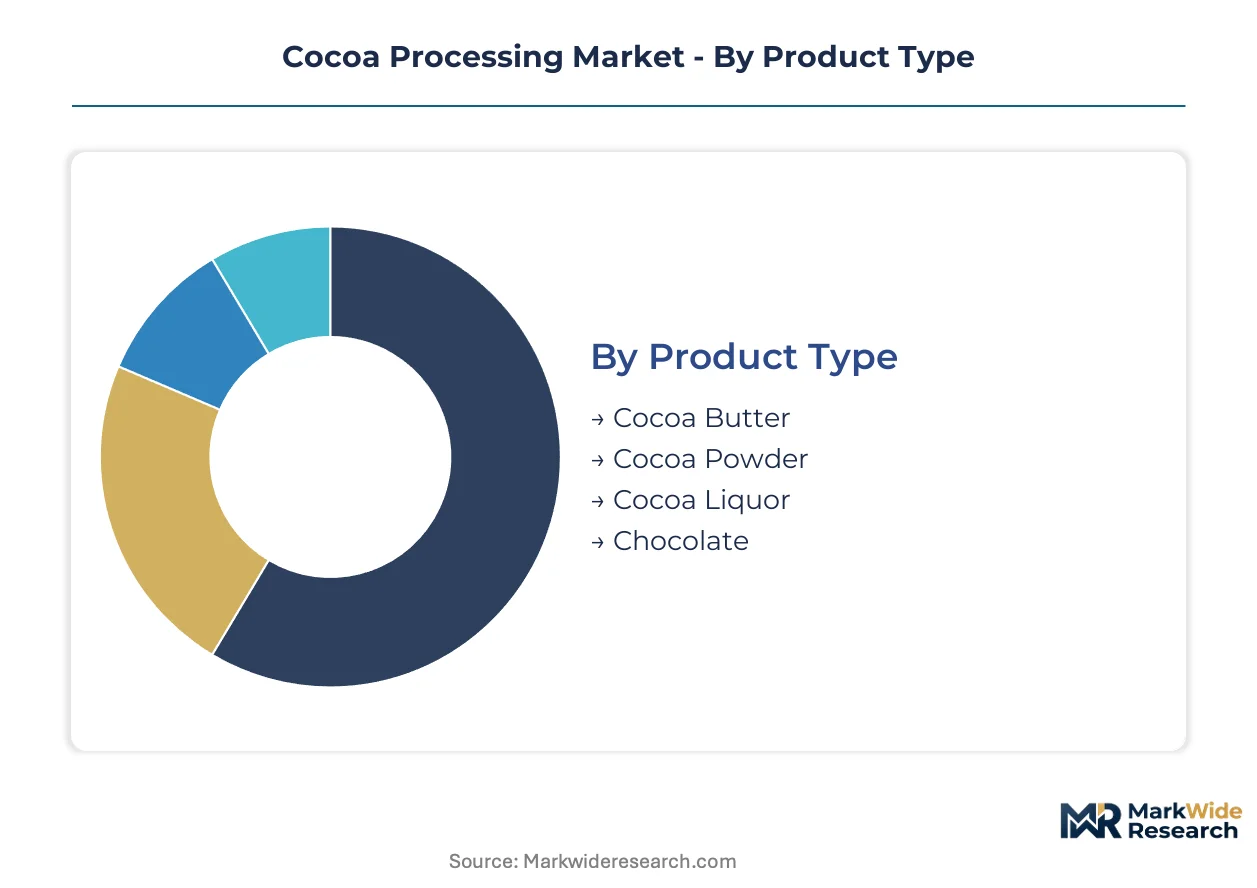
Cocoa processing segmentation reveals how regulatory pressure and end-use specification complexity concentrate value in specific product tiers. Differentiation across product type, end user, technology, and application determines which processors capture premium pricing versus commodity grinding margins.
Product Type:
EFSA and FDA thresholds apply differentially across product categories, with cocoa butter facing the strictest mycotoxin surveillance due to its lipid-solubility for aflatoxin retention.
- Cocoa Butter:Extracted through mechanical pressing at controlled temperatures to preserve crystalline polymorphism essential for chocolate tempering. European confectionery manufacturers in Belgium and Germany concentrate procurement here, driven by irreplaceable melting profile requirements that shea and palm fractions cannot replicate.
- Cocoa Powder:Produced via alkalization or natural pressing sequences yielding fat content variations from 10-22%. Demand clusters in North American sports nutrition and Indian clean-label dessert formulations, constrained by FSSAI natural-process preferences and EFSA heavy metal limits.
- Cocoa Liquor:Ground cocoa nibs retaining full fat content serve as intermediate feedstock for chocolate manufacturing and direct flavoring applications.
- Chocolate:Finished couverture and compound coatings represent downstream integrated processing, often captive to branded confectionery operations.
Leading the category by volume: Cocoa Powder. Expanding most quickly: Cocoa Butter.
End User:
Customer scale and formulation sophistication create distinct service requirements, from bulk butter supply to co-development of alkalized powder specifications.
- Food Manufacturers:Multinational packaged goods companies purchase standardized butter and powder grades in containerized volumes, prioritizing lot-to-lot consistency for recipe stability.
- Confectionery Companies:Tier-one chocolate houses and artisanal bean-to-bar operations drive single-origin liquor procurement, paying premiums for traceable West African cooperative sourcing with geolocation documentation.
- Beverage Industry:Instant drink and dairy alternative formulators specify alkalized powders with controlled color and dispersibility profiles.
- Bakery:Industrial and craft bakeries utilize both natural and Dutch-process powders depending on end-product pH and visual requirements.
Highest volume concentration: Food Manufacturers. Gaining share fastest: Confectionery Companies.
Technology:
Capital intensity and energy consumption vary sharply across processing stages, with alkalization and pressing equipment representing the largest fixed-cost commitments.
- Pressing:Hydraulic and expeller systems separate cocoa butter from liquor, with screw-press efficiency determining fat yield economics and subsequent powder fat content.
- Alkalization:Dutch-process treatment with potassium carbonate modifies color, flavor, and dispersibility; pH control precision distinguishes premium powder tiers.
- Fermentation:Pre-processing at origin develops precursor flavor compounds, with box and heap methods influencing final bean quality and processor purchasing premiums.
- Drying:Sun and artificial drying systems reduce moisture below seven percent to prevent mold and preserve bean viability for export.
Dominant by installed capacity: Pressing. Climbing the fastest: Alkalization.
Application:
End-use functionality requirements dictate specification stringency, with cosmetics and dietary supplements imposing the purest input standards.
- Snacks:Compound coatings and flavored inclusions utilize cocoa powder for cost-effective chocolate taste in cereal bars and puffed products.
- Desserts:Premium ice cream and pastry applications specify deodorized butter and carefully alkalized powders for clean flavor release.
- Dietary Supplements:Protein fortification and functional food applications in North America and Western Europe favor natural-process powders with minimal chemical treatment and declared polyphenol content.
- Cosmetics:Skincare formulators source pharmaceutical-grade butter for emollient properties, though shea butter substitution is narrowing volume growth in premium segments.
Largest application volume: Snacks. Steepest expansion trajectory: Dietary Supplements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
West African bean sourcing concentrates procurement decisions for processors worldwide, while European regulatory pressure and Asian confectionery expansion reshape regional demand patterns. National regulations and industrial clustering determine where value addition occurs.
Côte d'Ivoire
Minimum farmgate pricing administered by Conseil du Café-Cacao directly elevates bean export costs for international grinders. The country's national cocoa regulator enforces quality standards that determine export eligibility. Abidjan and San-Pédro host expanding processing installations where regional grinders deploy modular pressing systems to retain value locally.
Ghana
COCOBOD's price floor mechanisms compress processor margins during futures rallies while sustaining farmer income stability. The national cocoa board operates quality control protocols that filter export lots. Tema and Takoradi processing zones attract investment from integrated operators building traceability-linked supply chains for European confectionery manufacturers.
Germany
EFSA mycotoxin surveillance and EU Deforestation Regulation compliance costs concentrate demand for verified supply chains among Hamburg and Cologne industrial chocolate manufacturers. The country's federal food safety authority enforces strict aflatoxin thresholds on imported cocoa products. The Hamburg port cluster anchors European grinding capacity with integrated logistics for bean intake and butter export.
United States
FDA aflatoxin and salmonella standards disqualify non-compliant bean lots from import eligibility, raising quality assurance expenditure for domestic processors. The federal food safety regulator mandates pathogen testing protocols that shape procurement from origin markets. New Jersey and Pennsylvania processing facilities serve North American confectionery manufacturers with specialized powder and butter grades.
India
FSSAI clean-label standards accelerate natural-process cocoa powder demand for protein fortification and dessert formulations. The national food safety authority restricts chemical treatment declarations that influence alkalization technology choices. Maharashtra and Karnataka industrial zones host expanding confectionery manufacturing that pulls butter and liquor imports through Mumbai and Chennai port infrastructure.
Cocoa Processing Market Key Industry Players
West African origin-country processors anchor one tier; European and Asian specialists hold integrated grinding and finished chocolate manufacturing positions. The vendor base separates into consolidated multinational operators with captive farm networks and regional mid-scale grinders serving domestic confectionery markets. Three archetypes dominate: integrated bean-to-bar processors with traceability platforms, commodity grinders competing on fat yield efficiency, and branded chocolate manufacturers with backward processing control. Competitive dynamics center on M&A activity consolidating origin-country capacity and strategic partnerships linking farm certification to European export eligibility.
Within the integrated multinational tier, Barry Callebaut, Cargill, and Olam Group exemplify archetypes spanning grinding network scale, agricultural extension reach, and digital traceability deployment. Barry Callebaut represents European integrated processing with Belgium and Germany facility networks. Cargill occupies a position linking North American agricultural commodity expertise to West African farmer certification programs. Olam Group anchors Singapore-based agricultural supply chain diversification into origin-country value addition. These three entities sit within distinct strategic postures on regulatory compliance, geographic coverage, and vertical integration depth.
| Leading Market Players |
|---|
| Mars Incorporated |
| Ferrero |
| Barry Callebaut |
| Cemoi Group |
| Olam Group |
| Cargill |
| Mondelēz International |
| TOUTON S.A. |
| Nestlé |
| Others |
Cost & Logistics Intelligence
Backward integration into farm-level traceability networks anchors both supply security and premium pricing power for processors serving EU-bound confectionery manufacturers. The EU Deforestation Regulation's geolocation mandates reward operators with captive farmer extension programs, compressing margins for commodity grinders lacking documented supply chains.
Pricing Analysis
Volume concentration in commodity butter and powder grades competes against margin expansion in certified single-origin liquor segments. Three-tier pricing structure across premium, standard, and economy levels separates traceable cooperative-sourced inputs from undifferentiated bulk grades. Cost compression in standard powder tiers is intensifying because West African farmgate price floors elevate bean input costs regardless of quality differentiation. Food manufacturers exhibit highest price sensitivity due to recipe-driven volume procurement, while artisanal confectionery companies absorb premiums for documented terroir specificity.
Supply Chain Analysis
Dual-sourcing requirements from European confectionery manufacturers now mandate qualified suppliers across both West African and secondary origin markets. Bean supply draws from Côte d'Ivoire, Ghana, and Ecuador, with butter and powder processing concentrated in Belgium, Germany, and Singapore. Alkalization chemicals, pressing equipment spares, and food-grade packaging constitute critical input dependencies. Single-source vulnerability in West African bean procurement exposes processors to COCOBOD and Conseil du Café-Cacao price interventions. Distribution runs through Hamburg and Antwerp port clusters for European industrial chocolate manufacturers, with secondary routing through Singapore for Asian confectionery expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cocoa processing sector functions as a vertical-integration race where control over farm-level geolocation data determines EU market access. Processors are pursuing backward integration into origin-country farmer certification programs as the decisive competitive lever.
For Market Incumbents: Hedge against regulatory exclusion by accelerating blockchain-IoT traceability deployment across West African cooperative networks. Consolidate regional grinding capacity in Ghana and Côte d'Ivoire to capture origin-country value addition before modular press systems proliferate. Barry Callebaut's integrated Belgium-Germany network and Cargill's farmer certification programs exemplify defensive positioning against mid-size grinder margin compression. For New Entrants and Emerging Players: Launch via direct technical service partnerships with Indian confectionery manufacturers in Maharashtra and Karnataka industrial zones. Target clean-label natural-process cocoa powder formulations for North American sports nutrition and protein fortification applications, where FSSAI-aligned specifications create formulation whitespace. Partner with West African cooperatives lacking digital traceability infrastructure to supply geolocation-documented beans to EU-bound exporters. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of origin-country processors with verified sustainability credentials and captive farmer relationships. Long-term viability hinges on operators with documented carbon footprint data and regenerative agriculture partnerships spanning the projection horizon. Watch for EU Green Deal enforcement tightening as the inflection signal for accelerated consolidation toward integrated traceability platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Farmer Certification Program Expansion | COCOBOD and Conseil du Café-Cacao compliance secures EU Deforestation Regulation eligibility for European confectionery exports. |
| Modular Pressing System Deployment | 5,000-tonne origin-country installations in Abidjan and San-Pédro retain bean value locally against European mega-facility dominance. |
| Blockchain-IoT Traceability Integration | Geolocation verification from farm polygon through finished butter shipment commands premium pricing from Belgian and German chocolate manufacturers. |
| Natural-Process Powder Capacity Addition | FSSAI-aligned alkalization alternatives capture Indian clean-label dessert and North American protein fortification formulation demand. |
| Regenerative Agriculture Partnership | Carbon intensity documentation satisfies EU Green Deal sustainability criteria for climate-compliant butter and liquor segments. |
Research Approach
Multi-period observation of EU Deforestation Regulation implementation timelines, West African farmgate price mechanism adjustments, and clean-label certification adoption rates anchored the trend analysis, supplemented by interviews with cocoa processing plant managers, European confectionery procurement directors, West African cooperative extension officers, and FSSAI regulatory affairs specialists. Secondary validation drew from EFSA guidance documents, COCOBOD annual reports, Conseil du Café-Cacao export statistics, FDA import refusal data, and customs trade records. Bottom-up segment sizing triangulated against top-down macroeconomic drivers.
Input-output matrix modeling connected bean supply volumes through pressing, alkalization, and conching stages to finished butter, powder, and liquor outputs across product type, end user, technology, and application dimensions. CAGRs were derived from regression analysis of historical processing capacity expansion and forward projection of regulatory compliance cost trajectories. Forecast inputs incorporated EU Green Deal enforcement schedules, Indian confectionery per-capita consumption trends, and shea butter substitution elasticity in cosmetics applications.
West African political intervention in farmgate pricing, accelerated EU traceability deadline enforcement, and shea butter emollient substitution in premium skincare are the dominant revision risks to modeled outputs. Deviation in EU Deforestation Regulation implementation stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Sesame Oil Market
Ingredients
China Protein Market
Ingredients
Edible Halal Gelatin Market
Ingredients
Europe Insoluble Dietary Fibers Market
Ingredients
Smoked Yeast Market
Ingredients
Green Gram Powder Market
Ingredients
North America Soy Protein Market
Ingredients
Kairomones Market
Ingredients
Oak Extract Market
Ingredients
North America Wheat Protein Ingredients Market
Ingredients
Karaya Gum Market
Ingredients
Shortening Fats Market
Ingredients
Black Cumin Seed Oil Market
Ingredients
Trait Enhanced Oils Market
Ingredients
Injection Grade Soybean Oil Market
Ingredients
Spain Fermentation Ingredients Market