
 Cocoa Market | 2026-2036
Cocoa Market Size, Share, and Industry Trends Forecast 2026-2036
Cocoa Market Analysis
West African processing capacity expansion is reconfiguring global cocoa trade flows. Cargill Incorporated leverages its integrated supply chain from bean origination to chocolate manufacturing across multiple continents. Barry Callebaut AG anchors the industrial chocolate segment through its extensive global processing network. Mondelēz International competes in branded confectionery with sustained investment in sustainable sourcing programs.
Cocoa comprises the dried and fermented seeds of Theobroma cacao, typically processed into butter, powder, liquor, and cake with fat content specifications ranging from 10% to 24% for powder variants. The primary commercial purpose centers on flavoring, texturizing, and coloring applications across food and beverage manufacturing. Cocoa butter commands the largest value share among type segments due to its irreplaceable melting profile in chocolate confectionery. Alkalized cocoa powder represents the fastest-growing form segment as beverage producers seek darker color intensity and milder flavor notes for premium drink formulations.
The European Union Deforestation Regulation and FDA food safety standards collectively reshape traceability requirements and import compliance for cocoa entering major consumption markets. ECHA guidance on pesticide residues and the EU Green Deal sustainability benchmarks further tighten environmental accountability across the value chain. Stakeholders must monitor evolving due diligence obligations and origin certification schemes to secure long-term supply access and consumer trust.
Market Dynamics
The European Union Deforestation Regulation is compressing compliance timelines for cocoa traders while West African processing expansion redraws traditional bean export patterns. Supply chain actors must now embed traceability infrastructure from farm gate to finished product.
Growth Catalysts
- EU Deforestation Regulation:Mandatory geolocation and due diligence requirements for deforestation-free supply chains are accelerating investment in farm-level monitoring systems and satellite verification platforms.
- Alkalized cocoa powder:Beverage manufacturers seeking darker color intensity and smoother mouthfeel in premium drink formulations are expanding procurement of alkalized variants over natural powder grades.
- West African processing capacity:Côte d'Ivoire and Ghana are commissioning additional grinding facilities, capturing more value domestically and reducing raw bean export dependency.
Market Restraints
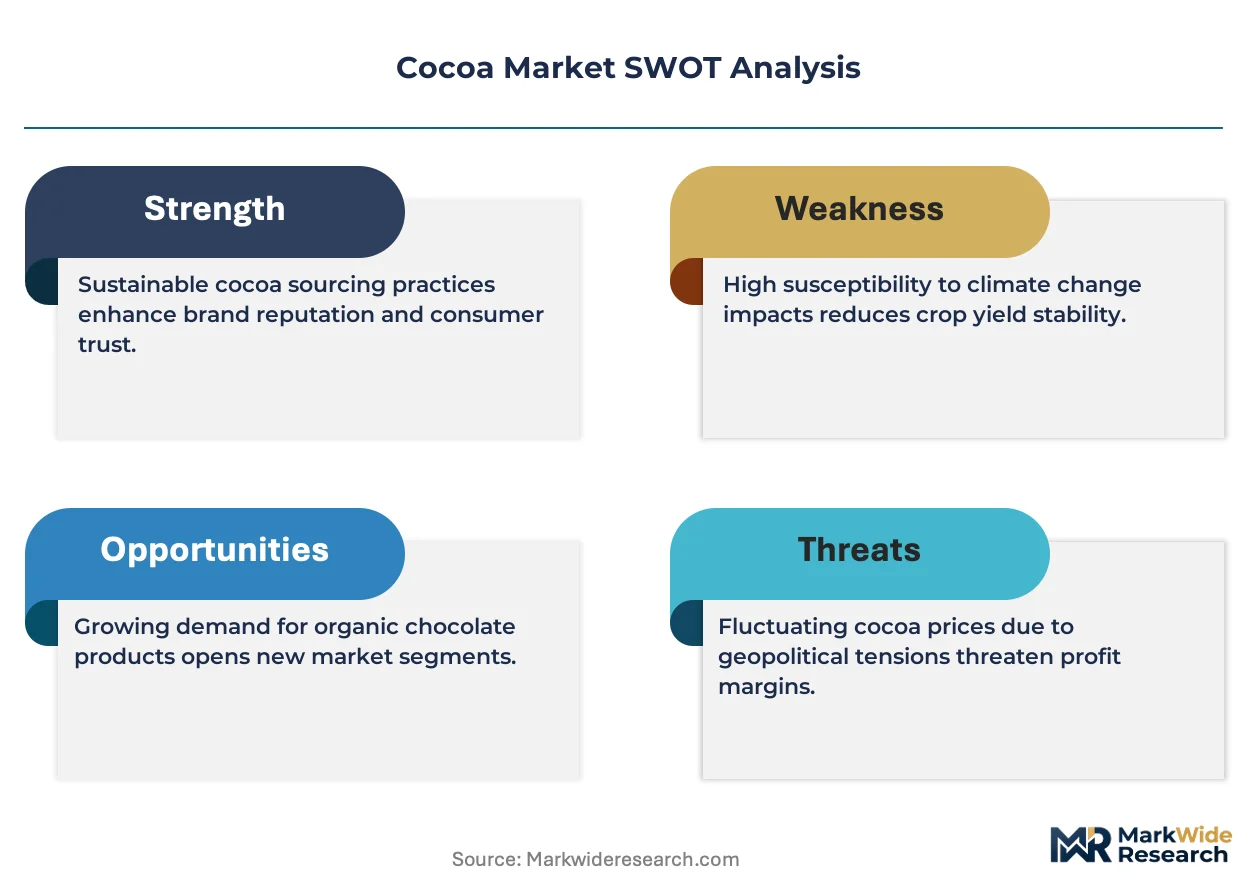
- Input cost volatility:Cocoa butter price swings tied to bean harvest variability constrain margin predictability for chocolate manufacturers with fixed-price retail contracts.
- Supply concentration risk:Over seventy percent of global cocoa bean output originates from Côte d'Ivoire and Ghana, creating systemic exposure to regional weather shocks and political instability.
- Regulatory friction:Divergent FDA food safety standards and EU pesticide residue limits under ECHA guidance force dual compliance tracks for exporters serving both markets.
Strategic Opportunities
- Underpenetrated origin diversification:Ecuador, Colombia, and Peru offer fine-flavor cocoa with established sustainability credentials but underdeveloped industrial-scale supply infrastructure.
- Regulatory tailwind:EU Green Deal sustainability benchmarks and carbon border adjustments create first-mover advantages for operators with certified low-emission supply chains.
- Technology convergence:Blockchain traceability platforms combined with mobile payment systems are hybridizing farm-gate transparency with direct farmer compensation mechanisms.
Industry Challenges
- Certification timeline compression:Rainforest Alliance and Fairtrade audit backlogs are extending compliance verification cycles beyond contract execution windows.
- Skill scarcity in agronomy:Aging farmer populations and limited youth recruitment into cocoa cultivation are constraining yield improvement program deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocoa Market |
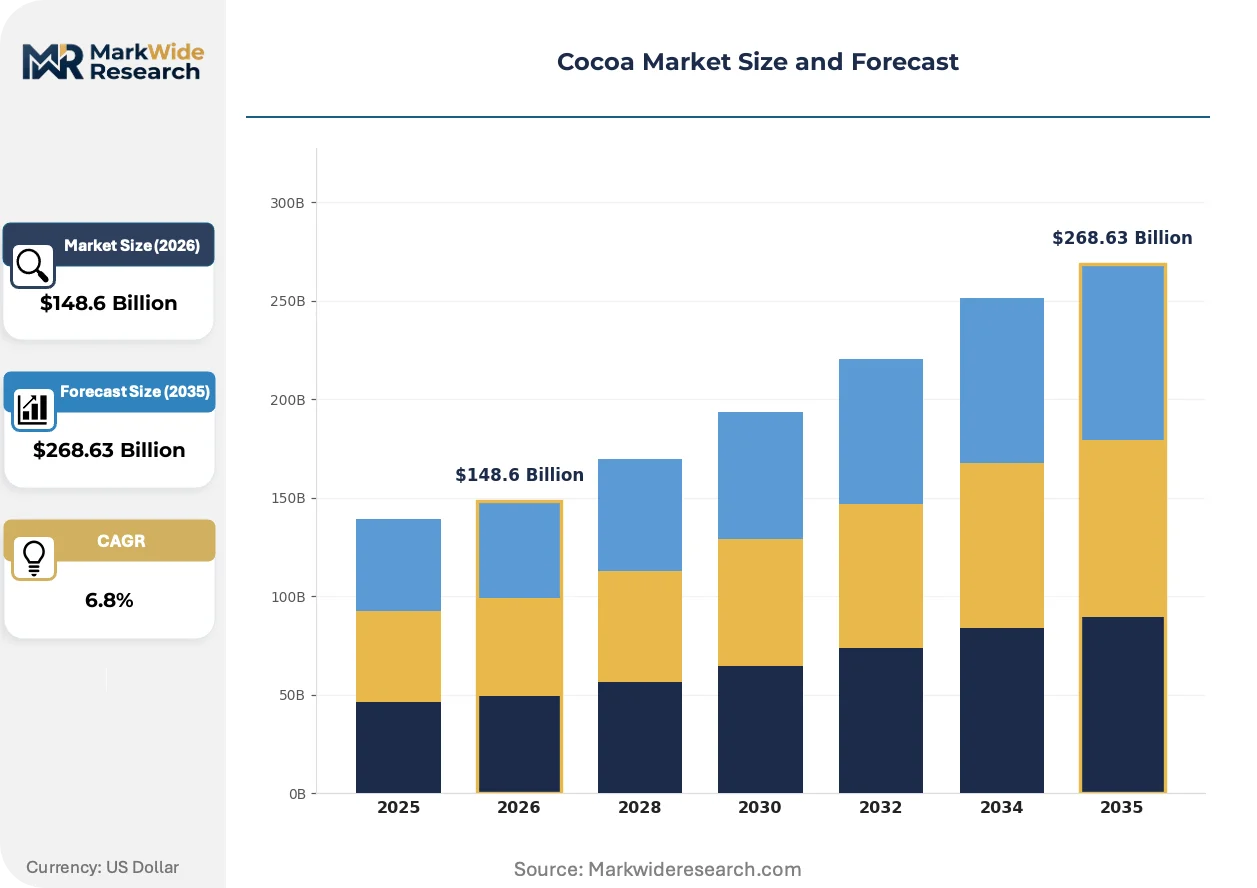
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $268.63 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Cocoa Butter, Cocoa Powder, Cocoa Liquor, Cocoa Cake Application: Confectionery, Beverages, Bakery, Dairy Form: Natural, Alkalized, Dark, Milk End User: Food Industry, Beverage Producers, Bakers, Retailers |
| Companies Covered | Barry Callebaut AG, Cargill Incorporated, Mondelēz International, Mars Incorporated, Nestlé, Ferrero Group, Olam International, The Hershey Company, ECOM Agroindustrial Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocoa Market Emerging Trajectories
Processing technology and regulatory architecture are converging to redefine how cocoa moves from origin to finished application. Three distinct vectors are compressing traditional value chain arrangements.
Precision fermentation of cocoa butter alternatives is hybridizing lipid chemistry with biotechnology to replicate the polymorphic crystallization behavior essential for chocolate tempering. Mid-sized confectionery manufacturers in North America and Western Europe are piloting these alternatives to reduce exposure to bean price volatility. The technology is enabling formulation flexibility that compresses the traditional butter-powder-liquor procurement bundle into single-source lipid solutions.
REACH chemical registration requirements and ECHA guidance on processing aids are tightening substance authorization for cocoa butter extraction solvents. Industrial chocolate producers must now substitute traditional hexane-based processes with aqueous or supercritical carbon dioxide alternatives. German and Swiss processing facilities are retrofitting extraction infrastructure fastest, driven by domestic chemical regulation enforcement timelines.
Direct-to-manufacturer sourcing contracts are displacing multi-tier intermediary structures that historically aggregated smallholder output. Bean-to-bar chocolate makers and specialty confectionery brands in Japan and the United States are establishing exclusive supply relationships with cooperative federations. This pattern is most visible in Ecuador and Madagascar, where flavor-profile differentiation commands origin-specific premiums above commodity exchange benchmarks.
Cocoa Market Segmentation
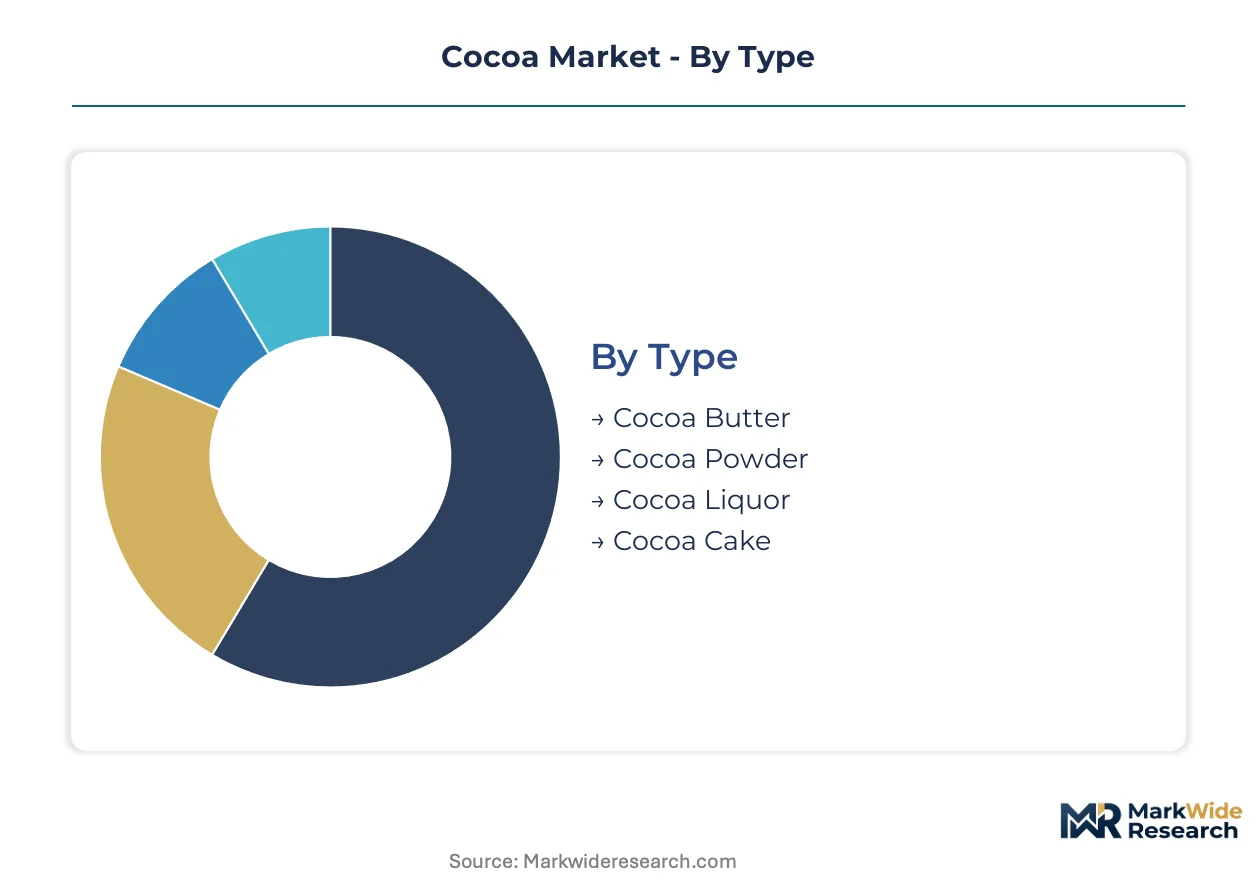
Cocoa market segmentation reveals distinct value capture patterns across processing stages and end-use applications. Technical specifications around fat content, pH levels, and flavor profiles determine procurement decisions for industrial buyers. Understanding these segment boundaries enables suppliers to align processing investments with demand concentration points.
Type:
Cost tier differentiation across cocoa derivatives reflects extraction complexity and functional irreplaceability in finished formulations.
- Cocoa Butter:The natural fat extracted from cocoa beans exhibits a unique triglyceride composition that delivers the polymorphic crystallization essential for chocolate tempering. European confectionery manufacturers anchor procurement volumes here, though bean harvest variability transmits directly into butter price swings that constrain margin predictability for fixed-contract retail chocolate producers.
- Cocoa Powder:Press cake residue is pulverized into powder variants with fat content specifications ranging from 10% to 24%. Beverage producers in Japan and the United States are expanding procurement of alkalized grades that deliver darker color intensity and milder flavor notes for premium drink formulations.
- Cocoa Liquor:Ground cocoa nibs yield this semi-liquid mass containing roughly equal parts fat and cocoa solids. Industrial chocolate manufacturers use liquor as the foundational input for subsequent butter and powder fractionation.
- Cocoa Cake:The compressed solid remaining after butter extraction serves as the feedstock for powder production. West African grinding facilities are capturing more cake processing domestically as regional capacity expands.
Cocoa butter commands the established base. The steepest expansion runs through cocoa powder.
Application:
End-use demand concentrates in categories where cocoa delivers functional properties difficult to replicate with alternative ingredients.
- Confectionery:Chocolate bars, pralines, and countlines depend on cocoa butter's melting profile for mouthfeel and shelf stability. German and Swiss processors maintain the most sophisticated confectionery supply relationships, driven by domestic chemical regulation enforcement timelines that favor advanced extraction infrastructure.
- Beverages:Hot chocolate mixes and ready-to-drink formulations utilize alkalized powder for solubility and color consistency. North American beverage manufacturers are piloting precision fermentation alternatives to reduce exposure to bean price volatility.
- Bakery:Cocoa powder provides color and flavor in cakes, cookies, and pastries without the fat content that compromises dough handling properties.
- Dairy:Chocolate milk and ice cream applications require powder grades that disperse uniformly in liquid matrices.
Confectionery anchors volume concentration. Beverage applications are gaining share fastest.
Form:
Processing intensity determines the functional attributes available to downstream formulators.
- Natural:Unprocessed cocoa retains acidic flavor profiles and lighter coloration suited to traditional European chocolate recipes.
- Alkalized:Dutch processing raises pH levels to reduce bitterness and deepen color. REACH chemical registration requirements and ECHA guidance on processing aids are tightening substance authorization for the potassium carbonate solutions used in alkalization.
- Dark:Higher cocoa solid content delivers intense flavor positioning for premium chocolate positioning.
- Milk:Lower cocoa content formulations incorporate dairy ingredients for mass-market palatability.
Natural form holds the traditional base. Alkalized processing is climbing the fastest.
End User:
Customer type shapes contract structures and traceability requirements across the value chain.
- Food Industry:Industrial chocolate manufacturers and confectionery multinationals purchase bulk butter and liquor under long-term supply agreements. FDA food safety standards and EU pesticide residue limits force dual compliance tracks for exporters serving both markets.
- Beverage Producers:Ready-to-drink and instant mix manufacturers prioritize powder solubility and color consistency specifications.
- Bakers:Artisan and industrial bakery operations procure powder grades optimized for batter dispersion and baking stability.
- Retailers:Private label chocolate programs and bean-to-bar operators establish direct sourcing relationships with cooperative federations in Ecuador and Madagascar.
Food industry buyers command the established procurement base. Direct-to-manufacturer sourcing through retailers and specialty operators is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European buyers favor cocoa butter for confectionery tempering, while North American beverage manufacturers drive alkalized powder procurement. Asian markets split between industrial chocolate inputs and premium bean-to-bar consumption. This consumption-mix differential shapes regional trade flows and processing investments.
Germany
Industrial chocolate manufacturers anchor European butter demand. REACH chemical registration requirements and ECHA guidance on processing aids are tightening substance authorization for extraction solvents. Cologne and Hamburg processing clusters are retrofitting infrastructure fastest, driven by domestic chemical regulation enforcement timelines.
United States
Beverage producers and specialty confectionery brands are expanding alkalized powder procurement. FDA food safety standards govern import compliance and pesticide residue limits. Pennsylvania and California industrial clusters are piloting precision fermentation alternatives to reduce exposure to bean price volatility.
Côte d'Ivoire
Domestic grinding capacity expansion is capturing more value from bean origination. National agricultural development programs and export licensing frameworks are restructuring trade flows. Abidjan processing zones are commissioning additional facilities, reducing raw bean export dependency.
Switzerland
Premium chocolate confectionery manufacturers concentrate high-value butter procurement. Swissmedic food safety oversight and bilateral trade agreements with West African origins shape import patterns. Zurich and Geneva industrial clusters maintain the most sophisticated confectionery supply relationships.
Japan
Bean-to-bar chocolate makers and beverage manufacturers are establishing direct sourcing relationships. METI import standards and consumer protection regulations govern quality specifications. Tokyo and Osaka specialty food clusters are driving origin-specific premium procurement above commodity exchange benchmarks.
Cocoa Market Vendor Landscape
Capability concentration sits with integrated processors controlling farm-gate to finished-product chains; scale advantage sits with branded confectionery multinationals commanding retail shelf space. The market structures around three tiers: agricultural traders with origination networks, industrial processors with fractionation expertise, and consumer-facing manufacturers with brand equity. Dominant competitive moves include backward integration into grinding assets and exclusive supply contracting with cooperative federations.
Within the integrated processing tier, Barry Callebaut AG and Cargill Incorporated exemplify archetypes combining origination control with global manufacturing footprints. Mondelēz International occupies a position representing branded confectionery specialists with sustained investment in sustainable sourcing programs. These three anchors demonstrate how capability depth in traceability infrastructure and regulatory compliance now separates competitive positions as procurement shifts toward direct-to-manufacturer contracting.
| Leading Market Players |
|---|
| Barry Callebaut AG |
| Cargill Incorporated |
| Mondelēz International |
| Mars Incorporated |
| Nestlé |
| Ferrero Group |
| Olam International |
| The Hershey Company |
| ECOM Agroindustrial Corp |
| Others |
Supply Flow & Price Mechanics
Côte d'Ivoire and Ghana's combined grip on global bean output compresses pricing power toward farm-gate origins while industrial chocolate manufacturers absorb volatility through long-term offtake structures. Margin pools concentrate in butter fractionation and alkalized powder processing where functional irreplaceability sustains premium capture.
Pricing Analysis
Long-term offtake agreements dominate procurement between West African grinding facilities and European confectionery manufacturers, insulating volume commitments from spot market swings. Price differentiation rests on certification tier—Rainforest Alliance and Fairtrade premiums separate mass-market butter from traceable supply—and alkalization grade for beverage applications. Pricing pressure stems from bean harvest variability transmitting directly into butter cost structures. Small-scale specialty chocolate makers exhibit highest price sensitivity due to limited hedging capacity, while integrated multinationals with captive grinding assets maintain lowest sensitivity.
Supply Chain Analysis
West African bean harvests from Côte d'Ivoire, Ghana, and Cameroon feed global processing networks with established sustainability credentials. Inputs center on fermented cocoa seeds, potassium carbonate for alkalization, and hexane alternatives for butter extraction. Single-source vulnerability concentrates in Abidjan and Tema port corridors where political disruption or weather shocks cascade rapidly. Distribution runs through integrated processors controlling origination-to-manufacturing chains, with direct-to-manufacturer contracting displacing traditional aggregator tiers in Ecuador and Madagascar specialty segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled farm-gate transparency is transforming cocoa into a platform economy where traceability data itself becomes a tradable asset class, interoperable across EUDR compliance systems and consumer-facing provenance applications.
For Market Incumbents: Entrench market position through backward integration into West African grinding assets and exclusive supply contracting with cooperative federations in Ecuador and Madagascar. Precision fermentation alternatives for cocoa butter represent the most credible substitution threat; incumbents should anchor defensive R&D in lipid chemistry replication to neutralize this vector before cost parity emerges. For New Entrants and Emerging Players: Fine-flavor origin segments in Peru and Colombia with underdeveloped industrial-scale infrastructure represent the most penetrable entry point for specialty confectionery brands. Direct-to-manufacturer sourcing relationships with Japanese and United States bean-to-bar makers offer a viable go-to-market angle that bypasses entrenched Cargill and Barry Callebaut distribution networks. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier processors with established EUDR compliance infrastructure and satellite verification platform integration. Long-term viability across the analysis window favors operators capturing value domestically in Côte d'Ivoire and Ghana as regional grinding capacity expands. The signal to watch is certification audit backlog duration—extended Rainforest Alliance and Fairtrade verification cycles indicate supply constraint pressure that favors compliant asset premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grinding Assets | Captures margin pools in butter fractionation while securing EUDR-compliant supply access. |
| Blockchain Traceability Platform Deployment | Enables farm-gate transparency that satisfies EU Deforestation Regulation geolocation mandates. |
| Alkalized Powder Capacity Expansion | Addresses beverage manufacturer procurement for premium drink formulations in North America. |
| Exclusive Cooperative Federation Contracting | Locks in fine-flavor origin supply from Ecuador and Madagascar above commodity benchmarks. |
| Precision Fermentation R&D Partnership | Defends against lipid chemistry substitution threatening traditional butter demand. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with cocoa traders, grinding facility operators, confectionery procurement leads, and cooperative federation managers; and secondary validation through customs trade records, EUDR implementation guidance, and ECHA processing aid registrations. Bottom-up triangulation across farm-gate production estimates and top-down demand modeling from beverage and confectionery consumption patterns ensured cross-verification. Stakeholder input spanned West African origination networks, European industrial clusters, and North American specialty chocolate segments.
Forecast inputs incorporated cocoa butter and powder grade segmentation, alkalization processing intensity tiers, and end-use application splits across confectionery, beverage, bakery, and dairy channels. CAGRs were derived from demand elasticity modeling against income growth patterns in premium chocolate consumption markets and supply-side capacity expansion timelines in Côte d'Ivoire and Ghana. The analytical framework weighted EUDR compliance cost pass-through, precision fermentation technology maturation curves, and generational consumption shifts among millennial and Gen Z demographics.
Stress conditions across West African weather variability, EU regulatory enforcement intensity, and biotechnology substitution pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions around certification adoption rates and regional processing capacity commissioning schedules. Cross-checking against ICCO supply-demand balances and exchange price volatility indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Horehound Extract Market
Ingredients
Sesame Oil Market
Ingredients
Textured Milk Protein Market
Ingredients
Europe Phytosterols Market
Ingredients
Middle East and Africa Fruit and Vegetable Ingredients Market
Ingredients
Baobab Powder Market
Ingredients
Gluten-Free Flour Market
Ingredients
United States Gelatin Market
Ingredients
North America Agar Market
Ingredients
Specialty Yeast Market
Ingredients
Vital Wheat Gluten Market
Ingredients
Instant Dry Yeast Market
Ingredients
Africa Soy Protein Ingredients Market
Ingredients
Starch-Derived Fiber Market
Ingredients
India Gelatin Market
Ingredients
Microbial Food Ingredients Market