
 Wet Food Pouch Market | 2026-2036
Wet Food Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Wet Food Pouch Market Analytics
ISO 22000 certification for food safety management systems is redrawing competitive boundaries in wet food pouch supply. Amcor leverages its global film extrusion network to sustain high-barrier laminate output for retort applications. Berry Global anchors North American capacity through vertical integration into blown film and pouch converting. Mondi competes with kraft-paper hybrid structures that target fiber-reduction mandates in European retail.
A wet food pouch is a flexible laminated package, typically constructed from polyethylene, polyester, and aluminum foil layers, designed to contain moisture-rich food products under retort or hot-fill processing while preventing oxygen ingress and microbial contamination. Its primary commercial purpose is to replace rigid cans with lighter, shelf-stable formats that reduce logistics cost and improve consumer convenience in pet food and ready-meal segments. Stand-up pouches occupy the dominant share of packaging type demand due to superior shelf presence and pallet efficiency, while zip lock configurations capture the fastest growth trajectory as pet owners prioritize resealability for multi-serve wet food. Meat-based formulations lead product type volume, though mixed protein blends are gaining traction as brands respond to diversification in companion animal nutrition.
FDA regulations on indirect food additives under 21 CFR 177 govern laminate compositions in the United States, while EU REACH and the EU Packaging and Packaging Waste Regulation impose chemical disclosure and recyclability requirements that reshape material selection across European supply chains. BIS certification for food-contact plastics in India adds another compliance layer for exporters targeting emerging demand. Stakeholders must monitor how extended producer responsibility frameworks evolve, as these will determine whether multilayer pouches retain market access or face substitution by monomaterial alternatives.
Market Dynamics
EU REACH compliance on food-contact materials is forcing converters toward barrier film innovation while private-label concentration in German retail locks in format standardization.
Growth Catalysts
- Retort pouch adoption:Pet food brands are expanding wet pouch formats for single-serve convenience, displacing rigid cans in premium companion animal nutrition segments.
- German retail placement:Private-label pet food pouches command strong shelf positioning in German supermarkets, creating volume anchors for converter capacity investments.
- Zip lock configuration demand:Pet owners prioritize resealability for multi-serve wet food, pulling investment toward spouted and slider-equipped pouch designs.
Market Restraints
- Aluminum foil supply concentration:High-barrier laminates depend on limited European foil rolling capacity, exposing converters to input bottlenecks.
- Multilayer recyclability friction:EU Packaging and Packaging Waste Regulation imposes chemical disclosure and recyclability requirements that complicate material selection.
- Monomaterial substitution threat:Polyethylene-only structures are gaining technical viability for select wet food applications, threatening aluminum-dependent formats.
Strategic Opportunities
- India export channel:BIS certification for food-contact plastics creates a compliance moat for early entrants targeting emerging companion animal nutrition demand.
- Kraft-paper hybrid structures:Fiber-reduction mandates in European retail are opening specification windows for paper-based barrier laminates in ambient wet meals.
- Extended producer responsibility frameworks:Evolving EPR rules will reward converters with established recycling partnerships and design-for-recycling capabilities.
Industry Challenges
- ISO 22000 certification timelines:Food safety management system audits are extending qualification periods for new converter entrants.
- Hot-fill process integration:Legacy canning lines require capital-intensive retrofitting to accommodate flexible pouch formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wet Food Pouch Market |
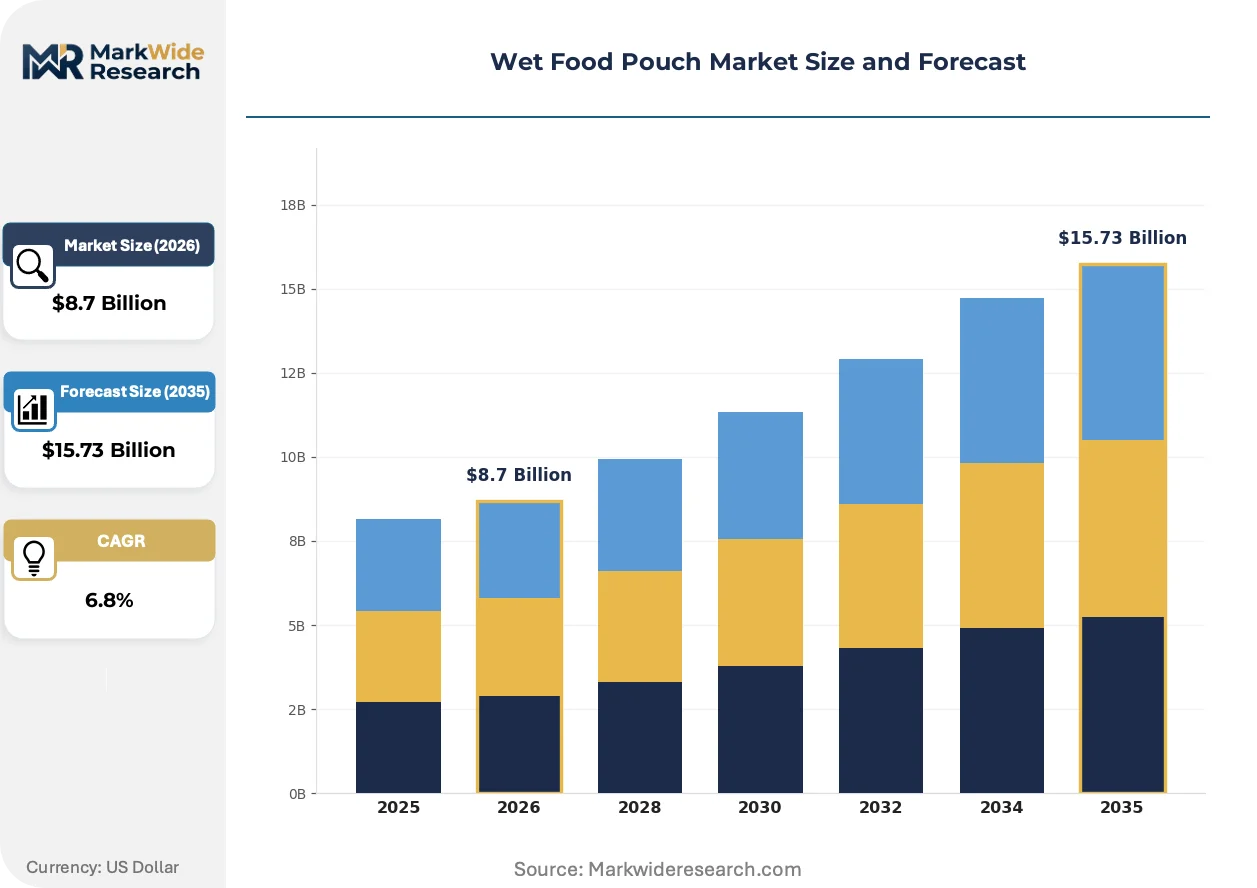
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat-Based, Fish-Based, Vegetable-Based, Mixed Protein Packaging Type: Stand-Up Pouches, Zip Lock Bags, Foil Pouches, Tear Notch Pouches End User: Pets, Human Consumption, Food Services, Retail Distribution Channel: Online Stores, Supermarkets, Convenience Stores, Specialty Shops |
| Companies Covered | Amcor, Berry Global, Ampac Holdings, Swiss Pac, Clifton Packaging, Berlin Packaging, Mondi, Sonoco Products Company, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wet Food Pouch Market Evolving Landscape
Active barrier technologies and regulatory chemistry disclosure are rewriting material specifications, while procurement patterns in pet food are compressing supplier qualification cycles.
High-barrier transparent oxide coatings are supplanting aluminum foil in select retort applications where microwaveability and optical inspection matter. Premium pet food brands in Germany and the Netherlands are piloting these structures for gravies and broths. This shift is supplanting traditional metallized polyester laminates in segments where brand differentiation through pack visibility outweighs absolute oxygen barrier performance.
EU REACH restrictions on per- and polyfluoroalkyl substances are tightening permissible chemistry in food-contact laminates. Industrial consequence falls heaviest on converters serving wet pet food and ready-meal segments with legacy grease-resistant coatings. German retailers are now demanding full substance disclosure down to 100 ppm thresholds, forcing reformulation of sealant layers and adhesive systems.
Direct sourcing from converter to brand is compressing the traditional distributor-wholesaler channel in European wet food packaging. Mid-size pet food manufacturers in France and Italy are building specification teams to engage pouch converters directly, bypassing regional packaging distributors. This pattern is most visible in organic and veterinary-diet segments where traceability requirements exceed distributor technical capabilities.
Wet Food Pouch Market Segmentation
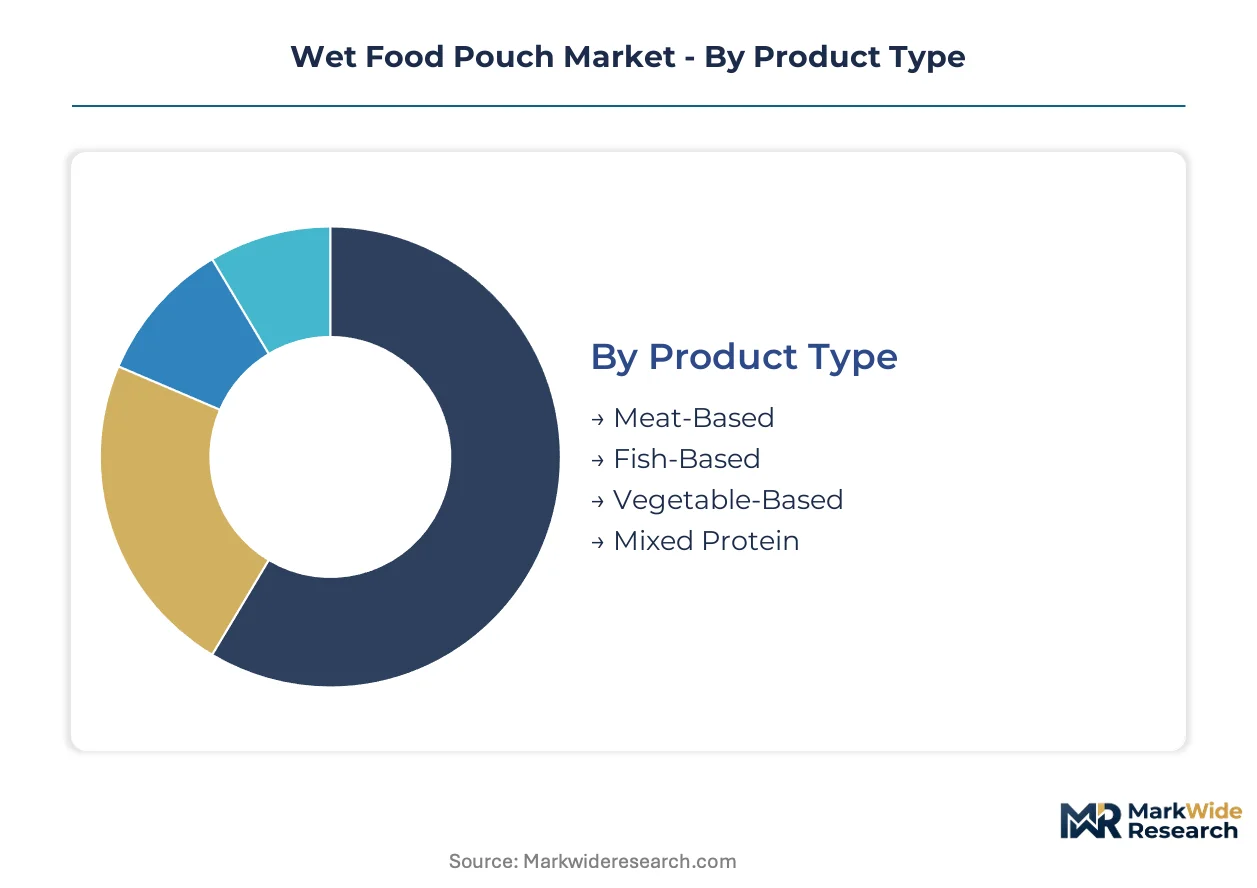
Wet food pouch segmentation reveals how regulatory pressure and processing requirements fragment converter capabilities across material specifications. Each dimension carries distinct compliance burdens that reshape supplier qualification and procurement patterns.
Product Type:
FDA regulations on indirect food additives under 21 CFR 177 and EU REACH disclosure mandates impose divergent chemistry requirements on protein-specific laminate formulations.
- Meat-Based:High-fat content demands aggressive oxygen barrier performance, typically delivered through aluminum foil laminates or metallized polyester layers. German private-label pet food brands anchor volume here, though REACH restrictions on per- and polyfluoroalkyl substances are forcing sealant reformulation.
- Mixed Protein:Formulation complexity creates variable pH and lipid migration profiles that stress adhesive bond integrity. Dutch and Italian premium brands are piloting these structures for companion animal nutrition diversification, pulling investment toward active barrier coatings.
- Fish-Based:Volatile amine compounds require specialized aroma barrier layers in retort applications.
- Vegetable-Based:Lower thermal processing tolerance permits thinner laminate structures with reduced aluminum dependency.
Established volume favors Meat-Based; emerging adoption favors Mixed Protein.
Packaging Type:
Format selection directly determines capital equipment requirements and line speed economics for converters.
- Stand-Up Pouches:Gable-bottom construction with multilayer barrier laminates dominates ambient wet pet food shelf placement. Germany and France drive specification standardization, though EPR frameworks are pressuring design-for-recycling modifications to bottom gusset geometry.
- Zip Lock Bags:Slider and press-to-close mechanisms add dimensional tolerance requirements that complicate high-speed filling. Pet owner resealability preferences in premium segments are climbing the fastest here, pulling converter R&D toward spout integration.
- Foil Pouches:Three-side-seal construction with full aluminum foil core remains standard for veterinary and therapeutic diets.
- Tear Notch Pouches:Laser-scored opening features reduce material overhead but limit resealability.
Volume concentrates in Stand-Up Pouches; specification innovation concentrates in Zip Lock Bags.
End User:
Traceability and certification requirements stratify sharply across consumer categories.
- Pets:ISO 22000 certification and lot-level traceability are non-negotiable for contract manufacturing relationships. Humanization trends in companion animal nutrition are expanding pouch adoption beyond traditional canned formats.
- Human Consumption:Retort processing specifications align with low-acid canned food regulations, demanding higher barrier performance than pet food equivalents.
- Food Services:Portion control and steam-table compatibility drive single-serve pouch specifications.
- Retail:Private-label concentration demands flexible MOQ structures and rapid format switching.
Certification intensity peaks with Pets; margin compression concentrates in Retail.
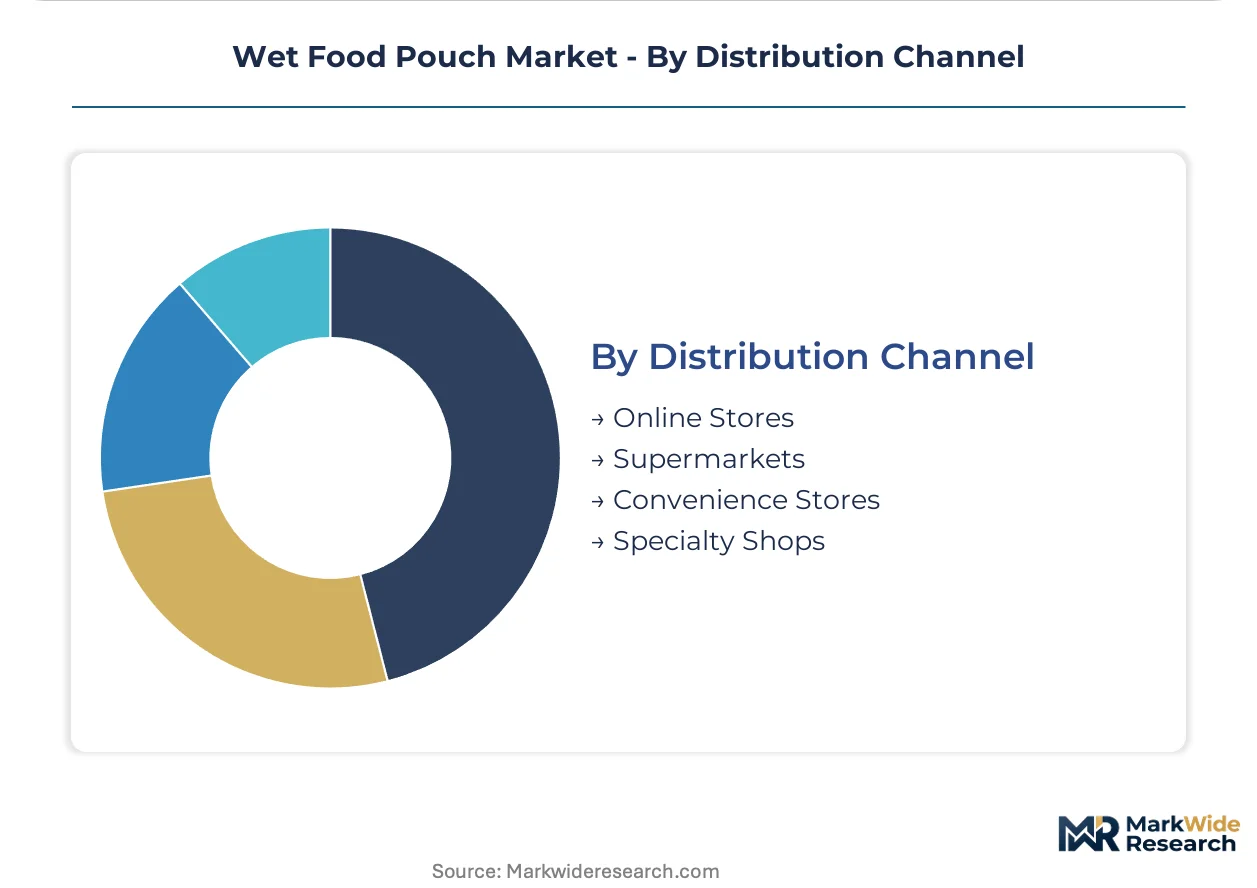
Distribution Channel:
Channel economics determine pack size standardization and pallet optimization requirements.
- Supermarkets:Shelf-ready packaging and case-count optimization dominate procurement specifications. German retail concentration enforces format standardization that locks in converter capacity allocation.
- Online Stores:Ship-in-own-container requirements and dimensional weight pricing favor lightweight pouch structures over rigid alternatives. Direct-to-consumer fulfillment is expanding most quickly in premium pet food subscription models.
- Convenience Stores:Impulse-oriented pack sizes and vertical merchandising constraints favor smaller footprint formats.
- Specialty Shops:Veterinary and organic certification claims require specialized printing and substrate verification.
Scale economies favor Supermarkets; channel growth favors Online Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH disclosure mandates on food-contact materials are redrawing procurement geography as converters seek compliant supply bases. Germany's private-label concentration anchors European volume, while Asia-Pacific emerging demand and North American pet food premiumization create divergent growth vectors.
Germany
Private-label pet food pouches command dominant supermarket shelf placement, driving format standardization across converter networks. ECHA enforcement of per- and polyfluoroalkyl substance restrictions forces sealant layer reformulation throughout the supply chain. The Rhine-Ruhr industrial corridor hosts concentrated flexible packaging capacity serving both domestic retail and Benelux export channels.
United States
Humanization trends in companion animal nutrition accelerate wet pouch displacement of traditional cans in premium segments. FDA oversight under 21 CFR 177 governs laminate composition compliance for indirect food additives. Wisconsin and Ohio host established converter clusters supplying Midwest pet food manufacturing corridors with high-barrier retort structures.
India
Rising pet ownership in metropolitan centers expands addressable market for imported wet food packaging formats. BIS certification requirements for food-contact plastics create qualification barriers that favor early-entrant converters with established testing relationships. Maharashtra's Thane-Belapur industrial zone attracts flexible packaging investments targeting domestic and Middle East export demand.
China
Domestic pet food brand consolidation drives specification upgrading toward retort-capable pouch formats. SAMR oversight of food-contact material safety standards intensifies post-import inspection protocols for foreign converters. The Yangtze River Delta flexible packaging cluster serves both local brand owners and contract manufacturing for European private-label exporters.
Netherlands
Premium organic pet food brands pilot transparent oxide-coated barrier structures for optical differentiation at retail. EU Packaging and Packaging Waste Regulation recyclability mandates accelerate design-for-recycling modifications to stand-up pouch geometries. The Eindhoven-Tilburg corridor hosts specialized coating operations supplying transparent barrier alternatives to aluminum-dependent laminates.
Wet Food Pouch Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The supplier base organizes around three archetypes: integrated multinational film producers, regional pouch converters with vertical film capabilities, and specialized barrier technology licensors. Consolidation pressure operates through backward integration moves and strategic partnerships with pet food brand owners seeking supply security.
Among integrated packaging groups, Amcor exemplifies global film extrusion scale applied to retort laminate output, while Berry Global anchors North American capacity through captive blown film production. Mondi occupies a distinct position representing fiber-based hybrid structures targeting European retail sustainability mandates. These three entities collectively illustrate how material technology specialization and geographic production placement define competitive positioning in high-barrier wet food applications.
| Leading Market Players |
|---|
| Amcor |
| Berry Global |
| Ampac Holdings |
| Swiss Pac |
| Clifton Packaging |
| Berlin Packaging |
| Mondi |
| Sonoco Products Company |
| ProAmpac |
| Others |
Value Network & Pricing Analysis
Converter capacity utilization above 85 percent in the Rhine-Ruhr corridor locks in price floors for high-barrier retort laminates, while underutilized foil rolling mills in Southern Europe create regional arbitrage windows. This scale asymmetry concentrates pricing power among integrated film producers and compresses margins for toll converters dependent on spot aluminum purchases.
Pricing Analysis
Certification level creates the primary spread, with ISO 22000-accredited converters commanding 15-20 percent premiums over uncertified competitors in German retail procurement. Three-tier pricing structure across premium, standard, and economy levels reflects barrier performance gradation, with aluminum-oxide-coated films occupying the premium tier and metallized polyester the standard. Cost compression in the economy tier is intensifying because private-label buyers are consolidating supplier panels. Pet food contract manufacturers show highest price sensitivity, while veterinary diet brands prioritize barrier reliability over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes have extended inbound resin lead times, forcing converters to carry higher polyethylene inventory buffers. Raw material sourcing concentrates in Germany, Belgium, and the Netherlands for film extrusion, while aluminum foil feeds from Greece and Italy. The supply chain hinges on single-source vulnerability in specialized adhesive chemistries subject to REACH disclosure mandates. Distribution runs through converter-direct relationships with pet food brand owners, bypassing traditional packaging distributors in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for barrier film selection and retort process optimization are expanding faster than commodity laminate sales, creating recurring revenue pools that offset raw material volatility. This service-attach dynamic rewards converters with formulation expertise and on-site technical support capabilities.
For Market Incumbents: Compound barrier technology leadership by acquiring specialized coating operations in the Netherlands and Belgium before transparent oxide alternatives reach cost parity. Lock in multi-year aluminum foil offtake agreements with Greek and Italian rolling mills to neutralize single-source exposure. Extend ISO 22000 certification coverage to all converting facilities to defend against private-label procurement consolidation.
For New Entrants and Emerging Players: After-sales technical support for retort process integration represents the most exploitable service gap, as incumbents under-serve mid-size pet food manufacturers transitioning from canning lines. Target Indian metropolitan brand owners seeking BIS-certified import partners for wet food pouch supply. Enter through design-for-recycling consulting engagements that address EU Packaging and Packaging Waste Regulation compliance before converting equipment investments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with established transparent barrier coating partnerships and recycling infrastructure alliances. Five-to-ten year viability rests on substitution risk from monomaterial polyethylene structures. Acquisition targets should demonstrate active barrier R&D pipelines and direct brand relationships. Watch aluminum oxide coating cost curves as the inflection signal for metallized film displacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blown Film | Captive polyethylene supply secures margin control against resin price volatility. |
| Transparent Oxide Coating Partnership | Access to microwaveable barrier technology addresses German premium pet food specifications. |
| Design-for-Recycling Certification | EPR compliance positioning unlocks continued access to EU retail channels. |
| Direct Brand Technical Service | On-site retort process support displaces distributor relationships in premium segments. |
| India BIS Certification Investment | Early compliance creates qualification moats for emerging companion animal nutrition demand. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU Packaging and Packaging Waste Regulation filings, ECHA substance restriction updates, and pet food industry trade data. Interviews with flexible packaging plant managers, pet food procurement leads, retail category buyers, and adhesive R&D directors were combined with analysis of customs records, SEC 10-K disclosures from listed converters, and BIS certification registries. Bottom-up capacity estimates and top-down demand projections were cross-validated through triangulation.
Segmentation dimensions modeled include barrier technology type, packaging format configuration, protein formulation category, end-use certification requirements, and geographic regulatory cluster. Volume and value outputs were derived through elasticity-adjusted extrapolation across the projection horizon, with CAGRs calibrated to historical converter capacity expansion rates and pet food brand format-switching timelines. Industry-specific inputs incorporated aluminum foil rolling capacity utilization, REACH compliance cost pass-through coefficients, and retort pouch adoption curves in premium pet food segments.
Material uncertainties — regulatory acceleration in per- and polyfluoroalkyl substance restrictions, aluminum supply disruptions from energy cost spikes, and technical breakthroughs in monomaterial barrier performance — sit outside the modeled envelope. Forecasts reflect assumptions about sustained private-label growth in German retail and continued EU enforcement of extended producer responsibility frameworks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Ready Meals Market
Packaged Foods
Singapore Ready-To-Eat Food Market
Packaged Foods
Packaged Rice Noodles Market
Packaged Foods
South America Pasta and Noodles Market
Packaged Foods
Club Store Packs Market
Packaged Foods
Man-Made Sausage Casing Market
Packaged Foods
Carbon Labeled Packaged Meal Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
North America Chewing Gum Market
Packaged Foods
Peanut Butter Market
Packaged Foods
United States Online Grocery Market
Packaged Foods
Instant Rice Market
Packaged Foods
Global Popping Candy Market
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
Europe Free from Food Market