
 Cocoa Butter Market | 2026-2036
Cocoa Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Cocoa Butter Market Intelligence
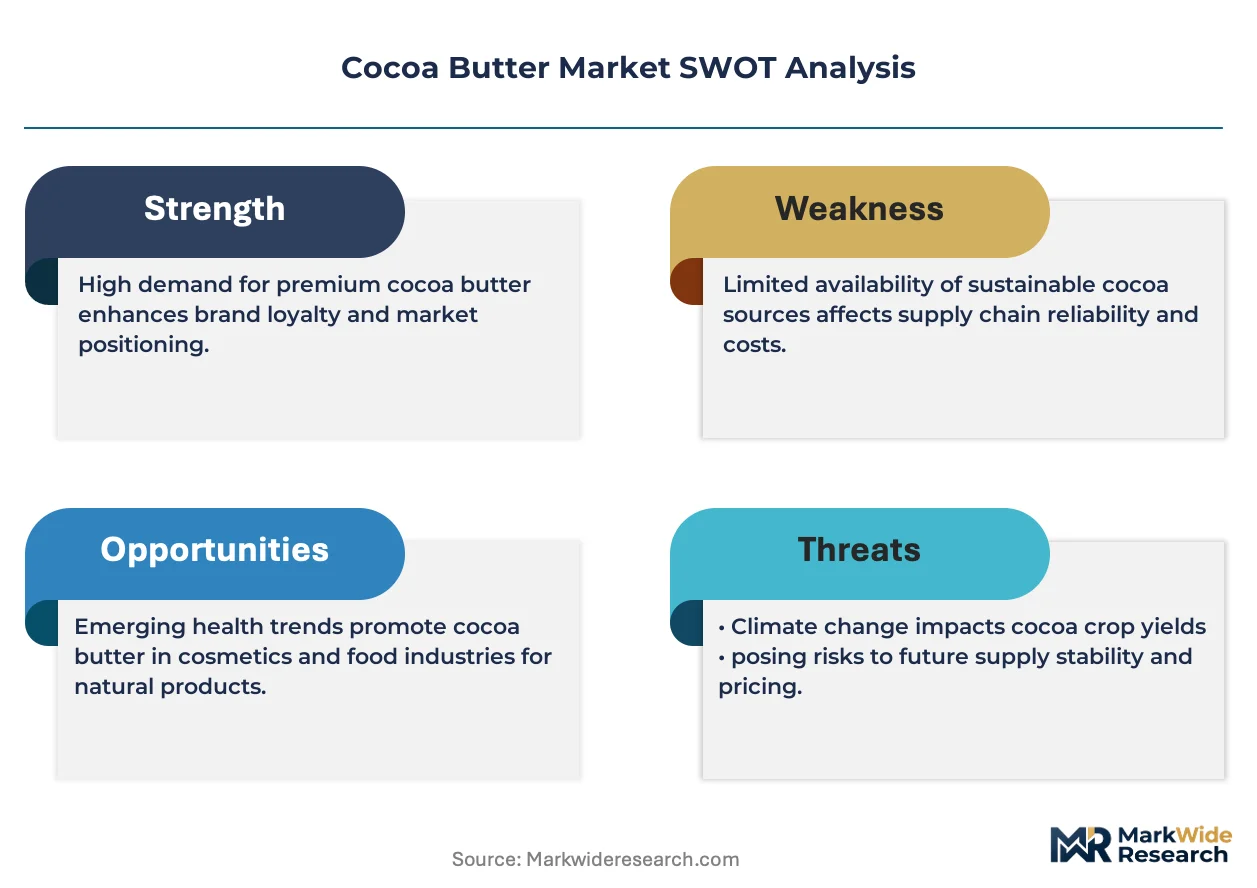
Rainforest Alliance certification is bifurcating the competitive landscape into compliant and non-compliant supply tiers. Barry Callebaut AG leverages its integrated bean-to-butter processing network across Côte d'Ivoire and Ghana to secure certified volumes. Cargill Incorporated anchors its position through farmer outreach programs that lock in traceable raw material flows. Olam International Limited competes by extending its sustainability verification infrastructure into smaller cooperative structures.
Cocoa butter is the natural fat extracted from cocoa beans, containing approximately 57-64% saturated fats dominated by stearic and palmitic acids alongside 33-40% monounsaturated oleic acid, with a melting point near 34°C that provides the snap and gloss essential to chocolate confectionery. The refined and deodorized grades command premium positioning in cosmetics and pharmaceuticals where odor neutrality and precise fatty acid profiles determine formulation acceptance. Confectionery applications still occupy the largest volume share, though organic cocoa butter is registering the fastest expansion as clean-label chocolate brands in Europe and North America reformulate around single-origin supply stories.
The EU Deforestation Regulation and FDA food safety standards are tightening chain-of-custody documentation, forcing exporters to adopt mass-balance or segregated certification systems. Ghana's Cocoa Board and Côte d'Ivoire's Coffee and Cocoa Council are tightening export licensing to capture more value through local processing mandates. Stakeholders must decide whether to absorb compliance costs through supplier consolidation or pass them through via butter premiums tied to verified provenience tiers.
Market Dynamics
The EU Deforestation Regulation is compressing supply chain timelines and forcing exporters to restructure traceability systems around mass-balance or segregated certification tiers.
Growth Catalysts
- Clean-label confectionery reformulation:Premium chocolate brands in Germany and Switzerland are expanding certified sustainable cocoa butter procurement to meet retailer sustainability mandates.
- REACH and EU Green Deal alignment:Cosmetics formulators are substituting petroleum-derived emollients with refined deodorized cocoa butter to satisfy chemical safety and carbon intensity disclosures.
- West African processing hub expansion:Côte d'Ivoire and Ghana are capturing downstream value through local butter extraction mandates that redirect export volumes.
Market Restraints
- Cocoa bean price volatility:Input costs swing with West African harvest cycles and speculative futures positioning, compressing processor margins.
- Supply concentration risk:Over 60% of global bean origin concentrates in Côte d'Ivoire and Ghana, exposing buyers to regional weather and political disruption.
- Shea butter substitution in cosmetics:Formulators in mass-market skincare are pivoting to shea-derived stearin for cost-sensitive applications.
Strategic Opportunities
- Single-origin organic certification:Clean-label chocolate brands in North America are building supply stories around Ecuadorian and Peruvian cooperative sourcing.
- Pharmaceutical-grade butter expansion:Suppository and ointment manufacturers are qualifying deodorized cocoa butter for USP monograph compliance.
- CSRD supply chain disclosure:EU corporate sustainability reporting mandates are creating premium tiers for fully traceable butter with geolocation verification.
Industry Challenges
- Chain-of-custody documentation complexity:Exporters must integrate geolocation data and farm polygon mapping into ERP systems to satisfy EUDR compliance deadlines.
- Refinery retrofitting capex:Deodorization and fractionation equipment upgrades require capital deployment to meet pharmaceutical odor neutrality specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocoa Butter Market |
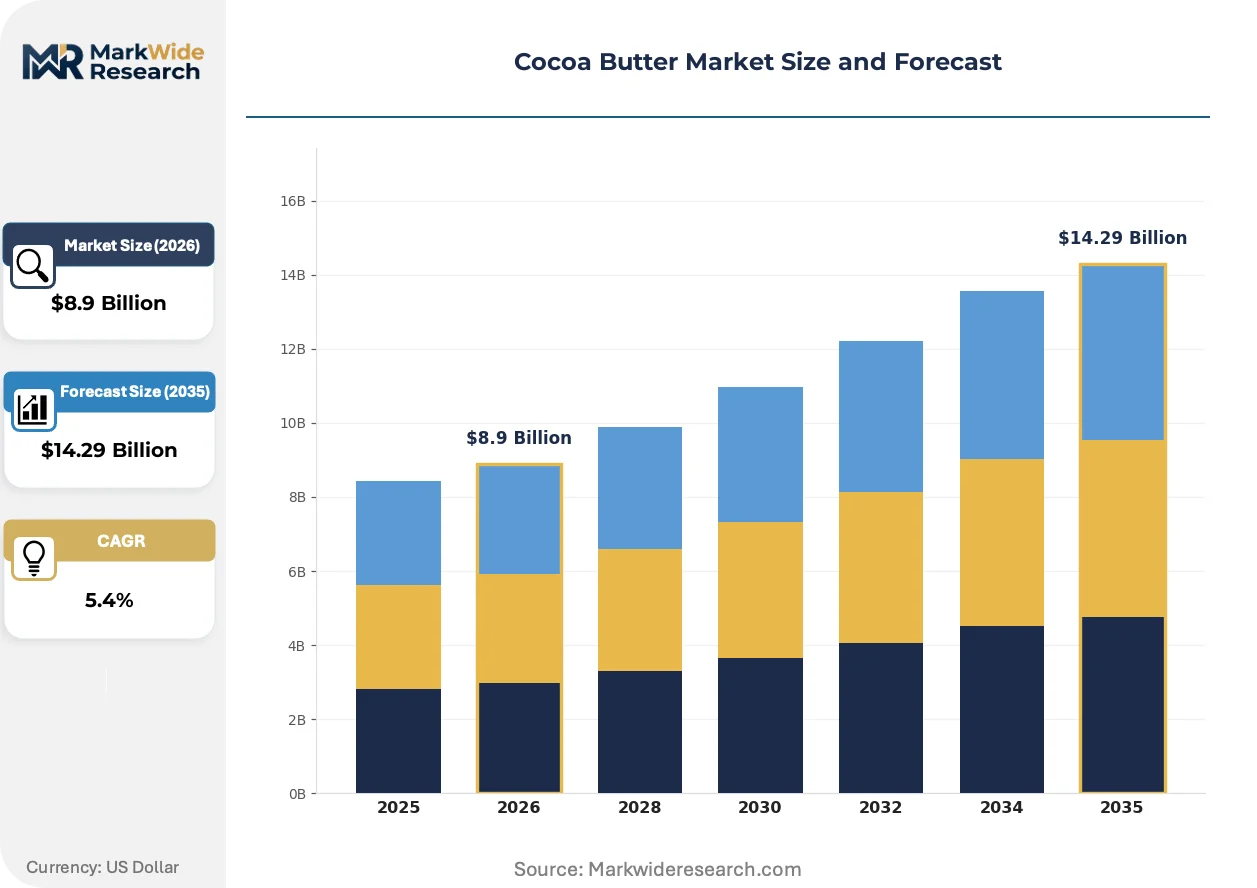
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $14.29 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Cocoa Butter, Refined Cocoa Butter, Organic Cocoa Butter, Deodorized Cocoa Butter Application: Confectionery, Cosmetics, Pharmaceuticals, Industrial Lubricants, Food Industry End User: Chocolate Manufacturers, Personal Care Brands, Pharmaceutical Companies, Industrial Manufacturers Packaging Type: Foil Bags, Plastic Containers, Bulk Drums, Glass Jars |
| Companies Covered | Mondelēz International, Olam International Limited, Barry Callebaut AG, TOUTON S.A., Cemoi Group, Cargill Incorporated, Mars Incorporated, Natra S.A., Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocoa Butter Market Strategic Shifts & Innovations
Processing technology and regulatory disclosure requirements are converging to reshape how cocoa butter is extracted, certified, and sold across confectionery, cosmetics, and pharmaceutical channels.
Supercritical CO2 extraction is miniaturizing at commercial scale, enabling mid-sized processors to bypass solvent-based degumming and produce pharmaceutical-grade butter with tighter fatty acid profiles. Specialty chocolate manufacturers in Belgium and Switzerland are adopting these systems to secure single-origin supply stories. The technology is miniaturizing capital barriers that previously locked premium processing behind integrated multinationals.
EMA and EFSA are tightening contaminant thresholds for polycyclic aromatic hydrocarbons in cocoa-derived ingredients, forcing European refiners to upgrade deodorization temperatures and filtration sequences. This regulatory compression is accelerating consolidation among smaller processors lacking thermal processing capabilities. Cosmetics formulators in France and Germany are now demanding batch-specific CoA documentation that exceeds previous food-grade standards.
Buyer consolidation among European retail private-label chocolate programs is displacing spot-market purchasing with multi-year offtake contracts tied to verified provenience tiers. This procurement restructuring is squeezing independent traders and redirecting volume through vertically integrated processors with captive farm outreach networks. The shift is most visible in German and Swiss supply chains where Aldi and Lidl sustainability mandates have compressed supplier panels.
Cocoa Butter Market Segmentation
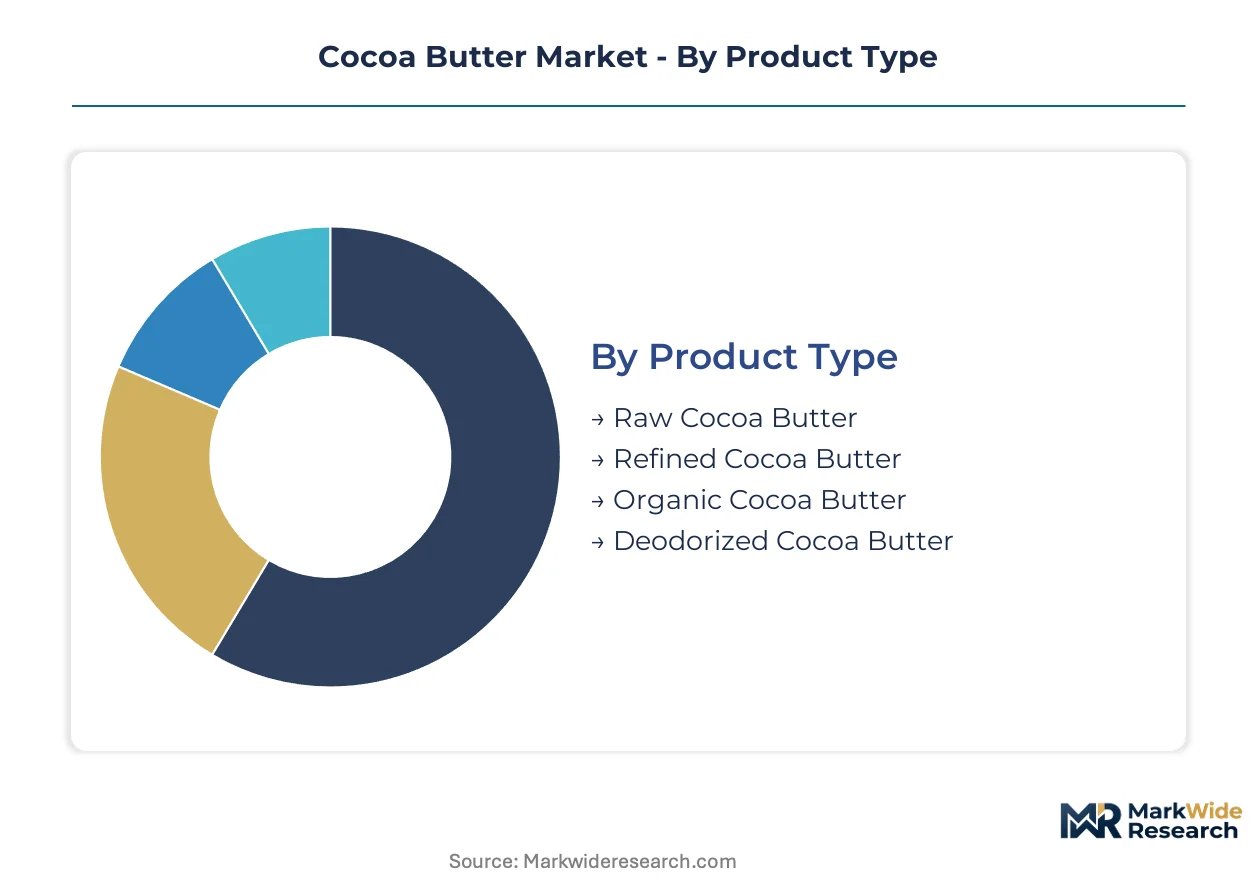
Cocoa butter segmentation maps directly to processing intensity, certification tiers, and end-use specifications that determine pricing power. Buyers across confectionery, cosmetics, and pharmaceutical channels source from distinct product grades with non-interchangeable quality thresholds.
Product Type:
Substitution pressure from shea butter and palm stearin hits hardest at the raw and unrefined tiers, where odor variation and inconsistent fatty acid profiles limit application scope.
- Deodorized Cocoa Butter:High-temperature steam stripping removes volatile compounds to achieve neutral odor and sub-0.1% free fatty acid content. Pharmaceutical manufacturers in Germany and Switzerland specify deodorized grades for USP-compliant suppository bases, where batch consistency determines supplier qualification.
- Refined Cocoa Butter:Alkalization and bleaching steps strip color and acidity while preserving the 34°C melting point critical to chocolate tempering. Premium confectionery brands in Belgium source refined grades for molded pralines where surface gloss requirements exclude raw alternatives.
- Raw Cocoa Butter:Cold-pressed extraction retains polyphenols and chocolate aroma for artisan bean-to-bar producers seeking single-origin flavor expression.
- Organic Cocoa Butter:Certified supply chains from Ecuadorian and Peruvian cooperatives command 15-40% premiums over conventional grades in North American clean-label chocolate formulations.
Refined cocoa butter retains volume leadership; organic cocoa butter holds the steepest expansion curve.
Application:
Margin structures diverge sharply across application tiers, with pharmaceutical and premium confectionery commanding triple-digit spreads over industrial lubricant grades.
- Confectionery:Tempering-stable polymorph V crystal formation provides the snap and gloss defining premium chocolate mouthfeel. Swiss and German manufacturers specify precise stearic acid ratios between 32-37% to control bloom resistance in seasonal gift assortments.
- Cosmetics:Emollient properties and comedogenic ratings near 4 position cocoa butter as a mid-tier moisturizer ingredient. French formulators blend refined grades with shea-derived stearin to balance cost and skin-feel in mass-market skincare.
- Pharmaceuticals:Suppository and topical ointment manufacturers require deodorized USP monograph compliance with documented heavy metal and pesticide residue testing.
- Food Industry:Bakery and ice cream applications leverage cocoa butter's solid fat content for texture modification in compound coatings.
- Industrial Lubricants:Biodegradable base stock applications in marine and food-processing equipment exploit oxidative stability from natural antioxidant content.
Confectionery absorbs the largest volume share; pharmaceutical applications are climbing the fastest as USP qualification expands.
End User:
Procurement scale and certification requirements stratify end users into spot-market buyers and contract-locked volume purchasers with divergent supplier relationships.
- Chocolate Manufacturers:Integrated processors like Barry Callebaut AG and Cargill Incorporated supply multinational brands with mass-balance certified butter under multi-year offtake agreements.
- Personal Care Brands:L'Oréal and Unilever specify refined deodorized grades with batch-specific CoA documentation exceeding food-grade standards for facial moisturizer formulations.
- Pharmaceutical Companies:Pfizer and GSK qualify suppliers through extended stability testing for suppository bases requiring 24-month shelf-life guarantees.
- Industrial Manufacturers:Food equipment and marine lubricant blenders source technical-grade butter through commodity traders with minimal certification overhead.
Chocolate manufacturers dominate procurement volumes; pharmaceutical companies are gaining share fastest as USP monograph adoption spreads.
Packaging Type:
Export logistics and contamination risk shape packaging selection, with ocean freight consolidation favoring bulk formats and premium retail channels demanding consumer-ready presentation.
- Bulk Drums:200-liter steel drums with nitrogen flushing preserve oxidative stability during West African port-to-Europe transit for industrial-scale chocolate processors.
- Foil Bags:Multi-layer aluminum laminates block light and moisture for 25kg artisan chocolate maker shipments requiring extended ambient storage.
- Plastic Containers:HDPE pails serve cosmetics compounders with intermediate batch sizes and frequent formulation changeovers.
- Glass Jars:Premium retail positioning for organic and single-origin variants in North American specialty food channels.
Bulk drums retain volume leadership; foil bags are expanding most quickly as mid-scale processor networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Deforestation Regulation is redirecting procurement flows toward verified supply corridors in West Africa and Latin America. Processing capacity expansion in origin countries is capturing downstream value previously exported to European refiners. Traceability mandates are compressing supplier panels and favoring integrated processors with captive farm networks.
Germany
Retail sustainability mandates from Aldi and Lidl are forcing chocolate manufacturers to source mass-balance certified cocoa butter. The country's national food safety regulator enforces strict contaminant thresholds under EU harmonized standards. Cologne and Hamburg host major processing facilities where deodorization equipment upgrades are accelerating to meet pharmaceutical-grade specifications.
Switzerland
Premium chocolate brands in Zurich and Geneva are expanding single-origin cocoa butter procurement for clean-label gift assortments. Swissmedic maintains pharmaceutical-grade standards that exceed general food safety requirements for suppository applications. The Lake Geneva corridor concentrates refining capacity where supercritical CO2 extraction systems are miniaturizing for mid-scale processors.
Côte d'Ivoire
The Coffee and Cocoa Council is tightening export licensing to mandate local butter extraction before shipment. Abidjan's processing hub is expanding fractionation capacity to supply European confectioners directly. San Pedro port infrastructure upgrades are reducing transit times for bulk drum shipments to Belgian and Swiss chocolate manufacturers.
Ghana
Ghana Cocoa Board licensing reforms are redirecting bean flows toward domestic processing facilities. Tema's industrial zone hosts expanding refinery complexes serving pharmaceutical and cosmetic grade demand. Accra-based cooperatives are adopting geolocation verification systems to satisfy EUDR farm polygon mapping requirements.
United States
FDA food safety standards and emerging state-level supply chain disclosure laws are elevating documentation requirements for imported cocoa butter. New Jersey and Pennsylvania processing clusters are qualifying deodorized grades for USP monograph compliance in suppository manufacturing. Specialty chocolate makers in Brooklyn and San Francisco are building direct trade relationships with Ecuadorian cooperatives for organic certified supply.
Cocoa Butter Market Key Industry Players
Player mix skews toward integrated processors with captive West African supply networks. The competitive structure concentrates around three tiers: multinational grinders with bean-to-butter infrastructure, regional refiners serving pharmaceutical specifications, and origin-country processors capturing local extraction mandates. Strategic differentiation centers on certification tier access, traceability system depth, and deodorization capability for odor-neutral grades. Consolidation pressures are intensifying as compliance costs favor scale, while technology licensing agreements spread supercritical extraction capabilities beyond integrated majors.
Among integrated processors with West African infrastructure, Barry Callebaut AG, Cargill Incorporated, and Olam International Limited occupy positions defined by their bean-to-butter network scale. Barry Callebaut exemplifies the European-based grinder archetype with extensive Côte d'Ivoire and Ghana processing presence. Cargill represents the agricultural commodity major model with farmer outreach programs locking in traceable raw material flows. Olam sits within the Singapore-origin diversified agribusiness tier extending sustainability verification into smaller cooperative structures. These three anchors demonstrate how geographic integration and certification infrastructure determine competitive positioning under tightening EUDR requirements.
| Leading Market Players |
|---|
| Mondelēz International |
| Olam International Limited |
| Barry Callebaut AG |
| TOUTON S.A. |
| Cemoi Group |
| Cargill Incorporated |
| Mars Incorporated |
| Natra S.A. |
| Nestlé S.A. |
| Others |
Cost & Logistics Intelligence
Bean-to-butter processing scale in Côte d'Ivoire and Ghana anchors cost structures across the value chain, compressing margins for smaller refiners while elevating price floors for certified grades. Capacity utilization at West African origin hubs directly shapes European import premiums and the viability of spot-market alternatives.
Pricing Analysis
Certification level creates the primary spread between deodorized pharmaceutical grades and raw commodity tiers. Three-tier pricing structure across premium, standard, and economy levels reflects EUDR compliance status, with mass-balance certified butter commanding substantial premiums over conventional alternatives. Price differentiation intensifies as Aldi and Lidl sustainability mandates force German manufacturers to absorb compliance costs or consolidate supplier panels. Industrial lubricant buyers exhibit highest price sensitivity, while Swiss pharmaceutical manufacturers prioritize batch consistency over unit economics.
Supply Chain Analysis
Côte d'Ivoire and Ghana anchor global cocoa bean supply, with over sixty percent of harvest origin concentrating in these two West African nations. The chain draws from smallholder cooperative structures, industrial plantation networks, and mid-scale farmer associations as primary input sources. Single-source vulnerability intensifies as local processing mandates redirect export volumes away from European refiners. Distribution runs through vertically integrated processors with captive farm outreach networks rather than independent trader channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Traceability infrastructure is emerging as the platform layer where certification interoperability determines supplier survival, with EUDR farm polygon mapping becoming the de facto standard for European market access.
For Market Incumbents: Secure backward integration into West African processing assets before export licensing reforms tighten further. Lock in multi-year offtake contracts with geolocation-verified cooperatives to defend against shea butter substitution in cosmetics and origin-country value capture mandates. For New Entrants and Emerging Players: Rainforest Alliance fast-track certification opens access to German and Swiss retail private-label programs displaced by Aldi and Lidl supplier panel consolidation. Target Ecuadorian and Peruvian organic cooperative sourcing for North American clean-label chocolate white space, leveraging direct trade relationships as differentiation against integrated majors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among processors with captive farm networks and deodorization capabilities serving pharmaceutical specifications. Long-term viability rests on EUDR compliance infrastructure depth rather than commodity trading scale. Watch for supercritical CO2 extraction technology licensing spreads as inflection signal for mid-scale processor competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origin Processing | Côte d'Ivoire's Coffee and Cocoa Council licensing reforms reward local butter extraction with preferential export quotas. |
| EUDR Compliance Infrastructure Buildout | Farm polygon mapping and geolocation verification systems satisfy EU Deforestation Regulation deadlines for European market access. |
| Pharmaceutical-Grade Deodorization Capacity | USP monograph compliance opens suppository and ointment manufacturing channels in Germany and Switzerland. |
| Supercritical CO2 Extraction Licensing | Technology miniaturization enables Belgian and Swiss mid-scale processors to bypass solvent-based degumming. |
| Single-Origin Organic Certification | Ecuadorian and Peruvian cooperative supply stories command premium positioning in North American clean-label chocolate. |
Research Approach
Initial hypotheses were tested against primary input from cocoa processing plant managers, confectionery procurement leads, cosmetics formulators, and cooperative agronomists and refined through secondary validation. Trade data from customs authorities, Coffee and Cocoa Council export statistics, SEC filings from integrated processors, and EUDR implementation guidance documents anchored quantitative baselines. Bottom-up volume estimates from origin-country processing capacity triangulated against top-down demand segmentation across confectionery, cosmetics, and pharmaceutical channels.
Variance decomposition across product grade, application specification, certification tier, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate synthesis rather than single-point extrapolation. Forecast inputs incorporated EUDR compliance timeline acceleration, shea butter substitution elasticity in mass-market skincare, and West African local processing mandate enforcement intensity.
Decision-makers should treat outputs as directional under sustained EUDR implementation and stable cocoa bean harvest assumptions; material deviation in regulatory enforcement or weather disruption would warrant model refresh. Recalibration cycles align with material shifts in EU deforestation policy implementation phases and origin-country export licensing reforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Smoke Ingredients for Food Market
Ingredients
Europe Protein Market
Ingredients
Alcohol Ingredients Market
Ingredients
Custom Dry Ingredients Blends Market
Ingredients
Global Infant Nutrition Ingredients Market
Ingredients
Rennet Market
Ingredients
Asia-Pacific Carrageenan Market
Ingredients
Prenatal Vitamin Ingredients Market
Ingredients
China Protein Market
Ingredients
Middle East and Africa Dairy Protein Ingredients Market
Ingredients
Sesame Seed Extract Market
Ingredients
Thinned Starch Market
Ingredients
Rice Bran Fatty Alcohols Market
Ingredients
Asia-Pacific Gelatin Market
Ingredients
Confectionery Ingredients Market
Ingredients
India Protein Market