
 Iran Breakfast Cereals Market | 2026-2036
Iran Breakfast Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Breakfast Cereals Market Analysis
Multi-source grain procurement is restructuring supply dynamics for Iranian cereal manufacturers. Shirin Meharara Company leverages domestic wheat and barley sourcing to sustain production continuity despite import constraints. Kellogg Company competes through brand recognition among urban consumers, while Nestle S.A. differentiates via fortified product lines aligned with local nutritional priorities. General Mills Inc. navigates distribution complexities through partnerships with regional wholesalers rather than direct retail presence.
Breakfast cereals comprise processed grain formulations—typically flaked, puffed, or extruded—often fortified with vitamins and minerals, designed for rapid preparation and consumption with milk or yogurt as a morning meal substitute. Ready-to-Eat formats dominate shelf space in Iranian supermarkets due to convenience alignment with dual-income household schedules, while Hot Cereals retain stronger penetration in northern provinces with colder climates. Whole Grain ingredient positioning commands premium pricing among health-conscious consumers in Tehran, whereas Corn-based formulations occupy volume-driven segments through lower per-unit costs accessible to price-sensitive buyers.
The Institute of Standards and Industrial Research of Iran mandates nutritional labeling and fortification standards that shape product formulation decisions, while the Ministry of Health and Medical Education oversees food safety protocols affecting import approvals and domestic manufacturing licenses. Iran's national customs administration enforces tariff structures on imported grain inputs and finished cereals that directly influence local production economics versus import substitution strategies. Stakeholders must monitor regulatory adjustments to fortification requirements and import licensing procedures as determinants of competitive positioning in this evolving market.
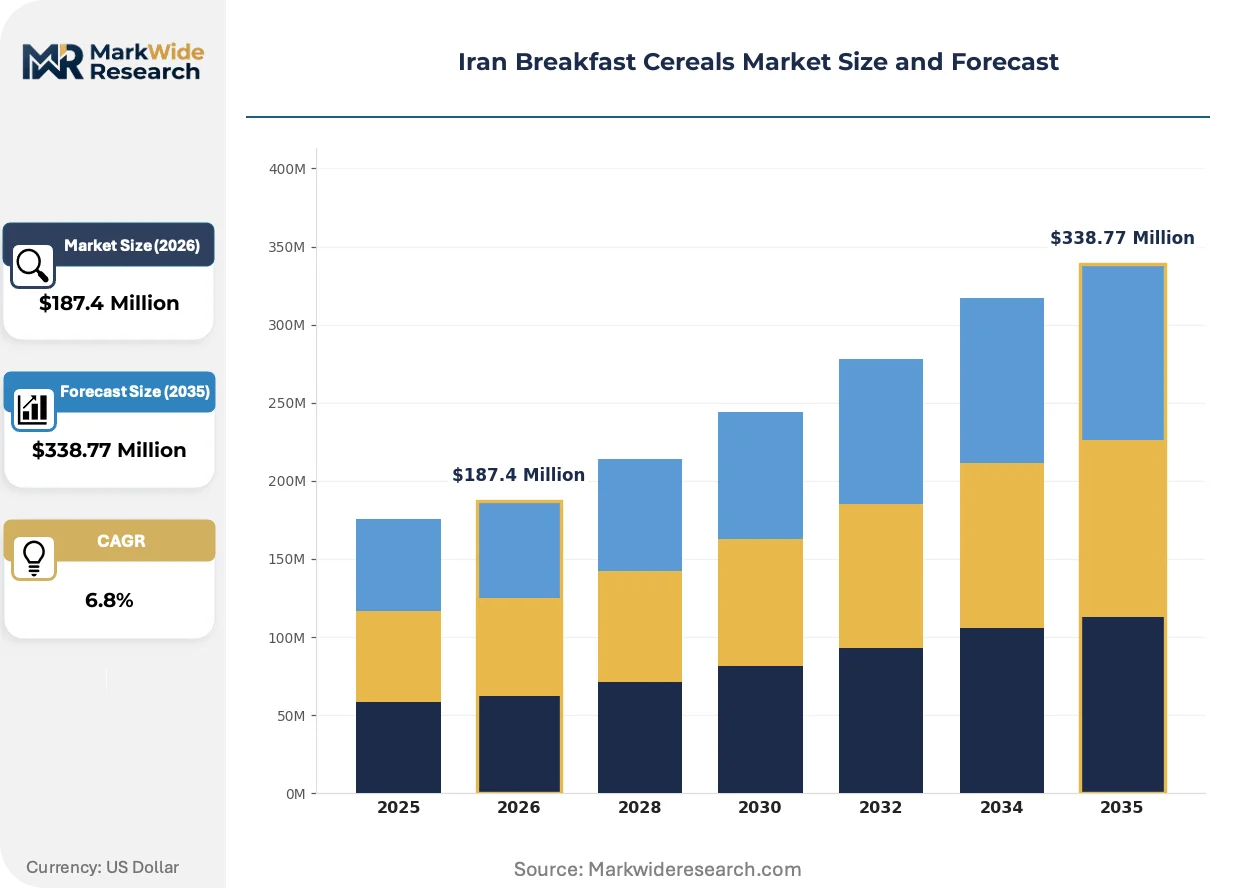
Market Dynamics
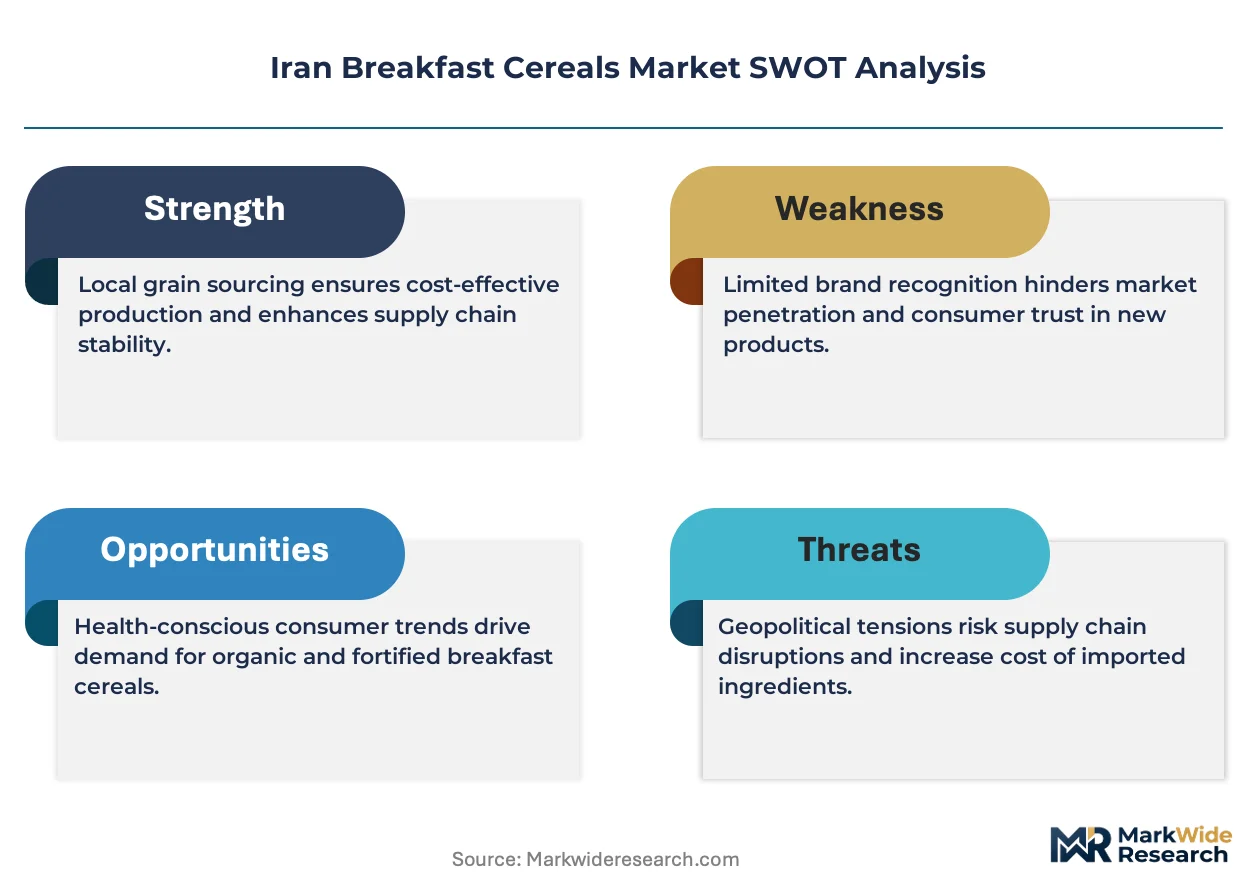
Fortification mandates from the Institute of Standards and Industrial Research of Iran are compressing formulation timelines while dual-income household schedules pull demand toward convenience formats. This regulatory-demand tension defines current competitive maneuvering.
Growth Catalysts
- Urban retail modernization:Supermarket chains in Tehran Province are expanding cold-chain capacity, enabling wider ready-to-eat cereal distribution to middle-income households.
- ISIRI fortification standards:Mandatory vitamin and mineral enrichment rules create product differentiation pathways for manufacturers investing in compliant formulations.
- Dual-income household expansion:Working parents in Mashhad and Tehran prioritize breakfast solutions requiring under three minutes of preparation time.
Market Restraints
- Grain import tariff structures:Iran's national customs administration imposes duties on wheat and barley inputs that elevate domestic production costs versus regional competitors.
- Currency volatility:Fluctuating rial exchange rates against dollar-denominated packaging and equipment imports destabilize capital expenditure planning for facility upgrades.
- Refrigerated logistics gaps:Cold-chain infrastructure remains concentrated in northern provinces, limiting fortified yogurt-accompanied cereal penetration to southern markets.
Strategic Opportunities
- E-commerce platform expansion:Online retail channels in Tehran Province are capturing cereal sales from traditional bazaar distribution, rewarding direct-to-consumer packaging investments.
- Whole grain premium positioning:Health-conscious consumers in northern provinces demonstrate willingness to pay elevated prices for fiber-forward formulations.
- Ministry of Health co-development:Partnerships with the Ministry of Health and Medical Education on school breakfast programs open institutional procurement channels.
Industry Challenges
- Food technologist scarcity:Formulation expertise for extruded cereal matrices remains concentrated among a limited pool of trained specialists in Tehran.
- Labeling compliance timelines:ISIRI nutritional disclosure updates require 90-120 day packaging redesign cycles that disrupt seasonal product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Breakfast Cereals Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Eat, Hot Cereals, Muesli, Granola Ingredient Type: Whole Grain, Oats, Corn, Rice Packaging Type: Bags, Boxes, Cups, Sachets Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers |
| Companies Covered | Shirin Meharara Company, OBST S.A., Kellogg Company, General Mills Inc., PepsiCo Inc., Nestle S.A., Shirin Asal, Kellanov, TakMakaron, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Breakfast Cereals Market Emerging Trajectories
Extrusion technology advancement is reshaping texture and fortification delivery in Iranian cereal manufacturing. Three developments are compressing competitive timelines.
Modified atmospheric packaging is converging with barrier film technology to extend shelf stability of vitamin-fortified flakes without synthetic preservatives. Urban supermarkets in Tehran are prioritizing these formats for their reduced spoilage rates. The structural result is converging with premium private-label expansion as local brands match multinational shelf-life performance.
ISIRI labeling amendments now mandate front-of-pack nutritional scoring that compresses marketing claims into standardized iconography. Manufacturers must reformulate or reposition existing SKUs to maintain shelf positioning under these disclosure rules. Tehran-based producers are responding fastest, leveraging proximity to regulatory consultation channels.
Clustering of breakfast consumption around workplace commutes is displacing traditional home-prepared morning meals among Mashhad's service-sector employees. Single-serve portion packs are capturing this occasion through convenience-store channels. Northern province cold climates sustain hot cereal demand, but Tehran's warmer seasons accelerate ready-to-eat format rotation.
Iran Breakfast Cereals Market Segmentation
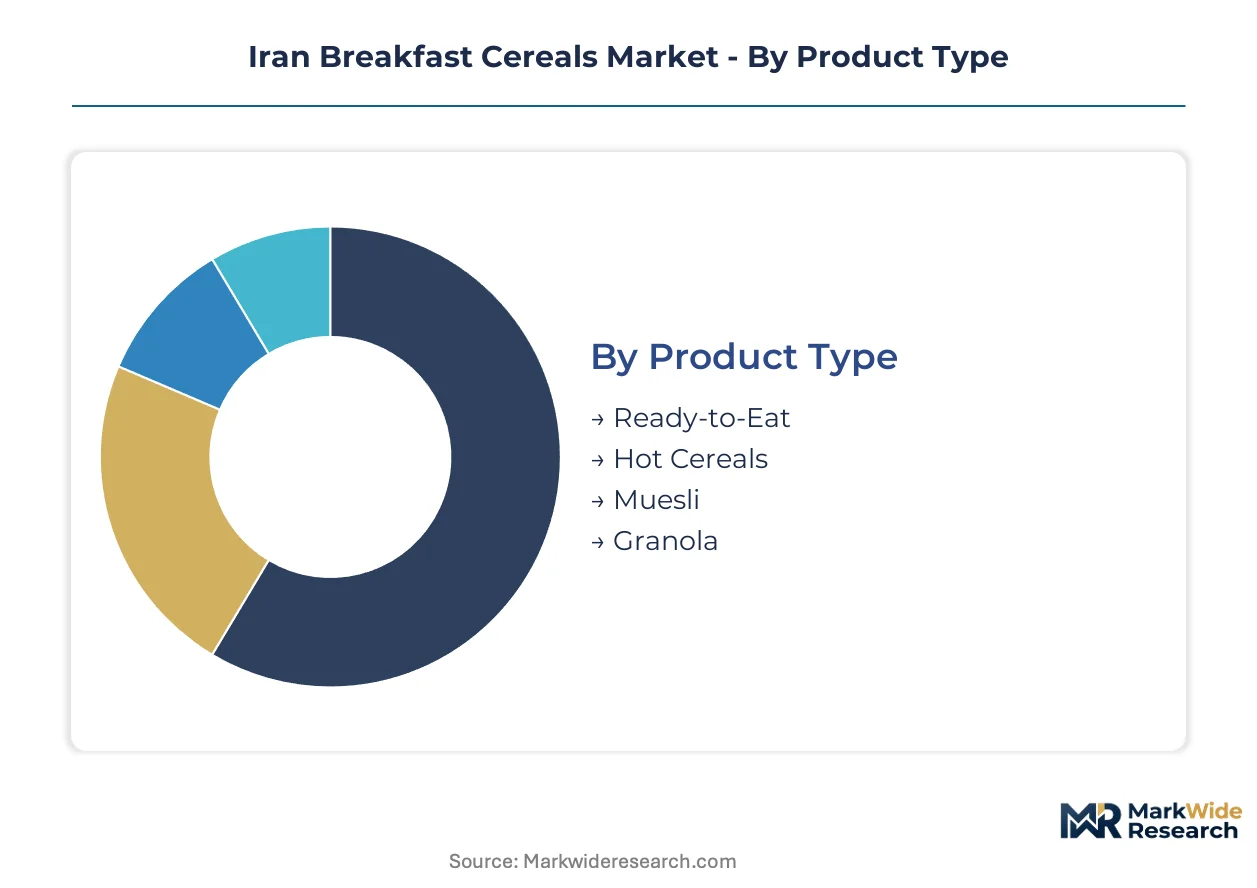
Segmentation in Iran's breakfast cereals market reveals how convenience demands, health positioning, and retail infrastructure shape purchasing decisions across Tehran's urban centers and provincial markets. Manufacturers align formulation, packaging, and channel strategies to distinct consumer clusters defined by preparation time constraints and nutritional priorities.
Product Type:
Volume-driven segments dominate supermarket shelf space while premium formats capture health-conscious households willing to pay elevated per-gram prices.
- Ready-to-Eat:Pre-processed grain formulations requiring no cooking, typically consumed with cold milk or yogurt. Tehran Province dual-income households drive demand as supermarket cold-chain expansion enables year-round distribution of vitamin-fortified flakes and puffed varieties.
- Hot Cereals:Oat-based or semolina formulations requiring hot water or milk preparation. Northern provinces including Gilan and Mazandaran sustain stronger penetration due to colder morning temperatures and traditional porridge consumption patterns.
- Muesli:Unbaked mixtures of rolled oats, dried fruits, and nuts targeting fiber-conscious consumers. Shirin Meharara Company and domestic producers emphasize local dried fruit inclusions to differentiate from imported alternatives.
- Granola:Baked oat clusters with sweeteners and oils, positioned as premium snacking or breakfast topping. Limited domestic production capacity constrains supply, creating import dependency for baked-cluster texture expertise.
Today's leader: Ready-to-Eat. Tomorrow's challenger: Muesli.
Ingredient Type:
Raw material sourcing geography and ISIRI fortification compliance requirements segment ingredient strategies across domestic procurement and import-dependent formulations.
- Whole Grain:Unrefined wheat, barley, or oat formulations retaining bran and germ layers. Health-conscious consumers in Tehran's northern districts pay premium pricing for fiber-forward positioning aligned with Ministry of Health nutritional guidelines.
- Oats:Rolled or steel-cut oat formulations imported primarily from Russia and Kazakhstan due to limited domestic cultivation. Tariff structures on oat imports elevate production costs versus wheat-based alternatives.
- Corn:Maize-based flakes and puffs leveraging domestic harvests from Khuzestan and Golestan provinces. Lower per-unit input costs enable volume pricing accessible to price-sensitive households in secondary cities.
- Rice:Puffed rice formulations traditional to northern Iranian breakfast culture. Localized demand concentration limits national distribution scale compared to wheat or corn alternatives.
Corn commands current volume leadership. Whole grain climbs fastest on health-premium positioning.
Packaging Type:
Packaging selection reflects retail channel requirements, portion control trends, and ISIRI labeling compliance timelines that favor standardized format investments.
- Bags:Flexible film packaging for bulk family-size cereal volumes. Dominates wholesale and traditional retail channels where price-per-gram sensitivity overrides premium presentation requirements.
- Boxes:Rigid cardboard containers with modified atmospheric inner liners. Tehran supermarket chains prioritize these formats for shelf stability and front-of-pack nutritional scoring visibility under ISIRI amendments.
- Cups:Single-serve rigid containers with peelable lids. Convenience stores near Mashhad workplace clusters stock these for commuter consumption occasions requiring no additional dishware.
- Sachets:Small-format flexible pouches for trial sizes or hot cereal single servings. E-commerce platforms utilize these for direct-to-consumer sampling campaigns with lower shipping weight.
Boxes anchor supermarket presence. Cups gain fastest on commute-consumption clustering.
Distribution Channel:
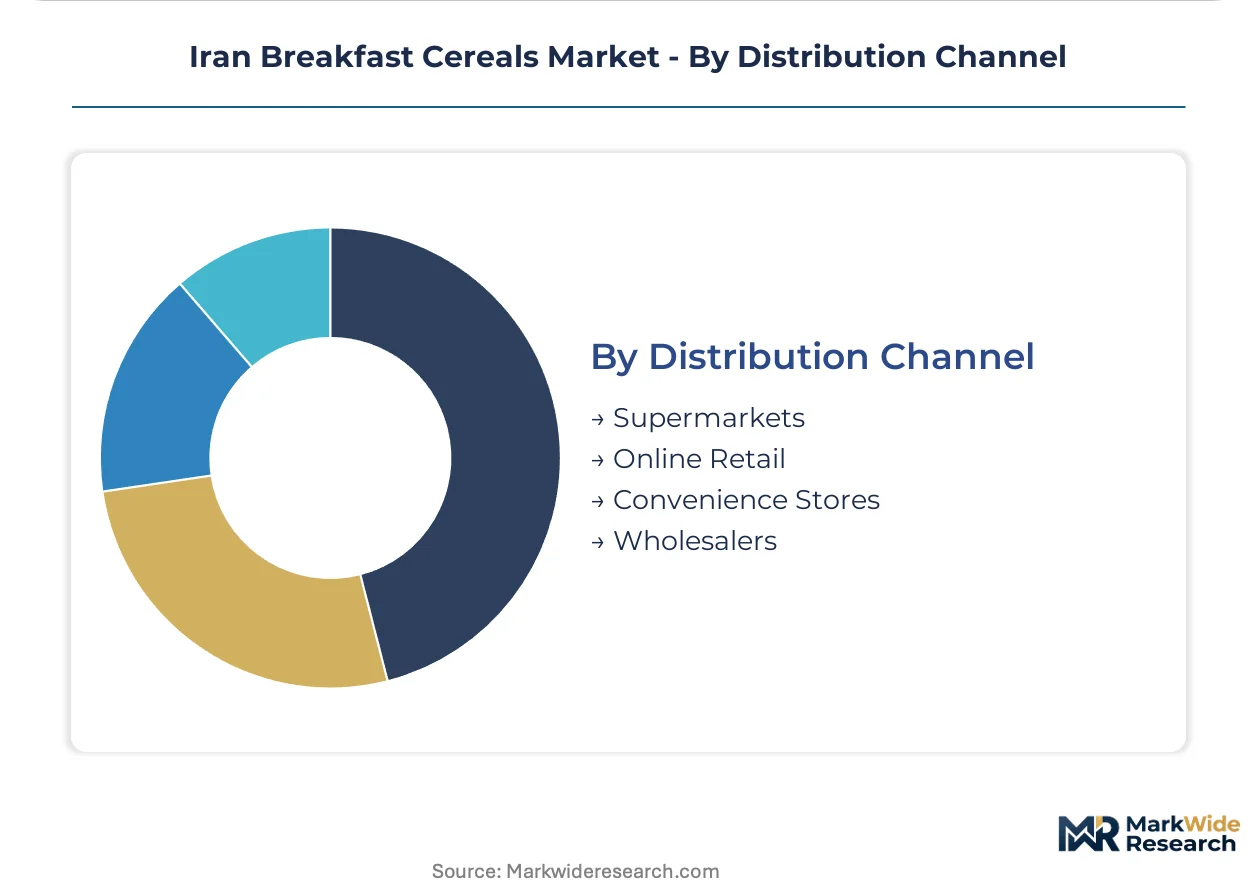
Channel mix evolution tracks retail infrastructure modernization and consumer migration from traditional bazaar commerce toward formalized retail with cold-chain reliability.
- Supermarkets:Chain retailers including Refah, Shahrvand, and Hyperstar with refrigerated dairy adjacencies. Tehran Province middle-income households concentrate purchases here, enabling impulse cross-selling with yogurt and milk categories.
- Online Retail:Digikala and Snapp Market platforms capturing urban consumers prioritizing home delivery over physical store visits. Direct-to-consumer packaging investments reward brands with subscription-capable logistics.
- Convenience Stores:Small-format urban retailers with limited shelf space favoring high-velocity SKUs. Single-serve and sachet formats dominate these locations near transit hubs and office districts.
- Wholesalers:Traditional distribution networks serving provincial retailers and bulk purchasers. General Mills and multinational entrants route through these intermediaries to circumvent direct retail establishment complexities.
Supermarkets hold current volume dominance. Online retail expands most quickly on platform infrastructure investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production cost differentials across Iranian provinces are redirecting manufacturing investment toward regions with lighter regulatory compliance burdens and established grain processing infrastructure. Provincial tariff variations and ISIRI enforcement intensity create arbitrage opportunities for manufacturers seeking operational efficiency.
Tehran Province
Dual-income households in Tehran and Karaj drive ready-to-eat cereal demand through supermarket chains with expanded cold-chain capacity. ISIRI labeling amendments receive fastest implementation here due to proximity to regulatory consultation channels. Industrial clusters in southern Tehran host extrusion technology specialists serving national distribution networks.
Mashhad
Commute-consumption patterns among service-sector employees pull single-serve portion pack demand through convenience stores near transit hubs. The Ministry of Health and Medical Education operates regional food safety oversight from this location. Manufacturing presence remains lighter than Tehran, with most supply routed through wholesale intermediaries.
Gilan Province
Colder morning temperatures sustain hot cereal penetration among traditional consumption households in Rasht and Anzali. Local rice cultivation supports puffed rice formulation production for regional distribution. Limited cold-chain depth constrains ready-to-eat format expansion beyond urban centers.
Khuzestan Province
Domestic corn harvests from Ahvaz agricultural zones supply volume-driven flake and puff manufacturing at lower per-unit input costs. Customs administration tariff structures on imported grain inputs elevate the competitive position of locally sourced formulations. Processing facilities cluster near port infrastructure for equipment import access.
Mazandaran Province
Whole grain positioning commands premium pricing among health-conscious consumers in Sari and Babol. Traditional porridge consumption patterns overlap with emerging fortified hot cereal demand. Refrigerated logistics gaps limit yogurt-accompanied cereal penetration to northern district supermarkets with dairy adjacencies.
Iran Breakfast Cereals Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue private-label and health-premium positioning through differentiated fortification strategies. Market structure concentrates around three archetypes: domestic grain-integrated manufacturers with captive supply chains, multinational brand licensors operating through wholesale partnerships, and regional specialists leveraging local dried fruit inclusions. Competitive maneuvering centers on ISIRI compliance speed and cold-chain distribution partnerships rather than direct retail confrontation.
Within the domestic-integrated tier, Shirin Meharara Company exemplifies grain-proximate manufacturing with wheat and barley sourcing strategies. Kellogg Company and Nestle S.A. represent multinational archetypes navigating Iran's distribution complexities through intermediary relationships rather than direct retail establishment. These three anchors illustrate the market's tripartite segmentation: local supply-chain control, global brand recognition, and fortified formulation expertise competing across distinct consumer access vectors.
| Leading Market Players |
|---|
| Shirin Meharara Company |
| OBST S.A. |
| Kellogg Company |
| General Mills Inc. |
| PepsiCo Inc. |
| Nestle S.A. |
| Shirin Asal |
| Kellanov |
| TakMakaron |
| Others |
Supply Flow & Price Mechanics
Extrusion technology specialists concentrated in southern Tehran compress labor-cost differentials between premium fortified formulations and economy corn-based tiers. ISIRI compliance timelines and currency volatility against dollar-denominated equipment imports widen these spreads as manufacturers pass through capital expenditure uncertainty.
Pricing Analysis
Distributor margins layered atop Tehran supermarket chains absorb 15-25% of final shelf price before retailer markup. Three-tier pricing structure across premium, standard, and economy levels segments on fortification intensity and whole grain certification rather than brand equity alone. Pricing pressure stems from grain import tariff structures elevating domestic production costs versus regional competitors. Price-sensitive buyers in secondary cities cluster in corn-based economy tiers, while Tehran's northern districts show least sensitivity to fiber-forward premium positioning.
Supply Chain Analysis
Domestic-content mandates from ISIRI and the Ministry of Health reshape sourcing toward Khuzestan corn harvests and domestic wheat procurement despite quality variability. Supply draws from Iran's grain belt provinces, with limited oat imports from Russia and Kazakhstan filling formulation gaps. Single-source vulnerability concentrates in extrusion equipment imports destabilized by rial volatility. Distribution runs through Tehran-based wholesalers serving provincial retail networks rather than direct manufacturer-to-supermarket relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iran's breakfast cereals market functions as a regulatory compounder where ISIRI fortification amendments accelerate product reformulation cycles and compress competitive timelines for compliant manufacturers.
For Market Incumbents: Cement cold-chain partnerships with Tehran supermarket chains before e-commerce platforms capture commuter-consumption occasions. Lock in multi-year domestic grain supply contracts with Khuzestan and Golestan agricultural cooperatives to buffer tariff exposure on imported inputs. ISIRI labeling compliance speed separates shelf-stable incumbents from seasonal launch disruptors. For New Entrants and Emerging Players: Begin with muesli and granola white-space targeting health-conscious households in northern provinces where import dependency for baked-cluster expertise creates supply gaps. Gilan and Mazandaran demonstrate penetrable demand for fiber-forward formulations with local dried fruit differentiation. Direct-to-consumer subscription packaging through Digikala bypasses wholesale margin layering. For Investors and Strategic Acquirers: Domestic grain-integrated manufacturers with captive wheat and barley sourcing represent the most active acquirer category in this space, consolidating regional extrusion capacity. Five-to-ten year viability hinges on ISIRI regulatory alignment speed and cold-chain infrastructure buildout. Watch Ministry of Health school breakfast program procurement announcements as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| ISIRI Compliance Acceleration | Front-of-pack nutritional scoring mandates force 90-120 day packaging redesign cycles that favor Tehran-proximate producers. |
| Domestic Grain Integration | Captive wheat and barley sourcing from Khuzestan and Golestan buffers tariff exposure on imported oat inputs. |
| Cold-Chain Partnership Expansion | Refrigerated dairy adjacencies in Refah and Shahrvand chains enable yogurt-accompanied cereal cross-selling. |
| E-Commerce Platform Entry | Digikala and Snapp Market subscription logistics reward direct-to-consumer sachet and single-serve packaging investments. |
| Ministry of Health Co-Development | School breakfast program partnerships open institutional procurement channels with volume offtake guarantees. |
Methodological Framework
Coverage spans Tehran Province, northern provinces including Gilan and Mazandaran, and corn-belt regions of Khuzestan and Golestan, with primary inputs from each. The research combines interviews with brand managers at domestic manufacturers, category buyers at supermarket chains, supply planners at grain processing facilities, and regulatory affairs specialists familiar with ISIRI procedures. Secondary validation draws from customs administration trade records, Institute of Standards and Industrial Research filings, Ministry of Health food safety protocols, and retail audit data from Tehran distribution networks. Bottom-up volume modeling triangulates against top-down market sizing across these inputs.
Granularity extends to product type, ingredient sourcing geography, packaging format, and distribution channel dimensions throughout the forecast period. CAGRs derive from trend extrapolation of dual-income household expansion, cold-chain infrastructure investment, and ISIRI regulatory amendment schedules. Modeled inputs include urban retail modernization indices, grain harvest yield variability, and currency volatility assumptions against dollar-denominated equipment imports.
Several conditions sit outside the modeled scope, including geopolitical disruptions to grain trade flows, abrupt ISIRI fortification standard reversals, and wholesale distributor consolidation beyond current intermediary structures. Forecasts reflect documented assumptions about regulatory stability and infrastructure investment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
South America Canned Fruits Market
Packaged Foods
Europe Ready-To-Eat Food Market
Packaged Foods
Packaged Burgers Market
Packaged Foods
Asia-Pacific Ready Meals Market
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
North America Ready-To-Eat Food Market
Packaged Foods
Instant Soup Market
Packaged Foods
Packaged Food Market
Packaged Foods
Global Popping Candy Market
Packaged Foods
Packaged Sprouts Market
Packaged Foods
North America Chewing Gum Market
Packaged Foods
South America Pasta and Noodles Market
Packaged Foods
Global Oven Bags Market
Packaged Foods
Dried Honey Market
Packaged Foods
Man-Made Sausage Casing Market
Packaged Foods
Convenience Food Market