
 Middle East and Africa Energy Bar Market | 2026-2036
Middle East and Africa Energy Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Energy Bar Market Foresight
The UAE's mandatory front-of-pack nutrition labeling rules is repositioning energy bar portfolios toward cleaner ingredient decks. General Mills sustains broad retail penetration across Gulf Cooperation Council hypermarket networks. Glanbia specializes in sports nutrition formulations that serve the region's expanding gym and CrossFit communities. KIND differentiates through visible whole-food ingredient positioning that resonates with premium buyers in Dubai and Riyadh.
A Middle East and Africa energy bar is a shelf-stable, nutrient-dense confection typically comprising protein isolates, cereal bases, and binding syrups, manufactured through cold extrusion or slab-forming processes, designed for portable caloric replenishment during physical exertion or meal-gap scenarios. Protein bars occupy the dominant value share given gym culture proliferation from Casablanca to Cape Town, while online retail channels represent the fastest-expanding distribution vector as Jumia and regional e-grocers deepen last-mile coverage. Meal replacement bars attract white-collar segments in Lagos and Nairobi where commute times extend traditional eating windows.
Saudi Arabia's SFDA enforces strict nutrient content claims verification, while South Africa's Department of Health implements mandatory salt and sugar reduction targets that constrain formulation latitude. The UAE's MOHAP coordinates with municipal food safety departments to accelerate novel ingredient approvals for functional bar launches. Stakeholders must monitor evolving Gulf state import tariff schedules on whey protein concentrates and nut commodities to preserve margin structures.
Market Dynamics
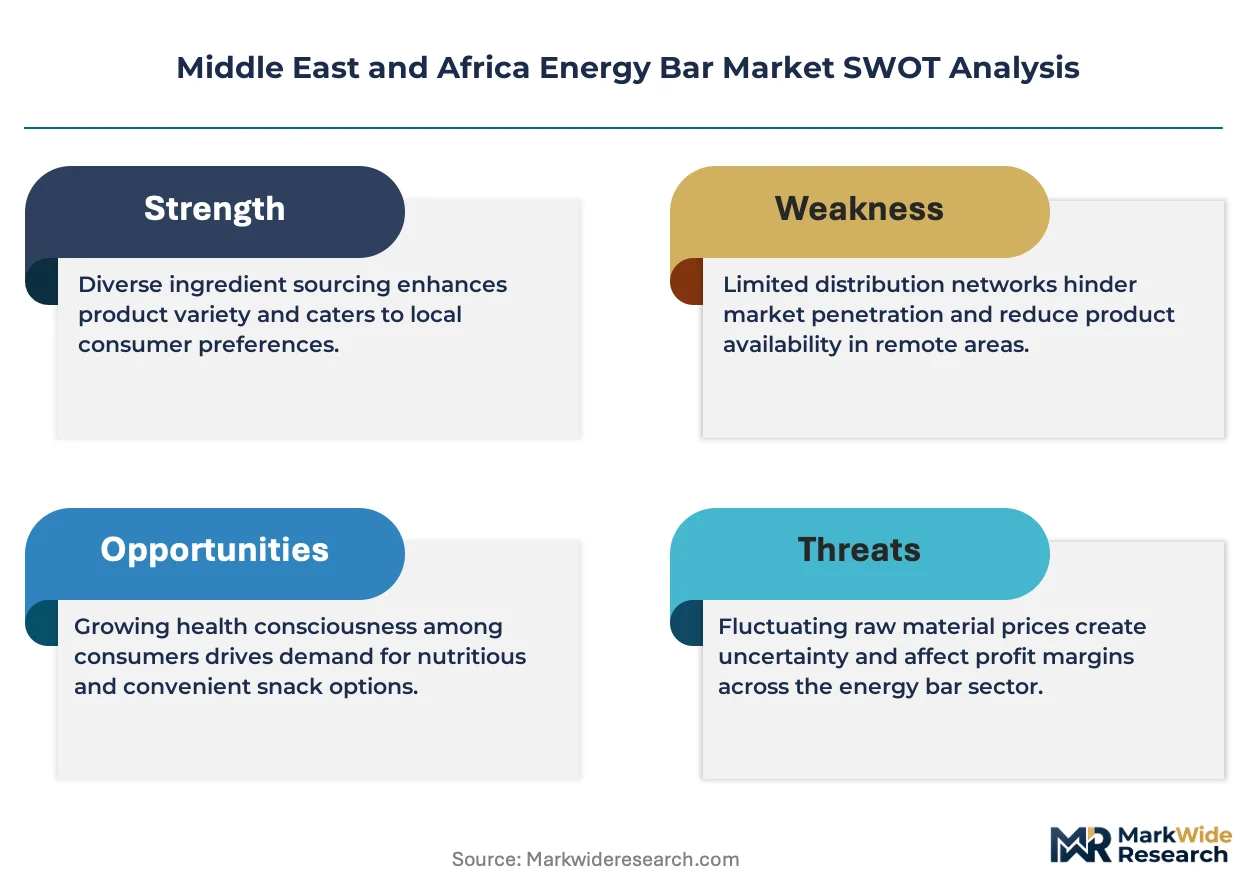
UAE's mandatory front-of-pack nutrition labeling and Saudi Arabia's SFDA enforcement are compressing formulation flexibility while redirecting R&D investment toward clean-label protein systems and alternative binding technologies.
Growth Catalysts
- SFDA Nutrient Claims Verification:Saudi Arabia's strict enforcement creates competitive moats for compliant manufacturers while accelerating industry consolidation around verified formulations.
- Gym Culture Proliferation:CrossFit and boutique fitness expansion from Casablanca to Cape Town drives protein bar consumption among urban professionals seeking portable nutrition.
- Last-Mile E-Commerce Infrastructure:Jumia and regional e-grocers are extending distribution reach into secondary cities previously underserved by traditional retail networks.
Market Restraints
- Whey Protein Concentrate Import Tariffs:Gulf state tariff schedules on dairy-derived inputs create margin pressure for cost-sensitive product tiers.
- Sugar Reduction Mandates:South Africa's Department of Health mandatory targets constrain palatability engineering and limit binder options.
- Date Syrup Supply Concentration:Regional dependence on Saudi and UAE date processing infrastructure creates input vulnerability during harvest volatility.
Strategic Opportunities
- Nairobi White-Collar Meal Replacement:Extended commute patterns in Kenya's capital create demand for satiety-focused bars positioned between snacks and full meals.
- Novel Ingredient Fast-Track Approvals:UAE's MOHAP coordination with municipal food safety departments accelerates functional ingredient launches for premium positioning.
- Plant Protein Convergence:Fava bean and chickpea isolate technologies meeting halal certification requirements open formulation pathways beyond conventional dairy.
Industry Challenges
- Reformulation Cycle Compression:Accelerating regulatory changes in Gulf states force shorter product development timelines without proportional budget expansion.
- Cold Chain Integrity for Enzyme-Stabilized Bars:Temperature excursion risks during last-mile delivery in Sub-Saharan climates limit shelf-life claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Energy Bar Market |
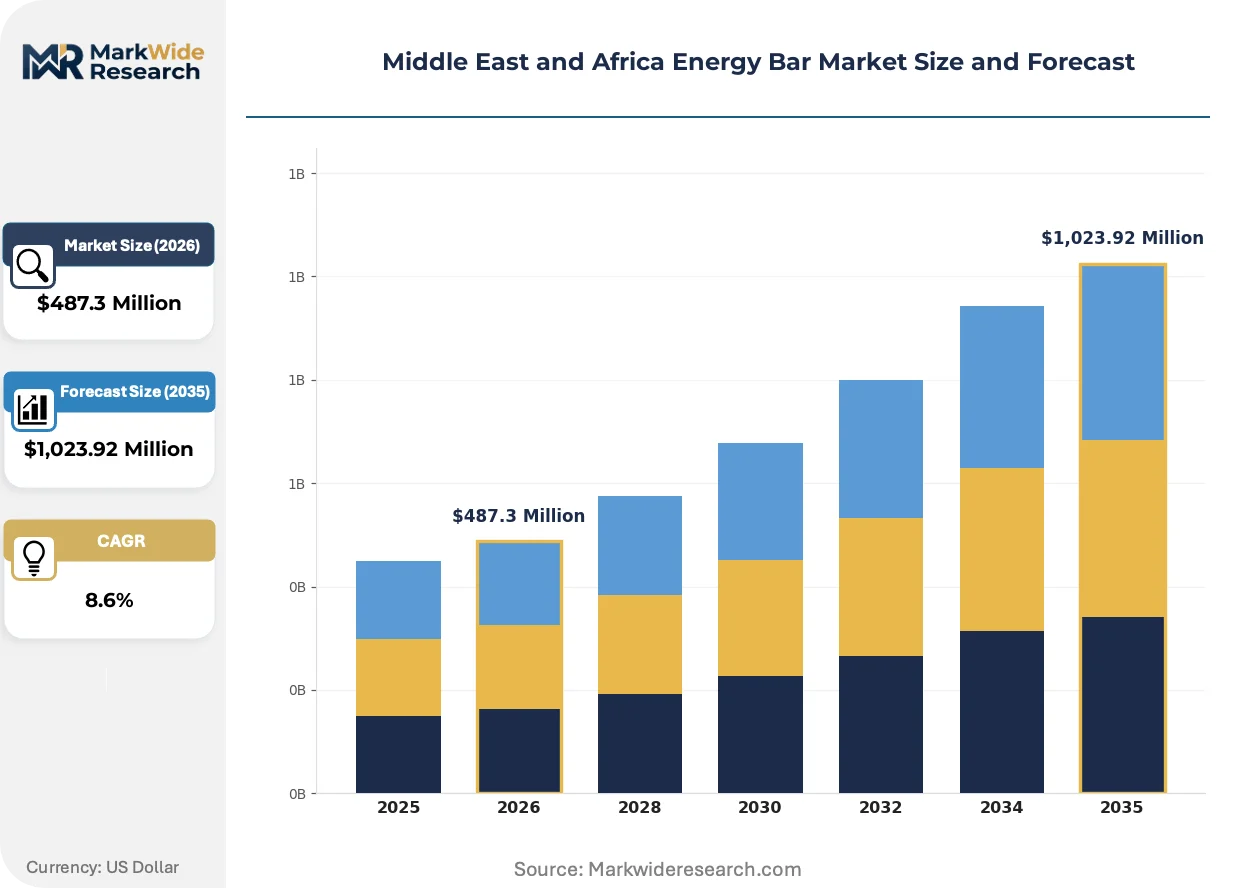
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bar, Granola Bar, Meal Replacement Bar, Fiber Bar End User: Athletes, Busy Professionals, Health-Conscious Consumers, Students Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Food Stores Ingredient Type: Nuts, Seeds, Whole Grains, Dried Fruits |
| Companies Covered | Post Holdings, Quest Nutrition, General Mills, Kellanova, Nestlé, Mondelēz International, KIND, Mars, Glanbia, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Energy Bar Market Shifts & Advancements
Cold extrusion equipment upgrades and binding syrup alternatives are restructuring production economics while regulatory labeling mandates force transparency investments across the value chain.
Date syrup and tapioca fiber binding systems are replacing conventional glucose syrups in premium formulations. Manufacturers serving Dubai and Riyadh's health-conscious segments are adopting these alternatives at accelerating rates. This ingredient pivot is expanding into mid-tier product lines as scale economies reduce cost premiums.
MOHAP's front-of-pack labeling coordination with municipal food safety departments is mandating nutrient disclosure density. Industrial consequence includes accelerated SKU rationalization and smaller portfolio breadth. Premium positioning in UAE retail is most affected, with brands responding through simplified ingredient decks and visual transparency marketing.
White-collar professionals in Lagos and Nairobi are compressing traditional meal windows through commute-extended workdays. Convenience retail and office-channel distribution are replacing conventional grocery purchasing for this segment. South Africa's metropolitan fitness culture exhibits the most visible consumption-pattern shift toward scheduled nutrition timing around training.
Middle East and Africa Energy Bar Market Segmentation
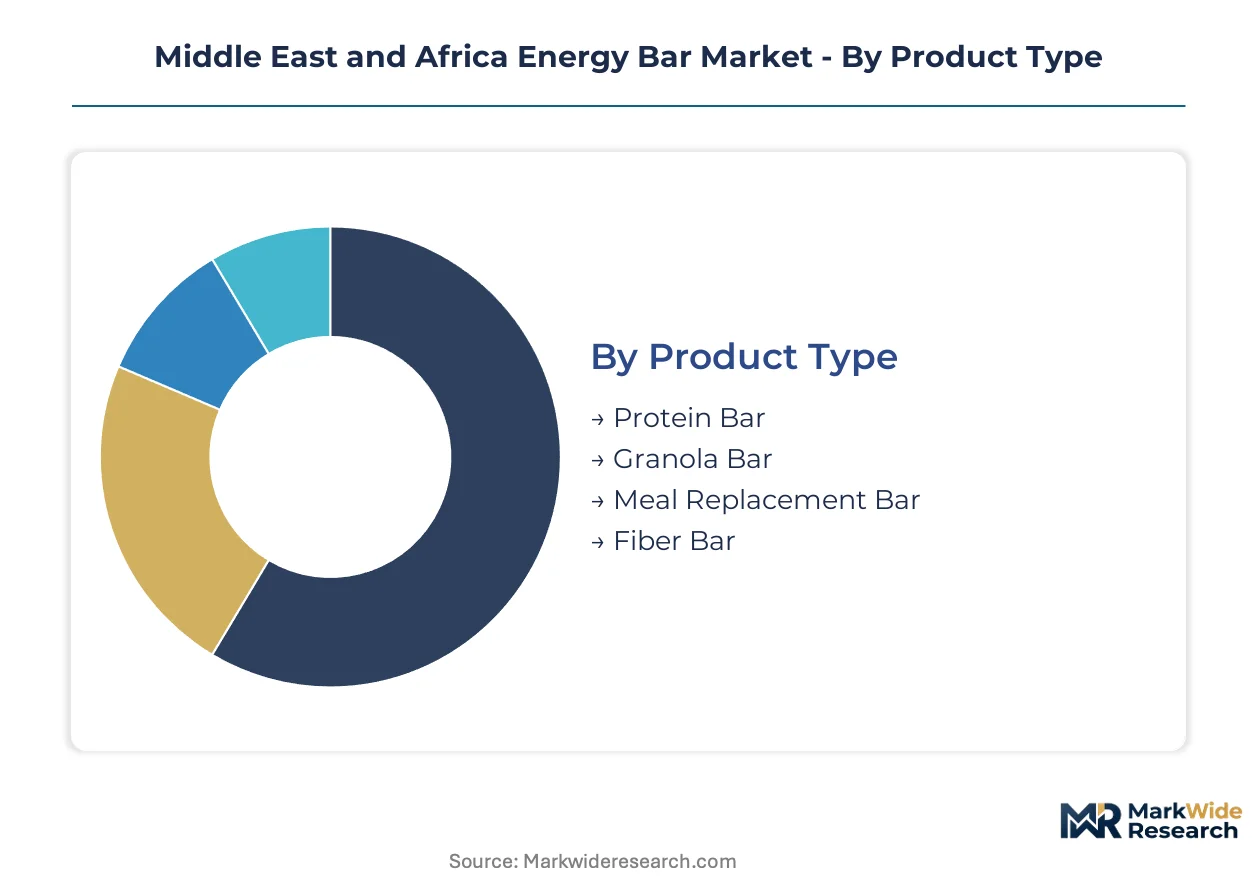
Energy bar manufacturers in the Middle East and Africa must navigate divergent capital requirements across product formats while calibrating distribution investments to urban density patterns. Segment-specific formulation costs and regulatory compliance burdens determine margin structures and competitive positioning.
Product Type:
Capital intensity varies sharply across formats, with protein bars demanding the highest upfront investment in cold extrusion equipment and isolate stabilization technology.
- Protein Bar:Cold-extruded formulations incorporating whey or plant isolates require precision moisture control and enzyme stabilization systems. Demand concentrates in Dubai and Riyadh gym networks where CrossFit culture drives scheduled consumption around training windows. Saudi Arabia's SFDA nutrient claims verification raises compliance costs for protein content labeling.
- Meal Replacement Bar:Higher caloric density and micronutrient fortification necessitate complex blending lines and stability testing protocols. Lagos and Nairobi white-collar segments adopt these for commute-extended workdays where traditional meal windows compress. South Africa's salt reduction mandates constrain palatability engineering in this category.
- Granola Bar:Baked cereal bases with binding syrups utilize simpler slab-forming equipment with lower technical barriers to entry.
- Fiber Bar:Prebiotic fiber integration requires specialized mixing to prevent texture degradation during shelf life.
Most installed capacity flows through protein bars. Expansion is steepest in meal replacement bars.
End User:
Customer acquisition costs diverge by professional density and channel access, with athletes commanding premium positioning budgets and students requiring price-engineered formulations.
- Athletes:Performance-oriented consumers prioritize protein density and timing precision over cost. Casablanca to Cape Town gym networks drive scheduled consumption patterns with strong brand loyalty to verified formulations.
- Busy Professionals:Nairobi and Lagos commuters seek satiety-focused bars bridging snack and meal occasions. Extended workday patterns favor convenience retail and office-channel distribution over traditional grocery purchasing.
- Health-Conscious Consumers:Dubai and Riyadh premium buyers respond to visible whole-food ingredient positioning and front-of-pack transparency.
- Students:Price-sensitive demand concentrates in South African metropolitan campuses and Gulf state universities with limited disposable income.
Largest volume flows through busy professionals. Athletes deliver the highest per-unit margins.
Distribution Channel:
Route-to-market economics favor scale-intensive formats in established retail while e-commerce investments absorb capital for geographic expansion.
- Online Retail:Jumia and regional e-grocers extend reach into secondary cities previously underserved by traditional networks. Last-mile infrastructure investments in Sub-Saharan climates face temperature excursion risks for enzyme-stabilized inventory.
- Supermarkets:Gulf Cooperation Council hypermarket networks sustain broad penetration but demand slotting fees and promotional support that compress margins for mid-tier entrants.
- Convenience Stores:Urban impulse purchasing in Lagos and Nairobi favors single-serve formats with higher per-gram pricing.
- Health Food Stores:Premium positioning in Dubai and Riyadh specialty retail supports cleaner ingredient decks and functional claims.
Highest throughput runs through supermarkets. Online retail is gaining share fastest.
Ingredient Type:
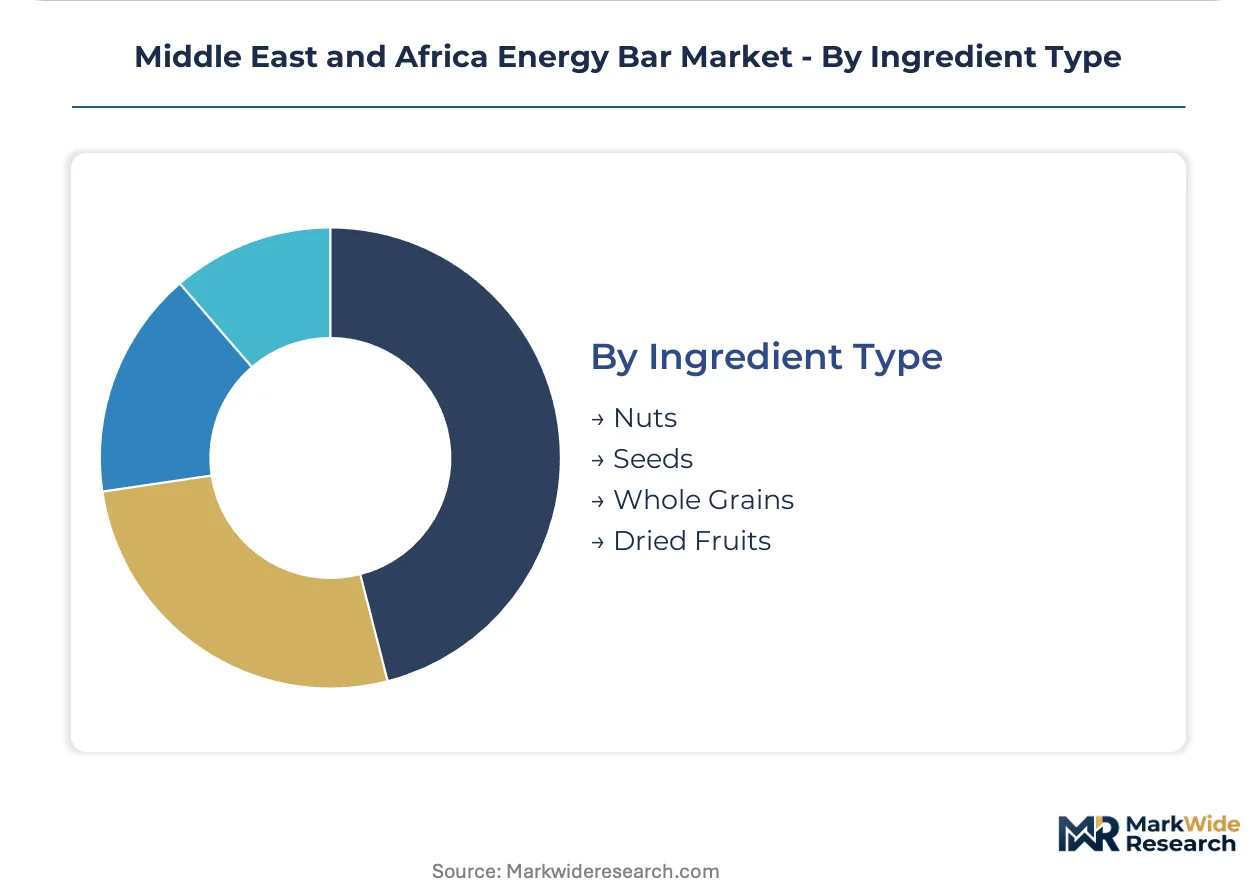
Input sourcing strategies concentrate around regional supply availability and halal certification requirements, with nut and date supply chains dominating formulation economics.
- Nuts:Almond and cashew bases command premium positioning in UAE and Saudi Arabia retail. Gulf state import tariff schedules on commodity nuts create margin pressure requiring forward contracting or regional sourcing pivots.
- Seeds:Chia and pumpkin seed integration supports plant-protein convergence trends meeting halal certification requirements.
- Whole Grains:Oat and quinoa bases provide cost-efficient carbohydrate foundations for mid-tier product lines.
- Dried Fruits:Date syrup from Saudi and UAE processing infrastructure replaces conventional glucose syrups in premium formulations, though harvest volatility creates input vulnerability.
Primary formulation volume incorporates nuts. Dried fruits are expanding most quickly as binding syrup alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Energy bar manufacturing in the Middle East and Africa traces its commercial scaling to Gulf state food processing investments during the 2000s, when date syrup extraction infrastructure originally built for traditional confectionery adapted to protein bar binding applications. Regional production now clusters around metropolitan fitness demand centers and export-oriented food technology zones.
United Arab Emirates
Dubai's CrossFit gym networks and Riyadh commuter corridors drive scheduled consumption of protein-dense formats. MOHAP's front-of-pack nutrition labeling mandates compress formulation flexibility while accelerating clean-label R&D investment. Abu Dhabi's Khalifa Industrial Zone hosts contract manufacturing facilities serving premium retail channels across the GCC.
Saudi Arabia
SFDA nutrient claims verification creates compliance moats for verified manufacturers while consolidating industry share around tested formulations. The Riyadh-Dammam corridor anchors domestic production capacity for date syrup-based binding systems. Jeddah's Red Sea logistics hub facilitates re-export to East African markets.
South Africa
Cape Town and Johannesburg metropolitan fitness cultures sustain the region's most visible consumption shift toward scheduled nutrition timing. The Department of Health's mandatory salt and sugar reduction targets constrain palatability engineering in meal replacement formats. Durban's port infrastructure handles nut commodity imports for regional formulation.
Nigeria
Lagos white-collar professionals compress traditional meal windows through commute-extended workdays, creating demand for satiety-focused bars. The country's national food safety regulator maintains evolving standards for fortified food claims. Port Harcourt's industrial zones host emerging contract manufacturing for West African distribution.
Kenya
Nairobi's extended commute patterns generate office-channel and convenience retail demand for portable nutrition bridging snack and meal occasions. The Kenya Bureau of Standards enforces labeling requirements for nutrient-dense packaged foods. Mombasa's port facilities serve as entry point for whey protein concentrates and specialty ingredients.
Middle East and Africa Energy Bar Market Competitive Landscape
Capital-heavy producers with captive manufacturing assets compete with asset-light brand architects relying on regional contract manufacturers. Market structure tilts toward consolidated multinational presence in premium retail channels alongside fragmented local formulators serving price-sensitive tiers. Three archetypes dominate: diversified food conglomerates with Gulf hypermarket leverage, sports nutrition specialists with gym-channel penetration, and clean-label challengers with whole-food positioning. Competitive moves concentrate on SKU rationalization responding to labeling mandates and strategic partnerships with regional e-grocers for last-mile expansion.
Among diversified food conglomerates, General Mills and Nestlé occupy positions defined by broad retail penetration across GCC hypermarket networks. Glanbia represents the sports nutrition specialist archetype with formulations targeting CrossFit and boutique fitness communities. KIND exemplifies clean-label positioning through visible whole-food ingredient transparency that resonates with premium buyers in Dubai and Riyadh.
| Leading Market Players |
|---|
| Post Holdings |
| Quest Nutrition |
| General Mills |
| Kellanova |
| Nestlé |
| Mondelēz International |
| KIND |
| Mars |
| Glanbia |
| Others |
Supply & Pricing Matrix
Gulf Cooperation Council hypermarket procurement teams command substantial volume leverage, compressing margin structures for mid-tier energy bar suppliers while rewarding compliant manufacturers with shelf-space premiums. This buyer concentration enforces a three-tier pricing structure across premium, standard, and economy levels that segments by certification status and ingredient transparency rather than protein density alone.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the Middle East and Africa energy bar market, with price differentiation driven by MOHAP front-of-pack compliance certification and halal verification tier. Cost compression in the standard tier is intensifying because Saudi SFDA nutrient claims verification raises formulation expenses without proportional retail price acceptance. Students in South African metropolitan campuses exhibit the highest price sensitivity, while Dubai health-conscious consumers show the lowest.
Supply Chain Analysis
Workforce availability constraints in UAE food technology zones and Saudi date processing corridors limit expansion velocity for binding syrup extraction capacity. Manufacturing concentrates in the UAE, Saudi Arabia, and South Africa, with raw material dependencies on Saudi date syrup, imported whey protein concentrates, and Indian cashew commodities. Single-source vulnerability in Saudi date processing infrastructure creates harvest-season supply risk. Distribution runs through GCC hypermarket networks and Jumia's last-mile e-grocery infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa energy bar market functions as a regulatory compounder where compliance investments generate compounding returns as SFDA and MOHAP enforcement tightens formulation standards and consolidates share around verified manufacturers.
For Market Incumbents:To counter margin compression from Gulf state whey protein concentrate import tariffs, secure backward integration into regional plant protein isolate production or establish long-term offtake agreements with UAE date syrup processors. Channel control through exclusive Jumia partnerships defends against emerging direct-to-consumer entrants.
For New Entrants and Emerging Players:Capture Nairobi white-collar meal replacement demand through office-channel distribution partnerships targeting commute-extended workday patterns. Plant protein formulations meeting halal certification requirements offer the most penetrable positioning against dairy-dependent incumbents. Lead with satiety-focused marketing rather than gym-culture performance claims.
For Investors and Strategic Acquirers:Regional food conglomerates with Gulf hypermarket leverage are the most active acquirer in this space, seeking clean-label capabilities to complement existing portfolios. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone. Watch for MOHAP novel ingredient fast-track approval velocity as an inflection indicator for functional bar premiumization potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | MOHAP front-of-pack mandates force ingredient deck simplification for UAE retail access. |
| Plant Protein Capacity Buildout | Fava bean and chickpea isolate investments reduce Gulf state dairy import tariff exposure. |
| E-Commerce Channel Expansion | Jumia partnerships extend reach into secondary cities beyond traditional hypermarket coverage. |
| Date Syrup Supply Integration | Backward integration into Saudi processing infrastructure secures binding input against harvest volatility. |
| Halal Certification Investment | Verified status unlocks premium positioning in Saudi Arabia and UAE retail channels. |
Research Methodology
Bottom-up urban professional consumption modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with brand managers at regional energy bar manufacturers, category buyers at GCC hypermarket chains, supply planners at date syrup processors, and regulatory affairs leads navigating SFDA compliance were validated against secondary sources including Saudi SFDA filing databases, UAE MOHAP food safety circulars, and Jumia merchant disclosure records. Top-down trade flow analysis and bottom-up channel audit data were triangulated to reconcile volume estimates.
Historical trendline analysis across protein bar, meal replacement bar, and granola bar shipment patterns informed the projection framework. Segmentation dimensions modeled include product format, end-user archetype, distribution channel, and ingredient type. CAGRs were derived from slope analysis of segment-specific growth trajectories, with forecast inputs incorporating gym network expansion rates in metropolitan centers and e-commerce penetration curves in Sub-Saharan markets.
Regulatory enforcement intensity shifts, date harvest yield volatility, and whey protein concentrate tariff schedule revisions are the dominant revision risks to the forecast framework. Practitioners should monitor SFDA audit frequency, Saudi agricultural ministry harvest reports, and Gulf Cooperation Council customs union policy deliberations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Saudi Arabia Ready Meals Market
Packaged Foods
Eco Bowls Market
Packaged Foods
Breakfast Food Market
Packaged Foods
North America Instant Noodles Market
Packaged Foods
Sugar Bags Market
Packaged Foods
Cereal Flakes Market
Packaged Foods
Instant Cereals Market
Packaged Foods
Protein Packed Foods Market
Packaged Foods
Food and Beverages Market
Packaged Foods
Canned Food Market
Packaged Foods
Private Label Food and Beverage Market
Packaged Foods
Canned Fruits Market
Packaged Foods
Morning Goods Market
Packaged Foods
Chewing Gum Market
Packaged Foods
Europe Ready-To-Eat Food Market
Packaged Foods
Plant Focused Dips Market